
Asia
Pakistan’s Strategic Economic Position in South Asia

Pakistan stands at the crossroads of South Asia, Central Asia, and the Middle East, positioning itself as a significant economic gateway in one of the world’s fastest-growing regions. With GDP growth of 5.70% in Q2 2025 and inflation dropping from 30.77% to 3.0%, Pakistan is emerging from economic turbulence with strong momentum.
This transformation represents more than statistical improvement. Pakistan’s strategic positioning combines geographic advantages with substantial infrastructure investments and regional partnerships that create unique opportunities for businesses, investors, and policymakers seeking exposure to South Asia’s evolving market.
The country’s economic recovery demonstrates sustained commitment to structural reforms. Foreign direct investment increased 41% to $1.618 billion, while the $62+ billion China-Pakistan Economic Corridor positions Pakistan as a regional trade hub connecting three major economic regions.
Key Economic Indicators
Pakistan’s GDP grew 5.70% in Q2 2025, with foreign direct investment increasing 41% to $1.618 billion. The China-Pakistan Economic Corridor worth $62+ billion positions Pakistan as a regional trade hub. Strategic location connecting three major regions offers unmatched access to maritime and overland trade routes.
Emerging opportunities span mining with $6 trillion reserves, digital economy generating $3.8 billion IT exports, and blue economy targeting $100 billion value by 2047. Regional partnerships through SAARC, ECO, and bilateral alliances strengthen Pakistan’s economic influence across South Asia.
Pakistan’s Economic Recovery and Current Performance
Pakistan’s macroeconomic stabilization achievements reflect comprehensive policy reforms and structural adjustments. The country achieved 5.70% GDP growth in Q2 2025, with projections indicating 3.10% growth by year-end 2025. This performance demonstrates Pakistan’s resilience and adaptive capacity.
The economy’s sectoral composition reveals balanced diversification. Services contribute 53% of the $373.07 billion GDP, followed by industry at 25% and agriculture at 22%. This distribution supports economic stability while providing multiple growth drivers.
Inflation control represents Pakistan’s most dramatic stabilization success. The rate plummeted from 30.77% in 2023 to 3.0% by August 2025. This achievement enables predictable business planning and increased consumer purchasing power.
Fiscal improvements complement monetary policy success. Pakistan achieved a primary surplus of 3.0% of GDP during July-March FY2025. This fiscal discipline demonstrates government commitment to sustainable public finance management.
Foreign direct investment surged to $1.618 billion between July 2024 and February 2025, representing a 41% year-over-year increase. Key FDI sectors include power projects, financial services, and oil and gas exploration. This investment growth indicates improving investor confidence and business climate.
Pakistan’s export profile totaled $32.44 billion, led by textiles, apparel, and cereals. Import composition reached $56.48 billion, dominated by mineral fuels and machinery. The trade balance shows gradual improvement as export competitiveness increases.
External account stabilization achieved a $1.9 billion current account surplus. Foreign exchange reserves rose to $16.64 billion by May 2025. These improvements provide economic stability and reduce vulnerability to external shocks.
Strategic Geographic Advantages and Infrastructure
Pakistan’s geographic position creates unmatched connectivity advantages. The country borders India, Afghanistan, Iran, and China, enabling unique multi-regional access. Arabian Sea coastline provides access to vital international shipping routes connecting Asia, Africa, and Europe.
Overland trade routes enhance regional connectivity. The Karakoram Highway strengthens China-Central Asia links while positioning Pakistan as an important transit hub. Energy pipeline routes from Central Asia and the Middle East further emphasize Pakistan’s strategic importance.
The China-Pakistan Economic Corridor represents transformative infrastructure investment. This $62+ billion project creates new trade corridors connecting Gwadar Port to China’s Xinjiang region. CPEC addresses Pakistan’s energy shortages while providing China secure import routes.
| Project Type | Investment (USD Billion) | Completion Status | Economic Impact |
|---|---|---|---|
| Energy Projects | $28.5 | 75% Complete | Reduced energy shortages by 40% |
| Transportation | $18.2 | 60% Complete | 30% reduction in logistics costs |
| Gwadar Port | $4.5 | 80% Complete | 200% increase in port capacity |
| Industrial Zones | $8.8 | 45% Complete | 150,000 projected jobs |
Infrastructure modernization delivers measurable benefits. Improved transportation networks reduce logistics costs by up to 30%. Special Economic Zones attract manufacturing investment while creating employment opportunities. Enhanced digital connectivity supports Pakistan’s growing IT services sector.
Energy grid expansion provides reliable power supply enabling industrial growth. These infrastructure investments create competitive advantages for businesses while supporting economic diversification efforts across multiple sectors.
Regional Economic Integration and Partnerships
Pakistan plays a founding member role in the South Asian Association for Regional Cooperation, helping establish regional cooperation frameworks. The country supports South Asian Free Trade Agreement initiatives despite political challenges limiting SAARC effectiveness since 2016.
India-Pakistan tensions restrict SAARC potential, prompting alternative regional cooperation mechanisms. Pakistan actively seeks new frameworks for enhanced economic integration across South Asia and beyond.
The Economic Cooperation Organization positions Pakistan centrally in connecting South and Central Asia. As a founding member, Pakistan promotes economic cooperation among 10 ECO member countries. Regional connectivity projects enhance trade flows while infrastructure development creates investment opportunities.
Current intra-regional trade levels remain low, indicating considerable expansion potential. Pakistan’s strategic position enables it to capture increased trade flows as regional integration deepens.
Strategic bilateral partnerships strengthen Pakistan’s economic position. The comprehensive China alliance extends beyond CPEC to encompass broad economic and strategic cooperation. Saudi Arabia’s Strategic Mutual Defense Agreement signed in September 2025 enhances economic ties alongside security cooperation.
Enhanced partnerships with Turkey and Iran expand cooperation in energy, trade, and investment sectors. Pakistan maintains economic relationships with US and European markets while developing new regional partnerships.
Regional trade integration provides access to combined markets exceeding 2 billion consumers. Complementary economies create trade synergies while cross-border investment opportunities expand in infrastructure and manufacturing. Technology transfer accelerates economic development through knowledge sharing initiatives.
Economic Challenges and Growth Opportunities
Pakistan faces substantial economic challenges requiring strategic responses. Political stability concerns hinder structural reforms and long-term planning capabilities. Export competitiveness requires diversification and modernization to maintain global market share.
Natural disasters, including 2024-2025 floods, cause substantial economic disruption and infrastructure damage. Debt management balances growth investments with fiscal sustainability requirements while maintaining investor confidence.
The mining sector offers transformative potential with $6 trillion mineral reserves including copper, gold, and rare earth elements. The Reko Diq project represents a major copper-gold mining venture expected to boost GDP contribution. Foreign partnerships and technology transfer requirements present both challenges and opportunities.
Pakistan’s digital economy generated $3.8 billion in IT exports during 2025, growing at 20% annually. The country possesses a large English-speaking workforce with expanding technical skills. Government Digital Pakistan initiatives promote technology adoption across sectors while serving domestic and international markets.
Blue economy development targets $100 billion value by 2047 through coastal resource development. Sustainable marine resource development includes fisheries, aquaculture, port infrastructure upgrades, and coastal tourism expansion.
| Sector | Investment Potential | Timeline | Job Creation | GDP Impact |
|---|---|---|---|---|
| Mining | $50 billion | 5-10 years | 500,000 | 3-5% GDP growth |
| Digital Economy | $15 billion | 3-5 years | 2 million | 2% GDP growth |
| Blue Economy | $25 billion | 10-15 years | 1 million | 4% GDP growth |
| Renewable Energy | $20 billion | 5-8 years | 300,000 | 2% GDP growth |
Structural reform priorities include state-owned enterprise modernization. Pakistan International Airlines privatization in December 2025 signals broader reform commitment. Energy sector transformation emphasizes renewable energy investments reducing import dependence.
Agricultural productivity improvements require technology adoption and value chain enhancements. Human capital development through education and skills training programs supports industrial growth requirements.
Investment Climate and Business Environment
Foreign direct investment growth demonstrates improved investor confidence across multiple sectors. The 41% FDI increase reflects diversification beyond traditional industries into technology and services. China leads investment sources, but diversification efforts attract partners from multiple regions.
Policy improvements include streamlined approval processes and enhanced investment incentives. Regulatory reforms simplify business registration and licensing procedures while reducing administrative barriers.
Key investment sectors for international businesses include energy infrastructure, manufacturing and textiles, technology services, and mining ventures. Power generation and renewable energy projects offer substantial opportunities. Export-oriented production facilities benefit from improved trade access.
Special Economic Zones provide tax incentives and infrastructure support for investors. Financial sector development improves banking services and capital market access. Skills development programs support industrial workforce requirements.
Risk mitigation addresses currency stability concerns through improved exchange rate management. Enhanced security measures protect business operations while infrastructure reliability continues improving. Bureaucratic efficiency reforms reduce administrative obstacles for investors.
The investment climate benefits from Pakistan’s strategic positioning and business environment improvements. These factors combine to create attractive opportunities for investors seeking South Asian market exposure.
Future Outlook and Strategic Implications
Medium-term economic projections indicate sustained recovery momentum. GDP growth forecasts show 3.60% in 2026 and 4.10% in 2027, demonstrating consistent expansion. Inflation targeting maintains 4.00% average through disciplined monetary policy implementation.
Investment climate improvements support continued FDI growth as structural reforms take effect. Export diversification reduces textile dependence through technology adoption and value-added product development.
Regional leadership opportunities position Pakistan as a trade hub using geographic advantages for transit trade growth. The country can become a key energy corridor for Central Asian resources while establishing itself as South Asia’s technology services center.
Financial services development includes Islamic finance expansion and regional banking capabilities. These sectors offer substantial growth potential while supporting broader economic development objectives.
Strategic recommendations for investors emphasize sector focus on mining, technology, and renewable energy opportunities. Partnership strategies should collaborate with local firms and government initiatives while managing investment risks through diversification.
Long-term perspectives should capitalize on Pakistan’s demographic dividend and infrastructure development progress. Policy priorities for sustained growth include institutional strengthening, human capital investment, innovation ecosystem development, and deeper regional integration.
Pakistan’s projected economic trajectory supports its emergence as a regional leader. The combination of strategic advantages, infrastructure investments, and policy reforms creates compelling opportunities for businesses and investors.
Frequently Asked Questions
What is Pakistan’s current GDP growth rate and economic outlook? Pakistan achieved 5.70% GDP growth in Q2 2025, with projections of 3.60% in 2026 and 4.10% in 2027. The economy has stabilized with inflation dropping from 30.77% to 3.0%, while foreign direct investment increased 41% to $1.618 billion.
How does the China-Pakistan Economic Corridor benefit Pakistan’s economy? CPEC’s $62+ billion investment transforms Pakistan’s infrastructure, reduces energy shortages by 40%, cuts logistics costs by 30%, and increases Gwadar Port capacity by 200%. The project positions Pakistan as a regional trade hub connecting China to Central Asia and beyond.
What are the main investment opportunities in Pakistan? Key sectors include mining ($6 trillion reserves potential), digital economy ($3.8 billion IT exports growing 20% annually), blue economy (targeting $100 billion by 2047), and renewable energy. These sectors offer substantial returns while supporting Pakistan’s economic diversification.
How stable is Pakistan’s business environment for foreign investors? Pakistan improved its investment climate through regulatory reforms, streamlined approval processes, and Special Economic Zones offering tax incentives. Foreign exchange reserves rose to $16.64 billion, while current account achieved $1.9 billion surplus, demonstrating economic stability.
What role does Pakistan play in South Asian regional cooperation? Pakistan is a founding member of SAARC and ECO, actively promoting regional trade integration. Despite political challenges, the country maintains strategic partnerships with China, Saudi Arabia, Turkey, and Iran while working toward new cooperation frameworks for enhanced economic integration.
Pakistan’s strategic economic position combines geographic advantages, infrastructure investments, and improving business climate to create South Asia’s emerging powerhouse. The country’s recovery from economic challenges demonstrates resilience while substantial growth opportunities across multiple sectors offer compelling prospects for investors and business leaders seeking regional market exposure.
South Asia’s Economic Powerhouse: Pakistan’s Strategic Position
1. Economic Performance Overview
Pakistan’s economy has shown signs of recovery and stabilization in 2024-2025, although it faces significant challenges. The GDP expanded by 5.70% in Q2 2025 compared to the same quarter in the previous year, with the fiscal year 2025 growth estimated at approximately 3.04% Pakistan GDP Annual Growth Rate – Trading Economics. Projections indicate a GDP growth of around 3.10% by the end of 2025, with forecasts of 3.60% in 2026 and 4.10% in 2027 Pakistan GDP Annual Growth Rate – Trading Economics. The GDP in current market prices was about $373.07 billion in December 2024 Pakistan GDP Annual Growth Rate – Trading Economics. The services sector contributes the most to GDP (53%), followed by industry (25%) and agriculture (22%) Pakistan GDP Annual Growth Rate – Trading Economics.
Inflation has eased, reaching 3.0% in August 2025, a significant drop from 30.77% in 2023 Pakistan Inflation Rate – Trading Economics. The inflation rate for 2024 was around 12.63% Pakistan Inflation Rate – Trading Economics. Inflation is expected to average around 4.00% by the end of 2025 Pakistan Inflation Rate – Trading Economics.
Foreign Direct Investment (FDI) saw a positive trend, with $1.618 billion attracted from July 2024 to February 2025, a 41% increase compared to the same period in the previous fiscal year OICCI Report (Mar 2025). Key sectors attracting FDI include power projects, financial business, and oil & gas exploration OICCI Report (Mar 2025). China is the leading FDI partner OICCI Report (Mar 2025).
Total exports in 2024 were valued at $32.44 billion, with major categories including textile articles, apparel, and cereals Pakistan Exports By Category – Trading Economics. Imports totaled $56.48 billion, with mineral fuels, electrical equipment, and machinery being the top import categories Pakistan Imports By Category – Trading Economics.
2. Geopolitical and Strategic Advantages
2.1. Geographical Location
Pakistan’s strategic location at the crossroads of South Asia, Central Asia, and the Middle East is a key advantage Wikipedia – Pakistan. It borders India, Afghanistan, Iran, and China, and has a coastline along the Arabian Sea Wikipedia – Pakistan. This position provides access to vital maritime trade routes and connects South Asia with Central Asia and China Wikipedia – Pakistan. The Karakoram Highway enhances overland trade and strategic connectivity Wikipedia – Pakistan.
2.2. Major Alliances and Strategic Partnerships
Pakistan maintains strong alliances that bolster its geopolitical standing:
- China: A close ally, especially in military, economic, and infrastructure collaboration, with the China-Pakistan Economic Corridor (CPEC) as a key project Wikipedia – Foreign relations of Pakistan.
- Saudi Arabia: Strong bilateral ties, including a Strategic Mutual Defense Agreement (September 2025), enhancing regional security cooperation MEI.
- Iran and Turkey: Important partners in national security and economic interests Wikipedia – Foreign relations of Pakistan.
- United States and Western Countries: Historically significant partnerships with fluctuating dynamics Wikipedia – Foreign relations of Pakistan.
2.3. Regional Infrastructure Projects: China-Pakistan Economic Corridor (CPEC)
CPEC is a major infrastructure project connecting Gwadar Port to China’s Xinjiang region Wikipedia – China-Pakistan Economic Corridor. It aims to modernize Pakistan’s infrastructure and alleviate energy shortages Wikipedia – China-Pakistan Economic Corridor. The project is valued at over $62 billion, providing China with a shorter and secure route for energy imports Wikipedia – China-Pakistan Economic Corridor. CPEC enhances trade links between China, Pakistan, and Central Asia, boosting Pakistan’s role as a regional trade hub Wikipedia – China-Pakistan Economic Corridor.
3. Economic Challenges and Opportunities
3.1. Macroeconomic Stabilization and Fiscal Management
Pakistan achieved significant macroeconomic stabilization by 2025, with a projected GDP growth of 5.7% over the medium term Finance Division. The government recorded a primary surplus of 3.0% of GDP for July-March FY2025 and a fiscal surplus in the first quarter of FY2024-25 Finance Division. Inflation fell sharply to 0.3% in April 2025 Finance Division. External accounts stabilized with a current account surplus of USD 1.9 billion, and foreign exchange reserves rose to USD 16.64 billion by May 2025 Finance Division.
The World Bank noted Pakistan’s 3.0% GDP growth in FY2025, driven by industrial and services sector rebound World Bank. Fiscal tightening and monetary policy helped anchor inflation and support surpluses World Bank.
3.2. Economic Challenges Hindering Growth
- Political Instability: Political instability has historically hindered structural reforms and economic stability IBA Report.
- Export Decline: Exports have declined, making growth reliant on debt and remittances World Bank Report.
- Natural Disasters: Floods in 2024-2025 have caused significant economic losses World Bank.
3.3. Opportunities and Potential Areas for Development
- Mining Sector: Unlocking a $6 trillion mineral reserve opportunity, with projects like Reko Diq expected to boost mining’s GDP contribution Balochistan Pulse.
- Digital Economy and IT Exports: IT exports grew to $3.8 billion in 2025, with 20% annual growth Balochistan Pulse.
- Blue Economy: Targeting a $100 billion value by 2047 through fisheries, aquaculture, port upgrades, and coastal tourism Balochistan Pulse.
- Social Programs and Human Capital: Efforts to reduce out-of-school children through education emergency policies and cash transfer programs Balochistan Pulse.
- Privatization and State-Owned Enterprise Reform: The privatization of Pakistan International Airlines in December 2025 Balochistan Pulse.
- Renewable Energy and Industrial Modernization: Emphasis on investment in agriculture, renewable energy, and industrial modernization Finance Division.
4. Pakistan’s Role in Regional Organizations
4.1. SAARC (South Asian Association for Regional Cooperation)
- Pakistan is a founding member of SAARC South Asia – Ministry of Foreign Affairs Pakistan.
- Pakistan supports SAARC initiatives, including the SAFTA agreement Enhancing Regional Cooperation: Pakistan’s Role in Revitalizing SAARC – ISSI.
- Political tensions, especially between India and Pakistan, have led to SAARC stagnation The Friday Times.
- Pakistan advocates for constructive engagement and dialogue with India South Asia – Ministry of Foreign Affairs Pakistan.
- Pakistan is exploring alternative regional cooperation frameworks Al Jazeera.
4.2. ECO (Economic Cooperation Organization)
- Pakistan is a founding member of ECO Pakistan and Economic Cooperation Organization (ECO) – ISSI.
- Pakistan promotes economic cooperation, regional trade, and infrastructural development within ECO Pakistan and Economic Cooperation Organization (ECO) – ISSI.
- Pakistan hosted the 13th ECO Summit in 2017 Pakistan and Economic Cooperation Organization (ECO) – ISSI.
- Challenges include low intra-regional trade and the need for improved infrastructure Pakistan and Economic Cooperation Organization (ECO) – ISSI.
5. Broader South Asian Regional Influence
- Pakistan’s strategic location enhances its geoeconomic importance CSCSS.
- Pakistan is involved in regional initiatives beyond SAARC and ECO, including discussions on new regional blocs Al Jazeera.
- Pakistan emphasizes peaceful neighborhood policies, regional connectivity, and economic integration South Asia – Ministry of Foreign Affairs Pakistan.
Sources
- https://tradingeconomics.com/pakistan/gdp-growth-annual
- https://tradingeconomics.com/pakistan/inflation-cpi
- https://www.oicci.org/app/media/2025/04/FDI-Mar-25.pdf
- https://tradingeconomics.com/pakistan/exports-by-category
- https://tradingeconomics.com/pakistan/imports-by-category
- https://en.wikipedia.org/wiki/Pakistan
- https://en.wikipedia.org/wiki/Foreign_relations_of_Pakistan
- https://mei.edu/publications/pakistans-strategic-defense-pact-saudi-arabia-new-security-architecture-wider-middle
- https://en.wikipedia.org/wiki/China%E2%80%93Pakistan_Economic_Corridor
- https://www.finance.gov.pk/survey/chapter_25/Highlights.pdf
- https://www.worldbank.org/en/news/press-release/2025/10/27/-pakistan-sustained-reforms-needed-for-inclusive-growth-economic-stability-and-flood-recovery
- https://cber.iba.edu.pk/pdf/book-series/state-of-pakistan-economy-2024-25.pdf
- https://thedocs.worldbank.org/en/doc/972c49ee47cc09d4face97b09ea64362-0310012025/pakistan-development-update-staying-the-course-for-growth-and-jobs-october-2025
- https://balochistanpulse.com/pakistan-economic-turnaround-2025
- https://mofa.gov.pk/south-asia
- https://issi.org.pk/enhancing-regional-cooperation-pakistans-role-in-revitalizing-saarc
- https://www.thefridaytimes.com/13-Nov-2025/saarc-limbo-india-pakistan-rivalry-crippled-south-asian-regionalism
- https://www.aljazeera.com/news/2025/12/5/pakistan-seeks-new-south-asian-bloc-to-cut-india-out-will-it-work
- https://issi.org.pk/pakistan-and-economic-cooperation-organization-eco
- https://cssprepforum.com/pakistan-is-located-on-the-cross-road-of-south-asia-explain-its-geostrategic-political-importance-and-challenges
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Are Asian stock markets rising in 2026?
Most of them are, but for very different reasons. Japan’s Nikkei 225 is trading at levels roughly 44% higher than a year ago on continued AI-linked technology strength; China’s benchmark indices climbed to multi-year highs at the start of the year on AI optimism and signs of economic recovery; and Pakistan’s KSE-100 has been one of the most volatile large gainers globally, crossing record highs early in the year before enduring sharp single-session pullbacks in September. Understanding each market separately matters more than treating “Asia” as one trade.
Japan: A 15-Year-Plus Bull Run Meets a Hawkish Central Bank
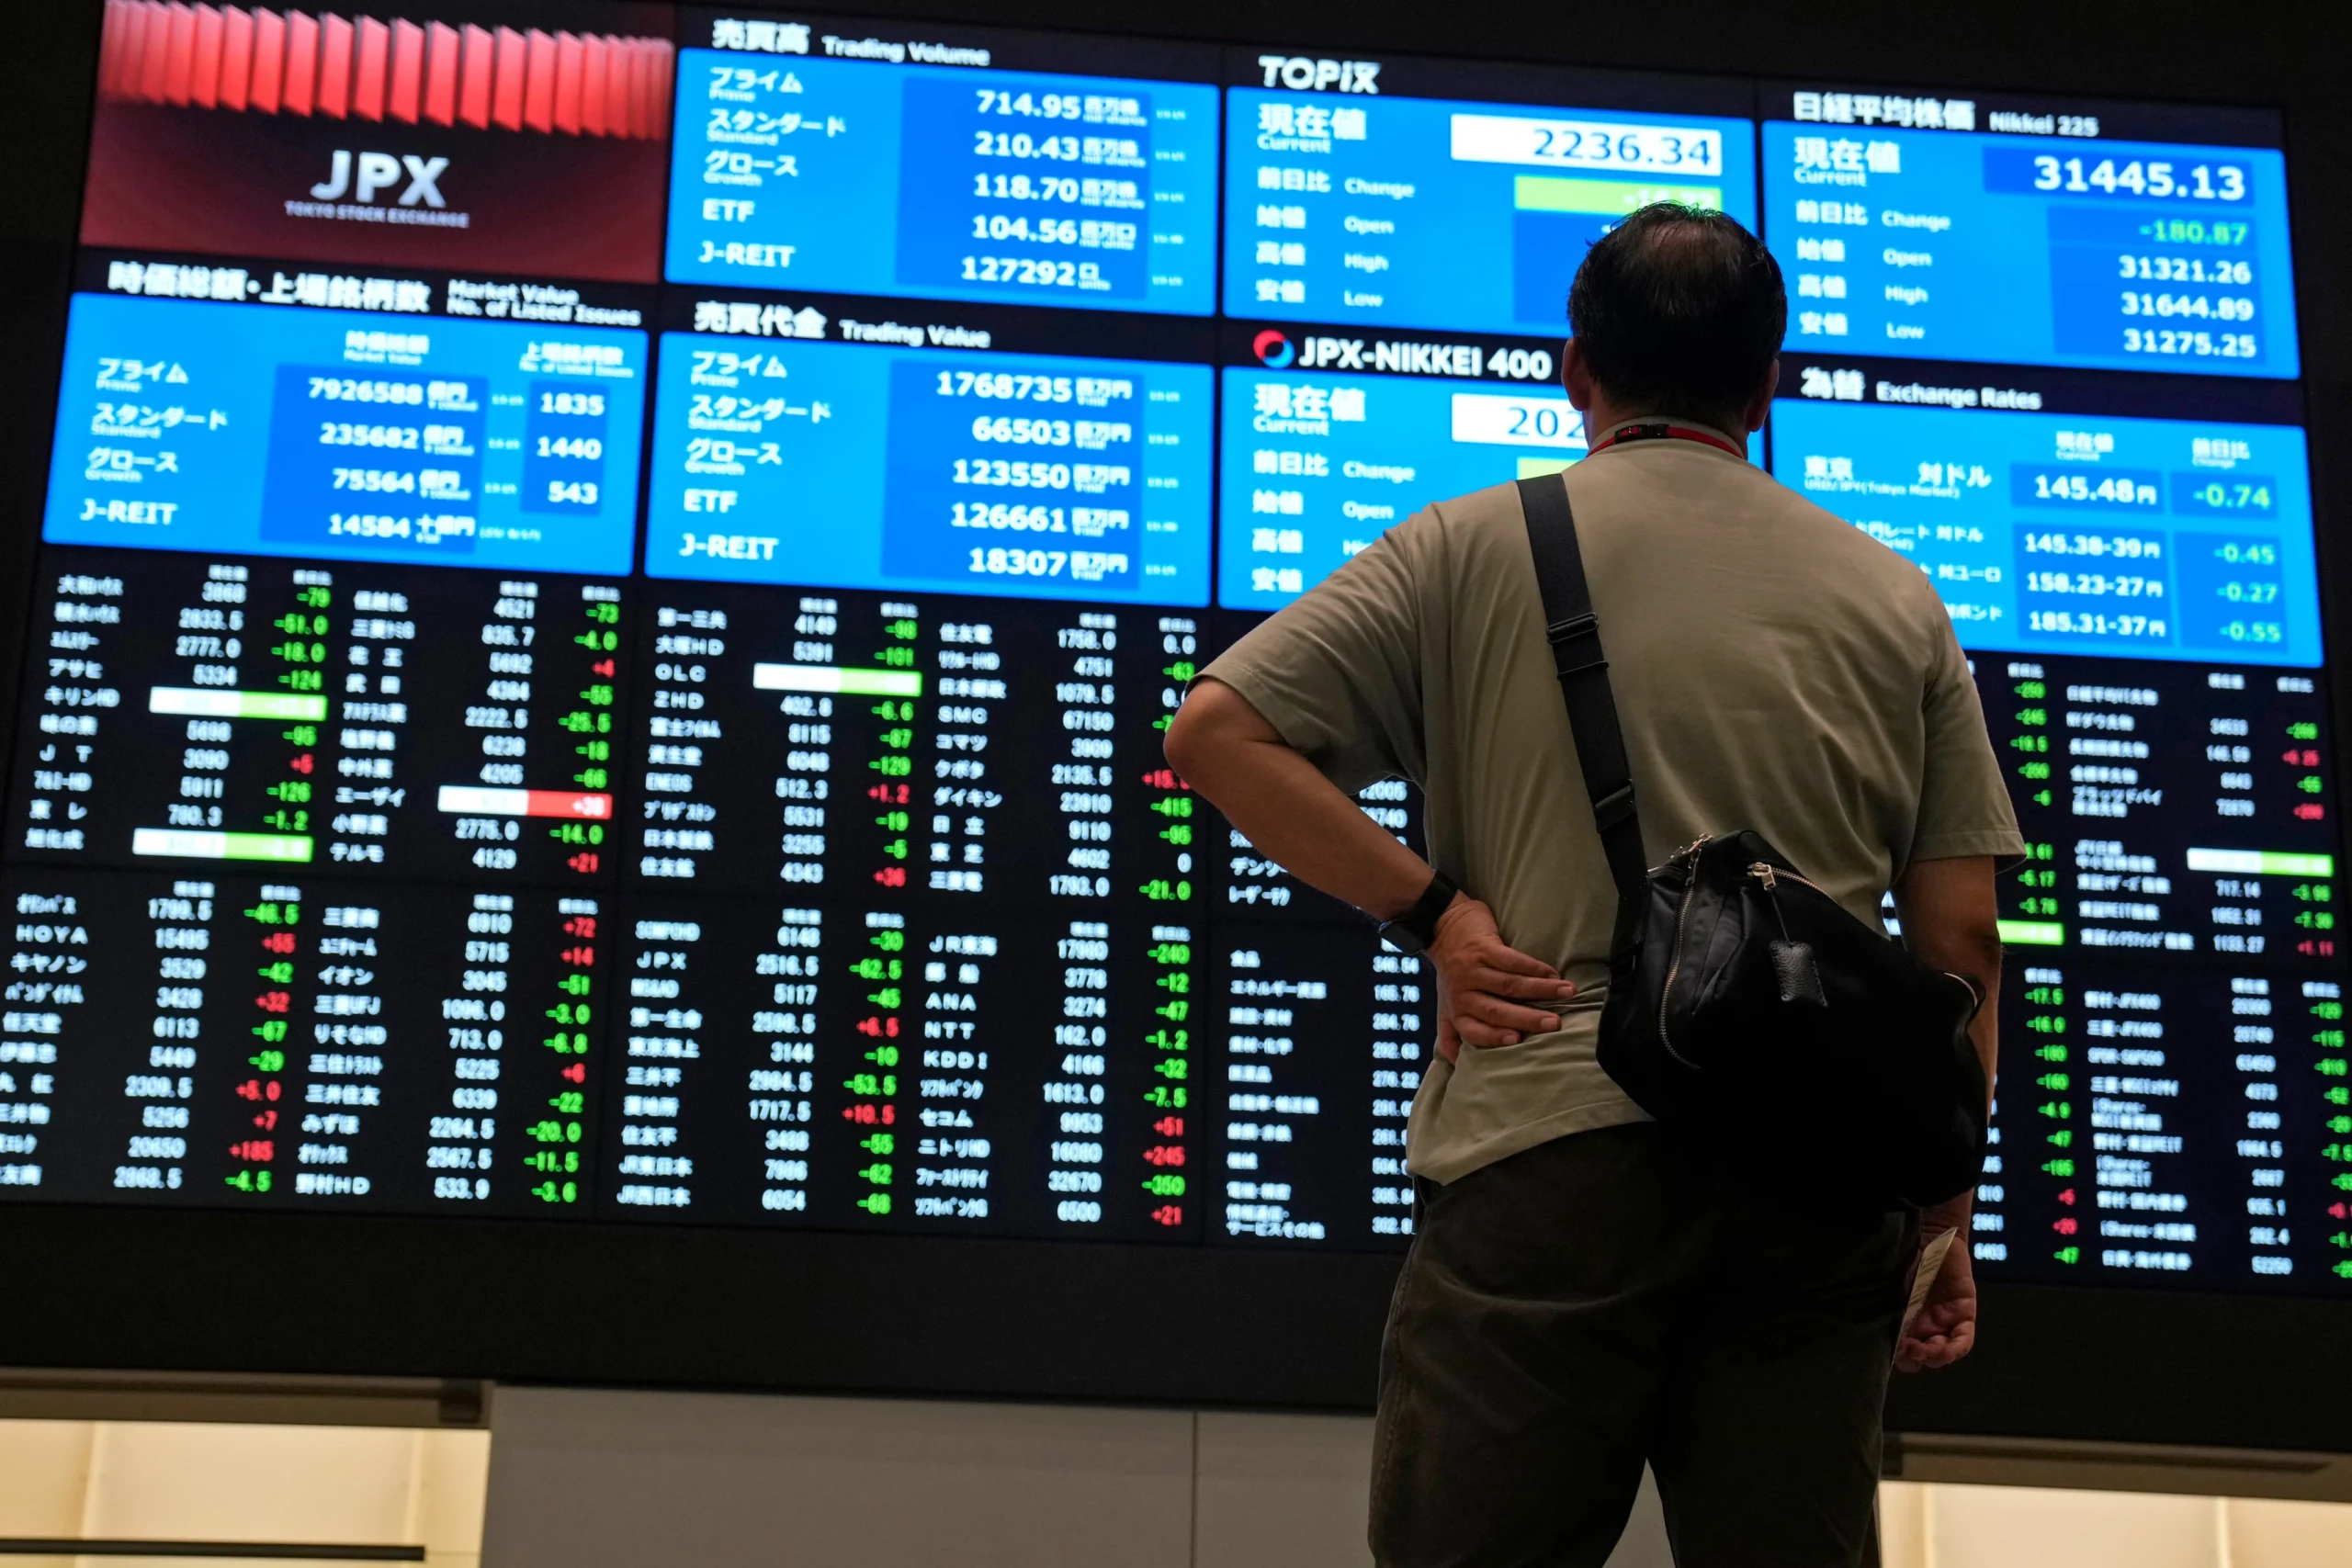
The Nikkei 225 closed at 65,018.95 on September 18, 2026, gaining 1.38% on the session and sitting 44.34% above where it stood a year earlier, according to data compiled by Trading Economics. That move came even as the Bank of Japan raised its policy rate by 25 basis points to 1.25% — a widely expected but still consequential tightening step, as policymakers balance elevated inflation and wage growth against pressure from U.S. Treasury Secretary Scott Bessent for currency and trade cooperation. Japan’s annual inflation rate held at 1.9% in August, with core inflation at 1.7% — below the Bank of Japan’s 2% target for a seventh straight month, suggesting the central bank still has room to normalize policy gradually rather than aggressively.
Technology and AI-related names have led Japan’s rally, with chip-equipment and materials names such as Advantest and Lasertec posting some of the sharpest single-day gains, echoing similar advances on Wall Street. That correlation is a theme across the region: Asian equity performance in 2026 has tracked the U.S. AI-capex story almost as closely as it has tracked domestic fundamentals.
China: AI Optimism Meets an Overheating Warning
China’s equity markets opened 2026 on a tear. The benchmark CSI 300 Index advanced 1.6% to close at its highest level in four years on January 6, while the Shanghai Composite rose 1.5% to its strongest level since July 2015, fueled by sustained optimism over the country’s AI advances and early signs of broader economic recovery, according to Bloomberg. Materials and technology shares led the advance, and the rally coincided with a robust pipeline of onshore AI-related IPOs.
That said, the rally showed early signs of overheating even in January: the 14-day relative strength index on the Shanghai Composite climbed above 75 — firmly into technical overbought territory — a level it had not touched since the previous September. Momentum has been uneven since; by late July, the Shanghai Composite had pulled back to a 16-week low on the CSI 300 gauge even as the broader index posted modest daily gains, reflecting a market still working through the tension between AI-driven optimism and valuation discipline. On the macro side, the IMF’s own China growth revisions this year have tracked a similar push-pull, with earlier 2025 forecasts putting Chinese growth near 4.8% before moderating toward roughly 4.2% as trade and property-sector headwinds persist.
Malaysia and Singapore: Steady Gains, Regional Correlation
Malaysia’s FTSE Bursa Malaysia KLCI has spent much of 2026 grinding toward multi-year highs rather than posting dramatic single-day swings. The index touched a more-than-six-year high near 1,686 points in early January, according to New Straits Times, and by early September had climbed further to around 1,714–1,715 points, per Bursa Malaysia futures data reported by Bernama, Malaysia’s state news agency. Analysts at Rakuten Trade have described the index as being in a healthy uptrend across both short- and long-term timeframes, with pullbacks read as consolidation rather than a change in trend.
Singapore’s Straits Times Index has moved in tandem with regional sentiment through the year, trading in the high-3,900-point range during mid-2026 sessions alongside comparable moves in Hong Kong’s Hang Seng and South Korea’s Kospi — a reminder that Southeast Asian and Northeast Asian benchmarks remain tightly correlated on any given trading day, even when their underlying economic drivers differ.
Pakistan: The Region’s Most Volatile Outperformer
Featured Snippet Target: Pakistan’s KSE-100 Index began 2026 at a record high above 176,000 points, climbed further past 186,000 and 188,000 in the following days on institutional buying and expectations of a policy rate cut, but has since seen sharp single-session pullbacks — including a 3,078-point, 1.79% drop on September 10 — underscoring how the world’s best-performing frontier market in early 2026 has also been among its most volatile.
The Pakistan Stock Exchange’s rally traces back to a shift in domestic asset allocation: brokerage house Topline Securities described the move from fixed-income instruments into equities — driven by falling returns on traditional savings vehicles — as the primary fuel behind sustained liquidity and elevated valuations, according to coverage from Aaj News. Banking names including United Bank Limited, Habib Bank, and MCB, alongside energy majors like Oil and Gas Development Company, have repeatedly featured among the index’s top contributors on both up and down days.
By early September, the picture had turned choppier. The KSE-100 gained 399 points on September 4 to close at 175,328, per ARY News, before dropping over 3,000 points just days later on September 10 — a reminder that Pakistan’s rally, while historic in percentage terms, remains far more sensitive to single-session sentiment shifts than its larger regional peers.
The Cross-Market Pattern
Three threads tie these otherwise disconnected markets together in 2026. First, AI-linked capital spending is now a genuine cross-border driver — Japanese and Chinese tech names have both rallied on echoes of the same U.S. hyperscaler capex story. Second, central bank policy divergence is widening: Japan is tightening from historically ultra-loose settings, while Pakistan has been cutting rates to support a still-fragile broader economy. Third, frontier and emerging markets — Pakistan chief among them — are delivering far larger percentage swings, in both directions, than developed Asian benchmarks, rewarding investors who can tolerate volatility but punishing those who chase momentum without hedging for pullbacks.
The Bottom Line
Asia’s 2026 story is not one market but five distinct ones moving on different clocks — Japan’s AI-and-rate-hike rally, China’s optimism-versus-overheating tension, Malaysia and Singapore’s steadier regional drift, and Pakistan’s high-beta swings around a genuine structural re-rating. Anyone allocating across the region needs a market-by-market view rather than a single “Asia” thesis.
Next step: Track Bank of Japan policy meetings, China’s Politburo economic guidance sessions, and Pakistan’s State Bank Monetary Policy Committee decisions together — the three events, spaced through the remainder of 2026, are the clearest near-term catalysts for each market’s next move.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The World Bank’s June 2026 assessment carries a phrase that should stop any investor mid-scroll: a “lost decade” of development for many emerging markets.
Global growth is projected to slow from 2.9% in 2025 to 2.5% in 2026 — the lowest rate since the COVID-19 pandemic — amid weaker prospects for energy-importing economies and those directly affected by hostilities.
Within that aggregate, Asia is splitting into two distinct groups. Understanding which side an economy falls on is now the primary emerging-market allocation decision.
Key Takeaways
- Global growth: 2.5% in 2026, firming in 2027–28 as energy supplies recover and trade strengthens.
- The revision was brutal. January 2026 projected 2.6% with an upward revision; June cut it.
- India remains the outlier. FY2026-27 growth of 6.6%, rebounding to 7.2% in FY2027-28.
- China decelerates. Growth slowing to 4.4% in 2026 from 4.9%.
- The 2020s are on track to be the weakest decade for global growth since the 1960s.
The Two Reports That Define 2026
The World Bank publishes Global Economic Prospects twice a year, and the gap between the January and June 2026 editions is the story.
January: Cautious Optimism
The January report described a global economy proving more resilient than anticipated despite persistent trade tensions and policy uncertainty, with growth easing to 2.6% in 2026 before rising to 2.7% in 2027 — an upward revision from the previous June forecast.
About two-thirds of that upgrade came from the United States alone.
June: The Energy Shock
By June, the Middle East conflict had driven sharp energy price increases and the projection fell to 2.5%, with emerging market and developing economies facing the weakest per capita income growth since the pandemic.
The Bank explicitly notes that the conflict’s impact on global trade has been partly offset by robust AI-related investment, while consensus inflation expectations picked up notably following the energy price surge. Local-currency bond yields and external bond spreads remained higher in commodity importers.
That last sentence is the whole emerging-market thesis in one line: commodity importers are paying more to borrow at exactly the moment they need to borrow more.
Asia’s Two Tiers
| Economy | Projection | Position |
|---|---|---|
| India | 6.6% FY26-27, 7.2% FY27-28 | Domestic-demand-led, upgraded |
| China | 4.4% in 2026 (from 4.9%) | Export-supported, stimulus-dependent |
| EMDEs (all) | 4.0% in 2026 (from 4.2%) | Slowing |
| EMDEs excl. China | 3.7% in 2026 | Flat versus 2025 |
| United States | 2.2% in 2026 | Tax-incentive supported |
The EMDE-excluding-China figure of 3.7%, unchanged from 2025, is the number that matters most and gets quoted least. Strip out China, and the developing world is not slowing — it simply is not accelerating. Stagnation at a level too low to close income gaps.
The India Case
India stands apart in the June projections. Growth is projected to moderate to 6.6% in FY2026-27 — a 0.1 percentage point upgrade relative to January — before rebounding to 7.2% in FY2027-28, a 0.6 point upgrade.
The moderation reflects private demand cooling under input cost pressures. The rebound reflects structural factors:
- Trade agreements. Implementation of major FTAs with the EU, UK and Australia is described as crucial to offsetting cooling merchandise demand from traditional Western markets.
- FDI sustainability. Trade agreements and structural business reforms are expected to sustainably support inflows across the forecast horizon.
- Fiscal trade-offs. Lower fuel taxes and GST reforms temporarily erode the revenue base, requiring a shift toward slower public capex growth and current spending cuts to avoid deficit spikes.
That last point is the underappreciated risk. India’s growth upgrade is partly financed by revenue concessions that must eventually be reversed or absorbed.
The China Case
China’s projected slowdown to 4.4% in 2026 came with an upward revision of four-tenths of a percentage point from the previous June forecast, attributed to fiscal stimulus and increased exports to non-US markets.
That revision has since been validated by trade data. The question for 2027 is whether export strength can persist if global demand slows to the 2.5% pace the Bank projects.
China’s position is structurally different from India’s: externally driven where India is domestically driven, stimulus-dependent where India is reform-dependent.
What the “Lost Decade” Framing Actually Means
The World Bank’s language is deliberately stark. If current forecasts hold, the 2020s are on track to be the weakest decade for global growth since the 1960s and too low to avert stagnation and joblessness in emerging market and developing countries.
The distributional evidence is concrete: at the end of 2025, nearly all advanced economies enjoyed per capita incomes exceeding their 2019 levels, but about one in four developing economies had lower per capita incomes than before the pandemic.
Chief Economist Indermit Gill framed the underlying tension precisely: the global economy has become less capable of generating growth while appearing more resilient to policy uncertainty — a divergence he warned cannot persist without fracturing public finance and credit markets.
Investment Implications by Tier
Tier 1 — Energy importers in the technology value chain. India, Vietnam, Malaysia, Taiwan, Korea. AI-related export revenues offset higher energy costs. Currency and equity performance has held up.
Tier 2 — Energy exporters outside the conflict zone. Gulf states excluding those directly affected, parts of Africa and Latin America. Favourable terms of trade, fiscal space expanding.
Tier 3 — Energy importers outside the technology chain. Pakistan, Bangladesh, Sri Lanka, Kenya, much of Sub-Saharan Africa. Higher import bills, higher borrowing costs, no offsetting export windfall.
Tier 3 is where sovereign stress concentrates. Higher local-currency bond yields and wider external spreads in commodity importers mean refinancing costs rise as fiscal positions deteriorate.
What This Means for the Global Market in 2027
The 2027 recovery is conditional on two assumptions. Activity is expected to firm in 2027–28 as energy supplies recover and trade strengthens. Both require the conflict to de-escalate. Neither is guaranteed.
AI adoption is the identified upside. The Bank names artificial intelligence adoption, clean energy investment and regional trade agreements as potential long-term recovery catalysts. Only the first is currently delivering at scale.
Sovereign debt is the accumulating risk. Elevated yields in commodity importers compound every year they persist. A 2027 refinancing wave at current spreads would strain multiple frontier sovereigns simultaneously.
Regional trade agreements are the underrated policy lever. India’s FTA implementation is the clearest test case. If it delivers the projected FDI and export offset, it becomes a template for the rest of emerging Asia.
Compare the IMF and World Bank carefully. The Fund projects 3.0% for 2026; the Bank projects 2.5%. The difference is methodological — PPP versus market exchange rate weighting — not a disagreement about the world.
Frequently Asked Questions
What is the World Bank’s global growth forecast for 2026?
The June 2026 Global Economic Prospects projects global growth slowing to 2.5% in 2026, down from 2.9% in 2025 — the lowest rate since the pandemic.
What is India’s projected GDP growth?
India is projected to grow 6.6% in FY2026-27 before rebounding to 7.2% in FY2027-28, both upgrades relative to January 2026 projections.
Why are World Bank and IMF forecasts different?
The World Bank weights using market exchange rates while the IMF uses purchasing-power-parity weights, which gives more weight to faster-growing emerging economies.
What does “lost decade” mean for emerging markets?
The Bank warns the 2020s could be the weakest decade for global growth since the 1960s, with roughly one in four developing economies having lower per capita incomes at end-2025 than in 2019.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025