
Physical AI
Physical AI and Driverless Tech: The Next Trillion-Dollar Industrial Revolution


Nvidia CEO Jensen Huang called it the “ChatGPT moment for physical AI” at CES in early 2026 — and by September, the capital markets have taken the claim seriously. Physical AI robotics has moved decisively from research demo to commercial deployment: PepsiCo is running 35 driverless trucks on public Arizona highways, Tesla has committed $20 billion in capital expenditure to convert Model S/X production lines into Optimus humanoid robot manufacturing, and venture capital poured $47.4 billion into physical AI startups across 521 deals in just the first half of 2026. This is not a speculative technology narrative anymore — it is an industrial IoT and supply chain automation software buildout with real revenue, real deployed hardware, and a credible multi-trillion-dollar addressable market.
Key Takeaways
- The global physical AI market was valued at $81.4 billion in 2025 and is projected to reach roughly $1.145 trillion by 2035 (33.5% CAGR), with some more conservative estimates putting the narrower AI-robotics segment at $15.24 billion by 2032.
- Humanoid robot shipments in China were revised sharply upward by Morgan Stanley — from 14,000 units at the start of 2026 to a projected 50,000 units by year-end, following Tesla’s own Optimus Gen 3 production ramp.
- Autonomous trucking has crossed from pilot to paid commercial operation: Gatik has completed 60,000 driverless orders incident-free with $600 million in contracted revenue, and Volvo plans to remove safety drivers entirely on U.S. highways by Q1 2027.
- Full trucking automation could save the U.S. economy an estimated $300 billion annually in labor costs, with $100–125 billion in net savings after accounting for technology costs.
- Roland Berger projects the humanoid robot industry alone could reach $750 billion by 2035 and $4 trillion by 2050 — a scale comparable to today’s global automotive industry.
From Pilot to Production: The 2026 Inflection Point
For years, physical AI robotics and driverless tech lived in the same category as flying cars — perpetually five years away. That changed in mid-2026, when a cluster of commercial milestones landed within days of each other. PepsiCo became the first major U.S. consumer-goods company to disclose large-scale autonomous truck use on public roads, running driverless vehicles between bottling plants, storage facilities, and retail customers including Walmart and Dollar General. Simultaneously, Einride completed its business combination and began trading on Nasdaq, and multiple autonomous trucking developers — Aurora, PlusAI, Waabi, Kodiak Robotics — began preparing factory-built, driver-out trucks for mass production rather than retrofitted pilot vehicles.
| Milestone | Company | 2026 Status |
|---|---|---|
| Driverless highway trucking at scale | PepsiCo / Aurora | 35 trucks operating in Arizona |
| Fully driver-out commercial deliveries | Gatik | 60,000 orders completed, $600M contracted revenue |
| 1,000-mile validated driverless lane | Aurora Innovation | Fort Worth–Phoenix, 250,000+ driverless miles, zero system-attributed collisions |
| Long-haul paid delivery with no human in cab | Bot Auto | Houston–Dallas (230 miles) completed |
| Full safety-driver removal target | Volvo Autonomous Solutions | Q1 2027, U.S. Sunbelt corridor, 300+ trucks by end of 2027 |
| Humanoid production scale-up | Tesla Optimus | $20B capex; Gen 3 with 22 degrees of freedom, 50 actuators |
The Regulatory Map Is Catching Up
Autonomous freight is no longer operating in a legal gray zone in its core markets. Over half of U.S. states now have autonomous truck testing or operation rules, and 24+ states explicitly permit self-driving trucks, led by Texas, Arizona, Florida, Arkansas, and Nebraska — where the majority of current commercial operations run. Both Aurora and Gatik briefed the FMCSA and NHTSA ahead of launching driverless operations, establishing a federal engagement pattern other operators are now following. Internationally, Japan is targeting Level 4 autonomous trucks in 2026, UN regulatory harmonization for autonomous vehicles is expected by mid-2026, and Dubai has launched Apollo Go robotaxis via Uber with an explicit goal of 25% autonomous transportation by 2030.
The Humanoid Robot Market: From Demonstrators to Factory Floors
The industrial IoT story of 2026 isn’t just wheels — it’s hands. Hyundai Motor Group debuted its Atlas humanoid robot for production settings at CES 2026, and BMW Group is deploying Figure AI’s Figure 02 humanoid to improve productivity, safety, and consistency in automotive operations. Tesla’s Optimus Gen 3, now in production at the Fremont facility, features 22 degrees of freedom and 50 actuators — a meaningful dexterity leap that is the underlying justification for Tesla’s unprecedented $20 billion capex commitment to convert core vehicle production lines toward robot manufacturing, the single largest physical-AI capital investment made by any automotive OEM to date.
| Market Sizing Estimate | 2025/2026 Baseline | Long-Term Projection | Source Methodology |
|---|---|---|---|
| Broad physical AI market | $81.4B (2025) | $1.145T by 2035 (33.5% CAGR) | Kaiso Research |
| Narrower AI-robotics component | $0.89B (2025) | $15.24B by 2032 (47.2% CAGR) | Edge AI/perception-focused definition |
| Humanoid robotics specifically | ~$4.2B (2026) | $40.5B by 2033 (38.2% CAGR) | Industrial + service applications |
| Humanoid industry (long-run) | — | $750B by 2035 / $4T by 2050 | Roland Berger |
The variance across these estimates — spanning more than a factor of three — reflects genuine definitional disagreement in the industry: some trackers count only AI-native perception/planning software, others include the full hardware, sensor, and actuator supply chain. What’s consistent across every methodology is the direction and steepness of the growth curve, not the exact terminal number.
Where the Capital Is Actually Flowing
Investment in supply chain automation software and industrial IoT is concentrated in a few clear categories:
- Logistics and warehousing — the single largest application vertical by 2026 market share, spanning autonomous forklifts, pick-and-pack robotics, and warehouse fleet orchestration software.
- Automotive manufacturing — both as a deployment site (BMW, Hyundai) and as a capital source (Tesla’s Optimus pivot).
- Long-haul freight — Aurora, Gatik, Kodiak, Waabi, Bot Auto, and Volvo Autonomous Solutions collectively represent the most commercially mature driverless segment.
- Compute infrastructure — Nvidia’s Isaac GR00T and Cosmos models underpin a large share of the perception and planning stack across multiple manufacturers, making Nvidia a structural beneficiary regardless of which individual robotics vendor wins.
Amazon, notably, already operates over 1 million robots handling roughly 75% of its global fulfillment volume, illustrating that at true hyperscale, physical AI has already moved well past the pilot stage into core operational infrastructure — a preview of where the broader industrial economy is heading.
Risk Factors Every Investor and Operator Should Price In
| Risk Category | Detail |
|---|---|
| Deployment pace overstatement | IFR (International Federation of Robotics) takes a more conservative view than industry vendors, noting real-world humanoid deployment remains largely limited to demonstrators/pilots, with true commercialization sitting later in China’s 2026–2030 plan period |
| Battery and power limitations | Cited as a persistent technical constraint on humanoid endurance and continuous operation |
| Labor market disruption framing | Industry voices like Gatik’s VP of Government Relations argue automation is complementing, not replacing, the existing truck-driver workforce — a narrative distinction with real policy implications |
| Capital concentration risk | A small number of players (Tesla, Nvidia, Amazon, Figure AI, Aurora) account for a disproportionate share of both funding and deployed units |
| Cybersecurity and compliance readiness | Analysts now cite this as mandatory for global and regional market access, not an optional add-on |
FAQ
How large is the physical AI market expected to become? Estimates vary by methodology, but the most-cited long-run figures point to roughly $1.1–1.15 trillion by 2035 for the broad physical AI market, with the humanoid robotics segment alone potentially reaching $750 billion by 2035 and $4 trillion by 2050.
Are driverless trucks actually operating commercially today, or is this still a pilot technology? Both, depending on the operator. Companies like Gatik and Aurora have moved beyond pilots into paid, driver-out commercial operations with real contracted revenue, while others are still in supervised testing phases. Volvo has publicly committed to full driverless highway operations by Q1 2027.
Which industries are adopting physical AI robotics fastest? Logistics and warehousing hold the largest current market share, followed closely by automotive manufacturing and long-haul freight. Amazon’s fulfillment network, handling roughly 75% of its volume via over 1 million robots, represents the most mature large-scale deployment today.
What is the biggest risk to the physical AI investment thesis? Deployment-pace overstatement is the most commonly cited risk — more conservative industry bodies like the IFR note that real-world humanoid deployment remains largely limited to demonstrators and pilots, with full commercialization likely later in the decade than some vendor projections suggest.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Tesla increasingly appears in market conversation as a bet on machines that sense and act in the physical world. The umbrella term “physical AI” covers autonomous driving, robotics, machine perception and control systems. Tesla’s stock appeal to some investors now extends far beyond the number of cars it sells. Yet the company’s existing manufacturing business remains essential because it generates the reported revenue and operating data from which investors can judge the cost of developing future products.
This tension creates a more interesting question than whether Tesla is a “robot stock” or a conventional automaker. How much of today’s business can support heavy investment in a future that may be valuable but is not yet fully deployed or proven at commercial scale? October offers two fresh reference points: Tesla’s third-quarter deliveries disclosure and a regulatory change in how its driver-assistance software is described in Europe.
What the third-quarter vehicle numbers actually show
In its October 2 investor-relations disclosure, Tesla reported 486,532 vehicle deliveries and 464,391 vehicles produced during the third quarter of 2026, as well as 13.7 GWh of energy-storage deployments. It scheduled its third-quarter financial results for October 21, 2026. These are units and storage volumes, not a substitute for revenue, net income, automotive margins or free cash flow, which were not included in that delivery announcement.
The breakdown also matters. Tesla reported 478,237 Model 3/Y deliveries, while other models accounted for 8,295. The concentration illustrates how important the high-volume core lineup still is. A reader should resist two common errors: treating a delivery beat as proof that margins grew, or treating investment in new technology as proof that the old business is no longer financially relevant.
An earnings review should compare realized selling prices, manufacturing costs, inventory, cash generation and capital investment—not simply quarterly unit growth. Those variables determine how much operating flexibility Tesla has when it chooses to fund long-horizon programs.
The physical AI thesis has distinct parts
Autonomous cars and humanoid robots rely on overlapping capabilities, including computer vision, decision-making and real-world control, but they are not the same business. A vehicle can use assisted-driving software while still requiring an attentive human driver. A fully driverless commercial operation demands different validation, redundancy, regulation, insurance and operational support. A robot used within a structured factory environment faces different challenges from one expected to work in unpredictable households.
Investors should separate demonstrations, limited deployments, approved service territories and broad commercial availability. Each marks a different stage of technical and business maturity. A promising demonstration may show capability without establishing that hardware can be built cheaply, insured affordably, serviced reliably and operated with acceptable safety results at large scale.
Why the European software name change matters
Reuters reported on October 9 that Tesla changed the name of its “Full Self-Driving” feature on several European websites to “Tesla Assisted Driving,” in the context of ongoing regulatory scrutiny and efforts to secure broader approval. The United States continued using “Full Self-Driving (Supervised)” in its branding. The name change is a product-marketing and regulatory development; it does not, by itself, tell investors whether a specific vehicle has become more or less capable.
Words like “self-driving” can create unrealistic assumptions about driver responsibility. Consumer-facing reporting should use the terminology regulators and official manuals apply to the particular jurisdiction and version. Approval in one place cannot be automatically generalized worldwide. Markets and roads vary in permitted use, required human supervision and applicable safety laws.
The robotaxi unit economics test
A profitable robotaxi model needs more than software that handles a route. It also needs high utilization, low intervention rates, an operating license, cleaning and charging systems, maintenance, insurance, support staff and a cost structure competitive with existing transportation options. An app can attract riders quickly, but the business only becomes compelling when revenue per vehicle comfortably exceeds depreciation, operations and service costs.
A simple editorial framework is to track hours active per vehicle, fare revenue per hour, empty miles, paid intervention events and monthly ownership costs. These figures should be reported only when disclosed or independently measured. Creating a precise return-on-investment estimate using promotional demos would give readers false confidence. Safety performance must be interpreted relative to operating conditions rather than cherry-picked mileage totals.
If the business works, it could create recurring revenue and deepen Tesla’s customer relationship. If the scaling effort is expensive or regulated narrowly, the company could spend heavily for a service whose economic contribution initially remains small.
Optimus and the industrial-robotics opportunity
The attraction of humanoid robotics is straightforward: a general-purpose machine could potentially perform tasks that would otherwise require multiple specialized systems. But commercial production and repetitive demonstrations differ. Robot safety, dexterity, endurance, battery replacement, maintainability and workplace integration all affect whether a deployment is economically viable.
A manufacturer may buy robots for predictable factory functions before approving them for customer-facing or domestic work. That intermediate path can be commercially important even if widespread household deployment is distant. Tesla could benefit from shared engineering across cameras, chips, batteries and motion control, but those synergies should be quantified through operating results when possible, not assumed from the existence of shared technology.
What higher rates do to Tesla’s strategy
Physical AI is capital intensive. Factories, vehicles, computing clusters and advanced tooling must be paid for before all expected future revenues arrive. In September, the Federal Reserve lifted its target range to 3.75%–4.00%, and long-dated Treasury yields were materially higher in October. Higher required returns generally place greater valuation pressure on cash flows expected far into the future.
That does not mechanically predict Tesla’s share price. Stock performance reflects earnings, risk sentiment, competition, optionality and expectations as well. But it increases the importance of cash generation from actual sales today. A company able to self-fund an emerging technology has different financing choices from one dependent on repeatedly raising expensive capital.
Competitors are solving adjacent problems
Legacy automakers, EV specialists, autonomous-vehicle companies, software developers and robotics manufacturers compete across different parts of Tesla’s future plans. Some focus on constrained autonomous environments; others prioritize driver-assistance features sold into millions of cars. Industrial robotics providers often target narrow tasks where safety and productivity are easier to demonstrate.
Tesla’s advantage, if it emerges, may come from scaling integrated hardware and software. A competitor’s advantage may come from specialization, regulatory experience or faster partnership deployment. Editorial analysis should avoid comparing a prototype robot with an established industrial automation business as if both are delivering the same product today.
What to ask on the October 21 earnings call
First, how did vehicle sales translate into gross profit and operating cash flow? Second, what was spent on AI computing, capacity expansion and robotics—and which portions may be recurring? Third, what safety, approval or service milestones were achieved in autonomy? Fourth, has energy storage become a stabilizing earnings contributor or does its growth require outsized additional capital?
The answer could be a mixed picture. Vehicle deliveries may look strong while prices pressure margins; autonomy may make technical progress without material revenue; energy deployments may grow but demand capital. An article that examines these effects separately will be more useful than one declaring an unequivocal victory or failure based on a single headline.
Frequently asked questions
Is Tesla only an automaker?
No. Tesla also develops energy and autonomy technologies, but vehicles remain central to its measurable current operating scale.
How many cars did Tesla deliver in Q3 2026?
Tesla reported 486,532 deliveries in its October 2 release, ahead of full earnings scheduled for October 21.
Does “Full Self-Driving” mean full autonomy everywhere?
No. Product branding, supervised operation, permitted capabilities and jurisdiction-specific approvals must be checked separately.
Is Optimus revenue already large enough to determine Tesla’s value?
This article does not establish that. Meaningful investor analysis requires disclosed commercialization, volume, profitability and deployment evidence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
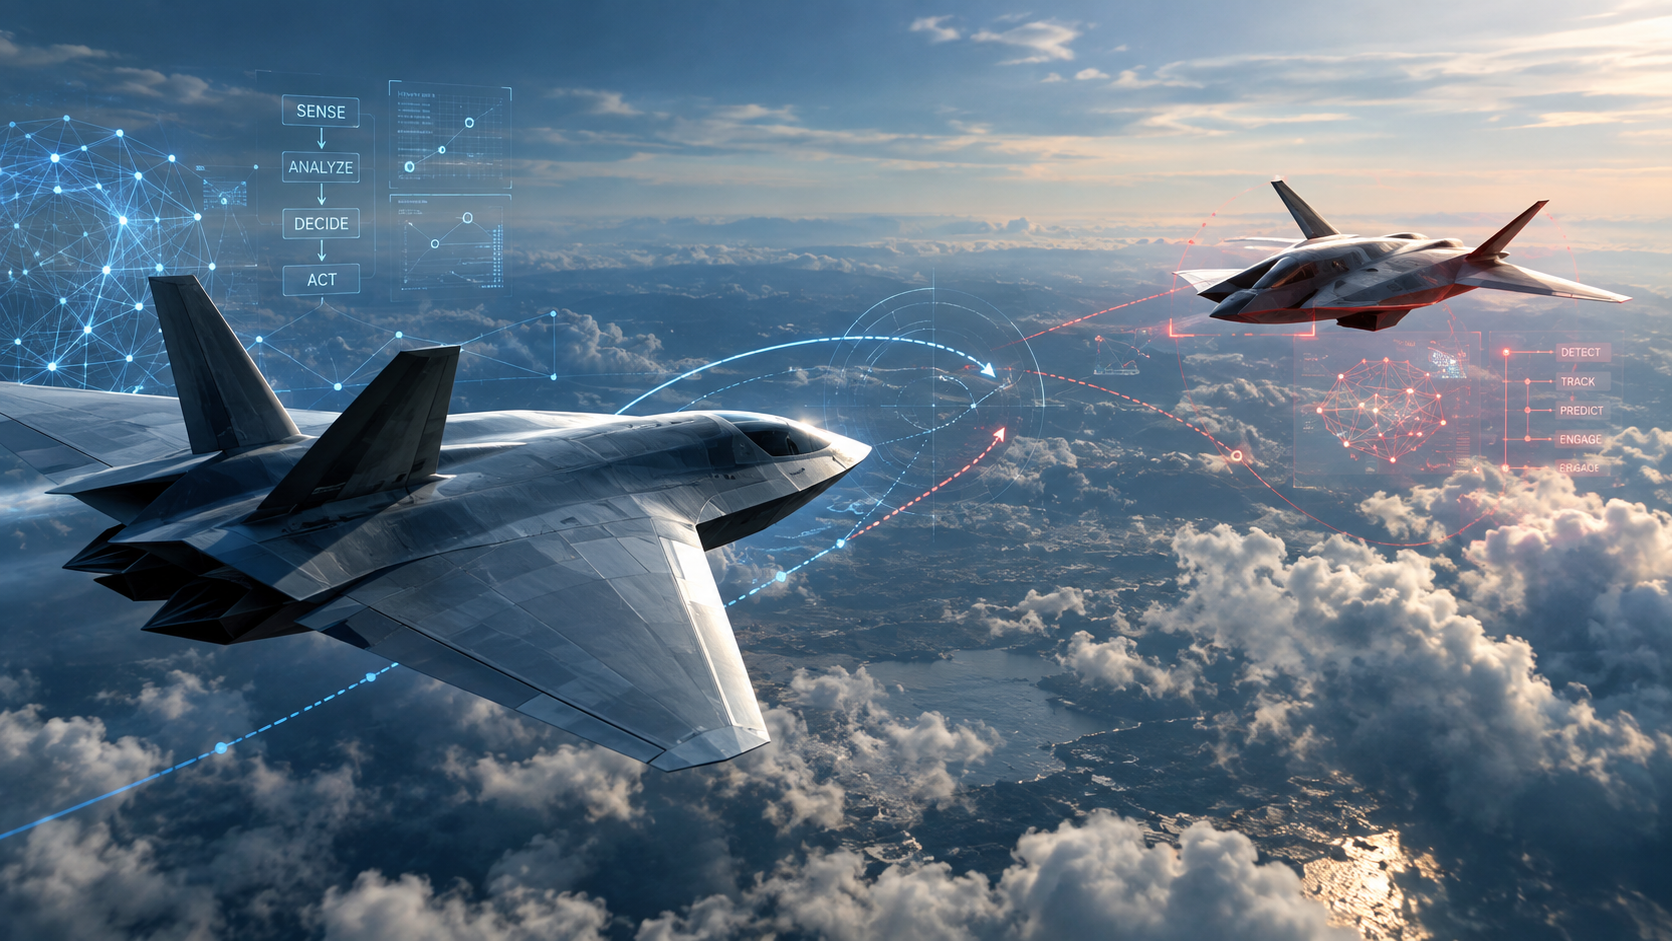
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025