
Analysis
Pakistan Budget 2026-27: Top 10 Proposals Explained

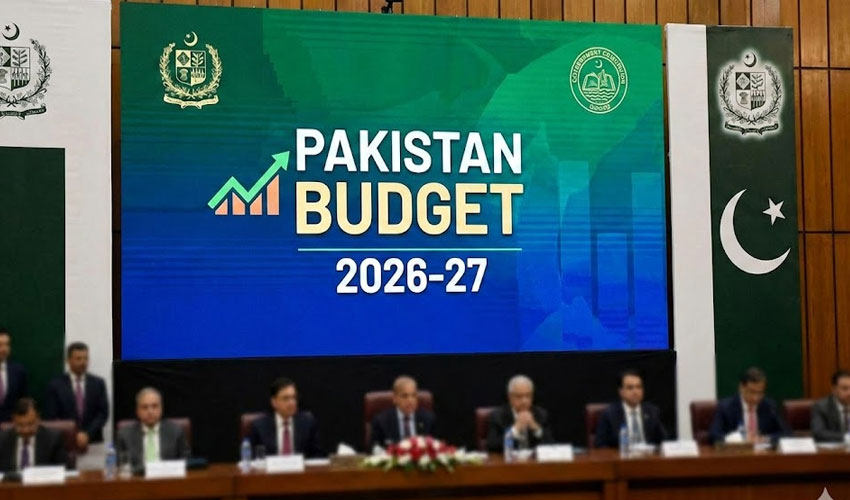
Pakistan is preparing its most consequential federal budget in years — one that must simultaneously satisfy the International Monetary Fund, relieve a battered middle class, and lay the economic groundwork for a country trying to graduate from perpetual crisis management. The stakes, as Finance Minister Muhammad Aurangzeb and his team head into final negotiations with an IMF staff mission currently stationed in Islamabad, could not be higher. With the budget expected in the first week of June 2026, here are the ten proposals shaping Pakistan’s fiscal direction for the year ahead.
The Fiscal Tightrope: Understanding Pakistan’s Budget 2026-27 Context
Pakistan enters this budget cycle with something it hasn’t had in years: momentum. Inflation has receded from its painful peak, foreign exchange reserves have been partially rebuilt, and the current account deficit is projected at roughly 1% of GDP, or approximately $4 billion. Yet the constraints are equally real.
The IMF’s latest staff report sets a federal revenue target of Rs17.145 trillion for FY2026-27 — a 13.5% increase over the current year, or more than Rs2 trillion in additional mobilisation. Federal Board of Revenue collections must reach approximately Rs15.264 trillion. To bridge the gap, Islamabad has committed to roughly Rs430 billion in new budgetary measures, combining tax policy tweaks, enforcement drives, and an 18% hike in the petroleum levy target to Rs1.73 trillion.
Meanwhile, negotiations between Pakistan and the IMF remain active, with the two sides still divided over growth projections — the government targets 4.1% GDP growth, the IMF forecasts closer to 3.5%. The fiscal deficit target of approximately 3.5% of GDP, and a primary surplus of 2% of GDP, are non-negotiable IMF conditions.
This is the arithmetic that frames every proposal listed below.
What are the key proposals in Pakistan’s Budget 2026-27?
Pakistan’s Budget 2026-27 focuses on ten core reforms: income tax relief for the salaried class, BISP expansion, FBR digitalisation, energy tariff reform, PSDP growth, IT sector incentive renewal, agricultural taxation, SOE privatisation, debt maturity extension, and governance improvements. The budget targets Rs17.145 trillion in federal revenues under IMF programme conditions.
The Top 10 Pakistan Budget 2026-27 Proposals
1. Income Tax Relief for the Salaried Class
The single most politically sensitive proposal in this budget is also among its most fiscally consequential. The salaried class contributed more than Rs425 billion in income taxes during the first nine months of FY2025-26 — making it, per capita, the most heavily taxed segment of Pakistan’s economy. That burden is plainly unjust when large swathes of the retail, wholesale, and agricultural sectors remain outside the tax net entirely.
The proposal under active discussion involves reducing income tax rates across salary brackets, with a potential increase in the tax-free annual income threshold beyond the current Rs600,000 floor. For earners between Rs600,000 and Rs2.5 million annually — the vast majority of Grade 1 through Grade 18 government employees — even a modest rate reduction translates into meaningful take-home pay improvement without any formal salary hike.
The government’s preferred approach appears to be using fiscal space freed from subsidy rationalisation to fund this relief rather than borrowing headroom. It’s politically elegant: workers get real money without triggering the IMF’s concern about wage-bill expansion.
Why it matters: Pakistan loses talent to the Gulf, Canada, and the UK partly because net take-home pay in formal employment is compressed by tax rates that exceed regional comparators. Reducing that burden supports formalisation and signals to the skilled workforce that the system is not entirely stacked against them.
2. BISP Expansion and Targeted Social Protection
As blanket power subsidies get capped — provisionally at Rs830 billion, or 0.6% of GDP — the political and social weight of that reduction must be redistributed through direct cash transfers. The Benazir Income Support Programme is expected to expand meaningfully, with monthly Kafaalat stipends potentially rising to Rs18,000 per family, up from current levels, channelled through the National Socio-Economic Registry database.
IMF structural benchmarks explicitly require maintaining the real value of the Kafaalat unconditional cash transfer through inflation-linked adjustments by January 2027. This is not charity — it is a structural condition attached to continued programme support.
The proposal also involves tightening BISP’s targeting mechanism. Roughly 40% of Pakistan’s population remains economically vulnerable, according to IMF assessments, yet leakage in social transfer programmes has been a persistent concern. Digitising federal and provincial government payments by June 2027, another IMF benchmark, should reduce that leakage substantially.
The tension here is real: a government committed to fiscal consolidation cannot simultaneously expand transfer payments and cut taxes without finding offsetting savings elsewhere. Where those savings come from is the budget’s central distributional question.
3. FBR Digitalisation and Tax Administration Overhaul
Pakistan does not merely have a revenue problem. It has a structural problem with how revenue is collected. Business Recorder has flagged for years what the World Bank’s own 2023 policy note confirmed: the country extracts disproportionately from a narrow compliant segment while leaving large, politically influential sectors effectively undertaxed.
The budget is expected to accelerate FBR digitalisation — mandatory e-invoicing, AI-driven audit selection, and electronic POS integration for Tier-1 retailers. These are not new ideas. What’s new is the IMF’s insistence on measurable benchmarks and the government’s willingness, partly under external pressure, to actually deploy them.
A “Pakistan Single Window” for domestic business operations — proposed in multiple policy papers circulating ahead of the budget — would reduce the compliance burden that forces businesses to spend more time defending tax classifications than expanding production.
What the data reveals: Pakistan’s tax-to-GDP ratio hovers around 10-11%, one of the lowest in Asia. Raising it requires not higher rates on existing taxpayers, but bringing the untaxed into the net. Every percentage point gained on that ratio is worth approximately Rs500 billion at current GDP scale.
4. Energy Sector Reform: From Blanket Subsidies to Cost-Recovery Tariffs
Pakistan’s circular debt — the accumulated unpaid liabilities cascading through the power sector — has become a fiscal black hole. The budget will formalise a shift away from blanket electricity subsidies toward cost-recovery tariffs for those who can afford them, with targeted BISP-linked support for those who cannot.
Semi-annual gas tariff notifications on July 1, 2026 and February 15, 2027, plus an annual electricity tariff adjustment due by January 2027, are now IMF structural benchmarks. These aren’t optional recommendations — they are programme conditions. Missing them risks triggering a halt in IMF disbursements.
Power subsidies are expected to be capped at approximately Rs830 billion, with savings redirected toward development spending and social protection. The petroleum levy target of Rs1.73 trillion — up 18% — will also add to household fuel costs.
The second-order question is whether politically difficult tariff adjustments can be implemented without triggering the kind of public backlash that has derailed similar reforms in the past. The government’s answer, implicitly, is that targeted BISP support plus income tax relief provides enough cushion to absorb the shock.
5. Public Sector Development Programme: Modest Growth, Sharper Focus
The federal PSDP is expected to see modest growth to around Rs986 billion from Rs873 billion this year, with provincial development spending projected at Rs2.5 trillion. Some reports place the ceiling closer to Rs1.1 trillion for the federal component, which would represent the most ambitious development allocation in several years.
The composition of PSDP spending matters as much as its size. The proposal involves shifting resources toward climate-resilient infrastructure, water security, and digital connectivity — areas aligned with the IMF’s Resilience and Sustainability Facility, which carries $1.4 billion in available financing for Pakistan’s green transition.
A government that earmarks PSDP spending for high-multiplier projects — roads that reduce logistics costs, power infrastructure that enables industrial activity, irrigation that boosts agricultural yields — generates far more fiscal return per rupee than one that funds prestige projects or political patronage schemes.
Caution is warranted: Pakistan’s PSDP utilisation rate has historically been poor, with large percentages of allocated funds remaining unspent by year-end. More money without better project management simply inflates the headline number.
6. IT Sector Incentives and the 0.25% Export Tax Renewal
Few budget decisions carry as much signalling weight per rupee as the renewal of the IT sector’s concessionary tax rate. Under Section 154A of the Income Tax Ordinance, Pakistan Software Export Board-registered entities currently benefit from a 0.25% final tax on IT export proceeds. That incentive expires on June 30, 2026 — the last day of the current fiscal year.
The Express Tribune and Business Recorder have both flagged this expiry as a critical decision point. Pakistan’s IT sector generated approximately $3.2 billion in exports in FY2024-25. The government’s stated target is $7.5 billion by 2027. Allowing a tax incentive that costs relatively little but signals commitment to the sector to quietly expire would send precisely the wrong message to a workforce already weighing whether to stay or emigrate.
The proposal to extend and potentially expand IT sector incentives — alongside a coordinated federal-provincial effort to harmonise sales tax treatment of domestic IT services — is among the budget’s lower-cost, higher-impact options. It should be a straightforward yes.
7. Agricultural Taxation: Closing Pakistan’s Most Glaring Loophole
Agriculture contributes roughly 24% of Pakistan’s GDP and employs nearly 40% of its workforce. It contributes a fraction of that proportional share in tax revenue. This is not an accident — it is a design feature of a tax system historically shaped by the interests of large landowners with political influence.
The World Bank’s own policy notes have identified Pakistan’s undertaxed agricultural and real estate sectors as the primary source of fiscal inequity. The IMF has consistently pushed for provincial agricultural income tax reforms as a condition of programme compliance.
The budget proposal involves mandating that provinces — which hold constitutional authority over agricultural taxation — implement minimum agricultural income tax rates aligned with those paid by the corporate sector. Several IMF benchmarks now incorporate this requirement explicitly. Whether provinces comply in substance, rather than just on paper, remains the key implementation risk.
What changes if this works: Even modest agricultural income tax collection — moving from the current near-zero effective rate to 1-2% of agricultural GDP — could yield Rs150-200 billion in additional annual revenue without raising a single rate on the salaried class.
8. SOE Privatisation and Reform
Pakistan’s state-owned enterprises collectively represent one of its largest and least-discussed fiscal drains. The Pakistan International Airlines, Pakistan Steel Mills, and dozens of other entities absorb billions in implicit and explicit subsidies annually while delivering poor services and haemorrhaging value.
The IMF’s structural benchmarks require amending PPRA rules by September 2026 to eliminate preferential treatment for SOEs in non-competitive procurement. That’s a process reform. The more ambitious budget proposal involves accelerating the privatisation pipeline — moving loss-making entities off the government’s balance sheet before the IMF programme concludes in late 2027.
The timeline is tight. Privatisation transactions require legal preparation, investor due diligence, and market conditions that can’t be manufactured on a budget cycle’s schedule. That said, even a credible commitment to a privatisation roadmap changes investor sentiment and reduces the implicit contingent liabilities that rating agencies attach to Pakistan’s sovereign risk profile.
9. Debt Servicing Strategy: Managing the Rs7.8 Trillion Gorilla
Debt servicing in FY2026-27 is projected at approximately Rs7.8 trillion — up from Rs7.3 trillion this year, and by far the single largest line item in the federal budget. This reality exposes Pakistan’s ongoing vulnerability to global interest rate movements and rupee dynamics, as the bulk of domestic debt is short-term and must be continuously rolled over at prevailing market rates.
The budget proposal involves lengthening the maturity profile of domestic debt — issuing more long-dated government securities to reduce rollover risk — and continuing the effort to issue Panda Bonds and other international instruments that diversify the creditor base. Pakistan issued its first Panda Bond in 2024, opening access to Chinese capital markets as a partial alternative to the IMF’s expensive conditionality.
The State Bank of Pakistan has also been tasked with developing a roadmap for gradual foreign exchange regime liberalisation by March 2027. A more transparent FX regime reduces currency risk premiums embedded in Pakistan’s borrowing costs. Even 50 basis points of risk-premium reduction on the domestic debt stock would save Rs35-40 billion annually in interest payments.
10. Governance Reform: Accountability, Anti-Corruption, and Digital Payments
The final proposal is also the hardest to price. Pakistan’s IMF programme now includes a requirement to identify the ten most corruption-prone government institutions by end-2026, subject them to detailed audit, and begin publishing annual statistics on corruption investigations and prosecutions by January 2027.
Alongside this, the government has committed to digitising all federal and provincial government payments by June 2027 — a reform that simultaneously reduces leakage, improves cash flow management, and generates the data trail needed for meaningful fiscal oversight.
The IMF has also directed Pakistan to enhance the autonomy and transparency of the National Accountability Bureau through merit-based selection reforms submitted to parliament.
These governance proposals don’t appear as line items in the budget. Their cost is political, not fiscal. Yet their implementation — or failure — will determine whether the structural reforms attached to everything else in this list actually take root or evaporate the moment the IMF programme concludes.
What Hangs in the Balance
The arithmetic of Pakistan’s FY2026-27 budget is demanding but achievable. The IMF has given the government enough room to include meaningful income tax relief, expanded social protection, and modest development investment — provided Islamabad delivers on revenue mobilisation, energy pricing reforms, and governance benchmarks simultaneously.
That “provided” is doing a great deal of work.
Pakistan has a long institutional memory of budgets that read well in June and unravel by October, when revenue shortfalls trigger supplementary tax measures and development cuts. The difference this cycle, arguably, is that the IMF’s structural benchmarks are more granular and more enforceable than in previous programmes. The third tranche was disbursed, the fourth review is underway, and Islamabad has more to lose from programme derailment than at any point since 2019.
As Pakistan’s primary surplus target of 2% of GDP by June 2026 is met, the conversation shifts from survival to architecture. This budget, if it holds together, is the first in a decade that could begin the slower, harder work of building an economy that doesn’t need rescuing every three years.
Whether it does will depend less on what’s announced in Parliament in early June than on what actually happens in July, August, and every difficult month that follows.
The budget is a document. What matters is delivery.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025