
Analysis
China Property Developers Bet on Chips — and Markets Are Falling for It

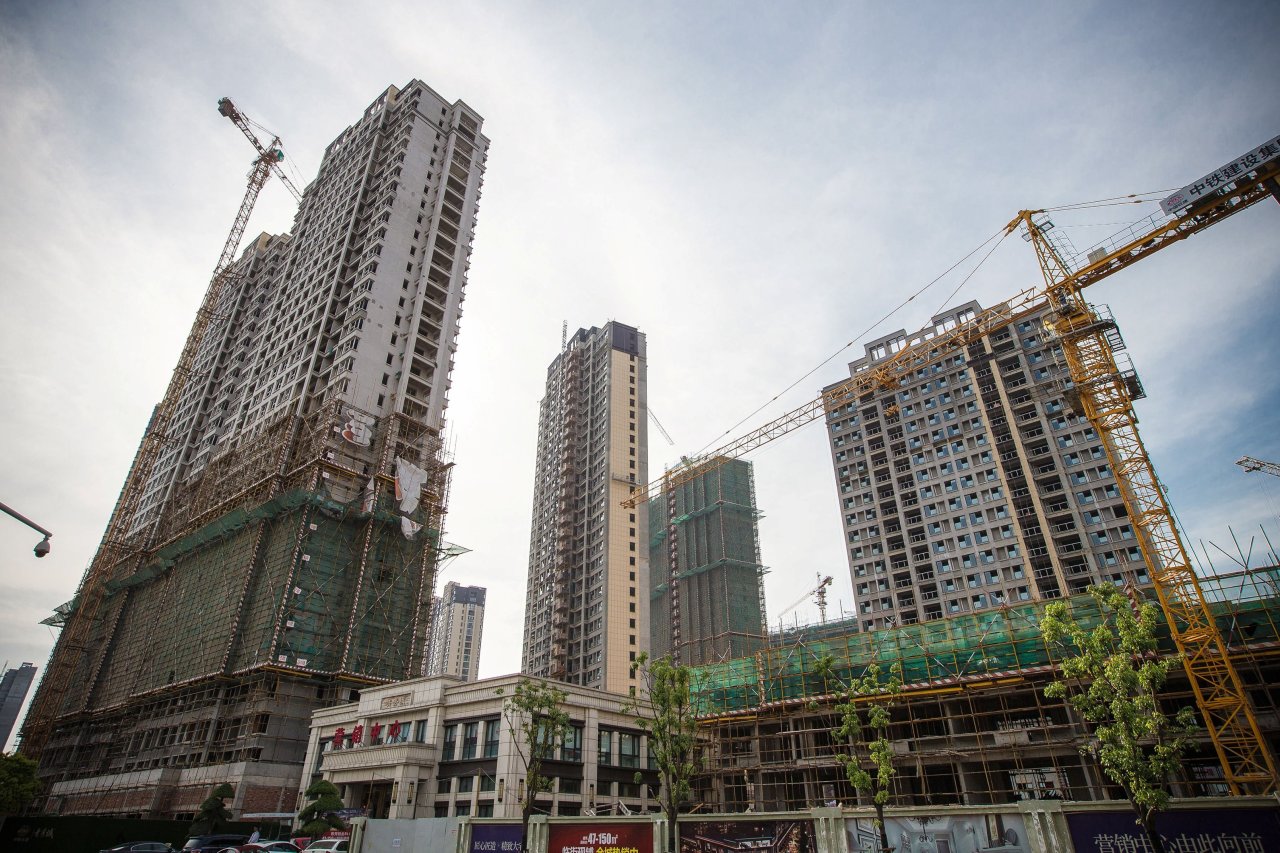
On May 13, 2026, shares in Metro Land hit China’s 10 per cent daily trading limit. The catalyst was not a debt restructuring deal, a government rescue, or even a surprise profit. It was a single announcement: the loss-making Beijing developer would acquire a 20 per cent stake in Xian Qixin Optoelectronics Technology, a Shaanxi-based firm that uses laser signals to produce semiconductor components. By the close, Metro Land’s stock had risen 389 per cent from its year-end 2025 level. The company had posted a net loss of 1.2 billion yuan the previous year. It didn’t matter. For China’s mainland retail investors, “chip” is currently the most valuable word in the financial lexicon — and the country’s embattled property developers have noticed.
A Sector Searching for a Story
China’s real estate industry has spent five years in controlled demolition. Evergrande defaulted, was ordered into liquidation, and was delisted. Country Garden — once the country’s largest developer by sales — defaulted on dollar bonds and is restructuring offshore debt. More than 70 per cent of Chinese mainland-listed developers expected to report net losses for 2025, according to data compiled by Yicai, with China Fortune Land Development alone projecting a deficit of between 16 billion and 24 billion yuan. The area of new homes sold last year fell 12.6 per cent to 881 million square metres, the fourth consecutive annual contraction. Property, which once contributed roughly a quarter of China’s GDP when related industries were included, is no longer a story investors want to tell.
Semiconductors, by contrast, are exactly the story investors want to tell. China’s STAR 50 Index — home to chip designers including Cambricon, Moore Threads, and MetaX — rose approximately 35 per cent in 2025, supercharged by the geopolitical frenzy that followed DeepSeek-R1’s emergence in January of that year. When Shanghai Biren Technology listed in Hong Kong on January 2, 2026, retail investors oversubscribed the offering 2,347 times. Two sectors: one dying, one ascendant. The arbitrage was obvious — even to people who build apartment blocks.
Section 1: The Chip Pivot and Why Property Developers Are Chasing It
China property developers’ semiconductor investment has taken several forms, from strategic minority stakes to headline-grabbing acquisition announcements that analysts struggle to justify on commercial grounds. Metro Land’s deal is the most visible recent example, but it’s far from unique. The pattern is consistent: a developer announces a move into chipmaking or chip-adjacent technology; A-share retail investors respond with a buying frenzy; the stock surges to daily limit; regulators intervene with questions; the stock retreats. Then the cycle repeats with a different company.
The underlying economics of the deals are rarely flattering. Metro Land, which reported a net loss that widened 15.3 per cent to 1.2 billion yuan in 2025, is acquiring a minority stake in a small laser-optics company — not a foundry, not a chip designer, not a firm with meaningful manufacturing capacity. The Shanghai Stock Exchange issued an inquiry letter within days, demanding the developer clarify the deal’s terms and disclose its financial health in detail. The stock retreated 23.5 per cent. Yet the episode had already done its work: Metro Land’s shares remain dramatically elevated from where they began the year.
The mechanics are rooted in China’s specific retail-investor culture and the political weight now carried by “tech self-reliance” as a narrative. “Chip-themed stocks are the new darlings of individual investors since such stocks play a key role in China’s technological innovation and carry the hopes of the whole nation,” said Ding Haifeng, a consultant at Shanghai-based financial advisory firm Integrity. His warning, though, was pointed. “The fanfare surrounding these companies is just a rude reminder that exchanges on the mainland could become a speculators’ market if company fundamentals are ignored.”
That word — fundamentals — is doing a lot of heavy lifting. The typical property-developer-turned-chip-investor is not acquiring a fabrication facility. It’s buying a small equity position in a company that sounds semiconductor-adjacent, hoping the association is enough to move the market. In most recent cases, it has been — for a few days, at least.
The precedent for this kind of cross-sector grafting isn’t new. During China’s internet boom of the 2010s, textile and food companies rebranded as technology firms to capture speculative flows. During the electric-vehicle surge of 2020-21, traditional manufacturers rushed to announce EV subsidiaries. The chip pivot of 2026 follows the same playbook, dressed in a more urgent geopolitical costume.
2: What the Rally Reveals About China’s Capital Markets — and Its Chip Ambitions
Why are Chinese property developers investing in semiconductors? The direct answer is that they aren’t, not really. They’re investing in the perception of semiconductor exposure, which is an altogether different thing. The distinction matters because it illuminates a structural fault line running through China’s capital markets: the gap between Beijing’s strategic objectives and how those objectives get priced by retail investors chasing momentum.
China’s genuine chip ambitions are vast and state-backed. The country’s 15th Five-Year Plan, covering 2026 to 2030, is expected to prioritise advanced logic process nodes, memory industry expansion, and breakthroughs in lithography, according to analysis from Yole Group. SMIC’s N+2 and N+3 nodes are approaching 7nm/5nm capability. ChangXin Memory Technologies has ambitions for high-bandwidth memory production by the end of this year. These are serious industrial efforts, costing hundreds of billions of yuan and taking decades to compound.
The property developers’ “chip investments” belong to a different universe. They are, at best, peripheral — minority positions in small firms that operate on the edges of the semiconductor supply chain. At worst, they are market-manipulation vehicles that exploit regulatory attention gaps and retail-investor enthusiasm for a politically charged sector.
The featured-snippet question this raises is worth answering plainly: Are Chinese real estate companies’ chip investments commercially legitimate? Broadly, no. Most announced property-developer chip deals involve negligible capital allocation into companies with limited manufacturing capability, positioned to capture share price appreciation rather than semiconductor output. Regulators at the Shanghai and Shenzhen exchanges have responded with inquiry letters, demanding clarity. But enforcement has been slow relative to the speed at which new announcements emerge.
The deeper irony is that the companies doing this are, in many cases, a drag on the very capital pools that China’s genuine chip sector needs. Institutional money being sucked into speculative property-developer rebounds is money not flowing toward the foundry expansions, equipment manufacturers, and EDA software developers where China’s strategic priorities actually lie. Shen Meng at Chanson & Co. has argued that A-share valuations may be detaching from economic logic, with new listings serving as “political symbols more than proven market disruptors.”
3: Downstream Consequences — for Markets, Regulators, and the Chip Industry
The second-order effects of this pattern run in several directions, not all of them obvious.
For China’s securities regulators, the property-to-chip pivot presents a familiar dilemma: how to protect retail investors from speculative excess without suppressing the patriotic investor enthusiasm that Beijing has spent years cultivating. The semiconductor sector’s political valence makes heavy-handed intervention tricky. A regulator who crashes a chip-themed stock rally risks being framed as an obstacle to tech self-reliance. The Shanghai Stock Exchange’s use of inquiry letters — essentially a public demand for explanation — is the least disruptive tool available, but it’s a brake, not a stop sign.
For legitimate chipmakers, the noise created by property-developer announcements has a subtler cost. When every company that acquires a 15 per cent stake in an optics firm gets treated as a semiconductor play, the analytical frame for the entire sector degrades. Moore Threads Technology, which listed in Shanghai in early 2026, reported losses that narrowed by up to 41 per cent in 2025 as revenue rose 247 per cent — real operational progress. Grouping that kind of result with a Beijing developer buying into a laser company distorts how the market prices genuine progress.
For international investors watching China’s market structure, the episode signals something worth noting. China’s property crisis has not produced the clean capital reallocation that a textbook deleveraging cycle would suggest. Instead of distressed developers liquidating and releasing capital toward productive sectors, many are performing a kind of market magic: conjuring value through association, staying listed through narrative gymnastics, and deferring the reckoning that their balance sheets demand. The government’s preference for “soft landings” in the property sector — avoiding mass defaults to protect social stability — has inadvertently enabled this.
The Hang Seng Tech Index’s 23 per cent gain in 2025 reflects genuine enthusiasm for companies like Biren and Cambricon, whose revenues are growing and whose technology, while still trailing Nvidia’s by several years, is closing the gap in specific application domains. Conflating that trajectory with property developers playing dress-up does neither story justice.
4: The Counterargument — Perhaps the Market Knows Something
Not everyone is dismissive. There’s a case — steel-manned, not strawmanned — that property developers pivoting toward semiconductors is economically rational, however messy the execution.
The argument runs like this: China’s property sector will not recover to its previous scale. Urbanisation has slowed, demographic headwinds are structural, and Beijing has made clear that the era of treating housing as a speculative asset is over. Developers with listed shells, existing management teams, and some residual capital need to find a new reason to exist. The semiconductor industry, heavily subsidised and politically prioritised, is the obvious destination. Some of those minority stakes — even in small companies — may eventually connect developers to supply chains that matter.
Country Garden’s venture arm had, before the developer’s collapse into crisis, built a 1.68 per cent stake in ChangXin Memory Technologies, which was valued at close to 140 billion yuan as of March 2024. That position, held before the chip-investment craze fully took hold, was a genuine early-mover bet on a serious company. The fact that Country Garden was forced to sell it to repay debts says more about its liquidity crisis than about the quality of the underlying investment.
The counterargument also points to history. Japan’s postwar industrial policy saw shipbuilders and textile firms successfully transition into electronics. South Korea’s chaebols built semiconductor empires on foundations that had nothing to do with silicon. Diversification under duress is not always theatre; sometimes it plants seeds that grow.
Still, the conditions for that kind of transition — patient capital, long industrial planning horizons, genuine technological investment — are conspicuously absent in the current wave of property-developer chip deals. Buying a 20 per cent stake in a laser-optics company to escape a stock exchange inquiry is not industrial policy. It is, as Ding Haifeng put it, an invitation for the A-share market to become a speculators’ circus.
Closing: The Price of a Narrative
China’s semiconductor ambitions are real, costly, and gathering momentum. The state’s commitment to chip self-reliance — through the Big Fund, through the 15th Five-Year Plan, through the patient cultivation of firms like SMIC, YMTC, and CXMT — is not in question. What is in question is whether the capital markets that are supposed to support that ambition can distinguish between the genuine article and a real estate company in a borrowed lab coat.
Metro Land’s share price, now sitting at 15.96 yuan after its brief ascent to 20.85 yuan, tells you everything. The 389 per cent rally was not a market verdict on the company’s chipmaking capabilities. It was a verdict on how easily the word “semiconductor” can be weaponised in a market hungry for a national hero story. The retreat, prompted by a regulator’s letter, was the market correcting what it never should have priced in the first place.
Beijing’s policymakers face a choice they haven’t yet made cleanly: encourage the retail enthusiasm that keeps property-developer stocks alive and A-share sentiment elevated, or enforce the analytical rigour that China’s genuine semiconductor champions actually deserve.
You can’t do both. Not for long.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
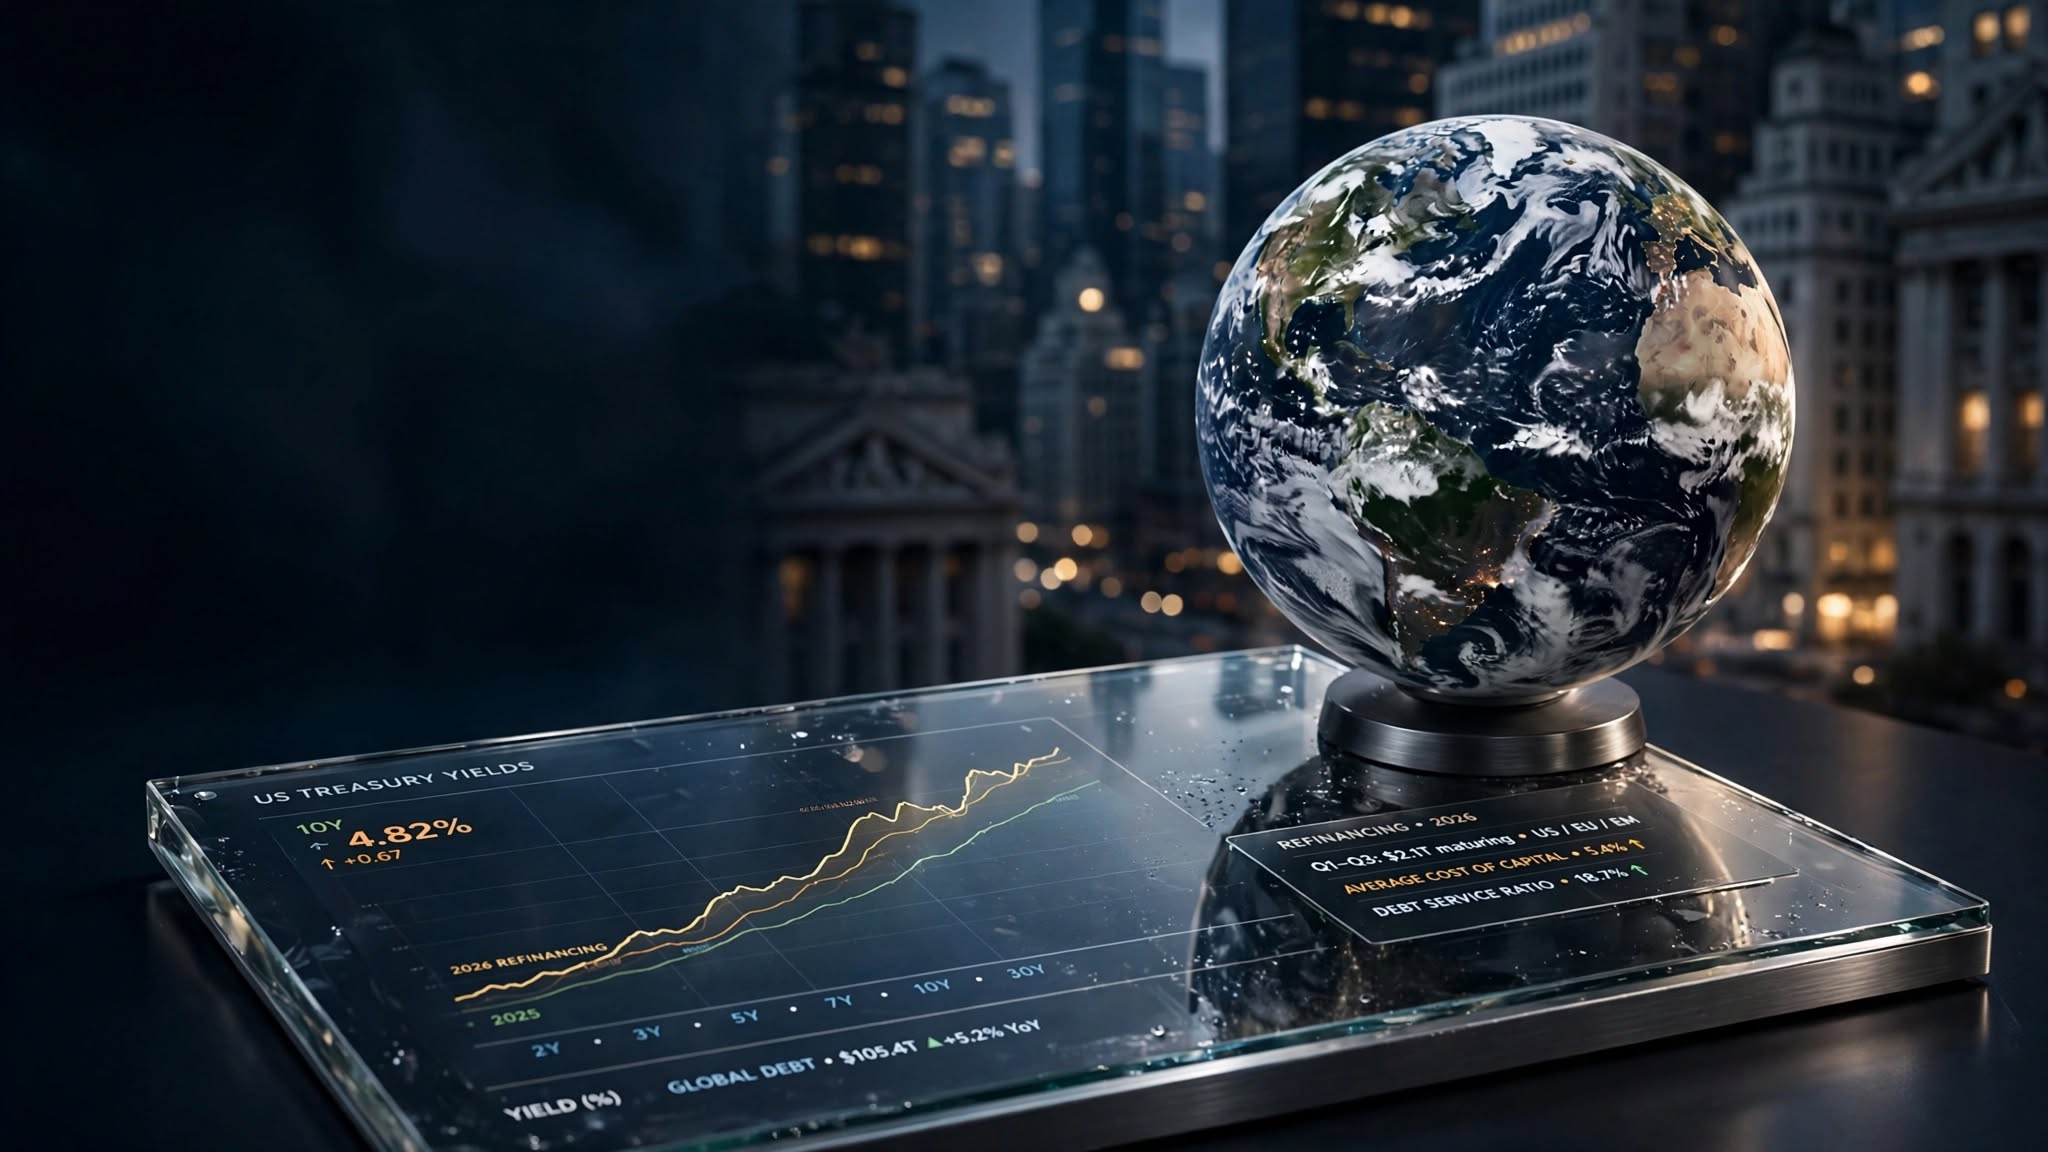
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
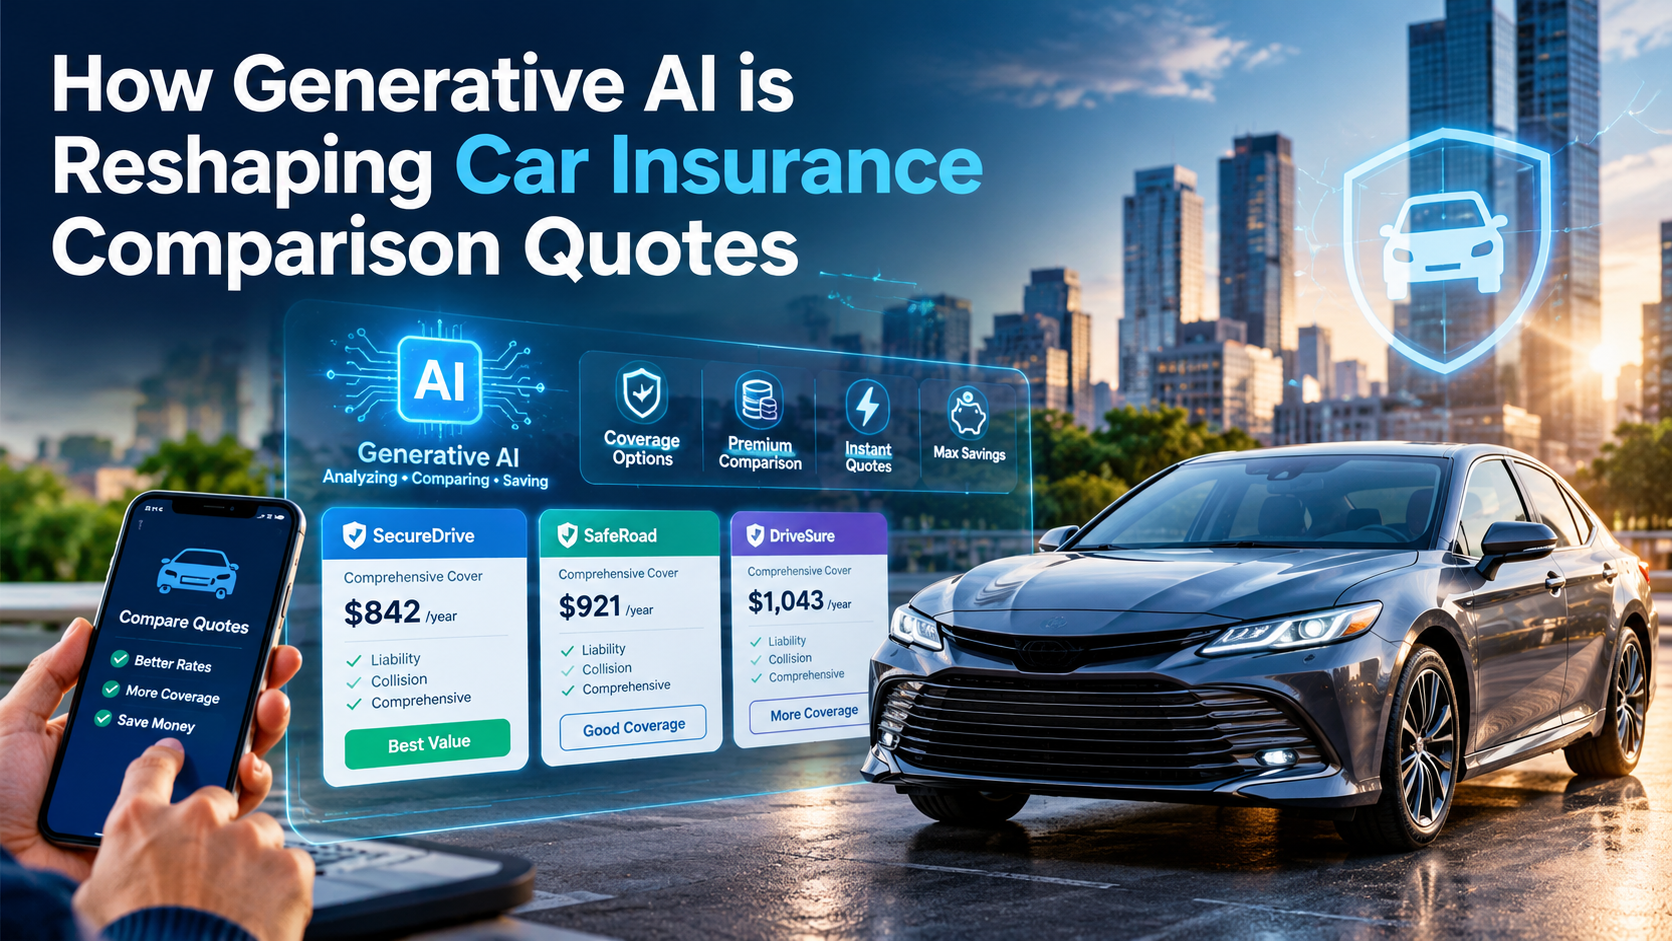
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

Tesla Physical AI 2026: Robotaxis, Optimus and TSLA Risks

NVIDIA’s AI Grip in 2026: Record Revenue Is Only Half the Investment Story

Hormuz Diesel Shortage: Why Crude Oil Recovery Isn’t Enough

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Jeff Bezos Three-Day Workweek View: What He Really Said

Celeste Frozen Pizza Discontinued: What Conagra Confirmed

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Stock Market Today: Dow Climbs 500 Points as Markets Shake Off Inflation Jitters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025