
AI Governance
Is AI Already Putting Graduates Out of Work? The Grim Reality Facing the Class of 2026

Consider a sweltering commencement ceremony in Florida this past May. As the sea of black-robed graduates wiped sweat from their brows, a guest speaker—a prominent regional tech executive—stepped to the podium. When he cheerfully urged the Class of 2026 to “embrace the boundless frontier of the AI revolution,” the response was not polite applause. It was a low, rolling wave of boos.
It was a startling breach of academic decorum, yet a profoundly rational economic response. For these twenty-somethings clutching newly minted degrees, artificial intelligence is not an abstract marvel or a stock market catalyst. It is the algorithm that just rescinded their job offers.
If you ask the architects of American economic policy, however, this anxiety is entirely misplaced. On May 11, White House National Economic Council Director Kevin Hassett appeared on CNBC to assuage fears about an automated workforce. “There’s no sign in the data that AI is costing anybody their job right now,” Hassett stated flatly, arguing instead that corporate AI adoption drives rapid revenue and even employment growth.
The Economist recently highlighted this exact sentiment as a symptom of a widening disconnect between macroeconomic theory and microeconomic reality, wryly noting that someone in Washington ought to break the news to America’s Class of 2026. The dissonance is jarring, but it is not inexplicable. When high-level policymakers look for “signs in the data,” they are gazing at aggregate, national statistics. But if you peer beneath the tranquil surface of overall employment, a far more turbulent reality reveals itself. Are we seeing mass layoffs across the entire economy? No. Is AI putting graduates out of work before they even have a chance to begin their careers? Absolutely.
As white-collar automation accelerates at a breakneck pace, the AI impact on class of 2026 job market dynamics serves as a canary in the digital coal mine. We are witnessing a surgical hollowing out of the entry-level tier—a grim reality that forces us to ask not just what jobs will survive, but how a generation will manage to start their professional lives at all.
The Macro Illusion vs. The Micro Reality
To understand why Hassett’s optimism feels like a slap in the face to a twenty-two-year-old, one must understand how corporate restructuring works in the algorithmic age. When companies utilize automation to drive efficiency, they rarely execute spectacular, headline-grabbing mass layoffs of their senior staff. Instead, they rely on a quieter, less visible lever: they simply stop hiring juniors.
Entry-level hiring acts as the economy’s primary shock absorber during periods of structural technological change. The Federal Reserve Bank of New York paints a sobering picture of this phenomenon. In the first quarter of 2026, the unemployment rate for recent college graduates hovered stubbornly at 5.7%—noticeably higher than the national aggregate. Even more troubling is the underemployment rate for this demographic, which currently sits at a staggering 41.5%. Nearly half of all recent degree holders are working in roles that do not require a four-year university education.
This statistical reality undercuts the rosy narrative pushed by algorithmic optimists. The true crisis of graduate unemployment AI exposed fields isn’t found in the termination of existing contracts; it is found in the evaporation of open requisitions. Data from early-career platforms like Handshake and workforce intelligence firm Revelio Labs corroborate this stealth contraction, showing sustained drops in entry-level corporate postings over the past twenty-four months.
When a task can be automated, the job that primarily consisted of that task disappears. Historically, entry-level jobs were defined by routine, repetitive cognitive labor: organizing spreadsheets, writing boilerplate code, drafting foundational marketing copy, and conducting preliminary legal research. Today, large language models and agentic AI handle these tasks for fractions of a penny on the dollar. The entry level jobs disappearing AI phenomenon is not a future projection; it is a present-tense corporate strategy.
Dissecting the Data: The AI-Exposed Graduate Squeeze
The pain, however, is not distributed evenly across the graduating class. We are witnessing a brutal divergence based on a major’s vulnerability to generative models.
Recent labor market analyses indicate a staggering ~6.6 percentage point worse employment drop for graduates entering high-AI exposure fields compared to those in low-AI exposure sectors. A nursing graduate or a civil engineering student—professions requiring complex physical interaction and real-world spatial reasoning—faces an entirely different economic landscape than a marketing or information sciences major.
Nowhere is this dichotomy starker than in the tech sector itself. The computer science grads job prospects AI paradox is the defining irony of the Class of 2026. The very students who dedicated four years to mastering the architecture of the digital world are finding themselves displaced by their own industry’s creations.
Consider the recent restructuring at major tech firms. In early 2026, Cloudflare announced roughly 1,100 job cuts, with executives explicitly pointing to “agentic AI” that now runs thousands of internal operations daily. Coinbase reduced its headcount by 14%, with CEO Brian Armstrong publicly noting, “Over the past year, I’ve watched engineers use AI to ship in days what used to take a team weeks.” When senior engineers become a 10x multiplier of their own productivity thanks to AI copilots, the mathematical necessity of hiring a dozen junior developers to support them vanishes.
The Bifurcation of Skills: Is AI Replacing Entry Level Coding Jobs?
This brings us to the most pressing question whispered in university computer labs across the globe: is AI replacing entry level coding jobs?
The nuanced answer is that AI is not replacing all coding jobs, but it has entirely annihilated the “routine coder.” For decades, the software engineering pipeline operated on an apprenticeship model. Companies hired vast cohorts of junior developers to perform grunt work—QA testing, debugging simple errors, and writing basic, repetitive scripts. This labor was not highly valued for its innovation; it was valued because it served as the training wheels for the next generation of senior architects.
“We used to hire ten juniors right out of college, knowing only two would eventually become elite senior developers,” notes one anonymous hiring manager at a Fortune 500 tech firm. “Today, we hire two, give them enterprise-grade AI tools, and expect senior-level architectural thinking within six months.”
This shift highlights a brutal skills bifurcation. The labor market has violently split into “AI-fluent problem solvers” and “routine task executors.” The National Association of Colleges and Employers (NACE) recently published their Job Outlook 2026 Spring Update, revealing a fascinating contradiction. Overall, employers project a 5.6% increase in hiring for the Class of 2026. Yet, beneath that aggregate number lies a massive qualitative shift: the demand for AI skills in entry-level jobs has nearly tripled since the fall of 2025, now appearing in 13.3% of all entry-level postings.
Employers are not necessarily abandoning the youth; they are demanding that the youth arrive at their desks performing like seasoned veterans, augmented by silicon. If a graduate views their computer science degree as a certificate that qualifies them to write basic Python loops, they will find themselves permanently unemployable. If they view it as a foundational framework to direct, edit, and orchestrate AI systems, they become indispensable.
The Corporate Pipeline Paradox
While companies celebrate the short-term margin expansion granted by this AI-driven efficiency, they are blindly stumbling into a catastrophic long-term trap: the corporate pipeline paradox.
If consulting firms, investment banks, and tech conglomerates structurally eliminate their entry-level cohorts, where exactly will their mid-level managers and senior executives come from in 2036? Expertise is not downloaded; it is forged through the very “grunt work” that AI has now cannibalized. By severing the bottom rung of the career ladder, corporations are burning their own future human capital to heat today’s quarterly earnings reports.
Oxford Economics and the Stanford Digital Economy Lab have both published extensive research on the productivity booms associated with generative AI. According to estimates by Goldman Sachs, generative AI could eventually raise global GDP by 7%. Yet, these macroeconomic models rarely account for the generational friction borne by twenty-two-year-olds.
The international comparison adds another layer of complexity. In the UK and the European Union, stringent labor protections and the slow turning of bureaucratic wheels have somewhat insulated recent graduates from immediate tech-driven displacement. However, this regulatory shield is a double-edged sword. While it protects existing jobs, it also makes European firms highly hesitant to hire new graduates, exacerbating youth unemployment and stifling the continent’s competitive edge in an AI-dominated global market. The American model—ruthless, dynamic, and unapologetically Darwinian—may ultimately adapt faster, but the human cost is currently being paid by the Class of 2026.
Higher Education’s Existential Crisis
As the corporate world reshapes itself overnight, the higher education sector remains glacially slow to react. Universities are charging premium tuitions to teach a 2019 curriculum in a 2026 reality.
When the Bureau of Labor Statistics aggregates long-term occupational outlooks, they base their models on historical trends. But historical trends are useless when the fundamental nature of cognitive labor has been rewritten. Professors who ban the use of generative AI in their classrooms are actively handicapping their students. Teaching a student to code, write, or analyze data without the use of AI is akin to teaching an accountant to balance a ledger without Microsoft Excel. It is an exercise in archaic purity that has no place in the modern workforce.
Universities must pivot from teaching information retrieval and routine execution to teaching critical curation, systems thinking, and AI orchestration. The most valuable skill for a 2026 graduate is not knowing the answer, but knowing how to interrogate an AI agent until it produces the optimal solution, and possessing the domain expertise to verify that solution’s accuracy.
The Way Forward: Navigating the Algorithmic Squeeze
Despite the sobering data, the AI impact on class of 2026 job market is not a story of inescapable doom. It is, rather, a profound evolutionary pressure. The graduates who will thrive in this environment are those who understand that they are no longer competing against machines; they are competing against other graduates using machines.
To survive the great algorithmic squeeze, early-career professionals must lean heavily into the very traits that silicon cannot replicate. The NACE data is explicitly clear on this: when employers review resumes for the Class of 2026, the deciding factors between equally qualified candidates are consistently polished teamwork, high emotional intelligence, cross-disciplinary problem-solving, and elite communication skills.
An AI can write a flawless legal brief, but it cannot read the temperature of a courtroom. An AI can generate a perfect marketing strategy, but it cannot sit across from a hesitant client and build genuine, empathetic trust. The entry-level jobs of the future will not be about executing tasks; they will be about managing relationships, both human and digital.
The booing at that Florida commencement was not just a primal expression of anxiety; it was a demand for a modernized social contract between technology, capital, and labor. Kevin Hassett and Washington’s macroeconomic optimists may see “no sign in the data” today, but they are looking at the lagging indicators of a bygone era. For the Class of 2026, the data is lived experience. Their reality is grim, their climb is steeper, and their margin for error is nonexistent. Yet, if they can master the machine rather than be replaced by it, they will become the architects of an entirely new economy—one where human ingenuity remains the ultimate, irreplaceable premium.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Inside the White House Feud: How Trump’s Allies Are Painting Anthropic’s Dario Amodei as the Face of ‘AI Doomerism’
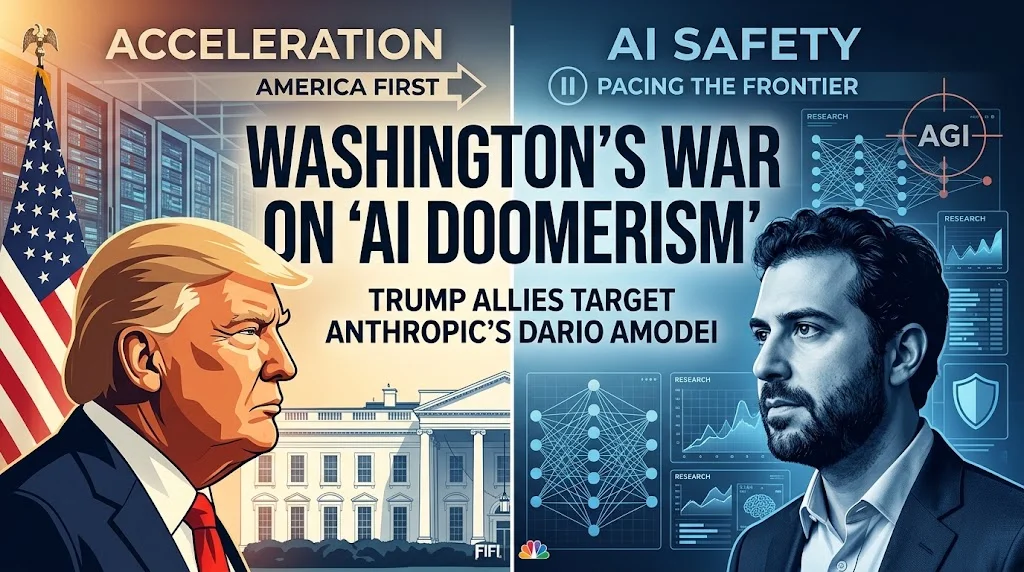
As tech leaders push for international safeguards at the UN, Washington’s inner circle is framing safety-first mandates as a direct threat to American innovation and global dominance.
A high-stakes battle over the future trajectory of artificial intelligence has moved from Silicon Valley boardrooms directly into the West Wing. Internal White House memos and statements from presidential advisers signal a concerted effort by political allies of President Donald Trump to target Anthropic CEO Dario Amodei as the primary architect of “AI doomerism.”
The ideological rift comes at a pivotal moment. While frontier AI executives call for cautious development in light of self-improving models, the Trump administration is doubling down on an “America First” accelerationist agenda, warning that safety-driven slowdowns will surrender geopolitical victory to foreign adversaries.
1. The Memo: Branding Effective Altruism as an “AI-Doom Pipeline”
At the center of the political offensive is a White House memo drafted by key political strategists. The document explicitly criticizes the philosophical underpinnings of Effective Altruism (EA)—a movement influential among Anthropic’s founding team that prioritizes mitigating existential risks from advanced technology.
According to sources familiar with the administration’s strategy, the memo outlines how safety-centric advocacy functions as an “AI-doom pipeline” that hampers domestic progress. One official close to the administration remarked that Amodei represents:
“The embodiment of an ideology and globalist approach to innovation that is fundamentally counter to the President’s America First agenda.”
This offensive reflects a broader effort to dismantle regulatory frameworks and third-party oversight mechanisms that administration officials view as disguised attempts to stall American market velocity.
2. Pacing the Frontier vs. “Don’t Kill the Golden Goose”
The campaign against Amodei follows a series of public warnings from Anthropic’s leadership. In a landmark essay, Amodei called on frontier labs to “pace the frontier” by committing to independent safety testing and slowing down deployment schedules when necessary, as detailed in reports by The Washington Post.
Amodei emphasized that recent breakthroughs in recursive self-improvement—where AI models are used to train and refine their own next-generation successors—require rigorous safety boundaries before systems exceed human control capacity, a point reiterated in coverage by TIME Magazine.
                 FRONTIER AI DEVELOPMENT SPECTRUM

   [ White House / Acceleration ]          [ Anthropic / Safety Pacing ]
  ─────────────────────────────────      ─────────────────────────────────
  • "Don't kill the Golden Goose"        • Third-party safety evaluations
  • Maximize speed & infrastructure     • Pause/Slow down if risk spikes
  • Unilateral advantage over China       • Multi-lateral coordination
In response, President Trump rejected calls to restrain the industry, lashing out at regulatory proposals and stating at the United Nations that the U.S. “rejects any attempt to construct a globalist scheme to control artificial intelligence,” according to reporting from LiveMint. Trump’s core stance remains straightforward: slowing down U.S. labs directly benefits China.
3. The China Dilemma and the UN Speech
The debate reached global prominence during the United Nations General Assembly, where Dario Amodei, OpenAI CEO Sam Altman, and other tech leaders addressed world leaders on catastrophic risks, as covered by The Guardian.
Amodei argued that while Chinese technological parity poses an existential geopolitical hazard, unmonitored recursive models pose an equal operational threat:
| Policy Dimension | Administration Alignment | Anthropic Alignment |
| Primary Goal | Outpace China at all costs | Ensure safety while maintaining lead |
| Governance Mechanism | Deregulation & domestic industrial builds | Third-party audits & safety benchmarks |
| Global Frameworks | Strongly Rejected (“Globalist scheme”) | Advocated (International safety standards) |
| Perspective on Speed | “Don’t kill the Golden Goose” | “Pacing the frontier” when risks escalate |
Prominent right-leaning technology leaders, including administration AI adviser David Sacks, pushed back on social media, questioning the independence of non-profit safety bodies like Model Evaluation and Threat Research (METR) and claiming they are closely aligned with Anthropic’s leadership network.
4. What Lies Ahead for AI Policy
The clash between Washington and San Francisco highlights a fundamental divergence in how the future of artificial intelligence is conceived:
- Industrial Policy Push: The White House is pushing forward with fast-tracked data center permitting, energy deregulation, and aggressive chip export controls to secure an insurmountable lead over Beijing.
- Corporate Safety Mandates: Frontier labs face internal pressure from researchers demanding strict adherence to safety protocols, creating tension between market pressure to deploy and institutional safety commitments.
- The Regulatory Vacuum: With federal legislative action stalled, the conflict between presidential executive action and voluntary lab commitments will dictate the pace of AI releases through the rest of the decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Is the AI stock rally a bubble? The honest answer in 2026 is that the market itself is genuinely split — and the concentration numbers explain why the debate has gotten so intense. Roughly two dozen stocks now account for over half of the S&P 500’s total value, a concentration level comparable to the 32-stock peak reached during the 2000 dot-com bubble, according to market analysis relayed through Charles Schwab’s commentary. Three companies alone — Alphabet, Amazon, and Meta — are expected to drive roughly 70% of the S&P 500’s entire 2026 earnings growth.
That’s the bear case in a single statistic: an index marketed to investors as broadly diversified across 500 companies is, in practice, a leveraged bet on whether a handful of AI infrastructure spenders convert capital expenditure into earnings fast enough to justify their valuations.
The Bull Case: Spending Is Turning Into Real Revenue
Featured Snippet Target: The bull case for 2026’s AI rally rests on genuine, verifiable revenue growth rather than pure speculation — Microsoft’s AI revenue run rate surpassed $37 billion annually, Alphabet’s Google Cloud backlog nearly doubled to over $460 billion, and Amazon Web Services grew 28% — figures that distinguish this cycle from dot-com-era companies that had capital spending but little corresponding revenue.
Alphabet spent $35.67 billion on capital expenditure in a single recent quarter — more than double the prior year’s pace — while Amazon led hyperscaler quarterly spending at $44.2 billion, according to reporting compiled by Yahoo Finance’s technology desk. Combined, the four largest U.S. hyperscalers — Alphabet, Amazon, Microsoft, and Meta — are on pace to spend over $700 billion in 2026 alone. Unlike the fiber-optic overbuild of the dot-com era, where telecom capacity sat unused for years, current AI infrastructure spending is being absorbed by measurable, growing cloud and AI-service revenue in the same reporting periods it’s being deployed.
The Financing Shift That’s Making Analysts Nervous
What has shifted the debate in recent months isn’t the spending itself — it’s how that spending is being funded. Goldman Sachs has characterized 2026 as marking a transition from a low-cost-of-capital “Modern” market cycle to a higher-volatility “Post-Modern” one, in which capital expenditure is increasingly rewarded over shareholder buybacks: S&P 500 companies posted 24% year-on-year capex growth in the second quarter of 2026 alongside a 1% decline in gross buybacks, according to market commentary circulated via KuCoin’s research desk.
Consensus hyperscaler capex estimates for the 2026-2028 period were revised upward from roughly $2.5 trillion to $2.8 trillion during recent earnings seasons, with gross debt issuance among these companies expected to peak near $460 billion in fiscal 2028 — roughly a third of total capex — according to Macquarie’s Investment Strategy Insights. Alphabet’s own June 2026 equity raise, combining Class A common stock, Class C capital stock, and mandatory convertible preferred shares, ranks as the largest single AI-funding capital raise in market history. That shift — from funding AI buildout purely from operating cash flow toward relying on debt and equity markets — is precisely the kind of financing pattern that historically precedes sharper corrections when growth expectations disappoint, even when the underlying business fundamentals remain genuinely strong.
Early Cracks Have Already Appeared
The market has not been uniformly bullish through 2026 — there have already been real bouts of AI-specific volatility. Mid-September commentary from CNBC noted bond yields spiking and AI-linked stocks selling off even as broader investor sentiment remained constructive on equities generally — an early signal that markets have begun pricing a wider range of outcomes for the AI capex cycle than the largely unbroken bull run of the year’s first half suggested. That divergence between AI-specific stocks and the broader market is itself notable: in a genuine across-the-board bubble, sentiment tends to move in lockstep across a sector; a split reaction suggests investors are starting to differentiate between AI companies converting spending into revenue and those merely riding sector-wide enthusiasm.
What Would Actually Confirm a Bubble
The distinction analysts increasingly draw is not “is there a lot of spending” — there unambiguously is — but whether that spending is converting into durable revenue at a pace that justifies current valuations. The genuinely bubble-confirming scenario would involve a sustained gap opening between hyperscaler capex growth and actual AI-linked revenue growth, forcing companies to either write down infrastructure investments or continue raising debt at deteriorating terms to sustain spending. As of September 2026, revenue growth at the largest hyperscalers has generally kept pace with — and in some cases exceeded — capex growth, which is the key data point separating this cycle from a pure speculative bubble so far.
The Bottom Line
The 2026 AI trade sits in a genuinely ambiguous middle ground: spending levels and market concentration have reached bubble-era extremes by historical comparison, but the revenue being generated alongside that spending remains real and, so far, largely justifies it. The financing shift toward debt — rather than the spending level itself — is the single most important variable to watch, because it introduces a genuine failure mode (refinancing risk, credit-market stress) that pure equity-funded capex would not carry. Neither the unambiguous bull case nor the unambiguous bubble case is fully supported by the data as it stands; both remain live possibilities depending on how the next several quarters of hyperscaler earnings play out.
Next step: Track the spread between hyperscaler capex growth rates and their AI-linked revenue growth rates each earnings season — a widening gap, more than any single stock’s valuation multiple, would be the clearest confirming signal that 2026’s AI rally has crossed from justified investment into unsustainable bubble territory.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- SpaceX reportedly completed a public listing in 2026, with reporting describing a valuation in the trillion-dollar range — a landmark event that shifted the bulk of Musk’s net worth away from Tesla and into SpaceX/xAI.
- xAI was folded into SpaceX in February 2026, combining Tesla, X, SpaceX, and xAI under increasingly overlapping ownership and infrastructure.
- Tesla’s Q2 2026 revenue came in at roughly $28 billion with a thin 1.4% operating margin, as capital expenditure surged toward AI and robotics rather than core EV production.
- Musk has reportedly been living near xAI’s Colossus supercomputer campus in Memphis during its latest expansion — a callback to his “production hell” habits at Tesla in 2017–18.
- Regulatory scrutiny is intensifying on multiple fronts: xAI’s Grok image generator has drawn investigations in Europe, Asia, Australia, and California, and Democratic senators have called for a Pentagon probe into SpaceX’s ownership structure.
The Portfolio, Reorganized
Musk’s business empire in 2026 looks structurally different than it did even eighteen months ago. Tesla, once the dominant source of his net worth, now sits alongside a combined SpaceX-xAI entity (sometimes referred to as SpaceXAI) that reporting has valued well into the trillions following its 2026 public-market debut. That shift matters for how markets should think about “Musk risk” — it’s no longer a single-stock story concentrated in Tesla.
Tesla: Thin Margins, Heavy AI Bet
Tesla’s Q2 2026 results showed the tension in the company’s current strategy:
- Revenue of roughly $28.2 billion against an operating margin of just 1.4% — among the thinnest in years.
- Capital expenditure up sharply year-over-year, directed heavily at AI and robotics infrastructure rather than incremental EV capacity.
- Robotaxi (Cybercab) and Optimus humanoid robot programs remain the company’s stated long-term growth bets, with Musk targeting expanded autonomous deployment across a meaningful share of the U.S. by year-end.
xAI: Burning Cash to Build Compute
xAI, now under the SpaceX umbrella, has been reported to consume roughly $1 billion per month in compute and infrastructure spend against an estimated $500 million in annualized revenue — a deliberately loss-leading posture aimed at building frontier AI capability (Grok) at scale. The Memphis “Colossus” supercomputer campus is the physical center of that buildout, and Musk’s decision to base himself near the site during its latest expansion signals how central it is to his current priorities.
The Regulatory Overhang
Musk’s expanding footprint has drawn parallel scrutiny across jurisdictions:
- xAI’s Grok image generator is under investigation in multiple countries over its capacity to generate harmful synthetic imagery.
- Senate Democrats have pushed for a Pentagon review of SpaceX’s ownership structure over undisclosed foreign investment concerns.
Neither issue has produced conclusive regulatory action as of this writing, but both represent tail risk for a portfolio increasingly concentrated in Musk-controlled entities.
Why This Matters Beyond Musk Himself
Musk’s 2026 moves are a useful proxy for a broader market theme: the shift of enormous private capital into AI infrastructure at a pace that outstrips current revenue generation. Whether that pattern resolves into durable competitive advantage (as bulls argue) or a capital-intensive cautionary tale (as skeptics argue) is likely to be one of the defining market questions through 2027.
What is Elon Musk’s biggest 2026 business move?
The completion of SpaceX’s public listing and its merger with xAI, reportedly valuing the combined entity in the trillions and shifting the majority of Musk’s net worth away from Tesla for the first time.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Bank of England Warns of AI Systemic Risk: How Autonomous Trading Threatens Financial Stability

Bank of Japan Hikes Benchmark Rate to 1.25%: Unwinding the Global Yen Carry Trade

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Battle for the Farm Belt: How Tariff Pressures and Fuel Costs Are Reshaping Iowa’s 2026 Midterms

Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN

Bank Jago’s Wealth Management Push:Indonesia’s 31.1 Million Investors boom

Beyond the Four-Year Degree: The $100K+ Trade Careers Young Americans Are Overlooking

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025