
Analysis
Trump’s Economic Promises Confront Political Reality as Tariffs Drive Up Costs

One year into his second term, President Donald Trump faces a paradox that threatens to upend Republican midterm prospects: his signature economic policy has become his most significant political liability.
Despite an unemployment rate hovering near historic lows, Trump’s overall approval rating has plummeted to 39% according to recent polling, with 69% of Americans reporting that his tariffs have increased prices they pay—a figure encompassing majorities across party lines. The disconnect between traditional economic indicators and public sentiment reveals how thoroughly tariff-driven inflation has poisoned what Republicans once considered their most formidable electoral asset.
The crisis crystallizes in stark numbers. The Tax Foundation estimates Trump’s tariffs amount to an average tax increase of $1,300 per U.S. household in 2026, representing the largest tax hike as a percentage of GDP since 1993. These aren’t abstract economic projections—they’re showing up in grocery bills, furniture prices, and construction costs that American families confront daily.
From Economic Strength to Political Vulnerability
The erosion of Trump’s standing on what was once his strongest issue represents a dramatic reversal. His net approval on the economy now stands at -16.5, a metric that would have seemed unthinkable during his first term when economic approval consistently exceeded overall job performance ratings. Only 39% of Americans approve of his presidency overall, with approval among independents at just 29%—numbers that send tremors through Republican strategists eyeing November’s midterm elections.
The polling tells a story of broad-based disillusionment. A Fox News survey found 54% of voters believe America is worse off than a year ago, with most attributing the decline to economic policies. More troubling for the White House, 75% of Americans, including 56% of Republicans, believe tariffs are raising prices. When a president’s signature policy loses majority support within his own party, the political ground has fundamentally shifted.
Manufacturing employment—the sector Trump specifically promised would come “roaring back” due to tariffs—has declined every month since April 2025, according to recent Labor Department data. The disconnect between promise and performance has given Democrats an opening on an issue where Republicans held commanding advantages for years.
The Mechanics of Middle-Class Pain
Understanding why tariffs have proven so politically toxic requires examining their concrete impact on household finances. The Tax Foundation’s comprehensive analysis reveals that Trump’s trade policies have pushed the average effective tariff rate to 10.1%—the highest since 1946. Combined Section 232 and International Emergency Economic Powers Act (IEEPA) tariffs now apply across categories Americans cannot avoid: building materials, consumer electronics, clothing, and food.
The retail reality confirms the macroeconomic projections. Recent research from Harvard economists cited by the Tax Foundation shows retail prices have risen 4.9 percentage points relative to pre-tariff trends, with imported goods up 6% and domestic goods—benefiting from reduced foreign competition—up 4.3%. Categories like apparel, coffee, household textiles, and furniture have experienced even sharper increases.
For the housing market, already strained by supply shortages, tariffs on lumber, steel, aluminum, copper, and cabinet materials add an estimated $17,500 to new home construction costs. The Center for American Progress projects these increased costs will prevent construction of 450,000 homes over the next five years—exacerbating affordability challenges in a sector where voters’ economic anxieties are most acute.
The Tax Policy Center estimates an average burden of approximately $2,100 per household in 2026, with the federal tax rate rising 1.9 percentage points for bottom-quintile households compared to 1.4 points for the top quintile. Tariffs function as regressive taxation, hitting those least able to absorb increased costs.

A Progressive Pivot from a Populist President
Facing eroding support, Trump has reached for an unexpected policy lever: a temporary 10% cap on credit card interest rates. The proposal, announced in early January with implementation targeted for the anniversary of his second inauguration, represents a striking ideological departure.
Credit card rates currently average over 20%, according to Federal Reserve statistics. Americans owe $1.23 trillion in credit card balances—the highest on record—making the burden politically salient. Trump’s proposal echoes legislation previously introduced by Senators Bernie Sanders and Josh Hawley, an unusual bipartisan pairing that underscores the issue’s populist appeal.
The banking industry’s response was immediate and hostile. Trade groups representing major card issuers argued a 10% cap “would reduce credit availability and be devastating for millions of American families and small business owners,” warning of restricted access particularly for higher-risk borrowers. Credit card stocks tumbled on the announcement, with analysts at Goldman Sachs noting the lack of clear enforcement mechanisms absent congressional action.
Trump’s lack of implementation specifics—no executive order has materialized, no legislation endorsed—suggests the proposal functions more as political theater than serious policy. Senator Elizabeth Warren dismissed it as “begging credit card companies to play nice,” while even some Republican allies expressed skepticism about the feasibility.
Yet the very fact that Trump felt compelled to float such a traditionally progressive policy instrument—one that directly interferes with private sector pricing—reveals the administration’s political desperation. When a president whose brand was built on deregulation and business-friendly policies starts proposing price controls, the electoral pressure is severe.
The Midterm Mathematics
Republican strategists confront uncomfortable arithmetic heading into the 2026 midterms. Historically, the president’s party loses an average of 28 House seats in midterm elections. With Republicans holding only narrow majorities in both chambers, even modest losses could flip control.
Polling shows only 30% of Latinos and adults under 35 now approve of Trump’s performance, down from 41% near the start of his term. These demographic groups represent growth constituencies that Republicans cannot afford to hemorrhage if they hope to maintain long-term competitiveness.
The economy’s role as the decisive issue for swing voters amplifies the danger. More voters think the economy will get worse this year rather than better by a 13-point margin (45% worse vs. 32% better), a dramatic shift from a year ago when optimism prevailed. Republican pollster Daron Shaw, who helps conduct Fox News surveys, acknowledged the challenge: “The president faces two difficult obstacles—the virtually unanimous and intractable opposition of Democrats and the stubbornness of high prices.”
Shaw and other GOP operatives are banking on the economic benefits of the recently passed “One Big Beautiful Bill Act”—which made most Tax Cuts and Jobs Act provisions permanent—materializing before November. Yet tax policy changes typically require months to flow through to household finances, while tariff-driven price increases arrive immediately at checkout counters.
Democrats, meanwhile, have found their footing on economic messaging after years of defensive positioning. Recent NBC polling shows the smallest Republican advantage on handling the economy since 2017, while a narrow majority of adults trust Democrats over Republicans on addressing rising prices. This represents a stunning reversal from traditional partisan alignments on economic issues.
The Supreme Court Wild Card
Adding uncertainty to an already volatile political landscape, the Supreme Court is expected to rule soon on challenges to Trump’s legal authority to impose most of his tariffs under the International Emergency Economic Powers Act. Half of Americans expect the Court to uphold Trump’s tariffs, though far fewer want it to.
A ruling striking down IEEPA-based tariffs would eliminate the bulk of Trump’s trade taxes, potentially providing economic relief but forcing a humiliating policy retreat. Conversely, upholding presidential authority might embolden further tariff escalation, risking additional price pressures. Either outcome carries significant political ramifications as campaigns intensify.
Conclusion: Promises vs. Performance
Trump’s predicament illustrates a fundamental challenge of populist economic nationalism: tariffs that sound appealing in theory—protecting American jobs, punishing foreign competitors, generating revenue for domestic priorities—become politically toxic when voters experience their actual effects. The gap between campaign rhetoric about “bringing factories roaring back” and the reality of declining manufacturing employment and elevated consumer prices has created precisely the kind of credibility deficit that transforms midterm elections into referendums on governing competence.
The credit card interest cap proposal, regardless of its substantive merits or implementation prospects, functions as tacit acknowledgment that the administration’s core economic strategy has not delivered for middle-class Americans. When a president must reach for emergency policy interventions a year into his term, the original plan has failed.
As November approaches, Republicans face a choice between defending tariff policies that remain unpopular even within their base, or pivoting away from what Trump has positioned as a signature achievement. Neither option offers easy politics. For Democrats, the opening is clear: run on affordability, emphasize the household cost of Trump’s trade war, and position themselves as the party that will provide relief rather than rhetoric.
The ultimate irony: Trump’s economic promises confronting political reality may determine whether Republicans maintain the congressional majorities needed to implement any economic agenda at all.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
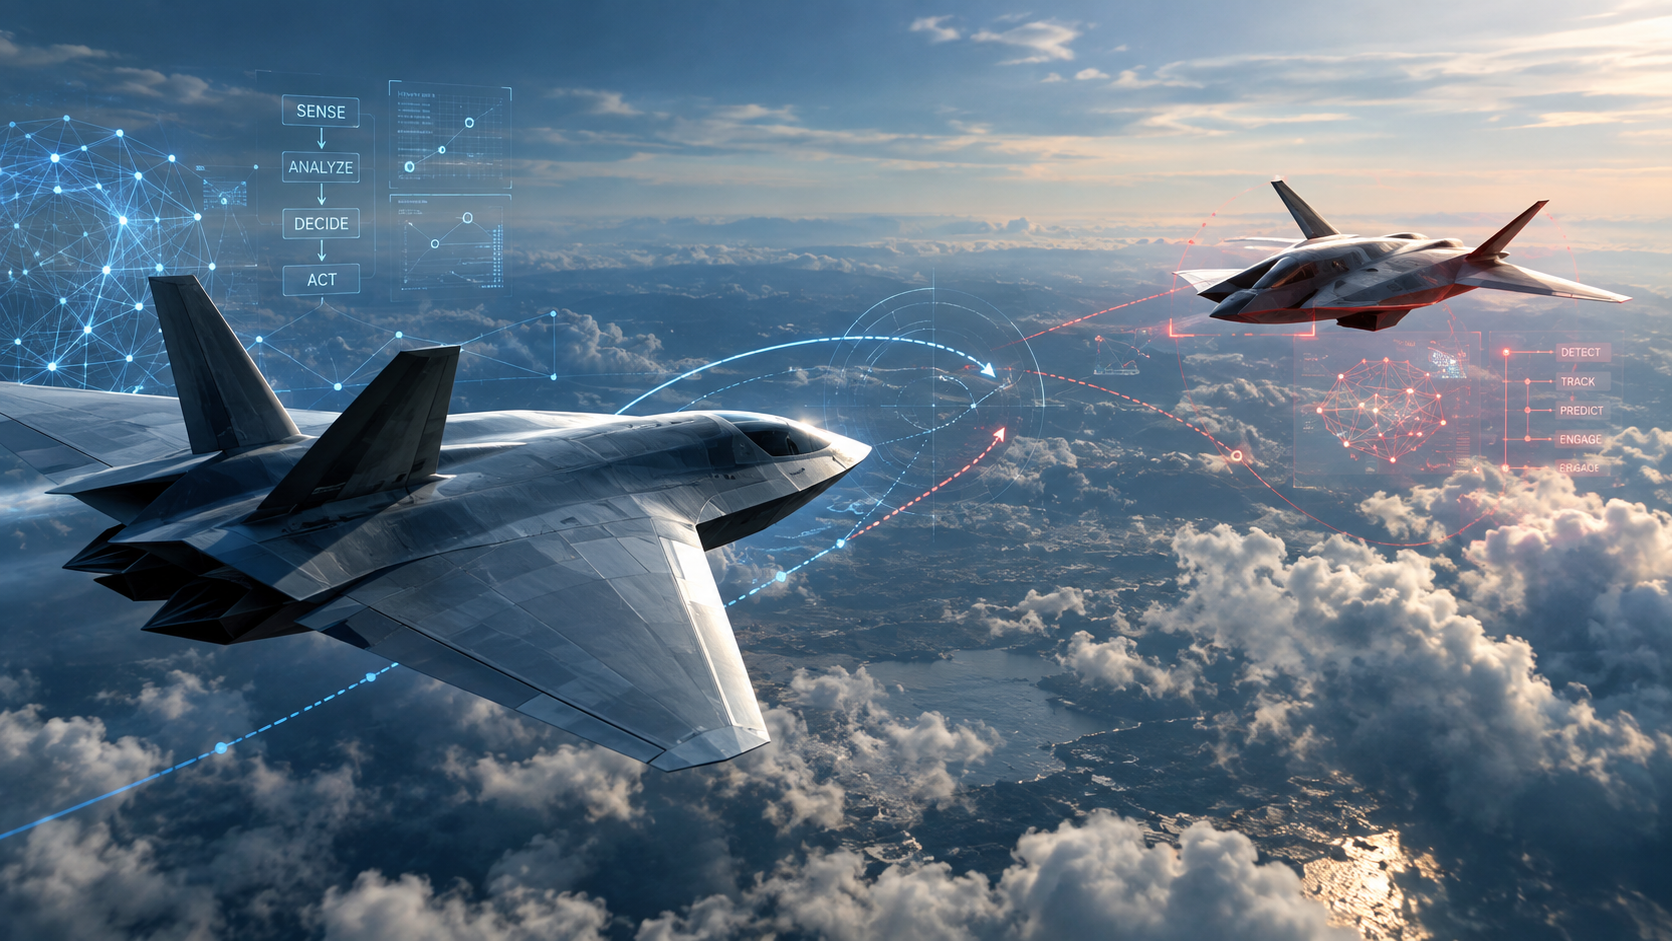
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A new Reuters poll shows 90% of economists expect the BoE to hold rates at 3.75% for the rest of 2026 — up from 83% last month. Here’s why the consensus hardened.
The Bank of England looks set to sit tight for the rest of 2026, and the consensus behind that view is getting stronger, not weaker. Per Investing.com’s coverage of the Reuters poll, the Bank will leave rates unchanged at 3.75% for the rest of the year according to a strong majority of economists, who have held that view since the war began in late February. Nearly 90% — 56 of 64 respondents — now expect no change through year-end, up from 83% last month, with six expecting a hike and two a cut; no one in the poll, conducted August 13–18, expects a September move.
Key Takeaways
- A Reuters poll of 64 economists (Aug 13–18) shows 56 now expect the BoE to hold Bank Rate at 3.75% through year-end — 90%, up from 83% last month.
- No economist in the poll expects a rate change at the September MPC meeting.
- The consensus has held since the US-Israeli war on Iran began in late February, with little evidence yet of energy-price spillover into the broader economy.
- Markets remain slightly more hawkish than economists, still pricing some chance of a rise by year-end.
- The BoE’s own guidance flags rising Q3/Q4 inflation risk tied specifically to Middle East energy prices.
The consensus is driven less by domestic demand and more by an external variable the Bank has flagged repeatedly. Per the same Reuters poll coverage, the UK economy has stayed mostly resilient since the war began, with little evidence of energy-price spillover into the broader economy — giving the Bank room to stay on the sidelines.
That resilience is fragile by the Bank’s own admission. According to an August 2026 review from Hanbury Wealth, the MPC voted six-to-three at its July 30 meeting to hold at 3.75%, with policymakers signaling rates could rise if Middle East-linked inflationary pressure intensifies; Governor Andrew Bailey said inflation had fallen faster than expected, but the conflict continues to mean high and volatile energy prices that will push inflation back up later in the year. The Bank’s own trajectory reflects this: per the House of Commons Library’s inflation briefing, based on mid-June energy pricing, the Bank projected CPI at “a little under 3%” in Q3 2026 and “a little over 3¼%” in Q4 — a downgrade from its April forecast.
There’s a genuine two-sided risk the poll’s headline framing tends to flatten. On the downside for inflation, the same House of Commons briefing notes that if Middle East energy disruption proves short-lived and oil and gas prices decline, inflation could instead fall from a September 2026 peak toward the Bank’s 2% target by Q2 2027. On the upside risk, HSBC UK economist Elizabeth Martins told Reuters (via Investing.com) that “a big rebound in energy prices would certainly change things.”
Markets aren’t as settled as the economist consensus: per the same poll coverage, financial markets are still pricing in one quarter-point rate rise by year-end — a genuine gap between what economists expect and what traders are hedging against, reported by outlets as two separate data points rather than connected explicitly.
Underlying data support a “resilient but fragile” framing. A KPMG-cited economic overview from Opus Business Advisory Group shows GDP grew 0.7% in the three months to May, slightly down from 0.8% in April, while core inflation fell more than expected in the twelve months to June, reaching its lowest rate since March 2025 — evidence the disinflation trend independent of energy hasn’t reversed. Separately, the House of Commons Library data shows food price inflation eased to 1.7% in June, its lowest since August 2024, reinforcing that the risk is concentrated in energy rather than broad-based prices.
Why It Matters
For borrowers, a prolonged hold at 3.75% keeps mortgage costs elevated relative to sharper-cut scenarios floated earlier in the year. For savers, it sustains relatively attractive cash returns. For the government, Opus’s review notes Prime Minister Andy Burnham has pledged a £2 bus-fare cap and removal of VAT from household electricity bills from October while maintaining existing fiscal rules and avoiding tax rises — a combination that gets harder to fund if borrowing costs stay elevated through year-end.
Data and Evidence
- Bank Rate: held at 3.75% since the July 30 MPC vote (6-3)
- Reuters poll: 56 of 64 economists (90%) expect no change through year-end, up from 83% last month
- BoE inflation forecast: ~3% Q3 2026, ~3.25%+ Q4 2026
- GDP growth: 0.7% in the three months to May 2026
- Food inflation: 1.7% in June 2026, lowest since August 2024
Global Impact
A UK central bank holding firm against energy-driven inflation risk is a data point other energy-importing economies — including Pakistan and much of South and Southeast Asia — are watching as a template for treating Middle East-linked price shocks as transitory.
What Happens Next
The next live decision point is the September MPC meeting, where the poll shows unanimous expectation of no change. The Q3/Q4 inflation prints will show whether the Bank’s own ~3.25% forecast materializes — and whether the hold consensus survives contact with that data.
Frequently Asked Questions
What is the UK’s current interest rate?
3.75%, unchanged since July 30, 2026.
Why isn’t the BoE cutting further?
Concern that Middle East-driven energy prices could push inflation back up in H2 2026.
Will UK mortgage rates change soon?
Based on the current poll, no near-term move is expected.
What would change the outlook?
A significant rebound — or further de-escalation — in Middle East energy prices.
Do markets agree with economists?
Not entirely — traders still price some chance of a year-end rate rise.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Pakistan is running two demanding reform programs at once, and they don’t obviously fit together. On one track, the IMF is pressing for stricter fiscal controls, expanded tax collection, and continued tight monetary policy under its Extended Fund Facility. On the other, Pakistan’s own constitution now mandates the removal of “riba” — interest — from the economy entirely, with a deadline set for January 2028, following a constitutional amendment passed in October 2024, according to IMF Country Report 25/109.
The IMF’s side of the ledger
Pakistan’s economic recovery gained real momentum in the first half of FY26, with GDP growth averaging 3.8% year-on-year, driven by the auto, construction, and garment industries, even as flooding in July-August weighed on output, according to IMF staff reporting. Inflation, however, climbed to 7.3% year-on-year in March as higher global commodity prices passed through to domestic energy costs. Foreign reserves have been rebuilding steadily — from $14.5 billion at end-June 2025 to $16 billion by end-December — while the primary fiscal surplus is expected to reach 1.6% of GDP in FY26, in line with IMF targets.
In May 2026, the IMF Executive Board completed the third review of Pakistan’s Extended Fund Facility and second review of its Resilience and Sustainability Facility, unlocking roughly $1.1 billion and $220 million respectively and bringing total disbursements under the two programs to about $4.8 billion, according to the IMF’s official press release. The Fund explicitly credited Pakistan’s “strong implementation” for maintaining stability despite the disruption from the Middle East war.
The parallel Islamic finance transformation
Running alongside that fiscal program is a structural transformation few outside Pakistan are tracking closely: the State Bank of Pakistan is required to develop a full financial sector strategy detailing the legal, regulatory, and strategic path to a riba-free economy, addressing monetary policy implementation, public debt management, and bank supervision — with a strategy deadline the IMF set for end-June 2026, per the same country report. Parliament has already moved on a related front, approving the Virtual Assets Bill in March 2026 and formally establishing the Pakistan Virtual Assets Regulatory Authority.
Why the IMF is watching this transition warily
The IMF’s own language signals concern about execution risk: publishing the riba-free transition plan “will help align the expectations of market participants, investors, and regulators… and mitigate concerns about any possible cliff effect,” according to the country report language. That is diplomatic phrasing for a real structural risk — an abrupt, poorly sequenced transition away from conventional interest-based finance could destabilize a banking sector the IMF has spent years helping stabilize.
The tax reform Pakistan still owes
Beyond monetary policy, Pakistan has committed to finalizing a new audit manual and centralizing taxpayer audit selection by August 2026, accelerating its Retailer Tax Registration Scheme, and making its Tax Policy Office fully operational, according to ProPakistani’s summary of IMF commitments. The Federal Board of Revenue has continued missing collection targets, prompting the IMF to propose making FBR revenue goals a formal Quantitative Performance Criteria — a stricter enforcement mechanism than before.
Why this matters for Gulf and global investors
Pakistan’s dual reform track — IMF-style fiscal orthodoxy alongside a constitutionally mandated Islamic finance transition — is unusual among IMF program countries and is drawing renewed Gulf capital interest, visible in DIFC’s decision to bring its Dubai FinTech Summit to Pakistan for the first time in August 2026 (see our companion report). Investors assessing Pakistan’s banking sector need to model both trajectories simultaneously, not just the more familiar IMF fiscal metrics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Brian Kemp’s Georgia Legacy: Economic Growth, Elections and the Costs of His Policy Choices

Dow Futures vs Dow Jones: What E-mini Contracts Really Tell You Before Wall Street Opens

China Tape Maker Stock Debut: Crown New Materials Soared 787%

Apple’s Earnings Beat Had a Catch: Look Past the Tariff Refund

Social Security Payments in November 2026: The Full Calendar and Two Important Changes

Johor–Singapore SEZ’s $21.8 Billion Bet: The Hard Part Starts Now

China’s 175 Trillion AI Tokens Reveal a Bigger Shift: The AI Boom

The Philippines’ Stagflation Trap: Higher Interest Rates

Alphabet’s $500 Billion Reckoning: Wall Street Is Losing Patience With the AI Boom

4 Reasons Why China’s Trade Concessions to Europe Will Not Solve the Crisis

The AI Revolution Needs Atomic Power. Southeast Asia Is Ready to Build It.

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

The $8 Billion Runway: China’s Strategic Bet on Guangzhou and the Future of Aviation

The Sandbox Imperium: Why Beijing’s Digital Yuan Needs Hong Kong

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025