
Analysis
Singapore Tightens Training Subsidies as Economic Pressures Mount

SkillsFuture funding reforms signal a strategic pivot toward industry-led upskilling—but at what cost to smaller providers and self-funded learners?
On a humid afternoon in December, Melissa Tan sat in her Jurong West training center watching enrollment numbers tick downward on her computer screen. After fourteen years running a mid-sized vocational training provider, she had weathered economic downturns, policy shifts, and the digitization of Singapore’s workforce. But the new SkillsFuture funding guidelines announced by SkillsFuture Singapore (SSG) in late January felt different. “We’ve built our reputation on serving individuals who want to pivot careers on their own initiative,” she explained over coffee. “Now we need forty percent of our students to be employer-sponsored. That’s a complete business model transformation.”
Tan’s predicament illustrates the complex trade-offs embedded in Singapore’s latest recalibration of its decade-old SkillsFuture initiative. Effective December 31, 2025, SSG has imposed substantially tighter funding criteria on approximately 9,500 training courses across 500 providers—requirements that privilege employer-driven training over individual initiative, data-validated skills over experimental offerings, and quantifiable outcomes over pedagogical innovation. The reforms arrive at a moment when Singapore’s small, open economy faces mounting pressure from technological disruption, an aging workforce, and intensifying regional competition for talent and capital.
The policy shift represents more than administrative housekeeping. It embodies a fundamental question confronting advanced economies worldwide: How do governments balance the democratization of lifelong learning with the imperative to channel scarce public resources toward demonstrable economic returns?
The Mechanics of Tightening
The new guidelines affect what SSG terms “Tier 2” courses—those developing currently demanded skills for workers’ existing roles or professions. (They explicitly exclude SkillsFuture Series courses focused on emerging skills, or career transition programs like Institute of Higher Learning qualifications.) The changes impose three primary gatekeeping mechanisms:
Course approval: Prospective courses must now demonstrate alignment with either (1) skills appearing on SSG’s newly released Course Approval Skills List, derived from data science analysis of job market trends, or (2) documented evidence of industry demand through endorsement from designated government agencies or professional bodies. This represents a marked departure from the previous approach, which permitted a broader range of training offerings to access public subsidies.
Funding renewal threshold: From December 31, 2025 onward, courses seeking to renew their two-year funding cycle must demonstrate that at least 40 percent of enrollments came from employer-sponsored participants. This metric directly measures whether training aligns with enterprise workforce development priorities rather than individual hobbyist pursuits.
Quality survey compliance: Beginning June 1, 2026, courses must achieve a minimum 75 percent response rate on post-training quality surveys, with ratings above the lower quartile. This mechanism aims to eliminate providers who deliver mediocre experiences while gaming enrollment numbers.
A transitional framework softens the immediate impact. Between December 31, 2025 and June 30, 2027, selected course types—including standalone offerings from institutes of higher learning, courses leading to Workforce Skills Qualification Statements of Attainment, and certain other categories—receive a one-year grace period if they fail the 40 percent employer-sponsorship threshold. But the reprieve is temporary; from July 1, 2027, all Tier 2 courses must meet the full criteria.
The Economic Logic: Aligning Supply with Demand
The rationale behind these reforms emerges clearly when viewed against Singapore’s macroeconomic imperatives and recent labor market data. According to SSG’s 2025 Skills Trends analysis, demand for AI-related competencies has surged across industries, with skills like “Generative AI Principles and Applications” experiencing the fastest growth in job postings data. Simultaneously, green economy skills—sustainability management, carbon footprint assessment—and care economy capabilities have gained prominence as Singapore pursues its Green Plan 2030 and grapples with demographic aging.
Yet training providers, responding to consumer demand rather than labor market signals, have often proliferated courses in saturated or declining sectors. The mismatch represents a classic market failure: individual learners, lacking perfect information about employment prospects, gravitate toward familiar or fashionable topics rather than areas of genuine skills shortage. Training providers, incentivized to maximize enrollment volumes, oblige. Public subsidies then inadvertently subsidize this misalignment.
The 40 percent employer-sponsorship requirement cleverly leverages employers’ superior information about workforce needs. Companies investing real money in their employees’ training create a demand-side filter that SSG believes will naturally favor courses addressing actual productivity gaps. “Employers vote with their wallets,” one SSG official noted at the January 27 Training and Adult Education Conference announcing the changes. “If a course can’t attract employer sponsorship, we need to ask whether it’s truly addressing labor market needs.”
From a public finance perspective, the logic is straightforward. Singapore, despite its fiscal strength, operates under self-imposed constraints: a balanced budget requirement, limited borrowing for current spending, and a cultural aversion to expansive welfare states. SkillsFuture expenditures have grown substantially since the program’s 2015 launch—Singaporeans aged 25 and above have collectively claimed over S$1 billion in SkillsFuture Credits, with enhanced subsidies for mid-career workers (aged 40-plus) adding further fiscal pressure. Ensuring these outlays generate measurable employment and productivity outcomes becomes imperative as the government contemplates longer-term structural challenges: an aging society requiring expanded healthcare spending, investments in digital infrastructure and green transition, and resilience measures against external economic shocks.
Global Context: Singapore’s Experiment in Comparative Relief
To appreciate the boldness of Singapore’s approach, consider its divergence from other advanced economies’ lifelong learning models. Denmark’s flexicurity system combines generous unemployment benefits with extensive active labor market policies, including subsidized adult education. But Denmark can afford this largesse through high taxation (total government revenue exceeds 46 percent of GDP, versus Singapore’s 20 percent) and a homogeneous, highly unionized workforce. South Korea’s K-Digital Training initiative, launched in 2020, channels subsidies toward digital skills bootcamps—but targets primarily youth and unemployed workers, not the broader workforce Singapore aims to reach.
France’s Compte Personnel de Formation (CPF) offers perhaps the closest parallel: a portable training account funded through payroll levies, giving workers autonomy over skill development. Yet France’s system has faced criticism for fraud, low-quality providers gaming the system, and inadequate alignment with labor market needs—precisely the pathologies Singapore’s reforms seek to preempt. A 2021 report in The Economist examining retraining programs across OECD countries found that success correlated strongly with employer involvement and labor market relevance, rather than mere accessibility.
Singapore’s model occupies a distinctive middle ground: universal entitlements (every citizen aged 25-plus receives credits), but channeled through market mechanisms and employer validation. The SkillsFuture reforms effectively tighten the alignment mechanism without abandoning the universalist principle—a pragmatic compromise characteristic of Singapore’s technocratic governance style.
The Squeeze on Training Providers: Winners and Losers
The employer-sponsorship threshold creates clear winners and losers among training providers. Large, established players with existing corporate relationships—polytechnics, ITE, private training centers serving multinational corporations—possess natural advantages. They can leverage long-standing contracts, industry advisory boards, and placement track records to attract employer-sponsored enrollments.
Smaller providers face steeper challenges. Many built their businesses serving self-funded mid-career professionals seeking new skills or side ventures—precisely the demographic segment the reforms indirectly penalize. “We’ve invested heavily in emerging areas like blockchain development and sustainability consulting,” explained one boutique training center director who requested anonymity. “These are forward-looking skills, but companies aren’t yet sponsoring at scale because the roles barely exist in their organizations. Under the new rules, we’re essentially being told to wait until the demand becomes mainstream—by which point the opportunity has passed.”
The enrolment cap mechanism, while intended to prevent gaming, compounds the squeeze. Courses reaching their enrollment limit before the funding renewal check (six months prior to the end of the two-year validity period) must pass quality checks before accepting additional students. High-demand courses thus face bureaucratic friction at the worst possible moment—when they’ve demonstrated market appeal. Lower-demand courses, by contrast, may never hit enrollment thresholds requiring scrutiny, creating a perverse incentive structure.
Training providers serving niche industries face particular vulnerability. Specialized sectors like maritime law, conservation biology, or heritage preservation generate modest enrollment volumes and limited employer-sponsorship rates (small firms in these fields often lack formal training budgets). Yet these represent precisely the differentiated capabilities that sustain Singapore’s position as a diversified, knowledge-intensive economy beyond the big four sectors (finance, logistics, technology, manufacturing).
Access and Equity: The Self-Funded Learner’s Dilemma
The employer-sponsorship emphasis raises important equity questions. Not all workers enjoy employer-sponsored training opportunities equally. Research by Singapore’s Ministry of Manpower shows that company-sponsored training tends to concentrate among degree-holders, professionals, and employees of large firms. Rank-and-file workers in SMEs, gig economy participants, and those in precarious employment—precisely the groups most vulnerable to technological displacement—face significant barriers.
Consider Raj Kumar, a 47-year-old logistics coordinator whose employer, a small freight forwarding company, lacks a formal training budget. Kumar has used SkillsFuture credits to complete courses in data analytics and digital supply chain management, hoping to transition into a more technology-oriented role. Under the new guidelines, his preferred courses may lose funding eligibility if they fail to attract sufficient employer sponsorship—forcing him to either pay full cost or choose less relevant but better-subsidized alternatives.
Women reentering the workforce after caregiving breaks present another equity concern. These mid-career returners often invest in self-funded retraining to compensate for skills atrophy or career pivots. Employer-sponsorship requirements create a catch-22: they need training to become employable, but courses require employer interest to remain subsidized.
SSG officials argue that alternative pathways remain available—SkillsFuture Career Transition Programs explicitly serve career switchers, and mid-career enhanced subsidies (covering up to 90 percent of course fees for Singaporeans aged 40-plus) continue supporting self-funded learning. But the distinction between “career transition” and “skills upgrading” proves blurry in practice. Many mid-career workers pursue incremental skill acquisition that doesn’t constitute wholesale career change yet enables internal mobility or role evolution. The new framework may inadvertently penalize this gray zone of professional development.
Data-Driven Skill Identification: Promise and Pitfalls
The Course Approval Skills List represents one of SSG’s more innovative elements. Using natural language processing and machine learning algorithms, SSG analyzes job posting data, wage trends, and hiring patterns to identify skills experiencing demand growth. The 2025 Skills Trends report reveals that 71 skills—spanning agile software development, sustainability management, and client communication—demonstrated consistently high demand and transferability across 2022-2024, with trends expected to continue into 2025.
This data-driven approach offers significant advantages over traditional expert panels or industry surveys. It’s faster, more comprehensive, and less subject to lobbying by incumbent industry players. The methodology also permits granular analysis—SSG now tracks not just skill categories but specific applications and tools (Python libraries, ERP systems, design software) required in job roles.
However, data-driven skill identification harbors limitations. Job postings reflect current employer preferences, not future needs. Emerging disciplines—quantum computing applications, circular economy frameworks, AI ethics—may barely register in job posting data until they’ve already achieved critical mass. By then, first-mover advantages have vanished. If training providers can only offer courses on SSG’s approved list, Singapore risks systematically underinvesting in forward-looking capabilities.
The methodology also privileges skills easily described in job postings. Tacit knowledge, soft skills, and creative competencies prove harder to quantify through algorithmic analysis. Yet these capabilities—judgment, cross-cultural communication, ethical reasoning—often determine long-term career success and organizational adaptability. A training ecosystem optimized for algorithmically identifiable skills may inadvertently neglect the human qualities most resistant to automation.
The Broader Stakes: Singapore’s Competitiveness Calculus
The SkillsFuture reforms must be understood within Singapore’s broader economic development strategy. The city-state has staked its future on becoming a hub for advanced manufacturing, digital services, sustainability innovation, and high-value professional services—sectors requiring a workforce that continuously upgrades capabilities. With neighboring countries investing heavily in technical education (Vietnam’s IT workforce, Thailand’s Eastern Economic Corridor initiative) and established hubs like Hong Kong and Seoul competing for similar industries, Singapore cannot afford complacency.
Yet the tightening carries risks. If Singapore’s training ecosystem becomes too employer-driven and algorithmically determined, it may sacrifice the experimental, entrepreneurial energy that has historically fueled its adaptive capacity. Many of Singapore’s successful industry pivots—from petrochemicals to biotech, from port logistics to digital banking—emerged from individuals and organizations pursuing capabilities ahead of obvious market demand.
The reforms also reflect broader tensions in Singapore’s governance model. The technocratic state excels at efficiency, optimization, and resource allocation toward measurable objectives. These strengths propelled Singapore from third-world poverty to first-world prosperity in two generations. But efficiency-maximizing systems can become brittle when confronted with uncertainty and ambiguity. Training that produces clear, quantifiable outcomes in stable domains may underperform when facing discontinuous change or nonlinear technological shifts.
Forward-Looking Implications: What Comes Next
The January 2026 announcement likely represents the opening salvo in a longer recalibration of Singapore’s lifelong learning architecture. Several trends warrant attention:
Increased emphasis on outcomes-based funding: Expect SSG to develop more sophisticated metrics beyond employer sponsorship—wage progression, job placement rates, productivity enhancements. The agency has already signaled interest in tracking post-training employment outcomes. Future iterations may adjust subsidy levels based on demonstrated impact.
Evolution of the Skills List methodology: As SSG refines its algorithmic approaches, the Course Approval Skills List will likely become more dynamic—updated quarterly rather than annually, incorporating leading indicators beyond job postings, and potentially using predictive modeling to anticipate emerging needs.
Differentiated treatment by sector: SSG may recognize that employer-sponsorship patterns differ across industries. Creative sectors, startups, and SME-dominated fields may receive adjusted thresholds or alternative validation mechanisms.
Greater integration with immigration and talent policy: The skills identified through SkillsFuture’s data infrastructure will increasingly inform Singapore’s employment pass criteria, tech.pass requirements, and sectoral talent initiatives. Training subsidies and immigration policy will converge into a unified human capital strategy.
Experimentation with training innovation zones: To preserve space for experimental offerings, Singapore may designate sandbox environments where providers can test new course concepts with lighter regulatory oversight before scaling.
The Danish Comparison: Lessons from Flexicurity
It’s instructive to contrast Singapore’s approach with Denmark’s vaunted flexicurity model, often cited as a gold standard for lifelong learning. Denmark spends approximately 2.5 percent of GDP on active labor market policies, including extensive adult education subsidies. Workers displaced by technological change or trade shocks can access generous retraining programs with income support.
But Denmark’s system operates in a fundamentally different institutional context. High trust between labor unions, employers, and government enables coordinated approaches to workforce adjustment. Collective bargaining determines training priorities. Social insurance funds (financed through high payroll taxes) cushion income shocks during reskilling. Cultural norms around equality and solidarity legitimize substantial transfers to support individual skill development.
Singapore lacks these institutional preconditions. Its tripartite labor relations model (government-union-employer cooperation) provides some coordination, but stops short of Nordic-style corporatism. The country’s fiscal conservatism precludes Danish-level spending. And Singapore’s multicultural, immigrant-heavy society (40 percent of the population are foreign workers or residents) complicates solidarity-based social insurance.
The SkillsFuture reforms implicitly recognize these constraints. Rather than expand public spending, they aim to spend existing resources more strategically. Rather than rely on trust-based coordination, they deploy data analytics and market mechanisms. This represents neither a superior nor inferior model, but an adapted solution to Singapore’s particular constraints.
The Economist’s Verdict: Calculated Risk or Overreach?
From a pure economic efficiency standpoint, the reforms possess clear merits. Channeling training subsidies toward employer-validated, data-confirmed skills should improve returns on public investment. The employer-sponsorship threshold creates skin-in-the-game dynamics that filter out marginal or dubious training offerings. And the quality survey requirements introduce accountability mechanisms previously absent.
Yet efficiency gains come with potential costs. By privileging current labor market demand over forward-looking capability building, Singapore may diminish its adaptive capacity. The employer-sponsorship threshold, while logical, risks excluding individuals in precarious employment or career transition phases. And the centralization of skill identification—however data-driven—concentrates epistemic power in a single agency that, like all institutions, harbors blind spots.
The optimal balance remains elusive. Singapore’s technocratic governance has historically navigated such trade-offs adeptly, adjusting policies as evidence accumulates. The transitional provisions built into the reforms suggest policymakers recognize implementation risks. Whether these safeguards prove sufficient will emerge over the next eighteen months as providers, employers, and individual learners respond to the new incentives.
What This Means for Stakeholders
For employers: The reforms create opportunities to influence training supply by directing sponsorship toward strategically valuable skills. Forward-thinking HR departments should inventory critical competencies, identify skill gaps, and proactively engage training providers to develop relevant curricula. SMEs, often lacking structured training budgets, may face disadvantages unless industry associations or government intermediaries help aggregate demand.
For training providers: Survival requires pivoting toward corporate partnerships and employer-sponsored enrollments. This means investing in business development capabilities, building industry advisory boards, and potentially consolidating to achieve scale. Providers serving niche or emerging fields face particularly acute pressures—they must either find creative ways to demonstrate industry demand or accept exit from the subsidized market.
For individual learners: Self-funded skill development becomes costlier and riskier. Prudent strategies include leveraging Career Transition Programs when making significant pivots, prioritizing employer-sponsored opportunities where available, and focusing SkillsFuture credits on courses appearing on SSG’s approved skills list. Mid-career workers should proactively discuss training needs with employers to access sponsorship.
For policymakers elsewhere: Singapore’s experiment offers lessons beyond its borders. The employer-sponsorship threshold provides a demand-side filter without abandoning universal access—a model potentially applicable in other advanced economies facing similar efficiency-equity trade-offs. The data-driven skills identification methodology, while imperfect, represents an improvement over purely expert-driven approaches. And the transitional framework demonstrates how aggressive policy reforms can incorporate adjustment periods to mitigate disruption.
The Bigger Picture: Singapore’s Perpetual Adaptation
Step back from the technical details, and the SkillsFuture reforms embody a deeper pattern: Singapore’s continuous recalibration in response to shifting circumstances. The 2015 SkillsFuture launch represented an initial bet on individual empowerment and lifelong learning. A decade’s experience has revealed implementation challenges—misaligned incentives, quality concerns, sustainability questions. The 2025-26 reforms adjust the model based on this learning.
This adaptive approach—launching initiatives, monitoring outcomes, adjusting parameters—characterizes Singapore’s developmental trajectory. The country pivoted from entrepôt trade to manufacturing to services to knowledge economy not through prescient master plans, but through iterative experimentation and course correction. The SkillsFuture reforms continue this tradition.
Yet adaptation has limits. Each course correction narrows future options. Path dependencies emerge. The shift toward employer-driven training may prove difficult to reverse if individual-initiative learning atrophies. Data-driven skill identification, once institutionalized, creates constituencies defending existing methodologies. Singapore’s policymakers must balance the need for optimization with preserving optionality.
Conclusion: The Test Ahead
The SkillsFuture funding tightening represents a calculated bet: that aligning training subsidies with employer demand and labor market data will enhance returns on human capital investment without unduly compromising access or innovation. It’s a quintessentially Singaporean solution—technocratic, efficiency-oriented, data-driven, yet wrapped in rhetoric of lifelong learning and social mobility.
Whether the bet pays off depends on execution and adaptation. Will the employer-sponsorship threshold effectively filter quality while preserving access for vulnerable workers? Will the Skills List methodology prove sufficiently forward-looking, or will it systematically underweight emerging capabilities? Will training providers adapt successfully, or will the sector consolidate in ways that reduce diversity and experimentation?
The answers will emerge gradually as the reforms take effect. Melissa Tan, the training provider director pondering her center’s future that humid December afternoon, exemplifies the stakes. Her ability to navigate the new landscape—finding corporate partners, aligning offerings with approved skills, maintaining quality—will determine not just her business survival but the aggregate health of Singapore’s training ecosystem.
For a small, open economy in a volatile world, the quality of that ecosystem matters immensely. Singapore’s prosperity rests not on natural resources or scale, but on its people’s capabilities. As artificial intelligence reshapes work, climate imperatives transform industries, and geopolitical tensions fragment global markets, continuous skill upgrading becomes not a policy choice but an existential imperative.
The SkillsFuture reforms, whatever their shortcomings, recognize this reality. They represent not the final word on lifelong learning policy, but another iteration in Singapore’s ongoing experiment in sustaining adaptability at the national scale. The city-state’s track record suggests it will continue adjusting, learning, and recalibrating as conditions evolve.
That flexibility—the institutional capacity to course-correct without abandoning core commitments—may prove Singapore’s most valuable skill of all.
Sources:
- SkillsFuture Singapore Official Announcement, January 27, 2026
- Skills Demand for the Future Economy Report 2025
- TPGateway SSG Funding Guidelines
- The Economist, “Retraining Low-Skilled Workers,” Special Report, January 2017
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


In an era defined by global economic volatility, supply chain fracturing, and the relentless search for post-pandemic growth drivers, middle powers face a stark choice: passively import technological paradigms dictated by foreign tech superpowers or aggressively architect a sovereign framework that harnesses next-generation efficiencies. Under Prime Minister Anthony Albanese, Australia has chosen the latter.
Navigating the delicate equilibrium between accelerating productivity gains and enforcing robust governance, the Albanese administration’s strategic pivot toward artificial intelligence (AI) has emerged as a compelling blueprint for modern statecraft. Far from a mere policy footnote, Australia’s calculated embrace of AI integration is positioning the nation’s economy for an unprecedented transformation—one projected to inject billions into the domestic ledger while safeguarding social cohesion.
The Productivity Imperative: Bridging the Gap
For years, advanced economies have grappled with sluggish productivity growth—a trend that has severely tested traditional fiscal and monetary levers. Australia has been no exception, confronting multi-decade lows in labour productivity growth that have squeezed profit margins, constrained real wage progression, and fueled cost-of-living anxieties.
Enter artificial intelligence. Economic modelling highlights that large-scale AI adoption could unlock up to AUD $142 billion annually for the Australian economy by 2030, serving as a multi-factor productivity catalyst. Rather than viewing technological automation as a displacement threat, Canberra’s policy machinery has reframed AI as an essential force multiplier across key national sectors—from mining optimisation and agricultural tech to precision manufacturing under the Future Made in Australia agenda.
Small and medium-sized enterprises (SMEs)—the lifeblood of the domestic economy—stand to gain immensely. By automating administrative burdens, streamlining compliance, and optimising supply chain logistics, AI integration allows local businesses to redirect capital toward innovation and high-value creation.
Pioneering a World-First Regulatory Framework
What separates Australia’s approach from the fragmented regulatory environments of the United States or the heavy-handed compliance models of the European Union is its proactive, harmonised architecture.
In July 2026, the Albanese government unveiled a world-leading national AI framework designed to provide certainty for investors while establishing strict guardrails for ethical deployment. Key pillars of this strategy include:
- Sovereign Standards and Intellectual Property Protection: Australia became a global pioneer by enacting clear protections ensuring that local creative works, literature, music, and journalistic output cannot be scraped for AI training models without explicit artist consent and compensation.
- Streamlined Compliance for Frontier Investments: By establishing unified national standards, the framework cuts through bureaucratic red tape, offering international investors expedited approval pathways conditional on adherence to safety and security benchmarks.
- A Binding Social Licence: The framework emphasises that technology must serve human agency. Ensuring public trust remains paramount; algorithms cannot operate as black boxes when critical public services, employment markets, and national security are involved.
Navigating the Geopolitical and Economic Crosswinds
Australia’s economic strategy does not exist in a vacuum. As great power competition reshapes global trade and globalisation pivots toward regional resilience, Canberra is leveraging its vast reserves of critical minerals, rare earths, and clean energy assets.
AI acts as the computational glue binding these traditional resource strengths with future-facing capabilities. For instance, optimising the extraction and processing of critical minerals required for global energy transitions relies heavily on advanced machine learning models and automated logistics. By coupling its natural resource abundance with top-tier university research and skilled graduate pipelines, Australia is making a compelling pitch to global venture capital: come build here, on Australian terms.
Comparative Strategic Advantages
| Strategic Pillar | Traditional Model | Australia’s AI-Integrated Approach |
| Productivity Driver | Capital investment & raw volume expansion | Multi-factor efficiency via sovereign AI deployment |
| Regulatory Stance | Reactive policy or unbridled laissez-faire | Proactive, world-first unified national standards |
| Workforce Strategy | Reliance on lagging skills adaptation | Empowering workers through institutional AI literacy and secure transitions |
| IP & Innovation | Lax protections for digital creators | Enforceable ownership rights over AI training inputs |
The Road Ahead: Can Australia Stick the Landing?
While the macroeconomic projections are dazzling, translating policy ambition into structural reality carries inherent risks. The success of Albanese’s vision will ultimately be judged by execution metrics over the remainder of the decade:
- Skills Alignment: Ensuring that the national education and vocational training sectors can rapidly upskill workers to meet the demands of an AI-augmented labour market.
- Cybersecurity Resilience: As critical infrastructure becomes increasingly digitised and reliant on automated machine-learning networks, national security frameworks must scale defensively to prevent state-sponsored cyber exploitation.
- Equitable Distribution: Ensuring that productivity dividends do not concentrate solely within major metropolitan tech hubs, but actively flow to regional communities and working-class Australians.
Conclusion
Australia’s economic narrative under the Albanese administration is shedding the old tropes of the “lucky country” relying purely on cyclical commodity booms. Instead, it is writing a new chapter of purposeful economic design. By harmonising technological disruption with rigorous ethical standards and worker-centric policies, Australia is proving that middle powers do not have to be passive spectators in the digital revolution—they can help write the rules of the game.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
For decades, the global dominance of the U.S. dollar has rested on two primary pillars: deep, unencumbered liquid capital markets and an indispensable global financial messaging protocol known as SWIFT. When Beijing launched its e-CNY initiative, Western observers initially framed it as a central bank digital currency (CBDC) designed primarily for domestic surveillance, retail convenience, and financial inclusion.
However, recent strategic moves highlight a far more ambitious objective. As documented by the South China Morning Post, Beijing is actively leveraging Hong Kong as its central offshore laboratory to establish the infrastructure required for international cross-border digital yuan adoption.
The crucial strategic question is no longer whether China can engineer robust distributed ledger architecture, but whether an offshore financial hub operating under “One Country, Two Systems” can bridge the gap between rigid domestic capital controls and global institutional acceptance. To succeed, China must resolve the fundamental tension between absolute monetary sovereignty and the open networks required for international currency adoption.
1. The Paradox of the Offshore Laboratory
China’s monetary expansion faces a well-documented structural paradox. According to macroeconomic research from the Carnegie Endowment for International Peace, no currency can achieve true international reserve status without offering open capital accounts and deep, freely convertible liquidity. Yet, completely relaxing capital controls would expose China’s domestic banking system to volatile international capital flows and speculative pressures.
Hong Kong serves as the pressure valve and testing ground for this paradox:
- Legal & Regulatory Buffer: Hong Kong maintains a trusted common law judicial system and an independent monetary authority (Hong Kong Monetary Authority).
- Convertibility Bridge: It allows mainland authorities to test e-CNY settlement, cross-border retail links, and digital asset integration without opening mainland financial markets directly to global speculative shocks.
- Institutional Liquidity: As the world’s premier offshore renminbi hub, Hong Kong provides the institutional counterparties necessary to build real-world transaction volume.
“The digital yuan’s true test lies not in domestic retail adoption, but in whether foreign counterparties can settle cross-border trade without taking on unacceptable regulatory or capital risks.”
2. Wholesale Settlement and Project mBridge
While retail consumer wallets attract considerable media attention, the real geopolitical shift is occurring at the wholesale institutional level. Strategic initiatives like Project mBridge—developed in partnership with the Bank for International Settlements (BIS), the People’s Bank of China, and regional central banks—demonstrate how multi-CBDC platforms can streamline international trade.
As reported in market analyses by Bloomberg and trade finance studies covered by Reuters, multi-lateral CBDC platforms offer significant operational advantages:
- Elimination of Intermediaries: Direct ledger-to-ledger transactions bypass traditional correspondent banking networks.
- Speed and Efficiency: Cross-border settlement times are reduced from days to seconds.
- Cost Reduction: Transaction costs and foreign exchange spreads across regional trade corridors in Asia and the Middle East are dramatically lowered.
If commercial enterprises operating in Hong Kong can settle trade directly in e-CNY with instant finality, Beijing creates a compelling economic incentive for trade partners that operates independently of Western clearing networks.
3. Geopolitical Implications & The Road Ahead
Western policymakers and central bankers are monitoring these developments closely. Recent congressional testimony and Treasury reviews highlighted by Reuters reflect growing concern in Washington that alternative settlement rails could gradually erode the reach and enforcement of Western financial sanctions.
However, technological capability alone does not guarantee global currency dominance. Until foreign corporate treasuries and central banks have full confidence in converted currency liquidity, property rights, and transparent legal protections, the digital yuan will serve primarily as an efficient alternative mechanism for bilateral trade rather than an immediate replacement for the U.S. dollar.
Institutional Summary & Comparison
| Dimension | Conventional Retail Focus | Wholesale / Strategic Reality |
| Primary Mechanism | Retail e-CNY wallets for tourists & merchants | Multi-CBDC corridors (Project mBridge) & Project Ensemble |
| Core Objective | Domestic payments & payment app competition | Disintermediation of correspondent banking and SWIFT rails |
| Primary Barrier | Consumer habituation & merchant readiness | Capital controls, currency convertibility, and institutional trust |
Sources & Citations
- South China Morning Post: Beijing wants Hong Kong to sow the seeds for the digital yuan
- Bank for International Settlements (BIS): Central Bank Digital Currency (CBDC) & Cross-Border Payments Research
- Carnegie Endowment for International Peace: China’s Financial System and Capital Account Dynamics
- Bloomberg Financial Analysis: Global Macro & Digital Currency Integration
- Reuters News & Analysis: Cross-Border Settlement and Global Trade Finance
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
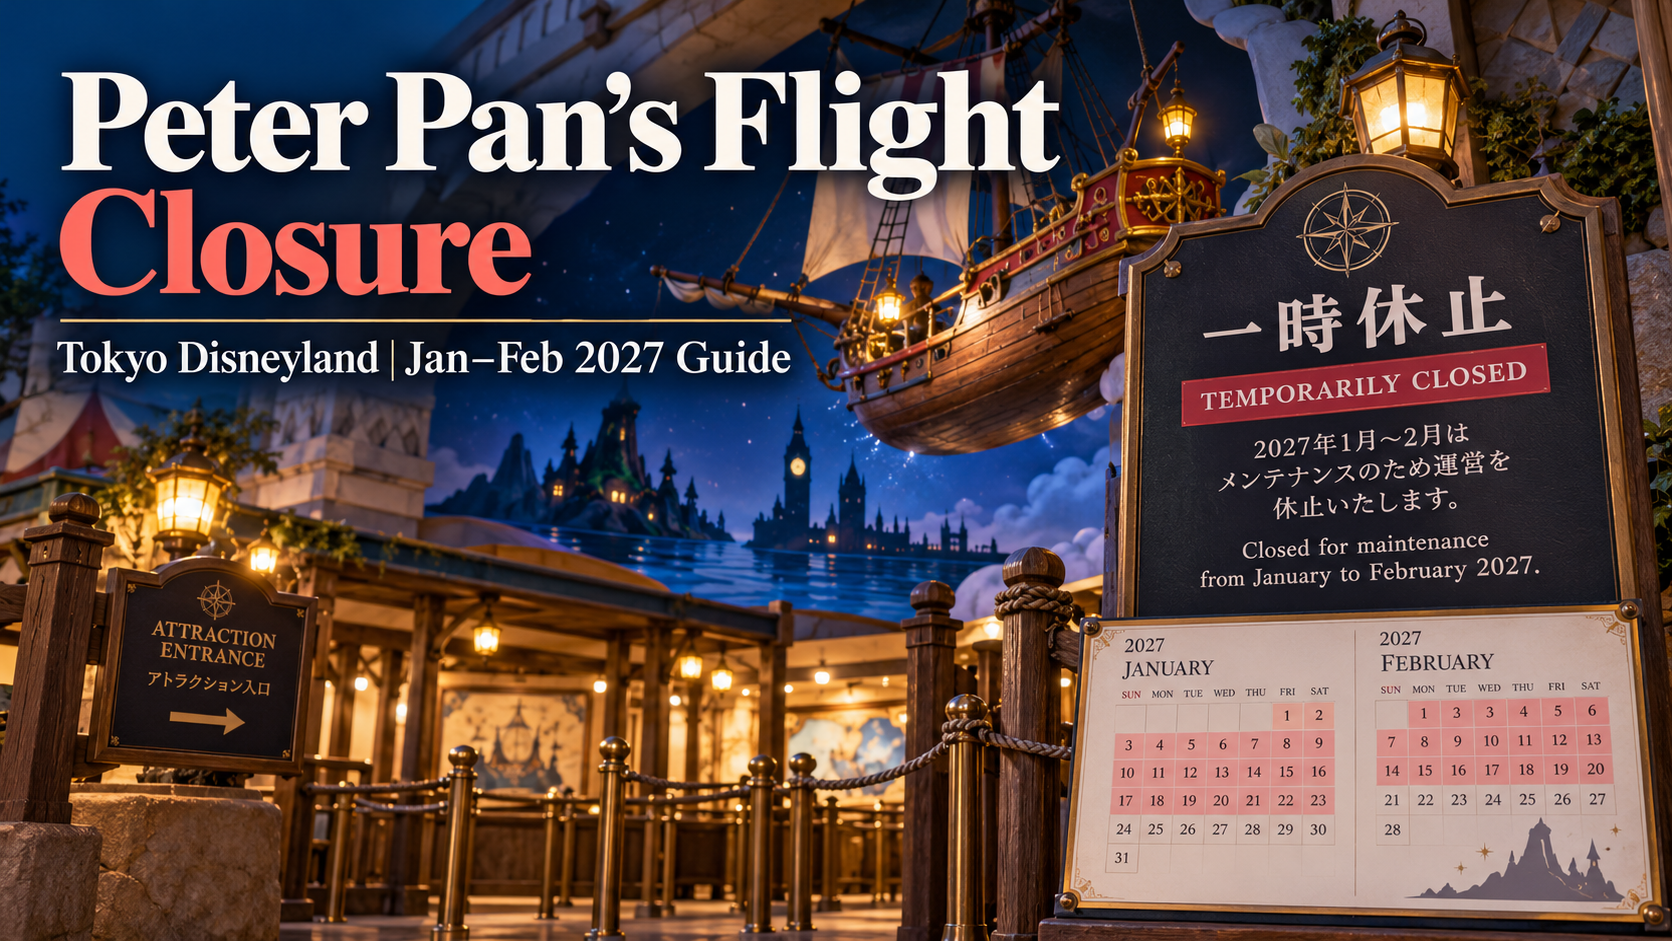
Guests planning a visit to Tokyo Disneyland in early 2027 should put one easily missed detail on their itinerary: Peter Pan’s Flight is scheduled to be temporarily closed from January 6 through February 2, 2027. The operator lists the dates both on its official attraction page and in the Tokyo Disneyland closure schedule. This is a scheduled interruption, not an announcement that the classic ride is being removed permanently. Travelers visiting on dates inside that window should assume the attraction will not be available unless Tokyo Disney Resort publishes a change.
The distinction matters because online references to “Peter Pan closing at Tokyo Disney” can confuse two different parks and two different experiences. Tokyo Disneyland’s Peter Pan’s Flight is a compact Fantasyland ride. Tokyo DisneySea has a separate, newer attraction called Peter Pan’s Never Land Adventure, with its own planned March 2027 maintenance period. The first planning step is making sure the information applies to the ticket you actually bought.
At a glance: what the operator currently says
| Planning question | Verified answer |
|---|---|
| Which attraction? | Peter Pan’s Flight |
| Which park? | Tokyo Disneyland, Fantasyland |
| Scheduled closure starts | January 6, 2027 |
| Scheduled closure ends | February 2, 2027 |
| Reopening expectation | After the listed closure window, subject to operator changes |
| Type of notice | Temporary closure; not announced as permanent |
| Where to recheck | Official attraction listing |
The dates are explicitly labeled as a temporary closure by Tokyo Disney Resort. Do not treat February 3 as an unconditional reopening guarantee: an operator may update maintenance information or temporarily suspend operations for other reasons. Check again shortly before travel and on the day you enter the park.
What is Peter Pan’s Flight?
Peter Pan’s Flight is a dark ride based on the familiar journey from London to Never Land. Guests sit in a flying pirate-ship vehicle that travels through a storybook environment. According to the operator’s ride information, it is in Fantasyland, lasts about two and a half minutes and carries two people per vehicle. It operates indoors and includes dark spaces. These details make it particularly appealing to families who want a gentle, classic Disney experience rather than a high-speed thrill ride.
There are restrictions worth noting even on operating days. The published guidance says a guest must be able to maintain a stable seated position independently and that children may not be held on an adult’s lap during the ride. If your group includes young children, anyone needing seating assistance or visitors uncomfortable with darkness, read the official description and accessibility guidance rather than assuming that the attraction suits everyone because it is short.
Short ride duration is not the same as short waiting time. Demand for well-known classics can vary with crowds, operating conditions and holiday schedules, so it is unwise to schedule a tight sequence of unrelated bookings around a predicted queue. The operator’s app and in-park staff can provide current operating information when the ride is available.
The dates around the closure are not interchangeable
A guest visiting January 5 has a fundamentally different planning position from someone arriving January 6. January 5 falls before the currently listed closure, while January 6 is its opening day. A February 2 visit falls on the final listed day of the maintenance window; February 3 is the earliest day after that window, not a contractual promise that the ride will run.
For a family staying at the resort for multiple days, the difference might be worth changing which day is assigned to Tokyo Disneyland. If one day is before January 6 and another is inside the closure, put Disneyland first if the classic Peter Pan ride is a must-do. But do not swap a park ticket or hotel reservation until you understand the applicable change and cancellation conditions. The economic cost of reshuffling an entire trip can exceed the benefit of experiencing one short ride.
A visitor traveling from overseas may be choosing between a single Disneyland day and a DisneySea day. In that case, consider the trip’s overall priorities. Someone who values vintage Fantasyland attractions may still prefer Disneyland even during the closure. Someone traveling expressly for an immersive Peter Pan adventure could be more interested in the DisneySea attraction—but must buy admission to that different park and verify its own operating schedule.
Other Tokyo Disneyland closures during the same period
The official park maintenance listing shows other attractions with early-2027 closure windows that may overlap your visit. At the time of this review, it lists Jungle Cruise: Wildlife Expeditions from January 6 through March 31, Splash Mountain from January 7 through February 4, and Haunted Mansion from January 8 through February 4. These are operator-published schedules, not independent predictions about refurbishment completion.
This makes the Peter Pan closure more significant for certain visitors than a single unavailable ride might suggest. A group that expected several classic experiences in one afternoon could find multiple priorities temporarily inaccessible. Conversely, the park contains many other attractions and entertainment offerings, and the attractions that remain open should be evaluated on their own current descriptions rather than guessed from historical schedules.
It is worth making a small “must ride / would enjoy / optional” list. Mark each attraction against the closure page. Then build flexibility around weather, performance calendars and queue variation. A plan with alternatives is more resilient than a rigid minute-by-minute schedule.
Better alternatives for different kinds of visitors
If the attraction’s appeal is gentle fantasy storytelling, explore other Fantasyland offerings listed in the official Tokyo Disneyland attraction directory. Filter for ride type and height or access restrictions, and read the current operating details. Do not assume that a neighboring attraction will be open merely because it is not listed in an older travel blog.
If the main attraction is Disney character immersion, devote time to character experiences, themed areas, shopping or scheduled entertainment that is actually available on your day. These can preserve the spirit of the trip without pretending they are substitutes for the ride itself. Some guests will prefer to spend the recovered time on a longer headliner; others may value an unhurried lunch and a park exploration that is less vulnerable to queues.
If the trip is built around Peter Pan specifically, Tokyo DisneySea’s Never Land Adventure may appear attractive. But it is not the same ride: it is a 3D boat-based experience in Fantasy Springs, with different restrictions and a different length. Tokyo Disney Resort’s DisneySea attraction page is the reliable way to compare them. Admission, access arrangements and the day’s capacity remain separate questions.
Parents should also avoid overstating the value of a replacement to children. “Another attraction has pirates” does not make it the planned Peter Pan experience. Setting expectations before entering the park is often more effective than negotiating disappointment in a crowded queue area.
Are refunds or ticket changes automatic?
The announcement of an attraction’s temporary closure does not itself demonstrate that every guest is entitled to a ticket refund or a date change. Theme-park tickets ordinarily grant admission subject to operating conditions, not a binding guarantee that every individual ride will operate. Actual ticket terms, package conditions and any operator-specific accommodation policy govern what can be changed.
Before buying or modifying a pass, review the official Tokyo Disney Resort ticket and reservations guidance and any reseller’s terms. A third-party package might combine transport, hotel rooms and tickets under separate cancellation rules. You should not rely on the statement “ride closed” as a universal reason for a penalty-free cancellation.
If your booking is complex, write down the name of the supplier, reservation reference, exact park date and type of admission. Seek a written answer before paying a change fee. This is particularly important if you plan to move only one day of a multi-day trip and keep the remainder unchanged.
Does Disney Premier Access help during the closure?
No paid queue-management product can make an attraction operate while it is closed. Disney Premier Access is a separate, paid tool for eligible operating experiences; eligibility and availability can change. The official Premier Access guide explains that places may sell out and that the price does not include park admission. It should not be marketed to families as a guaranteed workaround for a published maintenance closure.
The app can nevertheless be useful for other attractions and live operating information. If a ride is unavailable, remove it from the day’s queue-management plan and redirect attention to attractions genuinely offered that day. Check the current product terms before purchasing any additional access.
How to build a more reliable 2027 itinerary
Start with the official attraction closure list rather than the social-media version of it. Choose a date, read the list for the correct park, then check the pages for the two or three attractions most important to your group. If several favorites overlap with closures, compare another travel day, but preserve buffer time and cost limits.
Once you have a provisional itinerary, check whether your whole group can experience the alternatives. A family with a toddler and grandparents may have different needs from a group of teenagers. Ride seating rules, dark environments, height restrictions and walking distances deserve attention before buying optional upgrades.
A week before departure, look at the operator’s park calendar and attraction pages again. On the morning of your visit, follow current app information and staff instructions. Write down a backup plan that does not depend on a single ride reopening on the first conceivable day.
Quick visitor questions
Is Peter Pan’s Flight shutting permanently? The published notice says temporary closure January 6–February 2, 2027. It does not announce permanent removal.
Is it in Tokyo Disneyland or DisneySea? Peter Pan’s Flight is in Tokyo Disneyland’s Fantasyland. DisneySea has the separate Never Land Adventure.
Can I ride on February 2? The current listing includes February 2 in the closure window. Do not plan on riding that day.
Is February 3 the official reopening day? It is the first day after the presently announced closure period, assuming the dates are unchanged. Confirm the park’s live information rather than treating operation as guaranteed.
Should I change my trip? That depends on how important this specific ride is compared with hotel, flights, admission and other attractions. For most travelers, adjusting priorities within the same park is the lower-risk first option.
Final planning advice
This news is not a farewell to Peter Pan’s Flight. It is a defined, temporary gap in the operating calendar. The useful response is to check your exact visit date, compare the rides your family actually cares about and keep a realistic alternative ready. Tokyo Disneyland can still be an appealing destination during the listed closure; the difference between an enjoyable trip and a frustrating one may simply be accurate expectations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Nvidia Stops Reporting Singapore Revenue After It Hit 22% of Sales: What Investors Need to Know

Global Trade and Tariffs 2026:WTO Barometer Still Shows Growth

Extended Producer Responsibility Changes and the UK Hospitality Sector

GDP and Economic Growth in the US: How It’s Measured, Current Trends

Economic Globalization: How Global Trade Shapes the US Economy, Jobs, and Consumers

Best Life Insurance Companies in the United States 2026: Our Top 5 Picks

Pakistan Auto Policy 2026-31 Explained: EV Tax Cuts, $6 Billion Export Target

When Dollar Debt and Food Imports Collide: The Currency Squeeze

Why Freight and Storage Costs Keep Food Prices High After Oil Falls

Personal Injury Lawyer Near Me in NYC: How to Find the Right Attorney After an Accident

Why Falling World Food Prices Do Not Always Lower Grocery Bills

Oil Shocks and Core Inflation: Why the Two Move Differently

Singapore Cannot Fight Financial Fraud by Making Victims Bear the Risk Alone

Singapore Banking’s Real Test: Beyond Profits, Who Will Safeguard Financial Trust?

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Power Grid Emergency Across 13 States? What the October 2026 PJM Order Actually Says
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025