
AI
The Voice of the Next Billion: How Uplift AI is Rewiring the Global South’s Digital Frontier

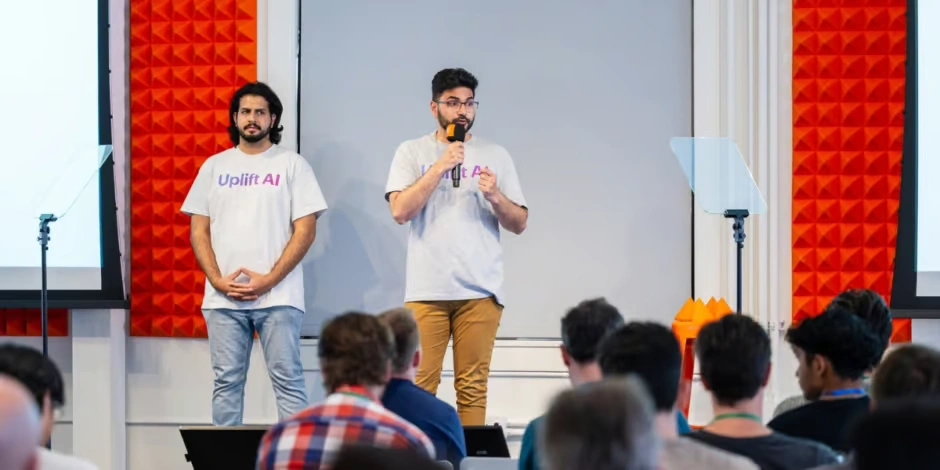
KARACHI — In the sun-drenched cotton fields of southern Punjab, a farmer named Bashir holds a cheap Android smartphone. He doesn’t type; he doesn’t know how. Instead, he presses a button and asks a question in his native Saraiki. Within seconds, a human-sounding voice responds, explaining the exact nitrate concentration needed for his soil based on the morning’s weather report.
This isn’t a speculative vision of 2030. It is the immediate reality being built by Uplift AI, a Pakistani voice-AI infrastructure startup that recently announced a $3.5 million seed round in January 2026. Led by Y Combinator and Indus Valley Capital, the round marks a pivotal shift in the global AI narrative—one where the “next billion users” are brought online not through text, but through the primal, intuitive medium of speech.
A High-Stakes Bet on Linguistic Sovereignty
The funding arrives as Pakistan’s tech ecosystem stages a gritty comeback. Following a 2025 rebound that saw startups raise over $74 million—a 121% increase from the previous year’s doldrums—Uplift AI’s seed round represents one of the largest early-stage injections into pure-play AI in the region.
Joining the cap table is an elite syndicate including Pioneer Fund, Conjunction, Moment Ventures, and a group of high-profile Silicon Valley angels. Their conviction lies in a sobering statistic: 42% of Pakistani adults are illiterate. For them, the LLM revolution of 2023–2024 was a spectator sport. By building foundational voice models for Urdu, Punjabi, Pashto, Sindhi, Balochi, and Saraiki, Uplift AI is effectively building the “operating system” for a population previously locked out of the digital economy.
The Engineers Who Left Big Tech for the Indus Valley
Uplift AI’s pedigree is its primary moat. Founders Zaid Qureshi and Hammad Malik are veterans of the front lines of voice technology. Malik spent nearly a decade at Apple and Amazon, contributing to the core logic of Siri and Alexa, while Qureshi served as a senior engineer at AWS Bedrock, designing the very guardrails that govern modern enterprise AI.
“Off-the-shelf models from Silicon Valley treat regional languages as an afterthought—a translation layer slapped onto an English brain,” says Hammad Malik, CEO of Uplift AI. “We built our Orator family of models from the ground up. We don’t just translate; we capture the cadence, the cultural nuance, and the soul of the language.”
This “ground-up” philosophy involved a massive, in-house data operation. The startup has spent the last year recording thousands of hours of native speakers across Pakistan’s provinces to ensure their Speech-to-Text (STT) and Text-to-Speech (TTS) engines could outperform global giants like ElevenLabs or OpenAI in local dialects. According to the company, their models are currently 60 times more cost-effective for regional developers than Western alternatives.
Traction: From Khan Academy to the Corn Fields
The market’s response suggests the founders’ thesis was correct. Uplift AI has already secured high-impact partnerships:
- Khan Academy: Dubbed over 2,500 Urdu educational videos, slashing production costs and making world-class education accessible to millions of non-reading students.
- Syngenta: Deploying voice-first tools for farmers to receive agricultural intelligence in their local dialects.
- Developer Ecosystem: Over 1,000 developers are currently utilizing Uplift’s APIs to build everything from FIR (First Information Report) bots for police stations to health-intake systems for rural clinics.
| Language | Status | Market Reach (Est.) |
| Urdu | Live | 100M+ Speakers |
| Punjabi | Live | 80M+ Speakers |
| Sindhi | Live | 30M+ Speakers |
| Pashto | Beta | 25M+ Speakers |
| Balochi/Saraiki | In-Development | 20M+ Speakers |
Competitive Landscape: The Regional “Voice-First” Race
Uplift AI does not exist in a vacuum. In neighboring India, well-funded players like Sarvam AI and Krutrim are racing to build sovereign “Indic” models. However, Uplift’s focus on voice-first infrastructure rather than just text-based LLMs gives it a unique edge in markets with low literacy and high mobile penetration.
While global giants like AssemblyAI or OpenAI’s Whisper offer multilingual support, they often struggle with “code-switching”—the common practice in Pakistan of mixing Urdu with English or regional slang. Uplift’s models are natively trained to understand this linguistic fluidity, making them the preferred choice for local enterprises.
Macro Implications: AI as a GDP Multiplier
The significance of this round extends beyond a single startup. It signals Pakistan’s emergence as a serious contender in the “Sovereign AI” movement. By investing in local infrastructure, the country is reducing its “intelligence trade deficit”—the reliance on expensive, foreign-hosted models that don’t understand local context.
According to Aatif Awan, Managing Partner at Indus Valley Capital, “Voice is the primary gateway to the digital economy in emerging markets. Uplift AI isn’t just a tech play; it’s a productivity play for the entire nation.”
The startup plans to use the $3.5M to expand its R&D team and begin its foray into the MENA (Middle East and North Africa) region, targeting other underserved languages. As the “Generative AI” hype settles into a phase of practical utility, the real winners will be those who can connect the most sophisticated technology to the most fundamental human need: to be understood.
What’s Next?
The success of Uplift AI suggests that the next phase of the AI revolution won’t happen in the boardrooms of San Francisco, but in the streets of Karachi and the farms of Multan. By giving a digital voice to the 42% who cannot read, Uplift AI is not just building a company—it is unlocking a nation.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


In an era defined by global economic volatility, supply chain fracturing, and the relentless search for post-pandemic growth drivers, middle powers face a stark choice: passively import technological paradigms dictated by foreign tech superpowers or aggressively architect a sovereign framework that harnesses next-generation efficiencies. Under Prime Minister Anthony Albanese, Australia has chosen the latter.
Navigating the delicate equilibrium between accelerating productivity gains and enforcing robust governance, the Albanese administration’s strategic pivot toward artificial intelligence (AI) has emerged as a compelling blueprint for modern statecraft. Far from a mere policy footnote, Australia’s calculated embrace of AI integration is positioning the nation’s economy for an unprecedented transformation—one projected to inject billions into the domestic ledger while safeguarding social cohesion.
The Productivity Imperative: Bridging the Gap
For years, advanced economies have grappled with sluggish productivity growth—a trend that has severely tested traditional fiscal and monetary levers. Australia has been no exception, confronting multi-decade lows in labour productivity growth that have squeezed profit margins, constrained real wage progression, and fueled cost-of-living anxieties.
Enter artificial intelligence. Economic modelling highlights that large-scale AI adoption could unlock up to AUD $142 billion annually for the Australian economy by 2030, serving as a multi-factor productivity catalyst. Rather than viewing technological automation as a displacement threat, Canberra’s policy machinery has reframed AI as an essential force multiplier across key national sectors—from mining optimisation and agricultural tech to precision manufacturing under the Future Made in Australia agenda.
Small and medium-sized enterprises (SMEs)—the lifeblood of the domestic economy—stand to gain immensely. By automating administrative burdens, streamlining compliance, and optimising supply chain logistics, AI integration allows local businesses to redirect capital toward innovation and high-value creation.
Pioneering a World-First Regulatory Framework
What separates Australia’s approach from the fragmented regulatory environments of the United States or the heavy-handed compliance models of the European Union is its proactive, harmonised architecture.
In July 2026, the Albanese government unveiled a world-leading national AI framework designed to provide certainty for investors while establishing strict guardrails for ethical deployment. Key pillars of this strategy include:
- Sovereign Standards and Intellectual Property Protection: Australia became a global pioneer by enacting clear protections ensuring that local creative works, literature, music, and journalistic output cannot be scraped for AI training models without explicit artist consent and compensation.
- Streamlined Compliance for Frontier Investments: By establishing unified national standards, the framework cuts through bureaucratic red tape, offering international investors expedited approval pathways conditional on adherence to safety and security benchmarks.
- A Binding Social Licence: The framework emphasises that technology must serve human agency. Ensuring public trust remains paramount; algorithms cannot operate as black boxes when critical public services, employment markets, and national security are involved.
Navigating the Geopolitical and Economic Crosswinds
Australia’s economic strategy does not exist in a vacuum. As great power competition reshapes global trade and globalisation pivots toward regional resilience, Canberra is leveraging its vast reserves of critical minerals, rare earths, and clean energy assets.
AI acts as the computational glue binding these traditional resource strengths with future-facing capabilities. For instance, optimising the extraction and processing of critical minerals required for global energy transitions relies heavily on advanced machine learning models and automated logistics. By coupling its natural resource abundance with top-tier university research and skilled graduate pipelines, Australia is making a compelling pitch to global venture capital: come build here, on Australian terms.
Comparative Strategic Advantages
| Strategic Pillar | Traditional Model | Australia’s AI-Integrated Approach |
| Productivity Driver | Capital investment & raw volume expansion | Multi-factor efficiency via sovereign AI deployment |
| Regulatory Stance | Reactive policy or unbridled laissez-faire | Proactive, world-first unified national standards |
| Workforce Strategy | Reliance on lagging skills adaptation | Empowering workers through institutional AI literacy and secure transitions |
| IP & Innovation | Lax protections for digital creators | Enforceable ownership rights over AI training inputs |
The Road Ahead: Can Australia Stick the Landing?
While the macroeconomic projections are dazzling, translating policy ambition into structural reality carries inherent risks. The success of Albanese’s vision will ultimately be judged by execution metrics over the remainder of the decade:
- Skills Alignment: Ensuring that the national education and vocational training sectors can rapidly upskill workers to meet the demands of an AI-augmented labour market.
- Cybersecurity Resilience: As critical infrastructure becomes increasingly digitised and reliant on automated machine-learning networks, national security frameworks must scale defensively to prevent state-sponsored cyber exploitation.
- Equitable Distribution: Ensuring that productivity dividends do not concentrate solely within major metropolitan tech hubs, but actively flow to regional communities and working-class Australians.
Conclusion
Australia’s economic narrative under the Albanese administration is shedding the old tropes of the “lucky country” relying purely on cyclical commodity booms. Instead, it is writing a new chapter of purposeful economic design. By harmonising technological disruption with rigorous ethical standards and worker-centric policies, Australia is proving that middle powers do not have to be passive spectators in the digital revolution—they can help write the rules of the game.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings.
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
Asian equities illustrate the danger of treating the region as a single asset class. Reuters reported on November 6 that South Korea’s Kospi had fallen about 8% and Japan’s Nikkei about 5% during the regional technology rout, while India’s Nifty 50 advanced roughly 0.51%. The divergence is notable because investors had spent years viewing Asian markets through a shared narrative of AI-led investment and export growth.
The IMF’s October Asia-Pacific outlook anticipated regional growth easing from 4.8% in 2026 to 4.4% in 2027, while still contributing disproportionately to global expansion. That is a strong headline but no guarantee for any individual exchange or company.
Chip supply chains create asymmetric risk
Japan, South Korea and Taiwan occupy different parts of the semiconductor, component and manufacturing ecosystem. Memory producers, equipment makers and foundries benefit when chip production and installation accelerate. Their shares can also fall sharply if markets question the volume, margins or ultimate returns on AI investment.
It is simplistic to equate the market reaction with the disappearance of AI demand. A business may continue growing while its share price corrects because valuations previously assumed flawless execution for years. Investors must separate an actual order cancellation from a fall in the multiple they are willing to pay for those orders.
India offers a different earnings composition.
India’s benchmarks include substantial financial, consumer and domestic-facing businesses. Lower imported crude prices can improve macroeconomic expectations through inflation, the trade balance and corporate margins. Reuters reported strong foreign buying on November 5 as sentiment improved. Such resilience can be meaningful even though it may reverse on later sessions.
An index’s headline performance can also conceal divergence. Financials may rise while smaller companies, richly valued technology suppliers or exporters weaken. A well-constructed comparison checks market breadth and earnings concentration instead of stopping at one benchmark return.
China and Hong Kong face their own constraints.
Chinese and Hong Kong-listed assets respond to property conditions, domestic consumption, export restrictions, currency dynamics and policy credibility. Their technology exposure overlaps with but is not identical to the U.S. AI trade. If global investors rotate away from expensive semiconductor leaders, relative valuations can help other markets—but only where credible profit growth supports them.
Exchange-rate effects complicate international performance. A local index can rise in home currency and still lose value for an investor whose base currency strengthens. Cross-border comparisons should therefore state whether results are in local currency or U.S. dollars.
Energy import dependence changes the ranking
The World Bank commodity outlook projects an elevated oil-price environment in 2026. Higher fuel prices reduce household purchasing power and raise transport and production costs in import-dependent economies. A reversal can offer relief, but the benefit varies with subsidy structures, hedging and exchange rates.
For Asian investors, the most revealing basket is not simply “technology versus everything else.” It includes oil-import sensitivity, export revenues, cash generation, financing costs and regulatory conditions. This is why a global shock can produce deeply divergent Asian sessions.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Asian market divergence |
| Interpretive opportunity | Contrast national sector mixes |
| Secondary question | Use oil import exposure |
| Next verification | Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
The regional average hides national balance sheets. Manufacturers, banks, households and governments experience an oil shock differently. Even countries in the same region may face opposite effects through exports, import bills and currencies. In this article’s subject—Asian stock markets 2026—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
The most useful comparison holds time and currency constant. Always align trading dates and specify whether reported returns are local-currency returns, translated-dollar returns or total returns. Otherwise, a comparison can be precise in appearance and misleading in substance. Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Contrast national sector mixes. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Use oil import exposure. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Separate multiple compression from demand. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three Asian market paths worth distinguishing
Technology spending stabilises. Asian chip exporters could recover if cloud companies reaffirm orders and memory suppliers report stable contract pricing. The recovery would still be uneven: a foundry, a memory producer and a consumer-electronics manufacturer respond to different demand drivers. Confirmation should come from corporate order books and earnings rather than a single regional index rebound.
A deeper investment retrenchment. If financing and power constraints delay new data-centre capacity, export-orientated producers in Japan, South Korea and Taiwan could face prolonged multiple compression and order revisions. Currency volatility may intensify foreign-investor returns, while an oil-price rebound would again pressure importers. The IMF’s regional growth projection would remain a baseline, not proof that equity earnings are safe.
Domestic-market rotation persists. India could continue to outperform on better energy terms of trade, bank earnings and household consumption even while North Asian technology stocks remain volatile. Yet an inflow-driven rally becomes fragile if valuations run ahead of earnings. Compare domestic profits, net foreign flows and oil import costs within each country before making regional generalisations.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
Questions readers are asking
Why did India outperform some Asian markets on November 6?
Reuters highlighted lower oil prices, foreign inflows and rotation away from AI-related names as important contributors.
Are all Asian technology stocks exposed equally?
No. Memory, foundry, equipment, consumer electronics and software firms face different customers and valuation risks.
Does lower oil help every Asian country?
No. Net importers often benefit, while exporters and energy producers can be hurt, subject to domestic policy and exchange rates.
Which data matters for an Asia comparison?
Synchronised index closes, local currency moves, industry weights, foreign flows, sovereign yields and corporate earnings.
The judgement
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. The most responsible conclusion is conditional: Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The November 5 sell-off was not confined to technology shares. It exposed the connections among data-centre financing, bond yields, energy risks and investor leverage.
The November 5 sell-off was not confined to technology shares. It exposed the connections among data-centre financing, bond yields, energy risks and investor leverage. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
Wall Street’s November 5, 2026 session delivered a severe reversal. The Associated Press reported that the S&P 500 fell 4.4%, the Nasdaq Composite dropped 5.5% and the Dow lost 3.4%. Reuters identified the semiconductor complex as a central source of selling, amid concern that projected AI infrastructure spending could be harder to finance and monetize.
A single bad session cannot establish a recession or the collapse of a technology cycle. It can, however, force investors to distinguish businesses with self-financing earnings from projects whose valuations depend on cheap capital, permissive regulation and uninterrupted investment commitments.
Why semiconductor losses spread
The transmission mechanism begins with highly valued shares. When expected growth is revised downward, a large stream of distant future profits is discounted more heavily. Selling can accelerate as leveraged funds reduce exposures and benchmark-driven investors rebalance. If lenders become more cautious, the market repricing can affect the cost of building the very data centers that underpinned the bull case.
This feedback loop differs from a conventional earnings disappointment. It touches suppliers, cloud platforms, power equipment, utilities and firms building computational infrastructure. It also reaches international exchanges with heavy chip exposure. The critical question is whether financing constraints become durable or whether markets simply reset excessive valuation assumptions.
The bond market is the other half of the story
Stocks and government bonds are not independent safety valves. High bond yields increase the discount rate used to value future profits and the financing rate paid by capital-intensive builders. Reuters reported a U.S. 10-year Treasury yield around 4.835% after the November 5 close; that is a dated snapshot, not a current quote.
For global investors, currency movements add another layer. A stronger dollar can tighten financial conditions for foreign borrowers with dollar liabilities, even if local equity benchmarks have comparatively limited direct U.S. technology exposure. A disciplined market report therefore tracks yields, credit spreads and currency moves alongside equity indexes.
Oil can offset some damage but not every risk
The World Bank expects world energy prices to rise sharply in 2026 amid supply disruptions, while projecting moderation during 2027. Short-term crude declines may ease inflation fears in importers, benefiting transport, consumer demand and interest-rate expectations. Yet falling oil can also reflect concern about weaker demand. Context determines whether a cheaper barrel is good news.
Markets that import fuel and export software or services may gain a temporary cushion from cheaper oil even as technology sentiment weakens. Exporters with concentrated commodity revenues may face the opposite balance.
A correction is not automatically a crisis
Price declines are observations; financial crises arise when losses impair payments, credit intermediation or institutions. Early warning signs include widening funding spreads, disorderly collateral calls, bank liquidity stress and forced liquidation in unrelated assets. The absence of such evidence means commentators should avoid treating market volatility as proof of systemic breakdown.
History offers no mechanical rebound date. What investors can do is distinguish earnings downgrades from liquidity-driven selling, and concentrated corrections from broad credit deterioration. This framing is more informative than repeatedly asking whether the bottom has arrived.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Associated Press November 5 closing recap |
| Interpretive opportunity | Explain the financing feedback loop |
| Secondary question | Distinguish a liquidity event from earnings repricing |
| Next verification | Use dated synchronized closes in all comparisons; refresh before publication after the next U.S. session. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
Time horizon changes what a market move means. A one-day price change reflects transactions at a particular moment; an earnings outlook spans quarters and years. The two should be connected by valuation assumptions rather than treated as interchangeable. Liquidity-driven selling can exaggerate short-run price changes. In this article’s subject—global markets today—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
Exposure matters more than the label on the index. Portfolios are collections of businesses, currencies, durations and funding needs. Two investors who own the same benchmark can experience different financial outcomes because of leverage, hedging and cash requirements. Use dated synchronized closes in all comparisons; refresh before publication after the next U.S. session. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Explain the financing feedback loop. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Distinguish a liquidity event from earnings repricing. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Account for energy and FX. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
The market’s three competing narratives
A violent valuation reset. Under the benign interpretation, November 5 forced the market to reduce exaggerated AI-growth assumptions while solvent businesses retained access to financing. Earnings expectations would stabilize after revisions, credit spreads would stop widening and the strongest companies could still invest from their own cash flow. Equity volatility might remain painful without becoming a broader economic downturn.
Financing pressures become self-reinforcing. The dangerous interpretation is that lower stock prices weaken the ability of infrastructure developers to issue equity, just as bond costs climb and projects face local permitting challenges. Delayed builds then reduce orders for chips, power equipment and construction services. Further earnings revisions could follow. The question is whether this loop stays among speculative developers or begins affecting investment-grade borrowing and banks.
Markets rotate, rather than collapse. A third possibility is sustained selling in concentrated AI names alongside relatively stable cash-generating companies, financials or defensive sectors. This would change the leadership of equity markets without necessarily ending the expansion. To identify the path, compare sector breadth, revised capex guidance, bond issuance terms and short-term funding conditions. Calling a bottom before those indicators settle would confuse a trading hypothesis with evidence.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
Questions readers are asking
Why did stocks fall on November 5?
A rapid repricing of AI spending, semiconductor valuations and the cost of future data-center development drove losses across U.S. indexes.
Was the Nasdaq down more than the Dow?
Yes. Reports of the November 5 close put the Nasdaq loss near 5.5% and the Dow loss near 3.4%, reflecting different index exposures.
Is this necessarily a stock market crash?
No single percentage drop answers that question. Market conventions, cumulative drawdowns and financial-system effects matter.
What indicators should traders monitor?
Market breadth, bond yields, corporate-credit spreads, earnings revisions and the persistence of selling in nontechnology sectors.
The judgment
The November 5 sell-off was not confined to technology shares. It exposed the connections among data-center financing, bond yields, energy risks and investor leverage. The most responsible conclusion is conditional: Use dated synchronized closes in all comparisons; refresh before publication after the next U.S. session. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Personal Injury Lawyer Near Me in NYC: How to Find the Right Attorney After an Accident

Why Falling World Food Prices Do Not Always Lower Grocery Bills

Oil Shocks and Core Inflation: Why the Two Move Differently

Singapore Cannot Fight Financial Fraud by Making Victims Bear the Risk Alone

Singapore Banking’s Real Test: Beyond Profits, Who Will Safeguard Financial Trust?

Nvidia’s Share Price Is Not a Scorecard for Singapore’s AI Future

The Australian Dollar Is Not Asia’s Oracle. Singapore Should Listen Anyway

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth

Why a Weaker Currency Makes Imported Food More Expensive

How Oil Price Shocks Raise Food Prices in Importing Countries

Petrol and Diesel Prices in Pakistan Today: Complete Update for 9 November 2026

Wall Street’s Renminbi Paradox: Banks, Beijing and the Dollar

The Market Economy Is Winning

Bitcoin’s Dollar Trap: The Chart That Exposes the Future of Money

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

Stock Market Crash 2026? What the November Rout Actually Tells Us

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025