
Asia
Turning Stables and Schools into Lifestyle Hubs: Malaysia Reimagines Its Old Spaces

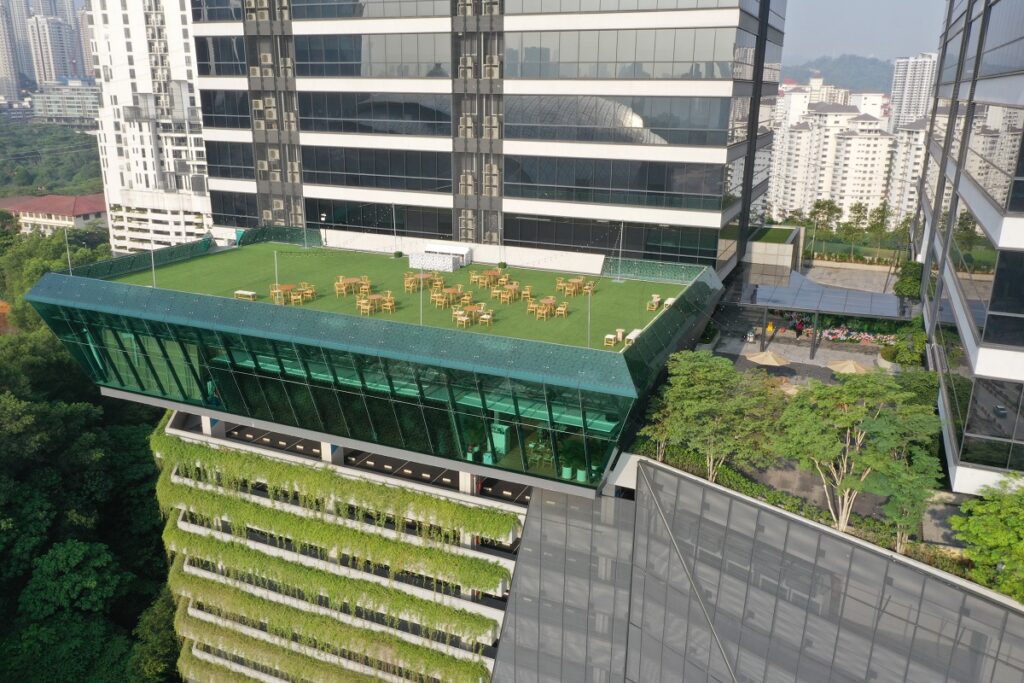
On a Saturday morning at the edge of Ipoh’s old racecourse, the air smells of Ipoh white coffee, damp timber, and something else — something harder to name. Call it momentum. Where more than 800 racehorses once stamped in colonial-era stalls, visitors now drift between artisan stalls, pausing at a betta fish gallery or a centuries-old kopitiam brand reborn in a repurposed stable lane.
The restored 60-year-old mechanical starting gate — shipped from the United Kingdom in the 1960s and now flanking the market entrance — has become, almost accidentally, the most potent symbol of modern Malaysia: a relic that still functions, still commands attention, and has found, against all probability, an entirely new reason to exist.
This is the Ipoh Stables Market, Asia’s first stable market, which opened to the public in January 2026. And it is not merely a charming weekend detour. It is the clearest expression yet of a structural shift reshaping Malaysian urbanism — one driven less by nostalgia and more by the cold arithmetic of construction economics, changing consumer psychology, and a belated national reckoning with what buildings are actually worth keeping.
The Market Realities Forcing Malaysia’s Hand
The timing of this adaptive reuse Malaysia wave is not accidental. It is, at its core, a rational response to a market that has made greenfield development increasingly punitive.
Malaysia’s construction costs have climbed steadily to approximately US$1,354 per square metre as of early 2026, according to Turner & Townsend’s International Construction Market Survey. While Malaysia remains roughly 75 percent cheaper than mature global markets like London, the direction of travel is unambiguous: expanded Sales and Service Tax (SST) measures introduced in mid-2025 have placed a six percent levy on commercial construction services, the proposed carbon tax will raise input costs for steel and energy sectors, and a tightening labour market has pushed skilled-worker pricing to levels contractors simply did not price into tenders. The Engineering News-Record’s 2026 Cost Report projects a further three percent escalation across Malaysia this year alone, with sharp asymmetric risks concentrated in commercial and mixed-use development.
For developers contemplating expensive greenfield builds in a market with already-soft commercial fundamentals — Kuala Lumpur’s office vacancy rate has been a persistent structural concern, not a cyclical blip — the calculus has shifted dramatically. When you can acquire a structurally sound heritage asset at a fraction of replacement cost and tap Budget 2026’s specific 10% income tax deduction on qualifying renovation and conversion expenditure (capped at RM10 million), with additional RM500,000 reliefs available to tourism operators registered with MOTAC, the spreadsheet begins to argue for repurposing over rebuilding almost before the pitch has been made.
This is Malaysia’s quiet adaptive reuse revolution — and it is smarter than new builds on almost every dimension that matters.
There is a demand dimension, too. Malaysia’s urban middle class — shaped by a decade of social media, by exposure to Melbourne’s laneway culture, Tokyo’s repurposed warehouses, and London’s converted Victoriana — has become acutely sensitive to what designers call placemaking: the quality of spatial storytelling that makes a destination feel irreplaceable rather than interchangeable. A 2023 study published in the Planning Malaysia Journal examining Penang’s Hin Bus Depot found that community participation and a tangible sense of cultural identity were primary drivers of both footfall and repeat visitation at heritage-led destinations — far outperforming what conventional retail metrics would predict. Younger Malaysians, specifically, are demonstrating a pronounced preference for destinations with authentic material character over the hermetically sealed environments of generic malls.
The economics reinforce this instinct. Research on adaptive reuse of colonial buildings in Malaysia, published in the Asian Journal of Environment, History and Heritage (December 2024), cites international evidence that rehabilitation projects can deliver a 9.8 percent uplift in surrounding property values, while adaptive reuse as a methodology can conserve up to 95 percent of a building’s embodied energy compared to demolition and rebuild. In a country that has just introduced a carbon tax and is committed to Kuala Lumpur’s Low Carbon Society Blueprint 2030, that embedded sustainability argument is no longer theoretical. It is policy-adjacent and commercially legible.
Four Flagship Projects Rewriting the Rules
Ipoh Stables Market: Repurposing Stables, Redefining Ipoh
The Perak Turf Club has stood at the heart of Ipoh’s social imagination since 1886. At its peak, the stables housed more than 800 racehorses across a thousand stalls. By the 2010s, the site had been whittled down to a functioning but diminished racecourse, and its historic stable blocks — structurally intact, architecturally rich — had stood dormant for over a decade.
PISM Management, entrusted with the transformation, chose restraint over spectacle. Approximately 70 percent of the original timber beams and corridor structures have been preserved. Salvaged bricks from the site — each carrying the weathered texture of a century’s activity — are incorporated throughout, not as decoration but as structural memory. The 60-year-old mechanical starting gate, an entirely functional object shipped from Britain in the 1960s, now greets visitors instead of racehorses. Project manager Suzanne Kew has described it with precision: “We’re building more than just a market — we’re nurturing a cultural ecosystem.” By January 2026’s grand opening, 137 stalls across six themed lanes had been activated, prioritising third-generation kopitiam owners, heritage food vendors, artisans and farmers who embody the spirit of old Ipoh.
What it gets right: Community curation over mass commercialisation. The vendor mix is an editorial choice, not a yield-maximisation exercise. The result is a destination with genuine specificity — Ipoh-ness — that no developer could manufacture from scratch.
REXKL: The Cinema That Refuses to Go Dark
A decade before adaptive reuse became a developer talking point in Malaysia, a group of creative entrepreneurs looked at the shell of the Rex Cinema on Jalan Sultan — scarred by three fires, last used as a backpackers’ hostel — and saw a 60,000 sq ft opportunity.
REXKL, documented by ArchDaily as a landmark of community adaptive reuse, opened in 2019 under architects Shin Chang and Shin Tseng of Mentahmatter Design. The approach was almost confrontationally minimal: retain the structure, clean and activate rather than demolish and rebuild. The grand staircase survived. The multilingual “Reserved Class” signage survived. The 1,000-seat hall, rather than being subdivided into retail cells, became an events stage and, from 2023, an 8,800 sq ft immersive digital art gallery — REXPERIENCE — deploying Unreal Engine 5, TouchDesigner, and spatial audio systems to transform the former cinema experience into something its original architects could not have imagined.
The results speak economically. REXKL has hosted over 1,000 events and empowered more than 100 social enterprises, making it not just a lifestyle hub but an active incubator for Kuala Lumpur’s creative economy. It helped to rejuvenate an entire precinct of downtown KL — the Petaling Street area — that conventional commercial logic had written off.
What it gets right: The acronym is the thesis. REXKL stands for Recycle, Empower, X-for-crossover, Knowledge and Learning. This is not branding — it is a genuine operational philosophy, and it shows.
The Campus Ampang: Malaysia’s First Adaptive Reuse Retail Development
The most commercially ambitious entry in this taxonomy is also the most instructive for the real estate sector. The Campus Ampang, officially Malaysia’s first adaptive reuse retail development, occupies the former campus of the International School of Kuala Lumpur (ISKL), established in 1976 and operating for nearly half a century before relocating.
The 140,000 sq ft site, a joint venture between Ukay Builders Sdn Bhd and Mega First Corporation Berhad, retains the swimming pool, football field, basketball courts, 500-seat auditorium, and multipurpose halls of the original school. The former canteen is now “The Playground,” a flexible events and market space. Led by HL Architecture Sdn Bhd, the design explicitly draws on Malaysian vernacular principles — passive ventilation, shaded verandas, open courtyards — rather than replicating the sealed, air-conditioned typology of a conventional mall. Folding origami-inspired roof canopies create sheltered drop-off points that reduce heat gain while functioning as visual landmarks.
As published in Architecture Malaysia magazine (December 2025), the project’s sustainability argument is structural, not cosmetic: major beams, slabs, stair cores, and the swimming pool structure were all retained and reworked, slashing both embodied carbon and construction timelines. With over 80 retail units — including QRA (launching its largest Malaysian store), Michelin-recognised Dancing Fish, and a curated roster of local brands celebrating Malaysian identity — the Campus draws from a catchment of over 650,000 people within ten minutes.
What it gets right: It does not pretend to be a mall. It is a precinct, and the spatial grammar — open, porous, sports-facility-anchored — produces a dwell time and community attachment that enclosed retail formats cannot replicate. Tatler Asia’s architectural analysis noted that the project “sets a new benchmark for adaptive reuse” in Malaysia — a verdict that, given the scarcity of genuinely ambitious precedents, carries real weight.
Hin Bus Depot, George Town: The Penang Model
Any honest assessment of Malaysia heritage buildings as lifestyle destinations must anchor itself in Penang, where UNESCO World Heritage designation has made adaptive reuse not merely fashionable but structurally embedded in the city’s identity. Hin Bus Depot, built in 1947 as a maintenance facility for the Hin Company Ltd’s fleet of blue buses, closed in the late 1990s and sat derelict until 2011, when three families with a property investment mandate encountered its Art Deco façade — rare in George Town’s predominantly Victorian and Georgian streetscape — and saw possibility rather than liability.
Established as an arts and events space in 2014 following Lithuanian street artist Ernest Zacharevic’s catalytic debut exhibition, Hin Bus Depot now functions as a fully operational creative ecosystem: gallery, artist studios, six food and beverage outlets, weekly Sunday market, and a programming calendar that in 2025 alone included collaborations with Singapore Art Week, internationally curated exhibitions, and community-rooted curatorial projects exploring Malaysian identity. Research published in the International Journal of Business and Technology Management (January 2026) confirmed that Hin Bus Depot scores highest among Penang’s repurposed heritage sites for public recognition of historical authenticity, with 59 percent of surveyed residents specifically citing heritage preservation as foundational to the site’s success.
What it gets right: Content programming as architecture. Tan Shih Thoe’s guiding principle — that the wrong content in a repurposed building will cause it to “die off” — is the most important single lesson the wider Malaysian adaptive reuse Malaysia movement needs to absorb.
Global Context: Where Malaysia Sits in the Wider Story
Malaysia is not reinventing this wheel. It is, however, spinning it faster than its regional peers — and with a cultural authenticity that separates the best of its projects from the aestheticised approximations visible elsewhere.
Singapore has pursued shophouse conversion aggressively, but the city-state’s land scarcity and regulatory precision mean adaptive reuse projects operate within tightly controlled frameworks that limit the organic, community-led dimension that makes Hin Bus Depot or Ipoh Stables Market feel alive. Barcelona’s superblocks — which repurpose road space rather than buildings, but operate from the same sustainable urban regeneration philosophy — have demonstrated how physical restructuring can shift consumption patterns and dramatically improve quality of life metrics. The UN-Habitat’s World Cities Report repeatedly cites heritage-led redevelopment as a high-leverage strategy for emerging economies seeking both tourism differentiation and community resilience, placing Malaysia’s current trajectory squarely within global best practice.
In the United States, the adaptive reuse boom has been catalysed by specific fiscal instruments — the Federal Historic Tax Credit, providing a 20 percent tax credit on qualifying rehabilitation expenditures — and has produced headline projects from Detroit’s Fisher Building to Chicago’s Fulton Market conversion. Malaysia’s Budget 2026 mechanisms are more modest in scale but represent a meaningful directional signal: government now understands that urban regeneration and adaptive reuse are not cultural indulgences but economic infrastructure.
The gentrification risk is real and should not be elided. George Town, Penang, offers the most legible warning: UNESCO designation, followed by adaptive reuse-led tourism growth, has driven residential rents in heritage corridors to levels that displace the very communities whose presence gave the district its character. The best-managed projects — REXKL’s explicit prioritisation of social enterprises, Ipoh Stables Market’s vendor curation around third-generation heritage businesses — attempt structural mitigation. But without consistent zoning protection, affordable commercial rate frameworks, and regulatory safeguards on cultural tenancy, Malaysian heritage-led redevelopment risks repeating a global pattern: curating character for visitors while pricing out the people who created it.
Malaysia’s edge over Singapore, Barcelona, or Brooklyn is precisely that it is early enough in this cycle to set better precedents. The institutional consciousness — within DBKL, within Think City, within progressive developers like those behind The Campus — is present. The policy architecture needs to follow.
Forward Outlook: 2027–2030 and the Decisions That Will Define It
The next five years will determine whether Malaysia’s lifestyle hubs — built on the bones of old schools, bus depots, racecourse stables and cinemas — constitute a genuine urban paradigm shift or an aesthetic trend that plateaus once the most photogenic assets have been absorbed.
Three developments bear watching. First, the scaling of Budget 2026’s conversion incentives: if the RM10 million deduction cap is raised and the eligibility criteria broadened to include smaller-scale heritage commercial properties, Malaysia could see a genuine second tier of adaptive reuse projects beyond the flagship developments. Cities like Ipoh, Seremban, and Taiping — which have substantial colonial-era building stock and far lower land values than Kuala Lumpur — are the obvious candidates for what might be called the democratisation of experiential retail Malaysia.
Second, Visit Malaysia Year 2026 has already elevated the tourism imperative of heritage-led destinations. If the government uses the data from this year’s visitor patterns to formalise cultural districts around active adaptive reuse clusters — the way Barcelona formally recognised and protected its barrios — the regulatory scaffolding for long-term sustainability improves dramatically.
Third, and most critically: Malaysia needs to train more architects and interior designers in adaptive reuse methodology. HL Architecture’s Martin Haeger, REXKL’s Mentahmatter, and Ipoh’s Tan Kai Lek represent a skilled but thin vanguard. As more developers recognise the financial and marketing logic of repurposing over rebuilding, the supply of competent adaptive reuse practitioners will become the binding constraint. Architecture schools, PAM (Pertubuhan Arkitek Malaysia), and CIDB need to make this a curricular priority, not an elective enthusiasm.
Bold prediction: by 2030, adaptive reuse will account for at least 20 percent of all commercial development activity in Penang and Kuala Lumpur’s urban cores, driven by a combination of rising greenfield construction costs, increasing carbon-accounting requirements, persistent commercial vacancy, and — most importantly — a consumer culture that has definitively moved on from the proposition that newer is better.
Conclusion: The Buildings Malaysia Has Always Had
There is something deeply Malaysian about the adaptive reuse instinct, even if the vocabulary is global. A culture that has, for generations, layered colonial shophouses with Peranakan tile work, converted British administrative buildings into galleries, and built entire food cultures inside corrugated-roof structures that have no business being as atmospheric as they are — this is a culture that has always known how to make old things function for new purposes.
The Ipoh Stables Market does not need to look like a European market hall to justify its existence. REXKL does not need to invoke Brooklyn to make its case. The Campus Ampang does not need Barcelona’s playbook. They are succeeding on their own terms, in their own material vocabulary, speaking to a generation of Malaysians who are, slowly and unmistakably, demanding cities that remember where they came from.
The stables stood empty for a decade. The school sat abandoned after its students left. The cinema went dark after the last fire. What Malaysia is doing, imperfectly but with increasing confidence, is deciding that the most sophisticated form of urban development is not erasure. It is continuation — at higher quality, with better programming, and with enough structural honesty to let the ghost of the original use stay visible in the walls.
That is not nostalgia. That is strategy. And in 2026, with construction costs climbing and consumer tastes maturing, it is also — finally, unmistakably — mainstream.
Further Reading & Sources:
- Turner & Townsend International Construction Market Survey 2026
- Engineering News-Record 4Q Cost Report 2026
- Malaysia Budget 2026 Property Incentives — SuperHomes Analysis
- REXKL — ArchDaily Feature
- The Campus Ampang — Architecture Malaysia Journal
- The Campus Ampang — Tatler Asia
- Hin Bus Depot Heritage Study — International Journal of Business & Technology Management
- Placemaking Study, Hin Bus Depot — Planning Malaysia Journal
- Drivers of Adaptive Reuse of Colonial Buildings in Malaysia — Asian Journal of Environment, History and Heritage
- UN-Habitat World Cities Report 2022
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
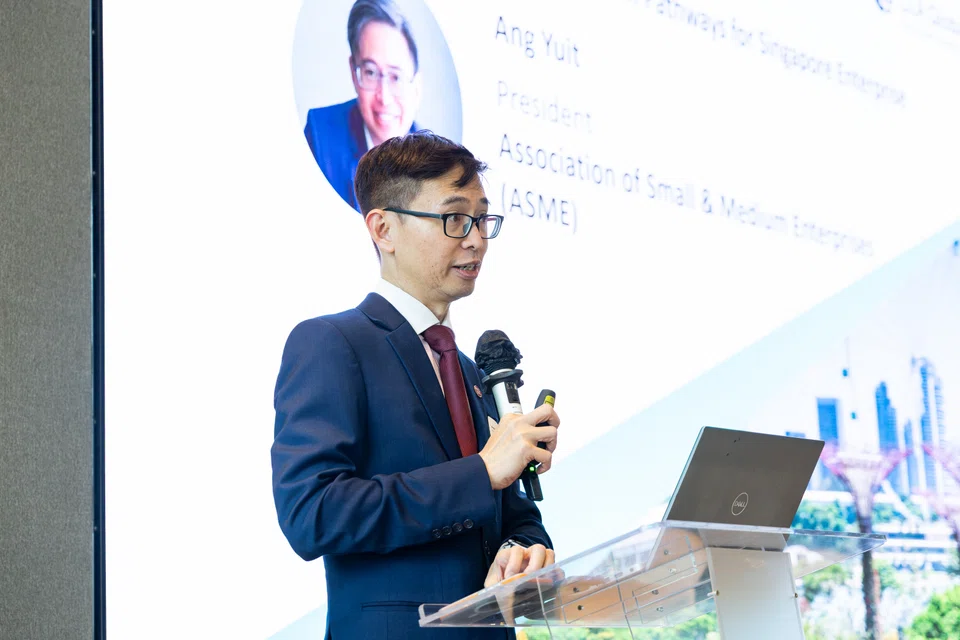
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Are Asian stock markets rising in 2026?
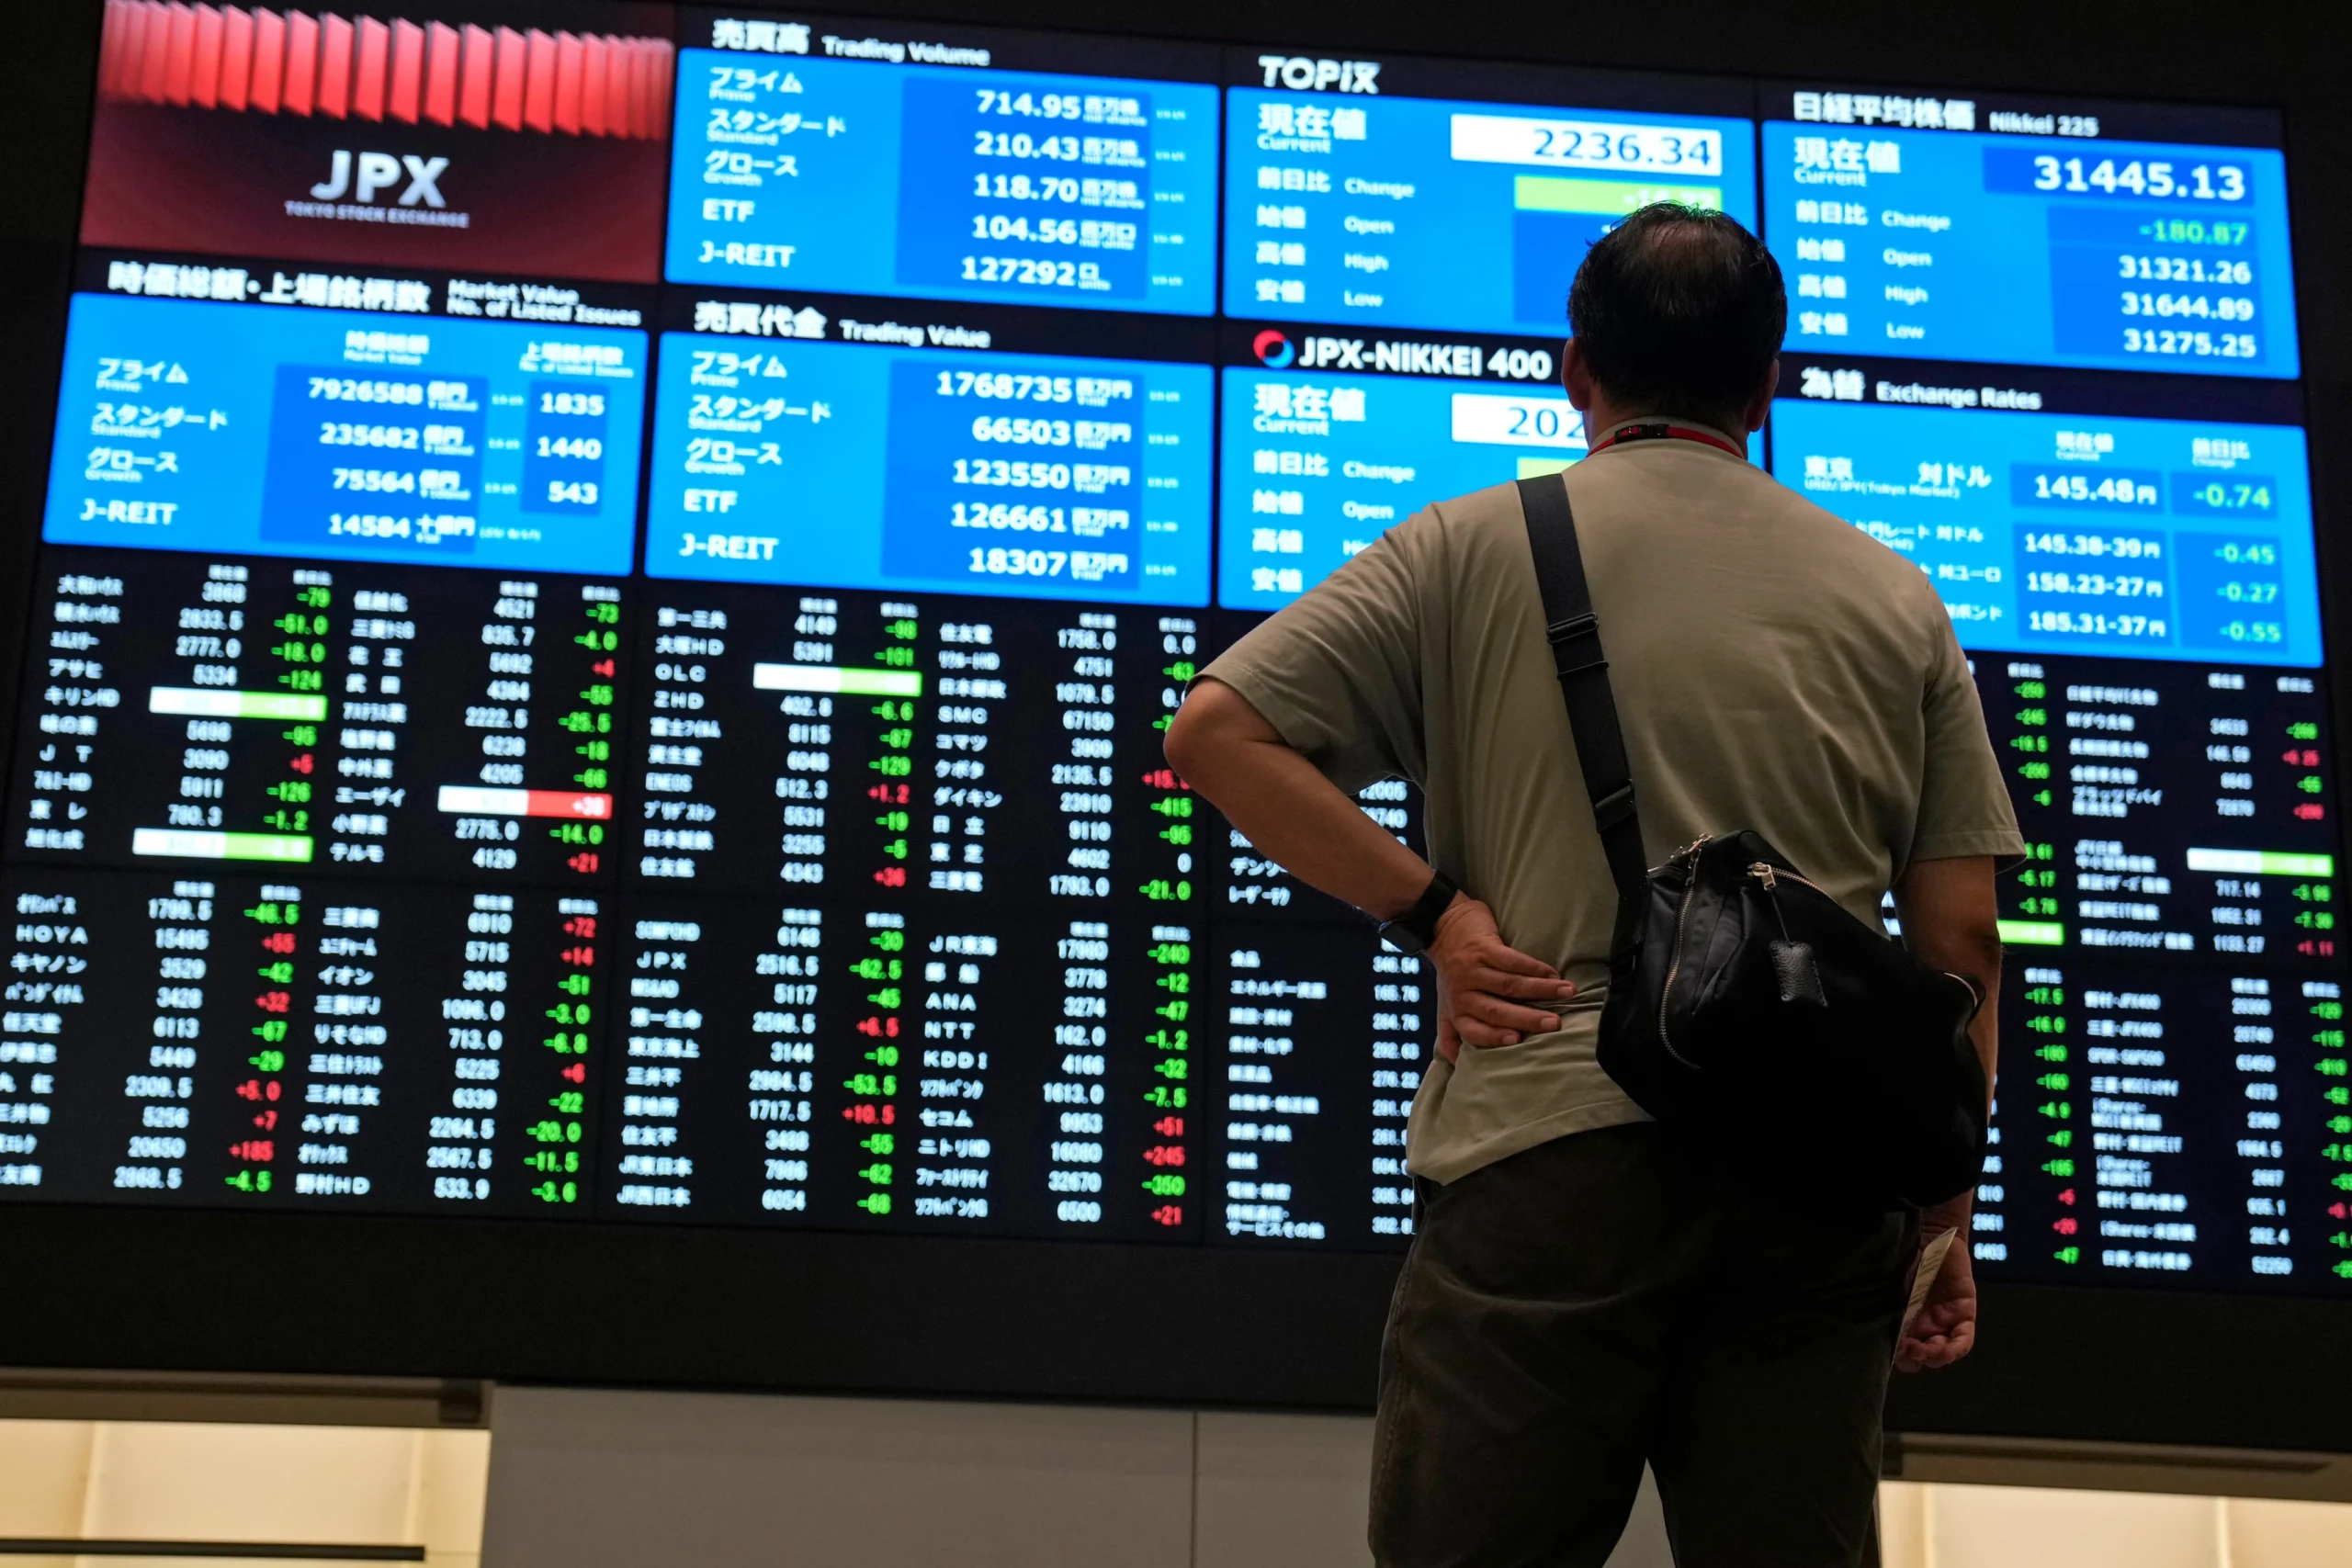
Most of them are, but for very different reasons. Japan’s Nikkei 225 is trading at levels roughly 44% higher than a year ago on continued AI-linked technology strength; China’s benchmark indices climbed to multi-year highs at the start of the year on AI optimism and signs of economic recovery; and Pakistan’s KSE-100 has been one of the most volatile large gainers globally, crossing record highs early in the year before enduring sharp single-session pullbacks in September. Understanding each market separately matters more than treating “Asia” as one trade.
Japan: A 15-Year-Plus Bull Run Meets a Hawkish Central Bank
The Nikkei 225 closed at 65,018.95 on September 18, 2026, gaining 1.38% on the session and sitting 44.34% above where it stood a year earlier, according to data compiled by Trading Economics. That move came even as the Bank of Japan raised its policy rate by 25 basis points to 1.25% — a widely expected but still consequential tightening step, as policymakers balance elevated inflation and wage growth against pressure from U.S. Treasury Secretary Scott Bessent for currency and trade cooperation. Japan’s annual inflation rate held at 1.9% in August, with core inflation at 1.7% — below the Bank of Japan’s 2% target for a seventh straight month, suggesting the central bank still has room to normalize policy gradually rather than aggressively.
Technology and AI-related names have led Japan’s rally, with chip-equipment and materials names such as Advantest and Lasertec posting some of the sharpest single-day gains, echoing similar advances on Wall Street. That correlation is a theme across the region: Asian equity performance in 2026 has tracked the U.S. AI-capex story almost as closely as it has tracked domestic fundamentals.
China: AI Optimism Meets an Overheating Warning
China’s equity markets opened 2026 on a tear. The benchmark CSI 300 Index advanced 1.6% to close at its highest level in four years on January 6, while the Shanghai Composite rose 1.5% to its strongest level since July 2015, fueled by sustained optimism over the country’s AI advances and early signs of broader economic recovery, according to Bloomberg. Materials and technology shares led the advance, and the rally coincided with a robust pipeline of onshore AI-related IPOs.
That said, the rally showed early signs of overheating even in January: the 14-day relative strength index on the Shanghai Composite climbed above 75 — firmly into technical overbought territory — a level it had not touched since the previous September. Momentum has been uneven since; by late July, the Shanghai Composite had pulled back to a 16-week low on the CSI 300 gauge even as the broader index posted modest daily gains, reflecting a market still working through the tension between AI-driven optimism and valuation discipline. On the macro side, the IMF’s own China growth revisions this year have tracked a similar push-pull, with earlier 2025 forecasts putting Chinese growth near 4.8% before moderating toward roughly 4.2% as trade and property-sector headwinds persist.
Malaysia and Singapore: Steady Gains, Regional Correlation
Malaysia’s FTSE Bursa Malaysia KLCI has spent much of 2026 grinding toward multi-year highs rather than posting dramatic single-day swings. The index touched a more-than-six-year high near 1,686 points in early January, according to New Straits Times, and by early September had climbed further to around 1,714–1,715 points, per Bursa Malaysia futures data reported by Bernama, Malaysia’s state news agency. Analysts at Rakuten Trade have described the index as being in a healthy uptrend across both short- and long-term timeframes, with pullbacks read as consolidation rather than a change in trend.
Singapore’s Straits Times Index has moved in tandem with regional sentiment through the year, trading in the high-3,900-point range during mid-2026 sessions alongside comparable moves in Hong Kong’s Hang Seng and South Korea’s Kospi — a reminder that Southeast Asian and Northeast Asian benchmarks remain tightly correlated on any given trading day, even when their underlying economic drivers differ.
Pakistan: The Region’s Most Volatile Outperformer
Featured Snippet Target: Pakistan’s KSE-100 Index began 2026 at a record high above 176,000 points, climbed further past 186,000 and 188,000 in the following days on institutional buying and expectations of a policy rate cut, but has since seen sharp single-session pullbacks — including a 3,078-point, 1.79% drop on September 10 — underscoring how the world’s best-performing frontier market in early 2026 has also been among its most volatile.
The Pakistan Stock Exchange’s rally traces back to a shift in domestic asset allocation: brokerage house Topline Securities described the move from fixed-income instruments into equities — driven by falling returns on traditional savings vehicles — as the primary fuel behind sustained liquidity and elevated valuations, according to coverage from Aaj News. Banking names including United Bank Limited, Habib Bank, and MCB, alongside energy majors like Oil and Gas Development Company, have repeatedly featured among the index’s top contributors on both up and down days.
By early September, the picture had turned choppier. The KSE-100 gained 399 points on September 4 to close at 175,328, per ARY News, before dropping over 3,000 points just days later on September 10 — a reminder that Pakistan’s rally, while historic in percentage terms, remains far more sensitive to single-session sentiment shifts than its larger regional peers.
The Cross-Market Pattern
Three threads tie these otherwise disconnected markets together in 2026. First, AI-linked capital spending is now a genuine cross-border driver — Japanese and Chinese tech names have both rallied on echoes of the same U.S. hyperscaler capex story. Second, central bank policy divergence is widening: Japan is tightening from historically ultra-loose settings, while Pakistan has been cutting rates to support a still-fragile broader economy. Third, frontier and emerging markets — Pakistan chief among them — are delivering far larger percentage swings, in both directions, than developed Asian benchmarks, rewarding investors who can tolerate volatility but punishing those who chase momentum without hedging for pullbacks.
The Bottom Line
Asia’s 2026 story is not one market but five distinct ones moving on different clocks — Japan’s AI-and-rate-hike rally, China’s optimism-versus-overheating tension, Malaysia and Singapore’s steadier regional drift, and Pakistan’s high-beta swings around a genuine structural re-rating. Anyone allocating across the region needs a market-by-market view rather than a single “Asia” thesis.
Next step: Track Bank of Japan policy meetings, China’s Politburo economic guidance sessions, and Pakistan’s State Bank Monetary Policy Committee decisions together — the three events, spaced through the remainder of 2026, are the clearest near-term catalysts for each market’s next move.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The World Bank’s June 2026 assessment carries a phrase that should stop any investor mid-scroll: a “lost decade” of development for many emerging markets.
Global growth is projected to slow from 2.9% in 2025 to 2.5% in 2026 — the lowest rate since the COVID-19 pandemic — amid weaker prospects for energy-importing economies and those directly affected by hostilities.
Within that aggregate, Asia is splitting into two distinct groups. Understanding which side an economy falls on is now the primary emerging-market allocation decision.
Key Takeaways
- Global growth: 2.5% in 2026, firming in 2027–28 as energy supplies recover and trade strengthens.
- The revision was brutal. January 2026 projected 2.6% with an upward revision; June cut it.
- India remains the outlier. FY2026-27 growth of 6.6%, rebounding to 7.2% in FY2027-28.
- China decelerates. Growth slowing to 4.4% in 2026 from 4.9%.
- The 2020s are on track to be the weakest decade for global growth since the 1960s.
The Two Reports That Define 2026
The World Bank publishes Global Economic Prospects twice a year, and the gap between the January and June 2026 editions is the story.
January: Cautious Optimism
The January report described a global economy proving more resilient than anticipated despite persistent trade tensions and policy uncertainty, with growth easing to 2.6% in 2026 before rising to 2.7% in 2027 — an upward revision from the previous June forecast.
About two-thirds of that upgrade came from the United States alone.
June: The Energy Shock
By June, the Middle East conflict had driven sharp energy price increases and the projection fell to 2.5%, with emerging market and developing economies facing the weakest per capita income growth since the pandemic.
The Bank explicitly notes that the conflict’s impact on global trade has been partly offset by robust AI-related investment, while consensus inflation expectations picked up notably following the energy price surge. Local-currency bond yields and external bond spreads remained higher in commodity importers.
That last sentence is the whole emerging-market thesis in one line: commodity importers are paying more to borrow at exactly the moment they need to borrow more.
Asia’s Two Tiers
| Economy | Projection | Position |
|---|---|---|
| India | 6.6% FY26-27, 7.2% FY27-28 | Domestic-demand-led, upgraded |
| China | 4.4% in 2026 (from 4.9%) | Export-supported, stimulus-dependent |
| EMDEs (all) | 4.0% in 2026 (from 4.2%) | Slowing |
| EMDEs excl. China | 3.7% in 2026 | Flat versus 2025 |
| United States | 2.2% in 2026 | Tax-incentive supported |
The EMDE-excluding-China figure of 3.7%, unchanged from 2025, is the number that matters most and gets quoted least. Strip out China, and the developing world is not slowing — it simply is not accelerating. Stagnation at a level too low to close income gaps.
The India Case
India stands apart in the June projections. Growth is projected to moderate to 6.6% in FY2026-27 — a 0.1 percentage point upgrade relative to January — before rebounding to 7.2% in FY2027-28, a 0.6 point upgrade.
The moderation reflects private demand cooling under input cost pressures. The rebound reflects structural factors:
- Trade agreements. Implementation of major FTAs with the EU, UK and Australia is described as crucial to offsetting cooling merchandise demand from traditional Western markets.
- FDI sustainability. Trade agreements and structural business reforms are expected to sustainably support inflows across the forecast horizon.
- Fiscal trade-offs. Lower fuel taxes and GST reforms temporarily erode the revenue base, requiring a shift toward slower public capex growth and current spending cuts to avoid deficit spikes.
That last point is the underappreciated risk. India’s growth upgrade is partly financed by revenue concessions that must eventually be reversed or absorbed.
The China Case
China’s projected slowdown to 4.4% in 2026 came with an upward revision of four-tenths of a percentage point from the previous June forecast, attributed to fiscal stimulus and increased exports to non-US markets.
That revision has since been validated by trade data. The question for 2027 is whether export strength can persist if global demand slows to the 2.5% pace the Bank projects.
China’s position is structurally different from India’s: externally driven where India is domestically driven, stimulus-dependent where India is reform-dependent.
What the “Lost Decade” Framing Actually Means
The World Bank’s language is deliberately stark. If current forecasts hold, the 2020s are on track to be the weakest decade for global growth since the 1960s and too low to avert stagnation and joblessness in emerging market and developing countries.
The distributional evidence is concrete: at the end of 2025, nearly all advanced economies enjoyed per capita incomes exceeding their 2019 levels, but about one in four developing economies had lower per capita incomes than before the pandemic.
Chief Economist Indermit Gill framed the underlying tension precisely: the global economy has become less capable of generating growth while appearing more resilient to policy uncertainty — a divergence he warned cannot persist without fracturing public finance and credit markets.
Investment Implications by Tier
Tier 1 — Energy importers in the technology value chain. India, Vietnam, Malaysia, Taiwan, Korea. AI-related export revenues offset higher energy costs. Currency and equity performance has held up.
Tier 2 — Energy exporters outside the conflict zone. Gulf states excluding those directly affected, parts of Africa and Latin America. Favourable terms of trade, fiscal space expanding.
Tier 3 — Energy importers outside the technology chain. Pakistan, Bangladesh, Sri Lanka, Kenya, much of Sub-Saharan Africa. Higher import bills, higher borrowing costs, no offsetting export windfall.
Tier 3 is where sovereign stress concentrates. Higher local-currency bond yields and wider external spreads in commodity importers mean refinancing costs rise as fiscal positions deteriorate.
What This Means for the Global Market in 2027
The 2027 recovery is conditional on two assumptions. Activity is expected to firm in 2027–28 as energy supplies recover and trade strengthens. Both require the conflict to de-escalate. Neither is guaranteed.
AI adoption is the identified upside. The Bank names artificial intelligence adoption, clean energy investment and regional trade agreements as potential long-term recovery catalysts. Only the first is currently delivering at scale.
Sovereign debt is the accumulating risk. Elevated yields in commodity importers compound every year they persist. A 2027 refinancing wave at current spreads would strain multiple frontier sovereigns simultaneously.
Regional trade agreements are the underrated policy lever. India’s FTA implementation is the clearest test case. If it delivers the projected FDI and export offset, it becomes a template for the rest of emerging Asia.
Compare the IMF and World Bank carefully. The Fund projects 3.0% for 2026; the Bank projects 2.5%. The difference is methodological — PPP versus market exchange rate weighting — not a disagreement about the world.
Frequently Asked Questions
What is the World Bank’s global growth forecast for 2026?
The June 2026 Global Economic Prospects projects global growth slowing to 2.5% in 2026, down from 2.9% in 2025 — the lowest rate since the pandemic.
What is India’s projected GDP growth?
India is projected to grow 6.6% in FY2026-27 before rebounding to 7.2% in FY2027-28, both upgrades relative to January 2026 projections.
Why are World Bank and IMF forecasts different?
The World Bank weights using market exchange rates while the IMF uses purchasing-power-parity weights, which gives more weight to faster-growing emerging economies.
What does “lost decade” mean for emerging markets?
The Bank warns the 2020s could be the weakest decade for global growth since the 1960s, with roughly one in four developing economies having lower per capita incomes at end-2025 than in 2019.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

IREN Stock in 2026: AI Cloud Growth, Bitcoin Transition and the Risks Investors Miss

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025