
Analysis
Strait of Hormuz Oil Flows Grind to a Halt Amid Escalating Israel-Iran Missile Barrage: Death Toll Mounts and Global Energy Markets Teeter

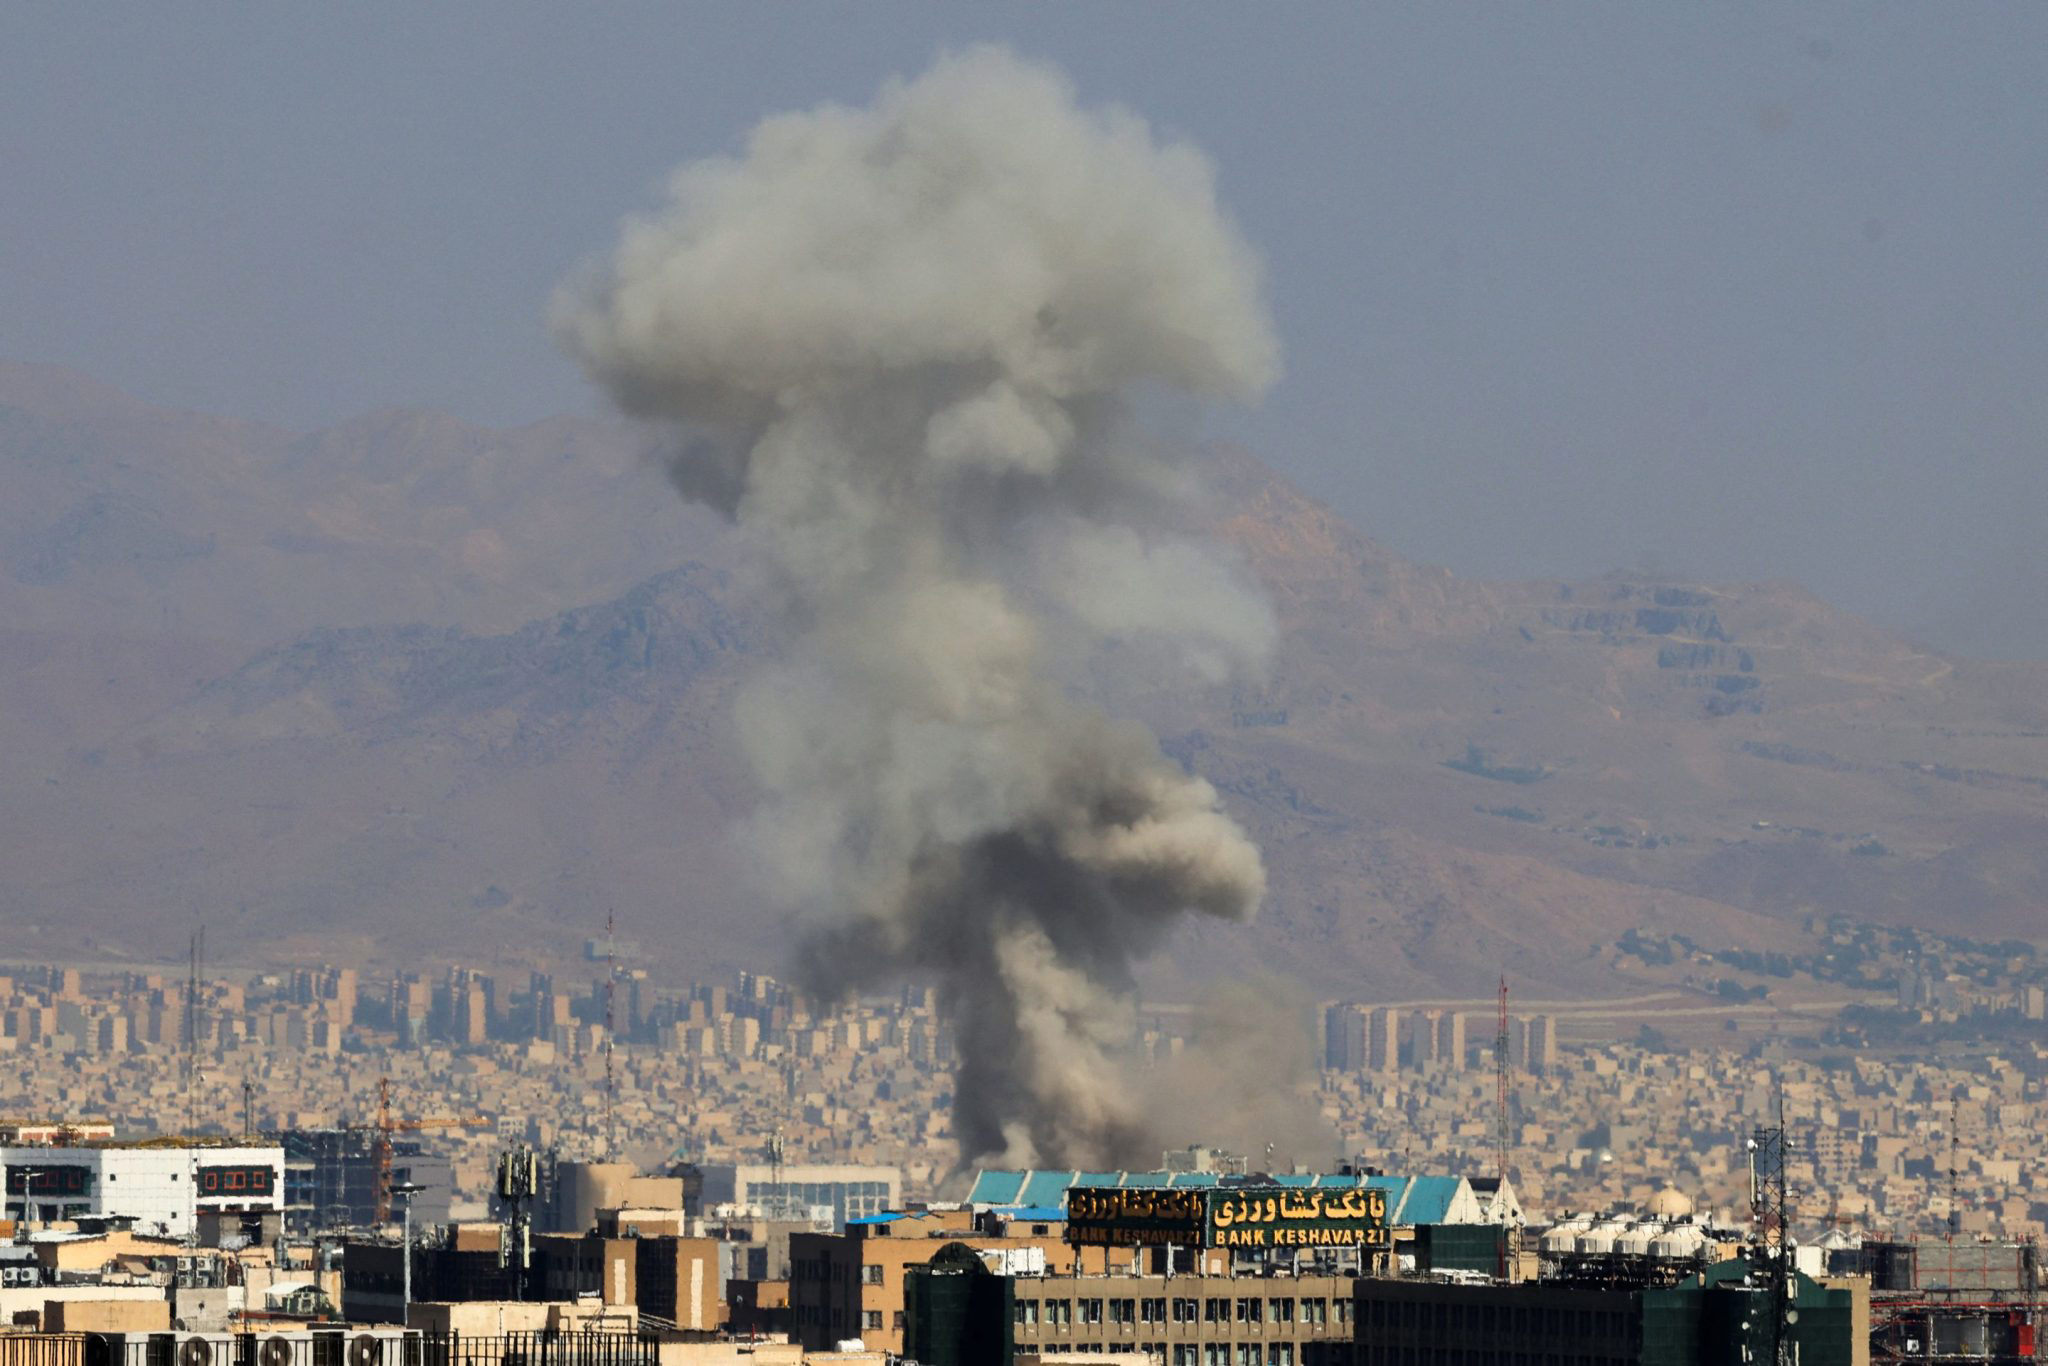
Twenty million barrels of daily oil flow hang in the balance as Iran and Israel exchange their most intensive missile salvos in the conflict’s history—threatening to transform a regional war into a global economic catastrophe.
By Staff Senior Correspondent, Global Energy Desk · With reporting from Tehran, Tel Aviv, Riyadh, and Washington Updated 2 March 2026, 14:32 GMT · 12 min read
📊 Key Metrics at a Glance
| Indicator | Value | Note |
|---|---|---|
| Brent Crude | $80.40 | ▲ +9.8% (24hr) · Eyeing $100 target |
| Flow at Risk | 20M bpd | 20% of global supply |
| Death Toll | 211+ | Iran: ~201 · Israel: ~9–10 · US: 3 |
| Tankers Halted | 47 | Major operators suspended transit |
On the morning of 2 March 2026, the Strait of Hormuz—a twenty-one-mile-wide channel that functions like a clogged artery in the global economy—fell quieter than it had in four decades of recorded maritime history. Tanker traffic had plummeted by an estimated 60 percent in forty-eight hours, according to shipping analytics firm Vortexa, as the world’s most consequential chokepoint absorbed the shockwaves of the most intensive Israel-Iran missile exchange since hostilities sharply escalated in February 2026. The human and economic costs are mounting with alarming symmetry: Iran’s Civil Defense Authority confirmed approximately 201 fatalities across Khuzestan and Bushehr provinces, while Israeli emergency services reported nine to ten civilian and military deaths in strikes on Haifa and the Negev. Three United States service members stationed in the region were also killed in rocket fire attributed to Iranian-backed proxies. The world is watching a regional war threaten to become a genuinely global energy crisis.
The Chokepoint Crisis: Why the Hormuz Strait Matters
To understand the severity of the current disruption, one must first appreciate the almost absurd concentration of risk that geography has bequeathed to the global oil trade. The Strait of Hormuz, nestled between Iran to the north and Oman to the south, carries roughly 20 million barrels of crude oil and petroleum products every single day—approximately one-fifth of total global supply, and fully 30 percent of seaborne oil trade, according to the U.S. Energy Information Administration. Critically, Al Jazeera‘s analysis of Hormuz shipping data confirms that Asia absorbs approximately 84 percent of all oil flowing through the strait—meaning that the economies of China, India, Japan, and South Korea are disproportionately exposed to any disruption of the corridor.
For the past 72 hours, that corridor has been, in practical terms, a war zone. Shell, TotalEnergies, BP, and Trafigura have all suspended new tanker transits, according to Reuters, mirroring the flight responses of shipping insurers who have invoked war-risk clauses and suspended coverage for Hormuz passages. The Lloyd’s of London Market Association placed the strait in its “Listed Areas” classification—a designation that effectively doubles or triples insurance premiums—within hours of the first confirmed missile strike on a vessel in Iranian territorial waters on 1 March.
“This is not a price spike. This is a structural rupture. The question is no longer whether markets will be disrupted, but for how long the world can absorb the shock before second-order crises begin cascading through Asian manufacturing chains.”
— Senior Energy Economist, HSBC Global Research, March 2026
Oil Flow Disruptions: A Country-by-Country Breakdown
| Country / Region | Pre-Crisis Daily Flow | Estimated Disrupted | % Exports via Hormuz | Alternate Route Available? |
|---|---|---|---|---|
| Saudi Arabia | 6.2 million bpd | ~4.8 million bpd | 77% | East-West Pipeline (max 2.0M bpd) |
| Iran | 1.8 million bpd | ~1.8 million bpd | 100% | None |
| UAE | 3.1 million bpd | ~2.1 million bpd | 68% | Habshan-Fujairah (1.5M bpd) |
| Iraq | 3.5 million bpd | ~3.3 million bpd | 94% | Kirkuk-Ceyhan (limited, conflict-damaged) |
| Kuwait | 2.3 million bpd | ~2.3 million bpd | 100% | None |
| Qatar (LNG) | 1.8M bpd equiv. | ~1.8 million bpd | 100% | None |
| ⚠ TOTAL | ~20 million bpd | ~16–18 million bpd | — | Bypass capacity: max 3.5–4M bpd |
The mathematics are brutal. Even with full utilization of alternate pipeline infrastructure—Saudi Arabia’s East-West Pipeline, capable of carrying up to 2 million barrels daily, and the UAE’s Habshan-to-Fujairah link at 1.5 million barrels daily—the bypass capacity barely scratches the surface of what is at stake. CNN‘s oil flow tracking data, corroborated by independent monitors at Kpler, suggests that even best-case rerouting through these corridors replaces only 3.5 to 4 million of the roughly 20 million barrels in jeopardy, leaving the global market to absorb a net shortfall of 8 to 10 million barrels per day in any sustained closure scenario.
Markets in Freefall: The Price Mechanics of Catastrophe
Brent crude opened the March 2 session at $80.40 per barrel—a 9.8 percent surge from Friday’s close, its steepest single-day gain since the Russian invasion of Ukraine in 2022, per Reuters. WTI followed at $78.10. Gasoline futures on NYMEX spiked 12 percent. But those numbers, dramatic as they are, almost certainly understate the trajectory if hostilities persist.
Rystad Energy’s crisis modeling, circulated to clients on the morning of 2 March, outlines three scenarios:
| Scenario | Duration | Brent Target | Probability |
|---|---|---|---|
| Base Case | 3–7 days, diplomatic resolution | ~$90 | ~60% |
| Adverse | 2–4 week strait closure | $100+ | ~25% |
| Severe | 1+ month military blockade | $115–$130 | ~15% |
⚡ Key Economic Pressure Points — March 2026
- UBS estimates a $10 rise in oil sustained for 12 months adds approximately 0.4–0.6 percentage points to global headline inflation.
- Goldman Sachs flags Asian central banks—already at the limits of rate flexibility—as most exposed to renewed imported inflation.
- Japan imports 87% of its crude via Hormuz; South Korea, 76%; India, approximately 60%—creating an acute shared vulnerability.
- OPEC’s 3.5 million bpd spare capacity, concentrated in Saudi Arabia and UAE, is itself partially bottlenecked by the Hormuz transit constraints.
- Global strategic petroleum reserves (SPR) total roughly 1.4 billion barrels—enough to cover approximately 40 days of the disrupted volume.
- LNG spot prices for Asian delivery jumped 18% in 48 hours, according to S&P Global Commodity Insights.
The Human Arithmetic of War: Casualties and Communities Under Fire
Behind every barrel figure lies a far more urgent accounting. In Iran’s southwestern Khuzestan province—home to the country’s most productive oil fields and a population of roughly 4.7 million—the strikes of 1 March left at least 143 confirmed dead, with dozens more missing beneath the rubble of residential blocks in Ahvaz and industrial facilities near Abadan, according to Iranian state media and corroborating reports from The Guardian. A further 58 fatalities were reported across Bushehr, where the presence of Iran’s nuclear power plant added an acute layer of geopolitical anxiety to the grief. The International Committee of the Red Cross issued an emergency statement calling for immediate humanitarian corridors.
In Israel, the strikes on Haifa’s industrial port district killed seven civilians and wounded thirty-four, while two Israeli Defense Forces soldiers died in a ballistic missile impact near Dimona in the Negev Desert, per Israeli emergency services and confirmed by The New York Times. Three U.S. service members—assigned to a joint logistics facility in northern Saudi Arabia—were killed in a drone strike attributed by Washington to Iranian-linked militia group Kataib Hezbollah. The Pentagon’s statement was carefully worded, stopping short of direct attribution to Tehran, but the White House’s subsequent communication to Iranian back-channels, reported by the Washington Post, left little ambiguity about American red lines.
The humanitarian dimensions of this conflict resist reduction to strategic calculation. In the port city of Bandar Abbas—Iran’s principal gateway to the Hormuz Strait—fishing families who have lived by the sea for generations are now sheltering in schools, their boats moored and their livelihoods suspended alongside the supertankers. The texture of suffering in a war like this is never captured by death tolls alone.
Geopolitical Architecture: How We Arrived at the Brink
The immediate trigger for the current escalation was a series of Israeli precision strikes on what Jerusalem characterized as advanced missile production facilities in Parchin and a Revolutionary Guard naval base near Bandar Abbas—strikes that Iran’s Supreme National Security Council described as “acts of open war” requiring a proportionate and “asymmetric” response. That response came in the form of a salvo of over 200 ballistic missiles and drones launched between the evening of 28 February and the early hours of 1 March, the largest such exchange since the October 2023 escalation cycle.
The United States, which has maintained an elevated naval presence in the Gulf through Carrier Strike Group 11, shot down an estimated 60 percent of the incoming Iranian projectiles in coordination with Israeli air defenses. But the political and symbolic damage of the exchange transcended its military outcomes: for the first time, Iran explicitly threatened to “exercise sovereign rights” over Hormuz transit—language that international maritime lawyers and energy strategists immediately recognized as the rhetorical prelude to a potential strait blockade.
Expert Analysis: Forecasts from Rystad, EIA, HSBC, and UBS
The analytical community is operating in rare unanimity about the severity of the situation, if not its precise trajectory. Arne Lohmann Rasmussen, Chief Analyst at Global Risk Management, described the crisis as “the most consequential threat to Hormuz transit since the Tanker War of 1984–88.” The EIA, in an emergency market note issued late on 1 March, revised its Q2 2026 Brent price band upward by $18 to a range of $88–$105, citing the compounding effect of already-tightened OPEC+ production schedules and limited SPR drawdown capacity.
HSBC’s Global Energy Research team flagged an underappreciated second-order risk: the impact on petrochemical feedstocks. “Asia’s refining complex is not configured to pivot rapidly to alternative crude slates,” the note read. “An eight-to-ten-million-barrel daily shortfall, even for two weeks, creates bottlenecks that resonate through plastics, fertilizers, and pharmaceutical precursors—sectors that global supply chains have never stress-tested against a Hormuz closure of this magnitude.” UBS, meanwhile, estimated that a six-week disruption would reduce Asian GDP growth by 0.8–1.2 percentage points in 2026, with India absorbing the deepest structural hit.
“OPEC’s spare capacity is not a magic lever. Most of it sits behind the same geographic bottleneck it is supposed to compensate for. The world has built a system where the cure and the disease share the same address.”
— Energy Policy Analyst, Oxford Institute for Energy Studies, 2 March 2026
The Bypass Illusion: Saudi and UAE Alternate Routes
Policymakers and market participants have repeatedly invoked alternate pipeline infrastructure as a potential pressure valve. The reality is considerably more constrained:
| Pipeline | Owner | Max Capacity | Current Est. Throughput | Terminus |
|---|---|---|---|---|
| East-West Pipeline | Saudi Aramco | 5.0M bpd | ~2.0M bpd | Yanbu, Red Sea |
| Habshan-Fujairah | ADNOC | 1.5M bpd | ~1.3M bpd | Fujairah, Gulf of Oman |
| Kirkuk-Ceyhan | Iraq/Turkey | 1.6M bpd | ~0.4M bpd (conflict-damaged) | Ceyhan, Mediterranean |
| Combined Realistic Bypass | — | — | ~3.5–4.0M bpd | — |
These corridors can divert at most 3.5 to 4 million barrels of the 20 million at risk—a bypass ratio that The Guardian‘s shipping correspondent characterized as “the equivalent of detouring a superhighway through a country lane.”
Asian Vulnerabilities: The 84 Percent Problem
For Asian economies, the Hormuz crisis is existential in a way it simply is not for Europe or North America:
| Economy | Hormuz Crude Dependency | Strategic Reserve Coverage | Emergency Response |
|---|---|---|---|
| Japan | ~87% | ~180 days | IEA coordinated release activated |
| South Korea | ~76% | ~130 days | Emergency cabinet convened 2 March |
| India | ~60% | ~90 days | Diplomatic missions to Riyadh, Moscow, Washington |
| China | ~55% | ~95–100 days (est.) | Aggressive spot buying, West Africa & Americas |
The asymmetry of exposure between East and West is not merely an economic footnote—it is a geopolitical faultline. If the crisis deepens, the divergent energy security interests of Asian importers and Western allies could complicate the construction of any unified diplomatic response, providing Iran with precisely the leverage its strategic doctrine has long sought to exploit.
Forward Implications: Scenarios, Diplomacy, and the Long Game
The most credible near-term diplomatic pathway runs through Oman, which has historically served as the back-channel of choice for U.S.-Iran communications. Omani Foreign Minister Badr Albusaidi was reportedly in contact with Iranian and American counterparts as of 1 March, but sources familiar with the talks described the atmosphere as “deeply unpromising.” A ceasefire framework, if it emerges, will almost certainly require verifiable Israeli pauses in airstrikes and reciprocal Iranian commitments on strait transit guarantees—conditions that current domestic political pressures in both Jerusalem and Tehran make extraordinarily difficult to operationalize.
In the medium term, the crisis will accelerate three structural trends already underway:
- Supply chain diversification — Asian oil importers pivoting toward the Americas and West Africa to reduce Hormuz dependency.
- LNG infrastructure acceleration — Qatar, Australia, and the United States will see renewed urgency in building strait-independent gas supply capacity.
- Energy transition momentum — The fragility of fossil fuel logistics chains, now viscerally apparent to policymakers from Tokyo to New Delhi to Berlin, strengthens the political economy of renewables investment.
The irony is almost Shakespearean—a war fought partly over the tools of the old energy order may ultimately hasten its unraveling.
But those are medium-term consolations. In the immediate term, the world must contend with the fact that twenty million barrels of daily supply—the lifeblood of the modern industrial economy—flows through a channel that is, right now, a battlefield. The Strait of Hormuz has always been humanity’s most consequential geographic gamble. That gamble, this week, is being called.
📬 Stay ahead of the crisis with real-time Energy & Geopolitics briefings—trusted by analysts at Goldman Sachs, Rystad Energy, and the IEA. Subscribe to the Global Energy Desk.
Related Analysis from the Global Energy Desk
- The Tanker War Playbook: How Iran Has Weaponized the Strait Before—and What It Cost the World · Energy & Geopolitics · February 2026
- Asia’s Hormuz Dependency: Why China, India, and Japan Have No Good Options If the Strait Closes · Energy Security · January 2026
- OPEC’s Spare Capacity Mirage: Why the World’s Emergency Oil Buffer Is Less Reassuring Than It Looks · Markets & Commodities · December 2025
- Beyond Brent: How an Israel-Iran War Would Cascade Into Fertilizers, Plastics, and Food Prices · Global Economy · November 2025
- The $100 Threshold: What History Tells Us About Oil Price Shocks and Recessionary Risk · Economic Modeling · October 2025
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025