
Analysis
Pakistan Poised to Ace IMF Targets: A Closer Look at the February 2026 Review

ISLAMAMABAD/KARACHI – As an International Monetary Fund (IMF) mission gears up for its arrival in the last week of February 2026, Islamabad finds itself in an unusually comfortable position. For the third review of the $7 billion Extended Fund Facility (EFF) and the second review of the Resilience and Sustainability Facility (RSF), Pakistan is likely to meet nearly all of its seven Quantitative Performance Criteria (QPCs) . This marks a significant departure from the history of last-minute scrambles and waiver requests that have often characterized the country’s long and troubled relationship with the global lender.
According to data compiled by Topline Securities and validated by recent state bank figures, the Pakistan IMF review 2026 is shaping up to be a technical success, even as underlying structural vulnerabilities continue to whisper warnings about the durability of this hard-won stability . The assessment, covering performance targets for September and December 2025, arrives on the back of macroeconomic indicators that, just two years ago, seemed like a distant mirage.
The Scorecard: A Fiscal Straight-A Student?
The upcoming review will assess Pakistan’s performance against the seven core QPCs—the non-negotiable red lines of the program that typically require a board-level waiver if breached. Based on available data for February 2026, the government has not only met but, in some cases, spectacularly exceeded these targets.
Net International Reserves (NIR) are projected to remain comfortably above the benchmark floors of negative $7 billion for September 2025 and negative $6.5 billion for December 2025 . This improvement is backed by real-world figures: gross foreign exchange reserves have swelled to $14.5 billion, a formidable jump from $9.4 billion at the start of the program, providing a crucial buffer against external shocks.
The fiscal story is even more impressive. Pakistan fiscal stability IMF metrics show the primary surplus hitting a projected Rs 3.5 trillion for September and Rs 4.1 trillion for December—massively outpacing the IMF’s targets of Rs 460 billion and Rs 3.2 trillion, respectively . This aligns with the full-year FY25 data, which recorded a primary surplus of 1.3% of GDP, a feat achieved through stringent expenditure control and a sharp compression of development spending.
On the monetary front, the Net Domestic Assets (NDA) of the State Bank of Pakistan are estimated in the range of Rs 12.5-13.5 trillion, well under the ceiling targets of Rs 14.9-15.1 trillion, indicating a tight lid on monetary expansion . Government guarantees and the push for new tax filers are also on track.
The Rs 1 Billion Blip and the FBR Conundrum
However, the report card is not entirely without a red mark. One indicator—the floor on targeted cash transfers under the Benazir Income Support Programme (BISP)—was technically missed in the prior review by a razor-thin margin of just Rs 1 billion . While final data for the December quarter is pending, this near-miss highlights a persistent tension: the human cost of austerity. As the government tightens its belt to satisfy IMF QPCs Pakistan performance, social safety nets are often the first to feel the strain, a point critics argue could undermine long-term social stability even as fiscal metrics improve.
A more significant shadow looms over the Federal Board of Revenue (FBR). Despite the fanfare around fiscal surpluses, Pakistan economy IMF targets face a substantial hurdle on the revenue side. The FBR has missed its tax collection target by a sizable Rs 336 billion . Officials are pinning hopes on recovering a portion of this shortfall through pending verdicts related to the Super Tax on high-income earners. Yet, even with this one-off fix, the tax-to-GDP ratio—stuck at around 10.3% —remains anemic compared to regional peers.
This paradox defines the current phase of the program: Pakistan is passing the IMF’s liquidity tests through administrative controls and expenditure cuts, but it is failing the solvency test of expanding its revenue base. As one analyst noted, the government is essentially surviving on a diet of fiscal discipline while the wound of tax evasion remains unhealed.
Beyond the QPCs: The Quiet RSF Revolution
While the headlines focus on the fiscal numbers, the February visit will also conduct the second review of the Resilience and Sustainability Facility (RSF). This often-overlooked component of the program is where Pakistan’s future economic viability is being quietly negotiated.
The EFF RSF Pakistan updates indicate a growing focus on climate resilience—a matter of existential importance for a country still scarred by the 2022 floods that caused over $30 billion in damages . The RSF aims to move beyond disaster response to proactive adaptation. Reform measures being scrutinized include improving public investment in water resource management and introducing climate risk disclosures for banks and corporations .
Here, the narrative shifts from spreadsheets to stories. The resilience of Pakistani communities against climate-induced displacement is now a variable in the economic equation. A failure to meet RSF benchmarks on water governance or disaster financing coordination between provinces wouldn’t just be an environmental setback; it would be a direct threat to the balance of payments stability the IMF is trying to protect. This interlinkage is something previous IMF programs ignored, but the 2026 review brings it to the forefront.
The Deep State of the Economy: Progress vs. Privilege
To understand the February 2026 review, one must look beyond the compliance checklist and into the political economy that shapes it. The IMF bailout Pakistan progress is undeniable on paper: inflation has cooled to a period average of 4.5% , the current account posted a surplus of 0.5% of GDP in FY25, and GDP growth is projected at a modest 3.2% in FY26 .
Yet, these aggregates mask the inertia of elite capture. A recent IMF governance diagnostic reportedly noted that corruption and privileged access to resources cost Pakistan as much as 6% of GDP annually—funds that could easily bridge the tax shortfall and fund development . The “steel” in the current program, as described by some observers, is designed to break these entrenched interests, demanding taxation of the agricultural and retail elites who have historically remained outside the net .
Key Data Snapshot: Pakistan’s IMF Program Performance (Feb 2026)
| Indicator | Target/Context | Actual/Projected |
|---|---|---|
| Gross Reserves | End-FY25 target | $14.5 billion (up from $9.4B) |
| Primary Surplus (FY25) | 1.0% of GDP (est.) | 1.3% of GDP |
| Inflation (Period Avg.) | FY26 Forecast: ~7% | 4.5% (Current) |
| FBR Tax Collection | Annual Target | Shortfall of Rs 336 billion |
| NIR (Dec 2025) | Floor: -$6.5 Billion | Comfortably Above Floor |
| Circular Debt | Pre-Program Level | Rs 2.4 trillion (Persistent Risk) |
This sets up a fascinating dynamic for the review. The government arrives in Washington and Islamabad (during the mission) with a strong hand—they have the numbers. But the IMF, backed by bilateral partners like the US, Saudi Arabia, and even the UAE, is likely to push back, arguing that the quality of the adjustment matters as much as the quantity . The real test isn’t whether Pakistan hit the December NIR target, but whether it can sustain the effort without resorting to the administrative “band-aids” of the past.
Navigating Choppy Waters: The Analogy of the Ship
Think of the Pakistani economy in early 2026 as a large ship that has finally managed to drop anchor in a storm. The Pakistan IMF review 2026 confirms the anchor is holding: the ship isn’t drifting toward default. The anchors are the $14.5 billion reserves and the primary surplus. However, the vessel remains battered. The engines (private investment) are sputtering—FDI has reportedly dropped—and the hull has leaks (circular debt in the energy sector has ballooned to Rs 2.4 trillion) .
The IMF mission’s role is akin to a meticulous insurance surveyor. They are checking if the temporary patches are holding. The government can proudly point to the engine room, showing that the flooding (inflation) has been pumped out. But the surveyors are peering into the dark corners, questioning why the pumps aren’t permanently fixed, and why the crew (the elite) refuses to row together.
Looking Ahead: The Exit or the Entrance?
As the February 2026 review concludes—likely with a successful disbursement—the focus will inevitably shift to the endgame. Can Pakistan exit this cycle of dependency, or is this merely another entrance into a new phase of stabilization without prosperity? The IMF has projected that sustained governance reforms could lift Pakistan’s growth to 5-6.5% over the next five years . Achieving this would require replicating the success of countries like Indonesia, which used IMF discipline as a launchpad rather than a life-support system.
For now, the government deserves credit for the optics. Meeting nearly all QPCs in a global environment of tight liquidity and geopolitical tension is no small feat. The primary surplus achievement, in particular, signals a newfound resolve in the finance ministry. But as the ship steadies, the real work begins. The February sun illuminates not just the calm waters ahead, but also the barnacles of inefficiency and privilege clinging to the hull. Scraping them off will determine whether this IMF program is remembered as Pakistan’s turning point or just another deferral of the inevitable reckoning.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
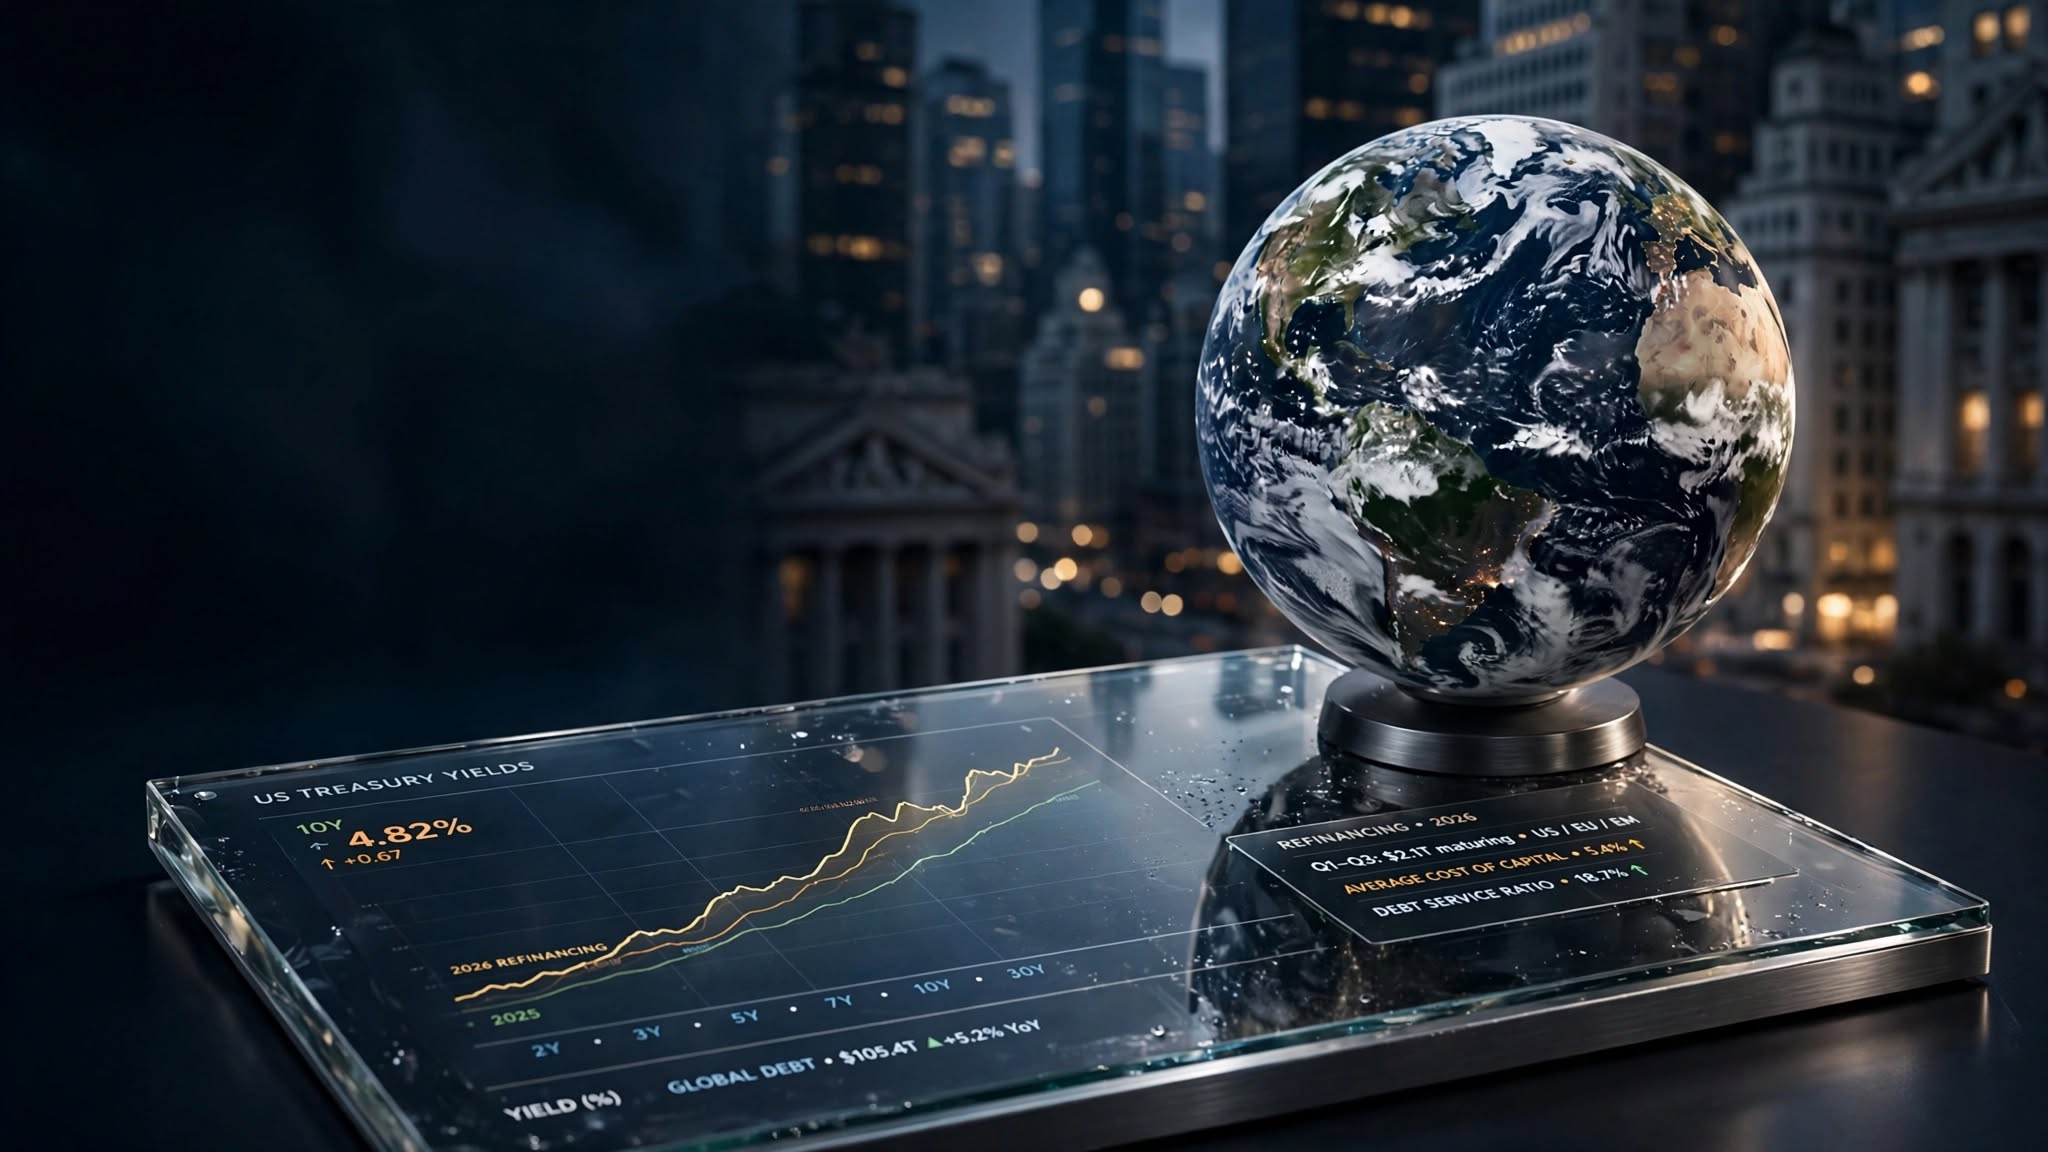
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
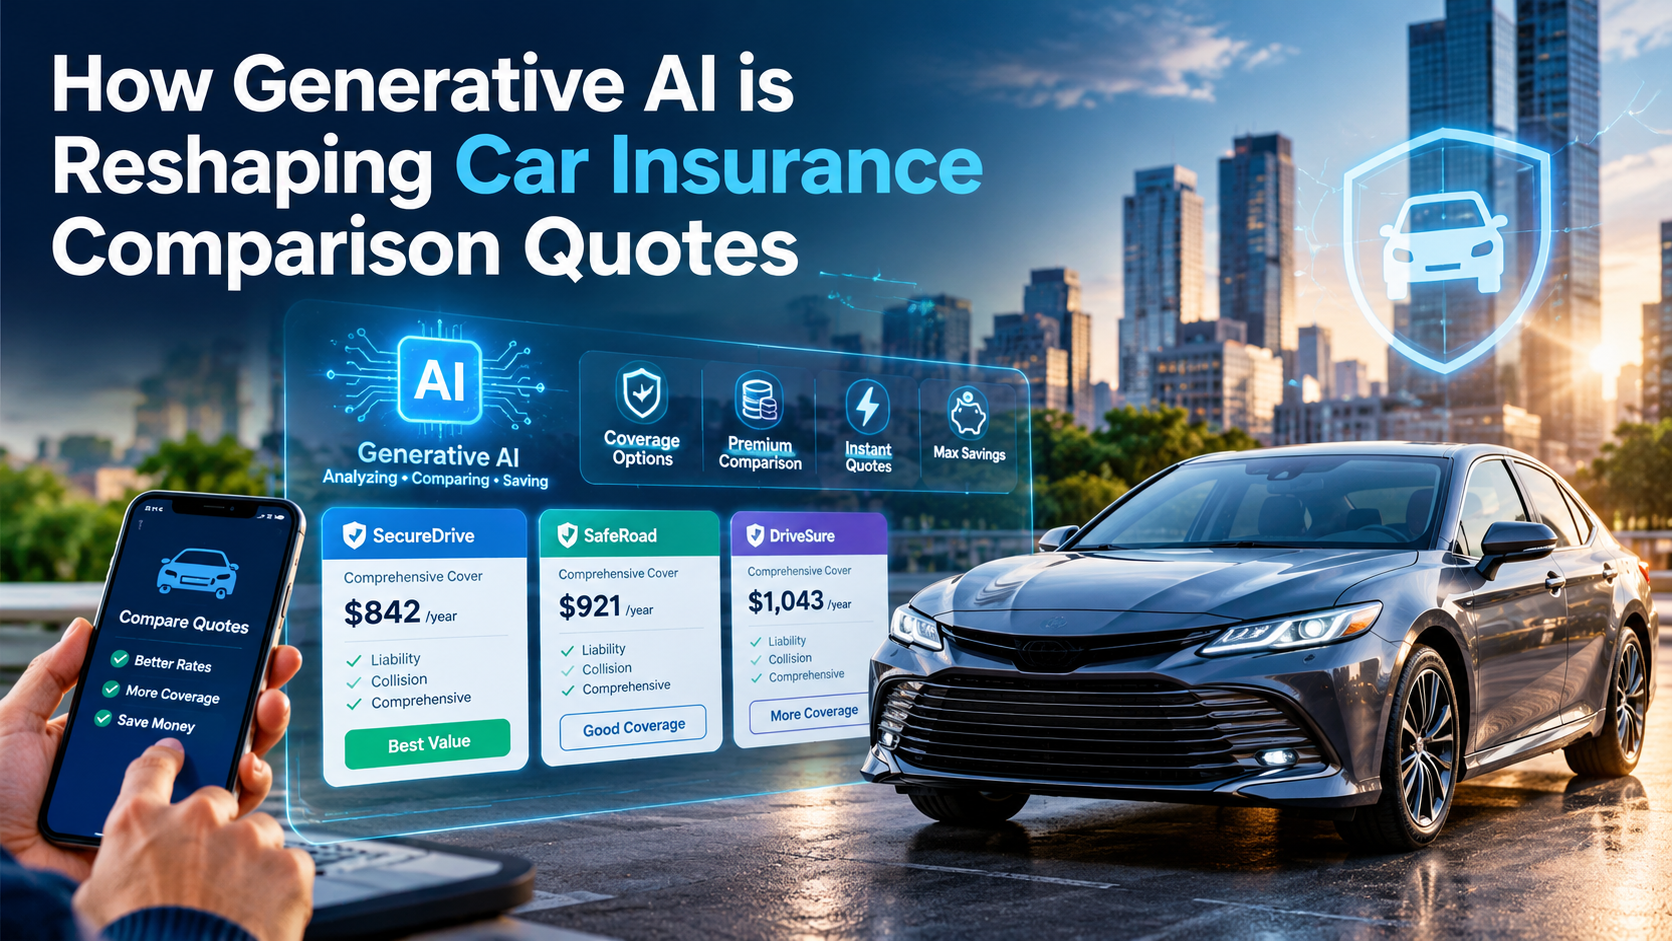
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025