
Analysis
Hong Kong Overtakes Switzerland as the World’s Top Offshore Wealth Hub

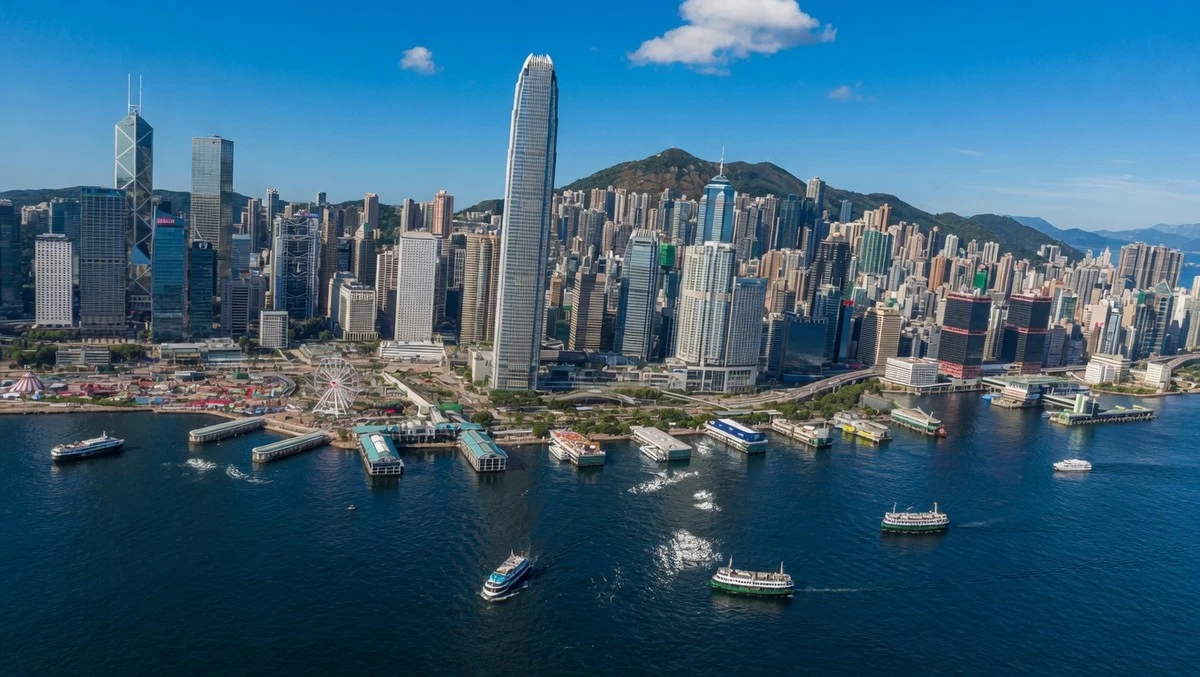
For the first time in more than two centuries, Switzerland is no longer the world’s largest destination for offshore private wealth. The crown has passed east — by a margin thin enough to be uncomfortable.
According to BCG’s 2026 Global Wealth Report, Hong Kong ended 2025 with $2.95 trillion in cross-border assets under management, edging past Switzerland’s $2.94 trillion. The gap — roughly $10 billion in a $15.7 trillion global market — is barely a rounding error. But in wealth management, symbolism travels. What once seemed a forecast too bold to believe has landed, quietly, as fact.
The proximate causes are well understood: mainland Chinese capital seeking offshore diversification, a revived IPO market that minted a new cohort of ultra-high-net-worth founders, and a deliberate policy campaign by Hong Kong’s government to court family offices with tax concessions and residency pathways. The structural causes run deeper, and they tell a story about where global wealth is being created and where its owners want it held.
The Numbers Behind Hong Kong’s Ascent as an Offshore Wealth Hub
BCG’s annual wealth survey found that cross-border wealth globally grew 8.4% last year, reaching $15.7 trillion. That growth was heavily concentrated. Inflows moved overwhelmingly toward the world’s top ten booking centres, amplifying an already pronounced concentration of private capital in a handful of cities. Hong Kong was the primary beneficiary in Asia.
The city’s rise from $2.1 trillion in 2020 to $2.95 trillion today represents a compound annual growth rate of roughly 7% — strong, but not spectacular by the standards of a city whose boosters long promised an 8.5% trajectory. What made the difference in 2025 wasn’t just volume; it was composition. The IPO cycle turned sharply upward. Hong Kong ranked as the world’s leading IPO venue in 2025, raising over HK$274 billion by mid-December alone. Each listing created a new cohort of liquid, newly wealthy founders — and each founder needed a private banker.
Alongside this, mainland Chinese insurance premiums purchased in Hong Kong hit HKD 62.8 billion in 2024, an eight-year high and a 6.5% year-on-year increase. Insurance-linked wealth structures are a significant entry point for Chinese nationals moving capital offshore — technically compliant, politically legible, and increasingly popular.
Then there are the family offices. By the end of 2025, Hong Kong hosted 3,384 single-family offices, a 25% increase in just two years, according to a Deloitte survey commissioned by the Hong Kong government. Of those, 1,095 managed assets of $100 million or more. That’s not a startup ecosystem; it’s an institutional wealth infrastructure.
The government of Chief Executive John Lee, who first set a target of 200 new family offices in his 2022 Policy Address, has since watched that figure be exceeded by an order of magnitude. The New Capital Investment Entrant Scheme, launched in March 2024, offers residency to investors allocating HKD 27 million to qualifying assets — a number calibrated precisely to attract the mainland’s upper-middle-wealthy rather than only the ultra-rich.
Why Hong Kong Overtook Switzerland — and Why It Matters for Global Wealth Flows
The straightforward answer: China. The more accurate answer: China’s property crisis, China’s capital controls, and China’s growing class of entrepreneurs who cannot conveniently keep their wealth in renminbi.
“Hong Kong is cementing its role as China’s gateway to global markets,” BCG wrote in its 2026 report, “though that same concentration ties its trajectory tightly to economic and regulatory developments on the mainland.” It’s a candid acknowledgement of a structural dependency that rivals would call a vulnerability and Hong Kong’s bankers would call an enduring competitive moat.
Why did Hong Kong overtake Switzerland as the world’s top cross-border wealth hub? Hong Kong’s rise is driven primarily by capital from mainland China seeking offshore diversification, a 2025 IPO boom that created a wave of new high-net-worth clients, and an aggressive government push to attract family offices through tax concessions and residency incentives — all against a backdrop of 9% projected annual growth through 2030.
That growth forecast matters. BCG projects both Hong Kong and Singapore will expand their cross-border wealth bases at roughly 9% annually through 2030. Switzerland is expected to grow at 6%. Over a decade, compounding turns a marginal lead into a structural dominance.
Yet the more consequential observation from the BCG data is what it implies about the architecture of global wealth management. Michael Kahlich, who co-authored the BCG report, put it plainly: “What ultimately matters is client proximity.” Two distinct regional poles are forming — Singapore and Hong Kong for Asia, Switzerland alongside the UK and the US for the Western world. The era of a single, neutral global safe haven, anchored in Alpine discretion, is giving way to a multipolar geography of private capital.
Switzerland spent two centuries accumulating that position. Its displacement — even partial, even narrow — represents a genuine inflection point. Jason Fong, a 27-year banking veteran tasked by the Hong Kong government with attracting family offices, was blunter about it in 2024: “They are crumbling and we are in a very advantageous situation.”
What the Shift Means for Banks, Markets, and the Architecture of Private Capital
The implications extend well beyond the wealth management industry itself.
For banks, the geography of client assets is the geography of revenue. HSBC, which contributed 54% of its group wealth and personal banking international revenue from Hong Kong in the first half of 2024, stands to gain disproportionately from the city’s continued rise. Standard Chartered, DBS, and Bank of China (Hong Kong) are positioned similarly. By contrast, UBS — which absorbed Credit Suisse and simultaneously retreated from parts of its Asian business — may find that its Switzerland-anchored model is progressively less suited to the clientele driving growth. That $10 billion gap between Hong Kong and Switzerland today could be $100 billion by 2028.
For policymakers, the shift raises questions that wealth managers prefer not to discuss in client-facing materials. Bloomberg Intelligence’s Hong Kong Wealth Management 2026 Outlook projects that China’s household assets will grow at 9.3% annually, with overseas investment rising from 8% to 11% of investable assets by 2030. That capital is predominantly routing through Hong Kong. It’s a dynamic that suits Beijing — the city provides offshore diversification for Chinese nationals while remaining within a jurisdiction that the mainland government controls at the constitutional level. For international policymakers worried about capital flight from China, or about financial stability in Hong Kong, the numbers represent both a success story and a risk concentration.
For businesses deciding where to book their treasury or establish their family office, the practical calculus has shifted. Hong Kong’s territorial tax system — no capital gains tax, no inheritance tax, no offshore income tax — remains structurally competitive. The Cross-Boundary Wealth Management Connect scheme, which now counts more than 160,000 investors, has created a bidirectional capital channel between Hong Kong and the Greater Bay Area that no other jurisdiction can replicate.
Still, the composition of Hong Kong’s inflows carries a concentration risk that Switzerland’s book does not. Switzerland’s appeal is precisely its diversification across source jurisdictions — Middle Eastern royalty, Latin American industrialists, European entrepreneurs, all in one account ledger. Hong Kong’s growth engine is, at its core, one large economy’s wealthy class seeking one particular form of offshore access. That’s a formidable engine. It’s also a single point of failure.
The Case for Switzerland — and the Limits of the Hong Kong Thesis
Credit where it is due: Switzerland is not losing clients. It’s gaining them, just more slowly.
“Geopolitical uncertainty reaffirms Switzerland’s role as a core global booking centre,” BCG noted in the same report that documented Hong Kong’s overtaking of it, “attracting flight-to-safety flows from more volatile regions such as the Middle East.” Wealthy individuals from the Gulf states, rattled by regional conflict and wary of the political exposure that comes with Gulf residency, have been moving assets to Switzerland with renewed urgency. That inflow is real, even if it’s smaller than what Hong Kong is absorbing from China.
There’s also the rule-of-law argument, and it’s not trivial. Hong Kong’s 2020 National Security Law fundamentally altered the city’s legal landscape. For wealth held across generations, the durability of legal protections matters as much as the tax rate. The Swiss legal system’s neutrality, its centuries of consistent enforcement, and its structural independence from any major geopolitical bloc represent attributes that cannot be replicated in Hong Kong under its current constitutional arrangement with Beijing.
The Swiss Bankers Association has identified compliance with international sanctions regimes as the leading geopolitical risk facing Swiss wealth managers — a concern prompted largely by Western sanctions on Russia. But the inverse concern applies to Hong Kong: wealth held there is subject to the risk that US or EU sanctions could eventually target mainland-linked entities operating through Hong Kong, given the territory’s eroding autonomy. That risk has not materialised in a way that disrupted the 2025 data. But sophisticated wealth owners holding multi-decade horizons are watching it.
Singapore offers a third path. Positioned between Hong Kong’s China-proximity and Switzerland’s Western neutrality, the city-state continues to grow at 9% annually — roughly matching Hong Kong’s trajectory but with a more diversified client base and a governance track record that generates less geopolitical anxiety. It’s the quiet competitor that neither Zurich nor Hong Kong fully accounts for.
A New Axis of Private Wealth
The $10 billion difference between Hong Kong’s $2.95 trillion and Switzerland’s $2.94 trillion is, in isolation, nearly meaningless. What it marks is a direction of travel that has been underway for years and is now officially confirmed.
Global wealth is growing fastest in Asia — and that wealth wants to be managed close to where it was created, by institutions that understand the tax codes, the family structures, and the political sensitivities of Chinese entrepreneurs. Hong Kong, for all its complications, remains the only city on earth that offers simultaneous access to mainland China’s capital markets and the infrastructure of an international financial centre. That combination is not easily replicated.
Switzerland retains what no Asian city yet possesses: centuries of demonstrated political neutrality, the institutional credibility of a jurisdiction that has outlasted empires, and a client base diversified enough to weather any single country’s economic cycle. The Swiss franc’s role as a safe-haven currency is a structural asset that the Hong Kong dollar — pegged to the US dollar and ultimately backstopped by Beijing — cannot claim.
The picture is more complicated than any single ranking conveys. What BCG’s 2026 data has confirmed is that the world’s private wealth now answers to two distinct centres of gravity. The question of which will be larger in a decade is less interesting than the question of what it means that the answer is no longer obvious.
Two centuries of Swiss dominance ended, quietly, sometime in 2025 — with barely $10 billion separating a former colony from the Alps.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025