
Opinion
Scott Bessent’s Fed Overhaul: How the Bank of England Blueprint Is Reshaping U.S. Central Bank Independence Under Trump

There is something deliciously ironic about the man who helped break the Bank of England now contemplating whether its institutional model could fix the Federal Reserve. Scott Bessent—U.S. Treasury Secretary, former Chief Investment Officer at Soros Fund Management, and a key architect of the 1992 “Black Wednesday” trade that forced sterling out of Europe’s Exchange Rate Mechanism—sat down in early March 2026 in the ornate Cash Room of the Treasury Building with interviewer Wilfred Frost of Sky News’ The Master Investor Podcast. The resulting conversation was interrupted, dramatically, by a White House aide informing the secretary that President Trump wanted him “right away” in the Situation Room. Iran. Oil at $120. The straits closing. Bessent departed and returned an hour later—and then calmly resumed discussing the structural architecture of American monetary institutions.
That juxtaposition—geopolitical fire on one side, institutional plumbing debates on the other—captures the peculiar moment the U.S. central banking system inhabits in 2026. Donald Trump has waged the most sustained assault on Federal Reserve independence since the Nixon era. Jerome Powell’s term as chair expires in May. Kevin Warsh has been nominated as successor. A Justice Department probe of the Fed’s building renovation costs has been widely interpreted as a political pretext to bend the institution’s will on interest rates. And through it all, Bessent has positioned himself as the most consequential—and arguably most complex—voice in the debate: a self-described guardian of market integrity who has simultaneously pushed, probed, and occasionally defended the Fed’s structural independence.
His measured comparison of the Federal Reserve and the Bank of England, delivered to Frost in that mid-March session, may prove to be among the most consequential policy signals of 2026. Understated in delivery, it was nonetheless rich with implication.
A Tale of Two Central Banks: What Bessent Actually Said
When Frost asked Bessent—a long-time Anglophile who spent formative professional years in London—whether he preferred the Bank of England’s operating model to that of the Federal Reserve, the Treasury Secretary was characteristically precise in his evasion-that-isn’t-quite-evasion.
“The Federal Reserve and the Bank of England are very different institutions,” Bessent said. “The Federal Reserve is a larger, more decentralized organization with multiple regional Federal Reserve Banks and Board of Governors members, but only a subset of these members have voting rights.”
He did not declare a preference. But the framing was deliberate. In Washington, what a senior official chooses to compare is often as revealing as what he endorses outright. Bessent’s willingness to surface the BoE model—its unified structure, its clearer Treasury-Bank coordination on financial stability, its post-1997 inflation-targeting mandate—as a reference point signals an intellectual appetite for institutional reform that goes beyond the usual rhetoric about “resetting” financial regulation.
The broader interview, which spanned Bessent’s macro investing philosophy, the economics of the Iran conflict, and his decision to decline the Fed chairmanship himself, painted a portrait of a Treasury Secretary who thinks about monetary architecture in frameworks shaped by three decades of global macro experience. He described his role as “guardian of the bond market”—a phrase that, when read against the BoE comparison, suggests he sees Treasury and the central bank as co-managers of a shared sovereign credit enterprise, rather than entirely separate sovereigns.
The Bank of England Framework: What It Would Mean in Practice
The Bank of England was granted operational independence in May 1997, when Chancellor Gordon Brown—in a move that stunned markets—transferred day-to-day monetary policy decisions to the Bank’s new Monetary Policy Committee. But the architecture that emerged was not independence in the American mode. It was coordinated independence: the Bank sets interest rates, but the inflation target itself is set by HM Treasury. The Chancellor writes the Bank Governor an annual letter specifying the target. Financial stability responsibilities are shared through the Financial Policy Committee, in which the Treasury is formally represented.
This is precisely the kind of structure that market analysts have begun examining in the context of the Bessent-Warsh era at the Treasury and Fed respectively. A Bloomberg Economics newsletter in February 2026, authored by senior economics editor Chris Anstey, explicitly explored whether Warsh at the Fed and Bessent at Treasury might “remodel” the central bank’s role along lines closer to the Treasury-Bank of England relationship. The BoE model offers three features that are increasingly discussed in Washington circles:
- A government-set inflation target with central bank operational freedom to meet it. Under such an arrangement, the Fed would retain rate-setting autonomy but the 2% inflation target—currently self-imposed—would be formally codified in legislation or established by Treasury directive, making the mandate more politically accountable.
- Integrated financial stability governance. The BoE’s Financial Policy Committee includes both Bank and Treasury officials in a formal coordination structure. Bessent, who has repeatedly argued that Treasury should “drive financial regulatory policy” and criticized what he calls “regulation by reflex” at the Fed, has already moved in this direction through his aggressive engagement with the Fed’s capital reform agenda and his remarks at the Federal Reserve Capital Conference.
- A more unified, less federalist structure. The BoE has no equivalent of the U.S. system’s twelve semi-autonomous regional reserve banks, each with its own president and policy voice. Bessent’s proposal for residency requirements for regional Fed presidents—suggesting that local bank heads should actually represent their regions—represents an oblique challenge to the national talent-search model that has produced a technically homogeneous but geographically detached leadership class at the regional banks.
The Historical Irony: The Man Who Broke the BoE
Any honest account of Bessent’s BoE affinity requires acknowledgment of the extraordinary biographical irony at its core. As detailed in Sebastian Mallaby’s authoritative history of hedge fund investing, More Money Than God, Bessent was a young portfolio manager at Soros’s Quantum Fund in September 1992 when the firm launched its legendary assault on the British pound. His research into the vulnerability of Britain’s variable-rate mortgage market to interest rate increases helped convince Stanley Druckenmiller—Soros’s chief strategist—to put on what became a billion-dollar short position against sterling. On the day of the climax, it was Bessent calling for the position to be pressed harder.
The pound crashed out of the Exchange Rate Mechanism. The Bank of England burned through billions in reserves trying to defend an untenable peg. It was a defining moment for the institution’s post-independence reform—and, indirectly, for the credibility argument that central banks should not be subordinated to politically-imposed exchange rate commitments. In a sense, Bessent helped create the conditions for the BoE’s 1997 reform by exposing the limits of the old model.
Three decades later, that same intellectual arc—skepticism of rigid institutional commitments, respect for market reality, appreciation for the need of clear mandates over ambiguous ones—appears to inform his thinking about the Fed. “Unlike most of my predecessors,” he told the Financial Times in October 2025, “I maintain a healthy skepticism toward elite institutions and elite viewpoints… But I have a healthy reverence for the market.” The Black Wednesday trade was, at its core, an argument that reality will eventually overwhelm institutional pride. Bessent appears to believe the same logic applies to the Fed’s current structural ambiguities.
Trump’s Escalating Assault: Where Bessent Fits
To understand what makes Bessent’s BoE musings consequential rather than merely academic, one must understand the full texture of the pressure the Trump administration has applied to the Federal Reserve since 2025.
The assault has been multi-frontal and escalating. Trump publicly demanded the Fed cut its benchmark rate to as low as 1 percent in July 2025. He visited the Fed’s headquarters in Washington in an unusual personal inspection of cost overruns in its building renovation—a move widely read as an attempt to manufacture grounds for removing Powell. Governor Lisa Cook was subjected to an attempted dismissal, ultimately challenged in court. Stephen Miran, Trump’s own Council of Economic Advisers chair, was installed as a Fed governor while remaining affiliated with the administration—a conflict of interest that drew sharp criticism from economists. And in January 2026, the Justice Department threatened the Fed itself with criminal proceedings over Powell’s congressional testimony about the renovation project. Powell responded with unusual sharpness: he called the probe a “pretext” to undermine monetary independence, and vowed to continue doing “the job the Senate confirmed me to do.”
Republican cracks followed almost immediately. Senator Thom Tillis of North Carolina, a Banking Committee member, declared that “if there were any remaining doubt whether advisers within the Trump Administration are actively pushing to end the independence of the Federal Reserve, there should now be none.” Representative French Hill, chairman of the House Financial Services Committee, called the investigation an “unnecessary distraction.”
Into this maelstrom, Bessent has navigated with the precision of a macro trader managing risk on multiple books simultaneously. He challenged Trump’s “revenge probe” of Powell, reportedly opposing the DOJ move on both legal and economic grounds. He has previously described Fed independence as a “jewel box that has got to be preserved.” Yet he has also consistently pushed for structural reforms that would—incrementally and deniably—tilt the balance of influence toward Treasury. The residency requirement proposal for regional bank presidents. The push for a “fundamental reset” of financial regulation. The meeting with Bank of England Governor Andrew Bailey in April 2025, after which the Treasury noted Bessent was “pleased to discuss his remarks from earlier in the week”—a formulation that deliberately linked the bilateral meeting to a broader policy signal.
Whether this constitutes a sincere reform agenda, a sophisticated diplomatic shield between Trump and full institutional destruction, or some combination of both is a question that defines Bessent’s peculiar role in one of the most consequential institutional debates of the decade.
Kevin Warsh and the Architecture of Change
The nomination of Kevin Warsh as Powell’s successor adds another layer of complexity to the BoE comparison. Warsh, a former Fed governor and veteran of the 2008 crisis response, has long argued that the Fed has accumulated too many responsibilities and that its balance sheet policy has strayed from its core monetary mandate. He has advocated for a narrower, more accountable central bank—a vision that has clear family resemblances to the post-1997 BoE model.
If Warsh and Bessent share an intellectual framework—operational independence for rate-setting, greater Treasury-Fed coordination on financial stability and macro-prudential regulation, clearer mandate accountability—the result could be a genuine institutional reorganization that achieves many of the BoE’s structural features without requiring congressional legislation. Much of the architecture could be achieved through changes to Treasury-Fed coordination agreements, adjustments to the Fed’s self-imposed communication frameworks, and the gradual reshaping of the FOMC’s composition through appointments.
Markets appear to have absorbed this possibility with relative equanimity. Upon Warsh’s nomination announcement, financial markets were steady—a signal, analysts noted, that investors viewed him as credible even if they anticipated a more accommodating rate posture. Mohamed El-Erian of Queens’ College Cambridge observed in a January 2026 Project Syndicate essay that the Trump-Powell feud had “raised fears of a grim future of unanchored inflation expectations, macroeconomic instability, and heightened financial volatility”—but concluded that internal and external checks were likely “sufficiently robust to prevent a major accident.”
The Risks: Why the BoE Model Is Not a Simple Blueprint
It would be intellectually dishonest to present the Bank of England framework as an uncomplicated upgrade for the United States. Several structural differences make a direct transplant enormously complex—and potentially dangerous.
Scale and complexity. The Fed is not simply a larger version of the BoE. It manages monetary policy for the world’s reserve currency, oversees a banking system of incomparably greater global systemic importance, and functions as the global lender of last resort in crises. The BoE operates within the European regulatory ecosystem (notwithstanding Brexit) and manages a much smaller sovereign debt market. Coordinating Treasury-Fed relations at the scale of the U.S. dollar system involves risks of fiscal dominance—the historical tendency, as seen in pre-1951 America and in multiple emerging market economies, for treasury departments to subordinate monetary policy to their own financing needs.
The 1951 Accord’s shadow. The Treasury-Federal Reserve Accord of 1951, which ended Treasury’s wartime control over Fed interest rates, is the foundational document of modern Fed independence. Any formal Treasury-Fed coordination mechanism risks, at the margin, reversing the logic of that accord. The Council on Foreign Relations has explicitly noted that “the Fed did not secure true operational independence from the federal government until the 1951 Accord, which allowed it to set monetary policy without concern for the long-term borrowing costs of the U.S. government.” Bessent, as a student of economic history, understands this tension acutely.
Dollar dominance and credibility externalities. The dollar’s reserve currency status depends, in part, on global confidence in the Fed’s independence from political pressure. Even perceived coordination between Treasury and the Fed on rate-setting—let alone formal institutional mechanisms—could trigger a reassessment by sovereign wealth funds, central bank reserve managers, and international investors of U.S. Treasury paper as the ultimate safe asset. Bessent himself has described this moment as “extraordinary for U.S. dollar dominance”—a framing that suggests he understands the fragility of that dominance and the asymmetric risks of appearing to compromise it.
The inflation target question. If the inflation target were to be formally transferred to Treasury—as in the BoE model—a future administration hostile to price stability could, in theory, simply adjust the target upward. The self-imposed 2% target at the Fed, whatever its ambiguities, cannot be changed unilaterally by the executive branch. A legislated or Treasury-directed target could be.
Forward Scenarios: Three Possible Outcomes
As Powell’s May exit approaches and Warsh prepares for what could be a contentious confirmation, three broad institutional trajectories present themselves.
Scenario 1: Managed Convergence. Warsh and Bessent establish informal Treasury-Fed coordination mechanisms that functionally resemble BoE-style fiscal-monetary alignment without formal institutional change. The Fed retains its legal independence, but Bessent’s Treasury plays a more active role in financial regulatory policy, the inflation target becomes more explicitly codified, and the FOMC communication framework is simplified. Markets adjust incrementally. Dollar credibility is maintained. This is the outcome Bessent appears to be engineering.
Scenario 2: Institutional Erosion. Trump’s political pressure intensifies after Warsh’s arrival, driving a majority of the FOMC—reshaped through strategic appointments—toward persistent accommodation of fiscal policy. Long-term Treasury yields rise as investors reprice U.S. sovereign credit risk. The dollar weakens. Global central banks accelerate reserve diversification. El-Erian’s “grim future” scenario is not averted, merely delayed.
Scenario 3: Reform and Renewal. A genuine legislative overhaul—modeled explicitly on the 1997 BoE settlement, but adapted for U.S. scale—establishes clearer mandate accountability, a reformed financial stability committee structure, and a streamlined FOMC. Controversial but coherent, this outcome is the most intellectually defensible but politically the least probable in the current polarized environment.
The Bond Market as the Final Arbiter
Bessent told Wilfred Frost that his defining framework—the one that has guided both his investing career and his tenure at Treasury—is that “the crowd is right 85% or 90% of the time. It’s really when things turn, or when you could imagine a different outcome than the consensus, that’s when you can really make a lot of money.” In 1992, he imagined a different state of the world for the pound. The bond market confirmed the trade.
The bond market is now running its own analysis on the Fed-Treasury question. Daily Treasury trading volumes of approximately $1 trillion—a figure Bessent himself cited at the November 2025 Treasury Market Conference—mean that any credible signal of fiscal dominance would be priced swiftly and punishingly. Bessent knows this better than perhaps any Treasury Secretary in history. He made his fortune understanding how institutional commitments collapse under market pressure. Now he is the institution.
That is, in the end, the deepest irony of the BoE comparison. The man who broke one central bank through superior market analysis is now trying to reform another through institutional architecture. The question for global investors, policymakers, and the international monetary system is whether those two skillsets—speculative precision and institutional design—can coexist in one Treasury Secretary navigating the most politically turbulent period for U.S. monetary institutions since the Second World War.
The bond market will have an opinion. It always does.
Expert Takeaways for International Investors and Policymakers
- Watch the Warsh confirmation hearings closely for signals on whether he endorses any formal Treasury-Fed coordination mechanisms. Language around “accountability,” “mandate clarity,” or “financial stability governance” will be more important than his positions on near-term rates.
- The BoE comparison is a signal, not a blueprint. Bessent is unlikely to push for a formal legislative restructuring. The more probable outcome is incremental administrative convergence—enough to reshape practice without triggering constitutional or market crises.
- Dollar-denominated assets carry a new institutional risk premium. The sustained assault on Fed independence—regardless of its ultimate outcome—has introduced a structural uncertainty into U.S. monetary credibility that sovereign investors will have to price for at least the remainder of Trump’s second term.
- The 1951 Accord is the key historical precedent. Any future Treasury-Fed coordination framework that echoes pre-Accord arrangements should be treated as a materially negative signal for long-duration U.S. Treasuries and the dollar’s reserve currency status.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


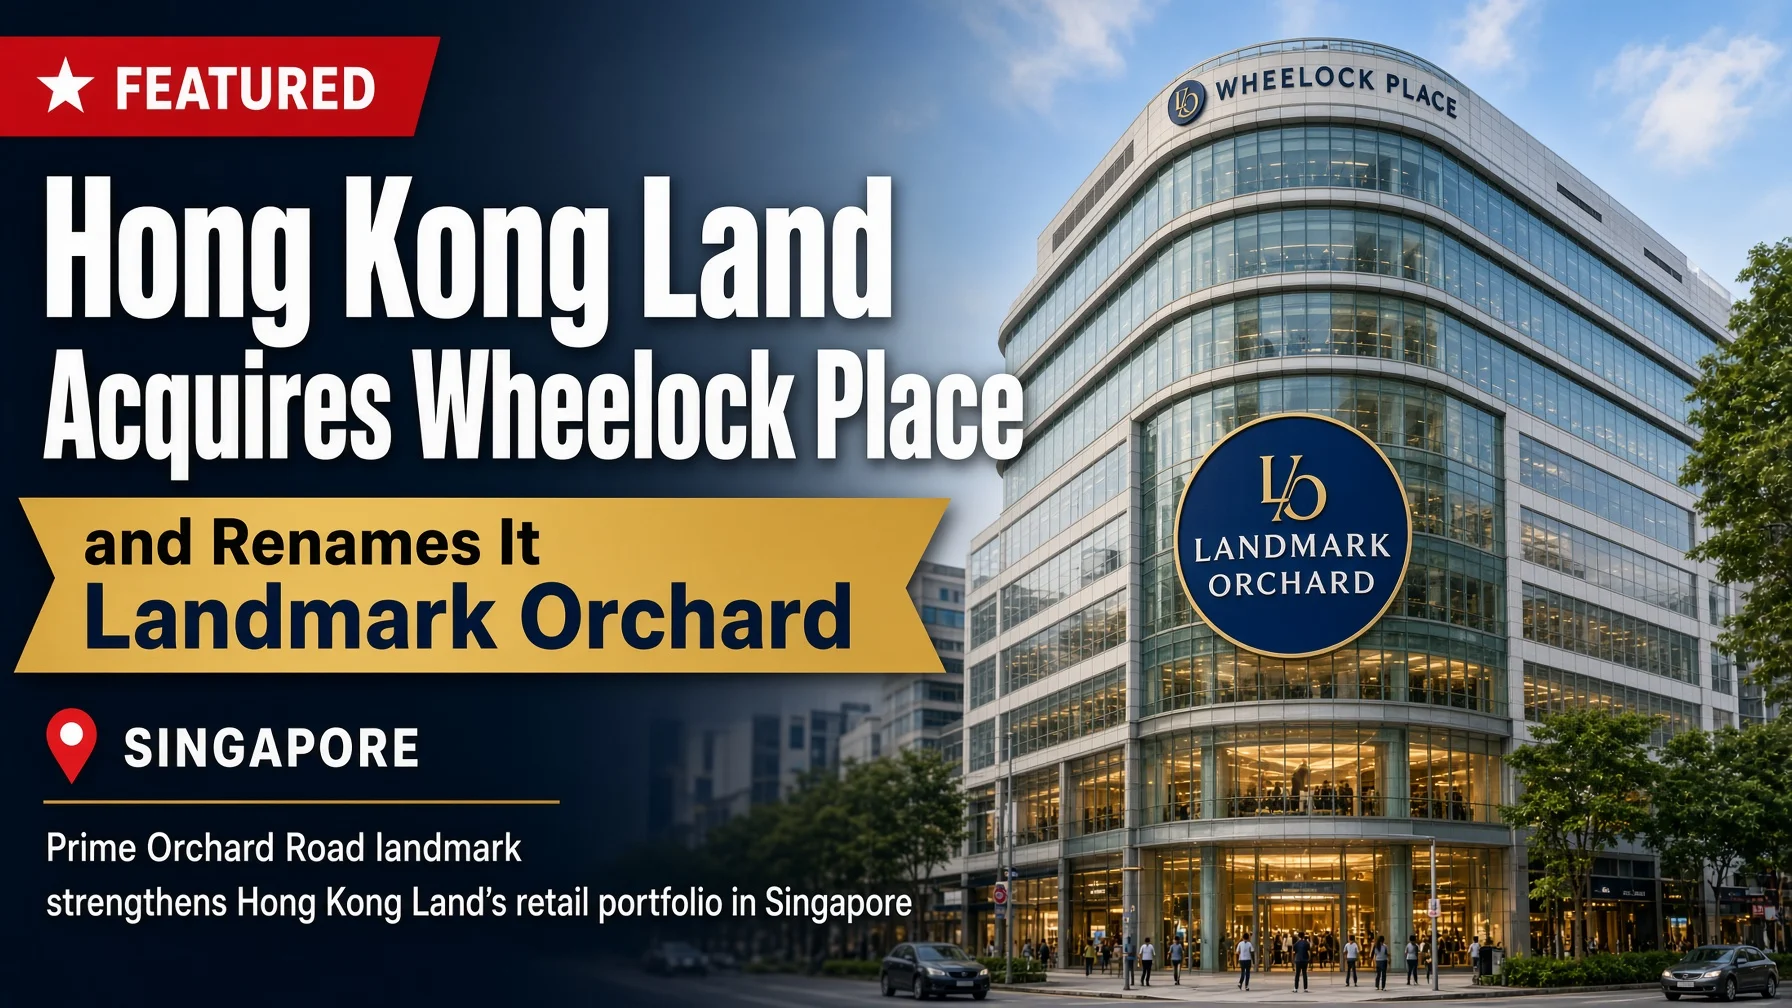
Hongkong Land’s Singapore Central Private Real Estate Fund completed the acquisition of Wheelock Place for approximately S$1.1 billion (roughly US$855–900 million) and, on 12 November 2026, renamed the prominent Orchard Road property Landmark Orchard. This is the first time the group has extended the Landmark brand beyond Hong Kong. The Straits Times
The 21-storey mixed-use building remains directly linked to Orchard MRT station and continues operating with existing office and retail tenants. The deal was the fund’s first acquisition since its February 2026 launch and advances Hongkong Land’s strategy of growing recurring income and its fund-management platform toward a target of roughly S$15 billion in assets under management. Channel NewsAsia
For Singapore’s commercial property market, the transaction confirms sustained institutional appetite for irreplaceable Orchard Road assets and signals long-term capital commitment to one of Asia’s premier retail and office corridors.
Table of Contents
- What Was the Acquisition Price and Deal Structure?
- Why Rename Wheelock Place to Landmark Orchard?
- What Are the Key Property Details and Location Advantages?
- How Does This Fit Hongkong Land’s Broader Strategy?
- What Does the Deal Mean for Orchard Road Tenants and the Precinct?
- What Enhancements and Capital Plans Are Expected?
- How Does the Transaction Compare with Recent Orchard Road Deals?
- Key Takeaways
- Frequently Asked Questions
What Was the Acquisition Price and Deal Structure?
The Singapore Central Private Real Estate Fund agreed in July 2026 to acquire Wheelock Place from an entity owned by Hong Kong-listed Wharf Real Estate Investment Company. The price of approximately S$1.1 billion aligned with an independent valuation. Completion took place around the end of August 2026, and the renaming became effective on 12 November 2026. The Straits Times
Allen & Gledhill advised the buyer, Lee & Lee represented the seller, and WongPartnership acted for the financing syndicate. The acquisition lifted the fund’s assets under management and was described as accretive to Hongkong Land’s underlying earnings. Hongkong Land maintains a majority equity stake in the fund and will earn additional management fees as the platform scales.
Why Rename Wheelock Place to Landmark Orchard?
Hongkong Land is deliberately exporting the Landmark identity that defines its flagship Central Hong Kong portfolio. Management stated that the name “Landmark Orchard” reflects a commitment to delivering a high-quality experience for tenants, visitors, and the surrounding community. The rebranding also creates regional brand consistency across the group’s premium commercial assets. Channel NewsAsia
Foo Pei Teng, Chief Executive of the fund, noted that this is the first use of the Landmark name outside Hong Kong and that the group intends to apply its long-term investment philosophy to the asset.
What Are the Key Property Details and Location Advantages?
Wheelock Place (now Landmark Orchard) comprises a 21-storey commercial tower and two basement levels with a total gross floor area of approximately 43,280 square metres. It offers office space, a retail podium, and car parking and enjoys direct underground connectivity to Orchard MRT station. The building sits at the strategic junction of Orchard Road, Scotts Road, and Paterson Road.
Originally opened in 1994 as Lane Crawford Place, it was later renamed Wheelock Place and has been a recognisable presence on Orchard Road for more than three decades. Its MRT linkage and central Orchard positioning provide strong footfall and accessibility advantages that institutional investors prize.
How Does This Fit Hongkong Land’s Broader Strategy?
The purchase advances two core objectives: expanding the third-party fund-management platform and increasing exposure to high-quality, recurring-income assets. The Singapore fund was established specifically to acquire rare institutional-grade properties. Completing a transaction of this scale within months of launch demonstrated both execution capability and limited-partner confidence. As assets under management move toward the S$15 billion target, Hongkong Land benefits from both co-investment returns and growing fee income.
The deal also extends the group’s Singapore footprint beyond the Marina Bay and CBD core into the Orchard Road belt, diversifying its local exposure.
What Does the Deal Mean for Orchard Road Tenants and the Precinct?
Existing office and retail tenants continue in occupation under the new name, so near-term operational disruption is minimal. Long-term institutional ownership by a well-capitalised player is generally viewed as positive for asset maintenance, tenant retention, and precinct quality. Over time, planned enhancements could improve the retail mix, common areas, and integration with the surrounding pedestrian and transit network, reinforcing Orchard Road’s competitiveness against other Asian shopping destinations.
What Enhancements and Capital Plans Are Expected?
Hongkong Land has not published a detailed capital-expenditure schedule. It has indicated that it will draw on extensive experience managing premium assets, including the ongoing multi-year transformation of its Hong Kong Landmark properties under the “Tomorrow’s CENTRAL” programme. Typical interventions for an asset of this type include selective retail reconfiguration, sustainability upgrades, improved vertical circulation, and stronger place-making around the MRT connection. Any major works are expected to be phased to limit tenant impact.
How Does the Transaction Compare with Recent Orchard Road Deals?
Prime Orchard Road assets trade infrequently. The S$1.1 billion price reflects both the property’s scale and its irreplaceable location. Comparable recent transactions in the precinct have also attracted long-term institutional capital, underscoring that global and regional investors continue to view Orchard Road as a core holding despite cyclical retail challenges. The Landmark rebranding adds a differentiating brand layer that few competing assets possess.
Transaction and Asset Snapshot
| Item | Detail |
|---|---|
| Purchase price | ≈ S$1.1 billion (US$855–900 million) |
| Buyer | Hongkong Land Singapore Central Private Real Estate Fund |
| Seller | Entity owned by Wharf Real Estate Investment Company |
| Completion | End-August 2026 |
| Renaming effective | 12 November 2026 |
| Gross floor area | ≈ 43,280 sq m |
| Key feature | Direct Orchard MRT connection |
| Fund AUM target | ≈ S$15 billion |
| Brand significance | First Landmark name use outside Hong Kong |
Key Takeaways
- Hongkong Land acquired Wheelock Place for approximately S$1.1 billion and renamed it Landmark Orchard.
- The transaction is the first acquisition of the Singapore Central Private Real Estate Fund.
- It marks the first extension of the Landmark brand beyond Hong Kong.
- Existing tenants remain in place; enhancements are planned over the medium term.
- The deal supports Hongkong Land’s dual goals of recurring-income growth and fund-management expansion.
- It reinforces institutional confidence in prime Orchard Road real estate.
Frequently Asked Questions
When did the name change take effect?
12 November 2026.
Do existing tenants have to move or renegotiate immediately?
No. Office and retail tenants continue operating under the new name.
Who sold the property?
An entity controlled by Wharf Real Estate Investment Company.
Is this Hongkong Land’s first Singapore asset?
No, but it is the fund’s first acquisition and the group’s first major Orchard Road holding under the new vehicle.
What is the fund’s assets-under-management target?
Approximately S$15 billion.
Will there be immediate large-scale renovations?
No detailed disruptive works have been announced; the emphasis is on continuity followed by phased enhancement.
How does the price compare with the independent valuation?
It was described as being in line with a recent independent valuation.
Conclusion
The conversion of Wheelock Place into Landmark Orchard is simultaneously a major real estate transaction and a strategic branding move for Hong Kong Land. For property, investment, and business audiences, the deal illustrates continued appetite for scarce Orchard Road assets and the expanding role of sponsored private funds in Singapore’s commercial market. Tenants and visitors should experience continuity in the near term, while the new ownership and landmark identity create a platform for gradual, quality-focused upgrades that can further strengthen one of the city’s most recognisable commercial addresses over the coming decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The UK government’s decision to exempt glass drinks containers supplied directly to pubs, restaurants, and other licensed venues from most Extended Producer Responsibility (EPR) fees from April 2027 directly addresses cost pressures on the hospitality sector. Official illustrations show potential savings of up to 6 pence per beer bottle and 10 pence per wine bottle, equating to as much as £870 a year for a typical pub. GOV.UK
Broader reforms will also modulate future fees so that easy-to-recycle materials such as glass and paper attract lower charges, while harder-to-recycle plastics face relatively higher costs. The changes respond to sustained industry and media pressure over double charging.
Table of Contents
- What EPR Changes Affect Hospitality?
- How Large Is the Financial Impact on Pubs?
- Why Was the Original EPR Scheme Problematic for Pubs?
- What Broader Fee Modulation Reforms Are Planned?
- How Have Industry Groups and Media Responded?
- When Will Pubs Actually See the Savings?
- Key Takeaways
- Frequently Asked Questions
What EPR Changes Affect Hospitality?
From April 2027, glass drinks containers supplied directly by producers to licensed hospitality venues (pubs, restaurants, and similar premises) will no longer be liable for the majority of Extended Producer Responsibility packaging fees. The exemption is intended to eliminate the situation in which businesses paid both commercial waste-collection charges and EPR fees on the same glass. GOV.UK
Environment Secretary Dame Angela Eagle stated that the government had listened to concerns from the hospitality sector and the British glass industry and was acting to reduce fees on the most recyclable packaging while tackling double charging.
How Large Is the Financial Impact on Pubs?
Government examples indicate savings of up to 6 pence per beer bottle and 10 pence per wine bottle. For a pub selling 10,000 beer bottles and 3,700 wine bottles annually, the combined relief could reach £870 per year. These figures are illustrative upper-end amounts; actual savings will depend on volumes and the degree to which producers and wholesalers pass the reduced fees through the supply chain. The Grocer
Defra has also indicated that wider modulation could reduce fees for the most recyclable packaging by up to 40 percent.
Why Was the Original EPR Scheme Problematic for Pubs?
Hospitality venues already contract and pay for the collection and recycling of their commercial glass waste. The introduction of EPR fees created a second charge on the same material without delivering an additional service to the venue. This double charging raised operating costs for pubs at a time when the sector was already managing elevated energy, wage, and supply costs, and it disadvantaged UK glass producers relative to some imported alternatives. The Times
What Broader Fee Modulation Reforms Are Planned?
Alongside the hospitality exemption, the government will consult on restructuring packaging fees so that easy-to-recycle materials (including most glass and paper) attract lower charges while hard-to-recycle formats, particularly certain plastics, face higher fees. Defra estimates this approach could lower fees for highly recyclable packaging by 30–40 percent. A separate call for evidence on reusable packaging systems is also planned for 2027. GOV.UK
How Have Industry Groups and Media Responded?
The British Beer and Pub Association welcomed the removal of double charging on glass. Glass-industry representatives similarly supported measures that reduce the cost burden on a highly recyclable domestic product. Campaigns by outlets including The Telegraph and The Mirror had highlighted the impact on pubs and glassmakers in the months preceding the announcement. Some publican groups have sought explicit confirmation that tenanted and leased pubs will benefit on the same terms as managed estates. The Mirror
When Will Pubs Actually See the Savings?
The exemption applies to EPR fees calculated from April 2027. Invoices and supply contracts in place before that date are unaffected. Any reduction in the price of bottled beer or wine at the bar will occur only if producers and distributors pass the lower fees downstream; the government announcement itself does not mandate retail price cuts.
Illustrative Annual Saving for a Typical Pub
| Product | Assumed Annual Volume | Maximum Unit Saving | Maximum Annual Saving |
|---|---|---|---|
| Beer bottles | 10,000 | 6 pence | £600 |
| Wine bottles | 3,700 | 10 pence | £370 |
| Combined | — | — | Up to £870 |
Key Takeaways
- Glass drinks containers supplied directly to licensed hospitality venues will be largely exempt from EPR fees from April 2027.
- Official examples show potential savings of up to £870 per year for a mid-volume pub.
- The change directly addresses the double-charging criticism that had been levelled at the original scheme.
- Wider fee modulation is expected to further favour glass and paper over many plastic formats.
- The measures support both the hospitality sector and UK glass manufacturers.
- Consumer price effects depend on how much the supply chain passes through costs.
Frequently Asked Questions
When does the hospitality glass exemption take effect?
April 2027.
Does the exemption cover every type of glass packaging?
It applies to glass drinks containers supplied directly by producers to licensed pubs, restaurants, and other hospitality venues.
Will the price of a pint or a bottle of wine fall immediately?
Not automatically. Any retail price reduction depends on whether suppliers pass the fee savings through.
Is this change linked to recent newspaper campaigns?
Yes. Both The Telegraph and The Mirror had run prominent coverage of the cost impact on pubs and the glass industry.
Will plastic packaging become more expensive under the wider reforms?
Fee modulation is designed to increase charges on harder-to-recycle materials relative to glass and paper.
Are tenanted and leased pubs included?
The announcement covers licensed hospitality venues; industry bodies are seeking clear confirmation that tenanted estates receive equivalent benefit.
Conclusion
The EPR adjustments announced in November 2026 constitute a targeted and practical correction for the UK hospitality sector. By removing most packaging fees on glass supplied directly to pubs and restaurants from April 2027, and signalling stronger future rewards for recyclability, the government has responded to a clearly identified cost pressure. For business, hospitality, and consumer audiences, the changes should deliver measurable relief to licensed venues while reinforcing the principle that packaging charges ought to reflect real-world recycling outcomes. The extent to which those savings reach the customer will be determined by commercial decisions further down the supply chain in 2027 and beyond.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The latest data from the U.S. Bureau of Economic Analysis show the American economy maintaining solid momentum into late 2026. Real GDP expanded at an annualised rate of 3.4 per cent in the third quarter, accelerating from 2.2 percent in the prior quarter, supported by gains in consumer spending and business investment (BEA advance estimate). This performance underscores the direct link between GDP and economic growth: the former quantifies the total value of goods and services produced, while the latter tracks how that value expands over time. For US business leaders, operations managers, and financial analysts, monitoring these signals is essential for capital allocation, hiring plans, and technology investments. Understanding the mechanics of GDP and economic growth helps enterprises anticipate demand shifts, manage cost pressures, and deploy resources—particularly AI tools—more effectively in a $30-trillion-plus economy.
What Is the Relationship Between GDP and Economic Growth?
Gross Domestic Product represents the market value of all final goods and services produced within the United States during a specific period. Economists express this through the expenditure approach:GDP=C+I+G+(X−M)
Here, C stands for personal consumption expenditures, I for private investment, G for government spending, X for exports, and M for imports. The formula aggregates spending by households, businesses, and the public sector while adjusting for trade. GDP and economic growth are closely related but distinct concepts. GDP is a stock measure of output at a point in time, whereas economic growth refers to the percentage change in real GDP over successive periods.
Year-over-year or quarter-over-quarter increases in real GDP, which strip out inflation, provide the clearest gauge of expansion in productive capacity. When real GDP rises, the economy is generating more goods and services after accounting for price changes. Sustained positive growth supports rising incomes, higher tax revenues, and expanded business opportunities. Conversely, negative growth signals contraction. The U.S. Department of Commerce notes that these federal economic indicators directly influence financial market expectations and corporate planning cycles.
Real vs. Nominal GDP: Why Inflation Adjustment Matters
Distinguishing between nominal and real measures is critical for accurate interpretation of GDP and economic growth. Nominal GDP values output at current prices, so it rises with both volume increases and inflation. Real GDP adjusts for price changes using a base year, isolating actual growth in quantity. GDP per capita further divides total output by population, revealing average living standards.
| Measure | Definition | Inflation Adjustment | Best Use Case |
|---|---|---|---|
| Nominal GDP | Total output valued at current market prices | No | Current-dollar size of the economy |
| Real GDP | Output adjusted to constant prices | Yes | Tracking true economic growth |
| GDP Per Capita | Total GDP divided by population | Optional (real preferred) | Comparing living standards across time or countries |
The World Bank Open Data places US GDP well above $30 trillion in recent years, with per-capita figures among the highest for large economies. Relying solely on nominal figures can overstate growth during inflationary periods. Businesses therefore prioritise real series when forecasting demand or evaluating investment returns.
Key Drivers of US GDP and Economic Growth in 2026
Four primary components shape US GDP and economic growth. Recent BEA data and market research highlight their relative contributions and evolving dynamics.
- Personal Consumption Expenditures: Accounting for roughly 68 percent of GDP, household spending remains the dominant driver. Resilient outlays on services and goods have underpinned recent expansions, supported by employment levels and wealth effects from equity markets.
- Private Domestic Investment, Including AI-Related Capex: Business fixed investment has accelerated, particularly in equipment and intellectual property tied to artificial intelligence. J.P. Morgan Economic Research observes that enterprise AI capital expenditure, alongside solid consumer spending, continues to propel modern US growth despite offsetting effects from higher imports of technology hardware (J.P. Morgan trends).
- Government Spending: Federal and state outlays contribute through defense, infrastructure, and transfer programs. Shifts in nondefense spending and inventory adjustments at federal agencies have influenced quarterly results.
- Net Exports: The trade balance typically subtracts from growth. Rising imports of capital goods, especially information-processing equipment, have tempered the net contribution of investment in recent quarters.
Together, these pillars produced the 3.4 percent advance-estimate gain in Q3 2026. Monitoring shifts among them allows enterprises to align supply chains, pricing strategies, and capacity plans with prevailing demand.
How Macroeconomic Growth Impacts US Enterprises and AI Adoption
Periods of solid GDP and economic growth create both opportunities and pressures for US companies. Expanding consumer spending lifts top-line revenue, while elevated business investment signals confidence in future demand. At the same time, tighter labour markets or residual inflation can raise operating costs. In such environments, organisations increasingly turn to automation and AI-powered knowledge platforms to expand output without proportional increases in headcount or overhead.
Platforms such as EEsel.ai enable operations teams to centralise institutional knowledge, automate routine customer and internal queries, and free specialists for higher-value work. When macroeconomic conditions support investment, firms that deploy these tools can capture productivity gains that compound over multiple expansion cycles. Conversely, during slower growth phases, the same capabilities help protect margins by reducing service costs and improving response consistency. Federal Reserve policy, which balances employment and price stability, further influences the cost of capital available for such technology deployments. Companies that integrate macroeconomic signals into their capital-planning processes are better positioned to time AI adoption for maximum return.
Limitations of GDP as a Measure of Economic Health
Despite its utility, GDP has well-recognized shortcomings as a comprehensive welfare metric. It excludes non-market activity such as unpaid household production and volunteer work. It also does not capture the distribution of income; aggregate growth can coincide with rising inequality. Intangible digital value—open-source software, data networks, and many platform effects—is only partially reflected in measured output. Environmental externalities and leisure time likewise fall outside the boundary of the accounts. These limitations do not diminish the value of GDP for tracking cyclical momentum, but they remind decision-makers to supplement it with complementary indicators such as employment, median wages, and productivity statistics.
Frequently Asked Questions (FAQ)
What is a healthy GDP growth rate for the US?
Most economists consider real GDP growth of roughly 2 to 2.5 percent sustainable over the long term for the United States, consistent with labour-force and productivity trends. Rates above 3 percent, as seen in the Q3 2026 advance estimate, are strong but typically temporary.
How often is US GDP reported?
The Bureau of Economic Analysis releases GDP estimates quarterly. An advance estimate appears about one month after the quarter ends, followed by a second estimate and a third estimate incorporating more complete data.
What is the difference between real and nominal GDP growth?
Real GDP growth adjusts for inflation and therefore measures changes in the volume of output. Nominal growth includes both volume and price changes and can appear higher during inflationary periods.
Why does business investment, especially in AI, matter for GDP?
Private investment directly adds to GDP and raises future productive capacity. AI-related capital expenditure has been a notable contributor to recent US growth, even after accounting for associated imports.
In summary, GDP and economic growth remain foundational signals for understanding the US economy’s trajectory. The 3.4 percent real expansion recorded for the third quarter of 2026, driven by consumer spending and business investment, illustrates both the resilience of private demand and the rising role of technology capital formation. Enterprises that track these indicators closely can better calibrate hiring, pricing, and technology strategies. Tools that improve operational productivity—such as EEsel.ai’s AI knowledge-management capabilities—offer a practical means of converting macroeconomic momentum into sustained competitive advantage without simply scaling headcount.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Democrats Won Congress. Can They Fix the U.S. Economy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025