
Opinion
Scott Bessent’s Fed Overhaul: How the Bank of England Blueprint Is Reshaping U.S. Central Bank Independence Under Trump

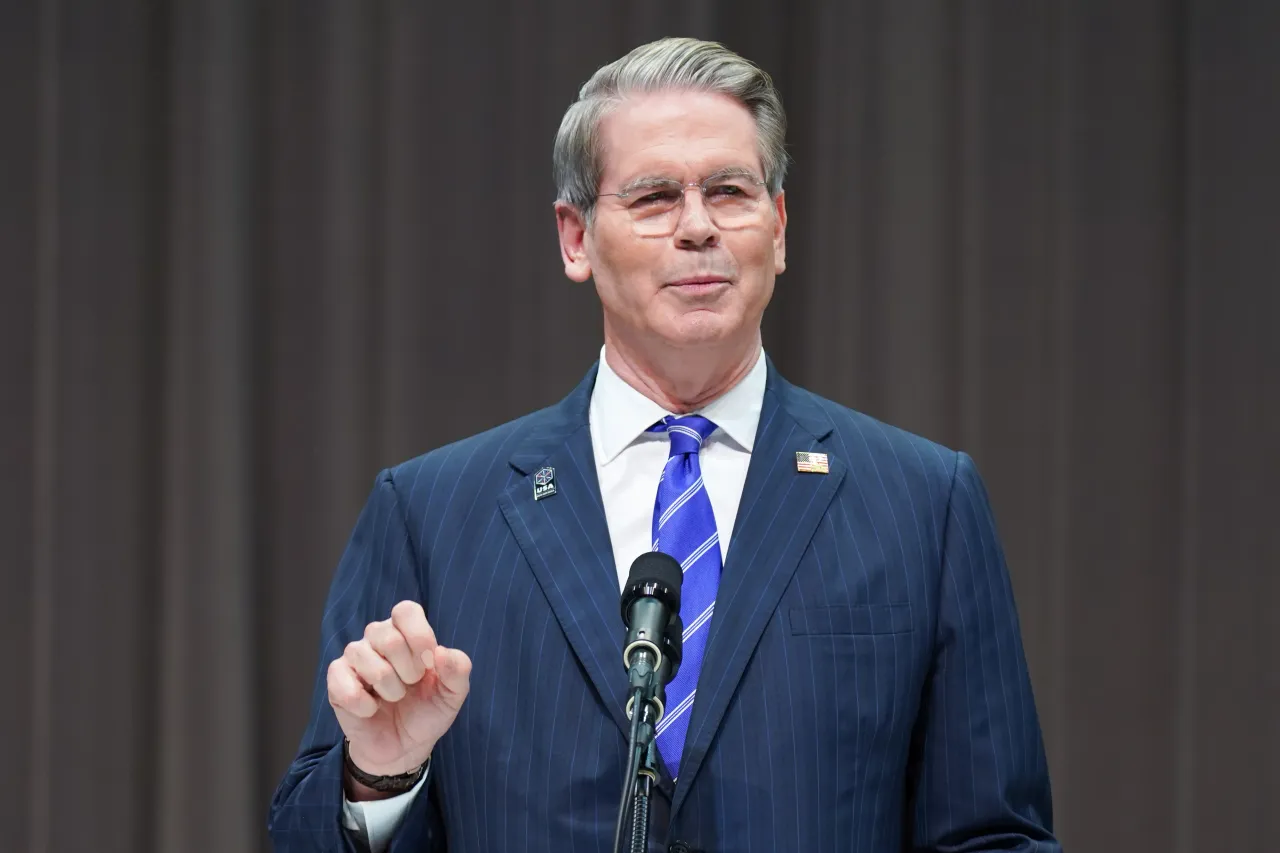
There is something deliciously ironic about the man who helped break the Bank of England now contemplating whether its institutional model could fix the Federal Reserve. Scott Bessent—U.S. Treasury Secretary, former Chief Investment Officer at Soros Fund Management, and a key architect of the 1992 “Black Wednesday” trade that forced sterling out of Europe’s Exchange Rate Mechanism—sat down in early March 2026 in the ornate Cash Room of the Treasury Building with interviewer Wilfred Frost of Sky News’ The Master Investor Podcast. The resulting conversation was interrupted, dramatically, by a White House aide informing the secretary that President Trump wanted him “right away” in the Situation Room. Iran. Oil at $120. The straits closing. Bessent departed and returned an hour later—and then calmly resumed discussing the structural architecture of American monetary institutions.
That juxtaposition—geopolitical fire on one side, institutional plumbing debates on the other—captures the peculiar moment the U.S. central banking system inhabits in 2026. Donald Trump has waged the most sustained assault on Federal Reserve independence since the Nixon era. Jerome Powell’s term as chair expires in May. Kevin Warsh has been nominated as successor. A Justice Department probe of the Fed’s building renovation costs has been widely interpreted as a political pretext to bend the institution’s will on interest rates. And through it all, Bessent has positioned himself as the most consequential—and arguably most complex—voice in the debate: a self-described guardian of market integrity who has simultaneously pushed, probed, and occasionally defended the Fed’s structural independence.
His measured comparison of the Federal Reserve and the Bank of England, delivered to Frost in that mid-March session, may prove to be among the most consequential policy signals of 2026. Understated in delivery, it was nonetheless rich with implication.
A Tale of Two Central Banks: What Bessent Actually Said
When Frost asked Bessent—a long-time Anglophile who spent formative professional years in London—whether he preferred the Bank of England’s operating model to that of the Federal Reserve, the Treasury Secretary was characteristically precise in his evasion-that-isn’t-quite-evasion.
“The Federal Reserve and the Bank of England are very different institutions,” Bessent said. “The Federal Reserve is a larger, more decentralized organization with multiple regional Federal Reserve Banks and Board of Governors members, but only a subset of these members have voting rights.”
He did not declare a preference. But the framing was deliberate. In Washington, what a senior official chooses to compare is often as revealing as what he endorses outright. Bessent’s willingness to surface the BoE model—its unified structure, its clearer Treasury-Bank coordination on financial stability, its post-1997 inflation-targeting mandate—as a reference point signals an intellectual appetite for institutional reform that goes beyond the usual rhetoric about “resetting” financial regulation.
The broader interview, which spanned Bessent’s macro investing philosophy, the economics of the Iran conflict, and his decision to decline the Fed chairmanship himself, painted a portrait of a Treasury Secretary who thinks about monetary architecture in frameworks shaped by three decades of global macro experience. He described his role as “guardian of the bond market”—a phrase that, when read against the BoE comparison, suggests he sees Treasury and the central bank as co-managers of a shared sovereign credit enterprise, rather than entirely separate sovereigns.
The Bank of England Framework: What It Would Mean in Practice
The Bank of England was granted operational independence in May 1997, when Chancellor Gordon Brown—in a move that stunned markets—transferred day-to-day monetary policy decisions to the Bank’s new Monetary Policy Committee. But the architecture that emerged was not independence in the American mode. It was coordinated independence: the Bank sets interest rates, but the inflation target itself is set by HM Treasury. The Chancellor writes the Bank Governor an annual letter specifying the target. Financial stability responsibilities are shared through the Financial Policy Committee, in which the Treasury is formally represented.
This is precisely the kind of structure that market analysts have begun examining in the context of the Bessent-Warsh era at the Treasury and Fed respectively. A Bloomberg Economics newsletter in February 2026, authored by senior economics editor Chris Anstey, explicitly explored whether Warsh at the Fed and Bessent at Treasury might “remodel” the central bank’s role along lines closer to the Treasury-Bank of England relationship. The BoE model offers three features that are increasingly discussed in Washington circles:
- A government-set inflation target with central bank operational freedom to meet it. Under such an arrangement, the Fed would retain rate-setting autonomy but the 2% inflation target—currently self-imposed—would be formally codified in legislation or established by Treasury directive, making the mandate more politically accountable.
- Integrated financial stability governance. The BoE’s Financial Policy Committee includes both Bank and Treasury officials in a formal coordination structure. Bessent, who has repeatedly argued that Treasury should “drive financial regulatory policy” and criticized what he calls “regulation by reflex” at the Fed, has already moved in this direction through his aggressive engagement with the Fed’s capital reform agenda and his remarks at the Federal Reserve Capital Conference.
- A more unified, less federalist structure. The BoE has no equivalent of the U.S. system’s twelve semi-autonomous regional reserve banks, each with its own president and policy voice. Bessent’s proposal for residency requirements for regional Fed presidents—suggesting that local bank heads should actually represent their regions—represents an oblique challenge to the national talent-search model that has produced a technically homogeneous but geographically detached leadership class at the regional banks.
The Historical Irony: The Man Who Broke the BoE
Any honest account of Bessent’s BoE affinity requires acknowledgment of the extraordinary biographical irony at its core. As detailed in Sebastian Mallaby’s authoritative history of hedge fund investing, More Money Than God, Bessent was a young portfolio manager at Soros’s Quantum Fund in September 1992 when the firm launched its legendary assault on the British pound. His research into the vulnerability of Britain’s variable-rate mortgage market to interest rate increases helped convince Stanley Druckenmiller—Soros’s chief strategist—to put on what became a billion-dollar short position against sterling. On the day of the climax, it was Bessent calling for the position to be pressed harder.
The pound crashed out of the Exchange Rate Mechanism. The Bank of England burned through billions in reserves trying to defend an untenable peg. It was a defining moment for the institution’s post-independence reform—and, indirectly, for the credibility argument that central banks should not be subordinated to politically-imposed exchange rate commitments. In a sense, Bessent helped create the conditions for the BoE’s 1997 reform by exposing the limits of the old model.
Three decades later, that same intellectual arc—skepticism of rigid institutional commitments, respect for market reality, appreciation for the need of clear mandates over ambiguous ones—appears to inform his thinking about the Fed. “Unlike most of my predecessors,” he told the Financial Times in October 2025, “I maintain a healthy skepticism toward elite institutions and elite viewpoints… But I have a healthy reverence for the market.” The Black Wednesday trade was, at its core, an argument that reality will eventually overwhelm institutional pride. Bessent appears to believe the same logic applies to the Fed’s current structural ambiguities.
Trump’s Escalating Assault: Where Bessent Fits
To understand what makes Bessent’s BoE musings consequential rather than merely academic, one must understand the full texture of the pressure the Trump administration has applied to the Federal Reserve since 2025.
The assault has been multi-frontal and escalating. Trump publicly demanded the Fed cut its benchmark rate to as low as 1 percent in July 2025. He visited the Fed’s headquarters in Washington in an unusual personal inspection of cost overruns in its building renovation—a move widely read as an attempt to manufacture grounds for removing Powell. Governor Lisa Cook was subjected to an attempted dismissal, ultimately challenged in court. Stephen Miran, Trump’s own Council of Economic Advisers chair, was installed as a Fed governor while remaining affiliated with the administration—a conflict of interest that drew sharp criticism from economists. And in January 2026, the Justice Department threatened the Fed itself with criminal proceedings over Powell’s congressional testimony about the renovation project. Powell responded with unusual sharpness: he called the probe a “pretext” to undermine monetary independence, and vowed to continue doing “the job the Senate confirmed me to do.”
Republican cracks followed almost immediately. Senator Thom Tillis of North Carolina, a Banking Committee member, declared that “if there were any remaining doubt whether advisers within the Trump Administration are actively pushing to end the independence of the Federal Reserve, there should now be none.” Representative French Hill, chairman of the House Financial Services Committee, called the investigation an “unnecessary distraction.”
Into this maelstrom, Bessent has navigated with the precision of a macro trader managing risk on multiple books simultaneously. He challenged Trump’s “revenge probe” of Powell, reportedly opposing the DOJ move on both legal and economic grounds. He has previously described Fed independence as a “jewel box that has got to be preserved.” Yet he has also consistently pushed for structural reforms that would—incrementally and deniably—tilt the balance of influence toward Treasury. The residency requirement proposal for regional bank presidents. The push for a “fundamental reset” of financial regulation. The meeting with Bank of England Governor Andrew Bailey in April 2025, after which the Treasury noted Bessent was “pleased to discuss his remarks from earlier in the week”—a formulation that deliberately linked the bilateral meeting to a broader policy signal.
Whether this constitutes a sincere reform agenda, a sophisticated diplomatic shield between Trump and full institutional destruction, or some combination of both is a question that defines Bessent’s peculiar role in one of the most consequential institutional debates of the decade.
Kevin Warsh and the Architecture of Change
The nomination of Kevin Warsh as Powell’s successor adds another layer of complexity to the BoE comparison. Warsh, a former Fed governor and veteran of the 2008 crisis response, has long argued that the Fed has accumulated too many responsibilities and that its balance sheet policy has strayed from its core monetary mandate. He has advocated for a narrower, more accountable central bank—a vision that has clear family resemblances to the post-1997 BoE model.
If Warsh and Bessent share an intellectual framework—operational independence for rate-setting, greater Treasury-Fed coordination on financial stability and macro-prudential regulation, clearer mandate accountability—the result could be a genuine institutional reorganization that achieves many of the BoE’s structural features without requiring congressional legislation. Much of the architecture could be achieved through changes to Treasury-Fed coordination agreements, adjustments to the Fed’s self-imposed communication frameworks, and the gradual reshaping of the FOMC’s composition through appointments.
Markets appear to have absorbed this possibility with relative equanimity. Upon Warsh’s nomination announcement, financial markets were steady—a signal, analysts noted, that investors viewed him as credible even if they anticipated a more accommodating rate posture. Mohamed El-Erian of Queens’ College Cambridge observed in a January 2026 Project Syndicate essay that the Trump-Powell feud had “raised fears of a grim future of unanchored inflation expectations, macroeconomic instability, and heightened financial volatility”—but concluded that internal and external checks were likely “sufficiently robust to prevent a major accident.”
The Risks: Why the BoE Model Is Not a Simple Blueprint
It would be intellectually dishonest to present the Bank of England framework as an uncomplicated upgrade for the United States. Several structural differences make a direct transplant enormously complex—and potentially dangerous.
Scale and complexity. The Fed is not simply a larger version of the BoE. It manages monetary policy for the world’s reserve currency, oversees a banking system of incomparably greater global systemic importance, and functions as the global lender of last resort in crises. The BoE operates within the European regulatory ecosystem (notwithstanding Brexit) and manages a much smaller sovereign debt market. Coordinating Treasury-Fed relations at the scale of the U.S. dollar system involves risks of fiscal dominance—the historical tendency, as seen in pre-1951 America and in multiple emerging market economies, for treasury departments to subordinate monetary policy to their own financing needs.
The 1951 Accord’s shadow. The Treasury-Federal Reserve Accord of 1951, which ended Treasury’s wartime control over Fed interest rates, is the foundational document of modern Fed independence. Any formal Treasury-Fed coordination mechanism risks, at the margin, reversing the logic of that accord. The Council on Foreign Relations has explicitly noted that “the Fed did not secure true operational independence from the federal government until the 1951 Accord, which allowed it to set monetary policy without concern for the long-term borrowing costs of the U.S. government.” Bessent, as a student of economic history, understands this tension acutely.
Dollar dominance and credibility externalities. The dollar’s reserve currency status depends, in part, on global confidence in the Fed’s independence from political pressure. Even perceived coordination between Treasury and the Fed on rate-setting—let alone formal institutional mechanisms—could trigger a reassessment by sovereign wealth funds, central bank reserve managers, and international investors of U.S. Treasury paper as the ultimate safe asset. Bessent himself has described this moment as “extraordinary for U.S. dollar dominance”—a framing that suggests he understands the fragility of that dominance and the asymmetric risks of appearing to compromise it.
The inflation target question. If the inflation target were to be formally transferred to Treasury—as in the BoE model—a future administration hostile to price stability could, in theory, simply adjust the target upward. The self-imposed 2% target at the Fed, whatever its ambiguities, cannot be changed unilaterally by the executive branch. A legislated or Treasury-directed target could be.
Forward Scenarios: Three Possible Outcomes
As Powell’s May exit approaches and Warsh prepares for what could be a contentious confirmation, three broad institutional trajectories present themselves.
Scenario 1: Managed Convergence. Warsh and Bessent establish informal Treasury-Fed coordination mechanisms that functionally resemble BoE-style fiscal-monetary alignment without formal institutional change. The Fed retains its legal independence, but Bessent’s Treasury plays a more active role in financial regulatory policy, the inflation target becomes more explicitly codified, and the FOMC communication framework is simplified. Markets adjust incrementally. Dollar credibility is maintained. This is the outcome Bessent appears to be engineering.
Scenario 2: Institutional Erosion. Trump’s political pressure intensifies after Warsh’s arrival, driving a majority of the FOMC—reshaped through strategic appointments—toward persistent accommodation of fiscal policy. Long-term Treasury yields rise as investors reprice U.S. sovereign credit risk. The dollar weakens. Global central banks accelerate reserve diversification. El-Erian’s “grim future” scenario is not averted, merely delayed.
Scenario 3: Reform and Renewal. A genuine legislative overhaul—modeled explicitly on the 1997 BoE settlement, but adapted for U.S. scale—establishes clearer mandate accountability, a reformed financial stability committee structure, and a streamlined FOMC. Controversial but coherent, this outcome is the most intellectually defensible but politically the least probable in the current polarized environment.
The Bond Market as the Final Arbiter
Bessent told Wilfred Frost that his defining framework—the one that has guided both his investing career and his tenure at Treasury—is that “the crowd is right 85% or 90% of the time. It’s really when things turn, or when you could imagine a different outcome than the consensus, that’s when you can really make a lot of money.” In 1992, he imagined a different state of the world for the pound. The bond market confirmed the trade.
The bond market is now running its own analysis on the Fed-Treasury question. Daily Treasury trading volumes of approximately $1 trillion—a figure Bessent himself cited at the November 2025 Treasury Market Conference—mean that any credible signal of fiscal dominance would be priced swiftly and punishingly. Bessent knows this better than perhaps any Treasury Secretary in history. He made his fortune understanding how institutional commitments collapse under market pressure. Now he is the institution.
That is, in the end, the deepest irony of the BoE comparison. The man who broke one central bank through superior market analysis is now trying to reform another through institutional architecture. The question for global investors, policymakers, and the international monetary system is whether those two skillsets—speculative precision and institutional design—can coexist in one Treasury Secretary navigating the most politically turbulent period for U.S. monetary institutions since the Second World War.
The bond market will have an opinion. It always does.
Expert Takeaways for International Investors and Policymakers
- Watch the Warsh confirmation hearings closely for signals on whether he endorses any formal Treasury-Fed coordination mechanisms. Language around “accountability,” “mandate clarity,” or “financial stability governance” will be more important than his positions on near-term rates.
- The BoE comparison is a signal, not a blueprint. Bessent is unlikely to push for a formal legislative restructuring. The more probable outcome is incremental administrative convergence—enough to reshape practice without triggering constitutional or market crises.
- Dollar-denominated assets carry a new institutional risk premium. The sustained assault on Fed independence—regardless of its ultimate outcome—has introduced a structural uncertainty into U.S. monetary credibility that sovereign investors will have to price for at least the remainder of Trump’s second term.
- The 1951 Accord is the key historical precedent. Any future Treasury-Fed coordination framework that echoes pre-Accord arrangements should be treated as a materially negative signal for long-duration U.S. Treasuries and the dollar’s reserve currency status.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Development Finance
Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway
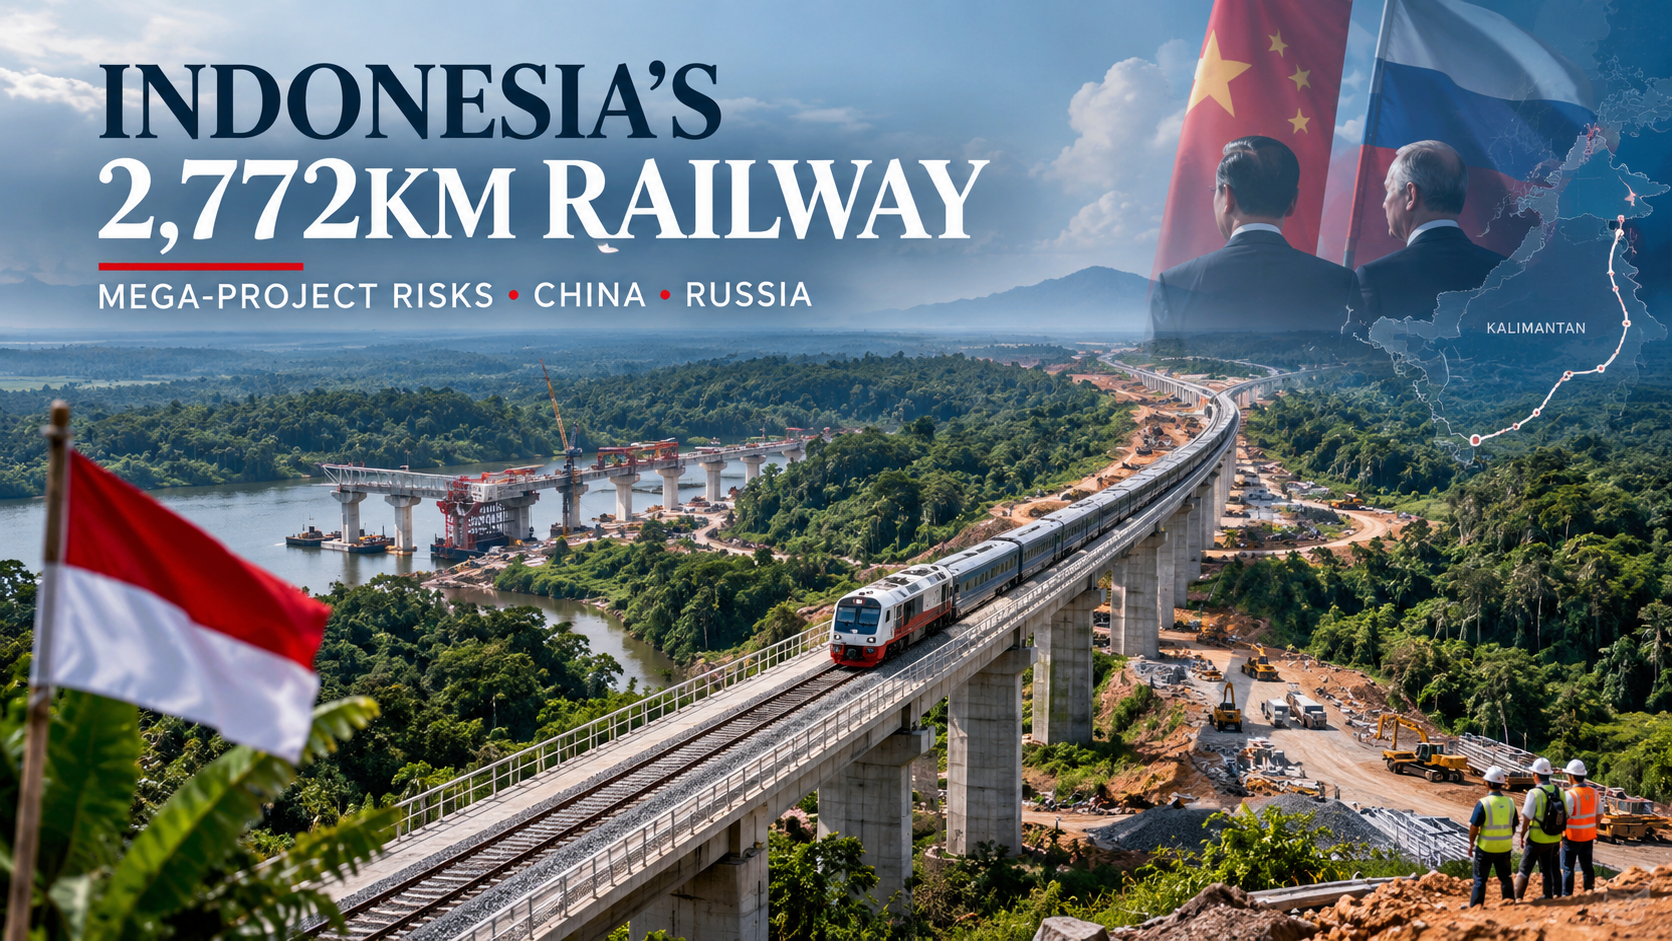
Indonesia is looking to foreign investors—primarily China and Russia—to help fund the ambitious 2,772-kilometer Trans-Kalimantan railway. The sprawling network aims to transform the resource-rich island of Borneo by vastly improving the transportation of minerals and passengers. However, as Jakarta maps out the future of its national rail infrastructure, financial hangovers from previous mega-projects are dictating a far more cautious approach to international commercial agreements.
While the completion of Southeast Asia’s first high-speed rail line between Jakarta and Bandung initially boosted confidence, its crippling cost overruns—alongside the recently stalled underground metro project in Bali—have analysts and government watchdogs warning against the unmitigated risks of foreign-backed debt traps.
The Trans-Kalimantan Vision: Minerals, Connectivity, and Foreign Capital
The Trans-Kalimantan railway is a central pillar of Indonesia’s broader National Railway Master Plan, which targets an expanded 12,100 km of operational railways by 2030. The initial phases aim to construct a 730-kilometer rail link connecting South, Central, and East Kalimantan. The railway will be crucial for the logistical transport of commodities and will eventually integrate with Indonesia’s new capital city, Nusantara.
According to statements by Indonesia’s Transportation Minister, Dudy Purwagandhi, the government is actively exploring foreign investment to shoulder the immense costs of the undertaking. Both Beijing and Moscow have expressed strong interest in the project, seeing it as a prime opportunity to deepen their economic footprint in Southeast Asia.
However, attracting the capital is only half the battle. Negotiating terms that protect Indonesia’s sovereign and economic interests is where the true challenge lies.
The “Whoosh” Warning: High-Speed Rail’s Lingering Debt
If Jakarta needs a blueprint on what to avoid, it only has to look at “Whoosh”—the Jakarta-Bandung high-speed rail. Originally championed as a symbol of Indonesian modernization and a flagship of China’s Belt and Road Initiative, the project broke ground in 2016 with an estimated price tag of $5.5 billion.
By the time it became operational in late 2023, complications ranging from delayed land acquisitions to the COVID-19 pandemic pushed the total project cost past $7.2 billion. The resulting cost overruns of between $1.2 billion and $1.9 billion forced Indonesian state-owned entities to take on heavy financial burdens.
Furthermore, lower-than-anticipated passenger revenues have generated operating losses reaching roughly $258 million in 2024, placing massive pressure on the state rail operator Kereta Api Indonesia (KAI). The high 3.4% interest rate on refinancing loans has triggered widespread domestic criticism and prompted the current administration to push for immediate debt renegotiations with Beijing. The “Whoosh” debacle demonstrates the acute fiscal vulnerability of heavy reliance on a single foreign creditor.
Bali’s Stalled Underground Metro
Concerns over foreign-funded infrastructure are not limited to Java. The highly publicized Bali Urban Subway (Bali Metro) provides another fresh cautionary tale regarding the viability of international megaproject investments.
Conceived as a solution to Bali’s crippling tourist traffic, the underground rail network held a high-profile groundbreaking ceremony in September 2024, backed by anticipated funding from Chinese and South Korean investors. However, as of late 2026, the project has suffered from zero visible progress. Facing an exorbitant estimated price tag of $20 billion and a stark lack of private investment commitment, the Bali provincial government was forced to abandon the underground design entirely in August 2026, pivoting to a much cheaper above-ground Light Rail Transit (LRT) alternative instead.
The abrupt stalling of the Bali Metro highlights the friction between grand infrastructure proposals and the harsh reality of foreign investor risk appetite—particularly when complex land acquisition and local topography are involved.
Strategic Caution Moving Forward
As Indonesia brings China and Russia to the negotiating table for the Trans-Kalimantan railway, it will likely prioritize rigorous feasibility studies, diversified funding models, and strict caps on state budget exposure.
Jakarta is learning that while international capital can expedite its transition into a modern economic powerhouse, the fine print of these multi-billion-dollar deals will determine whether these railways become engines of growth—or generations of debt. To successfully execute the Trans-Kalimantan railway, Indonesia must strike a delicate balance: leveraging foreign technological and financial muscle while fiercely protecting its domestic financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A single slip-and-fall lawsuit against an uninsured small business can wipe out years of profit in one settlement — yet a large share of small business owners still operate without even basic general liability coverage, often simply because no one ever explained clearly what’s actually required versus optional.
Business insurance isn’t a single product — it’s a category spanning general liability, workers’ compensation, professional liability, commercial property, and more, each protecting against different risks. Figuring out which coverage your specific business actually needs, and what it should reasonably cost, is one of the most commonly delayed and misunderstood decisions small business owners face.
This guide breaks down the core types of business insurance, current 2026 cost benchmarks, and how to build the right coverage package without overpaying.
How Business Insurance Actually Works: The Core Coverage Types
Most small businesses don’t need every type of commercial insurance — the right combination depends heavily on industry, whether you have employees, and whether you interact with the public or handle client data.
Key takeaway: General liability insurance isn’t legally required in most states, but it’s often necessary to secure a client contract, obtain a business license, or sign a commercial lease — meaning many business owners end up needing it as a practical requirement of doing business, even without a legal mandate.
The Core Business Insurance Types
- General liability insurance — covers third-party bodily injury, property damage, and personal injury claims arising from your business operations.
- Workers’ compensation insurance — required in most states once you hire employees, covering medical costs and lost wages for work-related injuries.
- Professional liability insurance (errors & omissions) — protects service-based businesses against claims of negligence, mistakes, or failure to deliver promised services.
- Commercial property insurance — covers physical business assets (equipment, inventory, the building itself) against fire, theft, and other covered perils.
- Business Owner’s Policy (BOP) — bundles general liability and commercial property coverage into a single, typically discounted policy.
- Cyber liability insurance — increasingly essential for businesses handling customer payment data or sensitive personal information.
Step-by-Step: Building Your Business Insurance Package
- Assess your specific risk profile — client-facing businesses, those with employees, and those handling sensitive data each face different primary risks.
- Determine legal and contractual requirements — workers’ comp is state-mandated once you have employees, and many commercial leases and client contracts require proof of general liability coverage.
- Get quotes for a Business Owner’s Policy first, since bundling liability and property coverage is typically more cost-effective than purchasing separately.
- Add specialized coverage as needed — professional liability for advice-based businesses, cyber liability for data-handling businesses, commercial auto for businesses with vehicles.
- Review coverage limits against your actual risk exposure, not just the cheapest available policy, since underinsurance can be as costly as no insurance in a serious claim.
- Reassess annually as your business grows, since coverage needs — and available discounts — change as revenue, staff count, and operations evolve.
Financial and Strategic Implications: 2026 Business Insurance Cost Benchmarks
Costs vary substantially by industry, business size, and claims history, but understanding typical ranges helps set realistic budget expectations.
| Coverage Type | Typical Monthly Cost (2026) | Notes |
|---|---|---|
| General liability insurance | $40–$100/month for most small businesses | Median new-customer rate around $55/month per Progressive Commercial data |
| Workers’ compensation | $45–$70/month median, varies heavily by industry risk | Office-based businesses pay far less than construction or manual-labor industries |
| Business Owner’s Policy (BOP) | $57–$150/month | Bundled liability + property, typically cheaper than separate policies |
| Professional liability (E&O) | Varies by profession and revenue | Higher for advice-heavy professions (consulting, financial services, healthcare-adjacent) |
Expert insight: Most small businesses pay roughly $500 to $2,000 a year for general liability or a BOP, with total costs climbing meaningfully once workers’ compensation, commercial auto, or professional liability are added — meaning a realistic total insurance budget should account for the full coverage stack your business actually needs, not just a single policy.
Why Cost Varies So Much by Industry
A home-based bookkeeper and a residential construction crew face fundamentally different risk profiles, and insurers price accordingly. A small consulting firm with a clean claims history might pay $750 to $1,200 per year for general liability coverage, while a construction company with similar revenue could pay $3,000 to $5,000 or more for the same coverage type, reflecting the materially higher claims frequency and severity in higher-risk industries.
Bundling and Discount Strategies
Bundling multiple policies with a single insurer commonly produces automatic discounts of 10% to 15%, and choosing a higher deductible — when cash flow allows — can meaningfully lower monthly premiums for businesses confident in their ability to absorb a modest out-of-pocket cost in the event of a claim.
How to Choose the Right Business Insurance
- Start with a Business Owner’s Policy if you qualify — most small businesses without significant specialized risk exposure fit within a standard BOP more cost-effectively than piecing together separate policies.
- Don’t skip workers’ compensation once you hire employees — it’s legally required in nearly every state and the penalties for non-compliance can be severe.
- Get quotes from at least three insurers, since — as with other insurance categories — identical coverage can price very differently between carriers for the same business profile.
- Work with an independent broker for complex risk profiles, since brokers can shop multiple insurers and identify industry-specific coverage gaps a single-carrier quote might miss.
- Review your policy annually as your business changes — added employees, new locations, or expanded services can all create coverage gaps if the policy isn’t updated.
- Don’t assume a personal umbrella policy covers business activity — business risks generally require dedicated commercial coverage, and mixing personal and business insurance can leave real gaps.
Key takeaway: The businesses that get burned by inadequate insurance are rarely the ones that skipped coverage entirely — they’re far more often the ones that bought a policy years ago and never revisited it as the business grew, leaving real gaps between what’s covered and what the business now actually does.
Future Outlook: Business Insurance Trends Through 2027
- “Social inflation” continues to pressure premiums upward. Rising litigation costs and larger jury awards continue to put upward pressure on general liability premiums nationally, a trend insurers refer to as social inflation, meaning even businesses with clean claims histories may see gradual rate increases independent of their own risk profile.
- Cyber liability coverage is shifting from optional to expected. As data breach costs and regulatory penalties continue rising, more commercial leases, client contracts, and vendor agreements are beginning to require proof of cyber liability coverage alongside traditional general liability.
- Digital-first insurers continue to compress quote-to-bind timelines. More small business insurance providers now offer instant online quotes and same-day coverage, reducing a process that historically took days or weeks through a traditional broker.
- State-level regulatory divergence on liability rules continues. States with joint-and-several-liability frameworks and higher litigation rates continue to see meaningfully higher general liability premiums than lower-litigation states, reinforcing the value of location-aware comparison shopping.
Frequently Asked Questions
Is business insurance legally required?
It depends on the type. Workers’ compensation is legally required in nearly every state once you have employees, while general liability insurance is not legally mandated in most states but is frequently required by landlords, lenders, and client contracts.
What’s the difference between general liability and professional liability insurance? General liability covers third-party bodily injury and property damage claims, while professional liability (errors & omissions) covers claims of negligence, mistakes, or failure to deliver services as promised — the coverage most relevant to service and advice-based businesses.
How much does small business insurance typically cost?
Most small businesses pay roughly $500 to $2,000 a year for general liability or a bundled Business Owner’s Policy, with total costs increasing once workers’ compensation, professional liability, or commercial auto coverage is added.
What is a Business Owner’s Policy (BOP)?
It’s a bundled policy combining general liability and commercial property coverage into a single, typically discounted package, well-suited to most small businesses without highly specialized risk exposure.
Do I need cyber liability insurance for a small business?
Increasingly yes, particularly if your business handles customer payment information or sensitive personal data, as data breach costs and related legal exposure have grown substantially in recent years.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Executive Summary & Key Takeaways
The global macroeconomic landscape is defined by monetary policy shifts, technological supply chain realignments, and shifting demographic dynamics. According to official economic monitoring by the International Monetary Fund (IMF World Economic Outlook) and the World Bank Group, global GDP exceeds $125 trillion in nominal terms.
- Top Position: The United States maintains its position as the largest nominal economy at $32.38 trillion, driven by tech innovation, resilient consumer demand, and deep capital markets, as highlighted by the U.S. Bureau of Economic Analysis.
- PPP Leader: China dominates Purchasing Power Parity (PPP) with an output of $44.30 trillion, reflecting its massive industrial capacity and domestic consumption scale.
- European Dynamics: Germany holds the 3rd spot nominally ($5.45 trillion), navigating energy transitions and industrial re-tooling ahead of Japan ($4.38 trillion).
- Emerging Growth Engines: India leads among major emerging markets with real GDP growth expanding above 6.4%, positioning it to challenge top-tier positions over the coming decade.
Global GDP Ranking Matrix: Top 10 Economies
Below is a comparative breakdown of the top 10 economies, combining Nominal GDP, PPP GDP, Nominal GDP Per Capita, and Real GDP Growth Rates aggregated from primary statistical repositories including Eurostat and the Federal Reserve Economic Data (FRED).
| Rank | Country | Nominal GDP (USD)∣PPPGDP(Int.) | Nominal GDP Per Capita | Real Growth Rate (%) | Key Dominant Sector |
| 1 | United States | $32.38 Trillion | $32.38 Trillion | $94,430 | 2.32% |
| 2 | China | $20.85 Trillion | $44.30 Trillion | $14,874 | 4.41% |
| 3 | Germany | $5.45 Trillion | $6.41 Trillion | $65,303 | 0.79% |
| 4 | Japan | $4.38 Trillion | $7.26 Trillion | $35,703 | 0.72% |
| 5 | United Kingdom | $4.26 Trillion | $4.72 Trillion | $61,056 | 0.80% |
| 6 | India | $4.15 Trillion | $18.90 Trillion | $2,813 | 6.48% |
| 7 | France | $3.60 Trillion | $4.73 Trillion | $52,083 | 0.86% |
| 8 | Italy | $2.74 Trillion | $3.87 Trillion | $46,505 | 0.52% |
| 9 | Russia | $2.66 Trillion | $7.53 Trillion | $18,525 | 1.09% |
| 10 | Brazil | $2.64 Trillion | $5.23 Trillion | $12,313 | 1.91% |
In-Depth Profile of the Top 10 Economies
1. United States
- Nominal GDP: $32.38 Trillion | PPP GDP: $32.38 Trillion | Per Capita: $94,430
- Growth Rate: 2.32%
- Economic Analysis: The U.S. economy remains the world’s chief financial powerhouse. Its growth is underpinned by flexible labor markets, dominant technology giants, and capital allocation mechanisms tracked by the Federal Reserve System. The nation’s strength in artificial intelligence, software infrastructure, biotechnology, and energy self-sufficiency shields it against foreign supply chokepoints.
- Macro Risk: High national debt levels and elevated interest rates aimed at controlling service-sector inflation.
2. China
- Nominal GDP: $20.85 Trillion | PPP GDP: $44.30 Trillion | Per Capita: $14,874
- Growth Rate: 4.41%
- Economic Analysis: China is the world’s industrial foundation and the largest economy measured by Purchasing Power Parity. According to global trade documentation from UNCTAD, China leads in global manufacturing export volumes, electric vehicle supply chains, solar tech, and rare earth processing.
- Macro Risk: Real estate market structural adjustments, local government debt debt-servicing burdens, and demographic headwinds from an aging workforce.
3. Germany
- Nominal GDP: $5.45 Trillion | PPP GDP: $6.41 Trillion | Per Capita: $65,303
- Growth Rate: 0.79%
- Economic Analysis: Germany serves as the industrial core of the European Union. Supported by a specialized network of medium-sized industrial leaders (Mittelstand), Germany excels in high-precision engineering, chemical processing, and industrial machinery.
- Macro Risk: Transitioning away from historically cheap pipeline gas toward green hydrogen/renewable infrastructure, combined with structural labor shortages.
4. Japan
- Nominal GDP: $4.38 Trillion | PPP GDP: $7.26 Trillion | Per Capita: $35,703
- Growth Rate: 0.72%
- Economic Analysis: Known for technological innovation and precision manufacturing, Japan benefits from high foreign assets, advanced robotics, and heavy domestic research investment. Trade flows published by the OECD iLibrary highlight Japan’s high value-add manufacturing integration across Asia and the Americas.
- Macro Risk: Persistent demographic contraction and high public debt-to-GDP ratios managed by the Bank of Japan.
5. United Kingdom
- Nominal GDP: $4.26 Trillion | PPP GDP: $4.72 Trillion | Per Capita: $61,056
- Growth Rate: 0.80%
- Economic Analysis: The UK relies heavily on services, which account for roughly 80% of total economic output. London remains one of the world’s premier financial centers, excelling in asset management, insurance, cross-border fintech, and legal services.
- Macro Risk: Supply-chain re-anchoring post-Brexit and sluggish domestic capital investment rates.
6. India
- Nominal GDP: $4.15 Trillion | PPP GDP: $18.90 Trillion | Per Capita: $2,813
- Growth Rate: 6.48%
- Economic Analysis: India is the world’s fastest-growing major economy. Driven by rapid digital public infrastructure expansion, nationwide transport investments, and expanding manufacturing under global supply chain diversification strategies (“China + 1”), India is rapidly scaling up both domestic consumption and industrial exports.
- Macro Risk: Job creation for a massive young workforce and infrastructure expansion bottlenecks.
7. France
- Nominal GDP: $3.60 Trillion | PPP GDP: $4.73 Trillion | Per Capita: $52,083
- Growth Rate: 0.86%
- Economic Analysis: France operates a diversified economy featuring strong tourism, aerospace (Airbus), luxury consumer conglomerates (LVMH, Kering), and nuclear energy generation. Its low-carbon electricity grid provides cost-stability advantages over neighboring industrial markets.
- Macro Risk: Public deficit management and rigid labor market structural adjustments.
8. Italy
- Nominal GDP: $2.74 Trillion | PPP GDP: $3.87 Trillion | Per Capita: $46,505
- Growth Rate: 0.52%
- Economic Analysis: Italy’s economy relies on an export-oriented manufacturing base in its northern regions, specializing in luxury automobiles, industrial automation, pharmaceutical production, and high-end textiles.
- Macro Risk: Public sector debt servicing and structural regional economic disparities between North and South.
9. Russia
- Nominal GDP: $2.66 Trillion | PPP GDP: $7.53 Trillion | Per Capita: $18,525
- Growth Rate: 1.09%
- Economic Analysis: Russia’s economy is anchored by natural resources, defense-industrial state expenditures, and energy commodity exports to non-Western trading partners across Eurasia and Africa.
- Macro Risk: International financial restrictions, currency volatility, and sanctions-driven technology supply constraints.
10. Brazil
- Nominal GDP: $2.64 Trillion | PPP GDP: $5.23 Trillion | Per Capita: $12,313
- Growth Rate: 1.91%
- Economic Analysis: Brazil dominates Latin America’s economic landscape, propelled by agricultural exports (soybeans, beef, sugar), iron ore extraction via Vale, deepwater oil exploration, and a sophisticated fintech banking sector.
- Macro Risk: Fiscal deficit volatility and vulnerability to global commodity price cycles.
Methodology: How Economic Output is Measured
Evaluating economic scale requires understanding three primary economic indicators:
                  ┌────────────────────────────────────────────────┐
                  │          Gross Domestic Product (GDP)          │
                  └───────────────────────┬────────────────────────┘
                                          │
            ┌─────────────────────────────┼─────────────────────────────┐
            ▼                             ▼                             ▼
┌───────────────────────┐     ┌───────────────────────┐     ┌───────────────────────┐
│     Nominal GDP       │     │        PPP GDP        │     │    GDP Per Capita     │
├───────────────────────┤     ├───────────────────────┤     ├───────────────────────┤
│ Expressed in current  │     │ Adjusted for local    │     │ Total output divided  │
│ USD exchange rates.   │     │ purchasing power.     │     │ by population.        │
│ Identifies global     │     │ Reflects internal     │     │ Measures average      │
│ capital power.        │     │ economic scale.       │     │ living standard.      │
└───────────────────────┘     └───────────────────────┘     └───────────────────────┘
- Nominal GDP (Current Prices in USD): Measures the market value of all final goods and services produced within a country in a given year. Nominal values convert domestic output using prevailing market exchange rates. While ideal for assessing international purchasing power, it fluctuates with currency market swings.
- Purchasing Power Parity (PPP): Adjusts for relative price levels and local living costs using an international basket of goods. According to data methodology guides from the Bank for International Settlements (BIS), PPP offers a realistic view of domestic production capability and domestic consumer capacity.
- GDP Per Capita: Divides total economic output by total population. This distinguishes between sheer economic scale (e.g., India or China) and individual living standards (e.g., Switzerland, Luxembourg, or the United States).
Key Takeaways for Global Economic Trends
- The Shift Toward Multipolar Growth: Asia’s expanding market share—led by China, India, Indonesia, and Vietnam—continues to outpace global growth averages, shifting the center of gravity of manufacturing and consumption.
- Energy Transition Dynamics: Nations with sovereign clean tech supply chains (China) or independent nuclear grids (France) gain structural cost advantages over those dependent on imported fossil fuels.
- Demographics vs. Productivity: Aging populations across Europe and East Asia mean future expansion depends heavily on capital deployment into automation, AI infrastructure, and high-margin service exports.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025