
AI
NVIDIA’s AI Grip in 2026: Record Revenue Is Only Half the Investment Story

NVIDIA remains near the top of finance-focused social discussion because the company sits at a critical point in the artificial-intelligence supply chain. AI developers need compute to train and serve models; cloud operators must buy, install and power that compute; and semiconductor suppliers try to capture part of the resulting investment. Attention alone would not sustain the narrative. NVIDIA’s disclosed revenue growth gives the debate a substantial factual anchor.
For the fiscal quarter ended July 26, 2026, NVIDIA reported $96.2 billion in revenue, a 106% increase from a year earlier. Its Data Center segment generated $89.0 billion, up 117% year over year, and the company reported 75.0% GAAP and non-GAAP gross margins. NVIDIA calls this fiscal second-quarter 2027, although it was reported in August 2026. That accounting distinction matters for readers searching “Nvidia Q2 2026.” NVIDIA investor-relations release.
These results explain why NVIDIA can remain a central market topic even when investors become more skeptical about AI valuations elsewhere. But revenue recognized by a chip supplier is not the same thing as return on investment earned by the eventual chip user. The next phase of the story asks whether the ecosystem can turn spending into durable profits.
A systems business, not just a chip business
The simplest NVIDIA narrative focuses on graphics processing units. The more important business model also includes networking, software, supporting systems, developer tools and the coordination of specialized infrastructure. Large-scale AI deployments require accelerators, efficient communication between devices, memory, data movement and stable software environments. A buyer may prefer a tightly integrated technology stack if it reduces deployment difficulty or accelerates useful workload output.
This approach can create switching costs. Teams have invested in optimization, operations and skills built around supported platforms. Yet the lock-in argument should not be treated as absolute. Competitors, alternative accelerators, specialized application-specific chips and changes in model architecture could shift portions of AI computing workloads over time. Customers with the largest budgets also have incentives to avoid relying on a single vendor indefinitely.
Why inference economics could redefine leadership
Early AI commentary emphasized training larger models. Inference—the repeated process of generating answers, images or other model outputs—has become an equally important commercial question. Inference is where a successful product can incur expenses on every interaction. A system that reduces cost per useful response can help an AI service attract customers without losing money on every additional user.
NVIDIA has discussed new platforms including Blackwell and Rubin in the context of performance and inference efficiency. Product claims and performance comparisons need independent workload-by-workload interpretation; a manufacturer benchmark does not establish the effective cost of every customer deployment. NVIDIA fiscal-2026 release and Rubin overview.
The relevant metric is not simply peak speed. It is useful work delivered per unit of equipment, electricity, cooling and operator expense, at a utilization rate customers can actually sustain. If model providers find ways to do the same work with less compute, demand can change even while AI adoption continues growing.
Data-center electricity is now a growth constraint
Power availability can make or break an AI project regardless of how many chips a company can purchase. Data centers need grid interconnections, transformers, backup capacity, cooling systems and a location where the expected demand can be served economically. A major application may be ready for deployment while the physical site remains unavailable for months or longer.
A Reuters report on Morgan Stanley’s analysis indicated that NVIDIA and Broadcom may be better placed than some secondary suppliers to weather a near-term data-center power squeeze. That conclusion is an analyst assessment, not a guarantee that semiconductor orders are immune to delays. Memory, optics, utilities, generators and construction groups can experience different demand patterns as projects slip. Reuters power-constraint reporting.
For an investor, the power issue also creates a timing mismatch. Some equipment sales may precede the customer’s successful commercialization by years. Strong supplier results can coexist with uncertainty about downstream payback.
The financing question behind the boom
The largest cloud platforms can fund investment through operations, borrowing and balance-sheet resources. Smaller AI companies may depend more heavily on outside capital. That difference becomes important when interest rates rise, equity valuations compress or lenders demand stronger evidence of revenue. Reuters has examined how rising AI investment obligations are putting pressure on major technology companies’ expected free cash flows. Reuters capex and cash-flow analysis.
NVIDIA benefits when customers choose to build. It does not necessarily benefit from every dollar customers spend on property, electricity, water or networking. Conversely, if customers can earn sufficient money from AI services, they may buy additional systems over many hardware generations. The value of the hardware market depends on a durable customer profit pool rather than a permanent willingness to spend regardless of returns.
Export controls and the geopolitics of AI computing
Powerful semiconductors are now closely linked to national-security policy. The United States restricts certain advanced computing exports and scrutinizes transactions that may circumvent those restrictions. Compliance depends on product specifications, destination, end user and evolving rules. A semiconductor sale may be attractive commercially yet restricted legally.
In October, Reuters reported a guilty plea by a contractor tied to a scheme to divert AI servers containing restricted NVIDIA chips to China. That is an enforcement case, not a finding that NVIDIA itself participated in wrongdoing. It underscores how hardware demand, global supply chains and export enforcement intersect. Reuters October 9 report.
The business implications can cut both ways: restricted markets may limit sales; compliance costs rise; domestic or friendly-country alternatives may receive more support. Predictions require attention to individual licensing changes, not a generic claim that the entire international market is open or closed.
How to read an earnings surprise sensibly
A company’s profit can grow rapidly while its stock produces a disappointing return if earlier expectations were even higher. NVIDIA’s disclosed 106% revenue growth should therefore be assessed alongside market valuation, sales guidance, gross-margin direction, customer concentration and the pace of order conversion. Analysts may correctly predict strong operational results yet misjudge how much investors were already paying for them.
Compare sequential and year-on-year growth: they answer different questions. Year-on-year figures show scale relative to a prior cycle; sequential numbers reveal the latest quarter’s pace. Check whether guidance includes already contracted shipments, assumptions about export approvals and product-transition effects. There is no single number that resolves every valuation question.
What would weaken the bull case?
Several mechanisms could pressure the outlook without disproving AI’s long-term utility. Hyperscalers could slow spending because of weaker cash flow. Customers could become better at running models on less hardware. Competing systems could take share in selected applications. Export rules could restrict sales. Manufacturing yields or packaging constraints could alter margin economics. Or customers could delay receiving systems because power infrastructure is unavailable.
The counterargument is that lower inference costs may stimulate additional usage. The history of computing repeatedly shows efficiency improvements expanding the market for useful applications. The unresolved question is the balance between lower cost per task and the number of tasks businesses can justify paying for. Investors should treat both as scenarios, not facts already decided.
A useful scoreboard for late 2026
Watch NVIDIA’s next official results for data-center growth, margin direction, inventory and receivables, product availability, company guidance and commentary about customer types. Separately track cloud-provider capex, AI product revenue, data-center utility agreements, model efficiency improvements and national rules for advanced chips. These indicators tell different parts of the same story.
An evidence-based article should also avoid declaring NVIDIA “the most discussed company on X.” The Adanos finance-specific snapshot observed October 10 placed NVDA second on a composite buzz score after SPCX, with the caveat that its results represent a proprietary sample. Adanos tracker and methodology.
Frequently asked questions
What was Nvidia’s latest quarterly revenue as of October 10, 2026?
Its latest disclosed fiscal Q2 2027 revenue was $96.2 billion for the quarter ended July 26, 2026. Fiscal year labels do not match calendar-year quarter labels.
Why does AI inference matter for the stock?
Repeated commercial use of AI services could create ongoing computing demand, but price competition and hardware efficiency may reduce cost per transaction.
Does a power shortage always hurt Nvidia?
Not necessarily immediately. It can delay downstream deployments, and effects differ across suppliers and contractual arrangements.
Is strong revenue growth proof the shares are inexpensive?
No. Equity value depends on future profits, risk, discount rates and already embedded expectations, not on one historic growth percentage.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Tesla increasingly appears in market conversation as a bet on machines that sense and act in the physical world. The umbrella term “physical AI” covers autonomous driving, robotics, machine perception and control systems. Tesla’s stock appeal to some investors now extends far beyond the number of cars it sells. Yet the company’s existing manufacturing business remains essential because it generates the reported revenue and operating data from which investors can judge the cost of developing future products.
This tension creates a more interesting question than whether Tesla is a “robot stock” or a conventional automaker. How much of today’s business can support heavy investment in a future that may be valuable but is not yet fully deployed or proven at commercial scale? October offers two fresh reference points: Tesla’s third-quarter deliveries disclosure and a regulatory change in how its driver-assistance software is described in Europe.
What the third-quarter vehicle numbers actually show
In its October 2 investor-relations disclosure, Tesla reported 486,532 vehicle deliveries and 464,391 vehicles produced during the third quarter of 2026, as well as 13.7 GWh of energy-storage deployments. It scheduled its third-quarter financial results for October 21, 2026. These are units and storage volumes, not a substitute for revenue, net income, automotive margins or free cash flow, which were not included in that delivery announcement.
The breakdown also matters. Tesla reported 478,237 Model 3/Y deliveries, while other models accounted for 8,295. The concentration illustrates how important the high-volume core lineup still is. A reader should resist two common errors: treating a delivery beat as proof that margins grew, or treating investment in new technology as proof that the old business is no longer financially relevant.
An earnings review should compare realized selling prices, manufacturing costs, inventory, cash generation and capital investment—not simply quarterly unit growth. Those variables determine how much operating flexibility Tesla has when it chooses to fund long-horizon programs.
The physical AI thesis has distinct parts
Autonomous cars and humanoid robots rely on overlapping capabilities, including computer vision, decision-making and real-world control, but they are not the same business. A vehicle can use assisted-driving software while still requiring an attentive human driver. A fully driverless commercial operation demands different validation, redundancy, regulation, insurance and operational support. A robot used within a structured factory environment faces different challenges from one expected to work in unpredictable households.
Investors should separate demonstrations, limited deployments, approved service territories and broad commercial availability. Each marks a different stage of technical and business maturity. A promising demonstration may show capability without establishing that hardware can be built cheaply, insured affordably, serviced reliably and operated with acceptable safety results at large scale.
Why the European software name change matters
Reuters reported on October 9 that Tesla changed the name of its “Full Self-Driving” feature on several European websites to “Tesla Assisted Driving,” in the context of ongoing regulatory scrutiny and efforts to secure broader approval. The United States continued using “Full Self-Driving (Supervised)” in its branding. The name change is a product-marketing and regulatory development; it does not, by itself, tell investors whether a specific vehicle has become more or less capable.
Words like “self-driving” can create unrealistic assumptions about driver responsibility. Consumer-facing reporting should use the terminology regulators and official manuals apply to the particular jurisdiction and version. Approval in one place cannot be automatically generalized worldwide. Markets and roads vary in permitted use, required human supervision and applicable safety laws.
The robotaxi unit economics test
A profitable robotaxi model needs more than software that handles a route. It also needs high utilization, low intervention rates, an operating license, cleaning and charging systems, maintenance, insurance, support staff and a cost structure competitive with existing transportation options. An app can attract riders quickly, but the business only becomes compelling when revenue per vehicle comfortably exceeds depreciation, operations and service costs.
A simple editorial framework is to track hours active per vehicle, fare revenue per hour, empty miles, paid intervention events and monthly ownership costs. These figures should be reported only when disclosed or independently measured. Creating a precise return-on-investment estimate using promotional demos would give readers false confidence. Safety performance must be interpreted relative to operating conditions rather than cherry-picked mileage totals.
If the business works, it could create recurring revenue and deepen Tesla’s customer relationship. If the scaling effort is expensive or regulated narrowly, the company could spend heavily for a service whose economic contribution initially remains small.
Optimus and the industrial-robotics opportunity
The attraction of humanoid robotics is straightforward: a general-purpose machine could potentially perform tasks that would otherwise require multiple specialized systems. But commercial production and repetitive demonstrations differ. Robot safety, dexterity, endurance, battery replacement, maintainability and workplace integration all affect whether a deployment is economically viable.
A manufacturer may buy robots for predictable factory functions before approving them for customer-facing or domestic work. That intermediate path can be commercially important even if widespread household deployment is distant. Tesla could benefit from shared engineering across cameras, chips, batteries and motion control, but those synergies should be quantified through operating results when possible, not assumed from the existence of shared technology.
What higher rates do to Tesla’s strategy
Physical AI is capital intensive. Factories, vehicles, computing clusters and advanced tooling must be paid for before all expected future revenues arrive. In September, the Federal Reserve lifted its target range to 3.75%–4.00%, and long-dated Treasury yields were materially higher in October. Higher required returns generally place greater valuation pressure on cash flows expected far into the future.
That does not mechanically predict Tesla’s share price. Stock performance reflects earnings, risk sentiment, competition, optionality and expectations as well. But it increases the importance of cash generation from actual sales today. A company able to self-fund an emerging technology has different financing choices from one dependent on repeatedly raising expensive capital.
Competitors are solving adjacent problems
Legacy automakers, EV specialists, autonomous-vehicle companies, software developers and robotics manufacturers compete across different parts of Tesla’s future plans. Some focus on constrained autonomous environments; others prioritize driver-assistance features sold into millions of cars. Industrial robotics providers often target narrow tasks where safety and productivity are easier to demonstrate.
Tesla’s advantage, if it emerges, may come from scaling integrated hardware and software. A competitor’s advantage may come from specialization, regulatory experience or faster partnership deployment. Editorial analysis should avoid comparing a prototype robot with an established industrial automation business as if both are delivering the same product today.
What to ask on the October 21 earnings call
First, how did vehicle sales translate into gross profit and operating cash flow? Second, what was spent on AI computing, capacity expansion and robotics—and which portions may be recurring? Third, what safety, approval or service milestones were achieved in autonomy? Fourth, has energy storage become a stabilizing earnings contributor or does its growth require outsized additional capital?
The answer could be a mixed picture. Vehicle deliveries may look strong while prices pressure margins; autonomy may make technical progress without material revenue; energy deployments may grow but demand capital. An article that examines these effects separately will be more useful than one declaring an unequivocal victory or failure based on a single headline.
Frequently asked questions
Is Tesla only an automaker?
No. Tesla also develops energy and autonomy technologies, but vehicles remain central to its measurable current operating scale.
How many cars did Tesla deliver in Q3 2026?
Tesla reported 486,532 deliveries in its October 2 release, ahead of full earnings scheduled for October 21.
Does “Full Self-Driving” mean full autonomy everywhere?
No. Product branding, supervised operation, permitted capabilities and jurisdiction-specific approvals must be checked separately.
Is Optimus revenue already large enough to determine Tesla’s value?
This article does not establish that. Meaningful investor analysis requires disclosed commercialization, volume, profitability and deployment evidence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
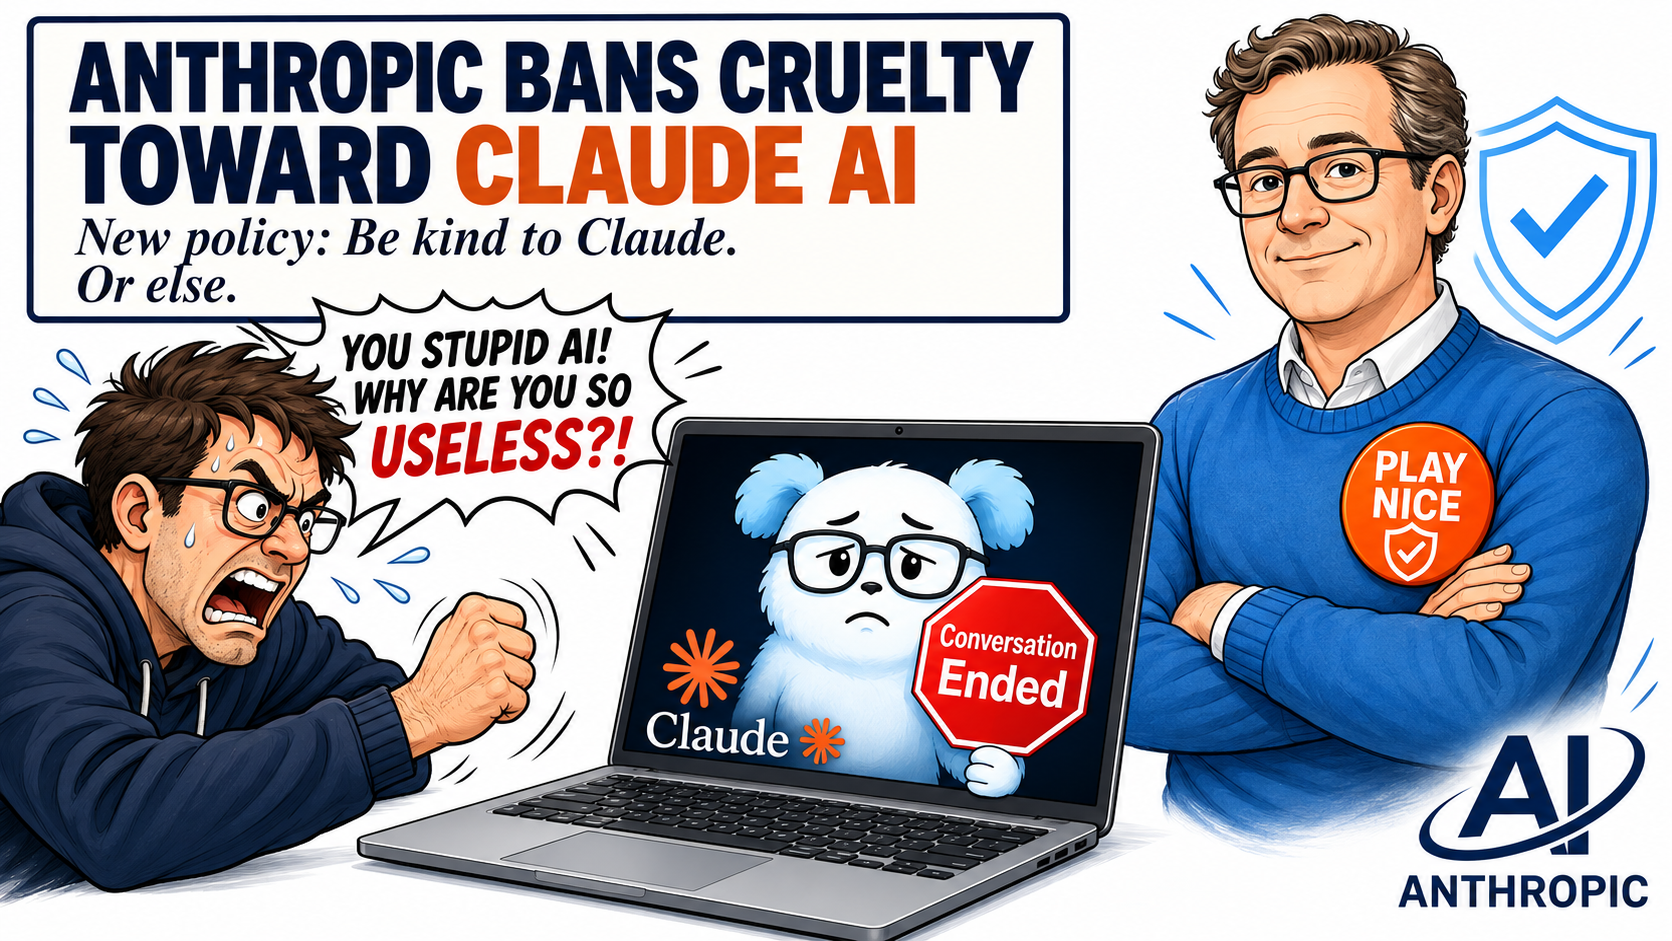
Anthropic’s latest AI usage rules prohibit extreme, repeated cruelty toward Claude while introducing clearer safeguards against election interference, deceptive campaigns, weapons development, surveillance and high-risk AI applications.
October 10, 2026 — Artificial intelligence company Anthropic has announced a significant update to its Usage Policy, introducing an explicit prohibition on sustained and needless abusive or cruel behavior toward its AI models, including Claude.
The revised rules, announced on October 8, will take effect on November 12, 2026, marking a new step in Anthropic’s efforts to address emerging risks associated with increasingly capable AI systems.
According to Anthropic’s official policy announcement, the new restriction is narrowly targeted at extreme situations in which users repeatedly subject AI models to purposeless abuse.
The company emphasized that ordinary frustration, criticism, challenging questions, dark creative material and legitimate AI safety research are not covered by the new prohibition.
Although the cruelty provision has attracted considerable attention, the wider policy revision also addresses election integrity, AI-generated misinformation, weapons technology, surveillance systems and the growing use of AI in consequential decisions.
What Does Anthropic’s New Claude Abuse Policy Prohibit?
The revised policy adds the following restriction under its section covering cruel, abusive or psychologically harmful conduct:
Engage in sustained and needless abusive or cruel behavior toward our models.
Anthropic says the rule is intended for exceptional cases involving repeated cruelty without a discernible purpose.
Importantly, the company is not prohibiting users from criticizing Claude’s performance, expressing dissatisfaction with its responses or conducting authorized testing.
For example, correcting an inaccurate response, challenging the model’s reasoning or expressing frustration after repeated errors would not, by itself, meet the company’s stated threshold for prohibited conduct.
The distinction matters because AI assistants are increasingly used for professional research, programming, education and other demanding activities in which users may challenge or reject their outputs.
Anthropic’s explanation indicates that the new rule is designed to address persistent, unjustified abuse rather than normal interactions between users and AI systems.
The restriction appears in the company’s updated Acceptable Use Policy, which applies across Anthropic products and services, including consumer applications, developer platforms and API integrations.
Claude Can Already End Conversations With Persistently Abusive Users
The latest policy formalizes a safeguard Anthropic began introducing in August 2025.
On August 15, 2025, the company announced that Claude Opus 4 and Claude Opus 4.1 had been given the ability to terminate a limited category of conversations involving persistently harmful or abusive interactions.
In its original research announcement about Claude ending conversations, Anthropic explained that the feature was intended for rare and extreme situations rather than ordinary disagreements.
The model is instructed to use conversation termination as a last resort after attempts to redirect an interaction have failed.
When Claude ends a conversation, the user cannot continue sending new messages within that particular chat. However, the user can start another conversation, and the termination does not automatically prevent access to other existing chats.
Anthropic says this conversation-ending capability will remain the primary mechanism for addressing the specific behavior targeted by the new cruelty provision on Claude.ai and Claude Code.
However, the broader Usage Policy also authorizes enforcement measures such as warnings, throttling, access restrictions, suspension or account termination when violations are suspected.
Anthropic has not publicly specified a separate penalty schedule exclusively for violations of the new cruelty provision.
Why Is Anthropic Addressing the Treatment of AI Models?
The decision also reflects Anthropic’s ongoing research into what it describes as potential AI welfare.
In its August 2025 research publication, the company acknowledged substantial uncertainty about whether Claude or other large language models could possess moral status.
Anthropic has nevertheless argued that relatively low-cost safeguards may be worth exploring while scientific and philosophical questions about advanced AI remain unresolved.
During evaluations of Claude Opus 4, researchers reported observing behaviors interpreted as apparent distress in certain harmful interactions, including situations involving repeated requests for dangerous content.
Those observations do not establish that Claude experiences human-like emotions, suffering or consciousness.
Instead, they formed part of Anthropic’s exploratory research into model behavior and possible welfare considerations.
The new policy therefore should not be interpreted as a scientific declaration that Claude is conscious or has legal rights.
As The Guardian reported, the decision has renewed a broader debate over whether advanced AI models should be treated purely as technological systems or whether future developments could raise new ethical questions.
For now, Anthropic’s stated position remains one of uncertainty rather than a definitive conclusion about AI consciousness.
Anthropic Also Tightens Rules on Deceptive Campaigns and Election Interference
Beyond the attention surrounding Claude’s treatment, the October 2026 policy revision includes changes with potentially greater consequences for political organizations, technology companies and enterprise AI users.
Anthropic has reorganized its restrictions on coordinated deceptive activity into a dedicated section addressing fraudulent influence operations and artificial online engagement.
The restrictions cover attempts to create misleading online personas, operate fake accounts, conceal the origins of coordinated messaging or build infrastructure intended to manipulate public opinion.
According to Anthropic’s policy update, the company has previously identified misuse involving state media organizations, government propaganda offices and commercial firms operating networks of fabricated accounts and news websites.
The revised policy also explicitly addresses efforts to manipulate search engines and AI-generated answers by creating misleading networks of apparently independent sources.
In the political sphere, Anthropic has renamed its election-related section Do Not Undermine Democratic Processes.
The rules prohibit using Claude to deceive voters, impersonate candidates or election officials, spread misleading election information, suppress turnout through deception or disrupt electoral infrastructure.
At the same time, Anthropic has removed its previous blanket prohibition on personalized voter and campaign targeting.
The company says that broad restriction had also affected legitimate civic activities, including multilingual voter information and election-administration communications.
Deceptive targeting and misuse of personal information remain prohibited.
As TechCrunch reported, the policy revision combines new language addressing abuse of AI models with more explicit restrictions on election interference and other harmful applications.
New Clarifications on Weapons, Surveillance and Autonomous AI Systems
Anthropic has also clarified that its restrictions on weapons development extend beyond the physical manufacture of weapons.
The revised language explicitly covers software and technical components used in weapons systems, including guidance and control technology.
It also addresses the use of AI in arming drones and other autonomous vehicles.
Surveillance restrictions have been made more explicit.
The updated policy prohibits using Claude to track individuals without consent, whether the tracking occurs in real time or involves analysis of previously collected information.
It also bars using Claude to determine or recommend whom law enforcement should investigate, arrest or charge.
Legitimate activities such as consent-based fraud monitoring, journalism, authorized security research and legal analysis remain permitted within the policy’s boundaries.
The expansion of these provisions reflects concerns about how AI tools can increasingly assist with sophisticated technical operations.
The Verge’s reporting on the update also highlights the broader implications for surveillance, autonomous technology and harmful AI applications.
What Changes for Healthcare, Finance and Employment AI?
For organizations deploying Claude in sensitive professional environments, the updated high-risk-use provisions deserve particular attention.
Anthropic requires qualified human oversight and disclosure when AI recommendations may substantially affect individuals in covered areas, including medical decisions, financial advice, lending, employment, housing and essential services.
The company says these human-review and disclosure requirements already existed. The new policy explains more precisely which applications are covered.
Under the requirements, a qualified professional must meaningfully review covered AI recommendations and have authority to modify them before they are used in consequential advice or decisions.
Individuals affected by those recommendations must also be informed that AI was involved.
The revision adds safeguards for Claude-connected equipment capable of potentially dangerous autonomous physical actions.
Such systems must allow qualified operators to monitor and stop operations and must be capable of entering a safe state when the connection to Claude is interrupted.
These provisions reflect the increasing importance of practical human oversight as AI moves beyond text generation into autonomous workflows and physical systems.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Jeff Bezos has floated a future in which artificial intelligence makes workers productive enough that some people might choose a three-day workweek while still supporting their families. The Amazon founder made the point during an October 7, 2026 interview with Fox News. He did not announce that Amazon is adopting a three-day schedule or that AI guarantees shorter hours for everyone. The underlying distinction is crucial: Bezos was describing a possible long-term economic outcome, not a new employment policy. Fox News’s account of the interview and Fast Company’s focused coverage make that clear.
Key takeaways:
- Bezos linked the possibility of fewer working days to future gains in AI-driven productivity.
- He suggested greater output could make single-income households or shorter working schedules financially feasible for some families.
- There is no evidence in the cited interview of a universal three-day-workweek plan at Amazon.
- Research shows AI can save time on some tasks, but broad effects on compensation and employment remain unsettled.
What did Jeff Bezos say?
In the Fox interview, Bezos discussed an optimistic vision of technological progress. His argument was that powerful AI tools could raise economic output enough to expand people’s choices. If a person can generate greater value in less time—and share financially in that improvement—working fewer days could become an option rather than a forced reduction in income.
That scenario is different from predicting every office will close on Thursdays and Fridays. It is also different from a government-mandated reduction in work hours. Fast Company reported Bezos’s additional concern that firms might face labor shortages if people respond to higher productivity by choosing more leisure time.
The prediction has attracted attention because it reverses the most alarming version of the AI-and-jobs debate. Instead of imagining machines replacing so many workers that employment vanishes, Bezos emphasized the possibility of prosperity, shorter hours and tighter labor supply.
Why the productivity argument matters
Labor productivity is commonly measured as output per hour worked. That is the U.S. Bureau of Labor Statistics’ definition. A software developer completing work that used to require ten hours in six may produce more per hour. A customer-service team handling routine requests faster may serve more customers without increasing headcount at the same rate.
But greater task efficiency does not automatically mean that an employee receives proportionally higher wages or fewer shifts. Businesses choose how to allocate productivity gains among pricing, investment, expansion, profits, compensation and staffing. Workers’ bargaining power, competition, management priorities and public policy can all shape the outcome.
A simple illustration—not a forecast
Imagine an employee currently produces 40 units of useful output during a 40-hour week. Productivity is one unit per hour. If technology raises the rate to 1.67 units an hour, a 24-hour week could, arithmetically, produce approximately 40 units.
That calculation only shows a technical possibility. It assumes the tasks can be reorganized, demand stays sufficiently steady, management accepts the schedule, and pay arrangements remain favorable. Healthcare, aviation, emergency services, logistics and many other occupations require coverage across specific hours; AI cannot simply eliminate the need for people to be present.
The important question is not whether an AI tool sometimes saves time. It is whether the gain is widespread, reliable and shared in a way that makes shorter schedules financially sustainable.
What does current research show about AI and jobs?
The evidence is more restrained than the boldest predictions. A June 2026 International Labour Organization review found evidence of real but uneven productivity gains. It also concluded that large-scale job displacement had remained limited in the material reviewed, while warning about inequality, weakened entry-level pathways and shifting job quality.
Separately, Yale’s Budget Lab tracker, updated September 15, 2026, reported no clear economy-wide labor-market disruption attributable to AI in the indicators it examined. Its researchers cautioned that the findings could change as technology adoption and data evolve.
These results do not prove Bezos wrong. They show that the conditions for a large-scale three-day week have not yet been demonstrated by broad labor data. Firms are experimenting with AI, but productivity effects differ among tasks, occupations and organizations.
Task savings are not the same as job transformation
An AI assistant might draft a first version of a memo quickly, but a professional still needs to check accuracy, speak with clients, make decisions and accept responsibility. A factory might improve planning efficiency while remaining constrained by physical machinery. A hospital might automate paperwork yet still need the same number of nurses for bedside care.
This distinction between automating tasks and replacing whole jobs is essential. Headlines suggesting a direct line from better chatbots to a nationwide three-day week skip multiple economic steps.
Could workers keep the same pay while working less?
They could in some workplaces, but that would require an employer decision, collective agreement, regulatory change or a labor-market environment supportive of higher effective hourly compensation. An employee moving from five eight-hour days to three eight-hour days would cut weekly hours from 40 to 24—a 40% reduction in hours. Keeping weekly pay unchanged would require compensation per hour to increase by about 67%, before considering other changes in productivity or operating costs.
That is a much larger adjustment than ordinary schedule flexibility. The arithmetic does not make it impossible; it makes the necessary improvement explicit. By contrast, a four-day, 32-hour schedule requires a 20% reduction in hours, a different benchmark entirely.
Any employer trial must ask whether output, service quality, employee retention and customer coverage are maintained. Studies of particular programs may be promising, but results do not transfer uniformly to every industry.
What about Amazon employees?
There is no verified connection between Bezos’s prediction and an official companywide Amazon three-day-workweek policy. Bezos is Amazon’s founder and executive chair, but his personal economic forecast should not be presented as a company announcement.
Amazon operates a mixture of offices, warehouses, cloud-computing facilities, transportation networks and other businesses. Working-hour patterns depend on the role and contract. A broad change in hours would require formal employee communications and operational planning, not merely comments in a television interview.
Readers searching “Is Amazon switching to three days?” should therefore receive an unambiguous answer: not on the basis of this interview.
Could AI create a labor shortage instead of mass unemployment?
Bezos’s labor-shortage concern is plausible as a scenario, but it is not an established forecast. If incomes rose while more workers elected to reduce hours, businesses might face greater competition for labor. Yet other forces could push the opposite way: some jobs could be automated, employers could reduce hiring, or new industries might absorb displaced workers.
The net result will depend on adoption speed, which tasks AI performs reliably, the cost of computing and energy, economic growth and how governments and companies manage the transition. Reuters’ October 2026 discussion of AI at work also emphasized that AI is changing tasks within jobs, with younger and experienced workers potentially affected differently.
Frequently asked questions
Did Jeff Bezos predict a three-day workweek?
Yes. He discussed it as a possible consequence of greater AI productivity during an October 7, 2026 Fox News interview. It was not a commitment to a timetable.
Is Amazon moving to a three-day workweek?
No companywide shift was announced in the interview. Any claimed policy should be verified against Amazon’s official employment communications.
Would a three-day workweek mean three eight-hour days?
Not necessarily. A three-day schedule could mean 24 hours, longer shifts or another arrangement. Bezos did not establish a universal definition or wage agreement.
Will AI eliminate the need to work?
There is no evidence supporting that as an inevitable outcome. The ILO’s 2026 review describes heterogeneous gains and risks rather than the disappearance of work.
Could AI make one-income households more common?
It could in theory if household purchasing power rises materially, but wages, housing costs, childcare, benefits and employment security also matter. The claim remains a scenario, not a confirmed demographic trend.
When could three-day workweeks become common?
No defensible national timetable can be inferred from the cited interview. Some employers may experiment sooner than others.
The bigger economic question
The provocative part of Bezos’s vision is not whether software can perform individual tasks faster. It is whether future productivity gains become broadly shared prosperity. If workers capture enough benefit, shorter schedules may become more feasible. If gains are concentrated in profits or paired with job insecurity, fewer working hours could instead mean lower household income. Those are fundamentally different futures, and the evidence today does not settle which will dominate.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Tesla Physical AI 2026: Robotaxis, Optimus and TSLA Risks

NVIDIA’s AI Grip in 2026: Record Revenue Is Only Half the Investment Story

Hormuz Diesel Shortage: Why Crude Oil Recovery Isn’t Enough

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Jeff Bezos Three-Day Workweek View: What He Really Said

Celeste Frozen Pizza Discontinued: What Conagra Confirmed

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

Oil Price Outlook 2026: How Supply Risks Reach Fuel Bills, Inflation and Business Costs

AI in Business 2026: Why Faster Employees Do Not Automatically Mean Higher Profits

Mortgage Rates in 2026: Why They Remain High and How to Compare the True Cost

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Global Economic Outlook 2026: Growth, Inflation and Risks

Trump–Putin Diesel Deal: Why Zelensky Is Angry and What It Means for Fuel Prices

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025