
Mining
Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?

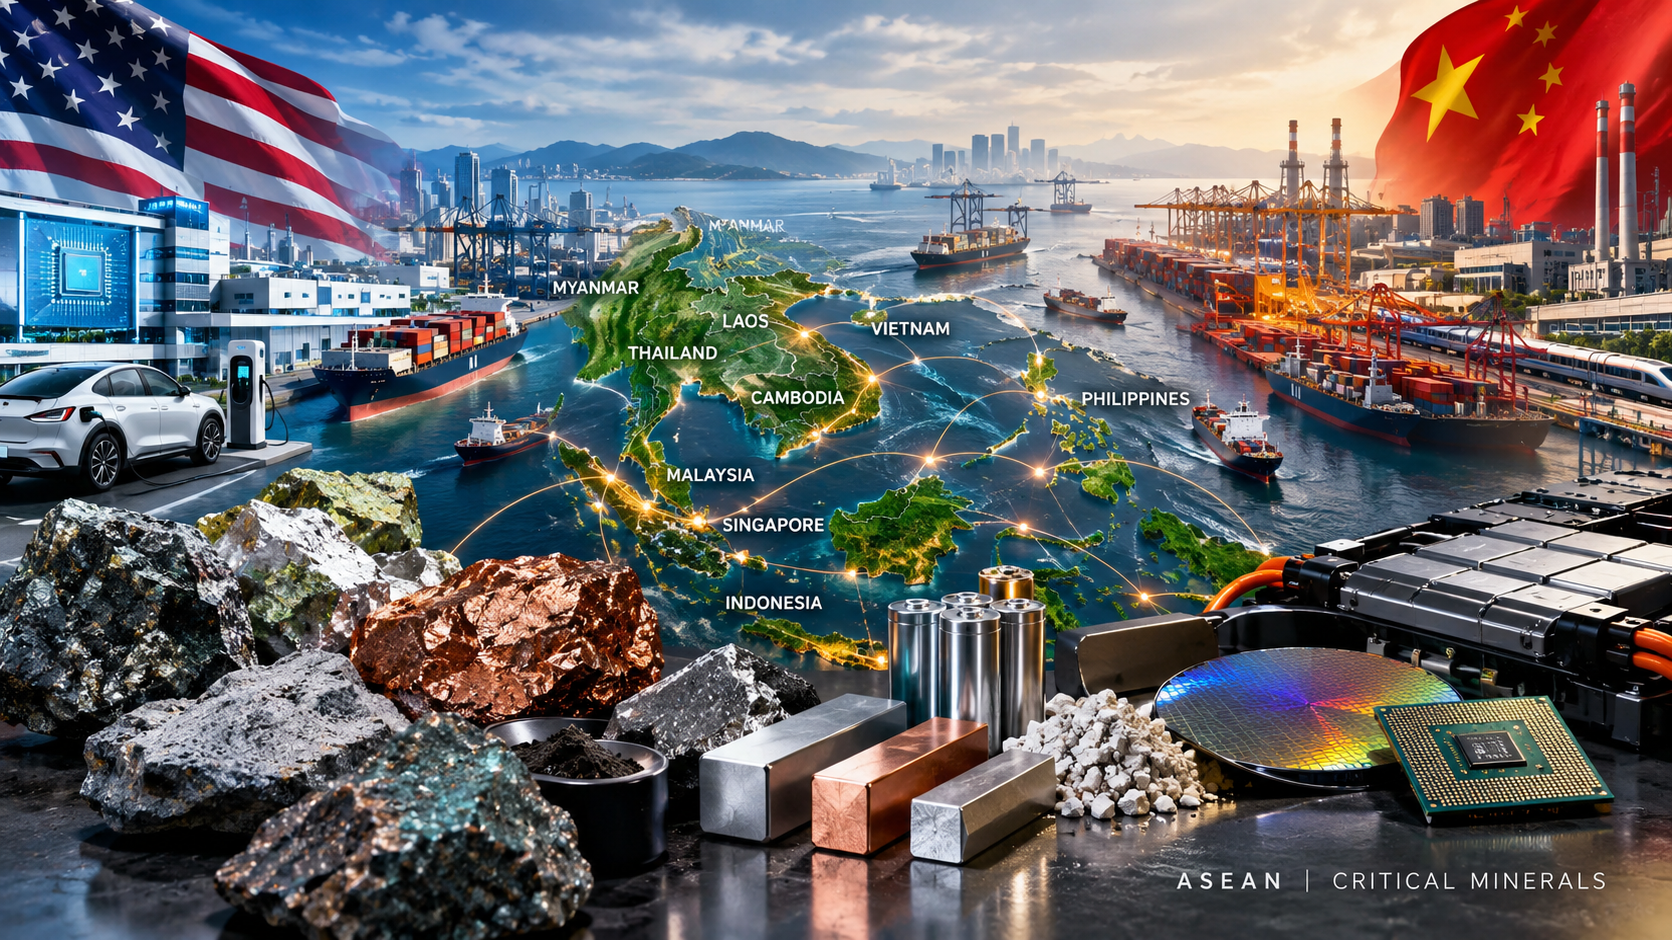
Southeast Asia is becoming one of the most important battlegrounds in the global critical-minerals economy. But the region’s biggest opportunity may not be choosing between Washington and Beijing—it may be using competition between the two to build more valuable industries at home.
The global race for critical minerals is entering a new phase.
Rare earth elements, nickel, graphite, cobalt, copper and other strategic materials are no longer simply commodities extracted from the ground. They are essential inputs for electric vehicles, batteries, semiconductors, renewable-energy systems, advanced electronics, artificial intelligence infrastructure, aerospace and defence.
That transformation has made mineral supply chains a central issue in economic and national security policy.
China remains deeply embedded in global processing and manufacturing networks, while the United States and its partners are investing heavily in alternative supply chains. For Southeast Asia, this competition creates both geopolitical pressure and an unusual economic opportunity.
Rather than viewing the US-China contest as a forced choice, ASEAN economies can potentially use it to attract capital, technology, processing expertise and manufacturing investment from multiple partners.
The critical question is no longer simply who controls Southeast Asia’s minerals?
It is increasingly:
Who helps Southeast Asia capture the greatest share of the value created from those minerals?
Why Critical Minerals Matter More Than Ever
The strategic importance of critical minerals is being driven by several simultaneous technological trends.
Electric vehicles require large quantities of battery materials and other minerals. Renewable-energy systems depend on metals used in grids, generators, batteries and permanent magnets. Semiconductor and advanced-electronics manufacturing requires materials including gallium, germanium, silicon, indium and rare earth elements.
The International Energy Agency’s Global Critical Minerals Outlook 2026 says demand for several important minerals is expected to continue expanding strongly toward 2040. Demand for nickel, graphite and rare earths is projected to grow substantially, while copper is expected to experience particularly large absolute demand growth because of its role in electricity networks.
The IEA also warns that the concentration problem has not disappeared.
In 2025, the average share of the largest refining country across key energy minerals reached approximately 70%, up from 68% in 2020. Indonesia has become dominant in nickel refining, while China remains the leading refiner for many other critical materials.
That concentration gives Southeast Asia an increasingly important role because the region contains both mineral resources and growing manufacturing capabilities.
Southeast Asia Is Not a Single-Mineral Story
One of the weaknesses of simplistic critical-minerals discussions is treating Southeast Asia as if it were dependent on one commodity.
It is not.
Different countries occupy different positions across the mineral value chain.
Indonesia: The Nickel Giant
Indonesia is the region’s most consequential critical-minerals player because of its enormous nickel industry.
According to the IEA’s Southeast Asia Energy Outlook 2026, Indonesia accounted for approximately 63% of global mined nickel production.
Nickel is particularly important for stainless steel and certain lithium-ion battery chemistries.
But Indonesia’s strategy goes beyond simply exporting ore.
The country has pursued downstream industrialisation policies designed to encourage domestic processing and attract investment in smelting, refining and battery-related manufacturing.
This changes the economics dramatically.
Exporting raw ore captures one layer of the value chain.
Mining, processing, refining, producing battery materials and eventually manufacturing components or finished products can capture substantially more.
Indonesia therefore represents an important test case for whether mineral-rich developing economies can convert geological advantages into industrial capabilities.
Malaysia: A Rare-Earth Processing Hub
Malaysia occupies a different position.
Its importance comes particularly from rare-earth processing.
The IEA’s 2026 critical-minerals assessment identifies Malaysia as one of the countries contributing to diversification in rare-earth refining.
The agency notes that increases in Malaysian production, together with new projects in the United States, helped reduce rare-earth refining concentration between 2023 and 2025.
This is strategically important because diversification is not simply about discovering another mine.
The bigger bottleneck is often what happens after mining.
Ore must be separated, refined and converted into materials suitable for industrial applications.
The difference between a mining economy and an advanced mineral-processing economy can therefore be enormous.
Malaysia’s experience demonstrates why Southeast Asian countries can potentially become important not only as resource suppliers but also as processing locations.
Myanmar and the Rare-Earth Supply Chain
Myanmar also occupies an important position in the regional rare-earth ecosystem.
The IEA’s Southeast Asia Energy Outlook 2026 estimates that Myanmar accounted for just under 20% of global mined rare-earth supply and more than 40% of heavy rare-earth elements.
That makes the country strategically significant despite the region’s broader diversification ambitions.
The supply chain, however, is complex.
A mineral can be mined in one country, transported to another for processing and ultimately incorporated into components manufactured somewhere else.
This interconnected structure means that no single country necessarily controls the entire value chain.
That is precisely where Southeast Asia’s leverage can emerge.
The Philippines and the Nickel Opportunity
The Philippines is another major player in regional nickel supply.
The country already occupies an important position in the global nickel market, while its geographic location places it close to major Asian manufacturing economies.
The strategic challenge is determining how much value remains inside the country.
If a resource-rich country exports primarily unprocessed material, much of the economic value is generated elsewhere.
If it develops refining, precursor materials, battery components and manufacturing capabilities, more of the economic activity can potentially remain domestically.
That is the broader lesson emerging across Southeast Asia.
China Still Has Enormous Supply-Chain Advantages
Any analysis of Southeast Asia’s options must acknowledge the scale of China’s existing position.
According to the U.S. Geological Survey’s 2026 China minerals profile, China accounted for approximately 71% of global mined rare-earth production in 2024.
The USGS also reports that China accounted for around 87% of rare-earth processing.
Those figures illustrate why replacing China’s role cannot happen simply by opening new mines.
Processing technology, equipment, technical expertise, logistics, financing and downstream manufacturing all matter.
The IEA’s Global Critical Minerals Outlook 2026 makes this distinction particularly important: announced mining projects outside dominant producers are growing, but refining and downstream manufacturing capacity remains much more constrained.
In other words:
The world may be able to diversify mines faster than it can diversify processing.
That creates an opportunity for Southeast Asia.
The US Is Trying to Build Alternative Supply Chains
Washington’s interest in Southeast Asia is not limited to obtaining raw materials.
The broader objective is supply-chain resilience.
The United States and its partners have been attempting to develop alternative sources for rare earths, battery materials and other strategic minerals.
The CSIS analysis of rare-earth export restrictions describes the substantial disruption created by China’s 2025 rare-earth restrictions and the subsequent US effort to develop alternative supply chains.
This competition gives Southeast Asian governments more bargaining space.
If Washington wants diversified mineral supplies while Beijing wants continued access to regional resources and manufacturing networks, Southeast Asian governments have an incentive to negotiate around investment, technology transfer, infrastructure and local value creation.
The strategic opportunity therefore extends beyond mining rights.
ASEAN’s Bigger Opportunity: Move Up the Value Chain
ASEAN itself has recognised the importance of developing mineral industries beyond extraction.
The ASEAN Minerals Cooperation Action Plan 2026–2030 explicitly identifies sustainable development of extractive industries and expanded upstream-to-downstream minerals and metals cooperation as regional priorities.
That is significant.
The next stage of Southeast Asia’s mineral strategy could involve building connected regional capabilities:
Mining → Processing → Refining → Components → Manufacturing → Recycling
Instead of every country attempting to build an entire supply chain independently, ASEAN economies could specialise in different stages.
Indonesia, for example, has enormous nickel capabilities.
Malaysia has experience in rare-earth processing and advanced manufacturing.
The Philippines has substantial nickel resources.
Vietnam possesses important rare-earth resources and manufacturing capabilities.
Singapore contributes finance, logistics, services and regional headquarters capabilities.
Thailand has developed automotive manufacturing infrastructure.
This creates the possibility of a regional ecosystem rather than isolated national projects.
The Real US-China Competition Is About Industrial Capacity
The US-China contest is often presented as a geopolitical struggle over who gets access to minerals.
But the deeper competition is about industrial capacity.
A mine alone does not produce an electric vehicle.
A rare-earth deposit alone does not produce a permanent magnet.
Nickel ore alone does not produce a battery.
The value is created through a chain of technological and industrial processes.
That is why the IEA warns that mining projects outside dominant suppliers are advancing faster than refining and downstream manufacturing.
For Southeast Asia, this is perhaps the most important strategic lesson.
Owning the resource is only the beginning.
Owning the processing technology, engineering expertise, manufacturing infrastructure and intellectual property can be considerably more important.
Why Southeast Asia Should Avoid Excessive Dependence on Any Single Partner
Diversification is not necessarily about replacing Chinese investment with American investment.
Nor is it about rejecting Chinese participation.
A more resilient model could involve multiple investment and technology partners.
China can contribute substantial manufacturing capabilities, supply-chain expertise and capital.
The United States can provide technology, financing, market access and strategic partnerships.
Japan and South Korea are already deeply integrated into Asian manufacturing networks.
Australia is a major resource supplier and has growing interest in regional critical-minerals cooperation.
Europe also has an interest in diversifying mineral supply chains.
For Southeast Asian governments, the economic objective can therefore be to encourage competition among potential partners rather than lock the region into a single dependency.
The Environmental Problem Cannot Be Ignored
There is, however, another side to the critical-minerals boom.
Mining and refining can create substantial environmental pressures.
Nickel processing, rare-earth separation and other mineral-intensive industries can require large amounts of energy and water while generating waste and emissions.
The long-term competitiveness of Southeast Asian mineral projects will therefore depend partly on environmental standards.
This is particularly important because major buyers increasingly care about the carbon footprint and traceability of industrial materials.
A country that can provide responsibly produced minerals with reliable environmental certification may eventually have an advantage over a low-cost producer with weak standards.
The region’s industrial strategy therefore has to balance three objectives:
Resource security.
Economic value creation.
Environmental sustainability.
Recycling Could Become Southeast Asia’s Next Strategic Advantage
Mining is not the only route to supply security.
Recycling could eventually reduce dependence on newly extracted minerals.
The IEA estimates that secondary supply could make an increasingly important contribution to mineral markets through 2040.
Battery recycling, magnet recycling and recovery of strategic metals from industrial waste could become increasingly important as the installed base of electric vehicles, batteries, electronics and renewable-energy equipment grows.
Southeast Asia’s expanding manufacturing base could give the region an opportunity to develop recycling industries alongside new mineral-processing projects.
That would create a more circular industrial model.
Instead of:
Mine → export → import finished product
the model could become:
Mine → process → manufacture → use → recycle → reuse
Such a system would potentially strengthen regional supply security while reducing pressure on new extraction.
What Could Southeast Asia Gain?
If Southeast Asian countries successfully move up the critical-minerals value chain, the economic impact could extend far beyond mining revenues.
Potential gains include:
- Higher-value manufacturing
- Skilled industrial employment
- Technology transfer
- Battery and EV production
- Semiconductor-related manufacturing
- Export diversification
- Greater foreign direct investment
- New logistics and infrastructure demand
- Growth in engineering and technical services
- Development of recycling industries
- Greater bargaining power with major economies
The objective should therefore not be to maximise mineral exports.
It should be to maximise the economic value generated per tonne of mineral resource.
The Biggest Risk: Becoming a New Raw-Material Dependency
There is an important paradox.
Southeast Asia could reduce dependence on China’s mineral supply chains while simultaneously becoming overly dependent on foreign companies for extracting its own resources.
That would solve one supply-chain problem while creating another.
A sustainable strategy requires local capabilities.
Governments therefore have an incentive to negotiate investment agreements that encourage:
- Local processing
- Workforce development
- Technology transfer
- Domestic supplier networks
- Research and development
- Environmental monitoring
- Transparent contracts
- Infrastructure investment
- Local manufacturing
The objective is not to prevent foreign participation.
It is to ensure that foreign capital helps create domestic industrial capacity.
Can ASEAN Turn Geopolitical Competition Into Economic Leverage?
The answer depends heavily on execution.
A 2026 analysis from the National University of Singapore’s Lee Kuan Yew School of Public Policy highlights Southeast Asia’s growing importance in critical minerals while examining the challenge of maintaining strategic autonomy amid intensifying US-China competition.
That strategic autonomy does not necessarily mean neutrality in every dispute.
Instead, it can mean preserving the ability to make economic decisions based on national and regional interests.
For ASEAN, that could translate into welcoming investment from multiple countries while avoiding excessive concentration in any single supply chain.
The Next Battle Will Be Over Processing, Not Just Mining
The global critical-minerals race is entering a new stage.
The first phase was about finding and extracting resources.
The second phase is about processing.
The third will increasingly involve advanced materials, components, manufacturing and recycling.
This distinction is crucial for Southeast Asia.
The region already possesses many of the raw ingredients required for a major role in the global mineral economy.
Indonesia has extraordinary nickel production.
Malaysia is strengthening its rare-earth processing position.
The Philippines remains an important nickel supplier.
Myanmar occupies a significant position in heavy rare earths.
Vietnam has substantial rare-earth potential.
Meanwhile, ASEAN’s manufacturing infrastructure connects the region to some of the world’s most important electronics, automotive and technology supply chains.
The question is whether those advantages can be integrated into a higher-value regional industrial strategy.
Southeast Asia’s Strategic Choice Is Bigger Than US vs China
The US-China critical-minerals competition is unlikely to disappear.
If anything, critical minerals are becoming more closely linked to technology policy, national security, industrial policy and the energy transition.
But Southeast Asian economies do not necessarily need to treat the competition as a binary choice.
Their greater opportunity may lie in diversification.
China’s enormous processing and manufacturing capabilities are difficult to replace quickly.
The United States and its partners are investing in alternative supply chains.
Japan, South Korea, Australia and Europe also have strong incentives to secure reliable mineral supplies.
That creates multiple potential sources of capital, technology and market access.
The strategic opportunity for ASEAN is therefore to ask a different question:
What can each partner contribute to Southeast Asia’s transition from mineral supplier to advanced industrial producer?
The answer could determine whether the region merely participates in the next critical-minerals boom—or becomes one of its major beneficiaries.
Bottom Line
Southeast Asia’s critical-minerals advantage is not simply the amount of nickel, rare earths or other resources beneath its soil.
Its real advantage is the combination of resources, manufacturing, logistics, growing energy demand, strategic geography and access to multiple global investment partners.
China’s dominance of processing gives Beijing significant influence, while US-led diversification creates additional demand for alternative supply chains.
For ASEAN economies, the opportunity is to use that competition to build processing capacity, attract technology, develop skilled workforces and establish downstream manufacturing.
The ultimate prize is not becoming the world’s cheapest source of minerals.
It is becoming a region that captures a much larger share of the value created from them.
In the emerging global critical-minerals economy, the countries that control the highest-value stages of the supply chain—not necessarily those that simply extract the most ore—are likely to have the greatest economic leverage.
Sources and Further Reading
- International Energy Agency — Global Critical Minerals Outlook 2026
- International Energy Agency — Global Critical Minerals Outlook 2026: Market Overview
- International Energy Agency — Southeast Asia Energy Outlook 2026
- International Energy Agency — Rare Earth Elements
- U.S. Geological Survey — China Mineral Industry Profile
- ASEAN — Minerals Cooperation Action Plan 2026–2030
- CSIS — Rare Earth Export Restrictions One Year Later
- National University of Singapore — Southeast Asia and Critical Minerals
- FULCRUM — Southeast Asia’s Room for Manoeuvre in Critical Minerals
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Malaysia is quietly running one of the more consequential balancing acts in global industrial policy: negotiating rare earth technology, investment and offtake terms with Washington, Tokyo, Seoul, Canberra, Paris and Beijing at the same time, according to Rare Earth Exchanges. The country is betting that its combination of geology, existing separation capacity and a firm export-ban policy can convert it from a mining afterthought into the leading non-Chinese node in the rare earth supply chain — without becoming exclusively dependent on any single partner.
The Asset at the Center of It
The Lynas Advanced Materials Plant (LAMP) in Kuantan, Pahang, is the largest rare earth separation facility outside China, and in early 2026 it became strategically load-bearing: the US Department of Defense signed a preliminary $96 million supply agreement with Lynas, according to industry tracker Rare-Earth-Mining.com. Malaysia’s broader reserve base is estimated at 16.1 to 18.2 million tonnes of non-radioactive rare earth elements, and Kuala Lumpur is targeting $3 billion in direct rare earth revenue by 2030 under its National Industry Plan — a target expected to draw roughly MYR 100 billion (about $25 billion) in new investment, per analysis from Lundgreen’s Investor Insights.
Lynas itself is expanding aggressively: expansion costs at its Malaysia operations have risen to roughly A$294 million as of 2026, reflecting the underlying difficulty of the chemistry involved — rare earth separation requires hundreds of sequential solvent-extraction stages, each demanding precise control, according to Discovery Alert’s capital-markets coverage. The company is also partnering with South Korea’s JS Link on a MYR 600 million magnet manufacturing facility in Pahang, per Lundgreen’s reporting — a move toward the downstream metals-and-magnets capability that separation alone doesn’t provide.
The Policy Lever: No Raw Exports
Malaysia’s core negotiating leverage is a standing ban on exporting unprocessed rare earth elements. Investment, Trade and Industry Minister Tengku Zafrul Abdul Aziz has reaffirmed the policy even amid a new minerals cooperation framework with the US, insisting the goal is local value creation rather than serving as a raw-material feeder to outside industries, according to Quest Metals. That stance forces every foreign partner — including Washington — to invest in Malaysian processing capacity if they want access to Malaysian rare earth output at all.
It’s a policy with real friction attached, however. A separation plant without downstream metals, alloys and magnet capability remains, in the framing used by Rare Earth Exchanges, only a partial victory — true technological sovereignty requires domestic engineers able to operate, modify and replicate the processes independently, not merely receive transferred technology.
The Timeline Problem
Malaysia’s own mining moratorium complicates the picture. According to The Edge Malaysia, a phased environmental and socio-economic study covering pre-mining (2024–25), mining (2026–27) and post-mining (2028–29) periods means no new mining will occur in permanent forest reserves until at least 2029 — even as midstream processing facilities are expected to reach full operation only around 2027–2030. That leaves a multi-year window in which Malaysia’s upstream supply and downstream capacity are both still ramping, even as geopolitical demand for a non-Chinese alternative is immediate.
A comprehensive sourcing guide from Malaysia4u frames the licensing history as instructive: Lynas’s operating permit has been threatened, extended, renegotiated and finally extended again for ten more years as of 2026 — evidence, the guide argues, that rare earth licenses in Malaysia function as politically negotiated assets rather than fixed regulatory clearances. Any investor or policymaker treating Kuantan as a settled, low-risk supply node is missing that history.
Why This Is a Six-Country Story, Not a US-China One
Most coverage frames rare earths as a binary US-versus-China contest. Malaysia’s actual position is multipolar: it holds observer status in the US-led Minerals Security Partnership, supplies Japan’s JOGMEC programs (Japan is Lynas Kuantan’s largest single customer), and has been recognized by the EU’s Critical Raw Materials Act as a strategic third-country partner — while continuing quiet engagement with Beijing, which still dominates roughly 70% of global rare earth production. That simultaneous multi-power courtship, more than any single supply deal, is what makes Kuantan the most contested industrial site in Southeast Asia in 2026.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
BRUSSELS — The European Union is establishing a dedicated crisis task force to prepare for a possible escalation in tensions with China over rare earth exports, reflecting growing concern that renewed restrictions on critical minerals could disrupt Europe’s manufacturing, technology, and defense industries if current trade arrangements expire later this year.
The move highlights Brussels’ increasing focus on economic security as geopolitical tensions reshape global supply chains. Rare earth elements, while produced in relatively small quantities, are indispensable for electric vehicles, wind turbines, semiconductors, military equipment, smartphones, and advanced industrial machinery.
Europe Braces for Supply Disruptions
According to reports, the European Commission is assembling an emergency group comprising senior officials from multiple departments to anticipate and coordinate responses to strategic supply chain shocks.
Officials are particularly concerned that China could tighten export controls on rare earth materials once the existing temporary understanding on exports reaches its expected expiry later this year. The task force would monitor market conditions, identify vulnerabilities, coordinate with member states, and develop contingency plans for industries most exposed to supply disruptions.
The initiative forms part of the European Commission’s broader strategy of strengthening the bloc’s economic resilience amid an increasingly uncertain geopolitical environment, according to reporting by the Financial Times. (Financial Times)
China’s Dominance Gives Beijing Significant Leverage
China occupies an exceptionally strong position in the global rare earth industry.
Industry estimates indicate that China accounts for roughly two-thirds of global rare earth mining while controlling nearly 90% of worldwide refining capacity. This means that even minerals extracted elsewhere often depend on Chinese processing before entering global manufacturing supply chains. (Reuters)
That concentration has become an increasingly important geopolitical issue after Beijing introduced export controls on several strategic minerals in recent years, demonstrating its ability to influence global supply chains during periods of heightened trade tensions.
Industries Most at Risk
A prolonged disruption could affect numerous European industries, including:
- Automotive manufacturing
- Electric vehicle production
- Aerospace
- Defense equipment
- Renewable energy technologies
- Consumer electronics
- Semiconductor manufacturing
European manufacturers rely heavily on a stable supply of permanent magnets and other components produced using rare earth elements.
Even temporary shortages could increase production costs, delay manufacturing schedules, and slow investment in Europe’s green energy transition.
Crisis Team Expected to Coordinate Emergency Response
The proposed task force is expected to serve as a rapid-response mechanism rather than a permanent regulatory body.
Among its anticipated responsibilities are:
- Monitoring critical mineral markets.
- Identifying alternative international suppliers.
- Coordinating emergency responses across EU institutions.
- Assessing industrial vulnerabilities.
- Exploring financial support mechanisms for affected sectors.
- Strengthening strategic stockpile planning.
Officials have also discussed the possibility of deploying European funding instruments to help maintain supplies should significant disruptions occur. (Financial Times)
Broader Strategy to Reduce Dependence
The crisis team is only one element of a wider European strategy aimed at reducing excessive dependence on a single supplier for strategically important materials.
European Commission President Ursula von der Leyen has repeatedly argued that Europe must “de-risk” rather than completely decouple from China by diversifying supply chains while maintaining commercial engagement.
Earlier proposals include legislation encouraging companies to diversify suppliers, increased recycling of rare earth magnets, and investment in alternative mining and refining projects both within Europe and among trusted international partners. (Reuters)
Trade Frictions Continue to Build
The rare earth issue comes amid broader economic tensions between Brussels and Beijing.
EU officials have expressed growing concern over persistent trade imbalances, industrial subsidies, market access restrictions, and the increasing use of export controls on strategic materials.
European Trade Commissioner Maroš Šefčovič has warned that without meaningful progress in addressing structural trade concerns, Brussels may pursue additional defensive trade measures.
At the same time, European leaders continue to emphasize dialogue with China, seeking to balance economic cooperation with greater strategic autonomy.
Diversification Will Take Years
While Europe is accelerating efforts to develop alternative supply chains, analysts caution that reducing dependence on China will not happen quickly.
Building new mines, refining facilities, processing plants, and downstream manufacturing capacity requires substantial investment, environmental approvals, and years of development.
Experts argue that diversification rather than complete replacement is the more realistic objective, as China’s established infrastructure and processing expertise remain difficult to replicate in the short term. (Financial Times)
Outlook
The creation of a European crisis task force underscores how critical minerals have become central to global economic and geopolitical competition.
As governments race to secure reliable access to strategic resources, rare earth supply chains are emerging alongside energy security and semiconductor production as key pillars of national economic resilience.
Whether the EU ultimately faces renewed export restrictions or reaches a longer-term understanding with Beijing, policymakers appear determined to ensure that Europe is better prepared for future disruptions than it has been during previous supply chain crises.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
US shipments of yttrium — a rare earth element critical to advanced semiconductor manufacturing — have collapsed roughly 95%, from 333 tons to just 17 tons, in the eight months following Beijing’s April 2025 export controls. China controls approximately 90% of global rare earth processing capacity, and industry executives now warn of potential production halts before the end of 2026 if the bottleneck isn’t resolved.
The Scale of the Chokepoint
China’s dominance isn’t primarily about mining rare earths — it’s about processing them into usable industrial form, a capability the country has spent decades building and that has no scalable near-term substitute elsewhere. Beijing’s October 9, 2025 export control expansion put yttrium, scandium, dysprosium, terbium and other elements under an opaque licensing regime that determines who receives shipments and when (TFTC).
The May 2026 US-China trade truce produced only a vague commitment to “address concerns” about rare earth shortages, with no binding timeline, no removal of specific controls, and no verification mechanism — leaving the underlying bottleneck largely unresolved months later (TFTC).
Why Yttrium and Scandium Specifically Matter
These are not obscure materials to the AI hardware story — they are load-bearing:
- Photonic chips rely on indium phosphide as a substrate material with no currently scalable commercial substitute, and one manufacturer holds roughly 40% of the global market for indium phosphide optical components (Discovery Alert).
- Scandium has become increasingly important in certain deposition processes used in leading-edge semiconductor fabrication, and shortages have already created measurable impacts on chip manufacturing yield (Discovery Alert).
- If a pending “Wave 2” suspension of controls expires without renewal, five additional rare earth elements would return to full restriction simultaneously — a compounding shock for industries that haven’t yet secured alternative sources, leaving manufacturers with a planning horizon of less than six months, according to critical minerals analysis (Discovery Alert).
A Sophisticated Form of Leverage
The October 2025 expansion marked what analysts describe as a qualitative shift: by extending restrictions to cover not just the raw materials but processing equipment, technical documentation, and accumulated operational refining knowledge, Beijing effectively weaponized decades of processing expertise as a strategic asset — targeting capabilities rather than simply commodities (Discovery Alert).
China escalated the response further in June 2026, blocking dual-use exports to ten US companies, including two rare earth producers whose output feeds directly into the US semiconductor and AI hardware production chain (Cryptopolitan). Researchers at the Center for Strategic and International Studies have warned that the pattern risks triggering “an export control and economic statecraft arms race” that could undermine global security and economic prosperity (Cryptopolitan).
The Market Is Already Repricing This
Domestic Chinese markets have responded aggressively: since the start of 2026, rare earth concept stocks on China’s A-share market have surged, with Grinm Advanced Materials up 200% and Oulai New Materials up as much as 350%, reflecting a market-led revaluation of who captures profit across the global semiconductor supply chain (BigGo Finance). The report notes that the combined annual net profit of 177 A-share semiconductor companies has historically been less than one-twentieth of a single US chipmaker’s profits — a gap Beijing’s rare earth leverage is explicitly aimed at closing.
The US Regulatory Backdrop
Washington’s own January 2026 export control rule tightened restrictions on advanced AI chips destined for China, introducing new total processing power thresholds and shifting licensing for chips like Nvidia’s H200 and AMD’s MI325X from presumptive denial to case-by-case review, subject to a 25% tariff, a 50% volume cap relative to domestic shipments, and mandatory US-based third-party testing (Informed Clearly). China’s rare earth controls function as the direct retaliatory counterpart to this regime.
Key Takeaways
- US yttrium shipments from China fell roughly 95% following Beijing’s April 2025 export controls, with prices up about 60% since.
- China controls approximately 90% of global rare earth processing capacity, giving it leverage that goes well beyond raw material supply.
- A pending expiration of “Wave 2” control suspensions could add five more restricted elements simultaneously, with manufacturers facing under six months of planning certainty.
- Chinese domestic rare earth stocks have surged as markets price in a structural shift in global semiconductor supply chain economics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Battle for the Farm Belt: How Tariff Pressures and Fuel Costs Are Reshaping Iowa’s 2026 Midterms

Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN

Bank Jago’s Wealth Management Push:Indonesia’s 31.1 Million Investors boom

Beyond the Four-Year Degree: The $100K+ Trade Careers Young Americans Are Overlooking

SpaceX Starship Achieves First Full Orbit on Historic 10-Hour Test Flight 14

Google’s $15B Finland AI Investment: Data Centers, Nuclear Power & Jobs

Fast Invoice Factoring: Rates, APR Math & Contract Traps

SOC 2 Type II Guide: Cost, Timeline & Compliance Companies

Hong Kong Wages Surge 3.4% in June: Sector Data & Analysis

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Gavin Baker AI Outlook: Why the Compute Shortage Persists Through 2028
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025