
Analysis
Oil Surges Past $125 as the Strait of Hormuz Blockade Enters Uncharted Territory

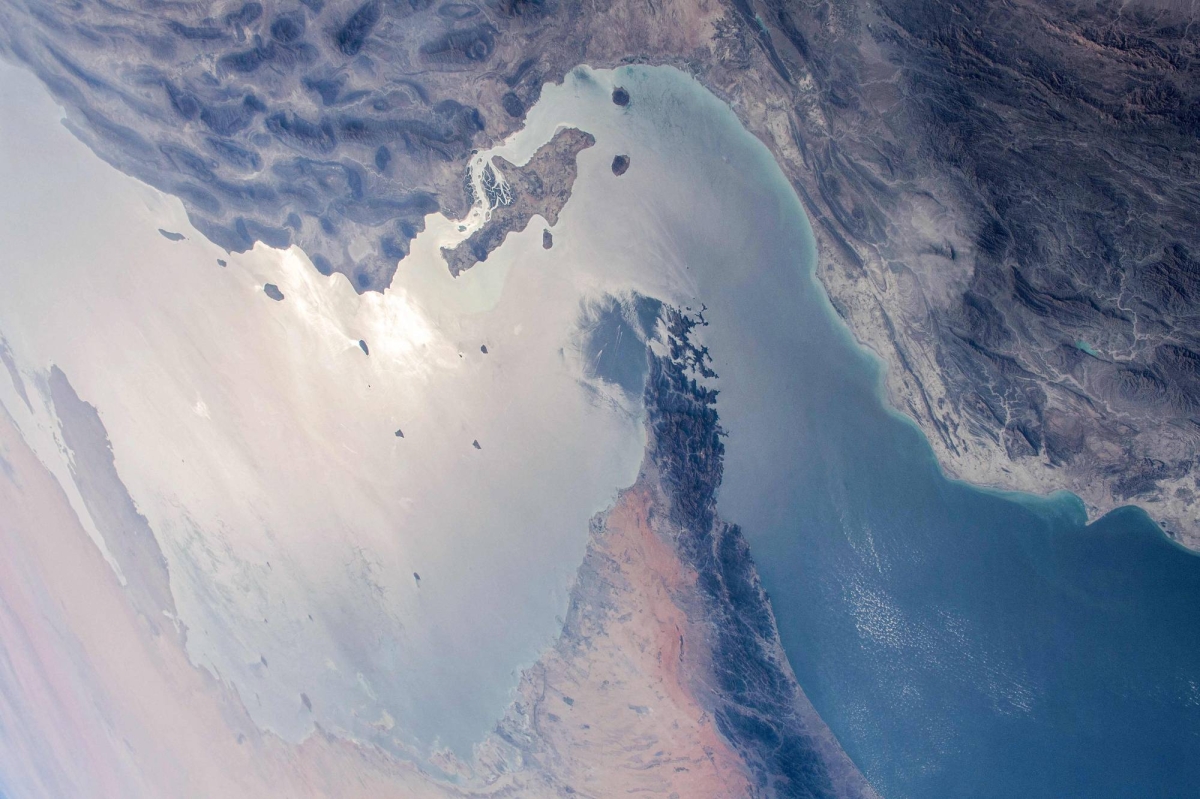
Brent crude hits a new conflict high as the world’s most critical energy chokepoint remains locked — and the real crisis has barely begun.
Brent crude has surged past $125 as the Strait of Hormuz blockade continues into its third week. Analysts warn of stagflationary shockwaves, supply disruption not seen since the 1970s, and a structural reshaping of global energy alliances. Here is what it means — and what comes next.
When historians eventually write the definitive account of the 2026 energy crisis, they will likely describe two distinct moments: the day the Strait of Hormuz effectively closed, and the day markets finally understood what that meant. As of April 30, Brent crude has surged past $125 per barrel — briefly touching $129 in intraday trading — rising more than 6% in a single session, its sharpest single-day move since Russia’s invasion of Ukraine in February 2022. WTI crude has tracked close behind, crossing $121 for the first time since the post-pandemic recovery cycle.
This is not a price spike. It is a structural rupture.
The dual blockade — Iranian-imposed restrictions on shipping lanes combined with a US naval cordon around Iranian export terminals — has effectively severed approximately 20% of global seaborne oil flows and a significant share of the world’s liquefied natural gas trade from the Persian Gulf. According to the Energy Information Administration, roughly 21 million barrels per day transited the Strait of Hormuz in 2024, making it by far the world’s most consequential energy chokepoint. With no credible diplomatic resolution in sight — and the Trump administration sending signals this week that the naval operation could be sustained for months — the question is no longer whether there will be economic pain. The question is how deep and how lasting.
The Anatomy of a Supply Shock: Why This Time Is Different
Energy markets have weathered crises before. The 1973 Arab oil embargo. The Iranian Revolution of 1979. The Gulf War. The post-Ukraine sanctions regime. Each produced a price surge, a period of demand destruction, and eventually a new equilibrium. But analysts at ING, who revised their 2026 Brent crude forecast sharply upward this week, argue this disruption is categorically different — not merely in scale but in structural character.
Previous supply shocks were largely unilateral: one actor restricting supply while global logistics adapted around them. What the Hormuz blockade has introduced is a bilateral chokepoint: Iran cannot export, but neither can Qatar’s LNG terminals operate at full capacity, neither can Abu Dhabi’s offshore production reach tankers freely, and neither can the dozens of supertankers now anchored in the Gulf of Oman receive clearance to proceed. The chokepoint is not a political statement. It is a physical lock.
Global oil inventories, already drawn down through 2025 by a combination of robust Asian demand and OPEC+’s disciplined production management, entered this crisis at their lowest seasonally-adjusted levels in over a decade. The International Energy Agency’s latest Oil Market Report underscores the alarming pace of inventory draws: OECD commercial crude stocks are declining at an annualized rate that, if sustained for two quarters, would represent a deficit not seen in the modern integrated oil market era.
The just-in-time architecture of global energy supply — designed for efficiency, not resilience — is now exposed as a systemic vulnerability. As Foreign Affairs recently argued, the era of treating energy logistics as a solved problem ended the moment a single maritime lane became a geopolitical weapon.
Stagflation’s Ghost Returns — and This Time It Has a Passport
The macroeconomic implications of a prolonged Hormuz disruption extend well beyond the pump price. To understand the full cascade, consider the chain of dependencies that a $125-plus oil price severs or strains simultaneously.
Jet fuel, diesel, and heavy fuel oil costs feed directly into shipping rates, which feed into the price of virtually every traded good on earth. The Baltic Dry Index — a proxy for global freight costs — has risen 34% since the blockade began. Agricultural commodity markets are already pricing in higher fertilizer costs: natural gas, partially rerouted from Gulf LNG, is the primary feedstock for nitrogen fertilizers, and Bloomberg’s commodity desk has flagged early signs of price pressures in key food-exporting regions across South Asia and Sub-Saharan Africa.
Central banks, which spent three years fighting the post-COVID inflation surge, now face what some economists are calling a “second-generation supply shock”: an exogenous price impulse that threatens to re-anchor inflation expectations upward just as they had stabilized. The Federal Reserve, the European Central Bank, and the Bank of England all face an identical and deeply uncomfortable policy trilemma: raise rates to suppress inflation and risk recession; hold rates and watch real incomes erode; or cut rates to cushion economic activity and risk entrenching a new inflationary plateau.
This is stagflation’s logic — slow growth, rising prices — and it has happened before. The 1979 oil shock produced exactly this outcome. But in 1979, the global economy was not carrying $330 trillion in aggregate debt, and digital interconnectedness had not made supply chain disruption simultaneously instantaneous and globally visible. The feedback loops today are faster, more correlated, and harder to break.
Winners, Losers, and the Uncomfortable Geography of Crisis
Not every actor in the global energy system suffers equally. Some, in fact, stand to benefit — at least in the short term. A rigorous analysis of winners and losers reveals the profound geopolitical realignment that high oil prices accelerate.
United States shale producers are the most obvious beneficiaries. The Permian Basin and the broader unconventional oil complex can operate profitably at $70 per barrel; at $125, they are printing money. Production capacity, constrained in recent years by investor pressure to prioritize returns over growth, is likely to see a capital surge. The Financial Times has reported preliminary signs of accelerated rig deployment in West Texas and the Bakken. More importantly, the US now holds extraordinary diplomatic leverage: its ability to flood the market with additional barrels — or withhold them — gives Washington a strategic tool as powerful as any sanctions regime.
Norway, Canada, Brazil, and Guyana — major non-OPEC, non-Gulf producers — all benefit from elevated prices while facing none of the direct disruption. Petrobras and the Guyana consortium operating the Stabroek block are sitting on some of the most valuable unexploited barrels on earth at current prices.
Renewable energy investors face a complicated dynamic. On one hand, the structural case for energy independence has never been more viscerally obvious to policymakers and the public. On the other, the capital equipment required for the energy transition — steel for wind turbines, copper for grids, polysilicon for solar panels — is itself energy-intensive to produce and transport. A sustained high-oil-price environment raises the transition cost even as it raises the transition imperative. The Brookings Institution’s Energy Security Initiative argues that this paradox will ultimately resolve in favor of renewable acceleration — but the transition path may be more inflationary than optimists assumed.
Asia’s industrial economies are in the most precarious position. Japan, South Korea, Taiwan, and India are heavily import-dependent and have limited domestic energy alternatives. India in particular, which had carefully cultivated discounted Russian crude supplies post-Ukraine as a hedge, now finds that hedge partially neutralized: Russian ESPO blend oil, routed through Asian terminals, cannot fully compensate for the Gulf volume loss. China, which holds the world’s largest strategic petroleum reserve and has been quietly drawing it down since late March, is buying time — but not much of it.
OPEC+ as an institution faces an existential paradox. Saudi Arabia, the UAE, and Kuwait — all Gulf producers — have capacity that is technically available but logistically stranded. Riyadh can pump; it cannot ship. The cartel’s ability to act as the global oil market’s “central bank” — its defining strategic role since the 1970s — has been surgically removed by the geography of conflict. This is not a drill for OPEC+. It is a structural demotion.
The Hormuz Blockade and the Strategic Petroleum Reserve Question
Washington’s Strategic Petroleum Reserve, drawn to multi-decade lows during the 2022 energy crisis and only partially replenished since, stands as one of the few immediately available shock absorbers in the current environment. The Biden administration’s aggressive SPR drawdown — documented extensively by the EIA — left the US with roughly 370 million barrels entering 2026, against a statutory capacity of 714 million. A coordinated IEA member-state release could, in theory, provide three to four months of buffer before structural supply measures take effect.
The Trump administration has been deliberately ambiguous about SPR deployment, signaling this week that any release would be “conditional on diplomatic progress” — a formulation that serves both as a pressure tool on Tehran and as a bargaining chip with domestic shale producers who prefer high prices. This calculated ambiguity is sophisticated energy statecraft, but it carries a cost: every day of uncertainty extends the price spike and deepens the inflation impulse.
The Atlantic Council’s Global Energy Center has recommended a coordinated 60-day IEA release combined with accelerated US shale production incentives — a dual-track approach that would signal resolve without sacrificing the leverage high prices provide.
The Peace That Isn’t Coming — and What That Means for Markets
Diplomatic channels between Washington and Tehran have not merely stalled; they have structurally collapsed. The Wall Street Journal reported this week that back-channel negotiations, which had been quietly active since February, were suspended after Iran-aligned proxy forces struck a US naval vessel in the Gulf of Oman. Neither side now has a clear off-ramp that does not involve some form of public capitulation — an outcome domestic politics in both countries makes nearly impossible in the short term.
This geopolitical cul-de-sac is what separates the current crisis from previous Gulf disruptions. In 1990-91, the international coalition was broad and the strategic objective clear. Today, the conflict’s scope remains deliberately ambiguous, the US Congressional mandate is contested, and America’s Gulf allies — particularly Saudi Arabia — are engaged in private mediation attempts that Washington has neither endorsed nor fully rejected. The Reuters analysis of Gulf diplomatic triangulation suggests Riyadh is attempting to position itself as the essential intermediary — a role that would dramatically enhance Saudi strategic leverage regardless of outcome.
Markets, which initially priced the blockade as a 2-to-4 week disruption, are now recalibrating to a 3-to-6 month scenario. That recalibration is what drove the 6%-plus session on April 29 and the brief touch above $129. When Goldman Sachs and ING revise upward simultaneously — and both now have Brent targets at $140 in a “prolonged blockade” scenario — the market signal is unambiguous. This is not a spike. It is a repricing.
What Policymakers Must Do — and Quickly
The policy response to this crisis must operate on three simultaneous tracks, and it must be coordinated internationally in a way that no single administration has yet demonstrated the will to organize.
The immediate priority is supply-side credibility. A coordinated IEA strategic reserve release, properly scoped and communicated, should be announced within days — not weeks. The signal matters as much as the volume. Markets price expectations; a credible commitment to supply stabilization can moderate the price surge even before a single barrel reaches port.
The medium-term priority is logistical diversification. The Hormuz crisis has exposed the fatal concentration of global energy logistics through a single, militarily-contestable waterway. Emergency investment in the East-West pipeline capacity across Saudi Arabia, expansion of Oman’s port infrastructure, and accelerated development of alternative LNG export facilities in the US Gulf Coast and Australia should receive immediate government-backed financing. These are not speculative infrastructure projects. They are geopolitical insurance.
The long-term priority — and this requires a degree of political courage that has been conspicuously absent — is a serious, funded, and globally coordinated acceleration of the energy transition. Not as an ideological commitment, but as a security imperative. Every gigawatt of domestic renewable capacity that Europe, Asia, and the US builds is one less barrel of politically hostage-able imported crude. The Hormuz blockade has made the ROI calculation on energy transition unmistakably clear: the cheapest barrel of oil is the one you never need.
The $125 Question: Ceiling or Floor?
At current trajectory, with inventories drawing, OPEC+ production stranded, and peace talks suspended, the $125 level looks less like a ceiling than a floor. The path to $140 — and beyond — is more visible than the path back to $90.
The one wildcard that could change this calculus rapidly is a breakthrough: a ceasefire, a partial reopening of the Strait to neutral-flag shipping, or an emergency diplomatic agreement brokered through Riyadh or Muscat. But diplomatic breakthroughs, by definition, are rarely predictable — and betting on one requires more optimism than current evidence justifies.
What the energy crisis of 2026 has revealed, above all, is a profound structural truth that decades of relative energy abundance had allowed the world to ignore: the global economy’s circulatory system runs through 21 miles of Iranian-controlled water. That single fact — more than any market statistic, analyst forecast, or policy announcement — is what markets are now, finally and belatedly, pricing in full.
The era of cheap, abundant, frictionless energy was always partly an illusion sustained by geography, diplomacy, and luck. In the Strait of Hormuz, all three have failed simultaneously. The world that emerges from this crisis — its alliances, its energy architecture, its inflation regime — will look fundamentally different from the one that entered it.
For investors, policymakers, and citizens alike, the only serious question is whether the response will be proportionate to the moment. History suggests it rarely is — until the cost of failing to respond becomes impossible to ignore.
The meter is running.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Despite decades of bans and strict handling mandates, asbestos remains a silent killer across legacy manufacturing plants, shipyards, and modern green-energy infrastructure retrofits. In 2026, regulatory changes by the EPA and tightened occupational health standards have triggered a fresh wave of mesothelioma litigation. Manufacturers attempting to fast-track industrial transitions are encountering catastrophic oversight, exposing workers to legacy toxins and opening corporate parent companies to unprecedented liability.
Navigating a mesothelioma claim in 2026 requires understanding how modern industrial supply chains intersect with historical exposure. Trusts established decades ago are being audited under stricter transparency laws, altering payout ratios and accelerating fast-track settlements for terminally ill plaintiffs.
Modern Industrial Exposure Hotspots
Green Retrofitting and Renewable Energy Infrastructure
A primary source of 2026 asbestos exposure occurs during the decommissioning and retrofitting of older industrial facilities for renewable energy production. Workers insulating electrical grids, modernizing HVAC systems, or upgrading manufacturing floors frequently disturb encapsulated asbestos materials that were improperly documented or ignored during facility audits.
Automotive and Aerospace Supply Chains
With advanced manufacturing booming, workers handling specialized friction materials, gaskets, and heat shields face ongoing risks. Supply chain tracing has become more sophisticated, allowing legal teams to pinpoint exact corporate entities responsible for raw material distribution across multinational borders.
| Industry Sector | Primary Exposure Risk | Legal Venue / Trust | Avg. Claim Value Range |
| Green Energy Retrofit | Disturbed insulation, pipe lagging | Federal Tort / Manufacturer Trust | $1.2M – $3.5M |
| Shipbuilding & Marine | Boiler insulation, structural seals | Asbestos Bankruptcy Trusts | $800K – $2.4M |
| Automotive Manufacturing | Brake components, high-heat gaskets | Third-Party Product Liability | $600K – $1.8M |
Securing Maximum Compensation: Steps for Plaintiffs
Time is of the essence in mesothelioma cases. Plaintiffs and their families must act decisively to secure financial recovery before statutes of limitations expire.
Retain Specialized Counsel: Work exclusively with national mesothelioma law firms possessing deep historical databases of asbestos-containing products.
Audit Employment History: Document every job site, supervisor name, and equipment brand encountered throughout your career.
Expedite Medical Filings: Secure a formal pathological diagnosis quickly to qualify for expedited trust fund distribution and priority trial settings.
“Expert Insight: Modern asbestos litigation is no longer just about historical tracking; it is about holding modern corporations accountable for failing to conduct rigorous environmental safety audits before initiating industrial retrofits.”
By combining meticulous work history reconstruction with aggressive multi-trust filings, victims can secure substantial financial relief to cover specialized immunotherapy and family support.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash 2026? How the Trump $5,000 Dividend Impacts Global Inflation

Tax-to-GDP Ratio Explained: Global Benchmarks, Fiscal Sovereignty & 2026 Insights

Trade Deficit & Terms of Trade Explained: Global Impact, Real-World Examples, and 2026 Insights

Supply vs Demand Shocks Explained: Market Equilibrium, Inflation Risks & Policy Responses in 2026

Microeconomics vs. Macroeconomics Explained: Key Differences, Interdependence & Global Impact

Devaluation vs Depreciation: Clear Differences, Causes, and Economic Impact

Purchasing Power Parity (PPP) Explained: Global Rankings, Living Standards & Why Nominal Exchange Rates Mislead in 2026

Remittances 2026: Global Trends, Household Resilience & Economic Lifeline for Developing Nations

Stagflation Explained: Causes, Global Impact & 2026 Economic Outlook

Understanding Foreign Exchange Reserves: Key Purposes and Global Impact

The Business of Gaming and Tech: How Global Economies Are Driven by Digital Consumerism

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Anthony Scaramucci’s Crypto Prediction: Why MicroStrategy’s Move Is Bitcoin’s “iPhone Moment”

Best Dividend Stocks 2026: European & Asian Blue Chips

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

The Rocket That Won’t Quit: Inside SpaceX’s Falcon 9 Launch Machine

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Retail Earnings Week: What Home Depot, Target & Walmart Reveal

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Tween Back-to-School Trends 2026: What’s Driving the $85B Season
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025