
Banks
Alan Greenspan Dead at 100: The Rise, Reign, and his Complicated Legacy

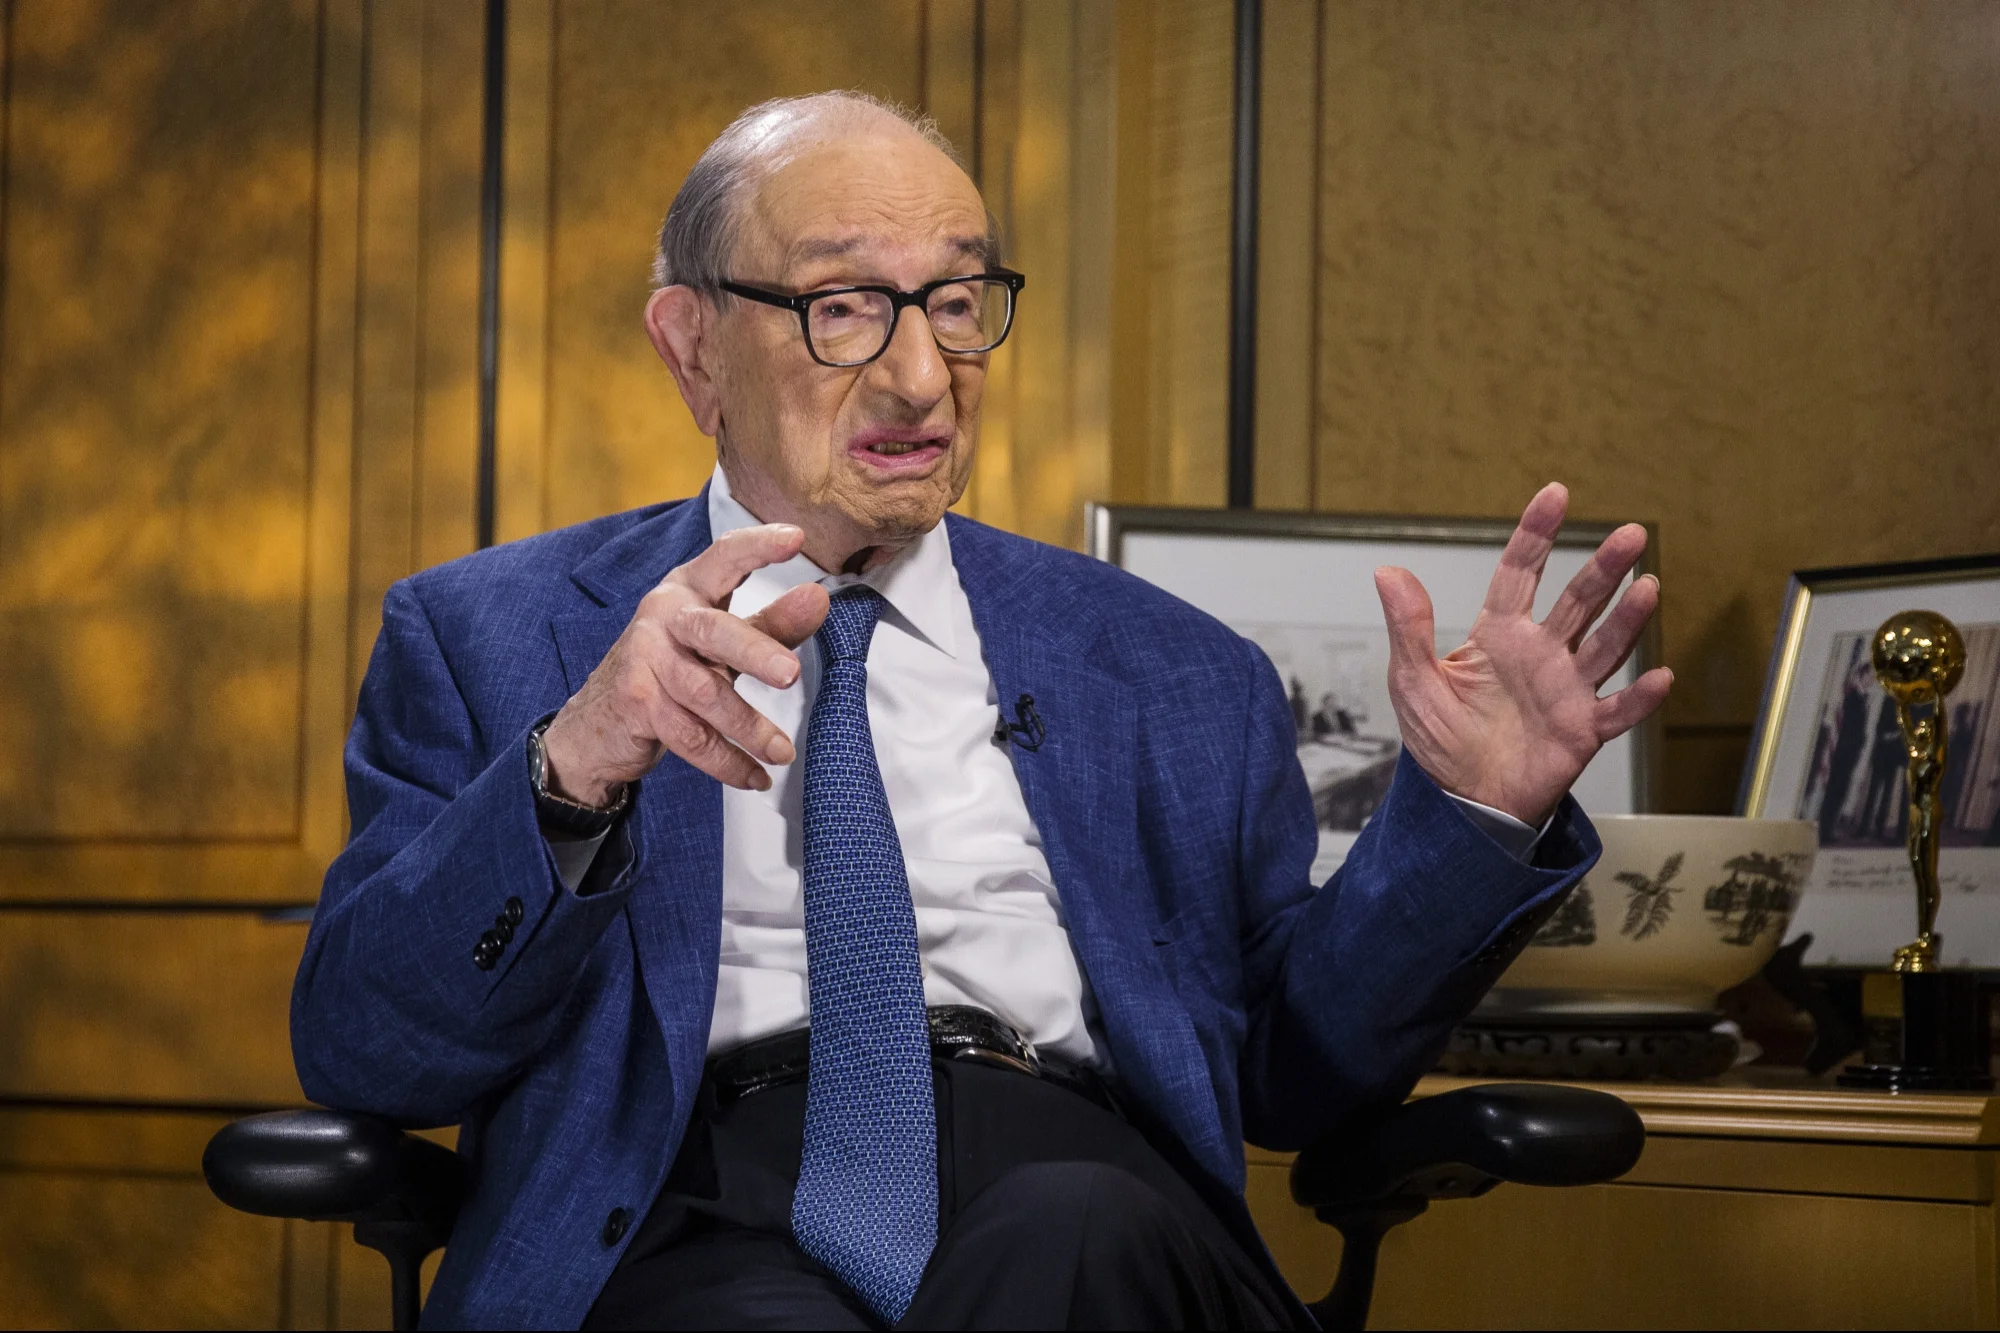
Alan Greenspan, the legendary Federal Reserve Chairman who steered the US economy for 19 years, died on June 22, 2026, at age 100. Here is the complete story of his legacy, from the “Great Moderation” to the 2008 financial crisis.
The Maestro Is Gone
The man who once moved global markets with a single phrase died quietly at his Washington home on June 22, 2026. Alan Greenspan, the 13th Chairman of the Federal Reserve who served under four US presidents, passed away at the age of 100 from complications of Parkinson’s disease. His wife of 29 years, NBC News correspondent Andrea Mitchell, announced the news in a statement that rippled across financial markets and economic circles worldwide.
The tributes poured in immediately. The Federal Reserve said it noted Greenspan’s passing with “deep sadness” and credited his “contributions to monetary policy and economic thought” for leaving “a lasting mark on this institution, on the broader field of economics, and on the country.” Ben Bernanke, who succeeded Greenspan and guided the Fed through the worst financial crisis since the Great Depression, called him “a great central banker who helped lead his country through almost two decades of prosperity.”
Yet the story of Alan Greenspan is not a simple tale of triumph. It is one of the most fascinating and contested legacies in modern economic history — a story of extraordinary success shadowed by catastrophic failure.
From Juilliard Jazz to Fedspeak: A Peculiar Rise to Power
Few would have predicted that a jazz clarinetist from Washington Heights, New York City, would one day become the most powerful unelected official on earth. Born on March 6, 1926, Greenspan showed mathematical acumen from a young age and attended the Juilliard School before pivoting to economics, earning his bachelor’s degree from New York University in 1948 and his master’s in 1950. He later completed a PhD from NYU in 1977.
In the early 1950s, Greenspan became an associate of Ayn Rand — the “Atlas Shrugged” author whose laissez-faire, objectivist philosophy would quietly shape his economic worldview for decades. From 1955 to 1987 he ran his own economic consulting firm, building a reputation on Wall Street as a careful, data-driven thinker before President Ronald Reagan nominated him as Fed Chairman in August 1987.
Two months after taking office, he faced his first crisis: Black Monday, the stock market crash of October 1987, when the Dow plummeted over 20% in a single day. Greenspan’s swift intervention — flooding the banking system with liquidity — averted a broader meltdown and established his reputation as a decisive crisis manager. The legend of “the Maestro” was born.
The Great Moderation: Greenspan’s Finest Hour
The 1990s were Greenspan’s golden decade. He presided over one of the longest economic expansions in US history, a boom stretching from 1991 to 2001, characterized by low inflation, surging stock markets, and unprecedented prosperity. Ordinary Americans hung on his every word. “With a couple of choice words he can momentarily send the stock market to heaven or hell,” the Washington Post noted in 1997.
His reign at the central bank coincided with what economists called the “Great Moderation” — a period of stability from the mid-1980s until 2007 marked by low inflation, stock market gains, and strong economic growth. He navigated the Fed through the Asian Financial Crisis of 1997–1998, the dot-com bubble’s early warning signs, and the shock of 9/11 — each time managing to keep the US economy afloat.
Greenspan became famous — or infamous — for a deliberately opaque speaking style known as “Fedspeak.” He once said he would “deliberately garble his syntax to avoid saying anything that might move financial markets.” Congress routinely left his testimony scratching their heads. Markets parsed his every word with forensic intensity.
The one exception — the phrase that defined his era — came in December 1996 when, surveying a booming stock market, Greenspan publicly wondered aloud whether investors were displaying “irrational exuberance.” The remark momentarily rattled global stock markets. Yet the bubble kept inflating for another four years.
The Shadow: 2008 and the Reckoning
When Greenspan retired in January 2006, after 19 years in office, he was celebrated as the greatest central banker of his generation. Within two years, that reputation was in ruins.
The 2008 global financial crisis — triggered by the collapse of a housing bubble built on subprime mortgage debt — wiped out trillions of dollars in wealth and cost millions of Americans their homes and jobs. Critics pointed directly at Greenspan’s record: his advocacy for financial deregulation, his reluctance to pop asset bubbles, his faith in the self-correcting wisdom of markets.
His loose hand at the central bank is widely cited as a contributing cause of the 2008 financial crisis. His successor guided the economy through the crisis. As MIT economist Simon Johnson later told PBS Frontline: “Alan Greenspan was coming from a very libertarian tradition: Keep your hands off everything. The markets will sort themselves out. And if there’s a problem, then we’ll clean up afterwards. That really was the way the Federal Reserve operated under his leadership for almost 20 years.”
In a remarkable moment of public introspection, Greenspan testified before Congress in 2008 and acknowledged a fundamental flaw in his worldview — that markets were not always as self-correcting as he had believed. As NPR’s retrospective noted, he will ultimately be remembered as “both a maestro of monetary policy and a reluctant regulator — his legacy shaped by the boom he fostered, and by the bust he failed to prevent.”
Greenspan in the Trump Era: A Defender of Fed Independence
Even in his final years, Greenspan remained engaged. In January 2026, months before his death, he co-signed a joint statement with other former Fed and Treasury officials denouncing a reported criminal probe of then-Fed Chair Jerome Powell, calling it “an unprecedented attempt to use prosecutorial attacks to undermine” the Fed’s independence.
It was a fitting final act — the man who had done more than anyone to build the modern Fed’s credibility, using his remaining influence to protect it.
What the Markets Said
News of Greenspan’s death broke on a Monday, and Wall Street paused to reflect. Economists from across the ideological spectrum recognized the end of an era. The BBC described him as the “architect of the modern American economy.” The New York Times called him the “pre-eminent economic policymaker of his time.”
Now, with a new Fed Chairman — Kevin Warsh — already signaling a hawkish pivot and inflation running at 4.2%, the echoes of Greenspan’s era feel more relevant than ever. The debate he ignited over when central banks should prick asset bubbles, how much communication is too much, and whether markets can truly regulate themselves, remains unresolved.
Key Facts at a Glance
| Fact | Detail |
|---|---|
| Full Name | Alan Greenspan |
| Born | March 6, 1926, New York City |
| Died | June 22, 2026, Washington D.C. (age 100) |
| Cause of Death | Complications of Parkinson’s Disease |
| Fed Tenure | 1987–2006 (19 years) |
| Presidents Served Under | Reagan, H.W. Bush, Clinton, George W. Bush |
| Famous Phrase | “Irrational exuberance” (1996) |
| Survived By | Wife, Andrea Mitchell (NBC News) |
FAQ
Q: What was Alan Greenspan’s most famous quote? “Irrational exuberance,” spoken in 1996 to describe a potentially overheated stock market. It sent global markets briefly into a tailspin and became one of the most cited phrases in financial history.
Q: Was Greenspan responsible for the 2008 financial crisis? He is widely considered a contributing factor. His advocacy for financial deregulation and his reluctance to regulate derivatives markets created conditions that enabled reckless risk-taking by banks. However, the crash occurred two years after he left office.
Q: Who replaced Greenspan at the Fed? Ben Bernanke succeeded him in 2006. Jerome Powell later became Chair, followed by Kevin Warsh in 2026.
Q: How long was Greenspan Fed Chairman? 19 years — the second-longest tenure in Fed history, behind only William McChesney Martin.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Open banking lets you share your bank account data with apps and services, such as budgeting tools and lenders, that you choose to use. In the United States, the framework is less settled than in Europe or the UK. The CFPB finalized its Section 1033 rule in October 2024, but a federal court has enjoined its enforcement, and the agency is rewriting the rule, including whether banks may charge fees for data access. The result is a patchwork in which market standards and state proposals are doing much of the work.
Key Takeaways
- The CFPB finalized its Section 1033 open banking rule in October 2024, but it is not in force, according to the Open Banking Tracker’s status update.
- The CFPB sent a proposed revision to the White House’s regulatory review office (OIRA) in August 2026, per Consumer Finance Monitor.
- A key open question is whether banks can charge fees for data access. The 2024 rule barred most such fees.
- New York has introduced open banking bills in committee, so state rules could diverge from federal ones.
- Industry practice is moving toward the FDX standard and away from screen scraping, according to the status tracker.
What Open Banking Means for You
Open banking refers to the ability to move your financial data securely between institutions and apps. A budgeting app might read your transactions to categorize spending. A lender might check your income and balances before approving a loan. In the best cases, the data sharing is read-only, consent-based, and easy to revoke.
Two components matter. Data access lets an app read your account information with your permission. Payment initiation lets an authorized app move money on your behalf. Most consumer use cases today involve data access.
Where the Rule Stands
Section 1033 of the Dodd-Frank Act gives consumers the right to access their financial data and to direct it to third parties. The CFPB’s implementing rule, the Personal Financial Data Rights rule, was published in the Federal Register in January 2025. Its compliance dates were phased, starting in 2026 for the largest data providers.
Those dates no longer bind in practice. A federal court in Kentucky enjoined the CFPB from enforcing the rule, according to an ABA Banking Journal report cited in the tracker, and the agency has reopened the rule for substantial revision. The April 2026 compliance deadline passed without becoming an enforcement trigger.
The CFPB’s revised proposal, sent to OIRA in August 2026, is expected to narrow or reshape several provisions. Analysts have flagged changes to who counts as a consumer or representative, limits on secondary data use, and whether data providers may charge fees.
Timing is uncertain. One analysis expected a revised rule in the Federal Register around the fourth quarter of 2026, with comments closing in early 2027. That projection is not confirmed, so check the Federal Register before relying on it.
The Fee Question
The fee question matters most for consumers because it shapes who pays for data sharing. The 2024 rule barred data providers from charging consumers or authorized third parties for access. Banks argued that this was one-sided and prevented them from recovering the cost of building and securing the infrastructure. Fintechs and consumer advocates argued that free access is a core consumer right.
If the revised rule allows fees, the most likely effect is higher costs for fintech apps that rely on bank data, which could be passed to consumers through subscription fees or reduced free features. If fees remain barred, the cost burden stays with banks.
State Action
While federal rules are in flux, states are acting. New York Assembly Bill 10640 and its Senate companion, S9483, were introduced in March 2026 and remain in committee. These bills focus on open banking data and could create state-level obligations that differ from federal requirements.
Consumers in states that pass such laws may gain protections the federal framework lacks. Companies operating nationally may face a patchwork of requirements, which could slow product development.
Market Standards Are Doing Real Work
Even without a binding federal rule, many institutions are building connections. The FDX standard, a U.S. data-sharing specification, has become a common reference point. Building on FDX reduces reliance on screen scraping, a method where an app logs in to your bank on your behalf using your credentials.
Screen scraping is less secure because the app holds your login details. Connections through standardized APIs typically let you grant and revoke access through your bank’s interface without sharing your password.
Protect Your Financial Data
Whether or not a rule is in force, these steps reduce risk:
- Review connected apps. Check your bank’s app connection list at least once a year and remove any service you no longer use.
- Prefer API connections over credential sharing. If an app asks for your bank username and password directly, look for an alternative connection method.
- Read data-use terms. Confirm whether the app sells or shares your data with third parties, and whether it uses your data for purposes beyond the service you requested.
- Limit permissions. Choose read-only access when payment initiation is not needed.
- Revoke access after use. If you stop using an app, revoke its access instead of leaving the connection active.
- Monitor statements. Watch for unexpected transactions, which can signal a compromised connection.
What to Watch Next
- The CFPB’s revised Section 1033 proposal and its Federal Register publication
- Whether the revised rule permits data-access fees, and at what level
- Progress of New York’s open banking bills and any similar state efforts
- Court rulings on the enjoined rule, which could affect timing and scope
Frequently Asked Questions
Is open banking legal in the U.S.?
Yes, sharing financial data with consented third parties is common. The question is which rules govern it. The CFPB’s Section 1033 rule is enjoined and under revision.
Is the CFPB open banking rule in effect?
No. As of mid-2026, a federal court has enjoined the CFPB from enforcing the rule, and the agency is rewriting it.
Can my bank charge me for sharing my data?
The 2024 rule generally barred fees. That provision is under reconsideration, so future rules could allow certain charges.
Is screen scraping dangerous?
It can be less secure, because the app stores or uses your login credentials. API-based connections are generally safer.
How do I revoke an app’s access to my bank data?
Most banks show connected apps in their online or mobile banking settings. You can usually revoke access there, and you may also be able to contact the app provider to delete your data.
What happens if a state passes its own open banking law?
State rules could add protections or obligations. Check your state’s legislature for pending bills if you live in New York or another state considering similar legislation.
Conclusion: Control What You Share
U.S. open banking is moving toward a clearer framework, but the final rules are not settled. Consumers can benefit from easier access to their financial data and better-tailored financial tools, provided they manage their connections carefully. Review your connected apps, prefer secure API connections, and follow the CFPB’s proposed rule as it moves toward publication.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
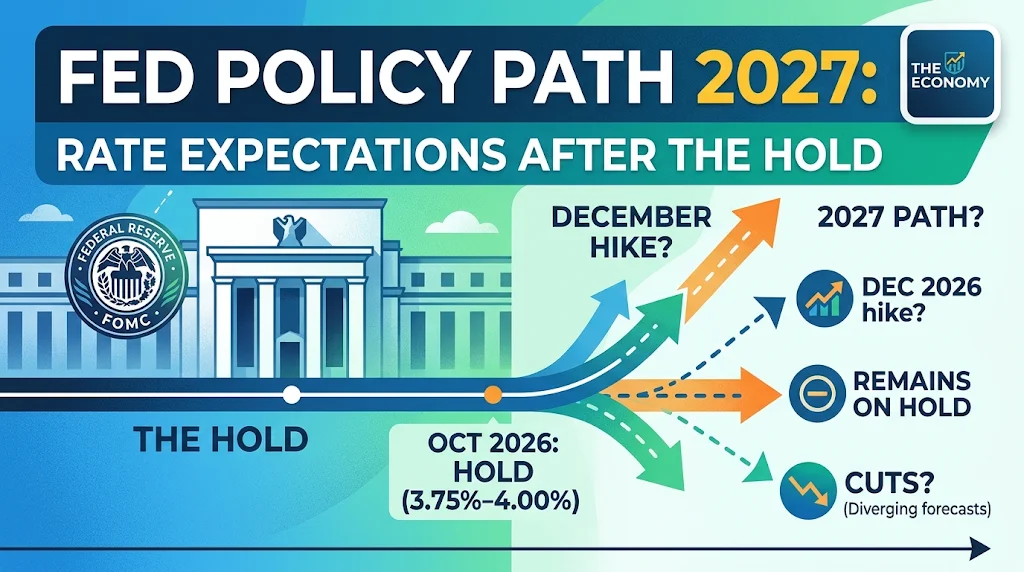
The Federal Reserve kept its policy rate unchanged in late October 2026, with two officials dissenting in favor of a hike, and the next move is now debated between a December increase and a longer hold into 2027. The federal funds target range was 3.75% to 4.00% after the October meeting, according to J.P. Morgan’s summary of the decision. The 2027 path depends on whether inflation eases enough for cuts to resume or stays high enough to keep tightening on the table.
Key Takeaways
- The Fed held rates in October 2026 despite elevated inflation, with two dissents favoring a quarter-point increase, per Charles Schwab’s meeting summary.
- Several major forecasters expect a December 2026 hike, including J.P. Morgan’s economists, who said the statement signaled a “hawkish bias.”
- Rabobank now expects the Fed to remain on hold through 2027, with one cut per year in 2028 to 2030.
- Goldman Sachs’s June forecast pushed its final two cuts of the cycle to June and December 2027, though its view predates the autumn hawkish turn.
- The Fed will hold eight meetings in 2027, but one will be devoted to strategy with no rate vote, which reduces scheduled chances to adjust policy.
Where Policy Stands Now
The Fed cut rates three times in late 2025, bringing the target range to 3.50% to 3.75% by December, according to a JPMorgan Asset Management review. The range sat at 3.75% to 4.00% at the October 2026 meeting, which means the committee moved toward restriction in 2026 rather than continuing to ease.
Two developments define the current debate. First, inflation has remained above target, with energy prices and tariffs cited by analysts as contributors. Second, Kevin Warsh now chairs the Fed, and his first meetings have been closely watched for signals about strategy. Schwab reported that Governor Lisa Cook and Cleveland Fed President Beth Hammack were among those opposing the hold, though reports differ on the exact dissent details, so verify against the official FOMC statement before publication.
Editors should note that the December 2025 Summary of Economic Projections, published by the New York Fed, is now out of date. It projected a median federal funds rate of 3.4% for 2026 and 3.1% for 2027. Those projections have been overtaken by the 2026 rate decisions and should be cited only as historical context.
The Case for a December Hike
The hawkish case rests on inflation and the committee’s language. J.P. Morgan’s economists interpreted the October statement as keeping December “a live option” for a hike, and they continue to expect one. Schwab reported that some forecasters, including Shah of Saxo, expected an increase in December and another in early 2027.
The argument for tightening is straightforward: if inflation expectations drift upward, the Fed risks losing credibility unless it acts. Oil price spikes linked to Middle East conflict and tariff pass-through have been cited as reasons that price pressures may persist.
Signals that would raise the odds of a hike:
- Core inflation readings that stay above target for consecutive months
- Strong payroll growth that tightens labor markets further
- Rising longer-term inflation expectations in Fed surveys
- Hawkish language in speeches by voting members before the December meeting
The Case for a Longer Hold
Rabobank’s updated view is that the Fed will stop short of further tightening and wait for data. Its analysts argue that the committee will likely stop at a higher neutral rate than its own projections suggest, but they do not expect a December move. After the hold, they see one cut annually from 2028 through 2030.
The hold case also rests on fiscal timing. Continuum Economics has argued that fiscal easing, including tax rebates scheduled to take effect in the first quarter of 2027, would give the Fed reason to wait and observe the effect before adjusting policy.
Signals that would support a hold:
- Inflation trending down toward target without a recession
- Softer hiring data, particularly in payroll and jobless claims
- Stable inflation expectations in consumer and market surveys
- Lower energy prices reducing headline inflation
Forecasts Are Diverging
The range of views is wide, which is itself a finding. Goldman Sachs, in June 2026, pushed its expected cuts into mid-2027. Rabobank now sees no cuts through 2027. J.P. Morgan sees a hike first. Markets have at times priced more hikes than economists, as Goldman noted in its analysis that market pricing sat above its own forecasts.
For readers, the practical takeaway is that rate expectations are uncertain in both directions. A single forecast should not be treated as a plan.
What the 2027 Meeting Calendar Changes
Warsh announced that one of the eight 2027 FOMC meetings will be devoted to “broad monetary policy strategy” without a rate decision or post-meeting statement. Fewer decision points could make the Fed slower to react to sudden shocks, though it could also reduce the risk of abrupt policy swings.
Investors should check the Fed’s official calendar and confirm which meetings include a rate vote, since the strategy meeting will not produce a rate announcement.
What This Means for Borrowers and Savers
For borrowers, the key variable is the longer end of the curve. Mortgage and corporate borrowing costs track Treasury yields more closely than the fed funds rate. A hold at restrictive levels keeps variable-rate debt expensive, while a December hike would add further pressure.
For savers, higher policy rates support yields on short-term deposits and Treasury bills. If the Fed holds through 2027, savings products may remain competitive, though yields could decline if cuts arrive later.
Practical steps:
- Review variable-rate debt and consider the cost of a 25-basis-point increase.
- Ladder short-term deposits or Treasury bills to reduce reinvestment risk.
- Avoid locking in long-term rates based on a single forecast.
Frequently Asked Questions
What is the current federal funds rate?
The target range was 3.75% to 4.00% after the October 2026 meeting, according to J.P. Morgan’s summary. Check the Federal Reserve’s website for the latest decision.
Will the Fed raise rates in December 2026?
Possibly. J.P. Morgan expects a hike, while Rabobank has added one to its forecast before resuming a hold. Markets and analysts disagree, and the outcome will depend on incoming inflation and jobs data.
When will the Fed cut rates again?
Forecasts vary. Rabobank sees no cuts through 2027. Goldman Sachs’s June forecast expected cuts in mid-2027, though that view predates the autumn hawkish turn.
Who is the Fed chair?
Kevin Warsh chairs the Federal Reserve as of late 2026, according to reports of the October meeting.
How many Fed meetings will have rate decisions in 2027?
Seven of the eight scheduled 2027 meetings are expected to include rate decisions. One is designated for strategy discussions without a rate vote.
How should homeowners prepare for a longer hold?
Consider the cost of variable-rate debt, compare refinancing options, and plan for mortgage rates that track longer-term Treasury yields more closely than the policy rate.
Conclusion: Plan for Both Outcomes
The 2027 rate path is genuinely uncertain. A December hike, a longer hold, or an eventual return to cuts are all plausible given current forecasts. The best guide is incoming data on inflation and jobs, along with the Fed’s own statements. Readers should treat forecasts as scenarios to prepare for rather than predictions to bet on.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
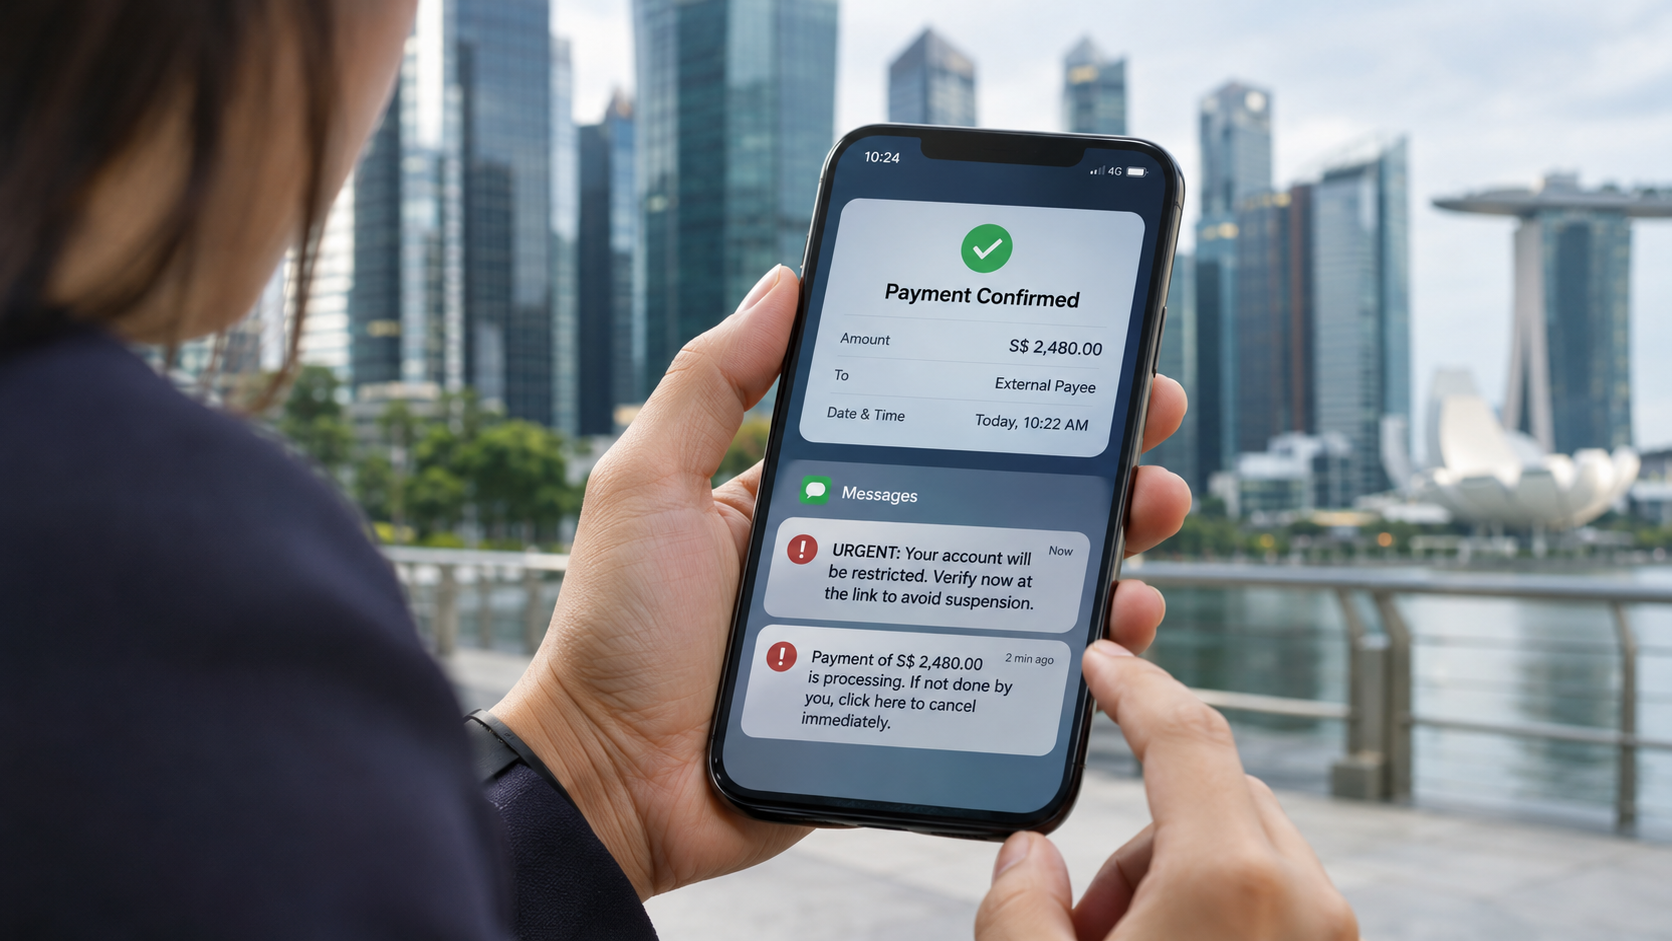
Scam losses are declining, but the economics of deception remain brutal. Singapore now needs a clearer answer to a question that digital finance has made unavoidable: when a payment is legitimate in form but fraudulent in purpose, who should bear the consequences?
A payment can be correctly authenticated, voluntarily approved and catastrophically mistaken. That is the uncomfortable reality behind a large share of modern financial fraud. Someone posing as an official convinces a frightened customer to transfer savings. A supposed investment adviser cultivates trust in a messaging group. A business receives an altered invoice from an apparently familiar supplier. In each case, the transaction may look authorized within the banking system even though the decision was engineered by a criminal.
Singapore has made measurable progress against scams, but the remaining scale is staggering. In the first half of 2026, Singapore Police Force figures reported by CNA recorded 16,821 cases and approximately S$410.6 million in losses. Reported cases were down 14.4% and losses down 17.9% year on year. This is progress, not victory.
The most revealing statistic is that about 80.8% of reported scams involved victims making transfers themselves, according to the same police account. This should change how the country frames the problem. The key vulnerability is often not a broken password but a manipulated person, persuaded to use a secure financial system in an insecure way. A defense based solely on telling customers to be more careful cannot be enough.
The answer is not an unconditional promise that banks refund every bad decision. It is a more intelligent division of responsibility that gives each participant a reason to stop fraud at the point where it has the greatest capacity to act.
The scale of the problem demands precision, not panic
Loss figures alone do not reveal the severity of individual harm or how much frozen money actually reaches victims. It matters.
The police’s half-year figures showed that investment scams caused roughly S$169.8 million in losses, making them the largest category by dollar amount. Government-official impersonation scams cost about S$90.8 million. Business email compromise losses rose to S$57.3 million, substantially higher than a year earlier, while e-commerce scams were the most common category by case count.
A serious strategy cannot treat these offences as interchangeable. An investment scam may unfold over weeks of persuasion. A compromised invoice might exploit a business’s payment workflow and supplier verification failures. A phishing attack may seek account credentials and allow an unauthorised account takeover. Prevention that works for one can miss another entirely.
The police also reported more than S$97.7 million in losses recovered or frozen through anti-scam efforts in the first half, and at least S$127.1 million in potential losses prevented. Those figures should not be added together and called money returned to victims. The recovered amount described funds secured in accounts or wallets, rather than automatically refunded, while prevention estimates refer to money that might otherwise have been transferred.
An important sign of progress appeared in a joint police-bank operation from July to August. Working with DBS, OCBC, UOB, Standard Chartered Singapore and GXS, authorities reported disrupting more than 400 ongoing scam attempts and averting over S$46 million in potential losses. The achievement shows what rapid intelligence-sharing can do. It also shows that the most useful intervention is often the one made before the transaction becomes irreversible.
The false boundary between ‘authorised’ and ‘fraudulent’
Banking law and payment systems need to determine whether a transaction was authorised. Customers need to determine whether the person asking them to pay is legitimate. Criminals exploit the gap between those two judgments. A person can authorise an instruction without understanding that the alleged identity, emergency or investment opportunity is fictitious.
From the bank’s operational perspective, the payment may have passed the required checks. From the customer’s perspective, the decision was based on deception. From a regulator’s perspective, the central challenge is to reduce the number of fraudulent transfers without imposing excessive friction on normal commerce. None of these perspectives is automatically complete.
The distinction matters because Singapore’s Shared Responsibility Framework, established by the Monetary Authority of Singapore and the Infocomm Media Development Authority, addresses a defined set of phishing scams and corresponding duties of financial institutions and telecommunications operators. It should not be represented as a universal, automatic reimbursement scheme for every investment scam, impersonation loss or unauthorised payment.
The MAS policy overview describes a duty-based approach to accountability, with expected payments when covered entities breach applicable duties. Outside its scope, other avenues of complaint, discretionary remediation and dispute resolution may still matter. A framework with boundaries can be useful, but misunderstanding those boundaries is dangerous for consumers.
Singapore therefore faces a policy question larger than the framework itself: should the treatment of authorised-but-fraudulent payments increasingly depend on whether an institution could reasonably have recognised and interrupted suspicious behaviour? If so, how can authorities define that standard without creating either limitless liability or a system so rigid that ordinary customers cannot transact?
The bank has information the consumer does not
A bank can observe transaction histories, unusual beneficiary patterns, sudden transfers, device activity and other signals that a customer usually cannot see. It may be able to identify a suspicious movement of funds across its network or cooperate with law enforcement more quickly than an individual victim. That informational advantage creates an obligation to invest seriously in monitoring and response.
In a November 4, 2026 parliamentary reply, the MAS chairman described safeguards including real-time fraud surveillance, transaction alerts and tools allowing customers to lock cards or contact emergency hotlines. These are meaningful measures, but their existence is not the same as proof that they catch every relevant pattern. The right questions are whether the alerts are timely, intelligible and effective, and whether a customer can obtain rapid assistance when something seems wrong.
Some transfers are anomalous for obvious reasons: an account suddenly sends large sums to unfamiliar recipients, or successive transactions rapidly drain savings. Other payments look routine until an external clue emerges—a fake commercial identity, a coerced beneficiary or an organised scam network. Banks should be judged against what their systems could reasonably know, not against an impossible expectation of omniscience.
There is a practical argument for narrowly designed delays on high-risk transactions. A pause can give a frightened customer time to speak with a trusted person, question the caller’s identity or contact the real institution using a verified channel. Delays can impede legitimate payments, so intervention must target demonstrable risk.
The strongest protection may be intelligently placed friction rather than universal friction. A system that quietly processes ordinary transactions while interrupting unusual, high-risk ones could protect both safety and convenience better than a blanket regime. Proving that requires measurement—false positives, prevented losses and customer outcomes—not slogans about innovation.
Platforms and communications networks are not innocent bystanders.
Many scams begin far from a bank. A fraudulent advertisement appears on a platform. A fake mentor builds credibility in a messaging group. A message impersonates a government office. An email thread is altered just before a supplier payment. By the time money reaches the banking system, crucial deception may already have happened elsewhere.
The mid-year police account highlighted investment-scam techniques involving impersonation and online chat communities. That makes digital platforms significant points of prevention. Verification of advertisers, rapid removal of impersonating accounts, better evidence preservation and effective escalation channels can affect whether the fraud is ever attempted successfully.
The challenge is to assign duties according to practical influence. Telecommunications providers can filter certain harmful communications. Platforms can moderate fraudulent ads and impersonation networks. Banks can assess money flows. Police can coordinate investigations and freeze illicit proceeds. Consumers still need reasonable opportunities to identify deception. A strategy that names only the victim at the end of the chain ignores the institutions able to intervene earlier.
Singapore’s September 2026 anti-scam legislative changes expanded tools for cooperation with service providers, including specified information-sharing and restrictions on accounts linked to scams. Such powers may reduce criminal opportunities, but they also need oversight. If a legitimate account is disabled in error, the disruption can be acute, particularly for someone who relies on it for wages or essential purchases.
It is possible to believe simultaneously that the state needs better anti-scam powers and that ordinary people need effective remedies when those powers are misapplied. A financial system worthy of trust should be able to hold both positions.
The overlooked issue of financial exclusion
Scam prevention increasingly intersects with the right to a basic bank account. Risk controls that are excellent at denying access can be poor at distinguishing malicious users from people caught in confusing or suspicious circumstances. For customers excluded from the payment system, a dispute over account access can quickly become a dispute over food, rent and employment.
In a November 3 parliamentary reply, the MAS chairman explained the availability of limited-purpose bank accounts for many Singapore citizens and permanent residents whose standard accounts are closed or denied, subject to exceptions. The principle is sound: severe restrictions should not automatically remove every avenue for essential lawful payment activity.
The implementation deserves scrutiny. Customers need understandable reasons to the extent legally possible, a realistic review process and accessible support. Regulators should study both the effectiveness of account restrictions against scams and the incidence of unjustified exclusion. If a protective system creates invisible hardship, it can erode trust even as it prevents crime.
A modern society increasingly treats digital payments as essential infrastructure. That raises the standard of fairness for institutions that control access. Banks should not be forced to take unlimited financial-crime risks, but neither should consumers be left without a credible path to resolve mistakes.
Artificial intelligence changes the economics of deception
The threat from AI is not merely a dramatic deepfake video. It is the ability to generate convincing messages at scale, tailor an impersonation to a specific victim, translate naturally across languages and maintain a persistent fictional identity. Criminals can lower the cost of experimentation while increasing the realism of some approaches.
In remarks accompanying the MAS 2025/2026 annual report, the regulator discussed more personalised AI-assisted scams and the need for banks to improve fraud-detection models. It also disclosed that roughly S$47 billion was protected under the Money Lock function as of May 2026. The function illustrates an important concept: the freedom to move money instantly is not always the same as the freedom to preserve it safely.
But there is also risk in overconfident automated decision-making. A model that labels a lawful transaction suspicious can trap customers in opaque procedures. A model that fails to recognise a new scam variant can provide false comfort. Human review, explainable escalation processes and testing against real outcomes should accompany claims of AI-driven protection.
The relevant innovation is not an impressive detection dashboard. It is a measurable reduction in losses and harm without intolerable collateral damage to legitimate financial life.
A fair counterargument: unlimited reimbursement would make matters worse
Those sceptical of expanded bank responsibility have a legitimate concern. If customers believe every authorised transfer will be reimbursed, some may take fewer precautions, while criminals devise new ways to abuse the guarantee. Banks may respond by charging more, rejecting more transactions or withdrawing services from customers they perceive as risky. A poorly designed liability regime could hurt the very households it intends to protect.
Such incentives must be taken seriously. Responsibility should be calibrated to what an institution could reasonably prevent and whether it fulfilled defined duties. Customers must retain agency, and payment systems must remain usable. A uniform compensation rule would be blunt; it could make ordinary financial activity less accessible without solving the underlying deception.
Yet the opposite extreme—treating every customer-approved transfer as solely the customer’s problem—would also produce bad incentives. A bank might invest less than socially optimal amounts in detection if most of the losses fall on households. A platform might profit from advertising while leaving expensive cleanup to police and banks. An effective framework makes prevention worthwhile for the parties best placed to prevent harm.
What a better Singapore model would measure
Singapore should report consistent statistics on preventable losses, intervention success, complaint outcomes and false-positive restrictions, alongside headline scam losses. It should distinguish money frozen from money repaid and publish clear explanations of how different scam types fit within different compensation regimes. Greater transparency would help the public understand actual protections rather than rely on vague assurances.
Banks and platforms should be encouraged to test interventions jointly, including targeted payment pauses, beneficiary warnings, suspicious-ad takedowns and rapid information-sharing. Police and regulators should assess which interventions prevent the most harm per unit of cost or inconvenience. Firms should have incentives to fix recurring weaknesses, while consumers should have practical routes to appeal and recovery.
At the same time, legal protections must respect privacy, proportionality and due process. Fighting financial crime does not justify indefinite, unexplained restrictions on innocent users. The system should protect both personal savings and access to the infrastructure of everyday life.
For policymakers, the central test is whether responsibility follows capacity. If one party controls a risky communication channel, another holds the money and a third maintains investigative powers, each should carry obligations aligned with the harm it can realistically prevent. Responsibility shared in this manner does not dissolve accountability; it makes it operational.
Trust is the ultimate financial infrastructure
Singapore’s falling scam totals are an achievement. But hundreds of millions in losses during six months remain a profound challenge for an economy built on trust, efficient transactions and sophisticated financial institutions. A victim who authorised a payment while being expertly deceived may bear part of the responsibility. That does not justify ignoring the systems that enabled the deception and the transfer.
The goal should not be to guarantee a world without financial crime, which no jurisdiction can promise. It should be to build a system in which fraud is harder to initiate, easier to interrupt, less devastating when it occurs and subject to remedies that ordinary people can understand.
Digital finance has reduced the friction of sending money. The next phase of progress must reduce the friction of keeping it safe. Singapore’s institutions have the skills and coordination capacity to do that. Whether they allocate the costs of prevention fairly will determine how much of the public’s trust they retain.
Singapore’s scam losses declined in the first half of 2026, but still reached S$410.6 million. Many victims authorised transfers themselves under deception, exposing a gap between technical payment security and real-world protection. An effective response should assign clear, proportionate duties to banks, platforms, telecommunications operators and regulators while preserving consumers’ access to essential financial services.
Singapore’s scam losses are falling, yet victims still lose hundreds of millions. The unresolved question is who should act—and who should pay—when fraud succeeds through a valid payment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Democrats Won Congress. Can They Fix the U.S. Economy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025