
Global Economy
Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Key Takeaways
- The Tipping Point: European Commission President Ursula von der Leyen has declared that Europe’s trade deficit with China has reached an “unsustainable” €1 billion per day, pushing bilateral trade relations to a historical tipping point.
- Enforcement Over Engagement: Signaling a fundamental shift in doctrine, von der Leyen issued a direct ultimatum: “Words are good. But deeds are better.”
- The Defensive Arsenal: Brussels is escalating beyond traditional anti-dumping tariffs, actively deploying the Foreign Subsidies Regulation (FSR), the International Procurement Instrument (IPI), and establishing a centralized European Critical Raw Materials Corporation under the RESourceEU framework.
- Supply Chain Exposure: European and Asian enterprises face heightened compliance scrutiny, potential market access restrictions, and supply chain realignment risks across green-tech, automotive, and critical mineral sectors.
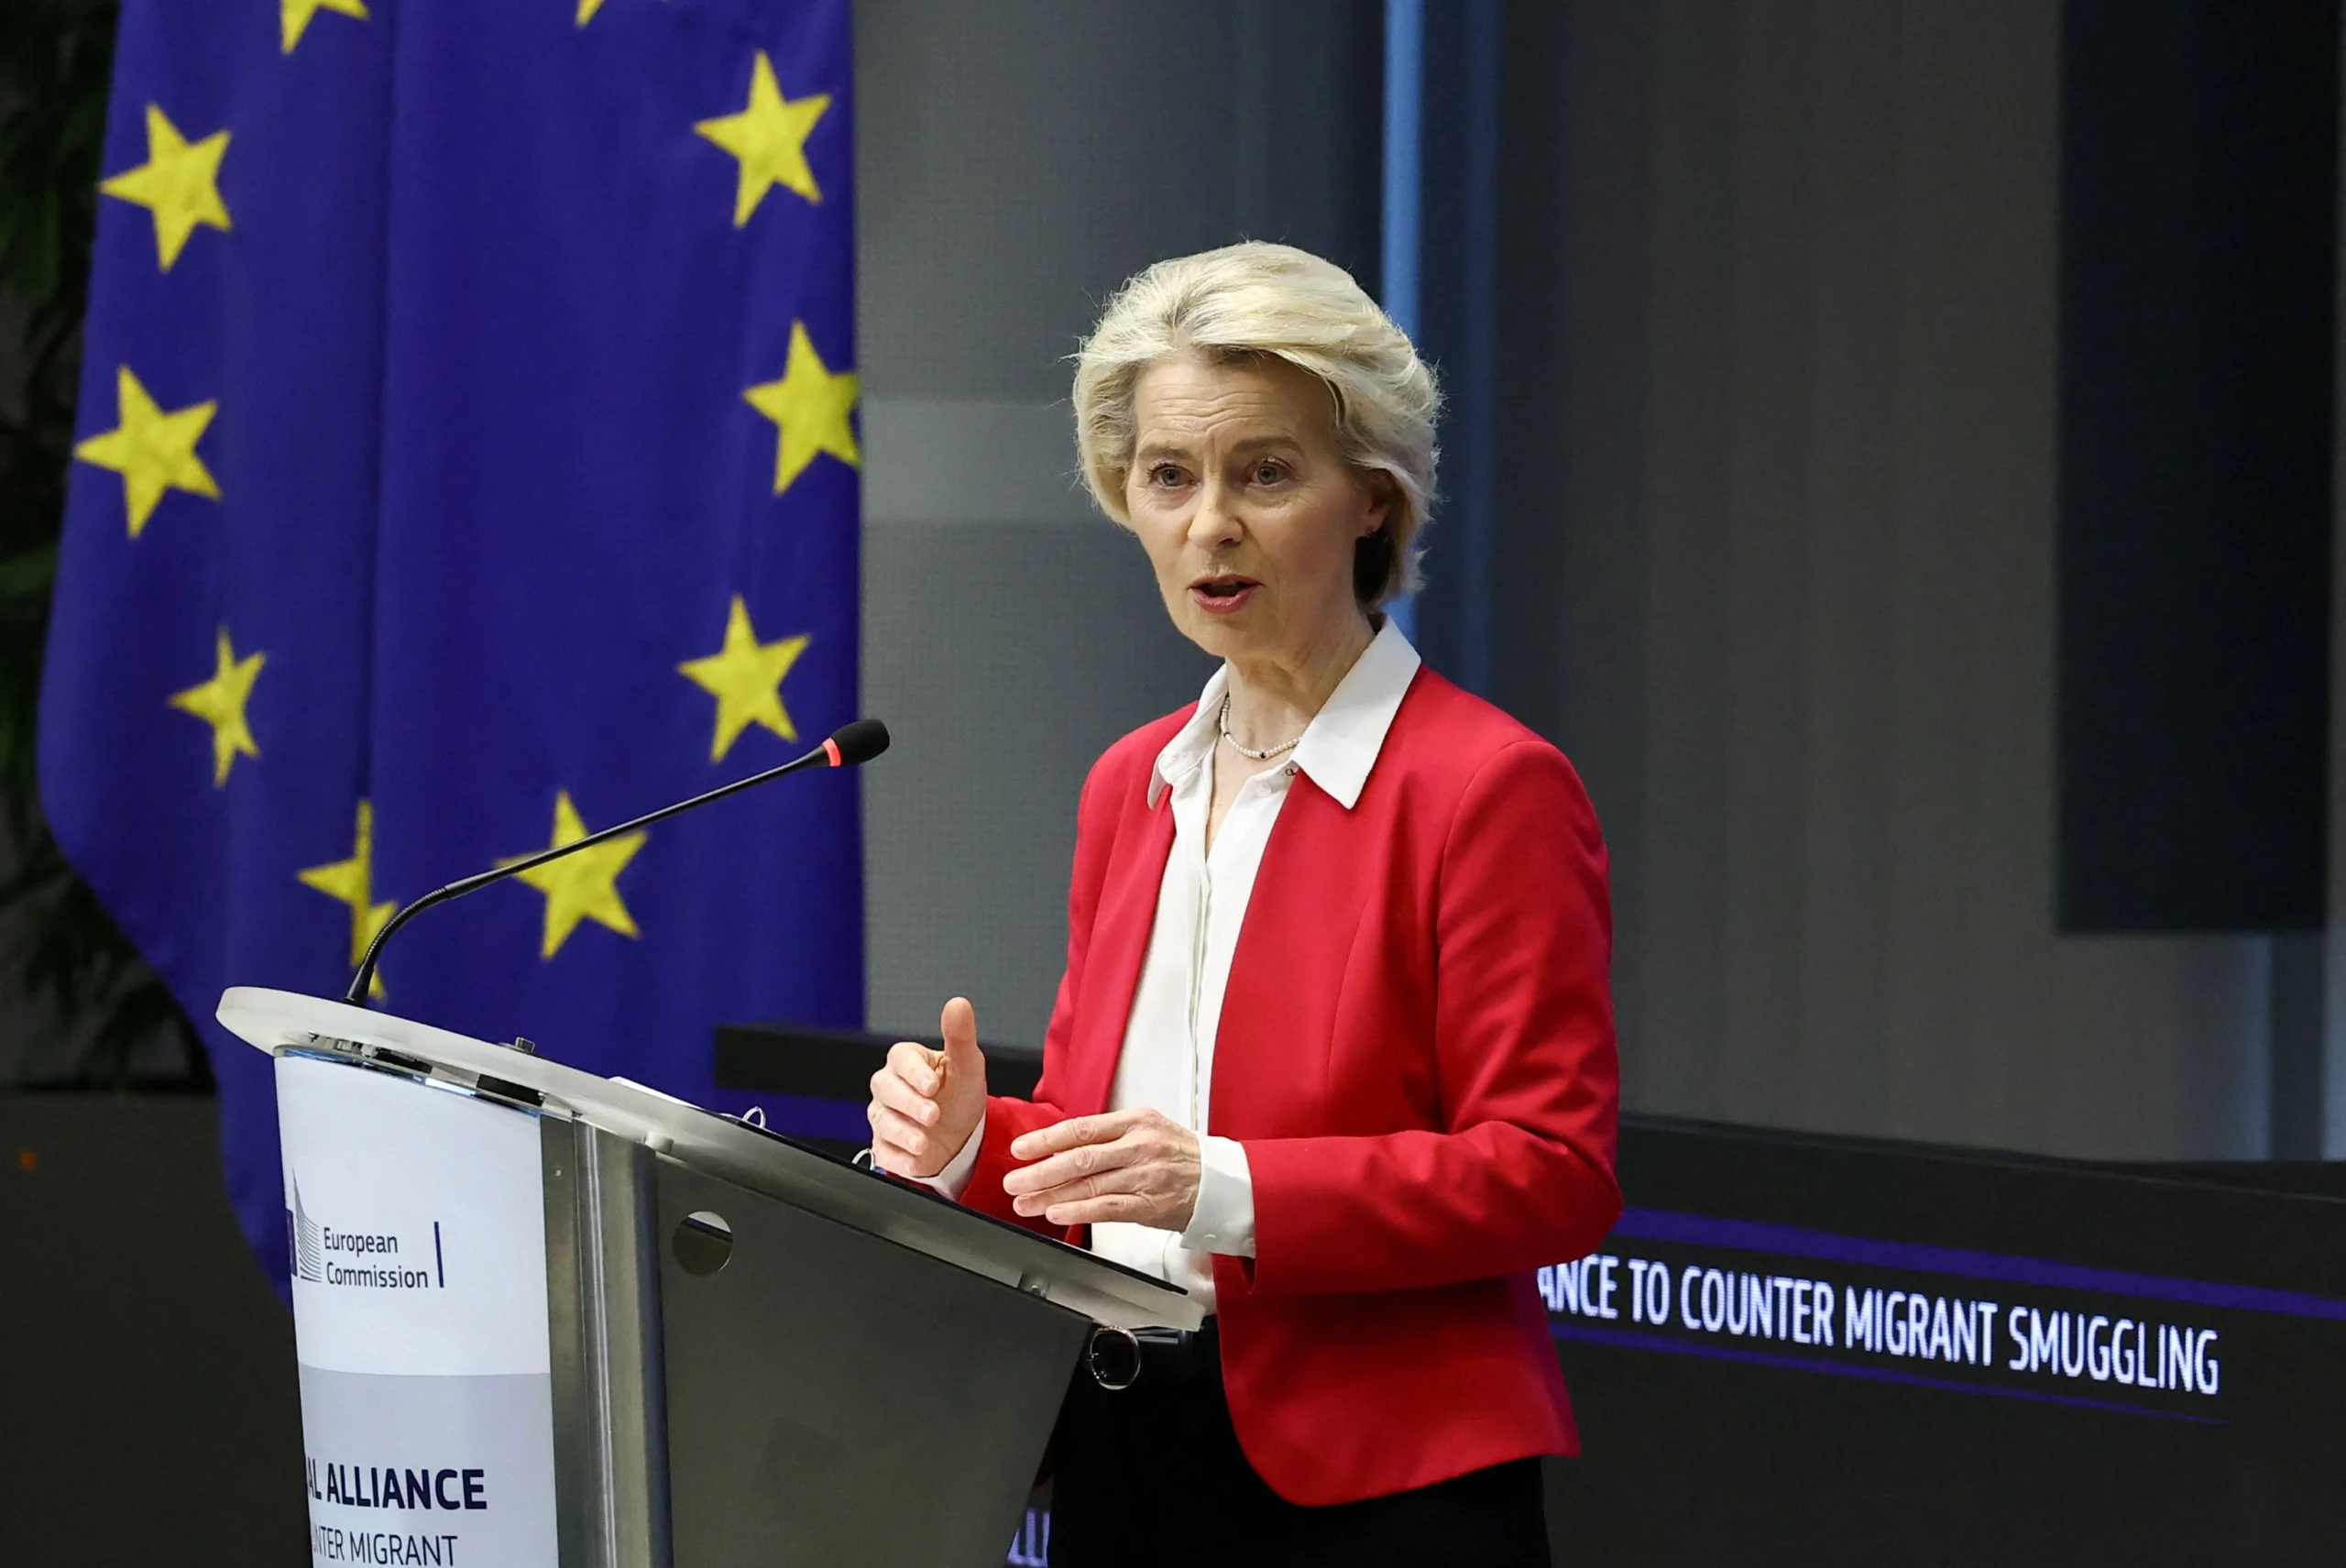
Commission President von der Leyen outlining EU trade policy in Brussels. Source: Yves Herman / REUTERS
The €1 Billion-a-Day Dilemma: Inside Brussels’ Trade Ultimatum
In her 2026 State of the Union address, European Commission President Ursula von der Leyen delivered her sternest warning to date regarding economic relations with Beijing. Citing structural industrial overcapacity in China and subsidized export dumping into the Single Market, von der Leyen emphasized that Europe’s trade deficit with China—now running at approximately €1 billion every single day—has crossed a critical threshold.
While reaffirming that diplomatic dialogue remains open, von der Leyen signaled that Brussels’ patience with protracted negotiations has expired:
“Words are good. But deeds are better. If market imbalances persist and level-playing-field conditions are not restored, the European Union will use all tools at its disposal to rebalance trade.” — Ursula von der Leyen, President of the European Commission
According to official data released alongside the address by the European Union External Action Service, the EU’s merchandise trade deficit with China has expanded sharply over the past decade. The expansion is driven by state-directed investments in clean technology, advanced industrial machinery, and automotive manufacturing, combined with persistent market barriers facing European exporters in mainland China.
Deconstruction of the EU’s Trade-Defence Arsenal
To move beyond political warnings, the European Commission is mobilizing a multi-layered regulatory architecture designed to shield European industries from non-market practices.
| Trade Defence Instrument | Legal Basis & Focus | Operational Impact on Chinese Exports |
|---|---|---|
| Foreign Subsidies Regulation (FSR) | EU Regulation 2022/2560 | Allows Brussels to inspect and block foreign state-subsidized companies from bidding on EU public tenders or acquiring European firms. |
| International Procurement Instrument (IPI) | EU Regulation 2022/1031 | Restricts access to EU public procurement markets for companies from countries that discriminate against EU businesses. |
| Anti-Subsidy & Anti-Dumping Duties | EU Regulation 2016/1037 | Enables retroactive tariffs on subsidized goods (e.g., Electric Vehicles, solar modules, wind turbines). |
| Critical Raw Materials Corporation (RESourceEU) | 2026 Industrial Strategy | Co-finances joint purchasing, strategic stockpiling, and processing of rare earth elements to reduce single-source dependency. |
As highlighted by macroeconomic analysis from Reuters Global Economic News, the Commission’s strategy represents a transition from reactive tariff enforcement to proactive market access restriction.
EU and China trade relations face growing regulatory and tariff barriers. Source: Bloomberg / Bloomberg via Getty Images
De-Risking in Action: Critical Minerals & the RESourceEU Imperative
A core pillar of von der Leyen’s strategic agenda is severing Europe’s vulnerable supply chain dependencies. China currently controls over 70% of global lithium refining, 85% of rare earth processing, and a dominant share of permanent magnet manufacturing.
To counter this vulnerability, von der Leyen confirmed the formal launch of the European Critical Raw Materials Corporation under the broader RESourceEU initiative. This entity will serve as a centralized buyer and investor, co-funding strategic mining, processing, and recycling projects within the EU, North America, and partner nations across Africa and Latin America.
Key objectives of the mineral security framework include:
- Extraction Mandates: At least 10% of the EU’s strategic raw materials extracted domestically by 2030.
- Processing Sovereignty: At least 40% of the EU’s annual consumption of strategic raw materials processed within the bloc.
- Diversification Caps: No more than 65% of any strategic raw material sourced from a single third country.
Economic reporting by the Financial Times Trade Analysis notes that these targets represent one of the most aggressive state-supported supply chain realignment efforts in modern European history.
Geopolitical Fallout & Beijing’s Countermeasures
Beijing’s Ministry of Commerce (MOFCOM) has expressed strong opposition to Brussels’ hardening stance, warning that increased trade barriers risk destabilizing global recovery and violating World Trade Organization (WTO) principles.
In response to European investigations under the FSR and anti-subsidy rules, China has initiated targeted anti-dumping probes into European exports, including brandy, dairy products, and agricultural machinery. Analysts anticipate that further unilateral measures by Brussels could prompt reciprocal restrictions on European automotive and chemical majors operating in mainland China.
+-----------------------------------------------------------------------+
|                 EU-CHINA TRADE TENSION CASCADE MATRIX                  |
+-----------------------------------------------------------------------+
| 1. EU Measures: FSR Inspections, Tariff Escalation, Raw Material Caps |
|    │                                                                  |
|    ▼                                                                  |
| 2. Chinese Countermeasures: Target Agribusiness, Spirits, Luxury Goods|
|    │                                                                  |
|    ▼                                                                  |
| 3. Corporate Impact: Supply Chain Realignment, Dual-Hub Production    |
+-----------------------------------------------------------------------+
Strategic Playbook for Global Business Leaders
For corporate executive teams and supply chain planners navigating this evolving landscape, the European Union Trade Policy Framework recommends three strategic adjustments:
- Audit State Subsidy Exposure: European subsidiaries of non-EU firms must conduct thorough audits of parent company subsidies, tax credits, and state grants to avoid disqualification under FSR procurement reviews.
- Diversify Critical Mineral Sourcing: Manufacturers reliant on graphite, neodymium, lithium, or cobalt should secure secondary supply contracts outside China ahead of 2027 compliance deadlines.
- Adopt “China + 1” Regionalization: Multinationals serving both European and Asian markets should decouple supply chains into distinct regional hubs to insulate operations from tariff hikes and export controls.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


IMF sees 3.0% global growth in 2026, the World Bank just 2.5%. Compare Europe and Asia forecasts, the gap between them, and what it means for capital.
Executive Summary / Key Takeaways
- The IMF’s July 2026 World Economic Outlook Update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average of 2024–25.
- The World Bank’s June 2026 Global Economic Prospects is far darker: 2.5% in 2026, the weakest since the pandemic, with two-thirds of economies downgraded since January.
- The two institutions are not contradicting each other — they use different weighting methodologies — but the direction of both revisions is the same, and the driver is the Middle East war.
- Europe and Central Asia was cut to 2.1% for 2026; East Asia and Pacific to 4.2%. The Middle East, North Africa, Afghanistan and Pakistan region takes the worst hit at 1.6%.
- The divergence that matters for allocators is not regional but structural: economies plugged into the AI-led technology cycle are outperforming energy importers that are not.
1. Introduction & Immediate Context
Two flagship forecasts, two very different headline numbers, one identical story underneath. Anyone building a 2027 capital plan needs to understand why.
The IMF’s July update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average observed across 2024–25 and broadly unchanged on a cumulative basis from the April 2026 World Economic Outlook. The Fund attributes the modest slowdown to the effects of the war in the Middle East, partly offset by accelerated demand-driven momentum in the global technology cycle thanks to advances in artificial intelligence and its adoption.
The World Bank is blunter. It forecasts global growth slowing to 2.5% in 2026 from 2.9% in 2025 — the lowest rate since the onset of the COVID-19 pandemic — amid higher energy prices, steeper inflation and increased borrowing costs. Forecasts for two-thirds of economies were downgraded relative to January. Growth is expected to improve to 2.8% in 2027 but will remain 0.4 percentage point below the 2010s average.
The gap between 3.0% and 2.5% is largely methodological: the IMF aggregates at purchasing-power-parity weights, the World Bank at market exchange rates, which gives slower-growing advanced economies more influence. Read the revisions, not the levels.
2. Core Market / Strategic Analysis
2.1 Regional forecasts side by side
| Region | World Bank 2026 | World Bank 2027 | Revision direction | Source |
|---|---|---|---|---|
| World | 2.5% | 2.8% | Cut from 2.6% (Jan) | World Bank |
| East Asia & Pacific | 4.2% | 4.4% | Cut from 4.4% (Jan) | World Bank |
| Europe & Central Asia | 2.1% | 2.3% | Cut from 2.4% (Jan) | World Bank |
| South Asia | 6.3% | 6.9% | Fastest-growing region | World Bank |
| MENA, Afghanistan & Pakistan | 1.6% | 5.0% | Cut from 3.6% (Jan) | World Bank |
| Sub-Saharan Africa | 4.0% | 4.4% | Marginal easing | World Bank |
| Low-income countries | 5.4% | — | Cut 0.3pp on the conflict | World Bank |
The MENAAP line is the single most violent revision in the dataset: from 3.6% to 1.6% for 2026 in five months, followed by a mechanical 5.0% rebound in 2027 as base effects and assumed energy normalisation kick in. For frontier-market investors with Pakistan or Gulf exposure, that V-shape is the entire investment thesis — and it rests on an assumption about how long the conflict lasts.
2.2 The European picture
Growth in Europe and Central Asia is projected to decelerate to 2.1% in 2026, weakening in roughly 70% of economies in the region, according to the World Bank’s regional highlights. Domestic demand remains the primary driver but is constrained in 2026 by elevated energy prices, which raise inflation and erode real incomes, and by tighter financial conditions.
Commodity exporters in the region — Azerbaijan, Kazakhstan and Turkmenistan among them — see export revenues supported by higher energy prices even as growth slows. In Russia, the World Bank estimates oil revenue gains at roughly 1.5% of 2025 GDP for each $10 per barrel increase in prices, with those gains mainly directed toward fiscal consolidation.
The euro area itself sits at the sluggish end. The IMF’s January 2026 update had projected euro-area growth steady at 1.3% in 2026 and 1.4% in 2027, noting that the region benefits less than others from the technology-driven investment boost and that lingering energy-price effects continue to drag on manufacturing. Planned defence spending increases are expected to show up in output only in later years given phased commitments running to 2035.
2.3 The Asian picture
East Asia and Pacific is projected to fall to 4.2% in 2026 before firming to 4.4% in 2027 — a downgrade, but still comfortably the second-fastest-growing region. South Asia leads globally at 6.3% in 2026 and 6.9% in 2027.
The IMF’s framing explains why Asia holds up better than Europe: economies plugged into the technology-led upturn experience stronger activity even when they are energy importers, while activity weakens for energy importers with limited participation in that cycle. Energy exporters outside the conflict zone benefit from favourable terms of trade.
3. Structural Drivers and Competitor Gaps
Most coverage treats these as two competing headline numbers. The more useful read is that both institutions have converged on the same three-channel transmission mechanism, articulated by IMF Chief Economist Pierre-Olivier Gourinchas when the April outlook was released: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock. The Fund noted at the time that the global economy had been on a roughly 3.3% trajectory and was heading for an upgrade before the war stopped that momentum, with inflation instead rising toward 4.4%.
Three structural points follow that competitors miss:
The dispersion is the story. The April WEO recorded a cumulative growth revision of nearly three percentage points for 2026 in the Middle East and North Africa, against comparatively modest effects in advanced economies. A single global number conceals a distribution this wide.
The 2027 rebound is conditional, not forecast. The World Bank’s recoveries across all regions in 2027–28 are driven by an assumed decline in energy prices and rebound in global activity. If Brent stays above $100, the rebound does not arrive on schedule.
AI is now a macro line item, not a sector story. Both institutions explicitly cite broader AI adoption as an upside risk offsetting the energy shock. That reframes technology capital expenditure as a national growth input, which is why Singapore, Malaysia and Taiwan are outperforming regional peers with similar energy exposure.
4. Key Implications for Stakeholders
Macro allocators. The IMF–World Bank spread is not noise to be averaged away; it is a signal about where you sit in the distribution. Market-weight exposure to advanced economies should be benchmarked against the World Bank’s 2.5%, not the IMF’s 3.0%.
Corporate strategists. Fiscal pressure is the binding constraint in developing markets. The World Bank flags that fiscal pressures will affect the ability to reduce poverty and food insecurity and to create jobs — which translates into weaker public procurement and slower infrastructure pipelines across frontier markets through 2027.
Frontier and EM investors. Emerging market and developing economies face their weakest per capita income growth since the pandemic. Pair that with the MENAAP downgrade and the case for selectivity over beta exposure is straightforward.
Watch the October calendar. The IMF’s next full World Economic Outlook lands with the Annual Meetings. Given the energy trajectory since July, the risk to the 3.0% figure is to the downside.
5. Frequently Asked Questions
Q1: What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, per its July 2026 World Economic Outlook Update — down from the 3.5% average recorded across 2024–25, with the Middle East war the principal drag.
Q2: Why does the World Bank forecast lower growth than the IMF?
The World Bank aggregates using market exchange rates while the IMF uses purchasing-power-parity weights, giving slower-growing advanced economies more influence in the World Bank’s 2.5% figure. Both revised downward for the same reasons.
Q3: Which region is growing fastest in 2026?
South Asia, at a projected 6.3% in 2026 rising to 6.9% in 2027, according to the World Bank. East Asia and Pacific follows at 4.2%.
Q4: How badly has the Middle East conflict hit growth forecasts?
The World Bank cut its MENA, Afghanistan and Pakistan forecast from 3.6% to 1.6% for 2026, and downgraded two-thirds of all economies since January. Global growth is now at its weakest since the pandemic.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Fed Rate Hike Projections vs. Trump’s Interest Rate Policy: What Global Markets Expect Next
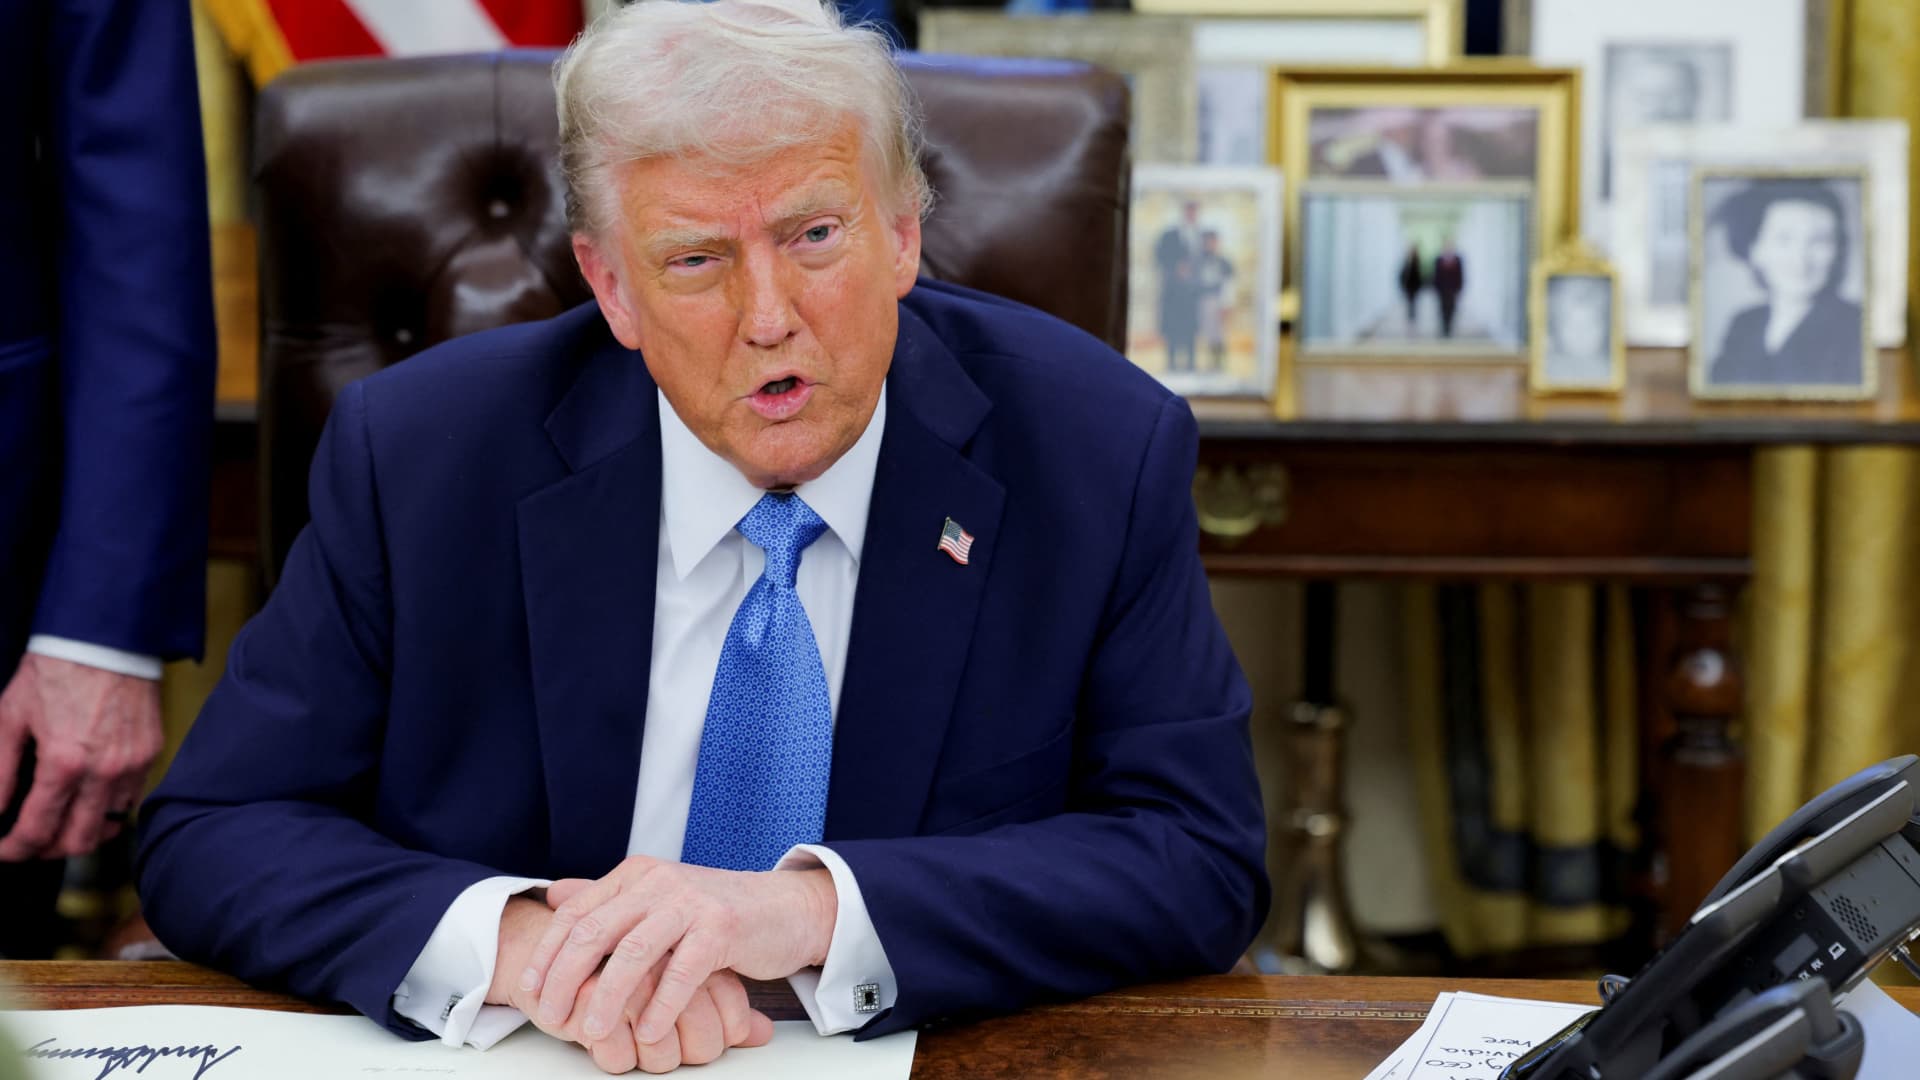
The Fed hiked to 3.75%-4% on Sept 16 as Trump demanded 1% rates. See the dot plot, the market reaction and what it means for borrowers next.
Executive Summary / Key Takeaways
- On 16 September 2026 the Federal Open Market Committee voted 12-0 to raise the federal funds target range by a quarter point to 3.75%–4.00% — the first US rate increase since July 2023.
- The statement was blunt: inflation remains elevated, and the action is meant to support a timelier return to the 2% goal.
- The dot plot showed 16 of 18 participants expecting at least one more quarter-point hike before year-end, with four seeing room for two. Chair Kevin Warsh declined to submit a projection at all.
- President Trump responded within hours, demanding that US rates fall to 1% “or less” — while saying he still has confidence in the chair he appointed.
- Markets sold the decision then partly reversed: the Dow fell more than 600 points, the 10-year Treasury yield topped 5%, and the two-year reached its highest level since 2024.
1. Introduction & Immediate Context
For three and a half years the direction of travel in US monetary policy was one-way — cuts, pauses and arguments about the pace of easing. That ended on Wednesday afternoon.
The Federal Reserve approved its statement by a 12–0 vote, lifting the target range for the federal funds rate by a quarter percentage point to 3¾–4 percent while continuing its policy of maintaining ample reserves in the banking system. The Committee described economic activity as expanding at a solid pace, noted that uncertainty remains elevated partly because of geopolitical developments, and observed that domestic spending has been resilient, productivity growth strong and capital investment robust.
Alongside that assessment sat a one-line justification for tightening: inflation remains elevated, and the policy action will support a timelier return to the 2 percent objective. That combination — firm growth, firm inflation — is what separates this decision from the reflexive easing bias markets carried through the first half of the year. As CNBC reported, futures markets had priced better than a 90% chance of the move, but the accompanying projections were more hawkish than most desks expected.
2. Core Market and Policy Analysis
2.1 What the dot plot actually says
The Summary of Economic Projections is the part institutional desks will trade for the next six weeks. Sixteen of eighteen policymakers anticipate at least one more quarter-point increase by the end of this year, and only two expect rates to stay where they are, according to Reuters. Four of those officials see two further hikes as possible.
Warsh’s refusal to publish his own dot is a deliberate break with a decade of Fed communication practice; he has said repeatedly that he opposes issuing forward guidance. For rate-sensitive borrowers that matters. The committee’s central tendency is now the only signal available, and it points higher.
| Metric / Indicator | Current Status | Projected Impact | Primary Source |
|---|---|---|---|
| Federal funds target range | 3.75%–4.00% (raised 25 bps, 12-0) | At least one further hike signalled for 2026 | Federal Reserve |
| FOMC dot plot | 16 of 18 see ≥1 more hike; 4 see two | Terminal-rate debate shifts toward 4.25%–4.50% | Reuters |
| PCE inflation projection | 3.7% in 2026, falling to 2.3% in 2027 | Above target across the forecast horizon | Fox Business |
| 10-year Treasury yield | Above 5% | Higher mortgage and corporate borrowing costs | Yahoo Finance |
| Prior policy path | Three cuts in 2025 to 3.50%–3.75%, then five holds | First reversal of the easing cycle since 2023 | Trading Economics |
2.2 The inflation case for tightening
Fed projections put PCE inflation at 3.7% in 2026, falling to 2.3% in 2027, with domestic spending remaining resilient, Fox Business reported. That is a second consecutive year of above-target inflation on the central bank’s own numbers, driven substantially by energy costs.
Warsh framed the decision in unusually plain terms at his press conference, saying that inflation is too high and has been for too long, and describing the vote as a sober, serious, responsible decision. Speaking to Bloomberg, he characterised the move as removing a dose of accommodation so that financial and credit conditions would sit more consistently with the Fed’s ultimate objectives — and said the action begins to show the central bank is serious about delivering price stability. He also noted that the economy has gathered speed since the July hold, with little sign of inflation cooling.
3. Structural Drivers and Competitor Gaps: The Independence Test
This is where most coverage stops short. The interesting variable is not 25 basis points; it is the institutional test now underway.
In the week before the meeting, the president, vice president, Treasury secretary and a senior White House economic counselor all publicly urged the Fed not to raise rates and in some cases to cut — an unusually broad pressure campaign even by the standards of Trump’s long-running criticism of the central bank, CNBC reported. Vice President JD Vance said the administration believes the Fed should be lowering rates and would appreciate help from the central bank. Treasury Secretary Scott Bessent argued that the Fed typically does not raise rates during a supply shock until second- or third-order inflationary effects appear.
The decision went the other way. Warsh voted with a unanimous committee despite that pressure, in a move read by analysts as an unambiguous signal that the White House should keep its hands off the Federal Reserve. Trump had selected Warsh in January after souring on former chair Jerome Powell — which is precisely what makes the vote consequential. This was not an inherited adversary defying the administration; it was the administration’s own appointee.
The presidential response came within hours. Trump wrote on Truth Social that US interest rates should be 1% or less because America is the best credit in the world, ending with a demand that rates be lowered fast, Reuters reported. He also appeared to link persistent US trade deficits to the central bank’s borrowing costs, though the two are largely unrelated. Asked later whether he believed Warsh had decided based on White House input, the president said he did not think so, and confirmed he still has confidence in the chair.
For sovereign allocators the pricing question is whether September establishes a durable precedent of operational independence, or whether the pressure campaign intensifies into 2027 as the midterm cycle bites. Long-end term premium is the cleanest instrument for expressing a view either way.
4. Key Implications for Stakeholders
Mortgage borrowers. The transmission channel is the long end, not the policy rate. The 10-year Treasury topped 5% around the decision while oil traded solidly above $100 per barrel, according to Yahoo Finance. Thirty-year fixed mortgage pricing tracks the long bond far more closely than the funds rate, so the term-premium repricing matters more than the hike itself.
Equity investors. Stocks reversed during Warsh’s press conference as markets read his remarks as hawkish, with the Dow dropping more than 600 points — over 1.2% — while the S&P 500 fell 0.4% and the Nasdaq finished near flat. Yardeni Research cut its year-end S&P 500 target to 7,900 from 8,400, citing higher Treasury yields driven by rising energy prices and an increased risk of a downturn over the next three to six months, CNBC noted.
Global markets. By Thursday, sentiment had steadied. Bloomberg reported Treasuries paring losses and US equity futures climbing as Warsh’s resolve reassured investors, with the two-year note easing a basis point to 4.72% after touching its highest level since 2024, and the 10-year and 30-year both slipping around two basis points.
Institutional positioning. The base case is now higher-for-longer with a live December hike. Markets are pricing one more 25-basis-point increase in 2026 followed by further tightening extending into 2027, per Seeking Alpha analysis of CME FedWatch pricing.
5. Frequently Asked Questions
Q1: What is the current Fed interest rate after the September 2026 meeting?
The federal funds target range is 3.75%–4.00%, raised by 25 basis points on 16 September 2026 in a unanimous 12-0 FOMC vote. It was the first US rate increase since July 2023 and partially reversed the 2025 easing cycle.
Q2: Will the Fed raise rates again in 2026?
The dot plot indicates 16 of 18 FOMC participants expect at least one further quarter-point increase before year-end, and four see two as possible. Markets currently price one additional hike in December, with more tightening possible into 2027.
Q3: How did Trump react to the Fed rate hike?
He demanded on Truth Social that US rates be cut to 1% or less, while telling reporters afterwards that he retains confidence in Chair Kevin Warsh and does not believe Warsh acted on White House instruction.
Q4: Why is the Fed hiking when inflation was supposed to be falling?
Fed projections put PCE inflation at 3.7% in 2026, well above the 2% target, driven substantially by energy prices. The Committee judged growth, productivity and capital investment strong enough to absorb tighter policy.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- SpaceX reportedly completed a public listing in 2026, with reporting describing a valuation in the trillion-dollar range — a landmark event that shifted the bulk of Musk’s net worth away from Tesla and into SpaceX/xAI.
- xAI was folded into SpaceX in February 2026, combining Tesla, X, SpaceX, and xAI under increasingly overlapping ownership and infrastructure.
- Tesla’s Q2 2026 revenue came in at roughly $28 billion with a thin 1.4% operating margin, as capital expenditure surged toward AI and robotics rather than core EV production.
- Musk has reportedly been living near xAI’s Colossus supercomputer campus in Memphis during its latest expansion — a callback to his “production hell” habits at Tesla in 2017–18.
- Regulatory scrutiny is intensifying on multiple fronts: xAI’s Grok image generator has drawn investigations in Europe, Asia, Australia, and California, and Democratic senators have called for a Pentagon probe into SpaceX’s ownership structure.
The Portfolio, Reorganized
Musk’s business empire in 2026 looks structurally different than it did even eighteen months ago. Tesla, once the dominant source of his net worth, now sits alongside a combined SpaceX-xAI entity (sometimes referred to as SpaceXAI) that reporting has valued well into the trillions following its 2026 public-market debut. That shift matters for how markets should think about “Musk risk” — it’s no longer a single-stock story concentrated in Tesla.
Tesla: Thin Margins, Heavy AI Bet
Tesla’s Q2 2026 results showed the tension in the company’s current strategy:
- Revenue of roughly $28.2 billion against an operating margin of just 1.4% — among the thinnest in years.
- Capital expenditure up sharply year-over-year, directed heavily at AI and robotics infrastructure rather than incremental EV capacity.
- Robotaxi (Cybercab) and Optimus humanoid robot programs remain the company’s stated long-term growth bets, with Musk targeting expanded autonomous deployment across a meaningful share of the U.S. by year-end.
xAI: Burning Cash to Build Compute
xAI, now under the SpaceX umbrella, has been reported to consume roughly $1 billion per month in compute and infrastructure spend against an estimated $500 million in annualized revenue — a deliberately loss-leading posture aimed at building frontier AI capability (Grok) at scale. The Memphis “Colossus” supercomputer campus is the physical center of that buildout, and Musk’s decision to base himself near the site during its latest expansion signals how central it is to his current priorities.
The Regulatory Overhang
Musk’s expanding footprint has drawn parallel scrutiny across jurisdictions:
- xAI’s Grok image generator is under investigation in multiple countries over its capacity to generate harmful synthetic imagery.
- Senate Democrats have pushed for a Pentagon review of SpaceX’s ownership structure over undisclosed foreign investment concerns.
Neither issue has produced conclusive regulatory action as of this writing, but both represent tail risk for a portfolio increasingly concentrated in Musk-controlled entities.
Why This Matters Beyond Musk Himself
Musk’s 2026 moves are a useful proxy for a broader market theme: the shift of enormous private capital into AI infrastructure at a pace that outstrips current revenue generation. Whether that pattern resolves into durable competitive advantage (as bulls argue) or a capital-intensive cautionary tale (as skeptics argue) is likely to be one of the defining market questions through 2027.
What is Elon Musk’s biggest 2026 business move?
The completion of SpaceX’s public listing and its merger with xAI, reportedly valuing the combined entity in the trillions and shifting the majority of Musk’s net worth away from Tesla for the first time.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Asian Markets Analysis: Navigating Volatility in China, Japan, and Singapore Stocks

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Fed Rate Hike Projections vs. Trump’s Interest Rate Policy: What Global Markets Expect Next

Singapore Stocks: The Ultimate Safe Haven for Markets and Finance in 2026?

Marie Gluesenkamp Perez: How a Former Shop Owner’s Moderate Politics Are Shaping Tech and Economy Bills

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Rolex Perpetual Market Value 2026: Why Luxury Watches Remain a Top Alternative Asset

PSX and KSE-100: How Pakistan’s Market Became One of Asia’s Best Performers

China Stocks vs. Japan Stocks: Where World Bank and IMF Data Point for 2027

Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

INTC Stock Forecast 2026: Can Intel’s Government-Backed Turnaround Hold?

Bitcoin Price Action in Q4 2026: Safe-Haven Asset or High-Risk Tech Play?

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Oil Surges as Strait of Hormuz Traffic Collapses Again

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

Global Chip Selloff Deepens: What’s Driving the Aug. 19 Semiconductor Rout

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025