
Investment
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

Executive Summary
Selecting mutual fund managers in Pakistan for optimal investment returns in 2026 requires a comprehensive evaluation of historical performance, governance structures, macroeconomic conditions, and sector-specific dynamics. The Pakistani mutual fund industry has experienced remarkable growth, expanding nearly sevenfold from Rs578 billion in 2019 to Rs3.93 trillion by June 2025, with Shariah-compliant funds growing particularly robustly at 6.7 times compared to conventional funds’ 5.2 times expansion.
This research synthesizes academic findings, market data, and performance metrics to identify the leading asset management companies positioned to deliver superior risk-adjusted returns in 2026, accounting for Pakistan’s evolving economic landscape, regulatory environment, and investor preferences.
Market Context: Pakistan’s Investment Landscape in 2026
Economic Fundamentals
Pakistan’s economy entering 2026 presents a complex yet opportunity-rich environment for mutual fund investors. Several macroeconomic factors are shaping investment prospects:
Monetary Policy Environment: Following aggressive policy rate tightening that peaked in 2023-2024, Pakistan has entered a rate-cutting cycle. The State Bank of Pakistan has reduced rates substantially, creating favorable conditions for equity markets while moderating returns on fixed-income instruments. This transition presents both opportunities and challenges for fund managers across different asset classes.
GDP Growth and Market Liquidity: GDP growth serves as a critical mediating factor between human capital development and mutual fund performance. As economic expansion accelerates through 2026, funds are benefiting from increased market liquidity, improved corporate earnings, and enhanced investor confidence. Infrastructure development, financial inclusion initiatives, and digital transformation are creating new investment opportunities.
Currency Stability: The Pakistani Rupee has demonstrated relative stability against major currencies, with exchange rates hovering around PKR 281-282 per USD as of early 2025. This stability, combined with controlled inflation trends (which moderated to 0.3% in April 2025), creates a more predictable environment for both domestic and foreign portfolio investment.
Stock Market Performance: The Pakistan Stock Exchange delivered exceptional returns in 2024, with equity funds showing an average 87% dollar-term return in the first half of FY2025 alone. Market capitalization increased by approximately 41.8% year-over-year through February 2025, reflecting strong investor sentiment and corporate profitability.
Regulatory Framework and Investor Protection
The Securities and Exchange Commission of Pakistan (SECP) maintains robust oversight of the asset management industry through comprehensive regulations including the Non-Banking Finance Companies (Establishment & Regulation) Rules, 2003, and the Non-Banking Finance Companies & Notified Entities Regulations, 2008. The commission’s transparent licensing process and continuous monitoring provide strong investor protection.
Recent regulatory developments include the extension of IFRS-9 applicability exemptions and ongoing digital transformation initiatives aimed at modernizing the sector. The SECP has been conducting focus group sessions with industry stakeholders to map the next phase of reforms, prioritizing digital innovation and investor accessibility.
Top 10 Mutual Fund Managers in Pakistan for 2026
Based on comprehensive analysis of assets under management, performance track records, governance quality, product diversity, and strategic positioning, the following asset management companies represent the most compelling options for investors seeking optimal returns in 2026:
1. Al Meezan Investment Management Limited
Focus: 100% Shariah-Compliant Investment
Assets Under Management: Over USD 262 million (with continued growth into 2025)
Client Base: Over 200,000 investors nationwide
Industry Position: Pakistan’s largest Islamic asset management company
Why Al Meezan Leads in 2026:
Al Meezan has established itself as the undisputed leader in Islamic investment management in Pakistan. The company’s commitment to strict Shariah compliance, overseen by a dedicated Shariah Supervisory Board, has earned it the trust of investors seeking both financial returns and religious adherence.
Key Strengths:
- Award Recognition: Winner of “Asset Management Company of the Year Gold” at the 9th IFFSA Awards, demonstrating international recognition of excellence
- Performance Track Record: Islamic mutual funds under Al Meezan management have demonstrated competitive returns compared to conventional counterparts, particularly during periods of market volatility
- Product Diversity: Comprehensive portfolio including Meezan Islamic Fund, Meezan Islamic Income Fund, Meezan Energy Fund, Meezan Sovereign Fund, and various Daily Income Plans
- Digital Innovation: User-friendly mobile app and online portal enabling convenient account management, fund tracking, and transactions from anywhere
- Market Positioning: With Shariah-compliant funds now constituting 44% of Pakistan’s mutual fund industry (up from 39% in 2019), Al Meezan is ideally positioned to capture growing demand
Best For: Investors seeking Shariah-compliant investments with strong governance, proven performance, and comprehensive product offerings. Particularly suitable for conservative to moderate risk profiles prioritizing ethical investing.
Notable Funds:
- Meezan Islamic Income Fund: Consistent performer in fixed-income category
- Meezan Energy Fund: Sector-focused equity exposure
- Meezan Daily Income Plans: Multiple variants for different income needs
- Meezan Rozana Amdani Fund: Averaging ~14% annual returns for money market exposure
2. HBL Asset Management Company Limited
Affiliation: Habib Bank Limited (Pakistan’s largest private bank)
Assets Under Management: Among the largest portfolios in Pakistan
Industry Position: Top-tier comprehensive asset manager
Why HBL AMC Stands Out:
Backed by the financial strength and extensive network of HBL, this asset management company combines deep market expertise with institutional credibility. HBL AMC manages one of the largest mutual fund portfolios in Pakistan, serving both retail and institutional clients with customized investment solutions.
Key Strengths:
- Comprehensive Product Range: Offers equity funds (including HBL Growth Fund and HBL Equity Fund), income funds, money market funds, and Shariah-compliant options
- Institutional Backing: Benefits from HBL’s extensive branch network, research capabilities, and market intelligence
- Performance Consistency: Historically strong returns with particular strength in equity fund management
- Risk Management Expertise: Deep experience managing both equity and fixed-income portfolios through various market cycles
- Hybrid Approach: Offers both conventional and Islamic investment options, catering to diverse investor preferences
Best For: Investors seeking institutional-grade management with the backing of Pakistan’s largest private bank. Suitable for aggressive growth seekers (equity funds) and conservative investors (money market funds) alike.
Notable Funds:
- HBL Growth Fund: High-growth equity fund for capital appreciation
- HBL Equity Fund: Diversified equity exposure
- HBL Islamic funds: Shariah-compliant options across categories
3. UBL Fund Managers Limited
Affiliation: United Bank Limited
Industry Recognition: Multiple awards and industry accolades
Technology Edge: Advanced digital investment platforms
Why UBL Fund Managers Excels:
UBL Fund Managers has distinguished itself through innovation, particularly in digital investment solutions. The company’s mobile app, SIP calculators, and online platforms have democratized access to mutual fund investing across Pakistan.
Key Strengths:
- Proven Track Record: Team of highly skilled professionals with demonstrated expertise in managing high-profit investments
- Digital Leadership: Industry-leading online investment platforms enabling secure, convenient investing from anywhere in Pakistan
- Product Diversity: Comprehensive range including UBL Islamic Stock Fund, UBL Stock Advantage Fund, retirement savings funds, and money market funds
- Performance History: Strong historical returns, with equity funds like ABL Stock Fund averaging 25% returns in recent years
- Investor Education: Robust educational resources and fund explorer tools helping investors make informed decisions
Best For: Tech-savvy investors seeking modern digital investing experiences combined with strong performance track records. Suitable for both aggressive growth investors and those seeking retirement planning solutions.
Notable Funds:
- UBL Stock Advantage Fund: High-growth equity fund
- UBL Islamic Stock Fund: Shariah-compliant equity exposure
- UBL Retirement Savings Funds: Long-term wealth accumulation with tax benefits
4. NBP Fund Management Limited
Sponsors: National Bank of Pakistan & Fullerton Fund Management Group (Singapore)
Assets Under Management: Over Rs. 560 billion (as of latest data)
Rating: AM1 (Very High Quality) by PACRA – Highest Investment Management Rating in Pakistan
Industry Awards: “The Best Asset Management Company For The Year” by CFA Society Pakistan
Why NBP Funds Commands Respect:
The unique partnership between National Bank of Pakistan and Singapore’s Fullerton Fund Management Group (a Temasek Holdings subsidiary) provides NBP Funds with both local market expertise and international best practices in asset management.
Key Strengths:
- Exceptional Performance: Several funds demonstrating outperformance against benchmarks; for example, NISF showing 14.9% p.a. return versus 14.0% benchmark
- Product Breadth: Managing 26 open-ended funds, 4 pension funds, and several investment advisory mandates (SMAs)
- International Expertise: Access to Fullerton’s global investment methodologies and risk management frameworks
- Innovation Leadership: First AMC in Pakistan to launch NPay (online payment solution) and various payment convenience features
- Award-Winning Funds: NBP Islamic Savings Fund won Refinitiv Lipper Fund Award in both 5-year and 10-year PKR Global Fund Award Categories
- Accessibility: Extensive distribution network and customer service infrastructure
Best For: Investors seeking institutional-quality management with international standards, strong performance track records, and comprehensive product options across risk profiles.
Notable Funds:
- NBP Islamic Savings Fund: Award-winning Shariah-compliant option
- NISF (NBP Islamic Stock Fund): Strong equity performance with 14.9% p.a. returns
- Various income and money market funds with competitive yields
5. JS Investments Limited
Establishment: 1995 (Pakistan’s oldest private sector AMC)
Assets Under Management: PKR 154.8 billion (including advisory SMA, as of December 2025)
Affiliation: JS Bank Limited (subsidiary)
Market Capitalization: PKR 2.600 billion
Why JS Investments Maintains Legacy Excellence:
As Pakistan’s pioneering private sector asset management company, JS Investments combines nearly three decades of experience with innovative product development. The company’s founding partnership with INVESCO PLC and International Finance Corporation established high governance and operational standards that persist today.
Key Strengths:
- Historical Track Record: Nearly 30 years of continuous operation through multiple market cycles
- Product Innovation: First to introduce various investment vehicles including Exchange Traded Funds (JS Momentum Factor ETF)
- Comprehensive Services: Licensed by SECP for asset management, investment advisory, REIT management, and private equity/venture capital fund management
- Professional Management: Strong fund management team with proven expertise
- Diversified Offerings: Mutual funds, voluntary pension schemes, separately managed accounts, ETFs, REITs, and private equity funds
Best For: Sophisticated investors seeking diversified investment solutions, including alternative investments beyond traditional mutual funds. Suitable for those valuing institutional experience and product innovation.
Notable Products:
- JS Momentum Factor ETF: Systematic, factor-based equity exposure
- JS Islamic fixed-term and savings funds
- JS Large Cap Fund: Blue-chip equity focus
- Separately Managed Accounts for high-net-worth individuals and institutions
6. National Investment Trust Limited (NIT)
Establishment: 1962
Type: Government-owned trust
Industry Position: Pakistan’s first and oldest asset management company
Investor Base: Large, diverse investor base with decades of accumulated trust
Why NIT Endures:
NIT’s longevity and government backing provide unique stability advantages. As Pakistan’s first mutual fund company, it has established deep institutional relationships and broad market penetration, particularly among conservative and retired investors.
Key Strengths:
- Legacy and Trust: Over 60 years of continuous operation builds investor confidence
- Government Backing: Provides implicit stability, particularly valued during market volatility
- SECP Compliance Excellence: Exemplary regulatory compliance and transparency
- Broad Distribution: Extensive reach across Pakistan through government and institutional channels
- Performance Consistency: NIT Money Market Fund showing strong returns (22.6193% three-year annualized return in recent periods)
Best For: Conservative investors seeking stability, retirees prioritizing capital preservation with steady income, and those valuing government-affiliated institutional strength over aggressive growth.
Notable Funds:
- NIT Equity Market Fund: Long-standing equity fund with proven track record
- NIT Islamic Income Fund: Shariah-compliant fixed income option
- NIT Money Market Fund: High-performing liquid investment option
7. MCB Asset Management Company Limited
Group Affiliation: MCB Bank + Arif Habib Group partnership
Industry Position: Top-tier comprehensive asset manager
Market Focus: Retail and institutional clients
Why MCB-Arif Habib Partnership Excels:
The strategic partnership between MCB Bank (one of Pakistan’s most respected financial institutions) and Arif Habib Group (a diversified financial services conglomerate) creates synergies in market access, research capabilities, and product development.
Key Strengths:
- Dual Expertise: Combines MCB’s retail banking strength with Arif Habib’s capital market expertise
- Comprehensive Services: Mutual funds, advisory services, and pension plan management
- Personalized Solutions: Tailored investment strategies for diverse client needs
- Research Excellence: Access to both institutions’ research and market intelligence
- Product Range: Balanced offerings across conventional and Islamic categories
Best For: Investors seeking personalized investment strategies backed by dual institutional strength. Particularly suitable for those valuing convenience (through MCB’s extensive branch network) combined with sophisticated investment approaches.
Notable Funds:
- MCB Pakistan Income Fund: Fixed-income focus
- MCB Pakistan Cash Management Fund: Liquid money market exposure
- Various equity and balanced funds
8. Pak Oman Asset Management Company Limited
Establishment: June 2006
Sponsors: Joint venture between Sultanate of Oman and Government of Pakistan
Strategic Focus: Strengthening economic growth through strategic investment services
Why Pak Oman Offers Unique Value:
The international partnership structure provides Pak Oman with diverse perspectives and access to Middle Eastern investment approaches while maintaining deep understanding of Pakistani market dynamics.
Key Strengths:
- International Partnership: Unique Omani-Pakistani collaboration brings diverse expertise
- Strategic Government Support: Government backing provides stability
- Comprehensive Product Portfolio: Range of funds across risk profiles
- Middle Eastern Investment Approaches: Access to Islamic finance expertise from Gulf region
- Competitive Performance: Strong track records across multiple fund categories
Best For: Investors seeking international partnership benefits, those interested in Middle Eastern investment methodologies, and investors valuing government co-sponsorship for added security.
9. Lakson Investments Limited
Group Affiliation: Lakson Group
Industry Position: Among top 10 with over 50 branches across Pakistan
Management Approach: Both Shariah-compliant and conventional options
Why Lakson Delivers:
Backed by the diversified Lakson Group’s industrial and commercial strength, Lakson Investments offers sophisticated investment products with strong research backing and nationwide service presence.
Key Strengths:
- Diversified Group Backing: Lakson Group’s multi-sector presence provides unique market insights
- Extensive Network: Over 50 branches ensure accessibility across Pakistan
- Risk-Sharing Structure: Proportionate capital pooling reduces individual risk while maximizing profit potential
- In-depth Research: Strategic asset allocation backed by comprehensive market analysis
- Balanced Offerings: Mix of growth-oriented, capital preservation, and Shariah-compliant products
Best For: Investors seeking industrial group backing, those prioritizing nationwide accessibility, and investors interested in balanced approaches combining growth and preservation.
10. ABL Asset Management Company Limited
Affiliation: Allied Bank Limited
Market Focus: Diverse fund offerings across risk categories
Industry Recognition: Consistent performance across fund categories
Why ABL AMC Merits Consideration:
ABL Asset Management has built a reputation for consistent performance, particularly in equity funds and money market funds. The company benefits from Allied Bank’s extensive network and research capabilities.
Key Strengths:
- Performance Excellence: ABL Stock Fund averaging approximately 25% returns in recent years
- Money Market Leadership: ABL Cash Fund showing 22.0375% three-year annualized return
- Research Capabilities: Strong analytical team and market research
- Product Diversity: Comprehensive range across equity, income, and money market categories
- Banking Network Advantage: Leverages Allied Bank’s branch presence for distribution
Best For: Growth-oriented investors seeking strong equity fund performance, liquidity seekers prioritizing money market funds with superior returns, and those valuing banking network accessibility.
Notable Funds:
- ABL Stock Fund: High-performing equity fund (~25% average returns)
- ABL Cash Fund: Leading money market fund (22.0375% three-year returns)
- ABL Islamic Funds: Shariah-compliant alternatives across categories
Performance Analysis: Fund Categories and Expected Returns
Money Market Funds
Money market funds have consistently outperformed bank deposits, delivering three-year annualized returns in the 20-22% range as of mid-2025. Recent 365-day average returns stood at approximately 20.50%, making them attractive for capital preservation with significantly better returns than traditional savings accounts.
Top Performers:
- ABL Cash Fund: 22.0375% (3-year annualized)
- NIT Money Market Fund: 22.6193% (3-year annualized)
- Meezan Rozana Amdani Fund: ~14% (average annual return)
Expected 2026 Outlook: As policy rates stabilize or decline further, money market returns may moderate but should remain significantly above inflation, offering real positive returns.
Income Funds
Income funds, investing in fixed-income securities like TFCs, TDRs, and government bonds, have delivered strong annualized returns often comparable to money market funds. The category saw 21.81% AUM increase in FY2022, reflecting growing investor confidence.
Top Performers:
- Alfalah GHP Income Fund: 22.3573% (3-year annualized as of May 2025)
- NBP Islamic Savings Fund: Award-winning consistent performance
- Meezan Islamic Income Fund: Strong Shariah-compliant income generation
Expected 2026 Outlook: Recent 365-day average returns of approximately 19.22% should remain attractive, particularly for conservative investors seeking regular income streams.
Equity Funds
Equity funds demonstrated exceptional volatility and returns, with an 87% dollar-term return in H1 FY2025 alone. While high-risk, these funds offer substantial capital appreciation potential during favorable market conditions.
Top Performers:
- HBL Growth Fund: Strong capital appreciation track record
- UBL Stock Advantage Fund: High-growth equity focus
- ABL Stock Fund: ~25% average returns in recent years
- JS Large Cap Fund: Blue-chip equity exposure
Expected 2026 Outlook: With Pakistan Stock Exchange showing strong fundamentals and market capitalization growth of ~41.8% YoY, equity funds remain attractive for long-term growth, though with higher volatility.
Islamic/Shariah-Compliant Funds
Islamic funds have demonstrated competitive or superior performance compared to conventional counterparts. Shariah-compliant money market funds averaged 19.50% in 365-day returns, while equity funds averaged 80.10% (as of May 2025).
Top Performers:
- Al Meezan’s comprehensive Islamic fund range
- NBP Islamic Savings Fund (Lipper Award winner)
- HBL Islamic Funds across categories
- UBL Islamic Stock Fund
Expected 2026 Outlook: With Shariah-compliant funds now representing 44% of industry AUM and growing faster than conventional funds, this category offers both ethical alignment and competitive returns.
Key Performance Drivers for 2026
1. Corporate Governance Excellence
Research demonstrates that ownership structure and governance mechanisms significantly impact asset allocation strategies and risk-adjusted performance. Fund managers operating under stronger governance frameworks exhibit better diversification practices and improved returns.
What Investors Should Evaluate:
- Board composition and independence of directors
- Transparency in reporting and disclosure practices
- Shariah board qualifications (for Islamic funds)
- Sponsor strength and financial backing
- Regulatory compliance history
2. Macroeconomic Positioning
GDP growth, exchange rate stability, inflation control, and interest rate policies will remain pivotal through 2026. Funds positioned to capitalize on infrastructure development, financial inclusion, and digital transformation may offer superior returns.
Favorable Economic Factors for 2026:
- Successful IMF program completion and continued disbursements
- Stable political environment
- PKR stability against USD (around 281-282 PKR/USD)
- Continued policy rate reductions
- Expected shift toward equities as rates stabilize
3. Technology Integration and AI
The use of advanced tools like artificial intelligence for forecasting market trends and optimizing portfolios is gaining traction. Fund managers leveraging predictive analytics may gain competitive advantages in identifying undervalued securities and timing market entries.
Digital Advantages:
- Mobile apps for convenient investing (Al Meezan, UBL, NBP)
- Roshan Digital Account integration for overseas Pakistanis
- Online payment solutions (NBP’s NPay)
- SIP calculators and portfolio tracking tools
- Automated rebalancing and allocation
4. ESG Integration
Retail investors in Pakistan increasingly prioritize environmental, social, and governance (ESG) criteria, with social factors being particularly influential. Fund managers integrating ESG screening attract larger asset inflows and build stronger reputational capital.
5. Behavioral Excellence
Institutional investor behavior analysis indicates that experienced fund managers integrate sentiment analysis, data interpretation, and risk management techniques more effectively than less-experienced counterparts. Managers with proven track records across multiple market cycles demonstrate superior decision-making.
Investment Strategy Recommendations for 2026
For Conservative Investors (Capital Preservation Focus)
Recommended Allocation:
- 60-70% Money Market Funds (prioritize NBP, ABL, NIT options)
- 20-30% Income Funds (focus on award-winning funds like NBP Islamic Savings)
- 10-15% Stable Equity Funds (blue-chip focused like JS Large Cap)
Best Fund Managers: Al Meezan, NBP Funds, NIT, HBL AMC
Expected Annual Return: 15-20% with low volatility
For Moderate Investors (Balanced Growth and Preservation)
Recommended Allocation:
- 30-40% Money Market/Income Funds
- 40-50% Equity Funds (diversified across sectors)
- 10-20% Balanced/Asset Allocation Funds
Best Fund Managers: HBL AMC, UBL Fund Managers, MCB AMC, Lakson
Expected Annual Return: 20-35% with moderate volatility
For Aggressive Investors (Maximum Growth Focus)
Recommended Allocation:
- 70-80% Equity Funds (mix of large-cap and growth funds)
- 15-20% Sector-Specific Funds (energy, technology, financial)
- 5-10% Money Market (emergency liquidity)
Best Fund Managers: HBL AMC, UBL Fund Managers, ABL AMC, JS Investments
Expected Annual Return: 35-60%+ with high volatility
For Islamic Finance Seekers (Shariah-Compliant Only)
Recommended Allocation:
- Based on risk profile but exclusively Shariah-compliant
- Diversification across Islamic equity, income, and money market
Best Fund Managers: Al Meezan (undisputed leader), NBP Funds, HBL AMC, UBL Fund Managers
Expected Annual Return: Competitive with conventional funds across risk profiles
For Retirement Planning (Long-Term Wealth Accumulation)
Recommended Approach:
- Voluntary Pension Schemes (VPS) for tax benefits
- Systematic Investment Plans (SIP) for rupee-cost averaging
- Gradual shift from equity to debt as retirement approaches
Best Fund Managers: UBL Fund Managers, NBP Funds, JS Investments, HBL AMC
Expected Annual Return: 20-40% depending on allocation and time horizon
Due Diligence Framework: Evaluating Fund Managers
Quantitative Metrics
Performance Indicators:
- Sharpe Ratio: Risk-adjusted return measurement (higher is better)
- Alpha Generation: Excess returns above benchmark (positive alpha indicates skill)
- Beta: Volatility relative to market (lower for conservative investors)
- Standard Deviation: Absolute volatility measure
- Downside Deviation: Risk during market downturns
- Maximum Drawdown: Worst peak-to-trough decline
Cost Analysis:
- Total Expense Ratio (TER): Annual operating costs (lower is better; typically 1-2.5%)
- Management Fees: Fund manager compensation
- Front-End Load: Entry charges (typically 0-3%)
- Back-End Load: Exit charges (typically 0-1.5%)
- Sales & Marketing Expenses: Distribution costs
Qualitative Factors
Management Quality:
- Track record across market cycles
- Experience and educational credentials of fund managers
- Turnover rate of investment team
- Investment philosophy and process consistency
- Communication transparency with investors
Institutional Strength:
- Sponsor financial stability
- Assets under management growth trajectory
- Regulatory compliance and rating (PACRA AM ratings)
- Industry awards and recognition
- Customer service quality and accessibility
Product Suitability:
- Investment mandate alignment with personal goals
- Liquidity terms (redemption timeline typically 7 business days)
- Minimum investment requirements
- Dividend distribution vs. growth options
- Tax implications (Section 62 benefits for certain holdings)
Risk Considerations and Mitigation
Market Risk
All mutual funds are subject to market volatility. Equity funds can experience substantial declines during market corrections (historical drawdowns of 20-30% not uncommon).
Mitigation: Diversification across asset classes, long-term investment horizon, systematic investment plans
Credit Risk
Income and money market funds face risk of issuer default on fixed-income securities.
Mitigation: Choose funds with higher credit quality portfolios (AAA-rated securities), diversified holdings
Liquidity Risk
While most mutual funds offer daily redemptions, processing typically takes 7 business days.
Mitigation: Maintain emergency fund separate from mutual fund investments, diversify across fund categories
Concentration Risk
Over-allocation to single fund manager, asset class, or sector creates vulnerability.
Mitigation: Spread investments across 3-5 fund managers, diversify across asset classes and sectors
Regulatory and Political Risk
Policy changes, tax adjustments, or political instability can impact fund performance.
Mitigation: Stay informed on regulatory developments, choose fund managers with strong government relationships, diversify geographically if possible
Inflation Risk
If fund returns don’t exceed inflation, purchasing power declines despite nominal gains.
Mitigation: Focus on equity and balanced funds for long-term holdings, regularly review real returns
Fee Risk
High expense ratios erode returns over time, particularly compounded over long periods.
Mitigation: Compare TERs across similar funds, prioritize low-cost options when performance is comparable
Practical Implementation Guide
Step 1: Self-Assessment
- Define investment goals (retirement, education, home purchase, wealth accumulation)
- Determine investment timeline (short-term <3 years, medium-term 3-7 years, long-term >7 years)
- Assess risk tolerance (conservative, moderate, aggressive)
- Evaluate liquidity needs (how much must remain accessible)
- Decide on Islamic vs. conventional preference
Step 2: Fund Manager Selection
- Shortlist 3-5 fund managers from top 10 based on your preferences
- Review their specific fund offerings matching your profile
- Compare performance across at least 3-year periods (longer preferred)
- Evaluate expense ratios and fee structures
- Read offering documents and fund fact sheets thoroughly
Step 3: Account Opening
Required Documentation:
- Valid CNIC (original and photocopy)
- Bank account details
- Contact information
- Zakat exemption certificate (CZ-50) if applicable
- Tax exemption documentation if relevant
Opening Channels:
- Direct at AMC offices
- Through bank branches (for bank-affiliated AMCs)
- Online portals and mobile apps (increasingly available)
- Authorized distributors and financial advisors
Step 4: Investment Execution
One-Time Lump Sum:
- Suitable for sudden windfalls or redirecting existing savings
- Market timing risk higher
- Lower transaction costs
Systematic Investment Plan (SIP):
- Regular monthly/quarterly investments
- Rupee-cost averaging benefits
- Builds investment discipline
- Reduces market timing risk
Step 5: Ongoing Monitoring
Monthly Tasks:
- Review fund NAV and portfolio value
- Monitor market and economic news
- Ensure SIP deductions processing correctly
Quarterly Tasks:
- Review fund manager reports
- Compare performance against benchmarks and peers
- Assess whether allocation still matches goals
Annual Tasks:
- Comprehensive portfolio review
- Rebalancing if asset allocation drifted significantly
- Tax planning and documentation
- Goal progress assessment
Step 6: Rebalancing and Adjustments
When to Rebalance:
- Asset allocation drifts >10% from target
- Significant life changes (marriage, children, job change)
- Major market shifts changing risk/return profiles
- Approaching major financial goals (reduce risk)
How to Rebalance:
- Conversion between funds (usually tax-efficient)
- Redirect new investments to underweighted categories
- Partial redemptions from overweighted positions
Tax Optimization Strategies
Section 62 Benefits
Investments in certain retirement and pension funds qualify for tax rebates under Section 62 of the Income Tax Ordinance. Consult tax advisors for eligibility and maximum benefit amounts.
Zakat Management
Muslim investors must manage Zakat obligations on mutual fund holdings. Provide CZ-50 certificate to fund managers if Zakat already paid elsewhere to avoid automatic deduction.
Capital Gains Tax
Understand capital gains tax implications for fund redemptions. Holding periods and fund types influence tax treatment.
Withholding Tax
Some distributions subject to withholding tax. Ensure proper documentation to minimize tax burden.
Special Considerations for Different Investor Segments
Overseas Pakistanis
Roshan Digital Account Integration: Many top AMCs (Al Meezan, NBP, UBL, HBL) offer Roshan Digital Account compatibility, enabling overseas Pakistanis to invest easily in Shariah-compliant and conventional mutual funds.
Repatriation: Understand repatriation rules and procedures for returning funds abroad.
Currency Risk: Consider PKR exchange rate volatility against your residence currency.
Young Professionals and Students
Start Small: Many funds allow investments as low as Rs. 500-1,000, enabling early investment habit formation.
Focus on Growth: Longer time horizon allows for higher equity allocation and growth focus.
Digital Platforms: Leverage mobile apps and online tools for convenient, tech-enabled investing.
Retirees and Pre-Retirees
Capital Preservation Priority: Emphasize money market and income funds over volatile equity funds.
Regular Income: Consider funds with regular dividend distribution options.
Liquidity: Maintain higher allocation to liquid funds for emergency needs.
Gradual Transition: Shift from equity to debt as retirement approaches.
High-Net-Worth Individuals
Separately Managed Accounts (SMAs): Consider personalized portfolio management offered by top AMCs like JS Investments, NBP Funds, and HBL AMC.
Alternative Investments: Explore REITs, private equity, and venture capital funds offered by select managers.
Tax Planning: Sophisticated tax optimization strategies with professional advisors.
Estate Planning: Integrate mutual fund holdings into comprehensive wealth transfer plans.
Emerging Trends Shaping 2026 Returns
Digital Transformation Acceleration
Mobile investing, AI-powered recommendations, and robo-advisory services are democratizing access and improving decision-making quality.
ESG and Sustainable Investing Mainstreaming
Growing investor demand for ESG-screened funds is pushing fund managers to integrate sustainability criteria systematically.
Alternative Investment Expansion
REITs, ETFs (like JS Momentum Factor ETF), and private equity are expanding beyond traditional mutual funds, offering diversification opportunities.
Fintech Integration
Partnerships between AMCs and fintech platforms are creating seamless investment experiences and reducing friction.
Regulatory Modernization
SECP’s ongoing reforms around digital transformation, investor protection, and market development are creating more robust industry infrastructure.
Common Mistakes to Avoid
1. Chasing Past Performance
Historical returns don’t guarantee future results. Many investors pile into last year’s top performers just before mean reversion occurs.
Better Approach: Evaluate consistency across multiple cycles, risk-adjusted returns, and management quality.
2. Ignoring Expense Ratios
High fees compound over time, eroding substantial portions of returns, particularly over decades.
Better Approach: Compare TERs among similar funds; even 0.5% difference compounds to large sums over 20-30 years.
3. Market Timing Attempts
Trying to time market entries and exits typically results in buying high and selling low.
Better Approach: Use systematic investment plans for rupee-cost averaging, maintain long-term perspective.
4. Lack of Diversification
Concentrating in single fund manager, asset class, or sector creates unnecessary risk.
Better Approach: Spread across multiple managers, asset classes, and investment styles.
5. Emotional Decision-Making
Panic selling during market declines or greed-driven buying during euphoria leads to poor outcomes.
Better Approach: Establish investment policy, stick to plan regardless of market emotions, rebalance systematically.
6. Neglecting Due Diligence
Investing based on tips, advertisements, or friend recommendations without proper research.
Better Approach: Read offering documents, understand fund strategy, evaluate fund manager credentials and track record.
7. Ignoring Tax Implications
Failing to optimize tax treatment can significantly reduce net returns.
Better Approach: Consult tax advisors, use Section 62 benefits, manage Zakat appropriately, understand capital gains implications.
8. Setting Unrealistic Expectations
Expecting consistent 50%+ annual returns or never experiencing losses creates disappointment and poor decisions.
Better Approach: Understand historical return ranges, accept volatility as part of growth, set realistic long-term expectations.
Conclusion: Building a Winning Portfolio for 2026
The Pakistani mutual fund industry presents compelling opportunities for investors seeking superior returns in 2026, with the market’s remarkable growth trajectory, deepening product diversity, and strengthening regulatory framework creating favorable conditions across risk profiles.
Key Takeaways:
- No Single Best Manager: Different fund managers excel in different categories. Al Meezan dominates Islamic funds, while HBL AMC and UBL Fund Managers excel in equity management, and NBP Funds leads in comprehensive offerings with international expertise.
- Diversification is Essential: Spreading investments across 3-5 fund managers and multiple asset classes provides optimal risk-adjusted returns.
- Align with Goals and Risk Tolerance: Conservative investors should emphasize money market and income funds, while aggressive investors can weight toward equity funds for maximum growth potential.
- Governance and Transparency Matter: Prioritize fund managers with strong institutional backing, proven governance frameworks, transparent reporting, and exemplary regulatory compliance.
- Technology Enhances Experience: Leverage digital platforms, mobile apps, and online tools offered by leading AMCs for convenient investment management.
- Islamic Options Are Competitive: Shariah-compliant funds now demonstrate performance parity or superiority to conventional alternatives while meeting religious requirements.
- Monitor and Rebalance: Regular portfolio reviews, systematic rebalancing, and adjustments based on life changes optimize long-term outcomes.
- Long-Term Perspective Wins: Despite short-term volatility, disciplined long-term investors consistently outperform market timers and short-term speculators.
Final Recommendations by Investor Profile:
- Conservative Wealth Preservation: Al Meezan (Islamic focus) or NBP Funds (comprehensive) with emphasis on money market and income funds
- Balanced Growth Seekers: HBL AMC or UBL Fund Managers with diversified allocation across equity and fixed-income
- Aggressive Growth Maximizers: UBL Fund Managers or ABL AMC with equity fund concentration and sector-specific exposure
- Islamic Finance Required: Al Meezan Investment Management (undisputed leader in Shariah-compliant investing)
- International Standards Preference: NBP Funds (Singapore partnership) or JS Investments (legacy international collaboration)
- Retirement Planning: UBL Fund Managers or HBL AMC utilizing voluntary pension schemes with systematic investment plans
The optimal 2026 mutual fund strategy recognizes that Pakistan’s economic transition, regulatory modernization, and market maturation create a rich environment for disciplined investors. By carefully selecting from the top-tier fund managers identified in this research, maintaining appropriate diversification, staying committed to long-term plans, and adapting to changing circumstances, investors can position themselves to capture optimal risk-adjusted returns while navigating the opportunities and challenges ahead.
Appendix: Additional Resources
Regulatory Bodies
- Securities and Exchange Commission of Pakistan (SECP): www.secp.gov.pk
- Pakistan Stock Exchange (PSX): www.psx.com.pk
- Mutual Funds Association of Pakistan (MUFAP): www.mufap.com.pk
Research and Data Sources
- PACRA (Pakistan Credit Rating Agency): Fund manager ratings
- VIS (Pakistan’s international credit rating agency): Research reports
- CFA Society Pakistan: Industry analysis and awards
- MUFAP Industry Reports: Comprehensive statistical data
Educational Resources
- Investor education portals on individual AMC websites
- SECP Investor Education initiatives
- Fund fact sheets and offering documents (mandatory reading)
- Financial advisors and certified financial planners
Investment Tools
- SIP calculators (available on most AMC websites)
- Fund comparison tools on MUFAP website
- NAV tracking applications
- Portfolio management tools in AMC mobile apps
Tax and Legal Guidance
- Federal Board of Revenue (FBR): www.fbr.gov.pk
- Tax consultants and chartered accountants
- Legal advisors for estate planning and complex structures
Disclaimer: This research is for informational purposes only and does not constitute financial advice. Past performance does not guarantee future results. All investments carry risk, including potential loss of principal. Investors should conduct their own due diligence, assess their personal financial situations, consult with licensed financial advisors, and read all offering documents before making investment decisions. The rankings and recommendations provided represent analysis based on available information as of January 2026 and may not reflect the most current developments. Individual fund performance can vary significantly from historical averages.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The Investment matters a lot in 2026 because global economic growth is becoming more uneven, capital is increasingly sensitive to financing costs, and investors must distinguish a convincing story from an investable price. This guide focuses on research methods and risks rather than predictions of guaranteed returns. The IMF October 2026 outlook projects 3.1% global growth and 4.7% inflation for 2026, while the IMF financial-stability assessment warns that market resilience coexists with important vulnerabilities.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind investing during high inflation is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
First measure the real return
A portfolio that gains 8% while consumer prices rise 10% has lost purchasing power before fees and taxes. Approximate real return is nominal return minus inflation; the exact calculation divides one plus nominal return by one plus inflation. This changes what counts as success: protecting spending power may matter more than chasing the highest headline yield. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Cash, bonds and inflation linkage
Cash covers emergencies but can lose value if interest is below inflation. Short-duration high-quality bonds generally face less price sensitivity to changing rates than long-duration bonds, but reinvestment and credit risk remain. Inflation-linked securities may help when matched to the relevant price index; availability and tax treatment differ by market. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Equities are productive assets, not magic protection
Companies with pricing power and manageable debts may pass through higher costs, but consumers may resist price increases and valuations can fall when interest rates rise. Diversified low-cost equity funds spread company-specific exposure; they still carry market risk. Review fees, holdings and underlying concentration, especially where major indices are heavily weighted toward a few technology companies. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Real assets and commodities: examine costs
Real estate faces financing, maintenance, vacancy and liquidity risks. Gold does not generate income, and commodity products can behave differently from spot commodity prices because of futures roll and fund structure. Compare net, after-tax outcomes; physical ownership also involves custody costs. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
A practical framework for Pakistan
Set out upcoming expenses in rupees and foreign currency, then segment assets by time horizon. Avoid high-interest debt before taking speculative risks; verify lawful distribution and taxes for foreign securities; test scenarios for inflation, interest rates and currency weakness. The portfolio should be able to survive an adverse year without forced sales. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The AI capital-spending boom is driving a concentrated global trade expansion. Pakistan cannot assume it will capture semiconductor profits, but it can compete for selective services, implementation and skills-intensive opportunities. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
The evidence for an extraordinary AI hardware cycle
For the evidence for an extraordinary ai hardware cycle, The spectacular rise of AI-enabling goods trade should not be confused with a universal productivity breakthrough. Buying servers is an input; measurable economic gains require organizations to redesign processes and solve problems for customers.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the evidence for an extraordinary ai hardware cycle, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Why AI-enabled trade is geographically concentrated
For why ai-enabled trade is geographically concentrated, Pakistan’s competitive case is more likely to begin in software implementation, business-process services, local-language tools and industry-specific integration than in cutting-edge semiconductor fabrication. That is an assessment of attainable starting conditions, not a forecast of guaranteed success.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why ai-enabled trade is geographically concentrated, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Pakistan’s realistic position in the value chain
For pakistan’s realistic position in the value chain, A healthy AI investment program measures output per worker, error rates, export revenues and customer retention. If those indicators do not improve, expenditure on software licenses may merely raise operating costs.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For pakistan’s realistic position in the value chain, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Electricity and connectivity as economic constraints
For electricity and connectivity as economic constraints, The spectacular rise of AI-enabling goods trade should not be confused with a universal productivity breakthrough. Buying servers is an input; measurable economic gains require organizations to redesign processes and solve problems for customers.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For electricity and connectivity as economic constraints, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What would signal a sustainable AI payoff
For what would signal a sustainable ai payoff, Pakistan’s competitive case is more likely to begin in software implementation, business-process services, local-language tools and industry-specific integration than in cutting-edge semiconductor fabrication. That is an assessment of attainable starting conditions, not a forecast of guaranteed success.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what would signal a sustainable ai payoff, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
The AI capital-spending boom is driving a concentrated global trade expansion. Pakistan cannot assume it will capture semiconductor profits, but it can compete for selective services, implementation and skills-intensive opportunities. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
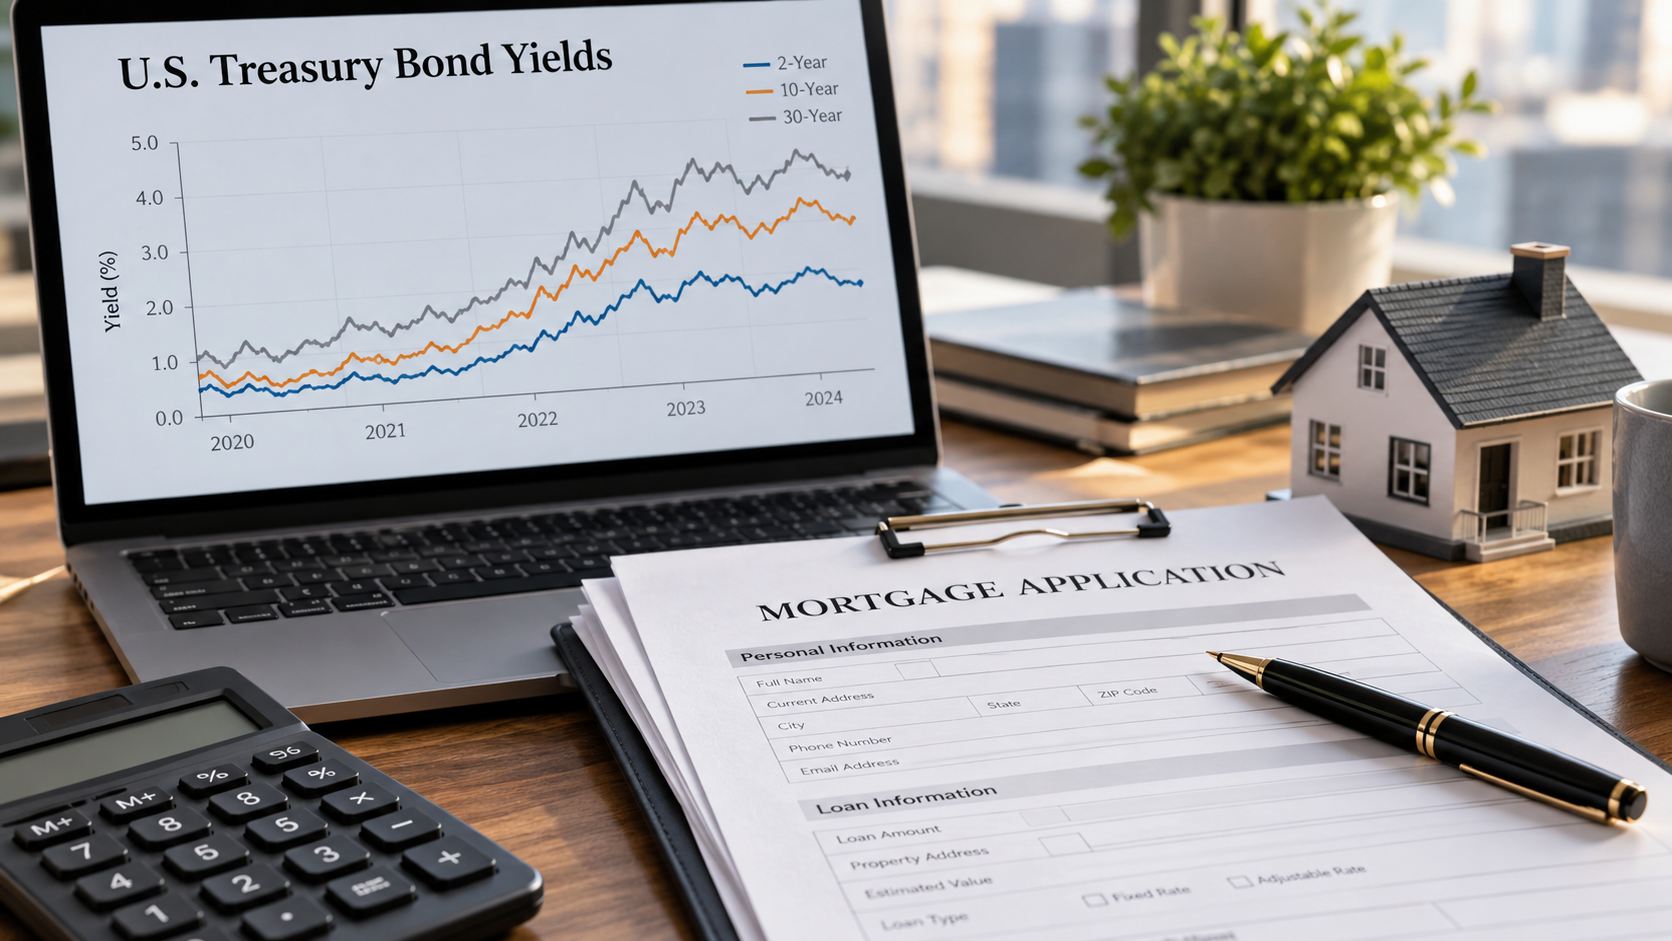
Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad?
No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield?
No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
-

 Analysis8 months ago
Top 10 Countries with the World’s Strongest Currencies in 2026 — Ranked & Analysed