
Research
The World’s Top 10 Economic Policy Research Institutes Shaping Global Decisions in 2026

As President Trump’s tariff policies shake global trade, inflation persists across advanced economies, and artificial intelligence promises to redefine labor markets, one question dominates finance ministries from Washington to Beijing: whose analysis can we trust? In an era where economic miscalculation carries trillion-dollar consequences, the world’s top economic think tanks have never wielded more influence—or faced greater scrutiny.
Behind every Federal Reserve pivot, every G20 communiqué, every IMF reform proposal sits months of rigorous research, often originating from a small constellation of elite policy institutes. These are not ivory tower abstractions. When the European Central Bank debates quantitative tightening, it cites Bruegel’s modeling. When South Korea designs industrial policy, it consults the Korea Development Institute. When the US Treasury crafts sanctions architecture, Peterson Institute papers line conference room tables.
This analysis identifies the best economic policy research institutes commanding genuine authority among central bankers, finance ministers, and international institution staff in 2026—organizations whose research doesn’t merely comment on policy but actively shapes it.
Methodology: Beyond Rankings, Toward Impact
The last Global Go To Think Tank Index from the University of Pennsylvania ceased publication in 2020 following its creator’s passing, leaving a significant gap in systematic think tank assessment. Our ranking synthesizes multiple authoritative sources: RePEc/IDEAS economist rankings, citation impact in premier journals (American Economic Review, Journal of Political Economy, Quarterly Journal of Economics), mentions in policy-relevant outlets (Financial Times, The Economist, The New York Times, Wall Street Journal), and documented influence on major policy decisions from 2024-2026.
We prioritize institutions demonstrating:
- Methodological rigor: Peer-reviewed output, transparent methodology, replicability
- Policy impact: Documented influence on legislation, regulatory frameworks, or international agreements
- Independence: Funding transparency, resistance to capture, intellectual diversity
- Global reach: Influence beyond home jurisdiction, multilingual dissemination
- Forward relevance: Research addressing 2025-2026 challenges (AI economics, climate transition, debt sustainability, geoeconomic fragmentation)
Key Distinction: This is not a roster of the most-cited economics departments (MIT, Chicago, Stanford) but rather dedicated policy research organizations bridging academic excellence with real-world applicability.
The Top 10 Leading Economic Think Tanks for 2026
1. Peterson Institute for International Economics (PIIE)
Location: Washington, D.C., USA
Founded: 1981
President: Adam S. Posen
Budget: ~$12-13 million (2019)
Staff: ~50 resident scholars
If there’s a single institute that defines leading economic think tanks 2026, it’s PIIE. Founded by C. Fred Bergsten at the suggestion of the German Marshall Fund, Peterson has become what The Washington Post calls “Washington’s premier think tank on the global economy.”
Why PIIE Ranks First: The institute won the Prospect Award for Best Economic and Financial Affairs Think Tank five consecutive years (2016-2020). Its scholars—including Olivier Blanchard (former IMF Chief Economist), Carmen Reinhart (former World Bank Chief Economist), and Adam Posen—represent an extraordinary concentration of policy experience. John Williamson coined the “Washington Consensus” while at Peterson, a framework that, however contested, defined development economics for two decades.
2025-2026 Relevance: PIIE’s research on the economic effects of Trump’s tariff proposals, published in early 2025, was directly cited in Congressional testimony opposing universal tariffs. The institute’s work on central bank independence, AI’s macroeconomic effects, and sovereign debt restructuring mechanisms informed G20 discussions in 2025.
Funding Transparency: Supported by foundations, corporations, individuals, and publication revenues. No government funding. Full disclosure available on website.
Notable Recent Work:
- Trade fragmentation and supply chain resilience studies
- Digital currency and cross-border payments frameworks
- Climate-related financial risk assessment
Visit: PIIE.com
2. Brookings Institution
Location: Washington, D.C., USA
Founded: 1916 (consolidated 1927)
Staff: 300+ scholars
Budget: Significantly larger than PIIE
The Brookings Institution remains the gold standard for breadth and institutional memory. Founded through the merger of three organizations, Brookings helped design the Marshall Plan and has maintained consistent influence through Republican and Democratic administrations alike.
Why Brookings Ranks High: Brookings was named the #1 Domestic Economic Policy Think Tank for three consecutive years (2016-2018) in the Penn Index. Its Hamilton Project generates economic proposals that regularly appear in presidential platforms. Former Treasury Secretaries, Fed Chairs, and CEA chairs populate its fellowship.
Distinctive Approach: Unlike PIIE’s laser focus on international economics, Brookings operates across the full policy spectrum—metropolitan policy, governance studies, foreign policy—with deep internal cross-pollination. This breadth enables holistic analysis: urban economists collaborate with trade specialists to model infrastructure investment under different trade scenarios.
2025-2026 Focus:
- Fiscal sustainability modeling amid rising interest burdens
- Labor market effects of generative AI
- Education-to-workforce transitions in the post-pandemic economy
Visit: Brookings.edu
3. Bruegel
Location: Brussels, Belgium
Founded: 2005
Director: Jeromin Zettelmeyer
Board Chair: Erkki Liikanen (Former ECB Governing Council)
Bruegel is Europe’s answer to Peterson, and in many respects its superior on EU-specific issues. Officially endorsed by French President Chirac and German Chancellor Schröder in 2003, Bruegel was established as a Brussels-based counterweight to Washington’s think tank dominance.
Why Bruegel Ranks Third: The 2020 Global Go To Think Tank Report ranked Bruegel the #1 international economics think tank worldwide (non-US) and #2 think tank worldwide overall. Its governance model—funded by EU member states, corporations, and institutions—provides genuine independence while maintaining policy relevance.
Unique Value: Bruegel’s proximity to EU institutions and command of European languages gives it unmatched access to continental policymaking. Its scholars regularly testify before the European Parliament and national legislatures. The institute pioneered real-time economic dashboards tracking Euro Area recovery, now standard in central banks globally.
2025-2026 Contributions:
- EU competitiveness in the AI era (co-published with CEPR)
- Green transition financing mechanisms
- European energy security post-Ukraine
Publications: 56 long reads, 86 short analyses, 53 podcast episodes (2023). The “Sound of Economics” podcast reaches 180,000+ listeners.
Visit: Bruegel.org
4. National Bureau of Economic Research (NBER)
Location: Cambridge, Massachusetts, USA
Founded: 1920
Network: 1,700+ affiliated scholars
President: James M. Poterba
NBER occupies a unique position—it’s simultaneously a think tank and a scholarly network connecting America’s top economics departments. Milton Friedman, Anna Schwartz, Simon Kuznets, and Wesley Mitchell produced foundational work here. Recent Nobel laureates James Robinson (2024), Robert Shiller (2013), and Thomas Sargent (2011) maintain NBER affiliations.
Why NBER Matters: NBER’s Business Cycle Dating Committee officially declares US recessions, giving it quasi-governmental authority. The NBER Working Paper series—over 32,000 papers—is the single most-cited economic research collection globally. Every major empirical advance in labor economics, public finance, and development economics appears here first.
Structure: NBER operates 20 research programs (Asset Pricing, Monetary Economics, Economic Fluctuations and Growth, etc.) and 14 working groups, facilitating cross-disciplinary collaboration unavailable elsewhere.
Policy Influence: NBER research on tax incidence, minimum wage effects, and social program evaluation directly informs Congressional Budget Office scoring. The institute’s pandemic-era work on fiscal multipliers was cited in over 40 national COVID relief debates.
2025-2026 Focus:
- High-skilled immigration and innovation
- Climate tipping points and economic modeling
- Behavioral responses to AI automation
Visit: NBER.org
5. Chatham House (Royal Institute of International Affairs)
Location: London, United Kingdom
Founded: 1920
Director: Bronwen Maddox
Budget: £20+ million
Chatham House shaped 20th-century international order—literally. Its 1919 founding grew from Paris Peace Conference discussions. The “Chatham House Rule” (statements not attributed to individuals) has become global standard for confidential policy dialogue.
Why Chatham House Ranks Fifth: Ranked #1 think tank outside the US for nine consecutive years and #2 worldwide for six years in the Penn Index. While broader than pure economics, Chatham House’s international political economy work influences trade negotiations, investment treaties, and sanctions architecture.
Distinctive Contribution: Chatham House excels at integrating economic analysis with geopolitical forecasting—essential as geoeconomics displaces traditional security analysis. Its work on China’s Belt and Road economic model, published in International Affairs (the journal it edits), provided frameworks adopted by OECD and Asian Development Bank.
2025-2026 Priorities:
- Economic statecraft in US-China competition
- Climate finance mechanisms for Global South
- Technology governance and semiconductor supply chains
Publications: International Affairs (bi-monthly journal), The World Today magazine, 300+ annual events.
Visit: ChathamHouse.org
6. Centre for Economic Policy Research (CEPR)
Location: London, UK (network-based)
Founded: 1983
Network: 1,500+ affiliated researchers across 52 countries
President: Beatrice Weder di Mauro
CEPR operates as Europe’s distributed answer to NBER—a network connecting economists across universities and institutions. This structure enables continent-spanning research collaborations impossible for single-location institutes.
Why CEPR Matters: CEPR’s Discussion Paper series rivals NBER’s working papers in citations. Its VoxEU portal publishes 8-10 policy briefs daily, reaching 400,000+ monthly readers—making cutting-edge research accessible to policymakers within days of completion.
Unique Model: Rather than employing resident scholars, CEPR facilitates research by university-based economists, then rapidly disseminates findings through conferences, publications, and policy networks. This lean structure maximizes intellectual diversity while minimizing overhead.
2025-2026 Impact:
- Research on European banking integration post-crisis
- Trade policy analysis amid US-EU-China fragmentation
- Monetary policy transmission in digital currency era
Key Programs: Collaborated extensively with Bruegel on EU competitiveness, with Kiel Institute on geoeconomics.
Visit: CEPR.org
7. Kiel Institute for the World Economy (IfW Kiel)
Location: Kiel, Germany
Founded: 1914
President: Moritz Schularick
Staff: 200+ researchers
Germany’s premier economic institute, IfW Kiel, celebrates its 110th anniversary in 2024 as one of the world’s oldest continuously operating economic research centers. Die Welt called it home to “the best economists in the world.”
Why Kiel Ranks Seventh: Ranked in the top 15 globally for economic policy (Penn Index, last edition). Kiel’s quarterly world economic forecasts are mandatory reading for European finance ministers and ECB policymakers. Its Ukraine Support Tracker, launched in 2022, has become the authoritative source for measuring international aid flows.
Methodological Innovation: Kiel pioneered the KITE (Kiel Institute Trade Policy Evaluation) model, now used by governments worldwide to simulate tariff scenarios. Recent simulations of US-China tariff escalation, showing 4.3% short-term US inflation under certain scenarios, informed Federal Reserve deliberations.
2025-2026 Contributions:
- Real-time global economic forecasts (quarterly)
- Geoeconomic fragmentation modeling
- European defense spending and growth tradeoffs
Data Excellence: Kiel maintains unique datasets on global trade, sovereign debt, and capital flows—freely accessible to researchers worldwide.
Visit: IFW-Kiel.de
8. Hoover Institution
Location: Stanford, California, USA
Founded: 1919
Director: Condoleezza Rice
Fellows: 200+ scholars
Budget: $75+ million
The Hoover Institution brings unusual combination of academic excellence (Stanford affiliation), policy experience (former cabinet secretaries, Fed governors), and ideological clarity (explicitly pro-market, limited government). Founded by Herbert Hoover to house his World War I archives, it has evolved into America’s leading conservative economic policy institute.
Why Hoover Ranks Eighth: Hoover fellows John Taylor, Michael Boskin, and Steven Davis represent decades of combined White House, Treasury, and Federal Reserve experience. The institution’s Working Group on Economic Policy produces research directly cited in Republican policy platforms, but its academic rigor ensures broader credibility—many Hoover studies are published in top peer-reviewed journals.
Distinctive Approach: Hoover’s integration with Stanford creates unique synergies—fellows collaborate with engineering faculty on technology economics, medical school researchers on healthcare policy, and business school scholars on corporate governance. Few think tanks can marshal such interdisciplinary expertise.
2025-2026 Focus:
- AI boom economic adaptation (conference proceedings published)
- Monetary policy independence debates
- Free market approaches to climate transition
Political Influence: Several Hoover fellows joined Trump’s first administration; the institution maintains connections across the conservative policy ecosystem.
Visit: Hoover.org
9. Cato Institute
Location: Washington, D.C., USA
Founded: 1977
President: Peter Goettler
Budget: $71+ million (2024)
The Cato Institute occupies a unique ideological space—libertarian rather than conservative, advocating free markets with civil liberties, drug legalization, immigration openness, and non-interventionist foreign policy. This heterodox mix enables Cato to influence debates both parties typically avoid.
Why Cato Ranks Ninth: Cato’s research on monetary policy, trade liberalization, and financial regulation carries weight precisely because it resists partisan capture. While Heritage Foundation embraced Trump’s tariffs, Cato’s economists maintained consistent opposition—earning credibility with trade skeptics of all persuasions. The institute’s Economic Freedom of the World index (published annually) is cited by governments as varied as Estonia, New Zealand, and Singapore.
Methodological Integrity: Cato refused donations from government-linked entities (famously declining Fannie Mae) and advocates positions hurting its donors when principle demands. This independence, though costly, preserves research credibility.
2025-2026 Contributions:
- Immigration economics (consistently pro-liberalization)
- Cryptocurrency and digital asset regulation
- Federal Reserve policy critique
Publication Strength: Cato Journal (since 1981), Regulation magazine, active podcast and video presence.
Visit: Cato.org
10. Korea Development Institute (KDI)
Location: Sejong City, South Korea
Founded: 1971
President: Cho Dong Chul
Staff: 150+ researchers
KDI represents emerging powers’ growing think tank sophistication. Established to guide South Korea’s development strategy, KDI documented one of history’s most successful industrialization stories—from $100 per capita GDP (1960s) to $35,000+ today.
Why KDI Ranks Tenth: KDI was consistently ranked the #1 international development think tank in multiple Penn Index editions and #6 think tank in Asia overall. Its influence extends beyond Korea through the Knowledge Sharing Program, advising governments from Vietnam to Colombia on development strategy. The World Bank and IMF regularly commission KDI research on industrialization, technology catch-up, and education policy.
Unique Positioning: As a non-Western, non-Chinese voice with development credibility, KDI offers frameworks appealing to middle-income countries seeking alternatives to Washington Consensus or Beijing models. Its work on industrial policy, export-led growth, and education investment provides evidence-based middle path.
2025-2026 Priorities:
- Demographic transition economics (Korea faces world’s lowest fertility)
- Semiconductor industry resilience
- Asia-Pacific economic integration
Global Reach: KDI hosts international conferences bringing together Asian, African, and Latin American policymakers—critical alternative to OECD-dominated gatherings.
Visit: KDI.re.kr/eng
Comparative Analysis: What Distinguishes Top-Tier Institutes
Funding Models and Independence
The most influential think tanks balance multiple funding sources to preserve independence:
- PIIE: Individual donors (86%), foundations (8%), corporations (3%)
- Brookings: Diverse foundation and individual support
- Bruegel: EU governments (plurality), corporations, international institutions
- NBER: University affiliations, publication revenues, private donations
- Cato: Individual donors (>90%), explicit refusal of government funding
Institutes accepting >50% funding from single sources face credibility questions—a cautionary tale as China’s state-funded think tanks seek global influence.
Geographic Distribution and the “Atlantic Bias”
Seven of ten institutes cluster in Washington-London-Brussels corridor, reflecting current global economic governance architecture. This concentration creates both strength (proximity to decision-makers) and weakness (potential blind spots on emerging markets).
Notable Absence: No Latin American, African, or Middle Eastern institutes rank top-10, despite these regions comprising 40%+ of global population. Chinese Academy of Social Sciences (CASS), though massive, lacks international credibility due to state control. India’s emerging think tanks (NCAER, ICRIER) have yet to achieve consistent global influence.
Methodological Approaches
The top institutes diverge on research philosophy:
- Empirical-First (NBER, KDI): Prioritize rigorous causal identification, careful data work
- Policy-First (PIIE, Bruegel): Balance rigor with timeliness, accessibility
- Ideological-First (Hoover, Cato): Maintain intellectual consistency within defined frameworks
- Convening-First (Chatham House): Emphasize dialogue, consensus-building alongside research
No single approach dominates; policy influence requires matching methodology to institutional mission.
The Digital Transformation
2025-2026 sees accelerating shift from printed reports to multimedia dissemination:
- Podcasts: Bruegel’s “Sound of Economics” (181,000 listens), Hoover’s “Uncommon Knowledge”
- Real-time data: Kiel’s Ukraine Tracker, Bruegel’s European Clean Tech Tracker
- Social media: PIIE’s active Twitter/X presence, NBER Digest summaries
- Interactive tools: Cato’s FreedomInthe50States.org, KDI’s economic dashboards
Institutes failing to adapt risk irrelevance as policymakers consume information via podcast and email brief rather than 50-page PDF.
2026 Economic Challenges: How Think Tanks Are Responding
The AI Economics Revolution
Every institute listed has launched major AI research initiatives in 2024-2025:
- Hoover: Stanford Emerging Technology Review, AI governance framework
- PIIE: AI’s impact on trade patterns and comparative advantage
- Brookings: Labor market disruption and policy responses
- NBER: Productivity effects, winner-take-all dynamics
Consensus emerging: AI represents more profound economic transformation than mobile internet, but policy frameworks remain dangerously underdeveloped.
Geoeconomic Fragmentation
Trump’s return accelerated US-China decoupling, forcing institutes to model “Cold War II” economic scenarios:
- Kiel Institute: KITE model simulating tariff escalation
- Peterson: Supply chain resilience frameworks
- Chatham House: Technology sovereignty analysis
- Bruegel: European strategic autonomy options
Key debate: Will fragmentation prove temporary (reverting to globalization) or structural (producing separate economic spheres)?
Climate Transition Finance
COP30 approaches with massive financing gaps; think tanks developing implementation pathways:
- Bruegel: EU carbon border adjustment mechanisms
- KDI: Asian climate finance architectures
- Brookings: Green industrial policy evaluation
- NBER: Climate risk insurance markets
Critical question: Can market mechanisms drive transition, or does climate crisis require centralized allocation?
Sovereign Debt Sustainability
Rising interest rates plus pandemic spending created unsustainable debt dynamics:
- PIIE: Debt restructuring mechanisms for middle-income countries
- Brookings: US fiscal trajectory analysis
- Chatham House: Geopolitics of IMF conditionality
- CEPR: Eurozone debt mutualization debates
Next global financial crisis likely originates in sovereign debt—precisely where think tanks proved most valuable during 2010-2012 Eurozone crisis.
Limitations and Emerging Competitors
The Ranking’s Subjectivity
No objective “top 10” exists. Alternative criteria could elevate:
- American Enterprise Institute: Conservative domestic policy influence
- Urban Institute: Social policy and poverty research
- IMF Research Department: Unmatched data access, though less independent
- OECD Economics Department: Policy coordination role
- Federal Reserve Regional Banks: Cleveland Fed inflation research, San Francisco Fed labor analysis
Our ranking prioritizes institutions with demonstrated cross-border influence on macroeconomic and trade policy—other institutes excel in specialized niches.
The “Emerging Powers” Gap
As global economic gravity shifts eastward and southward, Western institute dominance grows problematic. Promising developments:
- CASS (China): If granted genuine autonomy, could rival NBER
- NCAER/ICRIER (India): Growing sophistication, government connections
- Policy Center for the New South (Morocco): African perspective on development
- CEDES (Argentina): Latin American monetary policy expertise
2026-2030 will likely see rapid emergence of non-Western institutes as their governments realize soft power benefits.
The For-Profit Consulting Alternative
Management consultancies (McKinsey Global Institute, BCG Henderson Institute) increasingly compete with traditional think tanks—deeper private sector access, better compensation for talent, slicker presentation. However, undisclosed client relationships and profit motives limit credibility for genuinely independent research.
What Makes Research Influential? Lessons from the Top 10
Timing Matters as Much as Quality
PIIE’s 2016 analysis of Brexit economic costs, published weeks before the referendum, achieved massive policy impact—not because it was more rigorous than subsequent academic studies, but because it arrived when decision-makers needed guidance.
Access Requires Relationship Investment
Bruegel’s influence stems partly from former ECB President Jean-Claude Trichet chairing its board (2012-2020). Chatham House’s convening power rests on century-long relationship cultivation. Think tanks that treat policymakers as mere research subjects rather than partners lose influence.
Transparency Builds Trust
Brookings and PIIE publish full donor lists, scholar outside income, and methodology appendices. This transparency—costly in fundraising terms—pays dividends in crisis credibility. When COVID hit, their pandemic economic analyses were trusted precisely because past work was demonstrably independent.
Specialization vs. Generalization
The top 10 includes both specialists (PIIE on international economics) and generalists (Brookings across all policy domains). Success requires internal coherence: specialists must deeply dominate their niche; generalists must facilitate cross-domain insights unavailable elsewhere.
The Future of Economic Policy Research
Challenges Ahead
Data Access: As firms guard proprietary data more zealously, academic economists lose empirical advantage. Think tanks with private sector partnerships (Hoover-Stanford, KDI-Korean conglomerates) gain relative edge.
Polarization: As politics polarizes, maintaining bipartisan credibility grows harder. Brookings and PIIE face constant accusations of bias from both left and right—yet this criticism paradoxically demonstrates they occupy center ground.
Speed-Quality Tradeoff: Policymakers want answers yesterday; rigorous research takes months. Institutes rushing to relevance risk credibility; those prioritizing perfection risk irrelevance.
Funding Sustainability: As wealth concentrates, institute funding increasingly depends on handful of ultra-wealthy donors. Even transparent disclosure cannot eliminate influence concerns when single donors provide >10% of budgets.
Opportunities Emerging
Global South Partnerships: Top institutes collaborating with African, Asian, and Latin American counterparts can expand evidence base beyond OECD experiences. KDI’s Knowledge Sharing Program exemplifies this model.
Real-Time Analysis: Computing power enables continuous economic modeling unimaginable in analog era. Institutes maintaining up-to-date dashboards (Kiel’s Ukraine Tracker) gain authority as “first responders” to economic shocks.
Open Science Movement: Preprint servers, open data repositories, and code-sharing norms accelerate knowledge diffusion. Institutes embracing these practices (NBER’s public working papers) maximize research impact.
Interdisciplinary Integration: As economics intersects with climate science, epidemiology, and computer science, institutes fostering cross-disciplinary collaboration (Hoover-Stanford model) generate insights impossible within traditional boundaries.
Conclusion: Power, Influence, and Accountability
The world’s leading economic think tanks wield extraordinary power—shaping trillion-dollar policy decisions, defining terms of debate, conferring legitimacy on contested proposals. This influence rests on fragile foundations of trust, accumulated through decades of rigorous research, transparent methods, and demonstrated independence.
The ten institutes profiled here earned elite status through different paths: PIIE through laser-focused international economics mastery, Brookings through breadth and institutional memory, Bruegel through European integration, NBER through academic network effects, and so forth. Yet they share common attributes—intellectual integrity, methodological rigor, and commitment to evidence over ideology (even ideologically-committed institutes like Hoover and Cato subordinate politics to research quality).
As 2026 unfolds with its overlapping crises—AI transformation, geoeconomic fragmentation, climate emergency, debt sustainability—the demand for trustworthy economic analysis has never been greater. The institutes listed here will shape how democracies respond to these challenges. Whether they deserve such influence is ultimately for history to judge. That they currently possess it is beyond dispute.
Sources and Disclaimer
This ranking synthesizes multiple data sources including the Global Go To Think Tank Index (final 2020 edition), RePEc/IDEAS economist rankings, citation analysis from Web of Science, qualitative assessment of policy impact, and review of major institute publications from 2024-2025. While we strive for objectivity, all rankings involve subjective judgment. Readers should consult multiple sources when evaluating institutional credibility.
Rankings reflect 2026 assessment and are subject to change as institutions evolve.
For more on think tank influence and economic policy research, visit: Brookings.edu | PIIE.com | Bruegel.org | NBER.org
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


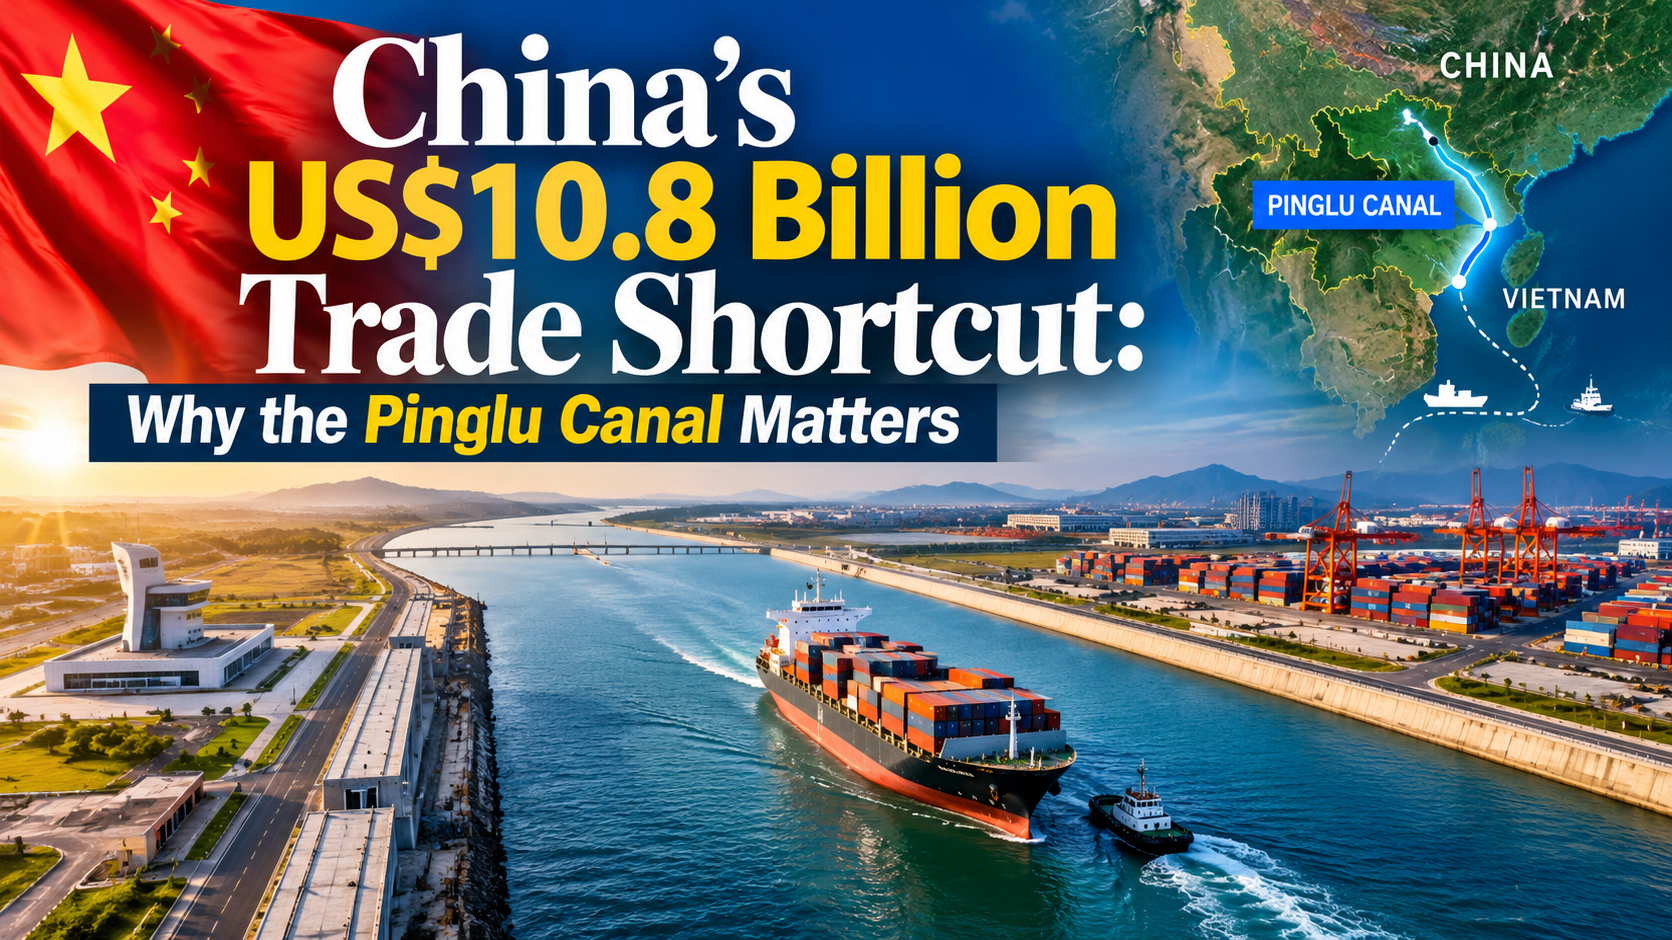
The delivery of the Pinglu 001 command and management vessel in early September 2026 signals that China’s US$10.8 billion inland waterway project is ready for commercial operations. With final vessel trials concluded and completion acceptance achieved in late August, the 134.2-kilometre Pinglu Canal is preparing to open. For logistics planners and manufacturers across Southeast Asia, this development fundamentally shifts the geography of regional trade. Rather than routing goods east through Guangzhou, inland Chinese factories can now send cargo directly south to the Beibu Gulf, shaving more than 560 kilometres off the maritime journey to ASEAN markets.
| Metric | Details |
| Project | Pinglu Canal |
| Location | Guangxi, China |
| Length | 134.2 km |
| Investment | ~US$10.8 billion (72.7 billion yuan) |
| Vessel capacity | Up to 5,000 tonnes |
| Destination | Beibu Gulf (via Qinzhou) |
| Expected opening | September 2026 |
| Strategic corridor | New International Land-Sea Trade Corridor |
| Main trade relevance | China-ASEAN connectivity |
What Is the Pinglu Canal?
The Pinglu Canal is China’s first major river-to-sea canal constructed since the founding of the People’s Republic. The waterway begins at the Xijin reservoir on the Yu River in Hengzhou (near Nanning, the capital of Guangxi) and cuts southward to meet the lower Qinjiang River in Qinzhou. This connection physically links Guangxi’s expansive inland river system directly to the Beibu Gulf.
Historically, cargo navigating the rivers of southwestern China had to float eastward down the Pearl River system to reach ocean-going ports in Guangdong province. The canal breaks this geographic constraint by blasting a direct southern corridor through the mountains, connecting inland manufacturing hubs directly to the deep-water facilities of Qinzhou Port and the open sea.
Why the First Command Vessel Matters
The arrival of the Pinglu 001 command vessel is the clearest indicator that the infrastructure phase has transitioned into the operational management phase. A canal handling 5,000-tonne vessels requires sophisticated maritime traffic control, lock synchronization, and emergency response capabilities. The delivery of this vessel proves that the bureaucratic and operational frameworks—not just the concrete locks and excavated channels—are ready to handle live commercial traffic. It acts as the final administrative sign-off before the floodgates open to scheduled freight lines in September 2026.
China’s US$10.8 Billion Bet on Faster Trade
At approximately 72.7 billion yuan (US$10.8 billion), the canal represents a massive capital injection into regional logistics. The economics of the project hinge on aggregate transport savings. Official estimates project that the canal will save regions along the route more than 5.2 billion yuan (US$720 million) annually in transportation costs.
These savings stem from reduced fuel consumption, faster turnaround times, and lower transshipment fees. For a manufacturer in Sichuan or Chongqing exporting electronics to Thailand, the cost of moving containers by river directly to the Beibu Gulf is substantially lower than rail-to-port or road-to-port alternatives. This infrastructure multiplier effect is expected to make western China’s exports more price-competitive in international markets.
The 560-Kilometre Shortcut: What Actually Changes?
The defining metric of the Pinglu Canal is the elimination of approximately 560 kilometres of inland transit.
Before
Factory → Inland river transport (eastward) → Pearl River Delta/Guangzhou ports → Ocean freight → ASEAN
After
Factory → Pinglu Canal (southward) → Beibu Gulf/Qinzhou Port → Ocean freight → ASEAN
This does not replace road or rail logistics, which remain vital for time-sensitive cargo. Instead, it offers a high-volume, low-cost multimodal alternative for bulk goods, raw materials, and heavy containerized freight that cannot bear the premium pricing of rail transport.
Why ASEAN Is at the Center of the Story
The canal’s strategic value is inherently tied to the Association of Southeast Asian Nations (ASEAN). ASEAN is China’s largest trading partner, and the trade volume is heavily skewed toward intermediate goods—components manufactured in China that are assembled in Southeast Asia.
Economies like Vietnam, Malaysia, Singapore, Thailand, and Indonesia require a constant, cheap flow of Chinese industrial inputs to feed their own export engines. By lowering the logistics friction between China’s industrial hinterland and these ASEAN markets, the canal effectively shrinks the economic distance between factories in Nanning and assembly lines in Hanoi, Rayong, or Penang.
Vietnam Could Be One of the Biggest Beneficiaries
Due to its geographic proximity to Guangxi and the Beibu Gulf, Vietnam is positioned to absorb the immediate effects of the canal. The cross-border supply chain between southern China and northern Vietnam is highly integrated, particularly in electronics, machinery, and textiles.
While the canal does not cross into Vietnam, it allows barges carrying intermediate goods from deep inside China to reach Qinzhou Port faster. From Qinzhou, short-sea shipping routes to Haiphong or Ho Chi Minh City can operate with greater frequency and lower baseline costs. This maritime bridge complements the heavily congested overland border crossings at Friendship Pass.
What It Means for China’s Inland Factories
For small and medium enterprises (SMEs) and large manufacturers in western China, the canal offers a margin buffer. Machinery producers, auto parts suppliers, and agricultural exporters often operate on razor-thin margins where logistics dictate profitability.
Access to a cheaper, higher-capacity water route allows inland factories to scale up production without being bottlenecked by rail quotas or high trucking costs. It essentially grants coastal shipping advantages to landlocked industrial parks.
The Beibu Gulf Port Becomes More Important
The Pinglu Canal is useless without a maritime outlet, which makes Qinzhou and the broader Beibu Gulf Port complex an integrated part of this logistics ecosystem. Over the past five years, Qinzhou has expanded its automated container terminals and warehousing facilities to handle the anticipated surge in river-to-sea cargo.
Cargo barges arriving via the canal will transship their containers onto ocean-going vessels at Qinzhou. Consequently, the Beibu Gulf is expected to see a sharp rise in vessel calls, attracting more international shipping lines and cementing its status as a primary hub for China-ASEAN trade, rather than a secondary feeder port.
The New International Land-Sea Trade Corridor
The canal is the physical backbone of the New International Land-Sea Trade Corridor (ILSTC). The ILSTC is a logistics network designed to connect western China to the global maritime network via Guangxi, rather than routing everything through the distant eastern seaboard.
The corridor utilizes a mix of rail, road, and now river transport. By adding a 5,000-tonne capacity waterway to the corridor, Guangxi solidifies its strategic mandate as the transit nexus for all western Chinese trade heading south to Southeast Asia and beyond.
Could Pinglu Canal Reshape China-ASEAN Supply Chains?
The opening of the waterway has the potential to alter regional inventory management and sourcing. If logistics costs drop and delivery reliability increases, ASEAN-based manufacturers may opt to source bulkier, heavier intermediate goods from western China rather than coastal China.
Furthermore, industrial investment could shift inland. If a company can achieve similar export costs from Nanning as it can from Shenzhen, the lower land and labor costs in Guangxi become highly attractive, potentially drawing manufacturing away from the saturated eastern provinces.
What the Canal Does NOT Solve
Despite its massive scale, the Pinglu Canal is not a cure-all for supply chain volatility. The waterway is restricted to vessels of approximately 5,000 tonnes. Ocean-going mega-ships carrying 20,000 TEUs cannot navigate it; all cargo must still be transshipped at the Beibu Gulf.
Furthermore, river transport is inherently slower than rail or road. Time-sensitive electronics or perishable goods will likely remain on trains and trucks. The canal is also susceptible to weather conditions, seasonal water levels, and potential lock congestion if vessel traffic exceeds design capacity.
Environmental and Social Questions
Constructing a 134-kilometre canal requires moving roughly 339 million cubic meters of earth. The ecological disruption to the regional river systems, wetlands, and local agriculture is substantial. To mitigate this, engineers incorporated ecological corridors, wildlife crossings, and water-saving lock technologies—such as the Madao hub, which recycles water to reduce consumption by 63%. Long-term environmental monitoring will be required to assess the actual impact on the Beibu Gulf’s marine ecosystems as freshwater and industrial traffic mix with the marine environment.
The Bigger Geoeconomic Picture
Geoeconomically, the canal is a tool for domestic rebalancing and regional integration. By enriching its western provinces, China addresses domestic economic inequality while binding ASEAN closer to its industrial orbit. It is a physical manifestation of supply-chain diversification, ensuring that China maintains multiple high-capacity trade routes that bypass potential bottlenecks in the South China Sea or the congested Pearl River Delta.
What Happens After the September 2026 Opening?
Short term
Expect initial operational adjustments as barges, lock operators, and port authorities sync their schedules. First commercial vessels will test the efficiency of transshipment at Qinzhou.
Medium term
Logistics companies will likely introduce dedicated river-to-sea freight products, bundling inland factory pickup with ASEAN delivery. Total cargo volumes will scale up over 2027 and 2028.
Long term
Sustained lower freight rates could trigger industrial relocation, with heavy manufacturing clustering around the canal’s inland hubs to exploit the cheap waterborne route to Southeast Asia.
| Factor | Before Pinglu Canal | Potential Post-Opening Effect |
| Inland-to-sea distance | Longer route (east) | Shorter route (south) |
| Logistics costs | Higher | Potentially lower |
| Access to Beibu Gulf | Rail/Road dependent | Direct high-capacity water |
| ASEAN connectivity | Existing but indirect | Stronger maritime bridge |
| Guangxi industrial competitiveness | Secondary | Potential major boost |
The Pinglu Canal is far more than a civil engineering triumph. It is a deliberate restructuring of China’s trade geography. By spending US$10.8 billion to carve a 560-kilometre shortcut to the sea, China is effectively moving its inland factories closer to Southeast Asia. While transshipment and vessel size limits remain, the sheer volume of cheap, waterborne freight that can now flow directly into the Beibu Gulf ensures that the Pinglu Canal will become a critical artery in the global supply chain.
FAQ
1. What is the Pinglu Canal?
The Pinglu Canal is a 134.2-kilometre inland waterway in Guangxi, China, designed to connect the inland river system directly to the Beibu Gulf, bypassing longer eastern routes.
2. When will the Pinglu Canal open?
Following the completion of vessel trials and project acceptance in August 2026, the canal is scheduled to open for commercial navigation in September 2026.
3. How much did the Pinglu Canal cost?
The project required a total investment of approximately 72.7 billion yuan, which translates to roughly US$10.8 billion.
4. How long is the Pinglu Canal?
The canal stretches 134.2 kilometres from the Xijin reservoir in Hengzhou down to the Beibu Gulf via Qinzhou.
5. Which countries will benefit from the Pinglu Canal?
While China benefits domestically, ASEAN nations—particularly Vietnam, Malaysia, Thailand, Singapore, and Indonesia—will benefit from faster and potentially cheaper access to Chinese industrial goods.
6. How will the canal affect China-Vietnam trade?
By lowering the cost of moving intermediate goods to the Beibu Gulf, the canal facilitates cheaper short-sea shipping to northern Vietnam, complementing existing cross-border supply chains.
7. Why is Guangxi important for ASEAN trade?
Guangxi borders Vietnam and the Beibu Gulf, making it China’s primary gateway to Southeast Asia for both overland and maritime logistics.
8. What is the New International Land-Sea Trade Corridor?
It is a strategic trade and logistics network connecting western China to global markets via southern ports, heavily utilizing rail, road, and river transport.
9. How much cargo can Pinglu Canal vessels carry?
The canal is designed to accommodate inland river vessels with capacities of up to approximately 5,000 tonnes.
10. Will the Pinglu Canal reduce shipping costs?
Yes, official estimates suggest the 560-kilometre shortcut will save regions along the route up to 5.2 billion yuan annually in transport costs.
Sources
- Xinhua: Pinglu Canal enters final preparations for September opening
- People’s Daily: Major Chinese river-to-sea canal passes completion acceptance
- Global Times: Pinglu Canal: How China’s ‘canal project of the century’ reshapes trade
- Wikipedia: Pinglu Canal Specifications & History
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
As foreign central banks dump $90 billion in US Treasuries and Brent crude convulses near $120, Islamabad’s unlikely role as peacebroker is paying an unexpected dividend on the trading floor.
There is a peculiar kind of optimism that only emerges in the eye of a hurricane. Wednesday morning at the Pakistan Stock Exchange felt exactly like that. At 12:05 p.m., the benchmark KSE-100 Index stood at 156,204.89 — having gained 7,461.58 points, or 5.02%, from the previous close — a move so violent that it triggered a mandatory market halt, suspending all equity-based trading under PSX circuit-breaker rules. ProPakistani The previous session had already closed higher. Tuesday’s KSE-100 session had ended at 148,743.32, up 1,900.34 points, as investors began pricing in whispers of a ceasefire from Washington. Profit by Pakistan Today By Wednesday noon, those whispers had become a roar.
This is not, however, a story only about Karachi. It is a story about a world economy convulsing under the weight of a war in the Persian Gulf, a $30 trillion US Treasury market being quietly liquidated by desperate central banks, and — most improbably — Pakistan sitting at the centre of the most consequential diplomatic negotiation of 2026. The KSE-100’s surge is at once a relief rally, a geopolitical signal, and a referendum on how tightly Pakistan’s financial fate is now knotted to its new role as peacebroker between Washington and Tehran.
Why Karachi Erupted: The Anatomy of a 5% Day
Buying momentum on Wednesday was broad-based, with strong activity across automobile assemblers, cement, commercial banks, fertiliser, oil and gas exploration, oil marketing companies, and power generation firms. Major index-heavyweights — HBL, MCB, MEBL, UBL, MARI, OGDC, PPL, POL, PSO, HUBCO, and ARL — all traded firmly in the green, reflecting renewed investor confidence amid easing geopolitical risk. ProPakistani
The rally follows emerging hopes of de-escalation in the Iran war after US President Donald Trump and Secretary of State Marco Rubio signalled that the conflict could end soon, with Washington indicating potential direct talks with Tehran’s leadership and a winding down of hostilities even without a formal deal. Profit by Pakistan Today Trump, speaking from the White House on Tuesday, said the US exit could come “within two weeks, maybe two or three.”
The market context matters enormously here. The rebound follows a brutal first-quarter correction, during which the Pakistan Stock Exchange benchmark declined around 15% amid geopolitical uncertainty and relentless selling pressure. Profit by Pakistan Today That selloff was not irrational. Pakistan’s economy is structurally exposed to Middle East energy prices — the country imports the overwhelming majority of its oil and LNG, and any sustained spike in Brent crude flows directly into inflation, the current account deficit, and State Bank of Pakistan reserves. When the war began on February 28, the PSX reacted the way a patient loses colour when told bad news: quickly, and all at once.
Wednesday’s reversal tells a different story. It tells you that the market had been pricing in far worse than what may now materialise. It tells you that institutional and retail buyers in Karachi, Lahore, and Islamabad are not just trading geopolitics abstractly — they are trading Pakistan’s specific role in ending this crisis.
The $90 Billion Treasury Liquidation: A Slow-Motion Earthquake Under Bond Markets
While traders in Karachi were celebrating, bond desks in New York, London, and Tokyo were navigating something far more structurally significant. New York Fed custody data shows that since the week before the conflict broke out — the week of February 25 — foreign monetary authorities have been net sellers of US Treasuries for five consecutive weeks, with the total sell-off exceeding $90 billion, and holdings falling to the lowest level since 2012. All-Weather Media
The Financial Times, citing Federal Reserve data, confirmed that the value of Treasuries held in custody at the New York Fed by official institutions — a group largely made up of central banks but also including governments and international institutions — has dropped by $82 billion since February 25 to $2.7 trillion. X
The mechanics driving this sell-off are not mysterious, even if their consequences are underappreciated. The direct cause of this round of selling is the urgent need for dollar liquidity among countries — from foreign exchange market intervention to paying energy import bills and financing defense spending, the surge in demand for dollars is forcing foreign central banks to liquidate their most liquid dollar assets: US Treasuries. Futu News
The single most striking data point in the disaggregated country-level picture is Turkey’s. Official figures show that since February 27 — the day before the US attacked Iran — Turkey’s central bank sold about $22 billion in foreign government bonds from its reserves, mainly US Treasuries. Turkey also sold or swapped about 58 tons of gold valued at over $8 billion. All-Weather Media
Brad Setser, Senior Fellow at the Council on Foreign Relations and arguably the world’s foremost tracker of sovereign reserve flows, has been clear about who else is in the queue. Setser stated that “many countries are unwilling to let their currencies depreciate further, as this would drive up oil prices denominated in local currencies — either implying more fiscal subsidies or increasing the burden on people’s daily lives. Therefore, many countries have generally decided to intervene in the foreign exchange market to try to limit the depreciation of their currencies.” Futu News India and Thailand, both large oil importers, have also seen foreign reserve drawdowns since the war began, though it remains unclear whether those represent outright Treasury sales or dollar deposit liquidations.
Bank of America US rates strategist Meghan Swiber has been unambiguous: the foreign official sector is selling US Treasuries, and the selling “confirms a more macro narrative — that foreign reserve managers and official accounts are diversifying away from US Treasuries.” All-Weather Media
The structural backdrop is equally sobering. A recent Morgan Stanley report shows the proportion of US Treasuries held by foreign investors has dropped to its lowest since 1997, with the share of coupon-bearing Treasuries held by foreign investors falling steadily since the 2008 peak of 64.4% and now near multi-decade lows. All-Weather Media The Iran war has not created this trend — but it has violently accelerated it. As the Financial Times reported on Tuesday, the bond market’s largest and most stable category of buyer is now, in a period of maximum global stress, a net seller.
This matters for Pakistan in a roundabout but real way. Higher US Treasury yields — the mathematical consequence of this selling pressure — tighten global dollar funding conditions, increase the cost of Pakistan’s external debt servicing, and strengthen the dollar in ways that amplify imported inflation. A faster resolution to the Iran conflict is, in this sense, not just a geopolitical good but a financial one for Islamabad.
The Strait, the Shock, and the Oil Market Nobody Saw Coming
The International Energy Agency has called it the biggest oil supply shock in history. Due to Iran’s selective blockade of the Strait of Hormuz, the world is losing as much as 20 million barrels of oil per day from Middle East producers. Since the war began five weeks ago, Brent crude has risen more than 50%. CNN
Brent crude was trading at just over $118 per barrel for May deliveries, while the more widely traded June delivery contract was around $103.50. The average price of gasoline in the United States crossed $4 per gallon for the first time since 2022. CBS News For emerging markets that import most of their energy, these numbers translate into something far more corrosive than headline inconvenience: they represent a structural transfer of wealth from oil-importing nations to a geopolitical standoff, mediated by a narrow chokepoint 21 miles wide at its narrowest point.
The Wall Street Journal, citing administration officials, reported that Trump and his aides had concluded that a military mission to reopen the Strait of Hormuz would extend beyond his four-to-six-week timeline, and he had decided to focus on targeting Iran’s missiles and navy before seeking to pressure Iran diplomatically to reopen it. Euronews
That shift — from military maximalism to diplomatic realism — is precisely what equity markets in Karachi, and indeed across emerging Asia, have been waiting for.
Pakistan’s Diplomatic Dividend: The Unlikely Peacebroker
The most remarkable subplot of this crisis is not the Treasury sell-off, nor the oil price spike. It is Islamabad’s transformation, over the past two weeks, from a country wracked by internal protests over the US strikes on Iran into a credible diplomatic interlocutor between Washington and Tehran.
Pakistan’s Foreign Minister Ishaq Dar confirmed that “US-Iran indirect talks are taking place through messages being relayed by Pakistan,” adding that Turkey and Egypt were also extending support to the initiative. US envoy Steve Witkoff confirmed presenting a 15-point action list as the framework for a peace deal, which mediator Pakistan gave to Iran. NPR President Trump then paused his deadline for the destruction of Iran’s energy plants by ten days to April 6, citing the ongoing talks. Special envoy Steve Witkoff confirmed at President Trump’s Cabinet meeting that the US has been negotiating with Iran through diplomatic channels with Pakistan as the conduit. CNN
Foreign Policy has described this as a role that makes more geopolitical sense than it initially appears. Pakistan is a rare country that has warm ties with both the United States and Iran and is engaged with the highest levels of both governments. Pakistan also represents Tehran’s diplomatic interests in Washington. Furthermore, Pakistan has dealt closely with the family of a key player on the US side — Middle East envoy Steve Witkoff. Foreign Policy
The domestic calculus is equally clear: Pakistan’s mediation push is driven by economic strain, security concerns, and strategic calculation. With energy markets volatile and the country reliant on Gulf oil and LNG imports, any sustained spike in global crude prices could deepen a crisis Pakistan can ill afford. Pakistan’s fragile economic recovery is under renewed stress, with constrained fiscal space and minimal strategic oil reserves. The Researchers
The PSX’s 7,500-point single-session surge is, in a narrow sense, investors pricing in the probability that Pakistan’s diplomatic gamble pays off. A ceasefire, even an imperfect one, would lower oil prices, ease imported inflation, reduce pressure on State Bank of Pakistan foreign reserves, and reopen the possibility of further monetary easing by the SBP — all of which are bullish for Pakistani equities.
Risks: The Rally Is Real, But the Ceasefire Isn’t — Yet
Markets have a well-documented habit of pricing in peace talks before those talks produce peace. The KSE-100’s gain on Wednesday is a bet, not a receipt.
Several credible risks remain. Iran has countered the US 15-point plan with its own five conditions, including recognition of Iran’s legitimate rights, payment of war reparations, and firm international guarantees against future aggression. Al Jazeera Those are not trivial demands from a country that has seen its Supreme Leader killed and its military infrastructure methodically dismantled. Ending the war with Iran retaining effective control of the Strait of Hormuz would be seen internationally as a strategic defeat for the United States — Iran would claim victory and might monetize its position by imposing tolls on transiting tankers, providing revenues to rebuild its military and nuclear programmes. CNN
Secretary of State Rubio has been clearer on the endgame than almost anyone. Rubio told Al Jazeera that “the Strait of Hormuz will be open when this operation is over — one way or another,” and rejected Iran’s demand to maintain sovereignty over the waterway as part of any agreement. Al Jazeera That language, while reassuring to oil markets in the abstract, leaves significant space for a breakdown in negotiations — and a resumption of exactly the kind of escalatory cycle that sent the KSE-100 down 15% in the first quarter.
Oil market participants appear to be processing this nuance already. Bond yields have been steadily rising throughout March as investors race to reprice the chances of rate hikes from central banks, with expectations of rate cuts at the Federal Reserve and the Bank of England having fallen sharply and in many cases being replaced by anticipations of hawkish monetary policy. CNBC That global repricing of central bank paths — driven directly by energy-led inflation — is a structural headwind for emerging market assets, Pakistan included, that does not disappear even if a ceasefire is signed.
Global Macro Implications: When the World’s Safe Asset Isn’t Safe Enough
Beneath the headline drama of the oil price spike and the stock market surge, the most consequential development of this crisis may be the one attracting the least retail attention: the systematic erosion of US Treasury demand at precisely the moment that Washington’s finances require it most.
Stephen Jones, Chief Investment Officer at Aegon Asset Management, described central banks’ actions as countries “raising war funds,” saying, “They are drawing on emergency reserves.” This round of selling is not an isolated event but a microcosm of a longer-term structural shift: global reserve management institutions are systematically reducing exposure to dollar assets. All-Weather Media
If the Iran conflict ends quickly, some of this pressure on the Treasury market will ease. Central banks in Turkey, India, and Thailand that have been intervening in FX markets to defend their currencies will face less pressure to continue liquidating reserves once oil prices fall. That normalisation would provide some relief to US bond yields. But the structural share of foreign holdings — already at a 27-year low — is not a tap that turns back on quickly. The trend that the war has accelerated was years in the making.
For Pakistan’s capital markets, the near-term playbook favours the bulls — as long as the diplomatic process holds. A ceasefire, lower Brent crude, a softer dollar, and resumed SBP rate cuts would be a nearly perfect cocktail for further PSX gains. The index, even after Wednesday’s surge, remains roughly 18% below its all-time high of approximately 189,556 points reached in January 2026. There is significant mean-reversion potential if geopolitical risk genuinely abates.
Outlook: Watch April 6 — and the Address to the Nation
The immediate calendar is unusually consequential. President Trump is scheduled to deliver a prime-time address to the nation on Wednesday evening providing what the White House described as “an important update on Iran.” The April 6 deadline for Iran to reopen the Strait of Hormuz — or face strikes on its energy infrastructure — creates a hard binary. Either the diplomatic track delivers a meaningful framework before that date, or markets face the prospect of a sharp escalatory spike.
Secretary of State Rubio, before departing for a G7 foreign ministers meeting in France, confirmed that “there are intermediary countries that are passing messages and progress has been made — some concrete progress has been made,” describing negotiations as “an ongoing and fluid process.” CNN
For investors in Karachi and beyond, the single most important watch item is not the KSE-100 level, nor the US Treasury yield, nor even Brent crude. It is whether Pakistan’s mediation — this extraordinary diplomatic intervention by a country whose consulate in its own largest city was attacked just a month ago — delivers enough of a framework before April 6 to allow both sides to step back from the precipice.
If it does, Wednesday’s 7,500-point surge will look, in hindsight, like the opening chapter of a recovery story rather than a false dawn in a prolonged storm. If it doesn’t, the circuit-breaker that paused trading on Wednesday could, in the weeks ahead, be pointing in the other direction.
Pakistan has been here before — not as a victim of great-power competition, but as its unexpected architect. It was Islamabad that facilitated Nixon’s 1971 opening to China. It may yet be Islamabad that writes the first line of a postwar order in the Persian Gulf. The KSE-100, for one day at least, has decided to believe it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Bessent and He Lifeng meet at OECD Paris to review the Busan trade truce before Trump’s Beijing summit. Rare earths, Hormuz oil shock, and Section 301 cloud the path ahead.
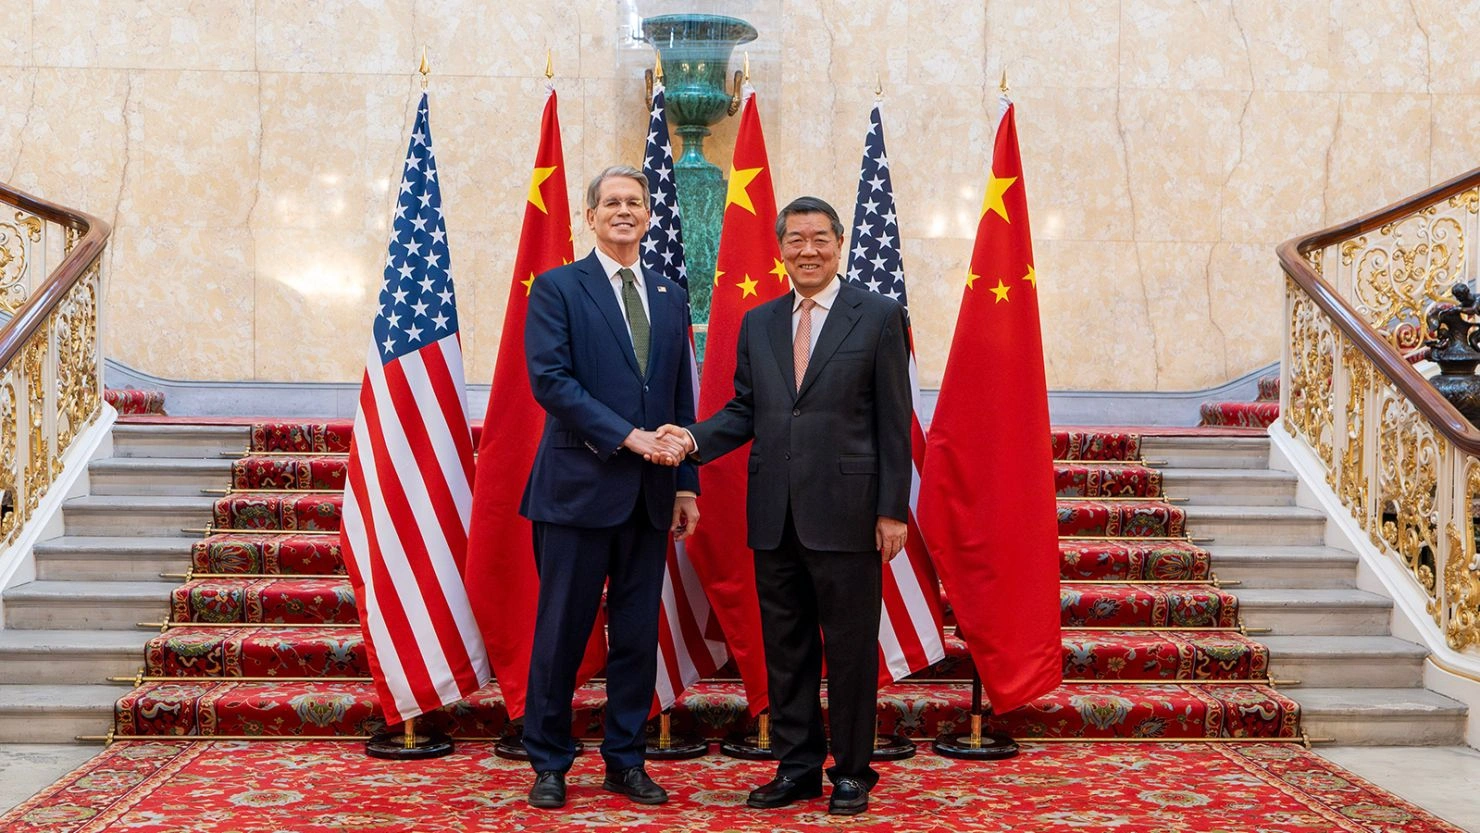
The 16th arrondissement of Paris is not a place that announces itself. Discreet, residential, its wide avenues lined with haussmann facades, it is the kind of neighbourhood where power moves quietly. On Sunday morning, as French voters elsewhere in the city queued outside polling stations for the first round of local elections, a motorcade slipped through those unassuming streets toward the headquarters of the Organisation for Economic Co-operation and Development. Inside, the world’s two largest economies were attempting something rare in 2026: a structured, professional conversation.
Talks began at 10:05 a.m. local time, with Vice-Premier He Lifeng accompanied by Li Chenggang, China’s foremost international trade negotiator, while Treasury Secretary Scott Bessent arrived flanked by US Trade Representative Jamieson Greer. South China Morning Post Unlike previous encounters in European capitals, the delegations were received not by a host-country official but by OECD Secretary-General Mathias Cormann South China Morning Post — a small detail that spoke volumes. France was absorbed in its own democratic ritual. The world’s most consequential bilateral relationship was, once again, largely on its own.
The Stakes in Paris: More Than a Warm-Up Act
It would be tempting to dismiss the Paris talks as logistical scaffolding for a grander event — namely, President Donald Trump’s planned visit to Beijing at the end of March for a face-to-face with President Xi Jinping. That reading would be a mistake. The discussions are expected to cover US tariff adjustments, Chinese exports of rare earth minerals and magnets, American high-tech export controls, and Chinese purchases of US agricultural commodities CNBC — a cluster of issues that, taken together, constitute the structural skeleton of the bilateral relationship.
Analysts cautioned that with limited preparation time and Washington’s strategic focus consumed by the US-Israeli military campaign against Iran, the prospects for any significant breakthrough — either in Paris or at the Beijing summit — remain constrained. Investing.com As Scott Kennedy, a China economics specialist at the Center for Strategic and International Studies, put it with characteristic precision: “Both sides, I think, have a minimum goal of having a meeting which sort of keeps things together and avoids a rupture and re-escalation of tensions.” Yahoo!
That minimum — preserving the architecture of the relationship, not remodelling it — may, in the current environment, be ambitious enough.
Busan’s Ledger: What Has Been Delivered, and What Has Not
The two delegations were expected to review progress against the commitments enshrined in the October 2025 trade truce brokered by Trump and Xi on the sidelines of the APEC summit in Busan, South Korea. Yahoo! On certain metrics, the scorecard is encouraging. Washington officials, including Bessent himself, have confirmed that China has broadly honoured its agricultural obligations under the deal Business Standard — a meaningful signal at a moment when diplomatic goodwill is scarce.
The soybean numbers are notable. China committed to purchasing 12 million metric tonnes of US soybeans in the 2025 marketing year, with an escalation to 25 million tonnes in 2026 — a procurement schedule that begins with the autumn harvest. Yahoo! For Midwestern farmers and the commodity desks that serve them, these are not abstractions; they are the difference between a profitable season and a foreclosure notice.
But the picture darkens considerably when attention shifts to critical materials. US aerospace manufacturers and semiconductor companies are experiencing acute shortages of rare earth elements, including yttrium — a mineral indispensable in the heat-resistant coatings that protect jet engine components — and China, which controls an estimated 60 percent of global rare earth production, has not yet extended full export access to these sectors. CNBC According to William Chou, a senior fellow at the Hudson Institute, “US priorities will likely be about agricultural purchases by China and greater access to Chinese rare earths in the short term” Business Standard at the Paris talks — a formulation that implies urgency without optimism.
The supply chain implications are already registering. Defence contractors reliant on rare-earth permanent magnets for guidance systems, electric motors in next-generation aircraft, and precision sensors are operating on diminished buffers. The Paris talks, if they yield anything concrete, may need to yield this above all.
A New Irritant: Section 301 Returns
Against this backdrop of incremental compliance and unresolved bottlenecks, the US side has introduced a fresh complication. Treasury Secretary Bessent and USTR Greer are bringing to Paris a new Section 301 trade investigation targeting China and 15 other major trading partners CNBC — a revival of the legal mechanism previously used to justify sweeping tariffs during the first Trump administration. The signal it sends is deliberately mixed: Washington is simultaneously seeking to consolidate the Busan framework and reserving the right to escalate it.
For Chinese negotiators, the juxtaposition is not lost. Beijing has staked considerable domestic political credibility on the proposition that engagement with Washington produces tangible results. A Section 301 investigation, even if procedurally nascent, raises the spectre of a new tariff architecture layered atop the existing one — and complicates the case for continued compliance within China’s own policy bureaucracy.
The Hormuz Variable: When Geopolitics Enters the Room
No diplomatic meeting in March 2026 can be quarantined from the wider strategic environment, and the Paris talks are no exception. The ongoing US-Israeli military campaign against Iran has introduced a variable of potentially severe economic consequence: the partial closure of the Strait of Hormuz, the narrow waterway through which approximately a fifth of the world’s oil passes.
China sources roughly 45 percent of its imported oil through the Strait, making any disruption there a direct threat to its industrial output and energy security. Business Standard After US forces struck Iran’s Kharg Island oil loading facility and Tehran signalled retaliatory intent, President Trump called on other nations to assist in protecting maritime passage through the Strait. CNBC Bessent, for his part, issued a 30-day sanctions waiver to permit the sale of Russian oil currently stranded on tankers at sea CNBC — a pragmatic, if politically contorted, attempt to soften the energy-price spike.
For the Paris talks, the Hormuz dimension introduces a paradox. China has an acute economic interest in stabilising global oil flows and might, in principle, be receptive to coordinating with the United States on maritime security. Yet Beijing’s deep reluctance to be seen as endorsing or facilitating US-led military operations in the Middle East constrains how far it can go. The corridor between shared interest and political optics is narrow.
What Trump Wants in Beijing — and What Xi Can Deliver
With Trump’s Beijing visit now functioning as the near-term endpoint of this diplomatic process, the outlines of a summit package are beginning to take shape. The US president is expected to seek major new Chinese commitments on Boeing aircraft orders and expanded purchases of American liquefied natural gas Yahoo! — both commercially significant and symbolically resonant for domestic audiences. Boeing’s recovery from years of regulatory and reputational turbulence has made its order book a quasi-barometer of US industrial confidence; LNG exports represent a strategic diversification of American energy diplomacy.
For Xi, the calculus involves threading a needle between delivering enough to make the summit worthwhile and conceding so much that it invites criticism at home from nationalist constituencies already sceptical of engagement. China’s state media has consistently characterised the Paris talks as a potential “stabilising anchor” for an increasingly uncertain global economy Republic World — language carefully chosen to frame engagement as prudent statecraft rather than capitulation.
The OECD itself, whose headquarters serves as neutral ground for today’s meeting, cut its global growth forecast earlier this year amid trade fragmentation fears — underscoring that the bilateral relationship between Washington and Beijing carries systemic weight far beyond its two principals. A credible summit, even one short of transformative, would send a signal to investment desks and central banks from Frankfurt to Singapore that the world’s two largest economies retain the institutional capacity to manage their rivalry.
The Road to Beijing, and Beyond
What happens in the 16th arrondissement today will not resolve the structural tensions that define the US-China relationship in this decade. The rare-earth bottleneck is systemic, not administrative. The Section 301 investigation reflects a bipartisan American political consensus that China’s industrial subsidies represent an existential competitive threat. And the Iran war has introduced a geopolitical variable that neither side fully controls.
But the Paris talks serve a purpose that transcends their immediate agenda. They demonstrate, to a watching world, that diplomacy between great powers remains possible even as military operations unfold and supply chains fracture. They keep open the channels through which, eventually, more durable arrangements might be negotiated — whether at a Beijing summit, at the G20 in Johannesburg later this year, or in another European capital where motorcades slip, unannounced, through quiet streets.
The minimum goal, as CSIS’s Kennedy observed, is avoiding rupture. In the spring of 2026, with the Strait of Hormuz partially closed and yttrium shipments stalled, that minimum has acquired the weight of ambition.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025