
Social Security
Social Security Payments in November 2026: The Full Calendar and Two Important Changes

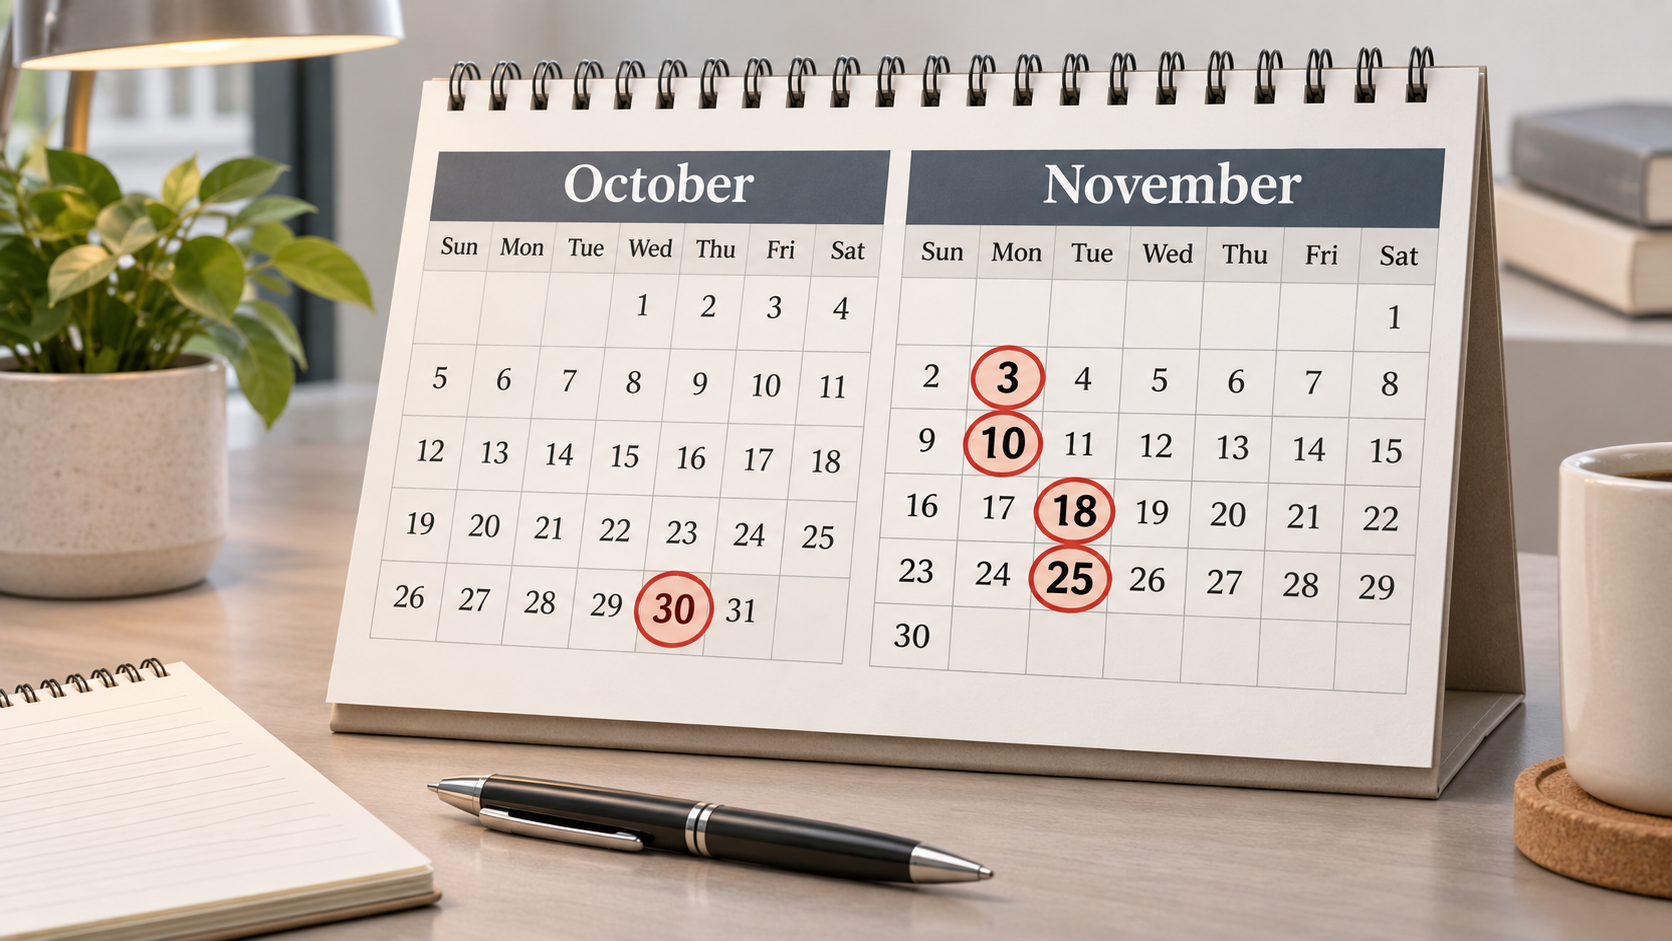
Payment dates depend on the benefit program and the worker’s earnings-record date of birth, with exceptions for long-standing beneficiaries and certain other categories. Always use the Social Security Administration’s payment-calendar hub to check the official schedule.
Quick answer: November 2026 payment dates are October 30 for November SSI; November 3 for many pre-May-1997 or dual-benefit recipients; November 10 for the first birthday cohort (moved from the Veterans Day holiday); November 18 for the second birthday cohort; and November 25 for the third. The SSA’s holiday-payment rule explains why scheduled payments move to the prior business day.
The verified November 2026 payment calendar
| Deposit date | Benefit category | Why this date? |
|---|---|---|
| Friday, October 30, 2026 | November Supplemental Security Income (SSI) | November 1 is a Sunday; SSI normally pays on the first |
| Tuesday, November 3, 2026 | Most people who began Social Security before May 1997 or receive both Social Security and SSI; some other exception groups | Special third-of-month payment cycle |
| Tuesday, November 10, 2026 | Most regular Social Security beneficiaries whose relevant birth date is the 1st–10th | Second Wednesday is Veterans Day, November 11 |
| Wednesday, November 18, 2026 | Most regular beneficiaries whose relevant birth date is the 11th–20th | Third Wednesday of November |
| Wednesday, November 25, 2026 | Most regular beneficiaries whose relevant birth date is the 21st–31st | Fourth Wednesday of November |
The dates follow the SSA’s scheduled-benefit system, the agency’s holiday-payment policy, and the November interpretation published by AARP’s payment guide, updated October 30. Receiving an SSI deposit on October 30 does not mean November’s SSI benefit has disappeared; the benefit for November was paid ahead of the calendar month.
Why the November SSI payment came in October
SSI is administered by Social Security, but it is not the same program as retirement benefits or Social Security Disability Insurance. It is designed for eligible people with limited income and resources who are aged 65 or older, blind or disabled. Its normal monthly payment date is the first day of the calendar month. Because November 1, 2026 fell on a Sunday, SSA advanced the November SSI payment to the preceding business day, Friday, October 30.
This creates an optical illusion in account histories. Some beneficiaries saw two SSI payment dates in October—one for October and another for November—and may see no separate SSI deposit dated within November. It is not, by itself, a missed payment or an extra benefit. The correct comparison is the benefit month to which a deposit relates, not simply the count of deposits posted between the first and last calendar dates of October.
The SSA’s official FAQ states that when a regularly scheduled benefit date falls on a Saturday, Sunday or legal public holiday, payment is made on the business day before. That general rule is the essential explanation for November’s SSI pattern. A beneficiary who uses separate accounts or receives both SSI and retirement or disability benefits should look at each payment entry individually.
Why November 10 replaces the expected November 11 deposit
For most people in the first birth-date group, Social Security is ordinarily paid on the second Wednesday of the month. In November 2026 that Wednesday is November 11, which is Veterans Day, a U.S. federal holiday. Under SSA’s holiday rule, the payment moves to Tuesday, November 10. The agency’s 2026 holiday listing confirms the Veterans Day observance.
This shift matters for budgeting because some websites mechanically list the “second Wednesday” without accounting for holidays. A reader who sees November 11 in a generic calendar might think the payment was delayed or missed when the actual scheduled issuance date was a day earlier. The AARP benefits schedule independently reports the November 10 adjustment.
A payment date is not a promise that every financial institution displays the funds at precisely the same hour. Electronic posting processes, account status and bank practices can affect the time you see a deposit. Do not assume that an early bank credit in a previous month created a new guaranteed government schedule.
Which birthday determines the Wednesday payment?
The SSA’s recurring payment FAQ explains the general date-of-birth groups: birth days 1–10 go to the second Wednesday, days 11–20 the third, and days 21–31 the fourth. But the relevant birthday can be the insured worker whose earnings record supports the benefit, not necessarily the birthday of the family member who receives a dependent or survivor payment.
Consider a surviving spouse who receives a benefit on a deceased worker’s record. The date-of-birth cycle can be linked to the worker’s birthday under SSA rules. Likewise, beneficiaries who receive on someone else’s earnings record should not automatically apply their own birth-date grouping. The Social Security regulations address payment-day assignments for benefits on the same earnings record.
Older beneficiaries and some people receiving both SSI and Social Security are assigned a different cycle, typically the third of the month. That exception is why a simplified headline saying “everyone born on the 1st–10th is paid November 10” is not quite right. Benefit category and relevant record take priority over a generic birth-date rule.
SSI, retirement, disability and survivor benefits are not interchangeable
SSI is a means-tested program; retirement and SSDI generally derive from Social Security-covered work and eligibility under the insurance system. Survivors’ benefits are tied to a deceased worker’s earnings record, while family benefits may be paid on a living worker’s record. All can involve the SSA, but they do not necessarily share the same payment timing.
The key service-journalism rule is to ask which program is involved before telling a reader the payment is late. Someone receiving both SSI and Social Security may have one deposit moved into October and another on November 3. Someone receiving SSDI but no SSI may be in a Wednesday cycle. A survivor can be on a different birth-date schedule than a friend who receives a retirement benefit of similar size.
When a payment amount differs, calendar explanations are not enough. Medicare premiums, benefit adjustments, recovery of an overpayment, tax withholding or other authorized factors can affect net deposits. Such questions require checking an official individual benefit notice or contacting SSA; a search article cannot determine why a particular person’s deposit changed.
Does the 2027 COLA affect the November 2026 check?
The SSA announced a 3.6% cost-of-living adjustment for 2027 on October 14, 2026. That is a confirmed announcement, not a forecast. However, it should not be added to the November 2026 check simply because the announcement was already public.
The agency says the increase applies to Social Security benefits beginning in January 2027, while the higher January SSI benefit is scheduled for December 31, 2026, because January 1 is a holiday. The SSA 2027 COLA fact sheet contains the principal national figures. An individual beneficiary’s actual net increase can differ from a simple multiplication of their current deposit because personal benefit amounts and deductions are not identical.
A reader who needs to plan winter spending should keep three dates separate: the announcement date, the benefit month and the deposit date. The 2027 policy change has a payment-calendar effect late in 2026 for SSI, but it does not turn ordinary November Social Security checks into 2027 payments.
What if your payment does not appear on the expected date?
First verify that the calendar date actually applies to your benefit. Missing this step can cause unnecessary alarms, particularly in November because two payment dates moved. Second, check the bank or card account to see whether the transaction is pending, credited under a different description or delayed by the institution. Third, read any recent official notice about a benefit, bank information or eligibility change.
The SSA payment calendar publication advises beneficiaries who do not receive payments on the expected date to allow three additional mailing days before contacting Social Security. Electronic-deposit problems may be investigated with the receiving institution as well. Avoid giving passwords, bank access codes or Social Security numbers to someone claiming in a text message that they can “release” a delayed payment.
If a payment remains missing, contact SSA through official channels and have the payment month, program and account information available in a secure setting. Do not post account identifiers on a public article’s comment thread. Government benefits generate many phishing attempts precisely when recipients are worried about timing.
Budgeting with staggered deposits
Monthly bills often arrive on calendar dates that do not track Wednesday cycles. If the rent is due before a scheduled deposit, a beneficiary may need to coordinate with a landlord, a utility provider or other institution in advance. The November 10 adjustment may help one group slightly, but the October 30 SSI payment is November’s money, not a windfall for extra spending in October.
A practical budget labels each deposit by benefit month and reserves enough for fixed expenses until the next scheduled payment. Some households receiving benefits on different records have two separate cycles. Avoid counting an anticipated 2027 COLA amount until you have checked the SSA notice for the actual personal figure.
Frequently asked questions
Is there an SSI payment in November 2026?
The November SSI benefit was scheduled to be paid October 30, because November 1 was Sunday. That is why many recipients do not see a separate SSI deposit dated in November.
Why am I being paid on Tuesday, November 10?
Your usual second-Wednesday Social Security payment falls on Veterans Day, November 11. SSA advances holiday payments to the prior business day.
Who gets Social Security on November 3?
It generally includes certain pre-May-1997 beneficiaries and people receiving both SSI and Social Security, as well as other eligible exception categories. Verify your own benefit cycle with SSA.
Will Thanksgiving delay November 25 benefits?
The fourth Wednesday is November 25, a day before Thanksgiving in 2026, so the regular fourth-Wednesday benefit is not moved by that holiday under the general rule.
Does the new 3.6% COLA arrive in November?
No. The 2027 COLA starts with 2027 benefit payments, with higher January SSI benefits beginning December 31, 2026.
Can I request a different Social Security payday?
The SSA FAQ generally says recurring payment dates cannot be changed merely on request. Particular exceptions are governed by agency rules.
What to do next
Identify your benefit program, the earnings record on which it is paid and whether you belong to a third-of-month exception group. Use the SSA official calendar to confirm the date and the 2027 COLA notice for future changes. For November 2026, the essential point is that two deposit days changed because of weekends and federal holidays—not because beneficiaries universally gained or lost a payment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


If you receive Supplemental Security Income (SSI), the benefit for November 2026 is scheduled to arrive on Friday, October 30, 2026, not on November 1. The explanation is straightforward: November 1 falls on a Sunday, and the Social Security Administration moves the payment to the preceding business day. This is a change in timing, not an additional benefit. There is no separate nationwide “November bonus” created by the calendar adjustment. The date appears in the SSA’s official 2026 payment calendar, which recipients should use in preference to viral claims about a surprise deposit.
For people budgeting rent, prescriptions or food, the distinction matters. A payment arriving before November begins still needs to last through November. It does not mean that every SSI recipient receives two November payments, that an application has been approved, or that their monthly benefit amount has increased.
The dates that matter: October through January
| Benefit month | Regular first-of-month date | Scheduled SSI payment | Why |
|---|---|---|---|
| October 2026 | Thursday, October 1 | Thursday, October 1 | Normal weekday |
| November 2026 | Sunday, November 1 | Friday, October 30 | Weekend adjustment |
| December 2026 | Tuesday, December 1 | Tuesday, December 1 | Normal weekday |
| January 2027 | Friday, January 1 | Thursday, December 31, 2026 | Federal holiday adjustment |
The first three entries are visible on the SSA’s 2026 calendar. The final entry is the start-of-2027 timing shown in the agency’s schedule; verify the 2027 calendar again near year-end. A benefit month describes the month a payment supports, not necessarily the month in which the bank account shows a credit. That single distinction resolves much of the confusion produced by payment-date headlines.
Why the November 1 weekend matters
SSI usually follows the first calendar day of each month. When that date falls on a weekend or federal holiday, the government schedules the disbursement earlier, on a day banks can process the payment. In 2026, November 1 is a Sunday. The immediately preceding Friday is October 30. This produces a payment in October that is for November.
The SSA’s calendar marks SSI dates separately from the shaded dates for retirement and other Social Security payments. Reading only the large October box while ignoring the calendar’s legend can produce the false impression that October 30 represents an unusual new program. It does not. It is an established scheduling practice, relevant this year because of the placement of the weekend.
Financial institutions can have different posting and notification practices. An employer-like “early direct deposit” feature offered by a bank is not the same thing as an official federal benefit date. Some accounts may display funds or pending transactions differently, but a recipient should rely on the SSA’s scheduled date rather than expect an earlier bank-specific credit.
Does SSI pay twice in October 2026?
In the sense of calendar entries, yes: eligible recipients ordinarily have the October benefit on October 1 and the November benefit on October 30. But those are two different benefit months. They are not two October entitlements, a double November payment or an increase to the benefit formula.
Consider a fictional recipient who has $200 remaining after paying October expenses on October 29. If the November SSI payment arrives on October 30, that new money may make the account balance look temporarily larger. But the money is intended to meet November’s costs. Spending it as a windfall could create difficulty before the next scheduled payment on December 1. The gap between the two dates may feel unusually long simply because November’s payment has been brought forward.
The reverse calendar pattern can also confuse recipients. At the end of December 2026, the January 2027 SSI payment is scheduled early because New Year’s Day is a holiday. A bank statement can therefore show two SSI deposits during December, but no separate SSI deposit on January 1. This is not evidence of a missed January entitlement. The same logic applies to the October–November transition.
SSI is not the same as Social Security retirement or SSDI
The terms are frequently bundled together in search results, but the programs are legally and administratively distinct. Supplemental Security Income is a federal benefit for qualifying people who have limited income and resources and meet age, blindness or disability requirements. Eligibility depends on multiple rules, including qualifying residence and citizenship or immigration categories. The SSA’s 2026 SSI eligibility explanation sets out the criteria.
Social Security retirement benefits, by contrast, generally draw on insured work records. Social Security Disability Insurance, or SSDI, likewise depends on covered work and disability rules. Their regular disbursement dates are not automatically identical to SSI. On the SSA calendar, many retirement and disability beneficiaries are grouped by birth date, receiving benefits on the second, third or fourth Wednesday of the month.
There are exceptions. People who began receiving Social Security before May 1997 and some individuals receiving both Social Security and SSI follow other schedule rules. A person receiving more than one program should distinguish the two payments before concluding that an amount is missing or doubled. The calendar’s legend explains the categories, while an individual’s SSA notice is the more precise account-level source.
A comparison for anyone checking a bank statement
| Question | SSI | Social Security retirement/SSDI |
|---|---|---|
| Broad basis | Income/resources plus qualifying age, blindness or disability | Insured work history and program requirements |
| Typical scheduled date | First of the month, moved earlier when needed | Often Wednesday birth-date schedule, with exceptions |
| November 2026 date | October 30 | Not automatically October 30 |
| Correct way to confirm | Official SSI payment calendar and award notice | SSA benefit schedule and personal record |
Do not use a newspaper’s generalized phrase “Social Security check” as proof that your own payment should arrive on October 30. The specific program is what determines the expected date.
Will every eligible person receive the same amount?
No. SSI payment levels are affected by the applicable federal benefit rate, countable income, living arrangements and other rules. Some states provide supplements. Being eligible for SSI does not necessarily mean receiving the maximum federal amount. The SSA’s federal SSI payment amounts page explains the maximum benefit framework; an individualized determination controls what a recipient actually receives.
The November scheduling shift does not revise the benefit rate or alter annual cost-of-living adjustment rules. If a recipient sees a changed deposit amount, possible explanations include a reported earnings change, a living-arrangement determination, an overpayment recovery or another administrative adjustment. None should be assumed without checking the SSA notice. A one-off rumor circulating online is not adequate evidence of a systemwide increase.
If you work while receiving SSI, reporting rules remain important even when a payment posts early. An early posting date is not permission to ignore wage, household or resource requirements. If circumstances changed, use the channels specified by SSA to report them. Where a notice is unclear, request an explanation before making financial decisions around an assumed ongoing payment amount.
What to do if the October 30 payment does not arrive
First, verify that you are expecting SSI, rather than retirement, survivors or SSDI benefits. Next, inspect the bank or Direct Express account used for your benefits; look for posted transactions and not just alerts. A pending transfer, a failed notification and a genuinely missing payment are different problems.
The SSA’s official benefit calendar advises people who do not receive a payment on the expected date to allow three additional mailing days before contacting Social Security. If you receive a check by mail, account for delivery time; if your normal payment is direct deposit, ask the financial institution whether it has received or rejected a payment. Do not share account credentials with a person claiming to expedite a deposit on social media.
If the money still is not available, contact the SSA through its official contact options or your local field office. Keep your payment notice, bank statement and dates handy. SSA can investigate an issuance problem, while a bank can explain posting or account restrictions. Reporting a missing payment accurately is more productive than filing multiple duplicate requests based solely on an online screenshot.
A change in bank details, a closed account or a recently updated benefit record can make investigation more complicated. Keep dated notes of who you contacted and what they advised, without distributing a Social Security number publicly. If the amount is unexpectedly reduced rather than missing, request the written benefit determination or overpayment explanation relevant to your case.
The budgeting problem created by early SSI dates
The risk is not that SSA withholds the November benefit. The practical risk is treating money as extra because it arrived before the month starts. A simple planning rule is to label the October 30 deposit “November essentials” in your budget. Allocate expected rent, utilities, medication, transport and groceries before optional spending. This is not a requirement of SSA; it is household cash-flow advice.
Suppose someone usually pays rent on November 1 and receives SSI on the same day. This year, the deposit is two days earlier. Setting aside the rent money on October 30 helps keep the weekend timing from changing the intended purpose of the benefit. If the recipient pays other bills on an automatic debit schedule, the earlier arrival does not necessarily change the debit dates.
Do the same when a late-month deposit appears just before a holiday. The temptation to budget by “number of deposits this month” can be misleading. Budgeting by benefit month avoids that trap and makes the next due date easier to anticipate. It is particularly important when household expenses are fixed and the recipient has little cash buffer.
Questions readers are asking
Is November SSI being paid on Friday, October 30, 2026?
Yes. The SSA’s 2026 payment schedule places the November SSI payment on October 30 because November 1 is a Sunday. That is the scheduled date, not a guarantee of an individual account’s real-time bank display.
Is October 30 an extra $200, $500 or other bonus?
No. The calendar change alone creates no supplementary nationwide benefit or bonus. Claims of specific unexpected bonus amounts require a separate lawful program announcement; none follows from the weekend shift.
Will there be another SSI deposit on November 1?
The ordinary November payment is moved to October 30. There is not normally a second payment for November on Sunday, November 1. If your record involves a correction or special issuance, SSA—not social media—must confirm it.
Why can two deposits appear in December 2026?
December’s regular SSI payment is scheduled on December 1. The payment for January 2027 is scheduled early on December 31 because January 1 is a holiday. Two dates in December do not mean two December benefit months.
Does the date apply to people who get Social Security retirement?
Not simply because they get Social Security. Most retirement and SSDI recipients use different dates. Check the SSA schedule’s payment categories and your personal notice.
Bottom line
The central fact is both simple and consequential: November 2026 SSI is scheduled for October 30, 2026. It is an earlier issuance of the regular November benefit, not extra money. Use the official federal calendar for the date, your personal benefit notice for the amount and an SSA contact channel if a genuinely expected payment does not arrive. The best protection against a misleading “double-payment” headline is knowing which month each deposit is actually paying for.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The Social Security Administration confirmed a 3.6% cost-of-living increase on October 14, 2026. Retirement and other Social Security payments rise beginning in January 2027, while adjusted SSI payments start December 31, 2026.
The Social Security Administration officially announced a 3.6% COLA on October 14, 2026, with January 2027 benefits affected and SSI increases beginning December 31, 2026. References to an unannounced 2027 COLA in the original article are superseded by this update. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
The Social Security Administration officially announced a 3.6% COLA on October 14, 2026, with January 2027 benefits affected and SSI increases beginning December 31, 2026. References to an unannounced 2027 COLA in the original article are superseded by this update. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
The 2027 Social Security cost-of-living adjustment was officially announced as 3.6% on October 14, 2026. The Bureau of Labor Statistics plans to release September inflation figures on October 14, supplying the final monthly input needed for the third-quarter calculation. Social Security says it will announce the next COLA in October. Avoid websites that state a projected percentage as though it were a confirmed benefit increase. Sources: Social Security Administration and SSA COLA announcement summary.
The important context competitors can overlook
The adjustment compares the July-to-September average of the CPI-W with the corresponding average in the prior base period, then rounds the percentage increase to one decimal place. It is not based simply on September year-over-year headline CPI. The confirmed 2026 COLA was 2.8%, which is an historical reference, not the 2027 outcome. With the percentage now announced, Medicare deductions, withholding and individual benefit amounts can make net deposits differ from a headline example. For primary-source checks and current reporting, see Social Security Administration and Bureau of Labor Statistics calendar. The key distinction is the confirmed 3.6% adjustment versus individualized net deposits.
A practical way to use this information
Bookmark the SSA COLA page rather than a social post. After the announcement, multiply your existing gross monthly amount by 1 plus the new rate and round only as the agency requires for your benefit. Compare that estimate with your official SSA notice and any Medicare premiums before adjusting a monthly spending plan. A $2,000 base and the confirmed 3.6% adjustment imply approximately $72 extra gross per month before rounding or deductions; the final individualized figure comes from SSA.
How a COLA percentage changes a monthly check
The arithmetic is useful only once the official COLA is known. The examples below are hypothetical gross increases, not predictions and not net deposits.
| Monthly benefit before adjustment | Hypothetical 2% raise | Hypothetical 3% raise | Hypothetical 4% raise |
|---|---|---|---|
| $1,500 | $30 | $45 | $60 |
| $2,000 | $40 | $60 | $80 |
| $2,500 | $50 | $75 | $100 |
After the agency announces the figure, replace the illustrative columns with the actual rate. Avoid treating the BLS September release date as a promise of an identically timed SSA announcement. The agency itself controls publication of its benefit tables and notices.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Has the 2027 COLA been announced? Yes. The SSA announced a 3.6% 2027 COLA on October 14, 2026.
When will new benefits arrive? The COLA is effective for December benefits generally paid in January; SSI has its own payment timing.
Why the CPI-W formula matters more than a prediction
The annual cost-of-living adjustment is designed to track price changes, not to reward beneficiaries for additional years of service or compensate every household for its exact spending mix. SSA compares the average Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) in July, August and September against the average from the last third quarter used to set a COLA. When the resulting percentage is positive, benefits are adjusted under the statutory formula. This means an unusually high single monthly inflation reading does not translate mechanically into an equally large annual raise. Readers who see forecasts from analysts should check which CPI-W releases were actually available when those forecasts were written.
Housing, food, healthcare and transportation costs can affect retirees differently from the CPI-W basket. A person who spends an unusually large share of their income on prescriptions or rent may experience greater pressure than the national index indicates. Conversely, people with fixed-rate mortgages and limited transportation expenses may experience a different inflation profile. The COLA is a national adjustment; it does not separately calculate the cost of living in Florida, California or any other state. It also does not directly determine a person’s eligibility for each unrelated assistance program.
Gross benefits, deposits and Medicare: three different numbers
A benefit increase is applied to the underlying Social Security calculation, but the amount landing in a bank account can depend on other items. Some beneficiaries have Medicare Part B premiums withheld. Others elect voluntary federal tax withholding or have deductions tied to particular circumstances. For a household budget, the relevant comparison is therefore last year’s net deposit against the next year’s net deposit, not simply the COLA rate multiplied by today’s direct deposit. Look at the gross amount, each deduction and the final payment separately when the benefit notice arrives.
For example, assume an illustrative gross benefit of $1,900 and a hypothetical 2.5% adjustment. The gross increase would be $47.50 before agency rounding and any deduction changes. If a separate monthly deduction also rises, the bank deposit will increase by less than $47.50. This is arithmetic, not a prediction of the coming COLA or Medicare premium. Check current Medicare information through Medicare.gov rather than assuming a headline on Social Security automatically describes Medicare costs.
A household budget test using the confirmed 3.6% increase
Retirees can now prepare using the confirmed 3.6% percentage. Start with a list of recurring essentials: housing, utilities, groceries, healthcare, transportation and debt payments. Identify which bills have already increased or will renew early in 2027. Then create three scenarios—no meaningful net increase, a modest net increase and a higher net increase—and test whether the monthly budget remains workable. The point is not to forecast the government announcement. It is to learn whether an existing emergency fund or spending adjustment would be needed if inflation remains elevated despite a benefit change.
For couples, include whether both people receive Social Security benefits, whether either has wages, and whether the household has pension or investment income. Someone receiving Supplemental Security Income should check SSI-specific payment information rather than simply applying a retired-worker example. Survivors and disability beneficiaries should also rely on their own SSA notices. A household with multiple benefit types should not assume every payment has identical timing or deductions.
Avoid misleading COLA headlines and scams
Historically, before the official announcement, headlines mixed forecasts, the prior year’s adjustment, preliminary CPI data and the amount of a hypothetical average check. Those are four different things. A correct headline should say whether the adjustment is estimated or official, give the year to which it applies and link directly to the issuing agency. Once confirmed, the actual percentage should be used consistently in every table, search snippet and social caption. If an older story stays live, label the update date prominently; search traffic can continue long after the numbers change.
Beneficiaries do not need to pay a third party to activate a standard COLA. Treat unsolicited calls or messages requesting a Social Security number, payment or banking credentials as suspicious. Navigate directly to SSA’s official website or your established account rather than following an unexpected text link. A legitimate forecast can help with planning; it is not a substitute for a personalized benefit notice.
Questions beneficiaries should ask after the release
- What official 2027 COLA percentage did SSA announce, and on what date?
- Does the statement show gross benefits as well as Medicare and other deductions?
- When will the relevant January or SSI payment be issued under the official calendar?
- Is a reported “average increase” describing all beneficiaries or a selected benefit category?
- Has any tax withholding or household income changed independently of the COLA?
These checks turn a widely searched announcement into information a retiree can actually use. The strongest article on this subject does not merely repeat a percentage: it explains where that number came from and why two beneficiaries can see different dollar changes.
How to calculate the confirmed 3.6% increase
For an illustrative $1,500 monthly gross benefit, a 3.6% increase equals $54 and produces an estimated $1,554 gross amount before any deductions or rounding. A $2,000 monthly gross benefit produces a $72 illustrative monthly increase; $2,500 produces $90. These examples are arithmetic, not individual benefit estimates, and should not be confused with take-home deposits. Medicare premiums, withholding and other adjustments can make the deposit different from the COLA multiplication. The agency says the average retiree increase is around $75; an average does not mean every recipient gets exactly that amount. See the official COLA announcement and 2027 SSA fact sheet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Social Security
Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check
The 2027 Social Security cost-of-living adjustment has not been officially announced as of October 12, 2026. This analysis is based on information available at the research cutoff; verify developing prices, schedules and rules before publication.
The 2027 Social Security cost-of-living adjustment has not been officially announced as of October 12, 2026. The Bureau of Labor Statistics plans to release September inflation figures on October 14, supplying the final monthly input needed for the third-quarter calculation. Social Security says it will announce the next COLA in October. Avoid websites that state a projected percentage as though it were a confirmed benefit increase. Sources: Social Security Administration and SSA COLA announcement summary.
The important context competitors can overlook
The adjustment compares the July-to-September average of the CPI-W with the corresponding average in the prior base period, then rounds the percentage increase to one decimal place. It is not based simply on September year-over-year headline CPI. The confirmed 2026 COLA was 2.8%, which is an historical reference, not the 2027 outcome. Even once the percentage is announced, Medicare deductions, withholding and individual benefit amounts can make net deposits differ from a headline example. For primary-source checks and current reporting, see Social Security Administration and Bureau of Labor Statistics calendar. The key distinction is pre-announcement accuracy; translate formula into household budget.
A practical way to use this information
Bookmark the SSA COLA page rather than a social post. After the announcement, multiply your existing gross monthly amount by 1 plus the new rate and round only as the agency requires for your benefit. Compare that estimate with your official SSA notice and any Medicare premiums before adjusting a monthly spending plan. A $2,000 base and a hypothetical 3% adjustment would mean $60 more gross per month; 3% here is only an illustration, not a forecast.
How a COLA percentage changes a monthly check
The arithmetic is useful only once the official COLA is known. The examples below are hypothetical gross increases, not predictions and not net deposits.
| Monthly benefit before adjustment | Hypothetical 2% raise | Hypothetical 3% raise | Hypothetical 4% raise |
|---|---|---|---|
| $1,500 | $30 | $45 | $60 |
| $2,000 | $40 | $60 | $80 |
| $2,500 | $50 | $75 | $100 |
After the agency announces the figure, replace the illustrative columns with the actual rate. Avoid treating the BLS September release date as a promise of an identically timed SSA announcement. The agency itself controls publication of its benefit tables and notices.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Has the 2027 COLA been announced?
No official 2027 percentage was available in the SSA material checked on October 12, 2026.
When will new benefits arrive?
The COLA is effective for December benefits generally paid in January; SSI has its own payment timing.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Social Security Payments in November 2026: The Full Calendar and Two Important Changes

Johor–Singapore SEZ’s $21.8 Billion Bet: The Hard Part Starts Now

China’s 175 Trillion AI Tokens Reveal a Bigger Shift: The AI Boom

The Philippines’ Stagflation Trap: Higher Interest Rates

Alphabet’s $500 Billion Reckoning: Wall Street Is Losing Patience With the AI Boom

4 Reasons Why China’s Trade Concessions to Europe Will Not Solve the Crisis

The AI Revolution Needs Atomic Power. Southeast Asia Is Ready to Build It.

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

The $8 Billion Runway: China’s Strategic Bet on Guangzhou and the Future of Aviation

The Sandbox Imperium: Why Beijing’s Digital Yuan Needs Hong Kong

Gold at the $4,000 Line: Possible December Fed Hike

Oil at $100+: Hormuz, a Qatari Peace Draft and the Iran Deadline

The Fed’s 10-2 Hold: Why Two Dissenters Wanted a Rate Hike

SBP Raises Policy Rate to 12%: What It Means for Your Loans, Savings and Business

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025