
Global Economy
Beyond the Bailout: Dismantling the Machinery of Pakistan’s Debt Trap

Pakistan has returned to the International Monetary Fund twenty-three times. Twenty-three. At some point, the conversation must shift from “how do we secure the next program” to “why does the machinery keep breaking down?”
The answer is not technical. It is not about capacity. It is about choice—specifically, the choice to maintain an economic system that rewards extraction over production, protects incumbents over entrants, and treats governance as a series of ad hoc deals rather than enforceable rules.
The Illusion of Planning
Every few years, a new committee is formed. A blueprint is drafted. Exports will be doubled. Investment will flood in. Growth will accelerate. Then nothing happens, because aspirations are not policies.
The real question is simpler: can a business start, scale, and operate without seeking permission at every turn? In Pakistan, the answer is no. The economy runs on discretion, not rules. Tariffs are negotiated. Tax exemptions are lobbied for. Energy prices are political decisions dressed up as technical adjustments.
This is not an economy designed for growth. It is designed for control. And control, by definition, limits entry. When entry is limited, competition dies. When competition dies, so does productivity.
The Energy Albatross
If there is a single sector that deserves to be called “ground zero” of Pakistan’s fiscal collapse, it is energy. The sector is fragmented across nearly two dozen entities, each with overlapping mandates and conflicting incentives. Prices are set not by cost recovery but by political calculus. The result is circular debt—a euphemism for a subsidy black hole that consumes billions annually and forces the government back to the IMF.
According to the World Bank’s Pakistan Development Update, the energy sector’s inefficiencies contribute significantly to the country’s fiscal imbalances. The problem is not technical complexity. It is governance failure. State-owned distribution companies operate as monopolies with no accountability for losses. Tariffs do not reflect costs. Political actors intervene when bills come due.
The solution is not another bailout. It is a shift to cost-reflective pricing, enforced through transparent contracts and independent regulation. This is not ideological. It is arithmetic. You cannot subsidize your way to solvency.
Taxation: From Predation to Participation
Pakistan’s tax system is broken by design. Rates are high for the few already in the net. Exemptions are widespread for those with influence. The result is a narrow base, crushing compliance costs for formal businesses, and a massive informal sector that operates entirely outside the tax system.
The Pakistan Institute of Development Economics (PIDE) Reform Agenda has consistently argued for what should be obvious: if you want more people to pay taxes, make it easier and cheaper to do so. Lower rates. Broaden the base. Remove exemptions. Digitize enforcement so that compliance becomes automatic, not adversarial.
Instead, the system does the opposite. It punishes formality and rewards informality. Businesses stay small to avoid detection. Transactions move to cash. The state responds by raising rates on those it can reach, which pushes more businesses underground.
This is not a growth strategy. It is a slow bleed.
What Growth Actually Requires
Growth is not engineered. It is not the output of a five-year plan or a committee report. Growth happens when firms can enter markets, compete on merit, and scale without bureaucratic gatekeeping.
The Asian Development Bank’s forecasts for Pakistan consistently note that structural constraints—particularly in trade policy, energy costs, and regulatory unpredictability—hold back potential. These are not external shocks. They are internal choices.
The state does not need to “create” growth. It needs to stop blocking it. That means shifting from a permission-based economy to a rules-based one. It means enforcing contracts rather than negotiating exemptions. It means allowing prices to signal costs rather than political preferences.
None of this is radical. It is what every functional economy does.
The Uncomfortable Truth
The IMF is not the problem. It is a symptom. The real problem is a political economy that depends on discretion, rewards rent-seeking, and treats public resources as bargaining chips.
Exiting the IMF permanently requires dismantling that machinery. It requires accepting that the state cannot subsidize, protect, and plan its way to prosperity. It requires shifting the source of economic dynamism from bureaucratic approval to market competition.
This is not a question of ideology. It is a question of survival. Pakistan can continue to seek programs every few years, each time promising reform and delivering adjustment. Or it can confront the fact that the system itself is the obstacle.
The choice, as always, remains political. But the consequences are already visible in the numbers: twenty-three programs and counting. At some point, pattern becomes policy. And the policy, whether deliberate or not, is dependence.
The alternative is not complicated. It is just uncomfortable. Remove the discretion. Enforce the rules. Let competition do its work. Growth will follow. But first, the machinery that prevents it must be dismantled.
The author is an independent economic analyst.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


When the benchmark 10-year U.S. Treasury yield crosses the 5.0% threshold, financial markets undergo a structural paradigm shift. Far beyond a routine spike in borrowing costs, a 5% yield alters the hurdle rate for global capital, re-prices risk across every asset class, and exposes systemic sovereign debt fragilities.
1. The 5.0% Benchmark: Why the “Risk-Free” Rate Reshapes Equities
The 10-year U.S. Treasury note is the foundational anchor of global finance. Its yield represents the risk-free rate ($R_f$) utilized in the Capital Asset Pricing Model (CAPM) and Discounted Cash Flow (DCF) models worldwide.
When $R_f$ rises from 2%–3% to over 5%, the present value of future corporate earnings contracts exponentially.
$$\text{Present Value} = \sum_{t=1}^{n} \frac{CF_t}{(1 + WACC)^t}$$
As the Weighted Average Cost of Capital ($WACC$) climbs alongside Treasury yields:
- Growth Stocks & Big Tech: Long-duration growth equities—where the majority of projected cash flows sit far in the future—suffer the sharpest valuation multiple compressions.
- Equity Risk Premium (ERP) Squeeze: With risk-free Treasury bills yielding 5%, the additional premium required to hold volatile equities shrinks dramatically, prompting institutional capital to migrate from stocks to bonds.
- Corporate Liquidity Crunch: Corporate debt refinancing costs double or triple compared to pre-2022 issuance levels, directly eroding net profit margins reported to the U.S. Securities and Exchange Commission.
2. Macroeconomic Catalysts: What Is Driving the Bond Sell-Off?
The surge to 5%+ yields is driven by three primary structural forces rather than a single economic data point:
┌─────────────────────────────────────────────────────────────────────────┐
│                      DRIVER 1: FISCAL EXPANSION                         │
│  U.S. national debt interest + mandatory entitlement outlays now absorb │
│  ~98% of federal tax revenues (Source: U.S. Treasury Department).       │
└────────────────────────────────────┬────────────────────────────────────┘
                                     │
                                     ▼
┌─────────────────────────────────────────────────────────────────────────┐
│                     DRIVER 2: ISSUANCE MISMATCH                         │
│  84% of 12-month Treasury debt issuance concentrated in short-term T-   │
│  Bills, creating severe rollover sensitivity to rate hikes.             │
└────────────────────────────────────┬────────────────────────────────────┘
                                     │
                                     ▼
┌─────────────────────────────────────────────────────────────────────────┐
│                     DRIVER 3: CAPITAL COMPETITION                       │
│  Corporate AI CAPEX spending (~$700B–$900B/yr) competes with sovereign  │
│  bond issuance for global institutional capital reserves.               │
└─────────────────────────────────────────────────────────────────────────┘
Sovereign Debt & Supply Shock
As documented by the U.S. Department of the Treasury, massive fiscal deficit spending has accelerated net bond issuance. Because traditional central bank buyers engaged in quantitative tightening (QT) while foreign sovereign buyers reduced purchases, price discovery has shifted to price-sensitive private institutional investors who demand higher yields (term premium) to absorb debt supply.
Global Central Bank Tightening Synchronicity
Monetary policy decisions from the Federal Reserve System and global partners—such as the Bank of Japan raising interest rates—have reinforced elevated global rate floors. Official global debt perspectives from the International Monetary Fund highlight how high real yields strain emerging market borrowing capacity.
3. Sector Impact Analysis & Asset Class Vulnerabilities
| Asset Class / Sector | Impact Level | Primary Vulnerability / Opportunity |
| Mega-Cap Big Tech | Moderate to High | CAPEX borrowing costs rise; DCF discount rate expansion reduces forward P/E multiples. |
| Commercial & Residential Real Estate | Severe Headwind | Mortgage rates track 10-year yields; refinancing resets create valuation pressure. |
| Short-Term T-Bills & Money Market | Highly Favorable | Yields above 5% offer competitive risk-adjusted real returns without duration risk. |
| Hard Assets (Gold / Precious Metals) | Strategic Hedge | Fiscal deficit concerns and dollar devaluation risks enhance gold’s monetary status. |
| Asian & Emerging Market Equities | Selective Upside | Valuations in South Korea, Japan, and India trade at significant discounts relative to U.S. multiples. |
4. Tactical Asset Allocation Framework
Navigating a 5%+ Treasury yield environment requires balancing yield capture, capital preservation, and equity growth.
Core Portfolio Takeaways
- The Cash-Equivalent Shield: Allocating 35% to short-dated T-Bills mimics Warren Buffett’s liquidity strategy at Berkshire Hathaway, locking in 5%+ yields while preserving optionality for market corrections as reported by CNBC Markets.
- Selective Equity Quality: Focus equity exposure on companies with pristine balance sheets, low debt-to-equity ratios, and pricing power capable of outrunning inflation.
- Monetary Hedges: Gold and hard assets provide downside protection against potential currency weakness if central banks step in to cap bond yields through yield curve intervention. Further macroeconomic debt analysis is regularly updated by Bloomberg Markets and Reuters Financial News.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
IMF sees 3.0% global growth in 2026, the World Bank just 2.5%. Compare Europe and Asia forecasts, the gap between them, and what it means for capital.
Executive Summary / Key Takeaways
- The IMF’s July 2026 World Economic Outlook Update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average of 2024–25.
- The World Bank’s June 2026 Global Economic Prospects is far darker: 2.5% in 2026, the weakest since the pandemic, with two-thirds of economies downgraded since January.
- The two institutions are not contradicting each other — they use different weighting methodologies — but the direction of both revisions is the same, and the driver is the Middle East war.
- Europe and Central Asia was cut to 2.1% for 2026; East Asia and Pacific to 4.2%. The Middle East, North Africa, Afghanistan and Pakistan region takes the worst hit at 1.6%.
- The divergence that matters for allocators is not regional but structural: economies plugged into the AI-led technology cycle are outperforming energy importers that are not.
1. Introduction & Immediate Context
Two flagship forecasts, two very different headline numbers, one identical story underneath. Anyone building a 2027 capital plan needs to understand why.
The IMF’s July update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average observed across 2024–25 and broadly unchanged on a cumulative basis from the April 2026 World Economic Outlook. The Fund attributes the modest slowdown to the effects of the war in the Middle East, partly offset by accelerated demand-driven momentum in the global technology cycle thanks to advances in artificial intelligence and its adoption.
The World Bank is blunter. It forecasts global growth slowing to 2.5% in 2026 from 2.9% in 2025 — the lowest rate since the onset of the COVID-19 pandemic — amid higher energy prices, steeper inflation and increased borrowing costs. Forecasts for two-thirds of economies were downgraded relative to January. Growth is expected to improve to 2.8% in 2027 but will remain 0.4 percentage point below the 2010s average.
The gap between 3.0% and 2.5% is largely methodological: the IMF aggregates at purchasing-power-parity weights, the World Bank at market exchange rates, which gives slower-growing advanced economies more influence. Read the revisions, not the levels.
2. Core Market / Strategic Analysis
2.1 Regional forecasts side by side
| Region | World Bank 2026 | World Bank 2027 | Revision direction | Source |
|---|---|---|---|---|
| World | 2.5% | 2.8% | Cut from 2.6% (Jan) | World Bank |
| East Asia & Pacific | 4.2% | 4.4% | Cut from 4.4% (Jan) | World Bank |
| Europe & Central Asia | 2.1% | 2.3% | Cut from 2.4% (Jan) | World Bank |
| South Asia | 6.3% | 6.9% | Fastest-growing region | World Bank |
| MENA, Afghanistan & Pakistan | 1.6% | 5.0% | Cut from 3.6% (Jan) | World Bank |
| Sub-Saharan Africa | 4.0% | 4.4% | Marginal easing | World Bank |
| Low-income countries | 5.4% | — | Cut 0.3pp on the conflict | World Bank |
The MENAAP line is the single most violent revision in the dataset: from 3.6% to 1.6% for 2026 in five months, followed by a mechanical 5.0% rebound in 2027 as base effects and assumed energy normalisation kick in. For frontier-market investors with Pakistan or Gulf exposure, that V-shape is the entire investment thesis — and it rests on an assumption about how long the conflict lasts.
2.2 The European picture
Growth in Europe and Central Asia is projected to decelerate to 2.1% in 2026, weakening in roughly 70% of economies in the region, according to the World Bank’s regional highlights. Domestic demand remains the primary driver but is constrained in 2026 by elevated energy prices, which raise inflation and erode real incomes, and by tighter financial conditions.
Commodity exporters in the region — Azerbaijan, Kazakhstan and Turkmenistan among them — see export revenues supported by higher energy prices even as growth slows. In Russia, the World Bank estimates oil revenue gains at roughly 1.5% of 2025 GDP for each $10 per barrel increase in prices, with those gains mainly directed toward fiscal consolidation.
The euro area itself sits at the sluggish end. The IMF’s January 2026 update had projected euro-area growth steady at 1.3% in 2026 and 1.4% in 2027, noting that the region benefits less than others from the technology-driven investment boost and that lingering energy-price effects continue to drag on manufacturing. Planned defence spending increases are expected to show up in output only in later years given phased commitments running to 2035.
2.3 The Asian picture
East Asia and Pacific is projected to fall to 4.2% in 2026 before firming to 4.4% in 2027 — a downgrade, but still comfortably the second-fastest-growing region. South Asia leads globally at 6.3% in 2026 and 6.9% in 2027.
The IMF’s framing explains why Asia holds up better than Europe: economies plugged into the technology-led upturn experience stronger activity even when they are energy importers, while activity weakens for energy importers with limited participation in that cycle. Energy exporters outside the conflict zone benefit from favourable terms of trade.
3. Structural Drivers and Competitor Gaps
Most coverage treats these as two competing headline numbers. The more useful read is that both institutions have converged on the same three-channel transmission mechanism, articulated by IMF Chief Economist Pierre-Olivier Gourinchas when the April outlook was released: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock. The Fund noted at the time that the global economy had been on a roughly 3.3% trajectory and was heading for an upgrade before the war stopped that momentum, with inflation instead rising toward 4.4%.
Three structural points follow that competitors miss:
The dispersion is the story. The April WEO recorded a cumulative growth revision of nearly three percentage points for 2026 in the Middle East and North Africa, against comparatively modest effects in advanced economies. A single global number conceals a distribution this wide.
The 2027 rebound is conditional, not forecast. The World Bank’s recoveries across all regions in 2027–28 are driven by an assumed decline in energy prices and rebound in global activity. If Brent stays above $100, the rebound does not arrive on schedule.
AI is now a macro line item, not a sector story. Both institutions explicitly cite broader AI adoption as an upside risk offsetting the energy shock. That reframes technology capital expenditure as a national growth input, which is why Singapore, Malaysia and Taiwan are outperforming regional peers with similar energy exposure.
4. Key Implications for Stakeholders
Macro allocators. The IMF–World Bank spread is not noise to be averaged away; it is a signal about where you sit in the distribution. Market-weight exposure to advanced economies should be benchmarked against the World Bank’s 2.5%, not the IMF’s 3.0%.
Corporate strategists. Fiscal pressure is the binding constraint in developing markets. The World Bank flags that fiscal pressures will affect the ability to reduce poverty and food insecurity and to create jobs — which translates into weaker public procurement and slower infrastructure pipelines across frontier markets through 2027.
Frontier and EM investors. Emerging market and developing economies face their weakest per capita income growth since the pandemic. Pair that with the MENAAP downgrade and the case for selectivity over beta exposure is straightforward.
Watch the October calendar. The IMF’s next full World Economic Outlook lands with the Annual Meetings. Given the energy trajectory since July, the risk to the 3.0% figure is to the downside.
5. Frequently Asked Questions
Q1: What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, per its July 2026 World Economic Outlook Update — down from the 3.5% average recorded across 2024–25, with the Middle East war the principal drag.
Q2: Why does the World Bank forecast lower growth than the IMF?
The World Bank aggregates using market exchange rates while the IMF uses purchasing-power-parity weights, giving slower-growing advanced economies more influence in the World Bank’s 2.5% figure. Both revised downward for the same reasons.
Q3: Which region is growing fastest in 2026?
South Asia, at a projected 6.3% in 2026 rising to 6.9% in 2027, according to the World Bank. East Asia and Pacific follows at 4.2%.
Q4: How badly has the Middle East conflict hit growth forecasts?
The World Bank cut its MENA, Afghanistan and Pakistan forecast from 3.6% to 1.6% for 2026, and downgraded two-thirds of all economies since January. Global growth is now at its weakest since the pandemic.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Fed Rate Hike Projections vs. Trump’s Interest Rate Policy: What Global Markets Expect Next
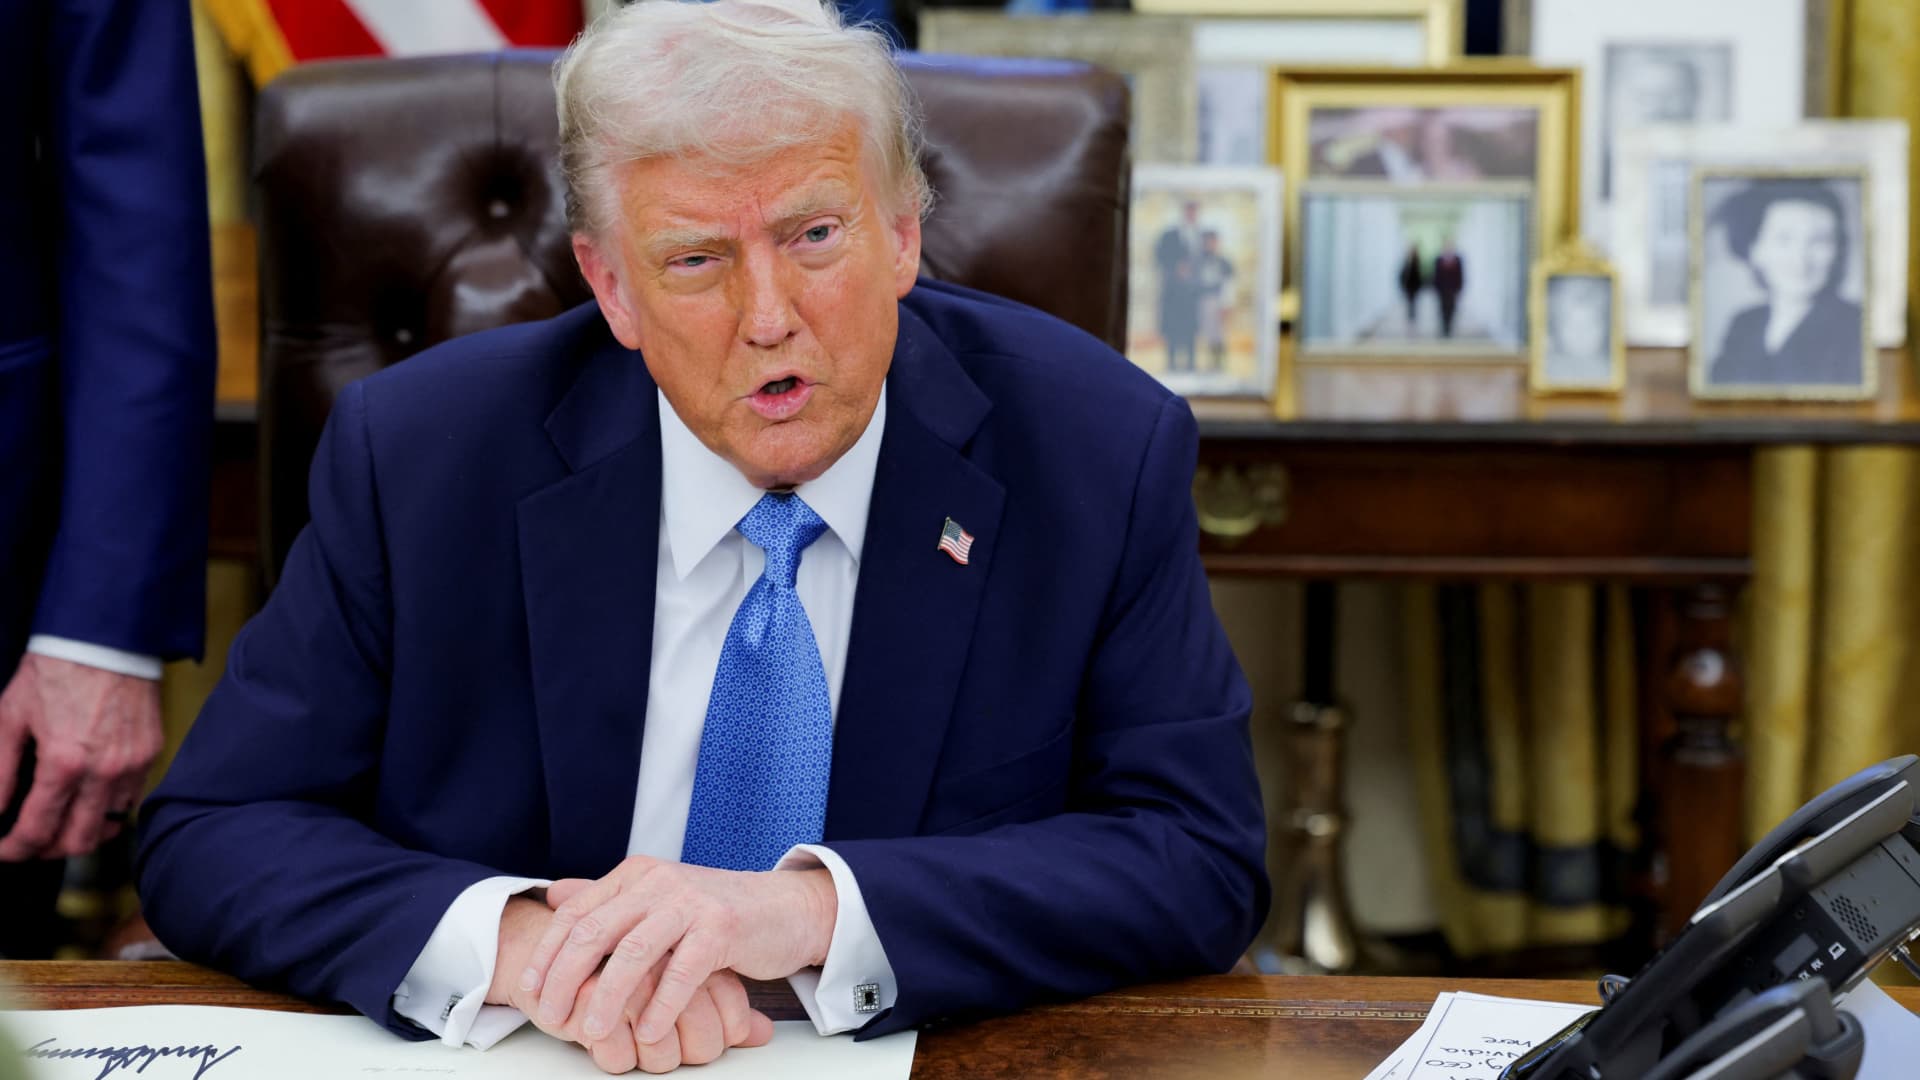
The Fed hiked to 3.75%-4% on Sept 16 as Trump demanded 1% rates. See the dot plot, the market reaction and what it means for borrowers next.
Executive Summary / Key Takeaways
- On 16 September 2026 the Federal Open Market Committee voted 12-0 to raise the federal funds target range by a quarter point to 3.75%–4.00% — the first US rate increase since July 2023.
- The statement was blunt: inflation remains elevated, and the action is meant to support a timelier return to the 2% goal.
- The dot plot showed 16 of 18 participants expecting at least one more quarter-point hike before year-end, with four seeing room for two. Chair Kevin Warsh declined to submit a projection at all.
- President Trump responded within hours, demanding that US rates fall to 1% “or less” — while saying he still has confidence in the chair he appointed.
- Markets sold the decision then partly reversed: the Dow fell more than 600 points, the 10-year Treasury yield topped 5%, and the two-year reached its highest level since 2024.
1. Introduction & Immediate Context
For three and a half years the direction of travel in US monetary policy was one-way — cuts, pauses and arguments about the pace of easing. That ended on Wednesday afternoon.
The Federal Reserve approved its statement by a 12–0 vote, lifting the target range for the federal funds rate by a quarter percentage point to 3¾–4 percent while continuing its policy of maintaining ample reserves in the banking system. The Committee described economic activity as expanding at a solid pace, noted that uncertainty remains elevated partly because of geopolitical developments, and observed that domestic spending has been resilient, productivity growth strong and capital investment robust.
Alongside that assessment sat a one-line justification for tightening: inflation remains elevated, and the policy action will support a timelier return to the 2 percent objective. That combination — firm growth, firm inflation — is what separates this decision from the reflexive easing bias markets carried through the first half of the year. As CNBC reported, futures markets had priced better than a 90% chance of the move, but the accompanying projections were more hawkish than most desks expected.
2. Core Market and Policy Analysis
2.1 What the dot plot actually says
The Summary of Economic Projections is the part institutional desks will trade for the next six weeks. Sixteen of eighteen policymakers anticipate at least one more quarter-point increase by the end of this year, and only two expect rates to stay where they are, according to Reuters. Four of those officials see two further hikes as possible.
Warsh’s refusal to publish his own dot is a deliberate break with a decade of Fed communication practice; he has said repeatedly that he opposes issuing forward guidance. For rate-sensitive borrowers that matters. The committee’s central tendency is now the only signal available, and it points higher.
| Metric / Indicator | Current Status | Projected Impact | Primary Source |
|---|---|---|---|
| Federal funds target range | 3.75%–4.00% (raised 25 bps, 12-0) | At least one further hike signalled for 2026 | Federal Reserve |
| FOMC dot plot | 16 of 18 see ≥1 more hike; 4 see two | Terminal-rate debate shifts toward 4.25%–4.50% | Reuters |
| PCE inflation projection | 3.7% in 2026, falling to 2.3% in 2027 | Above target across the forecast horizon | Fox Business |
| 10-year Treasury yield | Above 5% | Higher mortgage and corporate borrowing costs | Yahoo Finance |
| Prior policy path | Three cuts in 2025 to 3.50%–3.75%, then five holds | First reversal of the easing cycle since 2023 | Trading Economics |
2.2 The inflation case for tightening
Fed projections put PCE inflation at 3.7% in 2026, falling to 2.3% in 2027, with domestic spending remaining resilient, Fox Business reported. That is a second consecutive year of above-target inflation on the central bank’s own numbers, driven substantially by energy costs.
Warsh framed the decision in unusually plain terms at his press conference, saying that inflation is too high and has been for too long, and describing the vote as a sober, serious, responsible decision. Speaking to Bloomberg, he characterised the move as removing a dose of accommodation so that financial and credit conditions would sit more consistently with the Fed’s ultimate objectives — and said the action begins to show the central bank is serious about delivering price stability. He also noted that the economy has gathered speed since the July hold, with little sign of inflation cooling.
3. Structural Drivers and Competitor Gaps: The Independence Test
This is where most coverage stops short. The interesting variable is not 25 basis points; it is the institutional test now underway.
In the week before the meeting, the president, vice president, Treasury secretary and a senior White House economic counselor all publicly urged the Fed not to raise rates and in some cases to cut — an unusually broad pressure campaign even by the standards of Trump’s long-running criticism of the central bank, CNBC reported. Vice President JD Vance said the administration believes the Fed should be lowering rates and would appreciate help from the central bank. Treasury Secretary Scott Bessent argued that the Fed typically does not raise rates during a supply shock until second- or third-order inflationary effects appear.
The decision went the other way. Warsh voted with a unanimous committee despite that pressure, in a move read by analysts as an unambiguous signal that the White House should keep its hands off the Federal Reserve. Trump had selected Warsh in January after souring on former chair Jerome Powell — which is precisely what makes the vote consequential. This was not an inherited adversary defying the administration; it was the administration’s own appointee.
The presidential response came within hours. Trump wrote on Truth Social that US interest rates should be 1% or less because America is the best credit in the world, ending with a demand that rates be lowered fast, Reuters reported. He also appeared to link persistent US trade deficits to the central bank’s borrowing costs, though the two are largely unrelated. Asked later whether he believed Warsh had decided based on White House input, the president said he did not think so, and confirmed he still has confidence in the chair.
For sovereign allocators the pricing question is whether September establishes a durable precedent of operational independence, or whether the pressure campaign intensifies into 2027 as the midterm cycle bites. Long-end term premium is the cleanest instrument for expressing a view either way.
4. Key Implications for Stakeholders
Mortgage borrowers. The transmission channel is the long end, not the policy rate. The 10-year Treasury topped 5% around the decision while oil traded solidly above $100 per barrel, according to Yahoo Finance. Thirty-year fixed mortgage pricing tracks the long bond far more closely than the funds rate, so the term-premium repricing matters more than the hike itself.
Equity investors. Stocks reversed during Warsh’s press conference as markets read his remarks as hawkish, with the Dow dropping more than 600 points — over 1.2% — while the S&P 500 fell 0.4% and the Nasdaq finished near flat. Yardeni Research cut its year-end S&P 500 target to 7,900 from 8,400, citing higher Treasury yields driven by rising energy prices and an increased risk of a downturn over the next three to six months, CNBC noted.
Global markets. By Thursday, sentiment had steadied. Bloomberg reported Treasuries paring losses and US equity futures climbing as Warsh’s resolve reassured investors, with the two-year note easing a basis point to 4.72% after touching its highest level since 2024, and the 10-year and 30-year both slipping around two basis points.
Institutional positioning. The base case is now higher-for-longer with a live December hike. Markets are pricing one more 25-basis-point increase in 2026 followed by further tightening extending into 2027, per Seeking Alpha analysis of CME FedWatch pricing.
5. Frequently Asked Questions
Q1: What is the current Fed interest rate after the September 2026 meeting?
The federal funds target range is 3.75%–4.00%, raised by 25 basis points on 16 September 2026 in a unanimous 12-0 FOMC vote. It was the first US rate increase since July 2023 and partially reversed the 2025 easing cycle.
Q2: Will the Fed raise rates again in 2026?
The dot plot indicates 16 of 18 FOMC participants expect at least one further quarter-point increase before year-end, and four see two as possible. Markets currently price one additional hike in December, with more tightening possible into 2027.
Q3: How did Trump react to the Fed rate hike?
He demanded on Truth Social that US rates be cut to 1% or less, while telling reporters afterwards that he retains confidence in Chair Kevin Warsh and does not believe Warsh acted on White House instruction.
Q4: Why is the Fed hiking when inflation was supposed to be falling?
Fed projections put PCE inflation at 3.7% in 2026, well above the 2% target, driven substantially by energy prices. The Committee judged growth, productivity and capital investment strong enough to absorb tighter policy.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

2026 Real Estate Market News: Are We Heading for a Correction?

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Fidelity Crypto vs. Traditional Brokerages: A Guide for Modern Investors

The 2026 Global Smartphone Market: AI Integration and Competitor Analysis

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

Fidelity Investments Review: Maximizing Returns in a Volatile Stock Market

How Crypto Transformed the Trump Fortune: A $1.4 Billion Financial Breakdown

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Global Supply Chain Vulnerabilities: From Eurasian Trade Corridors to Food Consumer Recalls

Why 5% U.S. Treasury Yields Signal a Global Market Regime Shift.

Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025