
Geopolitics
Trump Pays $1 Billion to Kill Offshore Wind. The Tab Is Just Getting Started.

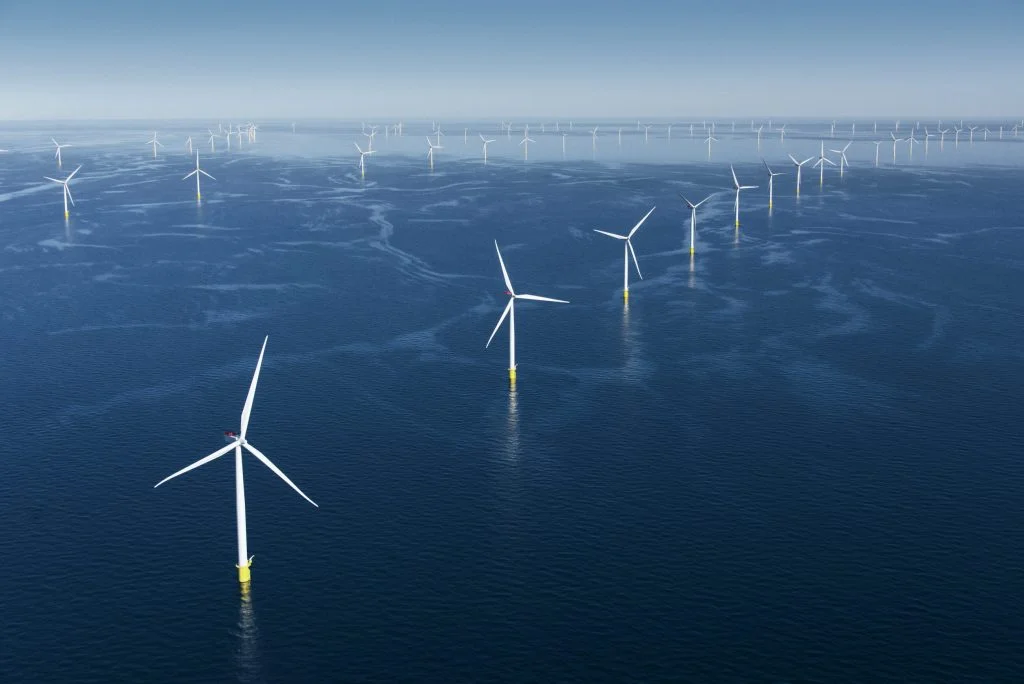
A landmark deal with TotalEnergies marks the first time Washington has paid a company not to build clean energy — and it may be the cheapest item on a much longer bill
The Deal That Rewrote the Rulebook
Houston’s CERAWeek energy conference — the annual rite where oil executives and government officials exchange pleasantries over fossil fuel futures — rarely produces genuine surprises. On the morning of Monday, March 23, 2026, it produced one.
Interior Secretary Doug Burgum and TotalEnergies CEO Patrick Pouyanné shook hands before cameras at the S&P Global gathering and announced what the Department of the Interior called a “landmark agreement”: the United States government would pay the French energy giant approximately $928 million to surrender two Atlantic offshore wind leases and pledge never to build another wind farm in American federal waters. In exchange, TotalEnergies would redirect that capital — dollar for dollar — into oil drilling in the Gulf of Mexico, shale gas production, and the construction of four trains of the Rio Grande LNG export terminal in Texas.
Together, the two cancelled projects — one off the New York-New Jersey coast, one off North Carolina — had the potential to generate more than four gigawatts of electricity, enough to power nearly one million American homes. NPR They will now generate nothing.
It was, depending on one’s vantage point, either a masterstroke of energy realpolitik or the most expensive act of ideological vandalism in the history of American energy policy. Probably, it is both.
How Washington Learned to Pay for Retreat
To understand how the Trump administration arrived at the strategy of paying developers to abandon renewable energy projects, you have to understand a problem it could not solve in court.
The tactical shift comes after federal courts repeatedly thwarted the administration’s efforts to stop offshore wind through executive action. U.S. District Judge Patti Saris vacated Trump’s executive order blocking wind energy projects in December, declaring it unlawful after 17 state attorneys general challenged it. WCAX Late last year, the administration invoked classified national security threats to stop work on five wind farms that were under construction. Developers and states sued, and federal judges allowed all five projects to resume construction. NPR Litigation was not working. So the administration found a new instrument: the checkbook.
Following TotalEnergies’ $928 million in investments in US energy projects, the United States will terminate Lease No. OCS-A 0538, located in the New York Bight area — originally purchased by Attentive Energy LLC in May 2022 for $795 million — and Lease No. OCS-A 0535, located in the Carolina Long Bay area, purchased in June 2022 for $133,333,333. U.S. Department of the Interior The mechanics are structured to appear budget-neutral at the surface: TotalEnergies invests the money first, then receives reimbursement, dollar for dollar, up to the original lease cost. But the fiscal logic collapses under scrutiny — the Justice Department will use nearly $1 billion in taxpayer funds to reimburse the company. CNN The public is absorbing the cost.
TotalEnergies had already paused its two projects after Trump was elected and pledged not to develop any new offshore wind projects in the United States. NPR The leases were, in practical terms, dormant. Washington is paying a billion dollars to kill something that had already stopped moving.
The Numbers Behind the Narrative
The administration’s framing of the deal centers on affordability — specifically, the Interior Department’s claim that offshore wind is “one of the most expensive, unreliable, environmentally disruptive, and subsidy-dependent schemes ever forced on American ratepayers.” Secretary Burgum has repeated this framing with the consistency of a campaign slogan.
The economics are considerably more nuanced. While offshore wind is more expensive than other forms of renewable energy because of its unique supply chain constraints, wind has no fuel costs and states negotiate set power price agreements with developers that don’t fluctuate — unlike natural gas and oil. CNN In an era when the US-Israel military campaign against Iran has fractured global oil markets and tightened shipping through the Strait of Hormuz, price stability carries its own premium.
As fossil fuel prices swing wildly from global shocks and extreme weather, the answer is obvious: we should be building more homegrown clean energy with stable costs. East Coast states are building offshore wind because it boosts affordable electricity supply on the grid, especially during cold snaps, when natural gas prices are sky-high, Environmental Defense Fund said Ted Kelly, Director and Lead Counsel at the Environmental Defense Fund.
The LNG side of the settlement also invites scrutiny. The Interior Department’s announcement says TotalEnergies will invest approximately $1 billion in oil and natural gas, including offshore oil platforms in the Gulf of Mexico and an LNG facility in Texas. But the company is already plowing billions into new offshore platforms, and it made a final investment decision on an expansion of its Texas LNG facility last year. The lease refund would only offset existing investments, not generate new infrastructure the company hadn’t already planned. Grist In other words, the United States may have paid $928 million for a pivot that was already underway.
Pouyanné’s Pragmatism — and Its Limits
Patrick Pouyanné has navigated TotalEnergies through the energy transition with a pragmatism that distinguishes him from the more ideologically committed leaders of rival majors. The French supermajor has aggressively built renewable capacity across Europe, Asia, and Africa; it remains a major offshore wind developer in the North Sea and has material projects in South Korea and Taiwan.
In his statement, Pouyanné said the refunded lease fees would allow TotalEnergies to support the development of US gas production and export. He added: “These investments will contribute to supplying Europe with much-needed LNG from the US and provide gas for US data center development.” CNBC The framing is astute. In the wake of disruptions to Middle Eastern energy supply, Europe’s renewed hunger for American LNG gives TotalEnergies strategic leverage to present its pivot not as retreat from clean energy, but as a geopolitical service.
Yet TotalEnergies’ own global portfolio tells a different story from its American accommodation. The company is simultaneously developing floating offshore wind in the North Sea and partnering with governments across Southeast Asia on solar infrastructure. The renunciation of US wind is a concession to political reality in Washington, not a statement of technological conviction. Pouyanné is settling accounts with one government while expanding his bets on the energy transition everywhere else.
The $5 Billion Question: Who’s Next?
The TotalEnergies deal may be the most consequential not for what it cancels but for the template it establishes.
The leases for several undeveloped offshore wind projects off the Atlantic, Pacific and Gulf coasts total more than $5 billion, and that doesn’t include additional pre-development costs incurred by developers. CNN German renewables company RWE, which paid more than $1.2 billion for three leases off the coasts of New York, California and the Gulf of Mexico, is one of the companies expecting to be reimbursed. CEO Markus Krebber said at a recent press conference: “If we never get the right to build the plants, I assume we’ll get the money we’ve already paid back. And if necessary, through legal action.” CNN
The arithmetic of a full unwind is staggering. If every undeveloped lease follows the TotalEnergies model, the federal government faces a potential liability exceeding $5 billion — paid out of Treasury funds to extinguish energy capacity that American states have already integrated into their grid planning. That money would not go toward grid modernization, transmission buildout, or any form of domestic energy investment. It would effectively be a subsidy for the fossil fuel status quo, laundered through a reimbursement structure.
Senator Chuck Schumer told the Associated Press that the payment “sets a dangerous precedent and is a shortsighted misuse of taxpayer dollars.” WCAX It is difficult to argue with the precedent concern on purely fiscal grounds.
Climate Goals, Grid Reality, and the China Dimension
The cancellation of 4+ gigawatts of planned offshore wind capacity does not occur in a vacuum. It occurs against a backdrop of soaring electricity demand from AI data centers, accelerating electrification of the US economy, and a global offshore wind market that is expanding at extraordinary speed — led, increasingly, by China.
Globally, the offshore wind market is growing, with China leading the world in new installations. NPR While the United States dismantles its pipeline, China is commissioning new offshore wind capacity at a rate that dwarfs anything attempted in the Western hemisphere. The Chinese offshore wind supply chain — turbines, foundations, cables, installation vessels — is becoming globally dominant precisely as American demand for that supply chain evaporates. If and when Washington reverses course, it will find itself dependent on Chinese-manufactured components, having surrendered the industrial learning-curve advantage that early deployment generates.
Energy experts have argued that the ongoing conflict and disruption to shipping in the Strait of Hormuz underscores the need to shift toward renewable energy sources, which are less vulnerable to geopolitical shocks. Canary Media This is not an abstract argument. It is an argument made urgent by the same crisis that TotalEnergies is now being paid to help resolve — by building more LNG terminals.
The grid reliability picture is equally complicated. On Monday, one of the wind farms targeted by the administration, Coastal Virginia Offshore Wind, started delivering power to the grid for Virginia. The developer, Dominion Energy, announced the milestone. NPR The technology works. The question is who benefits from the decision not to build it.
Harrison Sholler, US wind analyst for BloombergNEF, assessed the TotalEnergies deal’s market impact soberly: “Major policy changes and signals under a future administration will be needed if any offshore wind projects are to come online by 2035, in our view. TotalEnergies handing back their leases doesn’t change that, although it slightly reduces the pipeline of projects that could come online if positive policy changes do occur.” Canary Media
The Taxpayer, the Ratepayer, and the Geopolitical Bet
Defenders of the deal make a coherent, if contestable, case. America’s LNG infrastructure is a genuine geopolitical asset. The announcement came as the Iran conflict continued to disrupt global oil and gas supplies, making the US — the largest exporter of liquefied natural gas in the world — an even more critical supplier for markets in Asia and Europe. CNBC Rio Grande LNG, whatever its local environmental costs, will supply European markets that have spent four years scrambling to replace Russian pipeline gas. That is a real strategic value.
The Trump administration’s “energy dominance” framework is internally consistent: maximize hydrocarbon production and export, leverage geopolitical disruption to cement market share, and treat renewable energy as a domestic political liability rather than an economic opportunity. It is a bet that fossil fuel demand will remain structurally elevated through the 2030s, that the energy transition can be deferred without terminal competitive consequence, and that the geopolitical premium on American LNG will continue to subsidize the costs of that deferral.
It is also a bet of extraordinary cost if it proves wrong.
What Comes Next
The TotalEnergies deal is not an isolated transaction. It is the articulation of a doctrine: that the administration will use every available instrument — executive order, permit denial, court-resistant settlement, and now direct financial payment — to prevent offshore wind from establishing roots in American federal waters.
Sam Salustro, senior vice president of policy at Oceantic Network, said: “After failing to shut down offshore wind through strong-arm tactics and litigation losses, the administration is now spending $1 billion in taxpayer dollars to force developers out of the market. This political theater is meant to obscure the fact that offshore wind capacity is being pulled out of the pipeline when energy prices are skyrocketing.” Canary Media
The harder question — one that neither the administration’s cheerleaders nor its critics have fully reckoned with — is what this means for the industrial and investment landscape of the 2030s. Offshore wind projects require a decade of development; the capacity being cancelled today is capacity that would have powered American homes in the mid-2030s. The LNG terminals being funded in its place will take years to construct and are, by definition, fuel-cost dependent in ways that offshore wind is not.
Meanwhile, European energy ministries are watching the Washington drama with a mixture of calculation and alarm. They welcome American LNG as a bridge fuel; they are quietly relieved that TotalEnergies’ LNG commitments will flow their way. But they are also accelerating their own offshore wind programs precisely because they have learned, painfully, what fuel-price dependence costs in a geopolitically unstable world.
The United States, which pioneered modern offshore energy development and once led the global energy transition, has chosen a different path. For $928 million — and counting — it has purchased the right to revisit that choice later, at considerably higher cost, in a market shaped by competitors who did not pause.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


With the 2026 US midterm elections concluded, payroll departments are turning their attention to year-end processing and the possibility of late legislative changes that could alter 2027 withholding or reporting requirements. The IRS has already released inflation-adjusted figures for tax year 2027, but any lame-duck bill enacted with a 1 January effective date would compress the implementation window. Thomson Reuters Checkpoint
At the same time, industry surveys show continued acceleration in adopting AI and automation for payroll calculations, employee self-service, and compliance monitoring, along with growing interest in faster pay cycles such as weekly payroll.
Table of Contents
- What Are the Immediate Post-Election Priorities for Payroll Teams?
- Which 2027 Tax Adjustments Are Already Confirmed?
- Why Does Legislative Timing Create Implementation Risk?
- How Is Artificial Intelligence Changing Payroll Operations?
- What Is Happening with Faster Pay Cycles and Weekly Payroll?
- What Practical Steps Should Employers Take Now?
- How Should Organizations Prepare for Multi-State and Local Changes?
- Key Takeaways
- Frequently Asked Questions
What Are the Immediate Post-Election Priorities for Payroll Teams?
Monitor any tax legislation that emerges in the lame-duck session, finalise 2026 year-end reporting, load confirmed 2027 withholding tables, and prepare employee communications. Practitioners note that “timing is almost as important as the substance of the law” when changes arrive late in the calendar year. Thomson Reuters
Which 2027 Tax Adjustments Are Already Confirmed?
The IRS announced inflation adjustments for nearly 70 provisions. Illustrative standard-deduction amounts for 2027 include $33,200 for married couples filing jointly, $16,600 for single filers and $24,925 for heads of household. These figures flow directly into withholding calculations and Form W-4 processing and must be implemented for the first payroll of 2027. Thomson Reuters
Why Does Legislative Timing Create Implementation Risk?
Payroll systems, tax engines and year-beginning employee notices must be updated before the first 2027 pay date. A bill passed in December with a 1 January effective date leaves little room for testing and training, raising the probability of under- or over-withholding and subsequent corrections.
How Is Artificial Intelligence Changing Payroll Operations?
Industry research indicates that organisations are deploying AI for anomaly detection, predictive compliance, employee query handling and report generation. The technology is viewed both as a productivity tool and as a means of improving accuracy in multi-jurisdictional environments. Adoption continues to accelerate through 2026.
What Is Happening with Faster Pay Cycles and Weekly Payroll?
Search interest and employer adoption of weekly payroll and on-demand pay options continue to rise. Workers increasingly expect more frequent access to earned wages. Payroll teams must ensure that faster cycles remain compliant with tax-deposit schedules and reporting rules.
What Practical Steps Should Employers Take Now?
- Load the published 2027 IRS inflation adjustments into payroll systems.
- Establish a rapid-response protocol for any lame-duck legislation.
- Review state and local withholding changes effective 1 January.
- Audit AI and automation tools for accuracy and audit-trail capability.
- Communicate any material withholding changes to employees before the first 2027 payroll.
How Should Organizations Prepare for Multi-State and Local Changes?
Maintain updated tables for every jurisdiction in which employees work or reside, confirm reciprocity agreements, and test year-beginning payroll runs well before the first pay date of 2027.
2027 Standard Deduction Examples (IRS)
| Filing Status | 2027 Standard Deduction |
|---|---|
| Married filing jointly | $33,200 |
| Single | $16,600 |
| Head of household | $24,925 |
Key Takeaways
- Post-midterm focus shifts to 2027 implementation and year-end close.
- IRS inflation adjustments for 2027 are already published and must be loaded.
- Lame-duck legislation with short effective dates is the largest near-term risk.
- AI and automation adoption in payroll continues to accelerate.
- Weekly and faster-pay models are gaining traction.
- Proactive system updates and employee communication reduce compliance exposure.
Frequently Asked Questions
Do the midterm results immediately change federal payroll rules?
No. Existing law remains in force until new legislation is enacted and becomes effective.
When must the 2027 IRS adjustments be implemented?
In time for the first payroll of tax year 2027.
What is the biggest compliance danger right now?
Last-minute federal changes that alter withholding or reporting with a 1 January start date.
Is AI already handling core payroll calculations at most companies?
Adoption is growing rapidly but varies; many organisations still use AI mainly for ancillary tasks and exception handling.
Should employers delay updates until Congress adjourns?
No. Implement the known inflation adjustments now and retain flexibility for possible late changes.
Are weekly payroll cycles compliant with federal deposit rules?
Yes, provided deposit schedules and reporting are handled correctly by the payroll system.
Conclusion
Payroll professionals face a familiar but heightened post-election workload: absorb the already-published 2027 inflation adjustments while remaining ready for any surprise lame-duck provisions. For finance, HR and compliance audiences, the combination of legislative uncertainty and accelerating AI adoption makes disciplined change-management and testing essential. Organisations that prepare both their systems and their employee communications in advance will navigate the transition to 2027 with the least disruption.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
With more than half of approved investment still outside the implemented category, Malaysia and Singapore face a defining challenge: making their cross-border economic experiment deliver productive industry, skilled employment and lasting gains on both sides of the Causeway.
The Johor–Singapore Special Economic Zone (JS-SEZ) has amassed RM88.83 billion (about US$21.8 billion) in approved investments in the 18 months to June 2026. It is an impressive early pipeline for a project designed to turn two neighbouring economies into a more competitive manufacturing, logistics and technology hub.
But the more consequential figure is RM40.3 billion. That is the portion of approved investment that has reached implementation, according to the bilateral ministerial update released on Monday. In other words, approximately 45.4% has been implemented; RM48.53 billion, or 54.6%, remains outside that category. The approved projects are associated with 28,755 potential employment opportunities, including 12,796 jobs linked to implemented projects. These job numbers should not be interpreted as a verified count of positions already filled. Channel NewsAsia and Bernama reported the figures following the inaugural Johor–Singapore Cooperation Ministerial Committee meeting on November 2.
For investors, the difference between approval and implementation is not an accounting footnote. It is the space in which land, grid connections, workers, permits, financing and cross-border transport must come together. The project will be judged less by the volume of announcements it attracts than by how quickly they become operating businesses—and how much economic value stays with local workers and suppliers.
That is the central test for the master plan and investment blueprint expected at the Malaysia–Singapore Leaders’ Retreat in December 2026. The launch timetable was confirmed after this week’s ministerial meeting, but its publication and the measures it contains remain prospective. The Business Times and The Straits Times report that leaders intend to unveil the blueprint in December.
What the latest numbers actually measure
| Measure | Reported position | What it does—and does not—show |
|---|---|---|
| MIDA-covered approved investments, January 2025–June 2026 | RM88.83bn | Approvals tied to projects within the JS-SEZ footprint, not cash automatically spent |
| Investment value classified as implemented | RM40.3bn | Projects at implementation stage; not necessarily fully disbursed capital |
| Approved value not yet classified as implemented | RM48.53bn | Calculated difference; not proof that projects have been cancelled |
| Implementation share, by approved investment value | 45.4% | RM40.3bn divided by RM88.83bn; a value ratio, not a count of completed projects |
| Potential jobs linked to approved projects | 28,755 | Project-associated opportunities, not a confirmed headcount on payroll |
| Jobs linked to implemented projects | 12,796 | Associated employment figure; not necessarily every role hired |
Calculations are derived from the ministerial figures as reported by CNA. Totals and percentages may differ slightly because of rounding.
The distinction matters because large industrial and digital projects can take years to build. A semiconductor production facility, specialist chemicals plant or data-centre campus may pass through construction, commissioning and a phased production ramp before attaining the employment or output envisioned in its application. A snapshot of approvals does not reveal how many projects have met those later milestones.
There is also an attribution problem. In a September 25 investigation, The Business Times reported that MIDA tracked investments based on project location and could not determine what share had been caused specifically by the SEZ initiative. That qualification should shape every claim about the programme’s success. An investment located within a zone is not necessarily an investment that would never have happened without the zone.
This is particularly important in Johor, which already had proximity to Singapore, industrial parks, ports and a growing digital-infrastructure sector before the bilateral agreement took effect.
The RM132 billion question: why two official investment figures must not be conflated
A separate discrepancy deserves more attention. In his October 9 Budget 2027 speech, Malaysian Prime Minister Anwar Ibrahim cited RM132 billion of investment recorded in the JS-SEZ from 2025 to June 2026. The November 2 bilateral announcement, covering ostensibly the same period, uses RM88.83 billion in approved investment under MIDA’s purview.
The headline difference is RM43.17 billion. It is not evidence of investment disappearing, nor is it grounds for adding the figures together. The October speech did not provide enough methodology to reconcile the two totals publicly. One plausible explanation is different coverage of investment agencies or project categories, but that remains an explanation to test, not an established fact.
A credible investment dashboard should disclose what is included in each series, whether commitments, approvals and realised expenditure are distinguished, and whether overlapping projects have been removed. Until that happens, the RM88.83 billion figure is the more specifically defined basis for analysing the implementation rate announced this week.
That methodological transparency will matter as much as any new investment target. Reliable, comparable numbers help businesses distinguish a durable supply-chain opportunity from a promotional cycle.
Why Johor and Singapore believe they are stronger together
The bilateral agreement exchanged on January 7, 2025 was built around a simple economic proposition: Singapore has deep finance, research, commercial services and international connectivity; Johor offers industrial space, a manufacturing base and scope for larger-scale operations. Companies can divide functions across the border rather than choosing one country at the expense of the other.
Singapore’s Economic Development Board calls this a “twinning” model. A business could maintain its regional headquarters, design or high-value services in Singapore while locating assembly, warehousing or other land-intensive functions in Johor. The countries then compete jointly for projects that might otherwise choose a different Southeast Asian production network. Singapore EDB’s JS-SEZ guide describes this approach.
The legal geography is worth clarifying. The designated SEZ land lies in Johor, not in both countries, even though the economic arrangement is bilateral. An August 2026 Singapore parliamentary reply gave its footprint as 3,588 square kilometres, including the Iskandar Development Region and Pengerang. It covers nine flagship areas and promotes 11 sectors, including manufacturing, logistics, energy, the digital economy, healthcare, tourism and business services.
For Singapore, the potential gain is a broader operating hinterland and new markets for its engineering, services and financing firms. For Johor, it is a chance to move beyond low-cost industrial land into higher-productivity activities. But that division of labour is not automatically equitable. Johor’s workers need opportunities to develop technical and managerial skills, while Singapore firms need real efficiencies beyond the headline tax rate.
A tangible example is Singapore-based Agrocorp’s expansion into plant-protein extraction with a Japanese partner in Johor, using technology developed with the Singapore Institute of Technology. The project was cited in Singapore’s August 2026 parliamentary response as an illustration of cross-border complementarity rather than simple relocation.
The sectors that could determine the zone’s success
Advanced manufacturing and semiconductor equipment. The most valuable investment projects are not necessarily those with the largest construction budgets. Precision engineering, automation, medical devices and specialised components can create production capabilities that attract a network of suppliers and skilled technicians. The question is whether Johor-based companies gain access to these supply chains—and whether local technical workers move into better-paid roles.
Digital infrastructure and AI. Johor is already benefiting from regional demand for computing capacity. The corridor’s proximity to Singapore makes data centres commercially attractive, but AI-related facilities are also unusually intensive users of electricity and, depending on cooling systems, water. In Reuters reporting published July 24, 2026, concern over utility demand, environmental pressure and limited community benefits emerged as a significant test of the state’s data-centre expansion. Large capital expenditure does not automatically translate into proportionately large permanent workforces.
Ports, logistics and food supply chains. The region has an opportunity to combine Singapore’s commercial and shipping connections with Johor’s industrial and warehousing capacity. But the advantage only becomes measurable when trucks, components and finished goods move more predictably between facilities. The original agreement included streamlined land transshipment permits and initiatives to improve customs processes. Singapore EDB’s agreement factsheet sets out those measures.
Financial and corporate services. Malaysia’s Budget 2027 proposed additional support for global services hubs and financial activities, including steps associated with Forest City. Such services may diversify the SEZ beyond manufacturing, but tax advantages alone will not guarantee durable business activity. Regulators, investors and clients must also have confidence in governance and the quality of services.
The Sedenak industrial node. Budget 2027 also highlighted Nexus Sedenak, with potential investment of RM12 billion and a projection of 45,000 jobs. These are ambitions for a developing hub, not audited outcomes, and should not be added to the current 28,755 project-associated jobs as if they were already secured. Bernama’s October 30 reporting identified advanced manufacturing, integrated logistics, agri-food technology, green technology and pharmaceuticals as priority possibilities for the hub.
The economic common denominator is supplier depth. A factory that imports most inputs and generates little local technical expertise may add to production statistics without building a strong regional ecosystem. A smaller, more sophisticated operation with local engineering partners can have a lasting effect beyond its own payroll.
Tax incentives can attract investment. They cannot operate a factory.
Malaysia’s January 2025 official incentive announcement offered qualifying new manufacturing and services investments a 5% corporate tax rate for up to 15 years, together with a 15% special rate for eligible knowledge workers for 10 years. Eligibility is conditional, and the rates should not be presented as automatic for every company or employee in Johor.
Singapore, meanwhile, has established a JS-SEZ Project Office and provides internationalisation support through channels including its Market Readiness Assistance Grant and Enterprise Financing Scheme, according to the August 2026 government reply.
The policy challenge is to use incentives to encourage genuinely additional investment, higher-value jobs, local procurement and technical training rather than merely shifting corporate activity for a tax advantage. Authorities should publish clear eligibility and performance conditions, with a transparent account of which incentives continue under Malaysia’s wider investment framework.
The border problem: a five-minute train is not a frictionless economy
Connectivity is central to the pitch. The Johor Bahru–Singapore Rapid Transit System (RTS) Link is designed to connect Bukit Chagar with Woodlands North and has a planned capacity of up to 10,000 passengers per hour in each direction during peak periods, according to Singapore’s Land Transport Authority.
But its start date has changed. In an October 2, 2026 joint transport announcement, the authorities said passenger operations were now expected in February 2027, subject to independent safety certification and final regulatory approval. Treating the train as already operational—or promising an unconditional opening date—would mislead readers.
Even when it opens, the train solves only one part of the problem. Freight clearance, last-mile transport, worker permits, supplier delivery schedules and connections between dispersed industrial parks will remain essential. An efficient passenger service cannot by itself remove the costs of an unpredictable customs crossing for a factory moving components repeatedly each week.
The original 2025 agreement’s QR-code clearance measures and streamlined customs procedures were therefore not minor administrative details. In a cross-border production network, reliability may matter more than the occasional saving on wages or rent.
Four risks that could turn impressive approvals into disappointing results
1. Skills and wage retention. Johor must build a workforce that can support precision manufacturing and sophisticated services without losing too much of that talent to higher-paying opportunities across the Causeway. An August 2026 study by Malaysia’s Institute of Strategic and International Studies highlights the structural wage gap and the need to extend cooperation into skills, housing and liveability.
2. Energy and water constraints. Expanding data centres and advanced industrial activity requires reliable power and responsible resource planning. Reuters’ July investigation documented mounting scrutiny over the sector’s electricity and water use. A credible blueprint should connect project approvals to planned utility capacity, rather than assume that supply will materialise later.
3. Uneven local gains. Investment can cluster within major corporate groups while smaller suppliers struggle to qualify for procurement contracts. Local value should be measured in training, supplier participation and wages—not only tax revenue or land development. The ISIS research additionally warns about housing affordability, mobility and ecological risks across the corridor.
4. Governance and timing. The master plan was previously scheduled for March 2026 before being delayed while officials sought wider alignment. Business Times reporting in April documented the postponement. The delay need not be damaging if it produces a practical, joined-up plan; repeated changes without clear milestones, however, would make long-term investment decisions harder.
What December’s blueprint needs to contain
A persuasive master plan would go beyond mapping industrial land and repeating targets. Investors and residents should be able to find a credible delivery schedule that answers five questions.
First, which power, water, road and port projects must be completed before new factories can operate—and who pays for them? Second, which approvals can genuinely be handled through a single process, with published service standards? Third, what will governments report about completed investment expenditure, operational facilities and jobs actually filled? Fourth, which training programmes connect employers to Johor residents, and how will wages and local procurement be measured? Finally, what procedures will govern resource use, emissions, sensitive habitats and community complaints?
The new Johor–Singapore Cooperation Ministerial Committee could provide an institutional home for these answers. The November 2 meeting also put a joint investment forum on the calendar for the first quarter of 2027, according to CNA. A forum backed by clear implementation data would be more useful than another cycle of headline pledges.
For clarity, the key milestones are:
| Timing | Event or target | Status as of November 2, 2026 |
|---|---|---|
| January 7, 2025 | Bilateral JS-SEZ agreement exchanged | Completed |
| June 2026 | Cutoff for latest MIDA investment data | Reported in November |
| December 2026 | Master plan and investment blueprint at Leaders’ Retreat | Planned, not yet launched |
| February 2027 | RTS Link passenger operations | Target, conditional on approvals |
| First quarter 2027 | Next joint investment forum | Planned |
| First five years of the agreement | 50 projects and 20,000 skilled jobs | Longer-term policy ambitions, not present achievements |
The first-five-years targets appear in Singapore EDB’s January 2025 agreement coverage. The current 28,755 potential jobs cannot be used to declare the 20,000 skilled-jobs target achieved because the statistics measure different things and do not establish completed hiring or skill classifications.
The 2027 outlook: opportunity is real, execution is the variable
The outlook is neither a foregone triumph nor an impending failure. The zone has policy backing, an already substantial investment pipeline, established industrial assets and the commercial logic of two tightly connected economies. Those are real advantages. Private-sector analysis from FactSet has also described how the corridor can connect larger investment projects with regional supply chains, finance and digital infrastructure.
Three paths are possible. In a stronger outcome, authorities resolve utility and border bottlenecks, skilled workers are trained, firms expand local procurement and approvals move steadily into production. In a middling outcome, investment proceeds but is concentrated in a few capital-heavy industries, leaving more modest gains for workers and small companies. In a weaker outcome, infrastructure delays, compliance costs and resource constraints slow implementation, while impressive approval totals continue to mask uneven delivery. These are analytical scenarios, not numerical forecasts.
The fairest conclusion is also the most demanding: US$21.8 billion in approved investment is evidence that Johor and Singapore have attracted serious commercial interest. It is not yet evidence that the economic transformation has been completed.
December’s blueprint offers both governments a chance to define success more rigorously—through operating projects, productive jobs, stronger local suppliers and a border that functions as a commercial connection rather than a daily obstacle.
The investment announcements have made the JS-SEZ impossible to ignore. Its implementation record will determine whether the rest of the world has reason to copy it.
Frequently asked questions
How much investment has the Johor–Singapore SEZ attracted in 2026?
As announced on November 2, the JS-SEZ recorded RM88.83 billion (approximately US$21.8 billion) in MIDA-covered approved investments from January 2025 through June 2026. It is a cumulative period figure, not an amount approved in 2026 alone. CNA.
How much of the JS-SEZ investment has been implemented?
RM40.3 billion, approximately 45.4% of the approved total, was classified as implemented at the June 2026 cutoff. The remainder is RM48.53 billion, but that does not mean every remaining project is stalled or cancelled. Bernama.
When will the Johor–Singapore SEZ master plan be released?
The governments said the master plan and investment blueprint were scheduled for the Malaysia–Singapore Leaders’ Retreat in December 2026. As of November 2, the launch had not yet occurred. The Business Times.
When will the Johor Bahru–Singapore RTS Link open?
The official target is February 2027, subject to independent safety certification and regulatory approval. That is a target rather than a guaranteed opening. Singapore LTA.
What incentives can eligible businesses receive in the JS-SEZ?
Qualifying investments may receive a 5% corporate tax rate for up to 15 years, while eligible knowledge workers may qualify for a 15% rate for 10 years. Incentives are subject to rules and are not automatic across all businesses or workers. Malaysia Ministry of Finance.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Geoeconomics
Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?
Luiz Inácio Lula da Silva was reelected president of Brazil in the runoff election on October 25, 2026, receiving 64,256,232 votes, equivalent to 51.79% of valid votes, according to the official announcement by the Superior Electoral Court (TSE). The result concluded the vote count in the presidential contest against Flávio Bolsonaro, but it did not automatically answer investors’ questions about public debt, spending, inflation, and growth. To understand the dollar and Brazil’s stock market after the election, it is more useful to examine which policies will be proposed, who can approve them, and how asset prices will incorporate that information than to assume a single market response based on who won.
This analysis was prepared on October 26, 2026, and does not provide unverified intraday quotations for the dollar or the Ibovespa. The election result is attributed to the TSE; interest-rate information to the Central Bank of Brazil; and macroeconomic scenarios to IMF documents. Trading-session fluctuations require additional checks against data showing the time, market, and source.
What the TSE Confirmed—and What Remains Disputed
The TSE announced Lula’s victory in the early hours of October 26. The vote count recorded 51.79% of valid votes for the reelected president and 48.21% for Flávio Bolsonaro, according to the official result reported in the court’s election coverage. The margin matters: the published count produced a clear outcome, but it also revealed a politically divided electorate.
The Associated Press reported that Flávio Bolsonaro challenged the process after voting hours were extended under exceptional circumstances. According to the report, the head of the electoral court said the extension did not change the outcome. A political challenge is not the same as a judicial annulment of an election. Investors, voters, and journalists should distinguish between the announced result, any appeals, and any subsequent legal ruling. This prevents an allegation from being presented as an established fact.
The winner faces a reality that does not disappear when the votes are counted: governing will depend on budget negotiations, Congress, court decisions, and economic actors. An electoral mandate confers the power to propose measures, not unilateral authority to change every tax, expenditure, and monetary rule immediately.
Why the Dollar Has No Predetermined Political Reaction
The USD/BRL exchange rate indicates how many Brazilian reais are needed to buy one US dollar. When the rate rises, the US currency becomes more expensive in reais; when it falls, the real appreciates against the dollar. It is tempting to attribute every movement to the elected president. But the exchange rate is simultaneously influenced by US interest rates, commodity prices, importers’ demand, investor flows, fiscal expectations, and global risk aversion.
An election can change expectations about tax revenue, fiscal expansion, and the credibility of policy targets. But much of that adjustment may have happened before the result as opinion polls and perceived probabilities shifted. A relatively small movement after the vote count would not prove market indifference; likewise, a sharp rise or fall could reflect international news released at the same time.
The proper method is to compare the observed exchange rate with the previous closing rate, record the exact time in Brasília, identify the exchange-rate category, and check for competing news developments. The commercial exchange rate traded in financial markets is not the same as the rate charged by a currency exchange bureau for travel. The official PTAX reference rate also follows its own methodology and schedule, unlike a simple instantaneous quote. To check these categories, consult the Central Bank of Brazil’s foreign-exchange services.
Therefore, publishing a statement such as “the dollar surges after Lula’s victory” without a confirmed price, timestamp, and size of the move would be misleading. It would also be wrong to conclude that any appreciation of the real demonstrates full market approval of the government’s program. Markets do not vote; they reprice probabilities and risks in response to multiple sources of information.
The Selic Rate Links Fiscal Policy, Exchange Rates, and Asset Prices
At its September meeting, the Monetary Policy Committee (Copom) reduced the benchmark interest rate to 13.75% per year, effective September 17, 2026, according to the Central Bank’s official announcement. This is a verifiable figure from before the runoff election, not a Central Bank reaction to Sunday’s result.
Interest rates matter because comparatively attractive returns on investments denominated in reais can draw capital, provided investors consider the risks acceptable. However, high rates also make borrowing, corporate financing, and debt servicing more expensive, constraining economic activity and putting pressure on public finances. The relationship is not linear: fiscal deterioration could require higher interest rates to compensate for risk, even if monetary authorities wanted to stimulate the economy.
In its September 2026 Monetary Policy Report, the Central Bank described unusually elevated inflation risks, expectations that remained under pressure, and caution in the adjustment process. The document provides a more reliable starting point than interpretations made just hours after the election. Copom makes decisions based on inflation, expectations, economic activity, and risks; there is no automatic rule requiring interest rates to rise or fall because a particular candidate wins.
If the government’s policy signals are consistent with a sustainable fiscal path, the risk premium could decline. If investors perceive persistent spending growth without credible financing, longer-term interest rates could rise. These are conditional scenarios, not forecasts of rates on a particular day.
The Ibovespa Responds to Profits, Sectors, and the Cost of Capital
Brazil’s stock market is not a simple referendum on the government. Exporters may benefit from a weaker real when converting foreign-currency revenue, although dollar-denominated costs and currency hedges alter the effect. Retailers and credit-dependent companies are often more sensitive to domestic interest rates and consumer spending. Banks face their own variables: lending spreads, loan defaults, demand for credit, and regulatory changes.
Companies involved in oil, mining, pulp, and food production also respond to global demand and international prices. News concerning China, the United States, or freight costs may carry more weight in a trading session than a domestic announcement. State-owned companies require specific analysis of strategy, governance, tariff rules, investment plans, and capital allocation, without assuming changes will occur on the first day after the election.
There is also a statistical trap: the index’s performance can conceal underlying differences. A gain driven by a handful of large companies does not prove a broad improvement in financing conditions for every Brazilian business. To assess the market’s reaction, examine sector weights, trading volume, long-term interest rates, and the performance of companies with different currency exposures.
Monitoring Matrix: What to Watch Instead of Guessing the Closing Price
| Topic | Indicator Worth Monitoring | Potential Economic Impact |
|---|---|---|
| Budget and debt | Targets, revenue sources, and the spending trajectory | Risk premiums, long-term interest rates, and exchange rates |
| Central Bank | Inflation, expectations, and Copom statements | Credit, fixed-income investments, and stock valuations |
| Foreign trade | Commodity prices and demand from trading partners | Exporters and dollar inflows |
| State-owned companies | Investment plans, governance, and tariffs | Expected earnings and perceived risk |
| Institutional politics | Negotiations and formal decisions | Feasibility and timing of reforms |
None of these indicators should be reduced to a single headline. What matters most is identifying persistent changes between policy announcements and their implementation.
The Fiscal Challenge Remains After the Election
A government may want to expand public services, investment, and social programs. The economic question is how to finance those commitments while keeping them compatible with growth, taxation, and debt sustainability. If expansion boosts demand in the short term but undermines confidence in fiscal sustainability, the effects on consumption and long-term investment may point in opposite directions.
In its July 2026 annual consultation, the IMF projected 2.4% growth for Brazil in 2026, alongside external and fiscal risks. That forecast was made months before the runoff election; it was not a post-election update. The organization highlighted international trade, prices, and financial conditions as important variables for the coming years.
Tax revenues depend on economic activity and the composition of growth. A credit-driven cycle may temporarily boost government revenues without resolving structural spending pressures. Measures to improve productivity, infrastructure, and tax simplification take time to yield measurable results. Government plans should therefore be judged not only by their promises but also by their timelines, costs, funding sources, and ability to be implemented.
The assessment must also recognize that public finances cannot be captured by a single indicator. The primary balance, interest payments, financing requirements, and nominal GDP growth can move in different directions. Communication that highlights only one number risks obscuring the more important underlying trajectory.
Exports, China, and Washington’s Trade Policy
Brazil sells agricultural products, minerals, energy, and manufactured goods to a range of markets. Changes in relations with the United States or China may affect prices, tariffs, and productive investment. But an election does not automatically rewrite existing contracts or eliminate international rules. Trade negotiations commonly involve sectors with competing interests, meaning a political victory may generate benefits for one group and costs for another.
The real responds to foreign-currency inflows and outflows, but export earnings also depend on volume, prices, and timing. Higher commodity prices may support some export revenues even amid domestic political turbulence; a global demand slowdown may hurt exporters even if the government announces fiscal measures that investors consider prudent.
For readers outside financial markets, it is worth monitoring the prices of imported fuel, international airfares, electronics, and agricultural inputs. A more expensive dollar tends to raise some costs in reais over time, but the extent to which those increases reach consumers depends on inventories, competition, contracts, and taxes. No one should promise that a single day’s exchange-rate movement will immediately change every price.
Three Scenarios for 2027—not Three Predictions
Greater predictability scenario: The government and Congress negotiate a budget with clear targets, inflation declines, and external conditions do not deteriorate. In that case, risk premiums could fall and create room for less restrictive financial conditions. This does not mean every stock must rise or that the dollar will decline without interruption.
Intermediate scenario: Fiscal decisions advance unevenly, reforms take longer, and economic activity slows moderately. Exchange rates and interest rates could fluctuate in response to domestic and international factors, with widely varying outcomes across companies. This scenario is a reminder that a “neutral market” is an oversimplification: different sectors experience different effects.
Pressure scenario: External shocks, revenue shortfalls, or persistent doubts about financing drive up the cost of capital. Higher interest rates may support the currency at certain times, but they can also slow investment and weaken the debt outlook. The ultimate outcome would depend on the combination of shocks and the policy responses.
These scenarios are conditional exercises designed to aid analysis, not estimated probabilities or recommendations to buy or sell securities.
What Still Cannot Be Claimed as of October 26
Sunday’s election result has been officially announced. There is still no basis for attributing a definitive dollar exchange rate, a long-term Ibovespa trend, or a future Copom decision to that result alone. A new mandate does not, by itself, determine the final wording of laws, Congress’s actions, or external conditions. Nor should a challenge reported after the runoff be confused with an actual reversal of the election result.
To follow the transition, first consult TSE announcements and formal decisions; then review Central Bank documents, budget proposals, and corporate disclosures. Only after that should these developments be connected to timestamped financial data. In economic reporting, the order of verification matters: institutional fact, economic mechanism, and finally price interpretation.
Frequently Asked Questions
Did Lula Win Brazil’s 2026 Presidential Election?
Yes. The TSE announced his reelection with 51.79% of valid votes in the October 25 runoff, according to its October 26 announcement. His opponent’s challenge was reported as a challenge, not an annulment.
Will the Dollar Rise Because of the Result?
There is no automatic answer. The real reflects interest rates, fiscal expectations, trade, global dollar movements, and news already priced into markets. A credible forecast requires a clearly stated time horizon and explicit assumptions.
Will the Stock Market Rise or Fall Today?
A specific direction can only be reported using trading data identified by time and market. This article does not present an unconfirmed intraday price as fact.
Will the Central Bank Change the Selic Rate Because of the Election?
The decision depends on monetary-policy objectives and indicators, not an automatic electoral trigger. The official pre-election reference was 13.75% per year, announced in September 2026.
Does the Result Change Taxes Immediately?
No. Most tax and budget changes require a proposal, legislative consideration, approval, and rules governing when they take effect. The result changes the political context, but it does not replace legal procedures.
What Readers Need to Know
The election settled who won, not what the dollar will be worth or how each company will grow. The useful task now is to monitor the decisions that follow: the budget, political negotiations, fiscal credibility, inflation, interest rates, and trade relations. Well-informed readers do not need to react to every fluctuation; they need to understand which developments would change the assessment of risk.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Democrats Won Congress. Can They Fix the U.S. Economy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025