
Business
How AI Is Reshaping the Future of Global Business Analytics

Almost every large company is experimenting with AI, and almost none can yet prove it moved the profit line. That gap is the real story of business analytics in 2026.
Key Takeaways
- Adoption is broad, scale is not. In McKinsey’s latest global survey, 62% of respondents said their organizations are at least experimenting with AI agents, but no more than 10% reported scaling agents in any single function (McKinsey).
- Winners are rare and deliberate. About 6% of respondents qualify as “AI high performers,” attributing 5% or more of EBIT to AI and reporting significant value (same McKinsey survey).
- Efficiency is the common goal; growth is the differentiator. Eighty percent say they set efficiency as an objective, but the biggest gainers often add growth or innovation targets too (McKinsey).
- Analytics is shifting from reports to conversations and actions. The change is less about prettier dashboards and more about who can ask questions of data and how fast answers arrive.
| Era | How analytics worked | What changed |
|---|---|---|
| Descriptive BI | Analysts build dashboards | Fast reporting, limited foresight |
| Predictive models | Data scientists forecast demand, churn, risk | Better planning, but specialist-dependent |
| Generative AI | Anyone asks questions in natural language | Wider access to insight |
| Agentic AI | Systems monitor data and take defined actions | Analysis connected to execution |
From Dashboards to Decisions
Traditional business intelligence answered “what happened.” AI-driven analytics tries to answer “what will happen, why, and what should we do?”
The shift shows up in four places:
- Forecasting. Models ingest more signals (pricing, weather, logistics, macro data) to sharpen demand and cash-flow forecasts.
- Anomaly detection. Systems flag unusual transactions, supplier delays, or margin leaks before a human spots them.
- Natural-language querying. Staff ask questions in plain language rather than waiting in an analyst queue.
- Automated action. Agents trigger workflows, such as reordering stock or escalating a risk, within guardrails.
The Reality Check
McKinsey describes a landscape of wider use alongside “stubborn growing pains,” with the move from pilots to scaled impact still a work in progress at most organizations (McKinsey).
Common reasons projects stall:
- Messy data. Models are only as good as the inputs.
- Unclear ownership. No executive is accountable for the business result.
- Workflows left unchanged. AI is bolted onto old processes rather than redesigning them.
- Trust gaps. Leaders hesitate to act on outputs they cannot audit.
What High Performers Do Differently
McKinsey’s high performers share traits worth copying (McKinsey):
- They push for transformative innovation rather than only cost cutting.
- They redesign workflows instead of automating existing ones.
- They scale faster and invest more.
- They use AI across more business functions.
- They have advanced further with AI agents.
Global Considerations
Multinational analytics adds complications that single-market firms avoid:
| Challenge | Why it matters |
|---|---|
| Data residency and privacy rules | Different regions restrict where data can be stored and processed |
| Currency and inflation effects | Forecast models must handle multi-currency volatility |
| Language and local context | Models trained mostly on English data may underperform locally |
| Regulatory divergence | AI governance rules differ across jurisdictions |
| Talent distribution | Skills are concentrated in a few hubs |
How to Build an AI Analytics Roadmap
- Start with a decision, not a tool. Pick one high-value decision (pricing, credit risk, inventory) and measure it.
- Fix the data first. Clean, governed data beats a fancier model.
- Keep a human in the loop for high-stakes calls until accuracy is proven.
- Define the metric. Tie the pilot to revenue, margin, or cost, not “usage.”
- Redesign the workflow. Change who does what, not just which software they use.
- Plan governance early. Document model sources, approvals, and audit trails.
- Scale only what pays. Kill pilots that do not move a number.
Costs and ROI: A Simple Framework
Estimate return as: (annual benefit − annual run cost) ÷ total investment. Benefits include hours saved, errors avoided, and revenue lift; costs include licenses, cloud compute, integration, and training. Be conservative: McKinsey’s data shows efficiency gains are common but enterprise-level profit impact is much rarer.
Risks to Manage
- Inaccuracy. Generative outputs can be confidently wrong; verify before acting.
- Bias. Historical data can encode unfair patterns.
- Security. Sensitive data fed into tools needs controls.
- Overreliance. Skills atrophy when teams stop questioning outputs.
Frequently Asked Questions
How is AI changing business analytics?
It moves analytics from static reports toward forecasting, plain-language querying, and automated actions.
What percentage of companies use AI agents?
In McKinsey’s survey, 62% were at least experimenting, and no more than 10% were scaling them in any one function (McKinsey).
Who are “AI high performers”?
Organizations attributing 5% or more of EBIT to AI and reporting significant value; about 6% of respondents (McKinsey).
Why do AI projects fail to scale?
Poor data, unclear ownership, unchanged workflows, and weak governance.
What should a company do first?
Choose one measurable decision, fix the underlying data, and pilot with a human in the loop.
The companies that win with AI analytics will not be the ones with the most dashboards. They will be the ones that let the answer change what they do on Monday morning.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Black Friday 2026 falls on November 27, and retailers have already started their early sales. Adobe forecasts that discounts will deepen as the season progresses, from about 14% off in early November to roughly 30% during Cyber Week. The National Retail Federation projects holiday sales will rise 4.2% to $1.013 trillion across November and December. For shoppers, the data supports a simple rule: buy early for items whose discounts are already deep and whose prices are unlikely to fall further, and wait for Cyber Week on the rest.
Key Takeaways
- Adobe forecasts average discounts of about 14% in early November, 21% just before Thanksgiving, and 30% during Cyber Week, per its 2026 holiday shopping forecast.
- The NRF projects U.S. retail sales in November and December 2026 will grow 4.2% to $1.013 trillion, according to a November 2026 retail report.
- Affordability is shaping plans: 56% of consumers expect economic conditions to influence their holiday spending, per an NRF survey.
- Adobe forecasts record BNPL spending of $21.3 billion for the season, up 6.6% year over year, which makes it easier to overspend.
- Many shoppers now concentrate purchases on Thanksgiving weekend, with an NRF survey reporting 64% likely to do most shopping then.
The Calendar: What Is Already Live
Early sales have started. Target ran an early event from November 5 to 7, and Best Buy released its first wave of doorbuster deals in the same week, according to tech shopping coverage from early November.
The broader calendar follows a predictable pattern:
- Early November: Retailers launch preview sales, with Adobe forecasting roughly 14% average discounts.
- Pre-Thanksgiving (through November 26): Discounts deepen, with Adobe forecasting about 21%.
- Black Friday (November 27): Limited doorbusters and category promotions.
- Cyber Week (November 30 to December 2, approximately): Adobe forecasts the season’s deepest average discounts, near 30%.
Adobe also forecasts Thanksgiving as the strongest mobile shopping day, so expect app-only and mobile-exclusive prices to matter.
Buy Now or Wait? A Decision Framework
Not every discount deserves a purchase. Use this checklist before buying early:
Buy now if:
- The item is a known price low, confirmed with a price-history tool such as a browser extension or the retailer’s own price history
- You need it before the holidays and inventory is limited
- The return policy is clear and the retailer accepts returns through January
- The discount exceeds the forecast average for the period (about 14% in early November)
Wait if:
- The item is a common category, such as TVs, toys, or appliances, where Adobe expects deeper discounts later in the month
- You are not in a hurry and the price has not moved from its normal level
- The seller’s return window is short or the product is final sale
Adobe’s forecasts point to clothing and electronics as categories likely to see deeper cuts, though these are category-level estimates rather than guarantees for specific products.
Read the Fine Print on Doorbusters
Limited-quantity deals often sell out quickly, and some retailers advertise a compare-at price that was never the normal selling price. Two checks help:
- Compare the advertised price against at least two prior price points from the past 60 to 90 days.
- Confirm whether the lower price applies to the specific model and configuration you want, since some promotions use slightly different models.
The NRF’s survey data suggests shoppers are already price-sensitive. Verifying the real discount is a practical way to avoid paying more than necessary.
Watch Out for Buy Now, Pay Later
BNPL is growing rapidly in holiday spending. Adobe forecasts $21.3 billion in BNPL spending for the season, more than the Cyber Monday spending total from prior years. BNPL can make a discount look smaller in monthly terms, but it can also encourage purchases that strain a budget.
Before using BNPL:
- Confirm the total cost, including any late or missed-payment fees
- Check whether the plan overlaps with existing installment loans
- Make sure you can pay each installment from current income
Consumer groups have repeatedly warned that spreading holiday purchases across multiple plans can hide total debt, so keep a running list of all open BNPL balances.
Spending Is Uneven Across Households
The NRF data show a divide. Between January and June 2026, spending by the top 10% of earners rose 4.2%, while spending in the bottom two income deciles was flat, compared with an overall gain of 3.2%. For many households, Black Friday is less about finding a bargain than deciding whether to buy at all.
Budget-friendly strategies include setting a holiday spending cap, buying gifts early when prices are low, and using cash-back or rewards cards only if the balance is paid in full each month.
Frequently Asked Questions
When is Black Friday 2026? Black Friday falls on Friday, November 27, 2026, the day after Thanksgiving.
How much can I expect to save during early sales? Adobe forecasts average discounts of about 14% in early November, rising to roughly 30% during Cyber Week. Individual product discounts vary widely, so compare against price history.
Should I buy electronics now or wait? Adobe expects some categories, including TVs and appliances, to see deep discounts later in the period. Buy now if the price is already at a confirmed low and you need the product soon. Otherwise, consider waiting for Cyber Week.
Is BNPL a good way to pay during the holidays? It can be, if you can pay each installment on time and the total cost is clear. Missed payments can carry fees, and multiple plans can make it hard to track total debt.
Are early deals always better than Black Friday deals? No. Early deals are often good, but Adobe’s data indicate discounts typically deepen later in the period, especially during Cyber Week.
How do I verify a discount is real? Check the price against recent history using a price-tracking tool, and confirm the sale price applies to the exact model you are buying.
Conclusion: Shop Data, Not Hype
Black Friday 2026 offers real opportunities, but the data point to a measured approach. Early discounts are substantial, and deeper ones are forecast later in the month. Use price history, understand return policies, and treat BNPL with caution. Buy early when the deal is confirmed and needed, and wait when the category typically sees deeper cuts.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
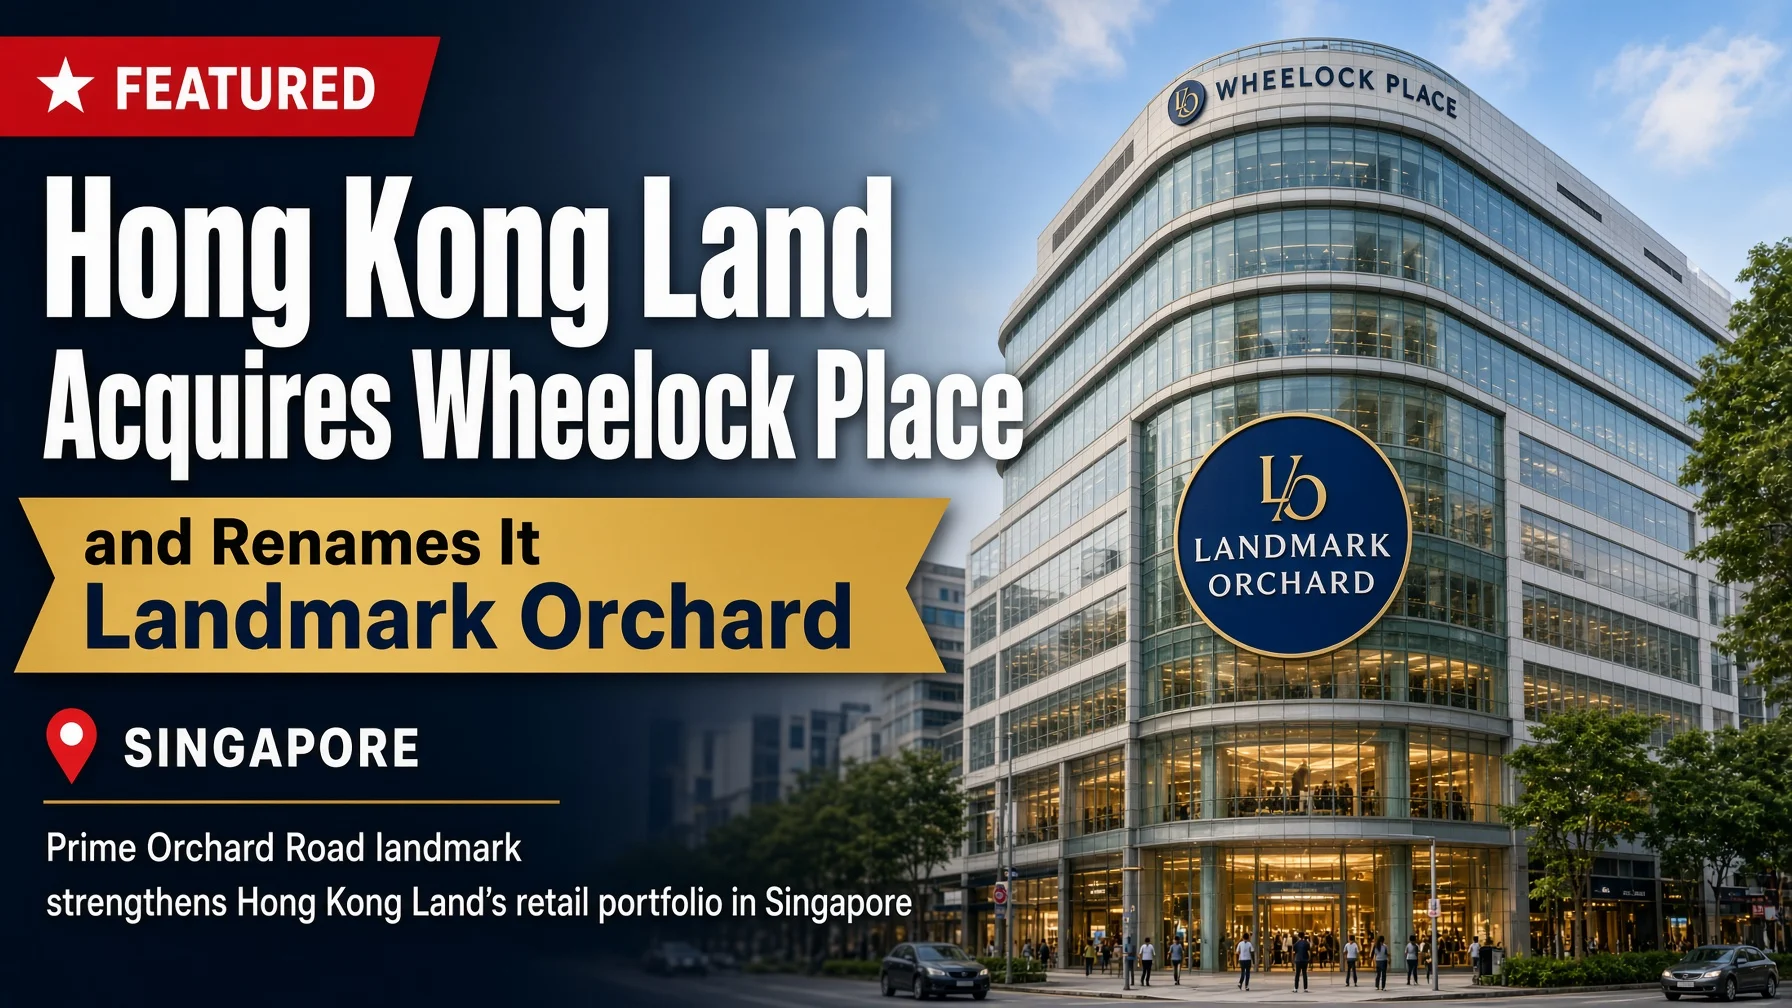
Hongkong Land’s Singapore Central Private Real Estate Fund completed the acquisition of Wheelock Place for approximately S$1.1 billion (roughly US$855–900 million) and, on 12 November 2026, renamed the prominent Orchard Road property Landmark Orchard. This is the first time the group has extended the Landmark brand beyond Hong Kong. The Straits Times
The 21-storey mixed-use building remains directly linked to Orchard MRT station and continues operating with existing office and retail tenants. The deal was the fund’s first acquisition since its February 2026 launch and advances Hongkong Land’s strategy of growing recurring income and its fund-management platform toward a target of roughly S$15 billion in assets under management. Channel NewsAsia
For Singapore’s commercial property market, the transaction confirms sustained institutional appetite for irreplaceable Orchard Road assets and signals long-term capital commitment to one of Asia’s premier retail and office corridors.
Table of Contents
- What Was the Acquisition Price and Deal Structure?
- Why Rename Wheelock Place to Landmark Orchard?
- What Are the Key Property Details and Location Advantages?
- How Does This Fit Hongkong Land’s Broader Strategy?
- What Does the Deal Mean for Orchard Road Tenants and the Precinct?
- What Enhancements and Capital Plans Are Expected?
- How Does the Transaction Compare with Recent Orchard Road Deals?
- Key Takeaways
- Frequently Asked Questions
What Was the Acquisition Price and Deal Structure?
The Singapore Central Private Real Estate Fund agreed in July 2026 to acquire Wheelock Place from an entity owned by Hong Kong-listed Wharf Real Estate Investment Company. The price of approximately S$1.1 billion aligned with an independent valuation. Completion took place around the end of August 2026, and the renaming became effective on 12 November 2026. The Straits Times
Allen & Gledhill advised the buyer, Lee & Lee represented the seller, and WongPartnership acted for the financing syndicate. The acquisition lifted the fund’s assets under management and was described as accretive to Hongkong Land’s underlying earnings. Hongkong Land maintains a majority equity stake in the fund and will earn additional management fees as the platform scales.
Why Rename Wheelock Place to Landmark Orchard?
Hongkong Land is deliberately exporting the Landmark identity that defines its flagship Central Hong Kong portfolio. Management stated that the name “Landmark Orchard” reflects a commitment to delivering a high-quality experience for tenants, visitors, and the surrounding community. The rebranding also creates regional brand consistency across the group’s premium commercial assets. Channel NewsAsia
Foo Pei Teng, Chief Executive of the fund, noted that this is the first use of the Landmark name outside Hong Kong and that the group intends to apply its long-term investment philosophy to the asset.
What Are the Key Property Details and Location Advantages?
Wheelock Place (now Landmark Orchard) comprises a 21-storey commercial tower and two basement levels with a total gross floor area of approximately 43,280 square metres. It offers office space, a retail podium, and car parking and enjoys direct underground connectivity to Orchard MRT station. The building sits at the strategic junction of Orchard Road, Scotts Road, and Paterson Road.
Originally opened in 1994 as Lane Crawford Place, it was later renamed Wheelock Place and has been a recognisable presence on Orchard Road for more than three decades. Its MRT linkage and central Orchard positioning provide strong footfall and accessibility advantages that institutional investors prize.
How Does This Fit Hongkong Land’s Broader Strategy?
The purchase advances two core objectives: expanding the third-party fund-management platform and increasing exposure to high-quality, recurring-income assets. The Singapore fund was established specifically to acquire rare institutional-grade properties. Completing a transaction of this scale within months of launch demonstrated both execution capability and limited-partner confidence. As assets under management move toward the S$15 billion target, Hongkong Land benefits from both co-investment returns and growing fee income.
The deal also extends the group’s Singapore footprint beyond the Marina Bay and CBD core into the Orchard Road belt, diversifying its local exposure.
What Does the Deal Mean for Orchard Road Tenants and the Precinct?
Existing office and retail tenants continue in occupation under the new name, so near-term operational disruption is minimal. Long-term institutional ownership by a well-capitalised player is generally viewed as positive for asset maintenance, tenant retention, and precinct quality. Over time, planned enhancements could improve the retail mix, common areas, and integration with the surrounding pedestrian and transit network, reinforcing Orchard Road’s competitiveness against other Asian shopping destinations.
What Enhancements and Capital Plans Are Expected?
Hongkong Land has not published a detailed capital-expenditure schedule. It has indicated that it will draw on extensive experience managing premium assets, including the ongoing multi-year transformation of its Hong Kong Landmark properties under the “Tomorrow’s CENTRAL” programme. Typical interventions for an asset of this type include selective retail reconfiguration, sustainability upgrades, improved vertical circulation, and stronger place-making around the MRT connection. Any major works are expected to be phased to limit tenant impact.
How Does the Transaction Compare with Recent Orchard Road Deals?
Prime Orchard Road assets trade infrequently. The S$1.1 billion price reflects both the property’s scale and its irreplaceable location. Comparable recent transactions in the precinct have also attracted long-term institutional capital, underscoring that global and regional investors continue to view Orchard Road as a core holding despite cyclical retail challenges. The Landmark rebranding adds a differentiating brand layer that few competing assets possess.
Transaction and Asset Snapshot
| Item | Detail |
|---|---|
| Purchase price | ≈ S$1.1 billion (US$855–900 million) |
| Buyer | Hongkong Land Singapore Central Private Real Estate Fund |
| Seller | Entity owned by Wharf Real Estate Investment Company |
| Completion | End-August 2026 |
| Renaming effective | 12 November 2026 |
| Gross floor area | ≈ 43,280 sq m |
| Key feature | Direct Orchard MRT connection |
| Fund AUM target | ≈ S$15 billion |
| Brand significance | First Landmark name use outside Hong Kong |
Key Takeaways
- Hongkong Land acquired Wheelock Place for approximately S$1.1 billion and renamed it Landmark Orchard.
- The transaction is the first acquisition of the Singapore Central Private Real Estate Fund.
- It marks the first extension of the Landmark brand beyond Hong Kong.
- Existing tenants remain in place; enhancements are planned over the medium term.
- The deal supports Hongkong Land’s dual goals of recurring-income growth and fund-management expansion.
- It reinforces institutional confidence in prime Orchard Road real estate.
Frequently Asked Questions
When did the name change take effect?
12 November 2026.
Do existing tenants have to move or renegotiate immediately?
No. Office and retail tenants continue operating under the new name.
Who sold the property?
An entity controlled by Wharf Real Estate Investment Company.
Is this Hongkong Land’s first Singapore asset?
No, but it is the fund’s first acquisition and the group’s first major Orchard Road holding under the new vehicle.
What is the fund’s assets-under-management target?
Approximately S$15 billion.
Will there be immediate large-scale renovations?
No detailed disruptive works have been announced; the emphasis is on continuity followed by phased enhancement.
How does the price compare with the independent valuation?
It was described as being in line with a recent independent valuation.
Conclusion
The conversion of Wheelock Place into Landmark Orchard is simultaneously a major real estate transaction and a strategic branding move for Hong Kong Land. For property, investment, and business audiences, the deal illustrates continued appetite for scarce Orchard Road assets and the expanding role of sponsored private funds in Singapore’s commercial market. Tenants and visitors should experience continuity in the near term, while the new ownership and landmark identity create a platform for gradual, quality-focused upgrades that can further strengthen one of the city’s most recognisable commercial addresses over the coming decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Why investors punished Google while largely sparing Microsoft—and what the historic sell-off reveals about the economics of artificial intelligence.
Wall Street has spent years rewarding technology companies for promising an artificial intelligence revolution. On October 29, it sent one of the revolution’s largest financiers a brutally different message: innovation may be impressive, but investors still expect a return on their money.
In a single trading session, approximately $500 billion evaporated from Alphabet’s stock market valuation. Shares in Google’s parent company plunged 12.6 percent, their worst one-day performance since the company’s public listing in 2004.
The extraordinary sell-off came after a quarter that, by many conventional measures, should have been cause for celebration. Alphabet reported revenue of $127.6 billion, a 25 percent increase from a year earlier. Its cloud division more than doubled its revenue. Operating income rose 30 percent.
Yet investors responded not with applause but with alarm.
The explanation lies in a troubling contradiction at the heart of the AI economy. The industry’s technological ambitions are accelerating faster than its capacity to translate those ambitions into cash.
What happened to Alphabet was not simply an earnings disappointment. It was a warning that the financial rules governing Silicon Valley’s AI investment boom may be changing.
And the contrasting treatment of Microsoft, which reported results on the same evening, offers an illuminating explanation.
The $500 Billion Warning
Alphabet’s financial results, released on October 28, exposed an uncomfortable imbalance.
The company generated $42.3 billion in operating cash flow during the third quarter. But it spent $51.4 billion on capital expenditure, primarily technical infrastructure. That left negative free cash flow of approximately $9.1 billion.
The previous quarter had produced a free-cash-flow deficit of $5.9 billion.
Two consecutive quarters in which capital investment exceeded internally generated operating cash represent a significant change in the financial profile of a business long celebrated for converting digital advertising into enormous amounts of cash.
The numbers are particularly striking because Alphabet’s investment programme shows little sign of slowing.
Management maintained its capital-expenditure forecast of $195 billion to $205 billion for 2026 and warned that spending would rise significantly again in 2027.
For investors, this raises a question that no amount of enthusiasm about large language models can easily answer: How much investment will be required before the financial rewards become commensurate with the costs?
The market was not reacting merely to the size of the expenditure. It was reacting to the possibility that infrastructure commitments could continue rising faster than the cash available to finance them.
There is, however, an essential distinction.
Alphabet is not a financially distressed company. According to its third-quarter regulatory filing, it held approximately $265 billion in cash, cash equivalents and marketable securities at the end of September, although that total included substantial equity holdings, including restricted SpaceX shares.
Its free cash flow over the preceding 12 months remained positive at $19.7 billion.
Moreover, an approximately $8.7 billion loss on equity securities—largely associated with SpaceX—depressed reported earnings without representing an equivalent quarterly operating cash outflow.
These distinctions matter. A temporary cash-flow deficit is not proof of impending insolvency, just as a large accounting profit is not proof that every investment creates economic value.
Alphabet has the resources to continue financing its ambitions. What investors are questioning is the price shareholders must pay for those ambitions, and the returns they will ultimately receive.
The market’s message is therefore more subtle than a rejection of AI: extraordinary financial capacity no longer guarantees unlimited investor patience.
Why Microsoft Escaped the Same Punishment
Microsoft’s earnings announcement provided a revealing contrast.
The company reported quarterly revenue of $92.3 billion, up 19 percent, while Azure revenue grew 48 percent.
It generated approximately $58 billion in operating cash flow and recorded $18.6 billion in positive free cash flow, despite capital expenditures of $45.2 billion.
Microsoft’s share price finished October 29 almost unchanged, declining approximately 0.2 percent.
That relative resilience was not because Microsoft had abandoned infrastructure spending. Nor was its investment programme fundamentally modest.
The company was continuing to commit extraordinary sums to data centres, processors and cloud infrastructure. Management projected approximately $170 billion in capital expenditures for calendar 2026, with some capacity deliveries delayed.
The distinction was that Microsoft’s operating cash generation continued to cover its cash capital investment, providing a financial cushion that Alphabet lacked during the latest quarter.
Microsoft also presented investors with a more immediately visible commercial connection between infrastructure and revenue.
Azure sells computing capacity directly to business customers. Microsoft can monetize AI through cloud consumption, enterprise software, development platforms and productivity subscriptions.
The relationship between customer demand, computational capacity and revenue is not perfectly transparent, but it is relatively straightforward.
When a business buys additional Azure computing capacity, Microsoft can demonstrate the associated revenue. That does not guarantee attractive returns on capital, but it offers investors a clearer path toward measuring them.
Alphabet faces a more complicated challenge.
Its infrastructure must support cloud customers, AI-model development and a vast collection of consumer services. Much of the expenditure is directed toward transforming products that users already access, including Search.
In those businesses, greater AI usage does not automatically produce a corresponding increase in revenue.
Nevertheless, the argument that Microsoft can finance its AI expansion entirely from internally generated cash also requires qualification.
On October 29, Microsoft priced a $25 billion offering of senior unsecured notes, with proceeds available for general corporate purposes, potentially including capital expenditure.
Even one of the industry’s strongest cash generators has chosen to supplement its financial resources through capital markets.
The real distinction is therefore not between companies that borrow and those that do not.
It is between companies whose investors remain confident in the relationship between investment, operating cash generation and future returns—and those for which that relationship has become harder to forecast.
Google’s Most Dangerous AI Problem Is Its Greatest Business
The more consequential challenge may lie beneath Alphabet’s capital expenditure.
Google’s search engine remains one of the most profitable commercial platforms ever created. For decades, its advertising model has depended on a remarkably efficient transaction: users express an intention, advertisers compete for their attention, and Google collects revenue.
Artificial intelligence threatens to alter that relationship.
Alphabet reported that Google Search and other advertising revenue grew 12 percent to approximately $63.4 billion in the third quarter, down from 17 percent growth in the preceding quarter.
The slowdown was not solely attributable to AI. Company executives pointed to currency effects and changing advertising patterns in specific industries, with foreign exchange identified as the largest factor.
But they also acknowledged that lower monetization in Google’s AI Mode was contributing to the deceleration.
This is the economic dilemma at the centre of Google’s transformation.
Traditional search presents users with advertisements alongside links to external websites. AI-powered search increasingly attempts to answer questions within Google’s own interface.
These experiences can be more useful, more conversational and more engaging. But the established commercial architecture does not transfer automatically.
A user who receives a comprehensive AI-generated answer may have less reason to click on conventional search results. Advertisers may need different formats to reach that user. Google must discover how to generate sufficient revenue from those interactions without compromising their usefulness.
Chief Executive Sundar Pichai has said AI investments are helping produce the fastest year-over-year growth in search queries in five years.
He has also reported that queries in AI Mode are, on average, three times longer than traditional searches.
Longer queries do not necessarily mean three times the computational cost. But they illustrate how significantly the product is changing.
The crucial question is whether this increased engagement can become sufficiently profitable engagement.
If Google’s new AI services attract greater usage but generate less advertising revenue per interaction, the company faces a double challenge: increasing infrastructure costs alongside uncertainty about monetization.
That possibility makes Alphabet’s situation different from a conventional infrastructure investment cycle.
Google is not merely building a new business. It is spending heavily to reinvent an existing one, partly to defend it against technologies that could undermine its established advantages.
And that creates a difficult strategic calculation.
Moving too slowly risks allowing competitors to redefine how consumers discover information. Moving too quickly could weaken the economics of the search business that finances Google’s technological ambitions.
For Alphabet, therefore, the cost of AI is not limited to servers, chips and electricity.
It also includes the possibility of disrupting one of the world’s most successful advertising models before an equally profitable successor is firmly established.
The Case Against Wall Street’s Verdict
There is a powerful counterargument to the market’s reaction.
Alphabet’s latest earnings contained evidence that its AI investments are already producing substantial commercial results.
Google Cloud revenue increased 103 percent to $30.7 billion, while the division’s operating income climbed from approximately $3.6 billion to $11.1 billion.
These are not the financial results of a business experiencing a collapse in AI demand.
They suggest that Alphabet is gaining meaningful commercial traction.
Importantly, the company said sales of its tensor processing unit systems made a significant contribution to Cloud’s expansion. Such hardware sales are not economically identical to recurring cloud-service revenue, and investors should distinguish between them when evaluating future growth.
Even so, the improvement in operating income is difficult to dismiss.
Alphabet has also built substantial expertise across semiconductor design, AI models, cloud infrastructure and consumer distribution.
Its ability to combine these capabilities may ultimately create advantages that narrower competitors struggle to replicate.
And large infrastructure investments frequently require cash long before their economic benefits become visible.
Data centres may take years to build and operate at full capacity. Customers may increase their spending gradually as applications move beyond experimentation into widespread deployment.
Judging a multiyear investment programme solely by two quarters of negative free cash flow would be shortsighted.
Indeed, if Alphabet’s investments strengthen its cloud business, improve the economics of inference and preserve Google’s position in search, the present spending surge could ultimately appear justified.
The difficulty is that investors must evaluate these possibilities before the returns become fully measurable.
That is what makes the debate so consequential.
The question is not whether Alphabet possesses valuable technology or whether demand for AI infrastructure exists. Its latest cloud results provide compelling evidence of both.
The question is whether today’s investment will earn sufficient returns to justify the company’s valuation after allowing for operating costs, depreciation, financing requirements and technological obsolescence.
That is a substantially higher standard than simply demonstrating rapid revenue growth.
The AI Boom Has Entered Its Financing Era
Alphabet’s experience is part of a much broader transformation in the economics of America’s largest technology companies.
The industry’s leading platforms are committing sums once associated with national infrastructure programmes.
Meta expects capital expenditures of $135 billion to $145 billion in 2026. It also reported negative free cash flow of approximately $2.1 billion in the third quarter.
Amazon’s October 29 results revealed a $42.4 billion free-cash-flow outflow over the preceding 12 months, despite AWS revenue growing 39 percent in the third quarter. Amazon maintained plans for approximately $220 billion in cash capital expenditures in 2026.
The enormous scale of these commitments suggests that AI is moving from a software-led innovation cycle into something closer to an industrial investment cycle.
Building the infrastructure requires land, electricity, cooling systems, semiconductors, financing and years of planning.
It also introduces risks unfamiliar to investors accustomed to the exceptional profitability of asset-light internet businesses.
An AI accelerator purchased today may become less economically competitive as newer processors arrive. Data-centre capacity must attract customers at prices sufficient to recover its cost. Electricity and cooling requirements can place lasting pressure on operating margins.
Accounting profits may remain strong while cash is tied up in new infrastructure.
Nor is the industry insulated from the cost of capital.
When borrowing becomes more expensive, when investors demand higher returns or when economic uncertainty affects enterprise spending, projects that once appeared compelling can become less attractive.
This does not mean an AI investment bubble must inevitably burst. Technological revolutions can deliver extraordinary productivity gains and create profitable businesses.
But history offers no guarantee that every company financing a technological revolution will capture a proportionate share of its economic benefits.
Railways transformed trade. Telecommunications transformed communication. The internet transformed commerce.
In each case, society’s long-term gains and the financial returns available to particular investors were not always the same thing.
Artificial intelligence may prove no different.
The Next Test Is Not Revenue Growth. It Is Return on Capital.
Investors should now demand more useful answers from technology companies than ever-larger announcements of capital expenditure.
How much additional revenue is generated by each dollar invested in computing infrastructure?
How quickly does new capacity reach commercially productive utilization?
Are businesses earning attractive margins after accounting for depreciation, energy, financing and maintenance?
And perhaps most importantly for Alphabet, can AI-powered search eventually produce revenue per user interaction comparable to—or better than—the traditional model it is replacing?
These questions matter more than headline declarations about model capabilities or user engagement.
Alphabet’s forthcoming fourth-quarter results, including further guidance on 2027 capital expenditure, will provide another opportunity to assess whether spending is beginning to stabilize relative to cash generation.
Microsoft will face similar scrutiny, especially as delayed GPU capacity becomes available and its own financing requirements increase.
The market’s relative tolerance toward Microsoft should not be mistaken for permanent immunity.
If AI revenue growth disappoints, or if capital requirements continue escalating faster than cash flow, even the strongest balance sheets will be tested.
There is another possibility, of course.
If AI adoption accelerates, infrastructure becomes more efficient and companies successfully develop profitable products, today’s expenditure could support years of earnings growth.
That outcome remains plausible.
But the burden of proof is shifting from technological promise to financial performance.
The End of Silicon Valley’s Blank Cheque
Alphabet’s historic sell-off may ultimately be remembered not as the moment Wall Street abandoned artificial intelligence, but as the moment it began taking the technology’s economics seriously.
The company did not lose roughly $500 billion in market value because its engineers had failed to build compelling AI products. It lost that value because investors became less confident about how much future cash shareholders would receive from the investments required to commercialize them.
Microsoft’s comparative resilience demonstrates the importance of that distinction. Investors were more willing to tolerate enormous capital commitments when supported by strong operating cash flow and clearer monetization prospects.
But Microsoft is not exempt from the same arithmetic, and Alphabet is far from defeated by it.
The real reckoning lies ahead.
Silicon Valley has successfully convinced the world that artificial intelligence will reshape how businesses operate and how people live.
Now it must prove that the economics of building that future will reward those paying for it.
For years, the defining question of the AI boom was who could build the most powerful technology. The defining question now is who can turn that technology into sustainable cash returns.
That is not the end of the AI revolution.
It may be the beginning of its financial maturity.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Tesla Cybercab and Robotaxi Economics in a Post-Midterm Environment

Impact of Pakistan’s Auto Policy on Local Manufacturers and Importers

Anthropic’s Financials and the AI Investment Thesis

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

SSI November 2026 Payment: Why Benefits Arrive October 30

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025