
Human Resourcs
Why Gen Z Job Market Struggles Persist in 2026 as Boomers Delay Retirement

Gen Z job market struggles intensify as baby boomers delay retirement and AI reshapes entry-level work. New data reveals the average age of new hires has spiked to historic highs in 2026.
Introduction: The Waiting Room Generation
Sarah Chen graduated summa cum laude from Georgetown in May 2024 with a degree in communications and a portfolio of internships at recognizable brands. Twenty months later, she’s still waiting tables at a Capitol Hill restaurant, her 247th job application pending in a digital void. Meanwhile, her manager—a 67-year-old boomer named Robert who once planned to retire at 62—just renewed his lease and shows no signs of stepping back.
This isn’t a story about individual failure or generational antagonism. It’s a structural realignment of the American workforce that’s quietly rewriting the rules of economic mobility.
New workforce analytics from Revelio Labs paint a startling picture: the average age of workers starting new positions has climbed to 42.3 years in late 2025, up from 38.1 years in 2019. For entry-level roles specifically, the median age has risen from 24.6 to 27.9 years over the same period. These aren’t marginal shifts—they represent a fundamental transformation in how labor markets allocate opportunity across generations.
Three converging forces are reshaping this landscape. First, baby boomers are delaying retirement en masse, driven by inadequate savings, longer lifespans, and the psychological rewards of continued engagement. Second, artificial intelligence and automation are hollowing out precisely the entry-level positions that once served as career launchpads for young workers. Third, economic uncertainty has made employers intensely risk-averse, favoring the perceived safety of experienced hires over the potential of unproven talent.
The result is a generational bottleneck with profound implications for social mobility, economic dynamism, and the very concept of the career ladder. Understanding this shift requires moving beyond simplistic narratives of lazy youth or greedy elders, and examining the deeper structural currents remaking work in the 2020s.
The Data Behind the Shift: Rising Average Age of New Hires
The numbers tell a story that individual anecdotes can only hint at. According to workforce data analyzed across millions of hiring transactions, the composition of new hires has undergone a dramatic demographic shift since the pandemic.
In 2019, workers under 30 accounted for 42% of all new hires in the United States. By the fourth quarter of 2025, that figure had dropped to 31%. Conversely, workers over 55 now represent 23% of new hires, up from 16% pre-pandemic. The center of gravity has shifted decisively toward older workers.
This trend extends beyond raw hiring numbers to encompass promotion rates and internal mobility. Research tracking career progression reveals that the average age at which workers receive their first managerial promotion has increased from 32 to 36 years over the past decade. The implicit message to younger workers is clear: you’ll need to wait longer for your turn.
The pattern isn’t uniform across all sectors. Technology companies, despite their youth-oriented culture, show some of the most pronounced shifts. Entry-level software engineering positions that once went to 22-year-old computer science graduates now routinely hire candidates in their late twenties with multiple prior roles on their resumes. The “junior developer” is becoming an endangered species, replaced by expectations of immediate productivity that favor experienced workers who can navigate complex codebases from day one.
Financial services and consulting have seen similar compression. Major banks and advisory firms, facing pressure to reduce training costs and minimize turnover, increasingly recruit from experienced talent pools rather than cultivate fresh graduates through traditional analyst programs. The old model of “up or out” apprenticeship has given way to lateral hiring of proven performers.
Even retail and hospitality—historically bastions of youth employment—are aging. Labor shortages in these sectors have prompted managers to retain older workers who might previously have transitioned to less physically demanding roles. The barista or sales associate is just as likely to be in their fifties as their twenties.
What explains this wholesale transformation? The answer lies not in any single cause, but in the interaction of demographic, technological, and economic forces that have aligned to favor experience over potential.
Why Boomers Are Delaying Retirement: Financial, Physical, and Existential Factors
The retirement plans of baby boomers have collided with economic reality. What was once envisioned as a graceful exit at 65—or even earlier—has morphed into an indefinite extension of working life for millions.
Financial Necessity Leads the Way
The primary driver is straightforward: inadequate savings. Despite decades of economic growth, the median retirement account balance for Americans aged 65-74 is approximately $200,000—a sum that sounds substantial until you calculate how long it needs to last. With life expectancy for a healthy 65-year-old now extending into the mid-eighties, retirees face the prospect of funding three decades without employment income.
Social Security, the bedrock of American retirement security, replaces only about 40% of pre-retirement income for average earners. The erosion of traditional defined-benefit pensions in favor of 401(k) plans has shifted investment risk onto individual workers, many of whom watched their savings crater during the 2008 financial crisis and struggle through the volatility of recent years.
Healthcare costs compound the financial pressure. Medicare doesn’t begin until 65, creating a coverage gap for those who might otherwise retire in their early sixties. Even after Medicare eligibility, supplemental insurance, prescription costs, and long-term care expenses can consume a substantial portion of fixed incomes. For many boomers, employer-provided health insurance is the golden handcuffs keeping them attached to their desks.
Housing equity, often touted as a retirement asset, proves less liquid than theory suggests. Reverse mortgages come with significant costs and complications. Downsizing requires navigating expensive and competitive housing markets. Many boomers find themselves asset-rich but cash-poor, living in homes whose paper value doesn’t translate into daily spending power.
Longer, Healthier Lives Change the Equation
Financial pressures tell only part of the story. Today’s 65-year-olds are fundamentally different from their counterparts a generation ago—they’re healthier, more active, and less inclined to view retirement as a final chapter.
Medical advances and lifestyle changes mean that many people in their sixties and early seventies possess the physical and cognitive capacity to continue working productively. The stereotype of the frail, confused elder bears little resemblance to the vigorous boomer still running marathons or managing complex projects.
This extended vitality intersects with shifting attitudes about work’s role in identity and purpose. For many professionals who spent decades building careers and deriving meaning from their work, retirement represents not liberation but loss. The structure, social connections, and sense of contribution that work provides aren’t easily replaced by leisure activities or volunteer work.
Organizations have adapted, offering flexible arrangements that allow older workers to scale back without fully departing. Part-time consulting, phased retirement, and remote work options enable boomers to maintain engagement on their own terms. These arrangements suit both parties—employers retain institutional knowledge and experienced judgment, while workers ease into retirement gradually.
The Unintended Consequences
Whatever the motivations—financial pressure, personal fulfillment, or some combination—the aggregate effect of delayed boomer retirement is a workforce that’s aging rapidly. In 2000, workers over 55 represented 13% of the labor force. Today, they account for nearly 25%, and projections suggest this share will continue growing through the end of the decade.
This demographic shift wouldn’t necessarily constrain opportunities for younger workers in a dynamic, expanding economy where job creation outpaces labor force growth. But the current moment is characterized by precisely the opposite conditions: slow growth, technological displacement, and corporate caution. Boomers aren’t retiring, and the economy isn’t generating enough new positions to absorb both older workers and younger entrants simultaneously.
AI and Economic Pressures Squeezing Entry-Level Jobs
While boomers occupy positions at the top and middle of organizational hierarchies, artificial intelligence and economic restructuring are systematically eliminating the bottom rungs of the career ladder.
The Automation of Beginning
Entry-level work has always served two functions: getting immediate tasks done, and training the next generation of skilled workers. AI is rapidly undermining both.
Consider the transformation of white-collar junior positions. Young lawyers once spent years reviewing documents and conducting legal research—tedious work, certainly, but invaluable apprenticeship in understanding case law and developing analytical rigor. AI-powered tools now perform this research in minutes, generating comprehensive briefs that senior attorneys can review and refine. The billable hours remain, but the learning opportunities for associates have evaporated.
Similar dynamics play out across professional services. Junior consultants who once built financial models and prepared PowerPoint decks find their roles compressed by sophisticated analytical software. Entry-level marketing analysts compete with AI systems that can segment audiences, optimize campaigns, and generate performance reports without human intervention. Accounting firms deploy machine learning algorithms that handle much of the routine work that once occupied first-year staff.
The technology sector faces its own paradox. While AI creates opportunities for experienced practitioners who can deploy and customize these systems, it eliminates many of the straightforward coding tasks that once allowed junior developers to contribute while learning. The pathway from computer science graduate to productive engineer has narrowed considerably.
Economic Anxiety Favors the Known
Layered atop technological change is a broader climate of economic uncertainty that makes employers deeply conservative in their hiring decisions.
The pandemic’s aftermath, inflation shocks, supply chain disruptions, and geopolitical instability have created an environment where companies prize predictability and proven performance. Hiring an experienced worker who can contribute immediately feels safer than investing in training a recent graduate who might take months or years to reach full productivity—and who might leave once that investment pays off.
This risk calculus is particularly acute in an era of rapid change where skills obsolescence accelerates. Why spend resources developing junior talent when the tools and techniques they’re learning might be outdated within a few years? Better to hire someone with current, demonstrable capabilities and worry about the next generation later.
The shift manifests in transformed job requirements. Positions advertised as “entry-level” increasingly demand three to five years of experience, fluency in multiple software platforms, and demonstrated results in previous roles. What was once understood as training that employers would provide has become a prerequisite that applicants must acquire elsewhere—though exactly where remains unclear.
The Apprenticeship Deficit
The compression of entry-level opportunity creates a vicious cycle. Young workers can’t gain experience because experience is required for employment. Alternative pathways—internships, apprenticeships, training programs—struggle to fill the gap at scale.
Unpaid or low-paid internships favor those with family financial support, exacerbating class divides. Formal apprenticeship programs, common in skilled trades, remain rare in professional white-collar sectors. Online courses and bootcamps proliferate, but can’t replicate the situated learning that comes from working alongside experienced practitioners on real problems.
The result is a growing cohort of young workers with credentials but without the practical experience that would make them attractive to risk-averse employers. Their skills remain theoretical, their potential unrealized, their frustration mounting.
The Human Toll on Gen Z: Stories, Struggles, and Adaptation
Behind the aggregate statistics are millions of individual stories of deferred dreams, financial precarity, and creative adaptation.
The Psychological Weight of Uncertainty
Mental health professionals report unprecedented levels of anxiety and depression among young adults navigating the job market. The experience of sending hundreds of applications into the void, receiving automated rejections or no response at all, and watching peers struggle equally corrodes confidence and hope.
The comparison with boomer experiences is stark and painful. That generation entered a labor market where college graduates could reasonably expect multiple job offers, employers invested heavily in training, and loyalty was rewarded with steady advancement. Today’s graduates face algorithms screening their resumes, AI-assisted interviews that feel dehumanizing, and the constant message that they’re not quite good enough.
This psychological burden intersects with other pressures defining Gen Z’s experience: student debt averaging $30,000 per borrower, housing costs that have outpaced income growth by historic margins, and a broader sense that the social contract promising education-led upward mobility has frayed beyond recognition.
Side Hustles and Alternative Pathways
Faced with constrained traditional employment, many young workers have turned to entrepreneurship, gig work, and portfolio careers that would have seemed exotic a generation ago.
Platforms like Upwork, Fiverr, and Etsy enable young people to monetize skills directly without passing through corporate gatekeepers. Content creation on YouTube, TikTok, and Substack offers routes to income and influence that don’t require permission from hiring managers. Freelance writing, design, coding, and consulting allow talented individuals to build reputations and client bases outside formal employment structures.
This shift contains both promise and peril. At its best, it represents genuine democratization of opportunity and entrepreneurial resilience. Young people denied traditional paths are creating their own, leveraging technology to access global markets and build businesses on their own terms.
At its worst, it’s precarity masquerading as flexibility. Gig work typically lacks benefits, job security, or advancement pathways. The constant hustle required to cobble together sufficient income from multiple streams can be exhausting and unsustainable. Not everyone has the temperament, skills, or resources to succeed as a solo entrepreneur.
The Geographic Dimension
Job market struggles aren’t evenly distributed across geography. Major coastal cities with diverse economies offer more opportunities than smaller metros and rural areas, but at the cost of living expenses that make entry-level salaries inadequate.
This creates difficult choices. Move to expensive cities where jobs exist but entry-level wages can’t cover rent without multiple roommates or family support? Or remain in affordable areas with limited opportunities in chosen fields? The compression of entry-level positions makes these tradeoffs more acute—when landing any job feels like winning the lottery, sacrificing location preferences becomes just another concession.
Remote work, initially heralded as a solution, has proven a mixed blessing. While it expands geographic options, it also intensifies competition. That entry-level marketing position at a Denver startup now attracts applicants from across the country, making an already difficult search even more competitive.
Global Parallels and Broader Implications
The generational employment squeeze isn’t uniquely American—similar dynamics are playing out across developed economies, suggesting deeper structural forces at work.
International Patterns
In the United Kingdom, youth unemployment has remained stubbornly elevated even as overall employment rates recovered from the pandemic. The “NEET” rate—young people not in education, employment, or training—stands above pre-2020 levels, particularly among those without university degrees.
Japanese labor markets show even more pronounced aging, with workers over 65 now comprising nearly 14% of the employed population, up from 9% a decade ago. The country’s declining birth rate compounds the generational imbalance, creating what economists call a “super-aged society” where traditional retirement patterns have broken down entirely.
European nations face similar pressures, though social safety nets and labor protections moderate some effects. Youth unemployment in Southern Europe—Spain, Italy, Greece—has long exceeded 20%, reflecting both cyclical economic weakness and structural mismatches between educational systems and labor market demands.
The Productivity Paradox
Standard economic theory suggests that labor markets should clear—if young workers are willing to accept lower wages than experienced workers, employers should hire them. The persistence of youth unemployment and underemployment alongside delayed retirement suggests something more complex is happening.
One explanation centers on skill-biased technological change accelerating faster than educational institutions can adapt. The skills taught in universities increasingly lag the capabilities required in rapidly evolving workplaces. Employers hire experienced workers not just for their general competence, but for specific, current expertise that can’t be acquired in academic settings.
Another factor is the changing nature of firm organization. As companies have flattened hierarchies and eliminated middle-management layers, they’ve reduced the supervisory capacity needed to train and mentor junior workers. Organizations structured around lean teams of senior practitioners have no obvious place to slot inexperienced newcomers who require significant oversight.
Long-Term Economic Consequences
The generational employment gap carries implications that extend well beyond individual career frustrations.
Economic mobility—the ability of each generation to exceed their parents’ living standards—depends on young people gaining productive work experience early in their careers. Delays in career launch compress lifetime earnings trajectories. Someone who starts meaningful employment at 27 rather than 22 loses five years of experience accumulation, wage growth, and retirement savings that compound throughout their working life.
Innovation and dynamism suffer when youth are locked out of opportunity. Historically, many breakthrough innovations came from young people bringing fresh perspectives to established industries. When entry barriers rise too high, these disruptive insights never reach the market. Organizations filled entirely with experienced workers, however competent, tend toward incremental improvement rather than radical rethinking.
Social cohesion frays when generations find themselves in zero-sum competition for limited opportunities. The temptation to blame boomers for “not retiring” or to dismiss Gen Z as “entitled” and “lazy” obscures the structural forces that have created mutual disadvantage. Boomers without adequate retirement savings can’t afford to step back; Gen Z graduates can’t gain the experience that would make them attractive hires. Neither group chose these circumstances.
Potential Solutions and Policy Paths Forward
Addressing the generational employment bottleneck requires interventions at multiple levels—corporate, educational, and governmental.
Corporate Innovation in Career Pathways
Forward-thinking organizations are experimenting with structures that create space for younger workers while retaining boomer expertise.
“Returnships” and structured apprenticeships bring recent graduates into organizations with explicit training timelines and mentorship pairings. Rather than expecting immediate productivity, these programs treat the first year as an investment in future capability. Companies absorb the costs by accepting slightly lower short-term output in exchange for developing loyal, well-trained employees with institutional knowledge.
Reverse mentoring programs pair junior employees with senior leaders, creating value exchange rather than one-way knowledge transfer. Young workers gain visibility and guidance while offering fresh perspectives on technology, social media, and emerging trends that older executives may not fully grasp.
Phased retirement programs help ease boomers out of full-time roles while preserving their knowledge. A 65-year-old might shift to part-time consulting, freeing up a full-time position while remaining available to train their successor. This gradual transition benefits everyone—the organization retains expertise, the boomer maintains income and purpose, and a younger worker gains opportunity.
Educational Adaptation
Universities and colleges must bridge the growing gap between academic curricula and workplace demands.
Expanding paid internship programs and cooperative education models gives students real work experience before graduation, making them more attractive hires. Partnerships between educational institutions and employers can create structured pathways that combine academic learning with practical application.
Micro-credentials and skills-based certifications offer alternatives to traditional degree programs, allowing workers to demonstrate specific competencies that employers value. Rather than relying on a bachelor’s degree as a general signal of capability, hiring processes could evaluate demonstrated skills in relevant technologies and practices.
Lifelong learning infrastructure becomes essential in a world where technological change renders skills obsolete rapidly. Programs that help mid-career workers retrain and adapt should expand, reducing the advantage that comes from already being employed and able to learn new tools on the job.
Government Policy Levers
Public policy can address structural barriers that prevent efficient generational transition.
Strengthening retirement security would enable more boomers to step back when they wish to. Expanding Social Security benefits, creating universal retirement savings accounts, and reforming healthcare to decouple coverage from employment would reduce the financial necessity of working into one’s seventies.
Tax incentives could encourage firms to hire and train younger workers. Wage subsidies or tax credits for creating entry-level positions with formal training components might offset the perceived risks of hiring inexperienced staff. These interventions would work best if designed to create genuine development opportunities rather than exploitative arrangements.
Active labor market policies—job placement assistance, training programs, wage insurance for career switchers—help match workers to evolving opportunities. Countries with strong active labor market policies, like Denmark and the Netherlands, show more successful generational transitions despite facing similar technological and demographic pressures.
Regulating AI deployment and automation might seem tempting but risks stifling productivity gains that ultimately benefit everyone. A better approach focuses on ensuring that gains from automation get shared broadly through progressive taxation, expanded social insurance, and public investment in skills development.
The Role of Cultural Narrative
Beyond policy mechanics, shifting cultural expectations matters enormously. The assumption that careers should follow a linear path from entry-level to senior positions over 40 uninterrupted years needs updating for a world of longer lives, multiple career chapters, and continuous technological change.
Normalizing career breaks, lateral moves, and later starts would reduce the stigma that currently attaches to non-traditional paths. A 30-year-old changing careers or a 45-year-old starting over should be seen as adaptive rather than failed. Similarly, a 70-year-old still working because they enjoy it should be distinguished from one working from desperation—and policies should address the latter while celebrating the former.
Conclusion: Toward a Multi-Generational Future
The collision between boomers delaying retirement and Gen Z struggling to launch careers isn’t primarily a story of individual moral failings or generational conflict. It reflects deeper structural shifts in how economies organize work, allocate opportunity, and distribute the gains from technological progress.
Solving this challenge requires moving beyond zero-sum thinking where one generation’s gains come at another’s expense. The goal isn’t to push boomers out prematurely or to lower standards for hiring young workers. Rather, it’s to create an economy dynamic enough to generate opportunity for workers at all life stages.
This means stronger retirement security so those who wish to step back can do so with dignity. It means educational systems that actually prepare young people for the work that exists, not the work of previous generations. It means corporate cultures that value fresh perspectives alongside experience. It means public policies that facilitate rather than obstruct generational transition.
The data showing rising age of new hires and compressed youth opportunity should serve as a call to action, not resignation. These trends aren’t inevitable—they’re the product of policy choices, corporate strategies, and social arrangements that can be reformed.
Sarah Chen, still waiting tables while sending out applications, and Robert, working into his late sixties despite dreams of retirement, aren’t enemies. They’re both responding rationally to a labor market shaped by forces largely beyond their control. Creating conditions where both can thrive—where experience is valued but youth gets its chance, where retirement is secure but those who wish to continue working can do so—should be the goal.
The future of work must be multi-generational by design, not accident. Getting there requires imagination, investment, and a willingness to challenge assumptions about how careers should unfold across a lifetime. The alternative—deepening generational resentment and wasted human potential—is too costly to accept.
The question isn’t whether Gen Z will eventually find its place or whether boomers will ultimately retire. Both will happen, in time. The question is whether we’ll build structures that make these transitions productive and humane, or whether we’ll continue muddling through, generation by generation, each facing unnecessary hardship that better systems could prevent.
The answer will shape not just individual careers, but the economic dynamism and social cohesion of the decades ahead.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The 2027 Veterans Affairs disability compensation increase is linked to the newly announced 3.6% Social Security cost-of-living adjustment. The Social Security Administration published that percentage on October 14, 2026, and VA explains that disability compensation uses the same annual percentage adjustment. That does not mean all veterans will receive an identical dollar increase. Your existing monthly payment, combined disability rating, eligible dependents and certain payment offsets determine the actual calculation. The essential distinction is between an official percentage and an individualized award letter. For primary-source background, consult SSA October 14 announcement; VA compensation rates; SSA 2027 fact sheet. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What has been officially announced
SSA confirmed a 3.6% 2027 COLA on October 14, replacing predictions published before the agency’s release. Its adjustment begins for Social Security benefits payable in January 2027, while increased Supplemental Security Income payments begin December 31, 2026. Veterans should not assume those Social Security disbursement dates are the same as VA deposit dates. The VA compensation website explicitly says that VA disability COLAs match Social Security’s percentage under law. The precise VA rate tables should be checked when the agency publishes or updates them. This article is about the rate change, not an assertion that any particular veteran’s payment has already increased.
How a percentage becomes an individual payment
A COLA works on the eligible base amount. Illustratively, multiplying $1,000 by 0.036 produces a $36 change and an adjusted total of $1,036. A $2,000 benefit yields a $72 arithmetic increase. These are not VA rating-table entries and should not be presented as 10%, 50%, or 100% disability compensation rates. The real award is calculated using statutory tables and the person’s dependency situation. A veteran with a spouse or children may receive a different absolute increase from an otherwise similarly rated veteran without dependents. Rounding conventions and deductions may also affect the displayed deposit.
The 2027 Veterans Affairs disability compensation increase is linked to the newly announced 3.6% Social Security cost-of-living adjustment.
Dependents, combined ratings and special compensation
The VA notes that eligible dependents may affect payments where a combined disability rating is at least 30%. Special monthly compensation can apply to particular severe disabilities or losses under separate criteria, making a generic table inadequate for everyone. Combined ratings are not simply the sum of individual conditions, so a change in one diagnosis should not be converted mechanically into a new combined percentage. Further, retirement-pay coordination, prior separation payments or other individual factors can affect the amount paid. Editorial charts should disclose their dependency assumptions and their effective dates in the column headings rather than hide them beneath a sensational figure.
2027 budgeting: gross change versus spending power
A 3.6% nominal payment increase does not demonstrate that every veteran will be better off in real terms. Housing, medicines, groceries and insurance can rise at different rates from the inflation index used to set the COLA. Build a basic household comparison using last year’s recurring expenses and next year’s expected bills. For example, a $72 monthly COLA is $864 over twelve months before payment-specific adjustments; that money may cover a recurring prescription, utility bill or part of a rent rise. Avoid claiming the COLA fully compensates every cost increase, because each household’s spending basket differs.
The safest way to check your own rate
Start with the latest VA compensation schedule for the applicable year, note your disability rating and household dependency category, and compare the official amount with your benefit history. Log into your VA account or review your award documentation if an amount seems unexpected. If a spouse, dependent child, school-age dependent or parent has changed status, contact the agency using its official process. Do not supply account passwords to third-party COLA calculators or assume a private website’s table is authoritative. The agency’s published figures—not estimates circulating on social media—should control your personal financial planning.
Worked example: how to interpret a difficult headline
A veteran paid $1,650 monthly might calculate $59.40 as a simple 3.6% illustration, leading to $1,709.40 before any statutory rounding or other changes. That is useful for household planning but not an official award. Another veteran might have a different dependency category and a higher eligible base. Compare the percentage consistently, then consult the actual table rather than transferring the first veteran’s dollar increase to the second. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| Official percentage | 3.6% SSA COLA is confirmed; it is not a forecast. |
| Illustrative increase | A multiplication example is not an official disability-rating table. |
| Actual deposit | Individual dependency, offsets and payment rules can matter. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- Publication of complete VA 2027 compensation tables.
- Any statutory or administrative change to payment dates.
- Updates to individual dependency or rating circumstances.
- Changes in VA online account notices.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
A published percentage is easy to quote; a defensible veteran-benefits explanation must also identify combined-rating, dependency and special-monthly-compensation distinctions. Generic internet tables rarely account for the exact individual award, so the most useful original value is a worked, explicitly illustrative calculation and a link to the VA category rules.
Frequently asked questions
Is the 2027 VA increase confirmed?
The underlying matching COLA is 3.6%, officially announced by SSA; use VA’s published compensation table to confirm exact dollar rates. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does everyone get the same number of extra dollars?
No. Percentage increases applied to different eligible base payments result in different dollar changes. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Does the adjustment change my disability rating?
No. A cost-of-living adjustment changes payment rates, not the medical or legal basis for a disability rating. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Can I estimate the new amount now?
You can calculate 3.6% of your current eligible base as an illustration, then reconcile it with VA’s official tables. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Bottom line
The 2027 Veterans Affairs disability compensation increase is linked to the newly announced 3.6% Social Security cost-of-living adjustment. The Social Security Administration published that percentage on October 14, 2026, and VA explains that disability compensation uses the same annual percentage adjustment. That does not mean all veterans will receive an identical dollar increase. Your existing monthly payment, combined disability rating, eligible dependents and certain payment offsets determine the actual calculation. The essential distinction is between an official percentage and an individualized award letter. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Jeff Bezos has floated a future in which artificial intelligence makes workers productive enough that some people might choose a three-day workweek while still supporting their families. The Amazon founder made the point during an October 7, 2026 interview with Fox News. He did not announce that Amazon is adopting a three-day schedule or that AI guarantees shorter hours for everyone. The underlying distinction is crucial: Bezos was describing a possible long-term economic outcome, not a new employment policy. Fox News’s account of the interview and Fast Company’s focused coverage make that clear.
Key takeaways:
- Bezos linked the possibility of fewer working days to future gains in AI-driven productivity.
- He suggested greater output could make single-income households or shorter working schedules financially feasible for some families.
- There is no evidence in the cited interview of a universal three-day-workweek plan at Amazon.
- Research shows AI can save time on some tasks, but broad effects on compensation and employment remain unsettled.
What did Jeff Bezos say?
In the Fox interview, Bezos discussed an optimistic vision of technological progress. His argument was that powerful AI tools could raise economic output enough to expand people’s choices. If a person can generate greater value in less time—and share financially in that improvement—working fewer days could become an option rather than a forced reduction in income.
That scenario is different from predicting every office will close on Thursdays and Fridays. It is also different from a government-mandated reduction in work hours. Fast Company reported Bezos’s additional concern that firms might face labor shortages if people respond to higher productivity by choosing more leisure time.
The prediction has attracted attention because it reverses the most alarming version of the AI-and-jobs debate. Instead of imagining machines replacing so many workers that employment vanishes, Bezos emphasized the possibility of prosperity, shorter hours and tighter labor supply.
Why the productivity argument matters
Labor productivity is commonly measured as output per hour worked. That is the U.S. Bureau of Labor Statistics’ definition. A software developer completing work that used to require ten hours in six may produce more per hour. A customer-service team handling routine requests faster may serve more customers without increasing headcount at the same rate.
But greater task efficiency does not automatically mean that an employee receives proportionally higher wages or fewer shifts. Businesses choose how to allocate productivity gains among pricing, investment, expansion, profits, compensation and staffing. Workers’ bargaining power, competition, management priorities and public policy can all shape the outcome.
A simple illustration—not a forecast
Imagine an employee currently produces 40 units of useful output during a 40-hour week. Productivity is one unit per hour. If technology raises the rate to 1.67 units an hour, a 24-hour week could, arithmetically, produce approximately 40 units.
That calculation only shows a technical possibility. It assumes the tasks can be reorganized, demand stays sufficiently steady, management accepts the schedule, and pay arrangements remain favorable. Healthcare, aviation, emergency services, logistics and many other occupations require coverage across specific hours; AI cannot simply eliminate the need for people to be present.
The important question is not whether an AI tool sometimes saves time. It is whether the gain is widespread, reliable and shared in a way that makes shorter schedules financially sustainable.
What does current research show about AI and jobs?
The evidence is more restrained than the boldest predictions. A June 2026 International Labour Organization review found evidence of real but uneven productivity gains. It also concluded that large-scale job displacement had remained limited in the material reviewed, while warning about inequality, weakened entry-level pathways and shifting job quality.
Separately, Yale’s Budget Lab tracker, updated September 15, 2026, reported no clear economy-wide labor-market disruption attributable to AI in the indicators it examined. Its researchers cautioned that the findings could change as technology adoption and data evolve.
These results do not prove Bezos wrong. They show that the conditions for a large-scale three-day week have not yet been demonstrated by broad labor data. Firms are experimenting with AI, but productivity effects differ among tasks, occupations and organizations.
Task savings are not the same as job transformation
An AI assistant might draft a first version of a memo quickly, but a professional still needs to check accuracy, speak with clients, make decisions and accept responsibility. A factory might improve planning efficiency while remaining constrained by physical machinery. A hospital might automate paperwork yet still need the same number of nurses for bedside care.
This distinction between automating tasks and replacing whole jobs is essential. Headlines suggesting a direct line from better chatbots to a nationwide three-day week skip multiple economic steps.
Could workers keep the same pay while working less?
They could in some workplaces, but that would require an employer decision, collective agreement, regulatory change or a labor-market environment supportive of higher effective hourly compensation. An employee moving from five eight-hour days to three eight-hour days would cut weekly hours from 40 to 24—a 40% reduction in hours. Keeping weekly pay unchanged would require compensation per hour to increase by about 67%, before considering other changes in productivity or operating costs.
That is a much larger adjustment than ordinary schedule flexibility. The arithmetic does not make it impossible; it makes the necessary improvement explicit. By contrast, a four-day, 32-hour schedule requires a 20% reduction in hours, a different benchmark entirely.
Any employer trial must ask whether output, service quality, employee retention and customer coverage are maintained. Studies of particular programs may be promising, but results do not transfer uniformly to every industry.
What about Amazon employees?
There is no verified connection between Bezos’s prediction and an official companywide Amazon three-day-workweek policy. Bezos is Amazon’s founder and executive chair, but his personal economic forecast should not be presented as a company announcement.
Amazon operates a mixture of offices, warehouses, cloud-computing facilities, transportation networks and other businesses. Working-hour patterns depend on the role and contract. A broad change in hours would require formal employee communications and operational planning, not merely comments in a television interview.
Readers searching “Is Amazon switching to three days?” should therefore receive an unambiguous answer: not on the basis of this interview.
Could AI create a labor shortage instead of mass unemployment?
Bezos’s labor-shortage concern is plausible as a scenario, but it is not an established forecast. If incomes rose while more workers elected to reduce hours, businesses might face greater competition for labor. Yet other forces could push the opposite way: some jobs could be automated, employers could reduce hiring, or new industries might absorb displaced workers.
The net result will depend on adoption speed, which tasks AI performs reliably, the cost of computing and energy, economic growth and how governments and companies manage the transition. Reuters’ October 2026 discussion of AI at work also emphasized that AI is changing tasks within jobs, with younger and experienced workers potentially affected differently.
Frequently asked questions
Did Jeff Bezos predict a three-day workweek?
Yes. He discussed it as a possible consequence of greater AI productivity during an October 7, 2026 Fox News interview. It was not a commitment to a timetable.
Is Amazon moving to a three-day workweek?
No companywide shift was announced in the interview. Any claimed policy should be verified against Amazon’s official employment communications.
Would a three-day workweek mean three eight-hour days?
Not necessarily. A three-day schedule could mean 24 hours, longer shifts or another arrangement. Bezos did not establish a universal definition or wage agreement.
Will AI eliminate the need to work?
There is no evidence supporting that as an inevitable outcome. The ILO’s 2026 review describes heterogeneous gains and risks rather than the disappearance of work.
Could AI make one-income households more common?
It could in theory if household purchasing power rises materially, but wages, housing costs, childcare, benefits and employment security also matter. The claim remains a scenario, not a confirmed demographic trend.
When could three-day workweeks become common?
No defensible national timetable can be inferred from the cited interview. Some employers may experiment sooner than others.
The bigger economic question
The provocative part of Bezos’s vision is not whether software can perform individual tasks faster. It is whether future productivity gains become broadly shared prosperity. If workers capture enough benefit, shorter schedules may become more feasible. If gains are concentrated in profits or paired with job insecurity, fewer working hours could instead mean lower household income. Those are fundamentally different futures, and the evidence today does not settle which will dominate.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
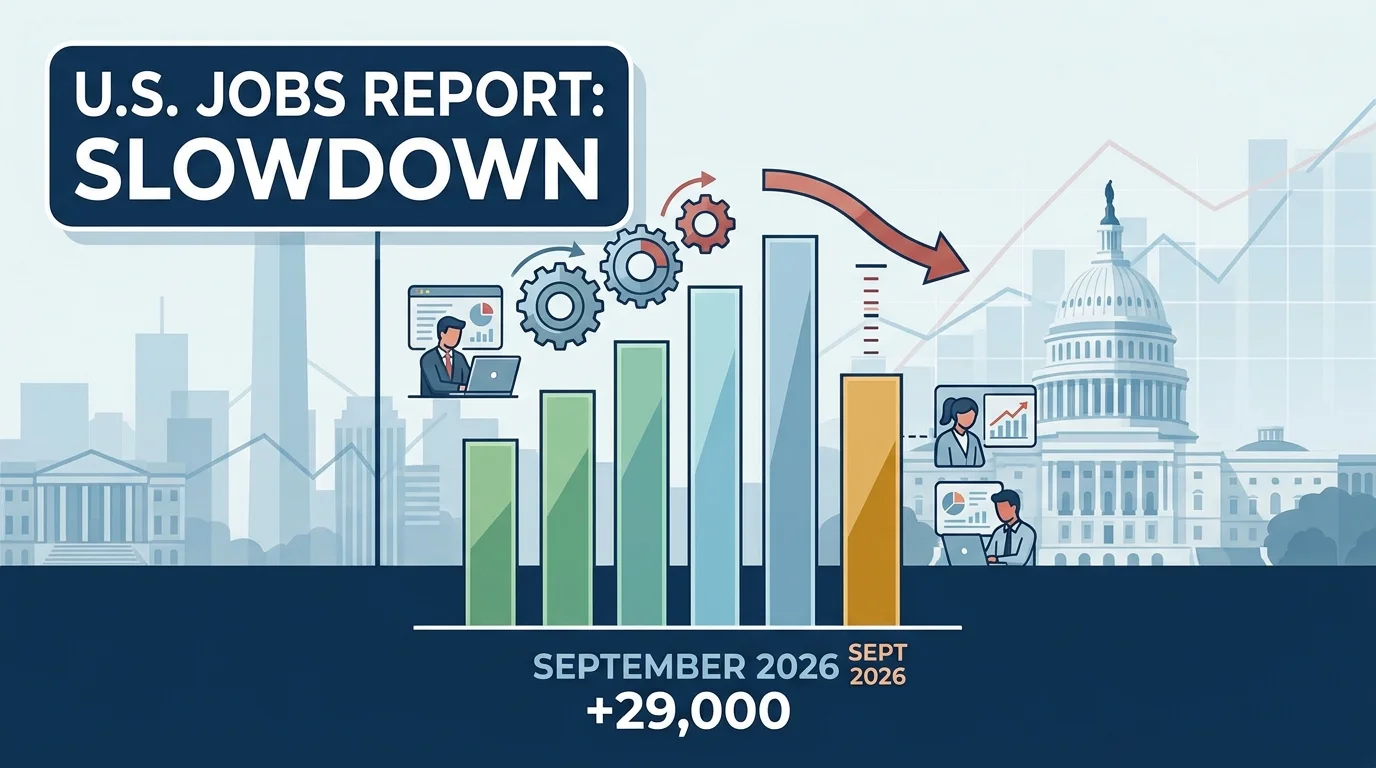
The U.S. labor market registered a sharp slowdown in September 2026, creating just 29,000 nonfarm payroll jobs—far below consensus forecasts of 84,000 to 95,000—while the national unemployment rate ticked upward to 4.2%. Data released by the U.S. Bureau of Labor Statistics highlights a broadening cooling trend across the private sector, accompanied by downward revisions to prior months and slowing wage expansion.
Executive Summary & Core Economic Indicators
The September numbers represent the weakest monthly payroll addition in over two years, signaling that prolonged high borrowing costs and corporate cost discipline are increasingly dampening hiring activity.
| Economic Metric | September 2026 Actual | Wall Street Consensus | Prior Month (August 2026) |
| Nonfarm Payroll Gains | +29,000 | +84,000 | +133,000 (Revised down from +162,000) |
| Unemployment Rate | 4.2% | 4.1% | 4.1% |
| Average Hourly Earnings (MoM) | +$0.05 (+0.1%) | +0.2% | +0.3% |
| Average Hourly Earnings (YoY) | +3.0% | +3.2% | +3.3% |
| Labor Force Participation Rate | 61.8% | 62.0% | 61.9% |
| Long-Term Unemployed Share | 27.1% | — | 26.8% |
Comprehensive Sectoral Breakdown
While job growth remained positive overall, expanding sectors failed to offset contractive pressures in service industries and negative net revisions from prior periods.
Sector Winners and Losers
- Health Care & Social Assistance (+17,000): Healthcare continued its trajectory as the primary engine of job creation, though gains decelerated significantly compared to its 12-month average monthly increase of 42,000.
- Construction (+11,000): Non-residential infrastructure and specialized trade contractors added modest headcounts, supported by ongoing federal energy and infrastructure outlays monitored by the U.S. Department of Labor.
- Manufacturing (+9,000): Factory employment posted light gains after several quarters of stagnation, primarily within durable goods manufacturing.
- Financial Activities (-7,000): Financial services experienced net losses, driven largely by layoffs in insurance carriers and mortgage origination units as elevated real estate yields curbed lending demand.
According to market sentiment tracking by Morningstar Market Research and economic feeds on Bloomberg News, the narrowing of job gains to fewer than three reliable sectors points to reduced labor demand across the wider service economy.
Negative Revisions & Wage Inflation Trends
A crucial element of the September report is the continuing pattern of downward revisions to past payroll data:
- July 2026 Revisions: Nonfarm payrolls were revised down by 31,000, shifting July’s net change into contraction territory at -10,000 jobs.
- August 2026 Revisions: August payroll additions were scaled down by 29,000, from an initial reading of 162,000 to 133,000 jobs.
- Combined Two-Month Drag: Revisions stripped 60,000 positions from previously reported figures, underscoring that momentum was weaker throughout Q3 than initially estimated.
Wage Growth and Inflation
Average hourly earnings for private nonfarm employees rose by 5 cents to $37.81, reflecting a year-over-year increase of 3.0%. This moderation in wage expansion aligns with the targeted disinflation trajectory monitored by the Federal Reserve System, reducing fears of a wage-price spiral while simultaneously limiting discretionary consumer spending growth.
Monetary Policy Implications for the Federal Reserve
The combination of slowing nonfarm payroll growth, a 4.2% jobless rate, and moderating wage pressures reshapes expectations for monetary policy.
Key macro takeaways for financial markets and monetary policy include:
- Pivot Toward Maximum Employment: Analysts at Reuters Economics and market analysts on Investing.com note that the Federal Open Market Committee (FOMC) must balance its inflation objective against rising risks to its full-employment mandate.
- Increased Probability of Rate Easing: Yields on short-term U.S. Treasury debt declined following the release, with interest rate futures pricing in a higher likelihood of consecutive 25-basis-point interest rate cuts at upcoming Federal Reserve policy meetings.
- Global Economic Fallout: International financial institutions, including the International Monetary Fund, track U.S. labor market developments closely, as softer domestic consumer demand in the United States directly influences global trade volumes and emerging market capital flows.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025