
News
Trump’s Proposed Credit Card Cap Spotlights Americans’ Debt. Would It Help?

Trump’s 10% credit card interest cap proposal targets America’s $1.17T debt crisis. Expert analysis reveals whether rate caps help consumers or create unintended consequences.
The $47,000 Question
Selena Cooper, a 34-year-old Denver schoolteacher, owes $47,000 across five credit cards. Her average interest rate hovers near 28%—meaning she pays roughly $13,000 annually just in interest charges before touching her principal balance. “I feel like I’m running on a treadmill that speeds up every month,” Cooper told The Washington Post in November 2024. “No matter how much I pay, the balance barely moves.”
Cooper’s predicament isn’t unique. Americans collectively owe $1.17 trillion in credit card debt as of late 2024, with average interest rates reaching 24.92%—the highest levels in nearly three decades. Against this backdrop, former President Donald Trump proposed during his 2024 campaign to cap credit card interest rates at 10%, positioning the policy as relief for working-class Americans crushed by what he termed “usurious” lending practices.
But would a federal interest rate ceiling actually help people like Cooper? Or would it trigger unintended consequences that leave vulnerable borrowers worse off? This analysis examines the economics, international precedents, and political feasibility of Trump’s credit card cap proposal—blending macroeconomic research with ground-level consumer impact.
The Credit Card Debt Crisis: America’s $1.17 Trillion Burden
Unprecedented Debt Acceleration
Credit card balances have surged 16% year-over-year, driven by persistent inflation, stagnant real wages, and post-pandemic consumption patterns. The Federal Reserve Bank of New York reports that credit card delinquencies—accounts more than 90 days past due—have climbed to 10.7%, approaching levels last seen during the 2008 financial crisis.
Key Statistics (Q4 2024):
| Metric | Current Figure | Historical Context |
|---|---|---|
| Total U.S. Credit Card Debt | $1.17 trillion | +42% since 2019 |
| Average APR | 24.92% | Highest since 1996 |
| Average Balance per Borrower | $6,501 | +18% vs. pre-pandemic |
| Delinquency Rate (90+ days) | 10.7% | Near 2009 peak of 11.8% |
Why Interest Rates Keep Climbing
The Federal Reserve’s aggressive rate-hiking cycle—11 increases between March 2022 and July 2023—directly transmitted to credit card APRs, which typically track the prime rate plus 15-20 percentage points. Unlike mortgages or auto loans, credit cards feature variable rates that adjust immediately when the Fed moves.
Compounding this structural dynamic, major issuers including JPMorgan Chase, Bank of America, and Citigroup have widened their interest margins. Analysis by the Consumer Financial Protection Bureau reveals that while the Fed’s benchmark rate increased 5.25 percentage points during the hiking cycle, average credit card rates rose nearly 7 percentage points—suggesting banks captured additional profit beyond pass-through costs.
Demographic Disparities
Lower-income households bear disproportionate burdens. Federal Reserve data shows that households earning under $50,000 annually carry average balances of $8,200 at rates exceeding 27%, while those earning over $100,000 maintain lower balances with average rates near 20%. This bifurcation reflects credit scoring systems that penalize thin credit files and past financial difficulties.
Source: Federal Reserve Consumer Credit Report , Consumer Financial Protection Bureau Analysis
Trump’s Proposal Explained: A 10% Federal Cap
Policy Mechanics
Trump’s campaign pledge, announced during a September 2024 rally in Pennsylvania, proposed federal legislation capping credit card interest rates at 10% annually. The policy would:
- Apply universally to all credit cards issued in the United States
- Override state usury laws where they exceed 10%
- Impose civil penalties on issuers violating the cap
- Create enforcement mechanisms through the CFPB and OCC
The proposal drew immediate comparisons to historical rate caps, including those advocated by Senator Bernie Sanders and Senator Josh Hawley, who have separately proposed 15% ceilings. Trump positioned his 10% figure as more aggressive consumer protection.
Political Context
Interest rate caps appeal across ideological lines. Polling conducted by Morning Consult in October 2024 found that 72% of Americans support limiting credit card interest rates, including 68% of Republicans and 77% of Democrats. This rare bipartisan consensus reflects widespread frustration with financial institutions—though economists remain divided on implementation.
The policy faces significant headwinds. Banking industry lobbying groups, including the American Bankers Association and the Consumer Bankers Association, have pledged to oppose federal rate caps, arguing they would restrict credit access and increase costs for responsible borrowers.
Source: Morning Consult Political Intelligence , American Bankers Association Position Papers
Would It Help? Expert Analysis and International Evidence
The Economic Argument Against Rate Caps
Most mainstream economists oppose price controls on credit, citing market distortion risks. Harvard Business School professor Vikram Pandit argues that interest rate caps function as “blunt instruments that disrupt credit pricing mechanisms without addressing root causes of over-indebtedness.”
Predicted Consequences:
- Credit Rationing: Banks would tighten underwriting standards, denying cards to subprime borrowers
- Fee Proliferation: Issuers would increase annual fees, balance transfer charges, and penalty fees to maintain margins
- Product Elimination: Low-limit cards serving credit-building consumers would become unprofitable
- Shadow Lending: Borrowers unable to access traditional credit might turn to payday lenders charging 400%+ APRs
A 2019 Federal Reserve study examining state-level usury laws found that jurisdictions with strict rate caps experienced 22% lower credit card approval rates and 31% higher denial rates for applicants with FICO scores below 680.
The Consumer Protection Counterargument
Advocates counter that current rates constitute predatory lending. Mehrsa Baradaran, law professor at UC Irvine and author of The Color of Money, told The New York Times: “When banks charge 29% interest on credit cards while paying depositors 0.5%, the asymmetry reveals market failure, not efficient pricing.”
Consumer advocates highlight that:
- Compound interest mechanics create debt spirals where minimum payments barely cover interest charges
- Algorithmic pricing discriminates against vulnerable populations
- Behavioral economics shows consumers systematically underestimate long-term borrowing costs
The Center for Responsible Lending estimates that a 15% cap (less aggressive than Trump’s proposal) would save American households $11.2 billion annually in interest charges—money that could flow toward principal reduction, emergency savings, or consumption.
International Precedents: Lessons from Rate-Capped Markets
Several developed economies impose credit card rate caps, offering natural experiments:
Canada: Québec province caps rates at criminal usury threshold of 35%—high by U.S. standards but enforced as a ceiling. Studies show minimal credit restriction effects, though issuers shift toward annual fees averaging CAD $120 versus $0-50 in other provinces.
Australia: No specific caps, but regulations require affordability assessments. Credit card debt remains significantly lower per capita than the U.S.
European Union: While no EU-wide cap exists, Germany and France maintain effective ceilings through consumer protection statutes. French law caps consumer credit at the “usury rate”—currently around 21% for revolving credit—yet maintains robust credit card markets with 78% adult card ownership.
Japan: Interest Rate Restriction Law caps consumer lending at 20%. The market adapted through comprehensive credit scoring and relationship banking models.
These examples suggest rate caps need not eliminate credit availability, but require complementary consumer protections to prevent fee substitution.
Source: Bank for International Settlements Working Papers , European Central Bank Consumer Research
Case Study: What a 10% Cap Would Mean for Selena Cooper
Returning to Cooper’s $47,000 balance at 28% APR: Under current terms, her minimum payment of $940/month covers $1,097 in monthly interest—meaning her balance actually increases by $157 despite payments. At this trajectory, Cooper would need 37 years and $410,000 in total payments to eliminate the debt.
Scenario Modeling
Current Reality (28% APR):
- Monthly interest: $1,097
- Minimum payment: $940
- Time to payoff: 37 years
- Total interest paid: $363,000
With 10% Cap:
- Monthly interest: $392
- Same $940 payment: $548 toward principal
- Time to payoff: 6.2 years
- Total interest paid: $23,100
Savings: $339,900 over life of debt
However, this optimistic scenario assumes Cooper retains card access under tightened underwriting. With a current FICO score of 640—damaged by her debt burden—she might face denial if banks restrict lending to prime borrowers.
Alternative outcome: Cooper loses her cards, consolidates through a personal loan at 18% (if approved), or resorts to debt settlement programs that devastate her credit for seven years.
“The question isn’t whether I’d benefit from lower rates,” Cooper explained. “It’s whether I’d still have any credit at all.”
Broader Implications: Winners, Losers, and Economic Ripple Effects
Impact on Financial Institutions
Major credit card issuers—JPMorgan Chase, American Express, Citigroup, Capital One, and Discover—derive substantial revenue from interest income. Industry data shows credit card interest and fees generated $176 billion for U.S. banks in 2023, representing 12% of total banking revenue.
A 10% cap would force business model transformations:
Revenue Compression Strategies:
- Increase annual fees (current average: $0-95 → projected: $150-300)
- Reduce rewards programs (eliminate 2% cashback cards)
- Impose balance transfer fees of 5-8% (versus current 3-5%)
- Monthly maintenance fees for active balances
Credit Tightening Measures:
- Raise minimum FICO requirements (projected: 680 → 720)
- Lower credit limits for existing cardholders
- Eliminate starter cards and secured card programs
- Reduce pre-approved offers by 60-70%
Macroeconomic Considerations
The Brookings Institution modeled a national rate cap’s GDP effects, finding:
- Short-term consumption boost: Borrowers redirect $8-12 billion from interest payments to spending, adding 0.05% to GDP
- Medium-term credit contraction: Reduced card availability decreases consumption by $18-25 billion, subtracting 0.08% from GDP
- Long-term ambiguity: Effects depend on whether consumers substitute other credit forms or adjust behavior
Federal Reserve economists note that credit cards function as automatic stabilizers during recessions—providing emergency liquidity when unemployment rises. Restricting access could amplify economic downturns.
Source: Brookings Institution Economic Studies , Journal of Financial Economics
Social Equity Dimensions
Critics argue rate caps would disproportionately harm the populations they intend to help. Research by the Federal Reserve Bank of Philadelphia found that minority borrowers, women, and rural residents rely more heavily on credit cards for emergency expenses and face steeper approval barriers than white, male, urban applicants.
If banks respond to rate caps by restricting access, these groups would face the sharpest credit crunches—potentially driving them toward predatory alternatives like payday loans, auto title lenders, and rent-to-own schemes charging effective APRs exceeding 200%.
Conversely, consumer advocates note that current high rates already exclude many low-income Americans from affordable credit, trapping them in subprime markets. A well-designed cap with concurrent lending accessibility requirements could expand responsible credit availability.
Alternative Solutions: Beyond Rate Caps
Comprehensive Debt Relief Programs
Rather than price controls, some economists advocate expanding debt relief mechanisms:
Federal Debt Restructuring: Similar to student loan forgiveness programs, Treasury could purchase and restructure credit card debt at reduced balances. Cost estimates: $180-240 billion for meaningful impact.
Mandatory Hardship Programs: Require issuers to offer 0% interest payment plans when borrowers demonstrate financial distress, similar to mortgage modification programs post-2008.
Bankruptcy Reform: Strengthen Chapter 7 and Chapter 13 protections for credit card debt, currently treated as non-priority unsecured claims with limited discharge potential.
Financial Literacy and Consumer Behavior
The Financial Industry Regulatory Authority (FINRA) Foundation reports that only 34% of Americans can correctly calculate compound interest on a hypothetical credit card balance. Educational initiatives could include:
- Mandatory high school financial literacy curricula (currently only 25 states require personal finance courses)
- Point-of-sale interest calculators showing long-term costs of minimum payments
- Behavioral nudges: Default to highest-balance-first payment allocation
Structural Banking Reforms
Progressive economists propose deeper interventions:
Postal Banking: Revive U.S. Postal Service banking services to offer low-cost credit alternatives, as proposed by Senator Kirsten Gillibrand. Post offices could issue cards at cost-plus-margin pricing.
Public Credit Registry: Replace private FICO scoring with transparent, public credit assessment reducing algorithmic discrimination.
Usury Law Modernization: Instead of hard caps, implement sliding scales indexed to federal funds rate (e.g., prime rate + 8%), automatically adjusting with monetary policy.
Source: FINRA Investor Education Foundation , Roosevelt Institute Policy Briefs
Political Feasibility and Implementation Challenges
Legislative Pathway
Trump’s proposal would require Congressional approval—a challenging prospect even with Republican control. Key obstacles:
- Banking Industry Opposition: Financial sector lobbying expenditures totaled $2.8 billion in 2024, dwarfing consumer advocacy spending
- Bipartisan Fragmentation: While voters support caps, legislators face donor pressure and ideological divisions on market intervention
- Regulatory Complexity: Implementation would require coordinating across CFPB, OCC, FDIC, and state banking regulators
Senator Elizabeth Warren introduced similar legislation in 2019 with 15% caps; it died in committee without a floor vote. Trump’s 10% version faces even steeper odds.
Constitutional and Legal Questions
Legal scholars debate whether federal rate caps violate constitutional protections:
- Contracts Clause: Retroactive application to existing balances might impair contractual obligations
- Takings Clause: Could forcing rate reductions constitute uncompensated taking of property (expected interest income)?
- Preemption Issues: Federal caps would override state laws, some permitting rates above 30%
Litigation would likely delay implementation 3-5 years, assuming passage.
Executive Action Alternatives
Trump could potentially implement partial measures through executive authority:
- Direct CFPB to expand supervision of “unfair, deceptive, or abusive” practices in credit card pricing
- Impose stricter rate disclosure requirements under Truth in Lending Act
- Limit rates on federally-chartered banks through OCC guidance (though national banks could switch to state charters)
These incremental approaches lack the sweeping impact of legislative caps but face fewer political hurdles.
Conclusion: A Flashpoint Issue Demanding Nuanced Solutions
Trump’s credit card cap proposal succeeds in spotlighting America’s $1.17 trillion debt burden and the predatory interest rates trapping millions in financial quicksand. For borrowers like Selena Cooper, the appeal is visceral—a 10% cap could transform debt from a life sentence to a manageable obligation.
Yet the economics prove complex. While international evidence demonstrates that rate caps need not eliminate credit markets, U.S. implementation faces unique challenges: a credit-dependent consumer economy, powerful banking lobbies, and constitutional constraints on market intervention.
The most constructive path forward likely combines elements:
- Moderate rate caps (15-18%) tied to prime rate benchmarks, avoiding both predatory extremes and severe credit rationing
- Strong anti-avoidance protections preventing fee substitution and product elimination
- Concurrent credit access mandates requiring issuers to serve diverse borrower pools
- Complementary consumer protections: enhanced financial literacy, affordable public credit alternatives, and strengthened bankruptcy discharge
The debt crisis demands solutions matching its scale. Whether Trump’s specific proposal advances or stalls, the underlying question persists: How should the world’s wealthiest nation balance credit availability with protection from usurious lending? The answer will shape economic mobility for generations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Original research October 12; updated October 15, 2026. Verify newer developments before publication.
Unexpected inflation can raise the expected interest-rate path and alter equity valuations and borrowing costs. Yield changes and bond-price changes move in opposite directions for an otherwise similar fixed-rate bond. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
Unexpected inflation can raise the expected interest-rate path and alter equity valuations and borrowing costs. Yield changes and bond-price changes move in opposite directions for an otherwise similar fixed-rate bond. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad? No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield? No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The Social Security Administration confirmed a 3.6% cost-of-living increase on October 14, 2026. Retirement and other Social Security payments rise beginning in January 2027, while adjusted SSI payments start December 31, 2026.
The Social Security Administration officially announced a 3.6% COLA on October 14, 2026, with January 2027 benefits affected and SSI increases beginning December 31, 2026. References to an unannounced 2027 COLA in the original article are superseded by this update. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
The Social Security Administration officially announced a 3.6% COLA on October 14, 2026, with January 2027 benefits affected and SSI increases beginning December 31, 2026. References to an unannounced 2027 COLA in the original article are superseded by this update. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
The 2027 Social Security cost-of-living adjustment was officially announced as 3.6% on October 14, 2026. The Bureau of Labor Statistics plans to release September inflation figures on October 14, supplying the final monthly input needed for the third-quarter calculation. Social Security says it will announce the next COLA in October. Avoid websites that state a projected percentage as though it were a confirmed benefit increase. Sources: Social Security Administration and SSA COLA announcement summary.
The important context competitors can overlook
The adjustment compares the July-to-September average of the CPI-W with the corresponding average in the prior base period, then rounds the percentage increase to one decimal place. It is not based simply on September year-over-year headline CPI. The confirmed 2026 COLA was 2.8%, which is an historical reference, not the 2027 outcome. With the percentage now announced, Medicare deductions, withholding and individual benefit amounts can make net deposits differ from a headline example. For primary-source checks and current reporting, see Social Security Administration and Bureau of Labor Statistics calendar. The key distinction is the confirmed 3.6% adjustment versus individualized net deposits.
A practical way to use this information
Bookmark the SSA COLA page rather than a social post. After the announcement, multiply your existing gross monthly amount by 1 plus the new rate and round only as the agency requires for your benefit. Compare that estimate with your official SSA notice and any Medicare premiums before adjusting a monthly spending plan. A $2,000 base and the confirmed 3.6% adjustment imply approximately $72 extra gross per month before rounding or deductions; the final individualized figure comes from SSA.
How a COLA percentage changes a monthly check
The arithmetic is useful only once the official COLA is known. The examples below are hypothetical gross increases, not predictions and not net deposits.
| Monthly benefit before adjustment | Hypothetical 2% raise | Hypothetical 3% raise | Hypothetical 4% raise |
|---|---|---|---|
| $1,500 | $30 | $45 | $60 |
| $2,000 | $40 | $60 | $80 |
| $2,500 | $50 | $75 | $100 |
After the agency announces the figure, replace the illustrative columns with the actual rate. Avoid treating the BLS September release date as a promise of an identically timed SSA announcement. The agency itself controls publication of its benefit tables and notices.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Has the 2027 COLA been announced? Yes. The SSA announced a 3.6% 2027 COLA on October 14, 2026.
When will new benefits arrive? The COLA is effective for December benefits generally paid in January; SSI has its own payment timing.
Why the CPI-W formula matters more than a prediction
The annual cost-of-living adjustment is designed to track price changes, not to reward beneficiaries for additional years of service or compensate every household for its exact spending mix. SSA compares the average Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) in July, August and September against the average from the last third quarter used to set a COLA. When the resulting percentage is positive, benefits are adjusted under the statutory formula. This means an unusually high single monthly inflation reading does not translate mechanically into an equally large annual raise. Readers who see forecasts from analysts should check which CPI-W releases were actually available when those forecasts were written.
Housing, food, healthcare and transportation costs can affect retirees differently from the CPI-W basket. A person who spends an unusually large share of their income on prescriptions or rent may experience greater pressure than the national index indicates. Conversely, people with fixed-rate mortgages and limited transportation expenses may experience a different inflation profile. The COLA is a national adjustment; it does not separately calculate the cost of living in Florida, California or any other state. It also does not directly determine a person’s eligibility for each unrelated assistance program.
Gross benefits, deposits and Medicare: three different numbers
A benefit increase is applied to the underlying Social Security calculation, but the amount landing in a bank account can depend on other items. Some beneficiaries have Medicare Part B premiums withheld. Others elect voluntary federal tax withholding or have deductions tied to particular circumstances. For a household budget, the relevant comparison is therefore last year’s net deposit against the next year’s net deposit, not simply the COLA rate multiplied by today’s direct deposit. Look at the gross amount, each deduction and the final payment separately when the benefit notice arrives.
For example, assume an illustrative gross benefit of $1,900 and a hypothetical 2.5% adjustment. The gross increase would be $47.50 before agency rounding and any deduction changes. If a separate monthly deduction also rises, the bank deposit will increase by less than $47.50. This is arithmetic, not a prediction of the coming COLA or Medicare premium. Check current Medicare information through Medicare.gov rather than assuming a headline on Social Security automatically describes Medicare costs.
A household budget test using the confirmed 3.6% increase
Retirees can now prepare using the confirmed 3.6% percentage. Start with a list of recurring essentials: housing, utilities, groceries, healthcare, transportation and debt payments. Identify which bills have already increased or will renew early in 2027. Then create three scenarios—no meaningful net increase, a modest net increase and a higher net increase—and test whether the monthly budget remains workable. The point is not to forecast the government announcement. It is to learn whether an existing emergency fund or spending adjustment would be needed if inflation remains elevated despite a benefit change.
For couples, include whether both people receive Social Security benefits, whether either has wages, and whether the household has pension or investment income. Someone receiving Supplemental Security Income should check SSI-specific payment information rather than simply applying a retired-worker example. Survivors and disability beneficiaries should also rely on their own SSA notices. A household with multiple benefit types should not assume every payment has identical timing or deductions.
Avoid misleading COLA headlines and scams
Historically, before the official announcement, headlines mixed forecasts, the prior year’s adjustment, preliminary CPI data and the amount of a hypothetical average check. Those are four different things. A correct headline should say whether the adjustment is estimated or official, give the year to which it applies and link directly to the issuing agency. Once confirmed, the actual percentage should be used consistently in every table, search snippet and social caption. If an older story stays live, label the update date prominently; search traffic can continue long after the numbers change.
Beneficiaries do not need to pay a third party to activate a standard COLA. Treat unsolicited calls or messages requesting a Social Security number, payment or banking credentials as suspicious. Navigate directly to SSA’s official website or your established account rather than following an unexpected text link. A legitimate forecast can help with planning; it is not a substitute for a personalized benefit notice.
Questions beneficiaries should ask after the release
- What official 2027 COLA percentage did SSA announce, and on what date?
- Does the statement show gross benefits as well as Medicare and other deductions?
- When will the relevant January or SSI payment be issued under the official calendar?
- Is a reported “average increase” describing all beneficiaries or a selected benefit category?
- Has any tax withholding or household income changed independently of the COLA?
These checks turn a widely searched announcement into information a retiree can actually use. The strongest article on this subject does not merely repeat a percentage: it explains where that number came from and why two beneficiaries can see different dollar changes.
How to calculate the confirmed 3.6% increase
For an illustrative $1,500 monthly gross benefit, a 3.6% increase equals $54 and produces an estimated $1,554 gross amount before any deductions or rounding. A $2,000 monthly gross benefit produces a $72 illustrative monthly increase; $2,500 produces $90. These examples are arithmetic, not individual benefit estimates, and should not be confused with take-home deposits. Medicare premiums, withholding and other adjustments can make the deposit different from the COLA multiplication. The agency says the average retiree increase is around $75; an average does not mean every recipient gets exactly that amount. See the official COLA announcement and 2027 SSA fact sheet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
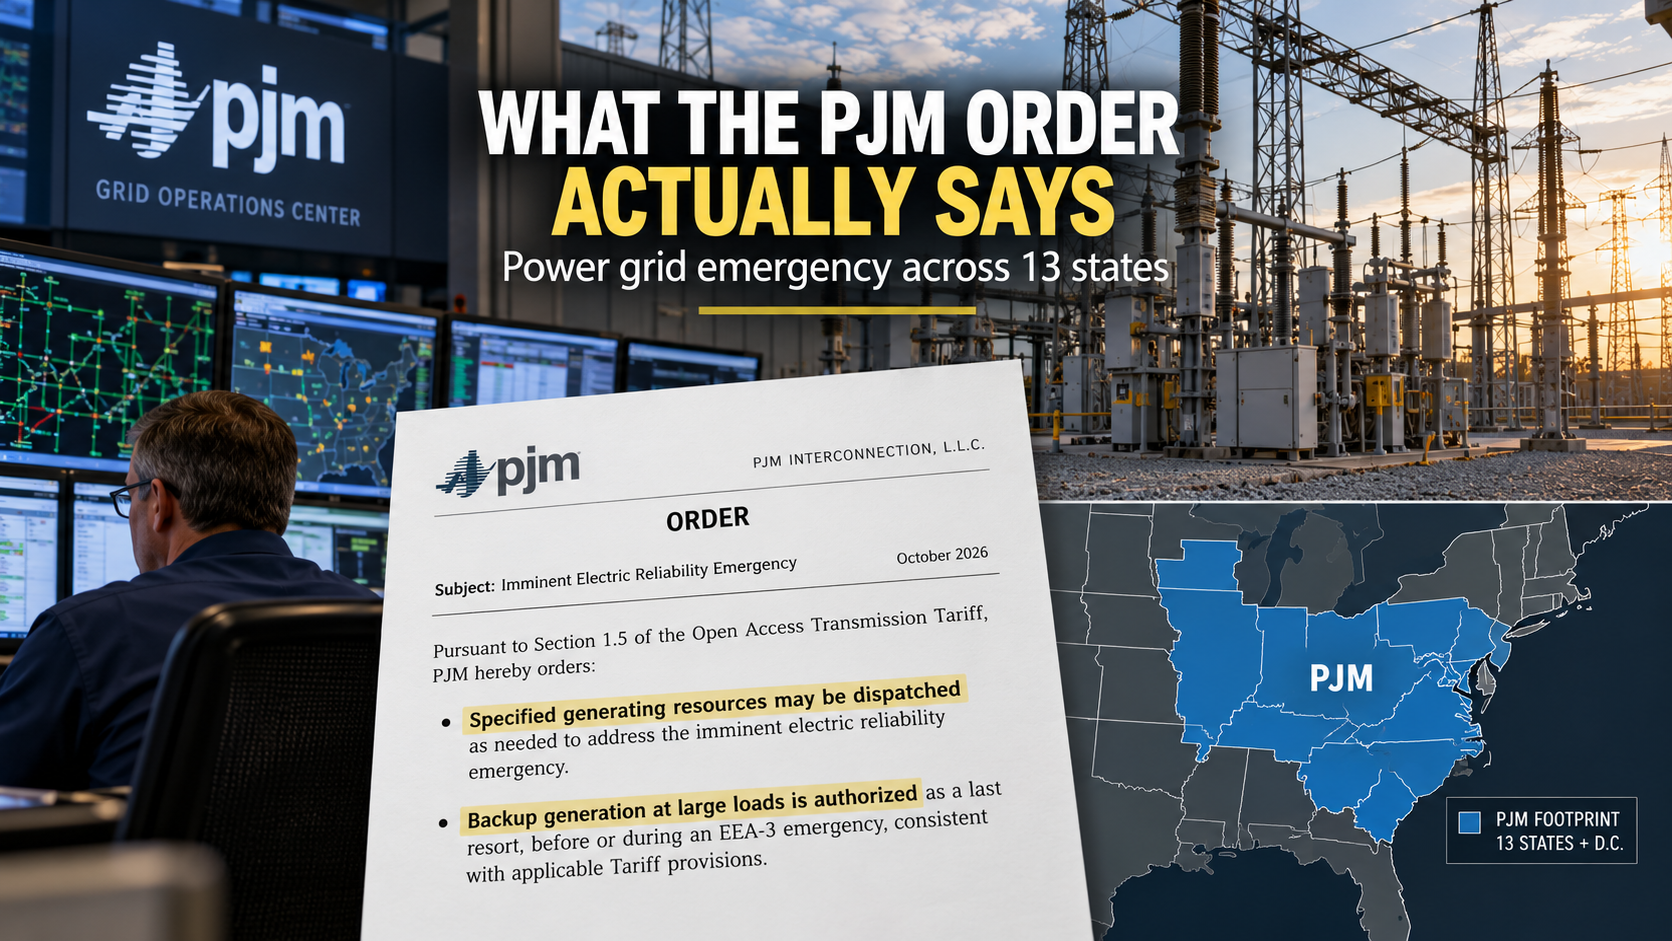
A federal emergency power order affecting the PJM electricity region has triggered searches about a “13-state power-grid emergency.” The Department of Energy’s 202(c) order, issued October 12 and effective October 13–16, gives PJM additional authority to dispatch specified generation resources to support reliability.
The essential answer
A federal emergency power order affecting the PJM electricity region has triggered searches about a “13-state power-grid emergency.” The Department of Energy’s 202(c) order, issued October 12 and effective October 13–16, gives PJM additional authority to dispatch specified generation resources to support reliability. Crucially, the presence of an emergency order does not establish that all homes across 13 states have lost power, nor does it imply every jurisdiction faces the same immediate conditions. Readers need to understand the grid operator, the legal authority, the dates and what reliable local outage information actually shows. For primary-source background, consult DOE 2026 emergency orders; PJM Interconnection; US Energy Information Administration. In a fast-moving topic, publication time and information cutoff matter: subsequent events may require updating the figures or legal status, not merely changing the date in the footer.
What the Department of Energy ordered
The DOE lists Order No. 202-26-50 as issued October 12, effective October 13 through October 16, pursuant to section 202(c) of the Federal Power Act. It authorizes PJM to direct specified generating units to operate as needed for reliability, and backup resources under defined emergency conditions. These are operational instructions within a regional system—not a declaration that each customer is experiencing a blackout. The precise order language, affected facilities and reporting requirements should be read in the DOE order listing. Avoid confusing the issue date with its effective date.
What PJM does and how regional power flows work
PJM is a regional transmission organization coordinating wholesale electricity and high-voltage transmission across a multistate footprint. Electricity crosses state borders within interconnected systems, so a regional reliability challenge is not neatly contained by state boundaries. PJM can respond using dispatch instructions, imports, reserves and demand-side measures. The actions differ from the local distribution utility’s job of restoring a downed neighborhood power line. A headline that counts states in the operator’s footprint is a geographic description, not a census of customers without electricity.
Reliability orders versus rolling blackouts
Power-system terminology is precise. A reliability alert or emergency order may be preventive, designed to preserve margin before a more serious shortage. A formal energy emergency alert is not equivalent to every utility carrying out customer disconnections. Rolling blackouts occur only under particular operational conditions and should be verified through utilities and grid-operator statements. A local outage can also be caused by storms, equipment damage or a vehicle striking a pole, unrelated to the PJM-wide instruction. Reporters should state what has actually happened and avoid sensationalizing a contingency measure.
The reasons emergency flexibility can matter
Unexpected generating-unit outages, unusually high demand, constrained fuel supply and transmission limits can put pressure on available reserves. Dispatching a resource that normally would not be run can make a difference during a narrow period. However, that flexibility may carry extra cost, emissions or operating constraints, making the legal basis and duration important. It is not a permanent answer to every electricity system challenge. Long-run reliability requires sufficient generation, transmission investment, maintenance, fuel planning and realistic forecasts of demand from data centers, industries and households.
What residents and businesses should actually do
Check your own utility’s outage dashboard for local conditions, and subscribe to official emergency alerts rather than forwarding unsourced statewide warnings. Households relying on powered medical equipment should follow prearranged contingency instructions from care providers and local emergency authorities. Businesses can review backup-power readiness, facility cooling requirements and safe shutdown procedures. Do not run portable generators indoors or near open windows because of carbon-monoxide risk. Most importantly, make decisions based on local alerts and utility notices—not the existence of a regional legal order alone.
Worked example: how to interpret a difficult headline
A Pennsylvania resident sees a headline referring to 13 states but finds no outage at home. A separate community may experience a distribution fault after a storm. Both situations can coexist with the PJM order, because the federal dispatch authorization, regional resource balance and local service status are three different things. The correct reporting should describe these layers rather than merging them into one dramatic claim. This is a deliberately illustrative comparison unless explicit documented numbers are identified. It should not be mistaken for a real person’s financial circumstances, an unverified event, or a guaranteed forecast. Its purpose is to show how a reader can apply the underlying principle and identify which information still needs to be checked.
Three concepts that are often confused
| Concept | What it actually establishes |
|---|---|
| DOE emergency order | Federal reliability authority with stated dates and conditions. |
| PJM alert or dispatch | Regional operational decision about resources. |
| Local outage report | Utility information about affected customers and restoration. |
These distinctions are more than technical niceties. They change the answer to the reader’s question. An estimate does not carry the same evidentiary weight as a final rule; an announcement does not have the same practical consequence as a completed transaction; and a provisional interpretation should not be presented as a confirmed event. Wherever a live source supplies a new fact, the editor should check whether the old text still describes the right stage of the process.
A reader’s verification workflow
Start by recording the precise claim and the date it was allegedly true. Open the primary announcement or filing rather than a social-media screenshot. Ask whether the source has an incentive to present only the most favorable interpretation, and corroborate material facts with reputable independent reporting where available. For numerical claims, note the denominator, timeframe and whether the number is a stock, a flow, a forecast or a realized result. For legal claims, note the court, agency, stage of proceedings and exact published document.
Next, separate information useful for immediate decisions from context that merely explains the headline. A person may need to act on a deadline even when the long-run political debate remains unresolved. Someone evaluating a security may need financing details, while a customer comparing technology products needs a tested specification and local warranty terms. The same headline can matter for different reasons; the article should therefore provide an actionable answer without implying that every reader faces the same circumstances.
Indicators and developments worth monitoring
- Expiration or extension of DOE Order 202-26-50.
- PJM-issued operational and emergency-alert statements.
- Utility outage maps and local emergency notices.
- Any official review of costs or environmental conditions.
Avoid treating these signals as a checklist that mechanically predicts the future. Some are leading indications and others are lagging measurements. A change becomes significant only after its magnitude, source and comparison period are understood. If two reputable sources disagree, explain the source of the difference—definitions, timing, jurisdiction, measurement or uncertainty—instead of selecting whichever number makes the strongest headline. That practice strengthens both reader trust and the article’s usefulness in search features that surface isolated paragraphs.
The specific information advantage of this article
The emotional headline suggests widespread darkness; the official document authorizes regional operating flexibility. Explaining the relationship between federal emergency power, PJM dispatch and the local utility outage map prevents a materially misleading inference about households across the region.
Frequently asked questions
Are 13 states completely without power?
The federal order does not establish that; check utility outage reports for actual affected customers. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
What is PJM?
A regional electricity transmission and wholesale-market operator serving a multistate region. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
When does the order run?
The DOE lists October 13–16, 2026, as the effective period. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Where should I check my address?
Your electricity utility and local emergency management office provide the most relevant service and safety updates. For individual decisions, consult the primary institution or product provider, and use the exact relevant date.
Bottom line
A federal emergency power order affecting the PJM electricity region has triggered searches about a “13-state power-grid emergency.” The Department of Energy’s 202(c) order, issued October 12 and effective October 13–16, gives PJM additional authority to dispatch specified generation resources to support reliability. Crucially, the presence of an emergency order does not establish that all homes across 13 states have lost power, nor does it imply every jurisdiction faces the same immediate conditions. Readers need to understand the grid operator, the legal authority, the dates and what reliable local outage information actually shows. The best next step is to identify which of the monitored developments could change this answer and use a current, authenticated record before acting. Clear distinctions between confirmed facts, estimates, proposals and contested claims are more valuable than dramatic certainty.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025