
Analysis
The Best Economics Books to Read This Summer: Analysts’ Top Picks

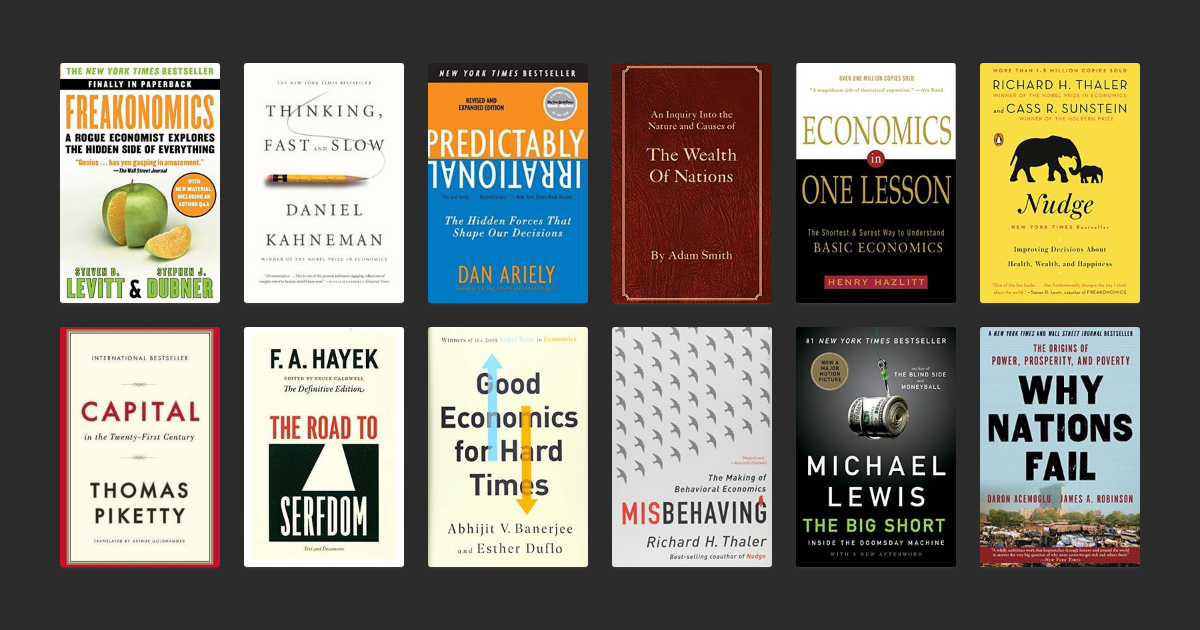
The global economy is operating in a state of suspended animation. Central banks have aggressively paused their tightening cycles, yet the anticipated soft landing remains stubbornly out of reach for much of the developed world. To parse this volatility, professionals need more than daily market briefings; they require deep structural clarity. Selecting the best economics books to read this summer requires filtering out pop-business fluff in favour of rigorous, systemic analysis. This year’s definitive titles tackle the end of the post-Cold War peace dividend, the productivity paradox of artificial intelligence, and the messy, expensive unwinding of globalized supply chains.
We are transitioning from an era of capital abundance to one of persistent, structural friction. The International Monetary Fund’s latest projections cap global growth at a sluggish 3.1% for the medium term, representing the weakest macroeconomic forecast in decades. Simultaneously, global public debt is on track to approach 93% of global GDP by the end of 2026, leaving policymakers with razor-thin margins for error.
Investors and institutional analysts are scrambling to update their mental models. The old correlations between sovereign bond yields and equity valuations have fundamentally broken down. The texts dominating the conversation this season do not offer quick, palliative fixes. Instead, they provide vital historical context for our current stagnation and mathematical frameworks for pricing in geopolitical risk. Understanding these texts is essential for anyone allocating capital, managing institutional risk, or drafting public policy in the latter half of the decade.
The defining economic hangover of our time is the return of structurally higher interest rates. For the past two decades, the Federal Reserve and the Bank of England operated under the core assumption that deflation was the primary enemy of state growth. The brutal inflation shock of the early 2020s shattered that consensus entirely.
To understand the permanent shift in central banking, the standout texts this season argue that the era of zero-interest-rate policy (ZIRP) was an historical aberration, not a baseline. The Organisation for Economic Co-operation and Development (OECD) notes that core inflation across G7 nations remained sticky at 3.8% well into late 2025, consistently defying aggressive rate hikes. This persistent stickiness forces a total re-evaluation of sovereign debt sustainability.
Authors in this space point to a grim reality: governments must now roll over their massive pandemic-era debt at significantly higher yields. In the UK alone, the Office for National Statistics (ONS) reported that debt interest payments hit £111 billion last year. This consumes tax revenue that would otherwise fund domestic growth initiatives or infrastructure projects.
This summer’s essential reading strictly dissects these fiscal constraints. The best analysts trace the direct line from monetary tightening to corporate defaults. They argue that zombie companies, kept alive artificially by a decade of cheap credit, face an imminent reckoning. Corporate bankruptcies in the US surged by 18% year-over-year, according to deeply researched S&P Global data. The books highlighting this trend offer a sobering look at capital reallocation, suggesting that this pain is a necessary feature of returning to sound money principles.
Still, the analysis goes far beyond domestic pain in the US and Europe. It extends to emerging markets, where a historically strong US dollar exports inflation across borders. The structural trap set by a hawkish Fed leaves developing economies with an impossible choice: defend their currencies and kill domestic growth, or let them slide and import hyperinflation. When Jerome Powell testified before the Senate in early 2026, he explicitly abandoned the notion of a quick return to cheap money, a pivot these books examine in forensic detail.
Furthermore, commercial real estate (CRE) presents the most immediate systemic vulnerability explored in these pages. The Federal Reserve’s Financial Stability Report highlights that over $1.2 trillion in commercial mortgages mature before 2027. Refinancing these depreciated assets at current rates will crystallize massive losses for regional banks. The books dissecting this dynamic do not just forecast a localized crash; they trace the contagion vectors from empty office towers in major metropolitan centres directly into global pension fund portfolios.
Beyond monetary policy, the structural rewiring of the labour market via Artificial Intelligence (AI) dominates the top macroeconomics books 2026 has to offer. The initial euphoria surrounding generative models has cooled significantly in financial capitals, replaced by hard, empirical questions about productivity metrics, capital expenditure, and wage suppression.
The best economics books to read this summer include authoritative texts on inflation dynamics, the macroeconomic impact of artificial intelligence, and the geoeconomic fragmentation of global trade. Top titles provide data-driven frameworks for investors and policymakers to understand the structural end of the zero-interest-rate era.
Economists are currently obsessed with the gap between technological capability and measurable economic output. MIT economist Daron Acemoglu‘s latest collaborative research sets the intellectual foundation for this summer’s most compelling arguments. The core thesis posits that while AI can automate specific cognitive tasks, its aggregate impact on Total Factor Productivity (TFP) remains statistically invisible.
Investment banks initially projected a global GDP boost of 7% over a decade due to AI integration. Yet, the texts emerging this season take a sharply critical view of such optimistic, linear modelling. They point out that capital expenditure on server infrastructure and energy grid expansion is vastly outpacing the actual revenue generated by these software tools.
The picture is more complicated than simple job displacement. The authors argue we are witnessing a massive “task reallocation” that hollows out middle-management while simultaneously creating physical bottlenecks in energy supply chains. Labour economist David Autor provides a necessary counterweight to the prevailing pessimism in his recent working papers, themes echoed heavily in this summer’s curated titles. He suggests AI could theoretically rebuild the middle class by democratising technical expertise, allowing lower-skilled workers to perform higher-value medical or coding tasks.
Yet, the consensus among the top titles remains heavily sceptical. They look at the empirical data showing tech companies aggressively reducing headcount while simultaneously reporting record profits. The productivity gains are currently being captured entirely by capital owners, not labour forces.
This creates a highly bifurcated economy. Companies that successfully integrate proprietary data with localized language models pull away from competitors, creating monopolistic dynamics that antitrust regulators are entirely unequipped to handle. The reading list this summer unpacks how the European Union’s AI Act might actually cement the dominance of incumbent tech giants by raising compliance costs to fatal levels for open-source start-ups. We must look closely at the wage data; real wages for knowledge workers plateaued in the first quarter of 2026, a trend these authors attribute directly to the commoditization of routine cognitive labour.
The third major theme dominating this summer’s reading lists is the aggressive, unapologetic return of state-directed industrial policy. The Washington Consensus, which championed free trade and deregulation for three decades, is officially dead. In its place is a scrambled, multi-trillion-dollar rush for domestic resource security.
Governments are no longer optimizing for cost efficiency; they are optimizing for systemic resilience. The World Bank’s latest Global Economic Prospects report highlights a staggering 20% drop in foreign direct investment (FDI) flowing between geopolitically unaligned nations. This fragmentation has massive downstream consequences for multinational corporations across three distinct vectors:
- Capital Expenditure: A forced, highly inefficient duplication of manufacturing infrastructure across rival trading blocs.
- Compliance Drag: Escalating legal and logistical costs required to navigate divergent export controls and international sanctions.
- Resource Hoarding: State-backed stockpiling of critical minerals, artificially restricting market supply and driving up baseline commodity prices.
Books tackling this subject focus heavily on the semiconductor industry and the chaotic transition to green energy. They detail how the US CHIPS and Science Act and the Inflation Reduction Act (IRA) have triggered a global subsidy arms race. Authors argue this capital misallocation will inevitably suppress global growth over the next decade. When Europe, the United States, and China simultaneously subsidise their own redundant supply chains, the mathematical result is structural overcapacity and severe trade friction.
Germany’s ongoing economic malaise serves as the primary case study in these chapters. The sudden loss of cheap Russian pipeline energy, combined with slowing Chinese demand for heavy industrial exports, has severely broken the European engine of growth. The European Central Bank (ECB) faces the unenviable task of managing localized stagflation within a fractured political union.
That said, these analysts also identify the unexpected winners of this global fragmentation. ‘Connector economies’ like Mexico, Vietnam, and India are rapidly capturing the manufacturing overflow as Western companies execute “China Plus One” derisking strategies. A standout statistic from a heavily cited text notes that Mexico officially surpassed China as the largest exporter to the US in late 2025, moving over $475 billion in physical goods. Investors reading these books will find actionable, data-rich blueprints for identifying which emerging markets stand to gain from the ongoing superpower decoupling. Traditional metrics like the Consumer Price Index (CPI) are suddenly less predictive of sovereign market movements than the shipping tonnage safely passing through the Strait of Malacca.
Competing Perspectives: The Degrowth Dissent
No comprehensive reading list is complete without seriously engaging with its harshest critics. While the mainstream macroeconomic texts focus on restoring sluggish growth and managing sticky inflation, a highly vocal minority of economists argues that the pursuit of infinite GDP expansion is biologically and ecologically bankrupt.
The ‘degrowth’ movement, once relegated to the fringe of academic sociology, has secured serious, mainstream publishing deals this summer. These authors provide a mathematical steel-man against the popular green-growth consensus. Their core argument rests on the absolute decoupling fallacy. The European Environment Agency (EEA) published data showing that while domestic emissions have fallen in developed nations, the total material footprint per capita continues to rise when factoring in imported goods.
Prominent ecological economist Herman Daly laid the theoretical groundwork decades ago, but this year’s authors apply his strict frameworks to the immediate, localized climate crises of 2026. They argue that technological substitution—replacing combustion engines with heavy lithium-ion batteries—merely shifts the ecological bottleneck from the atmosphere to the Earth’s crust.
Japanese philosopher Kohei Saito and his surprising commercial success regarding degrowth frameworks serves as a prime example. His thesis, heavily discussed in serious economic circles, argues that planetary boundaries cannot mathematically support infinite capital accumulation. Mainstream economists are forced to engage with this, not to adopt a radical framework, but to accurately account for hard ecological limits. If physical inputs like arable land, fresh water, and copper become absolute constraints, the standard Solow-Swan economic growth models break down entirely.
Rather than dismissing these texts as utopian fantasy, serious financial analysts are reading them to understand future regulatory risks. If global carbon pricing and aggressive resource taxes escalate, the degrowth models will suddenly look less like radical activism and more like predictive corporate risk modelling. Engaging with this dissenting view signals a refusal to be blindsided by rapidly shifting political realities. Acknowledging that the transition to a low-carbon economy may inherently suppress aggregate demand provides a much sharper edge to any long-term investment thesis than relying on outdated Keynesian multipliers.
The global economy in the latter half of the 2020s refuses to cleanly fit into twentieth-century analytical models. The sheer utility of the best economics books to read this summer is not that they offer perfectly accurate forecasts for the next quarter. Rather, they provide desperately needed, updated heuristics for an era defined by permanently higher capital costs, severe demographic inversions, and localized supply chain warfare.
Relying on out-of-date mental models is the fastest route to capital destruction. The prevailing economic narratives of the past decade—that technological monopolies will naturally democratise wealth, or that central banks can simply print their way out of a sovereign debt crisis—have been empirically and painfully disproven.
Professionals who dedicate time to these rigorous, heavily researched texts will possess a distinct analytical advantage. They will look past the daily, algorithmic noise of equities markets to see the shifting tectonic plates of the real, physical economy. Absolute clarity, not blind market optimism, is the ultimate competitive advantage for the remainder of the decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Despite decades of bans and strict handling mandates, asbestos remains a silent killer across legacy manufacturing plants, shipyards, and modern green-energy infrastructure retrofits. In 2026, regulatory changes by the EPA and tightened occupational health standards have triggered a fresh wave of mesothelioma litigation. Manufacturers attempting to fast-track industrial transitions are encountering catastrophic oversight, exposing workers to legacy toxins and opening corporate parent companies to unprecedented liability.
Navigating a mesothelioma claim in 2026 requires understanding how modern industrial supply chains intersect with historical exposure. Trusts established decades ago are being audited under stricter transparency laws, altering payout ratios and accelerating fast-track settlements for terminally ill plaintiffs.
Modern Industrial Exposure Hotspots
Green Retrofitting and Renewable Energy Infrastructure
A primary source of 2026 asbestos exposure occurs during the decommissioning and retrofitting of older industrial facilities for renewable energy production. Workers insulating electrical grids, modernizing HVAC systems, or upgrading manufacturing floors frequently disturb encapsulated asbestos materials that were improperly documented or ignored during facility audits.
Automotive and Aerospace Supply Chains
With advanced manufacturing booming, workers handling specialized friction materials, gaskets, and heat shields face ongoing risks. Supply chain tracing has become more sophisticated, allowing legal teams to pinpoint exact corporate entities responsible for raw material distribution across multinational borders.
| Industry Sector | Primary Exposure Risk | Legal Venue / Trust | Avg. Claim Value Range |
| Green Energy Retrofit | Disturbed insulation, pipe lagging | Federal Tort / Manufacturer Trust | $1.2M – $3.5M |
| Shipbuilding & Marine | Boiler insulation, structural seals | Asbestos Bankruptcy Trusts | $800K – $2.4M |
| Automotive Manufacturing | Brake components, high-heat gaskets | Third-Party Product Liability | $600K – $1.8M |
Securing Maximum Compensation: Steps for Plaintiffs
Time is of the essence in mesothelioma cases. Plaintiffs and their families must act decisively to secure financial recovery before statutes of limitations expire.
Retain Specialized Counsel: Work exclusively with national mesothelioma law firms possessing deep historical databases of asbestos-containing products.
Audit Employment History: Document every job site, supervisor name, and equipment brand encountered throughout your career.
Expedite Medical Filings: Secure a formal pathological diagnosis quickly to qualify for expedited trust fund distribution and priority trial settings.
“Expert Insight: Modern asbestos litigation is no longer just about historical tracking; it is about holding modern corporations accountable for failing to conduct rigorous environmental safety audits before initiating industrial retrofits.”
By combining meticulous work history reconstruction with aggressive multi-trust filings, victims can secure substantial financial relief to cover specialized immunotherapy and family support.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

INTC Stock Forecast 2026: Can Intel’s Government-Backed Turnaround Hold?

Bitcoin Price Action in Q4 2026: Safe-Haven Asset or High-Risk Tech Play?

The Target Pokémon x Owala Drop: Everything to Know Before It Sells Out

The U.S. Just Confirmed It Has Weapons in Space — Here’s What It Means for Defense Stocks

IRS 2027 Tax Bracket Projections: How to Get Ahead of Bracket Creep

Dow Jones vs. Middle East Tensions: How Wall Street Is Pricing In a 2026 Conflict Nobody Saw Coming

Bank of England’s September 17 Decision: Will UK Interest Rates Finally Move?

Inflation Is Outpacing Wage Growth Again: What It Means for Your Paycheck

10-Year Treasury Yield Tops 5%: What It Means for Mortgages, Stocks, and the Fed

Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies

Emerging Markets Update: The Impact of World Bank Policies on PSX Stability

Costco Oil Shortage 2026: Will Prices Double for All Synthetic Motor Oils?

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Gold’s Wild 2026: From a Record $5,600 Peak to a 24% Crash and Back Toward $4,500

Oil Surges as Strait of Hormuz Traffic Collapses Again

Bank of England Set to Hold Rates Through Year-End, Reuters Poll Shows

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Russia’s Black Sea Oil Exports Fall for a Fifth Straight Week

Global Chip Selloff Deepens: What’s Driving the Aug. 19 Semiconductor Rout

Shein Clothes Quality & Safety in 2026: What Lab Tests Show
-

 Markets & Finance8 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025