
Analysis
Regional Crises Are Dealing a Heavy Blow to Afghanistan’s Fragile Economy

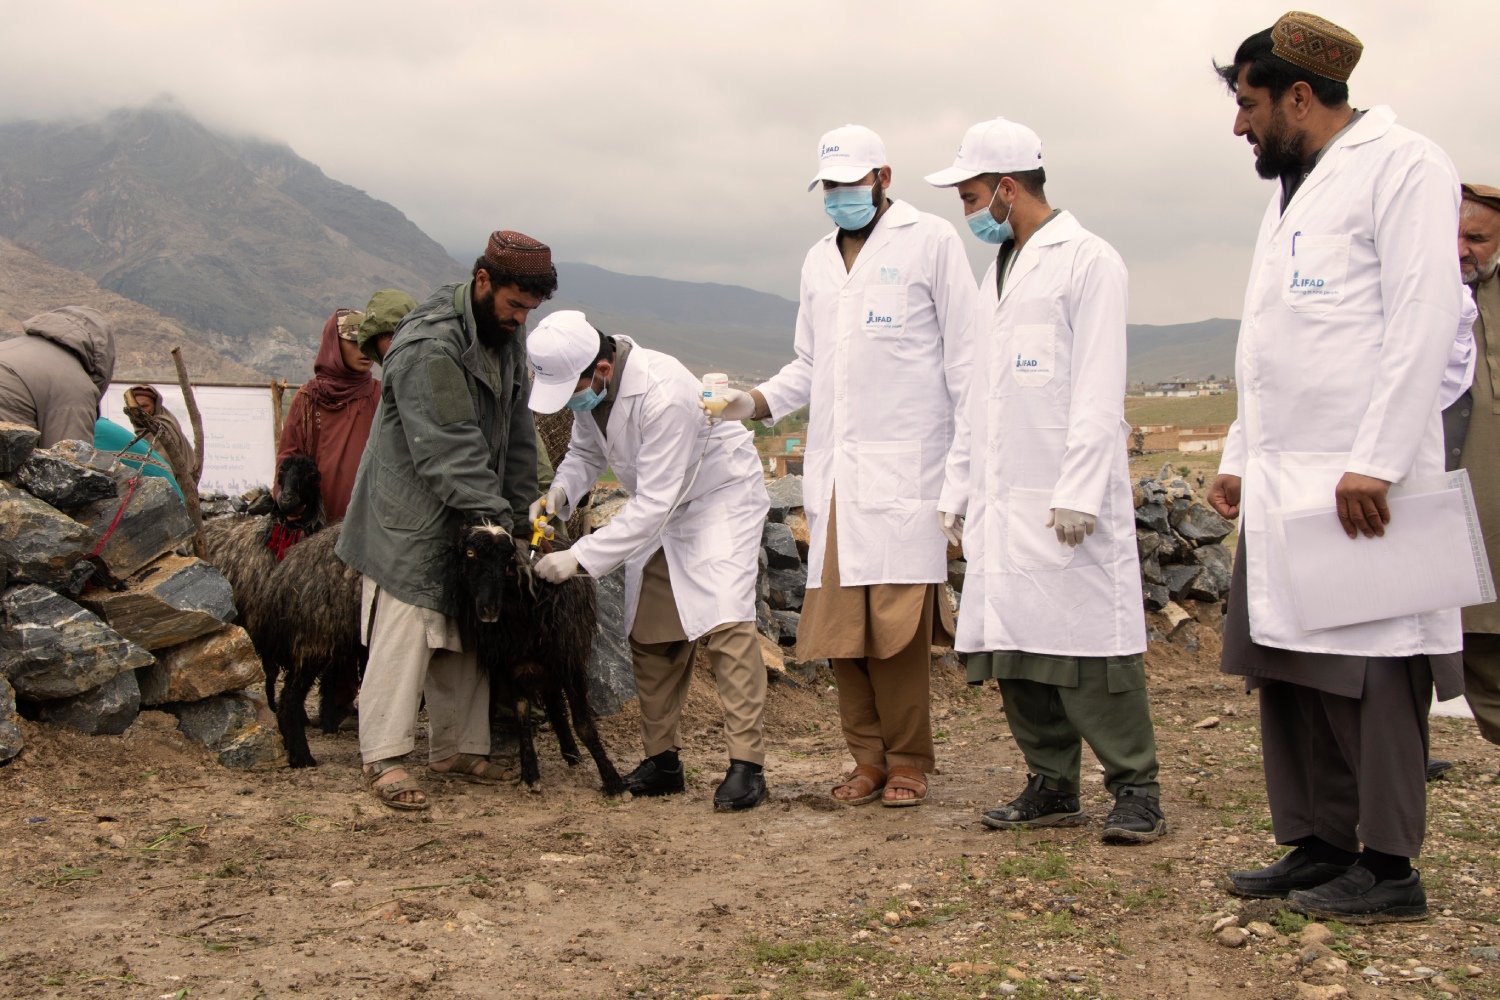
Trade routes in turmoil, mass deportations from Iran and Pakistan, shrinking foreign aid, and financial isolation are compounding Afghanistan’s economic distress — exposing a nation caught between geopolitical tremors and a governance crisis of its own making.
📌 Afghanistan’s fragile economy buckles under regional crises — mass deportations, blocked trade routes, shrinking aid, and financial isolation threaten a nation already on the edge.“
On a dusty stretch of the Torkham border crossing between Pakistan and Afghanistan, thousands of Afghans shuffle back across the frontier each week — some carrying little more than what fits in a single bag. They are the human face of a regional crisis that is quietly dismantling whatever fragile economic scaffolding Afghanistan has managed to erect since the Taliban swept to power in August 2021. The numbers are staggering: between September 2023 and July 2025, an estimated 4 to 4.7 million individuals returned to Afghanistan, expelled or coerced out of Pakistan and Iran in waves that rank among the largest forced return migrations in recent history.1
The macroeconomic optics, at first glance, are deceptively modest. Afghanistan’s GDP grew by an estimated 2.5 percent in 2024, according to the World Bank’s Afghanistan Development Update — a second consecutive year of expansion. The World Bank projects a further 4.3 percent growth in 2025, driven partly by the demand surge from millions of returnees stimulating activity in services and construction. But these headline figures mask a far grimmer reality beneath the surface: with population growth estimated at 8.6 percent in 2025, GDP per capita is projected to fall by 4 percent.1 Afghanistan is, in the starkest statistical sense, growing poorer as a nation even while its aggregate output ticks upward.
Key Data at a Glance
| Indicator | Figure |
|---|---|
| Projected GDP per capita change, 2025 | −4% |
| Returnees from Iran & Pakistan by mid-2025 | 4.7 million |
| Trade deficit (first 7 months FY2025) | $6.5 billion (+22%) |
| UN humanitarian funding gap, 2024 | 94% unmet |
The Migration Shockwave: From Labour Export to Labour Burden
For decades, Afghanistan’s informal economic model relied heavily on the remittance lifeline — millions of Afghans living and working in Iran and Pakistan sending money home, effectively subsidising household consumption across vast swathes of the country. That model has been violently disrupted. Iran, grappling with its own currency collapse, crippling Western sanctions, and the economic spillovers from regional conflict in Gaza and Lebanon, has steadily expelled Afghan workers. Pakistan, facing a severe balance-of-payments crisis and domestic political instability, launched its own expulsion campaigns. Approximately 5,000 migrants were returning to Afghanistan every week at the height of the crisis, according to the International Committee of the Red Cross.2
The returnees are not arriving as a homogeneous economic boon. The World Bank notes their socio-economic profile is “highly varied” — while some bring skills and modest savings, the majority arrive without formal education, resources, or employment prospects. Local labour markets, already unable to absorb the existing workforce, are buckling under additional pressure, particularly in border districts and informal urban settlements around Kabul, Jalalabad, and Kandahar. Nearly one in four young Afghans is unemployed, and that figure is almost certainly an undercount in an economy where data collection remains severely compromised.
“Afghanistan is growing poorer as a nation even while its aggregate output ticks upward — a statistical paradox that captures the essence of a crisis where growth and misery are advancing in lockstep.”
— World Bank Afghanistan Development Update, December 2025
Trade Routes Under Siege: The Cost of Geopolitical Turbulence
Afghanistan’s Commercial Arteries at Risk
Afghanistan occupies one of the most strategically critical positions in Eurasia — a potential land bridge connecting Central Asia to South Asia, and a historic crossroads of trade for millennia. Yet that geography has become more liability than asset. The country’s trade deficit widened by 22 percent in the first seven months of fiscal year 2025, reaching $6.5 billion — equivalent to roughly 30 percent of annual GDP — compared with $5.3 billion in the same period the prior year, according to the World Bank’s Afghanistan Economic Monitor.3
The drivers are structural and regional in equal measure. Sanctions-related friction, elevated transport and logistics costs, and the diplomatic isolation of the Taliban government have strangled export potential. Afghan merchants struggle to access international banking, cannot process letters of credit through mainstream financial institutions, and face persistent border closures or levies from neighbouring states pursuing their own domestic agendas. Pakistan’s closure of border crossings for days at a time — whether for political signalling or security operations — disrupts the fragile flow of Afghan goods heading toward South Asian markets. Iran’s own financial disorder complicates the western trade corridor. And to the north, the Central Asian republics, while diplomatically warming to Kabul, have yet to translate rail and road investment pledges into operational trade infrastructure.
The much-touted Trans-Afghanistan Railway, a $4.8 billion project designed to link Uzbekistan to Pakistan through Afghan territory, remains largely aspirational despite reaffirmed commitments in 2024. Similarly, the CASA-1000 power project — a $1.2 billion regional energy transmission initiative — has stalled, costing Afghanistan an estimated $1 billion in potential foregone economic activity.4 The gap between infrastructure ambition and economic reality is one of the most telling indictments of Afghanistan’s geopolitical predicament.
Aid Dependency in Free Fall: The Donor Fatigue Trap
Perhaps no single factor is more quietly devastating to Afghanistan’s economic outlook than the precipitous decline in international humanitarian and development assistance. The United Nations sought $3.06 billion in humanitarian funding for Afghanistan in 2024 — and received just $290 million, or roughly 6 percent of the ask, according to data cited by South Asian Voices.4 For a country in which more than half the population relies on humanitarian assistance to meet basic needs, that funding gap is not a budget line — it is a survival deficit.
The structural underpinning of the crisis is Afghan governance itself. The Taliban’s systematic exclusion of women from the formal economy — banning girls from secondary and tertiary education, prohibiting female employment across entire sectors — has functionally amputated one half of the country’s productive workforce. The World Bank and major Western donors have made clear that normalisation of financial relationships and direct budget support are contingent on measurable improvements in women’s rights. Those improvements have not materialised. The result is a grim fiscal doom loop: governance restrictions repel aid; declining aid shrinks government revenues; shrinking revenues reduce public services; deteriorating services deepen poverty and drive more emigration.
Domestic revenue mobilisation, while improving — tax revenues are projected to reach 17.1 percent of GDP in 2025 — cannot remotely compensate. Afghanistan’s Islamic Emirate has leaned heavily on customs duties and trade-related taxation as its primary fiscal instrument, making the treasury acutely vulnerable to the very trade disruptions that regional instability generates.1
Financial Exclusion and the Banking System’s Quiet Crisis
An Economy Running on Cash and Uncertainty
Behind Afghanistan’s macroeconomic statistics lies a banking sector in a state of near-chronic dysfunction. Non-performing loans have risen, lending activity remains severely constrained, and much of the new liquidity circulating in the economy — partially stimulated by returnee remittances and informal hawala networks — flows entirely outside the formal financial system. The Taliban’s mandated transition to Islamic finance, while ideologically coherent within their governing framework, has created regulatory uncertainty that deters both domestic entrepreneurs and potential foreign investors.
International financial institutions cannot engage directly. Afghan banks cannot connect to the SWIFT system under existing sanctions frameworks. The combination renders Afghanistan, in effective terms, a cash economy operating at the margins of the global financial architecture — unable to attract foreign direct investment, unable to finance long-term infrastructure, unable to build the institutional buffers that might cushion the next regional shock.
“Without improved governance, enabling private sector development, and attracting foreign investment, Afghanistan’s economy risks prolonged stagnation and continued dependence on humanitarian aid.”
— Faris Hadad-Zervos, World Bank Country Director for Afghanistan
The Outlook: Fragile, Not Falling — But for How Long?
Afghanistan’s economy is not in freefall. That distinction matters. The country has demonstrated a degree of resilience — record irrigated wheat harvests despite drought conditions, a stabilising currency, subdued inflation averaging just 2 percent in 2025, and a construction sector buoyed by returnee settlement demand. But these positive signals must be read against their context: the economy is still approximately 26 percent below its 2020 output level, nearly four years after the Taliban takeover triggered a $27 billion cumulative contraction.4 The recovery, such as it is, has restored perhaps 10 percent of those losses.
The regional crises compounding Afghanistan’s distress — Iran’s economic disorder, Pakistan’s political instability, the ripple effects of Middle Eastern conflict on energy prices and migration flows, and the still-nascent Central Asian trade corridors — show no signs of near-term resolution. Donor fatigue is real and appears structural rather than cyclical. Youth unemployment, restricted female participation, and a deepening subsistence crisis in the northeastern and southern provinces point toward a society where economic fragility is not a temporary condition to be managed, but a systemic state of affairs requiring a fundamental rethink of engagement strategies by the international community.
The hardest truth, one that donors, regional powers, and international institutions are slowly being forced to confront, is this: Afghanistan cannot bootstrap its way out of the current trap through trade, remittances, or informal sector growth alone. And the Taliban, for all their professed interest in economic diplomacy — hosting bilateral forums with Kazakhstan and Uzbekistan, pursuing railway agreements, signalling openness to Chinese investment — have yet to demonstrate that they are willing to make the governance choices that could unlock the international financial integration their economy desperately needs.
The mountains of the Hindu Kush have witnessed empires rise and crumble. The question now is whether Afghanistan’s fragile economic recovery can survive the compound weight of regional crises, governance paralysis, and donor disengagement long enough to become something more durable. The early signs are not encouraging.
Sources & Citations
Footnotes
- World Bank. Afghan Economy Expands Amid Persistent Challenges. December 2025. https://www.worldbank.org/en/news/press-release/2025/12/10/afghan-economy-expands-amid-persistent-challenges ↩ ↩2 ↩3
- Afghanistan International. Afghanistan’s Economic Growth Lags Behind Population Increase. April 2025. https://www.afintl.com/en/202504238617 ↩
- World Bank. Afghanistan Economic Monitor. October 2025. https://thedocs.worldbank.org/en/doc/ccd240ee3f0681167e0abc1e315564e8-0310012025/original/Afghanistan-Economic-Monitor-October-2025.pdf ↩
- South Asian Voices. Charting Afghanistan’s Economic Future: Recommendations for Reform. December 2024. https://southasianvoices.org/ec-m-oth-n-charting-afghanistans-economic-future-06-12-2024/ ↩ ↩2 ↩3
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

2026 Real Estate Market News: Are We Heading for a Correction?

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Fidelity Crypto vs. Traditional Brokerages: A Guide for Modern Investors

The 2026 Global Smartphone Market: AI Integration and Competitor Analysis

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

Fidelity Investments Review: Maximizing Returns in a Volatile Stock Market

How Crypto Transformed the Trump Fortune: A $1.4 Billion Financial Breakdown

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Global Supply Chain Vulnerabilities: From Eurasian Trade Corridors to Food Consumer Recalls

Why 5% U.S. Treasury Yields Signal a Global Market Regime Shift.

Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

BRICS+ Cross-Border Payments 2026: Interoperability Explained

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025