
Governance
Beyond the Bailout: 10 Strategic Imperatives to Resolve Pakistan’s Balance of Payments Crisis

Executive Summary: The Structural Surgery Required
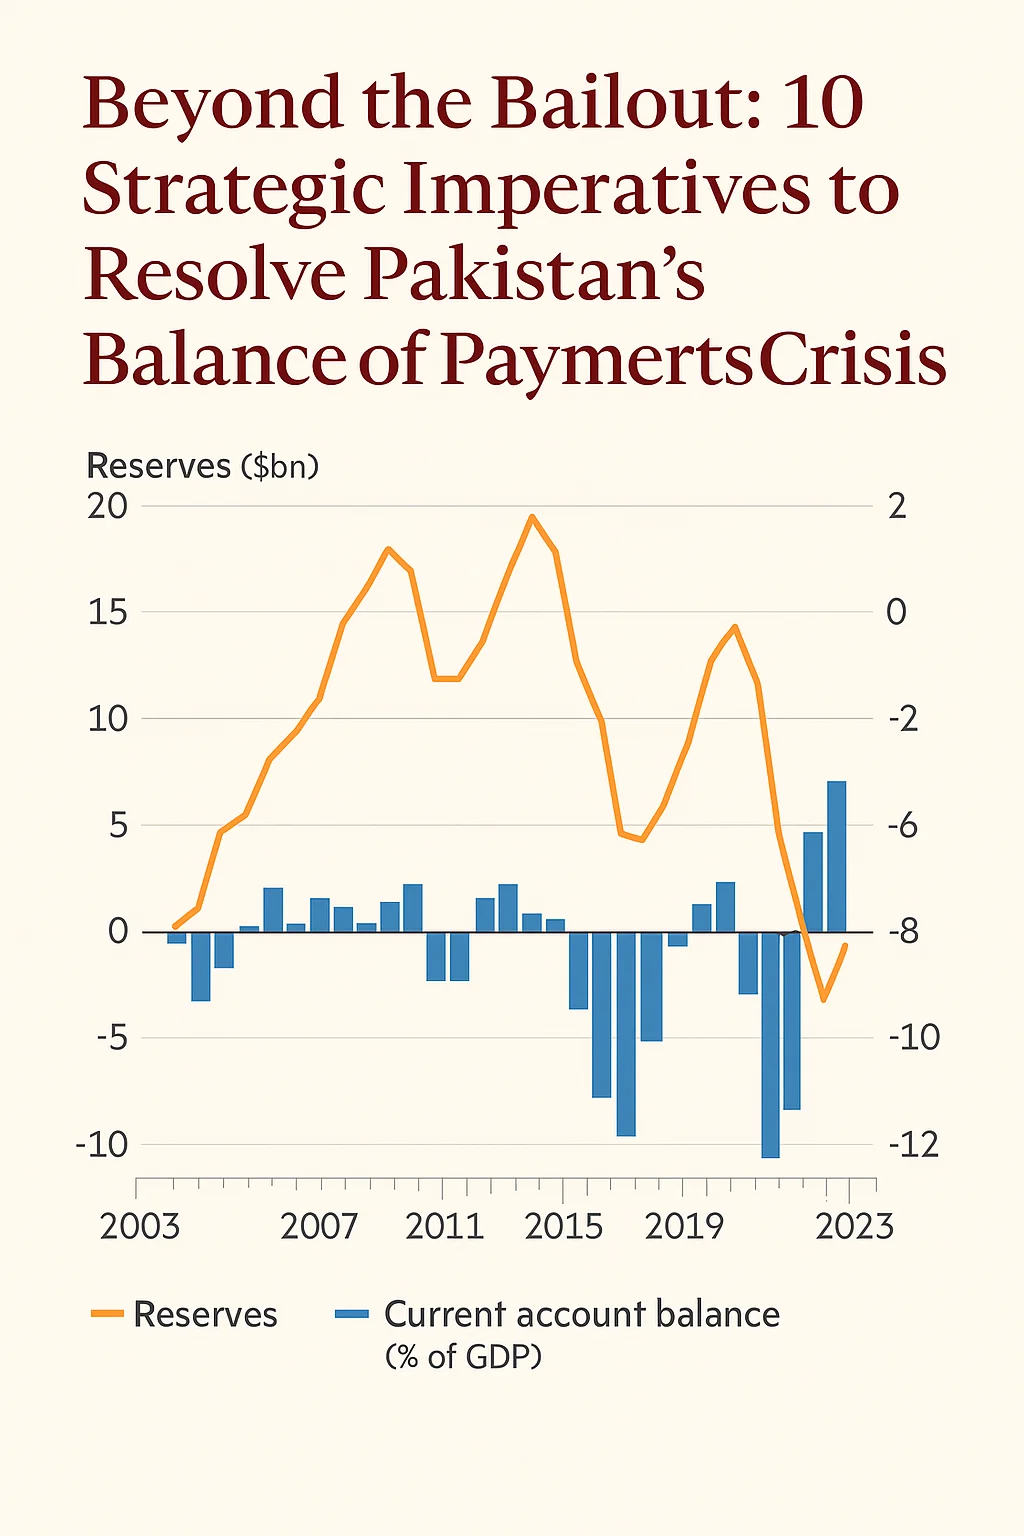
Pakistan’s economic history is defined by the “Stabilization Trap”—a recurring cycle where brief periods of consumption-led growth lead to a blowout in the Current Account Deficit (CAD), followed by emergency devaluations and IMF intervention. As of late 2025, the State Bank of Pakistan (SBP) has managed a precarious stability, with foreign exchange reserves crossing the $14.5 billion threshold and inflation cooling to a multi-decade low of 4.5%. However, the structural fragility remains.
To transition from a debt-dependent economy to a trade-led powerhouse, Pakistan must implement a ten-pronged “structural surgery” that goes beyond mere belt-tightening. This article outlines the roadmap for the Finance Ministry, the SBP, and the Planning Commission to achieve a sustainable Balance of Payments (BoP).
1. Institutionalizing the Market-Determined Exchange Rate
The first line of defense in any BoP crisis is the exchange rate. According to the IMF’s latest review (December 2025), maintaining a market-determined exchange rate is non-negotiable for buffering external shocks.
For the SBP, the objective is not to “defend” a specific number, but to ensure liquidity. A market-aligned Rupee encourages expenditure-switching: it makes imports expensive and exports competitive. Historical data shows that whenever the REER (Real Effective Exchange Rate) is kept artificially low, the CAD explodes.
Policy Directive: The SBP must continue its policy of minimal intervention, allowing the currency to act as an automatic stabilizer for the trade balance.
2. Fiscal Consolidation: The Primary Surplus Mandate
Balance of Payments issues are often “twin deficits”—a fiscal deficit that fuels a current account deficit. The Ministry of Finance has achieved a historic primary surplus of 2.4% of GDP in FY25.
To maintain this, the government must resist the urge for “populist” spending. High fiscal deficits lead to increased domestic demand, which inevitably spills over into higher imports.
- The Target: Sustain a primary surplus above 2% for at least three consecutive fiscal cycles to signal fiscal discipline to global bond markets.
3. Aggressive Export Diversification (Beyond Textiles)
The World Bank’s Pakistan Development Update (October 2025) notes a sobering trend: Pakistan’s exports as a percentage of GDP have shrunk from 16% in the 1990s to roughly 10% today.
Textiles account for nearly 60% of goods exports, making the country vulnerable to global commodity price shifts.
- The Solution: Policy focus must shift toward high-value-added manufacturing (engineering goods, pharmaceuticals) and agriculture-tech (Basmati rice, value-added horticulture). The government should provide “Smart Subsidies” tied strictly to export performance milestones rather than blanket energy subsidies.
4. Scaling the “Digital Frontier”: IT and Services Exports
While goods trade often struggles with energy costs, IT services are Pakistan’s most agile export sector. In FY25, IT exports and remittances have become a primary pillar of BoP stability.
- The Opportunity: With global trade policy uncertainty rising, digital services are less susceptible to physical trade barriers.
- Action: The Planning Commission must fast-track “Special Technology Zones” (STZs) with 5G infrastructure and ease of repatriation for foreign earnings to encourage global tech firms to set up hubs in Karachi and Lahore.
5. Reforming the Energy Mix to Reduce the Import Bill
Energy typically accounts for 25-30% of Pakistan’s total import bill. The reliance on imported RLNG and furnace oil is a structural “leakage” in the BoP.
- Strategic Shift: Accelerate the transition to domestic coal (Thar) and renewables (Solar/Wind).
- The IMF Perspective: The Resilience and Sustainability Facility (RSF) recently approved by the IMF for Pakistan specifically targets this. Every 1% increase in domestic energy share saves roughly $200 million in foreign exchange annually.
6. Formalizing Workers’ Remittances
Remittances reached a record $38 billion in FY25, effectively offsetting a significant portion of the trade deficit. However, a portion of these flows still bypasses official channels via the Hundi/Hawala system.
- Policy Tool: The SBP must continue narrowing the gap between interbank and open-market rates.
- Innovation: Launch “Remittance Bonds” with tax-free incentives for overseas Pakistanis, allowing these flows to be funneled directly into national development projects rather than just household consumption.
7. Strategic Import Substitution: The “Make in Pakistan” Initiative
The government should incentivize the domestic production of intermediate goods—chemicals, steel, and mobile components—that currently drain billions.
Note of Caution: This is not a call for 1970s-style protectionism. Instead, the “National Industrial Policy” should focus on integrating Pakistani SMEs into global value chains, making it cheaper to produce locally than to import.
8. Attracting “Sticky” Capital: FDI over “Hot Money”
The BoP is currently propped up by official debt and short-term portfolio investment. This is high-risk.
- The ADB Roadmap: The Asian Development Bank (ADB) emphasizes private sector-led growth. Pakistan needs Foreign Direct Investment (FDI) in productive sectors like mining and green energy.
- The SIFC Role: The Special Investment Facilitation Council (SIFC) must move beyond MoUs to actual “ground-breaking” projects, ensuring a stable regulatory environment that guarantees profit repatriation.
9. Tight Monetary Policy to Anchor Inflation
The SBP has prudently kept the policy rate at a level where the real interest rate remains positive. High interest rates serve two purposes in a BoP crisis:
- They discourage domestic credit-fueled consumption (imports).
- They make domestic assets attractive to foreign investors, helping the Financial Account.
- Projection: As inflation stays in the 5–7% target range, the SBP can gradually ease rates, but only once the BoP surplus is structurally consolidated.
10. Expanding the Tax Base to Reduce Sovereign Borrowing
A low tax-to-GDP ratio (currently near 9-10%) forces the government to borrow externally to fund its budget, worsening the external debt profile.
- Focus: The FBR must pivot from taxing “easy” sectors (manufacturing/salaried) to the informal retail, real estate, and agriculture sectors.
- The World Bank View: Modernizing tax administration could unlock an additional 3% of GDP in revenue, significantly reducing the need for foreign-funded budgetary support.
Policy Trade-off Matrix: BoP Resolution Strategies
| Measure | Time to Impact | Political Cost | Official Source Alignment |
| Currency Realignment | Immediate | High (Inflationary) | IMF/SBP Mandate |
| Energy Transition | Long-term | Moderate | WB/RSF Support |
| IT Export Focus | Medium-term | Low | Planning Commission |
| Tax Base Expansion | Medium-term | Very High | FBR/IMF Requirement |
| Remittance Incentives | Fast | Low | SBP/Ministry of Finance |
Conclusion: The Path Ahead
The 2025 data suggests that Pakistan has secured a “breathing space,” with the first full-year current account surplus in over a decade ($2.1 billion). However, this surplus is largely driven by compressed demand and record remittances rather than a massive surge in industrial exports.
To ensure that the next growth cycle does not lead to another crash, the Finance Ministry and the State Bank must remain vigilant. The transition from stabilization to sustainable growth requires the political will to tax the untaxed and the economic vision to pivot toward a service-led, export-oriented future.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Governance
Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy
Key Takeaways
- The conference is opposition theatre with real market-adjacent consequences. The Conservatives can’t change a single tax rate this week, but their pitch shapes how investors, developers and businesses read the next election.
- The headline is deregulation. Shadow chancellor Andrew Griffith promised “the most ambitious deregulation project in a generation”, including scrapping the Future Homes Standard, replacing Section 106 and the Community Infrastructure Levy with one charge, and abolishing Natural England and the Environment Agency.
- The tax pledges are specific but uncosted. Griffith said the party would scrap Labour’s levy on high-value homes and its packaging tax, and he committed to tax simplification as a mission for every Treasury minister.
- The backdrop is unforgiving. The UK 10-year gilt yield was about 5.4% at the end of September and the 30-year briefly approached 6%, according to market data, with the Budget due on October 28.
- Credibility is the currency. After 2022, any unfunded tax promise is judged first by bond markets and only second by voters.
Political conferences have a strange job. They are partly pep rally, partly job interview and partly policy laboratory. For the Conservative Party gathering in Birmingham this week, the interview is with two audiences at once: voters who rejected the party in 2024, and bond investors who still remember how the 2022 mini-budget ended.
That second audience is the one that moves prices. So what did the Conservatives actually announce, what might it do to the economy if it ever became law, and what should businesses, homeowners and investors watch for between now and the Budget?
Here is the practical read, with the caveat that everything below remains a proposal from the opposition benches.
What Happened in Birmingham
Kemi Badenoch opened the conference on Sunday, October 4, by publishing an almost 100-page document called The Right Way. In it she warned that living standards have stalled and that regulation has accumulated faster than anyone can remove it, per Press Association reporting. The document also acknowledges failures in earlier Conservative approaches to net zero, immigration and the way Brexit was delivered, as RTÉ reported.
On Monday, October 5, Griffith followed with the economic detail. According to the text of his speech, he framed the country as having a debt problem, a tax problem and a growth problem, and promised to scrap the Family Farm and Family Business inheritance tax, Labour’s packaging tax and its levy on high-value homes.
The Proposals at a Glance
| Proposal | Who it affects | Likely economic channel | Biggest open question |
|---|---|---|---|
| Scrap the Future Homes Standard | Housebuilders, buyers, energy bills | Cheaper construction, higher running costs | Does lower build cost reach buyers? |
| Replace Section 106 and CIL with a single charge | Developers, local councils | Faster approvals, simpler levies | Who funds local infrastructure? |
| Abolish stamp duty (existing policy) | Home movers, property market | More transactions, upward price pressure | Cost to the Exchequer |
| Abolish Natural England and the Environment Agency | Farmers, builders, regulators | Fewer permitting delays | Environmental enforcement capacity |
| Scrap extended producer responsibility for packaging | Manufacturers, retailers | A claimed £1.5 billion cost relief | Who pays for waste collection? |
| Scrap the high-value homes levy | Owners of expensive property | Tax relief for a narrow group | Revenue replacement |
| Back a third Heathrow runway | Aviation, logistics, construction | Long-run capacity and investment | Planning, cost and climate |
| Review Making Tax Digital and IR35 | Small firms, freelancers | Lower compliance burden | Details are still missing |
The Housing Trade-Off Nobody Mentions on Stage
The most concrete number in the package comes from a 2023 Birmingham City Council document the party’s researchers pointed to. It found that heat pumps, better efficiency and solar panels could add £30,789 to the cost of building a detached home. The same document estimated those technologies could cut £2,715 a year from energy bills, effectively paying for themselves in roughly 11 years.
Read that carefully. Scrapping the standard can lower the sticker price of a new home, but it may raise the lifetime cost of living in it. Whether buyers come out ahead depends on mortgage rates, energy prices and how long they stay put.
That is the pattern across the package. Almost every proposal moves a cost from one column to another, rather than deleting it.
The Market Backdrop: Why Bond Investors Are Watching
Here is the context that makes this more than a debate about red tape.
- The UK 10-year gilt yield rose to about 5.39% on October 5, according to Trading Economics, after a global bond sell-off pushed it to the highest levels since 2007.
- The 30-year yield touched roughly 6%, the first time since 1998.
- The Bank of England held Bank Rate at 3.75% in September, as noted by IFA Magazine, while markets price some tightening ahead.
- Chancellor John Healey, appointed by Prime Minister Andy Burnham on July 20, has said fiscal discipline will anchor the October 28 Budget.
A rule of thumb quoted in market commentary is that every quarter-point rise in gilt yields can erase billions of pounds of the Chancellor’s headroom. Higher yields make every tax-cutting promise harder to fund.
The Ghost in the Room: 2022
You cannot discuss Tory tax cuts without mentioning the mini-budget. In 2022 the government announced what Fortune described as the biggest set of unfunded tax cuts in half a century, and gilt markets reacted violently.
Griffith is plainly aware of the comparison. He framed himself as a chancellor who wants to cut taxes only when the country can afford it, and his package leans on deregulation and simplification rather than headline rate cuts. Voters and investors will test whether the arithmetic really works.
What Rivals Said
The reactions map the political terrain.
- Labour’s chair, Bridget Phillipson, said the Conservatives wanted to take the country back to a politics that let people down, and pointed to 14 years of government.
- The Liberal Democrats’ Daisy Cooper called the pledges “fantasy-land” financial promises.
- Reform UK’s Robert Jenrick said the Tories were copying his party’s policies, and contrasted them with Reform’s pledge to raise the income-tax personal allowance from £12,570 to £15,000.
The crowded right flank matters. A party that looks too cautious loses voters to Reform, and a party that looks reckless loses the bond market.
What This Means for Businesses, Homeowners and Investors
Nothing here changes your tax bill today. But the direction of travel is worth tracking.
If you run a business
Watch the Budget for signals on compliance costs. Proposals to review Making Tax Digital and IR35 and to scrap the packaging levy would matter, but only if they survive contact with Treasury costings.
If you own or plan to buy property
The stamp duty and new-build changes, if enacted, would affect transaction volumes and construction costs. Mortgage pricing, however, is driven by gilt yields, so the bond market will shape your costs more than any conference speech.
If you invest in UK assets
Treat the conference as a read on political risk. The relevant questions are how credible the fiscal framework looks, whether pledges are costed, and how the gilt market reacts on and after Budget day. This isn’t investment advice.
A Three-Question Test for Any Opposition Economic Plan
Conference season produces dozens of announcements, and most won’t survive contact with a Treasury spreadsheet. Here’s a quick filter you can apply to this package, or to any other.
1. Is it costed?
A pledge with a price tag can be argued with. A pledge without one can only be believed or doubted. With gilt yields already high, the market’s default setting is doubt. Watch whether the party publishes figures, and whether independent forecasters accept them.
2. Who ends up paying?
Abolishing a levy rarely abolishes the cost it was funding. Replacing Section 106 and CIL with a single charge, for example, still has to pay for roads, schools and drainage somewhere. The same goes for packaging waste, where scrapping the producer-responsibility scheme would lift a claimed £1.5 billion burden from businesses but leave the question of who funds collection and recycling.
3. Can it be delivered quickly?
Deregulation sounds fast and often isn’t. Abolishing two regulators and folding their work into a government department means legislation, transition and staff decisions. The party says it will set out plans “line by line,” which is the right instinct, because detail is what turns a conference slogan into a credible first-hundred-days timetable.
Apply the test and the package splits into two groups. Simplification and review proposals, such as Making Tax Digital and IR35, are cheap to promise and quick to reform. Structural changes to housing standards and environmental regulators carry larger consequences and bigger uncertainty. Markets will price the second group more cautiously, and rightly so.
Asked & Answered
Did the Conservatives announce any tax cuts at the 2026 conference?
They announced pledges to scrap several taxes and levies, including Labour’s high-value homes levy and its packaging tax, and confirmed existing policies such as abolishing stamp duty. None can take effect unless the party wins power.
What is the Conservatives’ deregulation plan?
Shadow chancellor Andrew Griffith called it the most ambitious in a generation. It includes scrapping the Future Homes Standard, replacing Section 106 and CIL with a single charge, abolishing Natural England and the Environment Agency, and removing packaging responsibility rules.
Would these policies lower house prices?
The party argues they would reduce building costs and boost supply. Economists would want to see how much of the saving reaches buyers, and how stamp duty abolition affects demand. The outcome is uncertain.
How do gilt yields affect the Conservatives’ plans?
Higher yields raise the government’s borrowing costs and shrink fiscal headroom, which makes unfunded tax cuts harder to defend. That is why bond-market credibility is central to the Conservative pitch.
When is the next major economic event for the UK?
The Autumn Budget is scheduled for October 28, 2026, and the Bank of England’s next decisions will also shape borrowing costs.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”
Core Premise & Scope
The Economist correctly diagnoses the structural breakdown of 20th-century tax systems across advanced economies. As sovereign debt loads surge, long-term bond yields remain elevated, demographic aging inflates entitlements, and defense and climate commitments expand, standard fiscal architectures are failing. The article argues that current systems rely too heavily on distortive income and labor taxes while ignoring immobile wealth, land, and environmental negative externalities.
Critical Analytical Gaps
While The Economist identifies key symptoms, its analysis exhibits four primary operational gaps:
- Failure to Address the AI Labor Tax Erosion: High-income nations derive over 40–60% of total tax revenues from Personal Income Tax (PIT) and Social Security Contributions (SSCs). As artificial intelligence and autonomous workflows displace high-wage cognitive labor, standard income tax bases will erode. The Economist treats labor taxation as static rather than declining.
- Abstract Land & Wealth Taxation Without Transition Economics: Advocating for Land Value Taxes (LVT) and property tax overhauls is theoretically sound but politically non-viable without explicit transitional mechanisms (such as tax credits against capital gains or phased revenue-neutral shifts).
- Over-reliance on OECD Consensus Enforcement: The piece assumes smooth global coordination via the OECD Inclusive Framework. In reality, jurisdictional profit-shifting and implementation friction between market nations and headquarters hubs create major enforcement leaks.
- Omission of Cash-Flow Expenditure Architectures: The analysis fails to evaluate Destination-Based Cash-Flow Taxation (DBCFT), which removes incentives for corporate inversion while exempting marginal investment from capital distortion.
Designing the Optimal Tax System for the 21st Century
Tax codes across the developed world are relics of a 1950s industrial economy. Built on the assumption of immobile domestic corporations, fixed physical factories, and stable wage labor, 20th-century tax models create massive deadweight losses, disincentivize capital formation, and fuel wealth inequality.
A modern tax architecture must maximize economic efficiency and neutrality while maintaining progressive distribution and fiscal solvency. Achieving this requires shifting the tax base away from productive inputs (labor and investment) toward unearned economic rents, immobile assets, and negative externalities.
       TRADITIONAL TAX BASE                   21ST-CENTURY TAX ARCHITECTURE
┌─────────────────────────────────┐       ┌─────────────────────────────────┐
│ • High Marginal Income Taxes   │       │ • Land Value Taxation (LVT)     │
│ • Corporate Income Tax (CIT)   │  ───► │ • Progressive Expenditure Tax   │
│ • Payroll & SSC Distortions    │       │ • Pigouvian Carbon Pricing      │
│ • Capital Gains Penalties       │       │ • Destination Cash-Flow Model   │
└─────────────────────────────────┘       └─────────────────────────────────┘
Structural Failures of Current Fiscal Architectures
Modern sovereign states face a structural triad of fiscal pressures:
- Demographic Entitlement Creep: Aging populations reduce the working-age tax base while accelerating expenditures on public pensions and healthcare.
- Labor Income Erosion: Technological displacement and the growth of independent digital work dismantle traditional payroll tax collection mechanisms.
- Capital Mobility & Base Erosion: Intangible assets (IP, algorithms, digital platforms) allow multinational entities to shift taxable profits across borders, undermining standard corporate income taxes.
According to data from the Urban-Brookings Tax Policy Center, high marginal tax rates on capital and labor depress long-run economic growth by creating deadweight loss wedges between pre-tax returns and post-tax rewards.
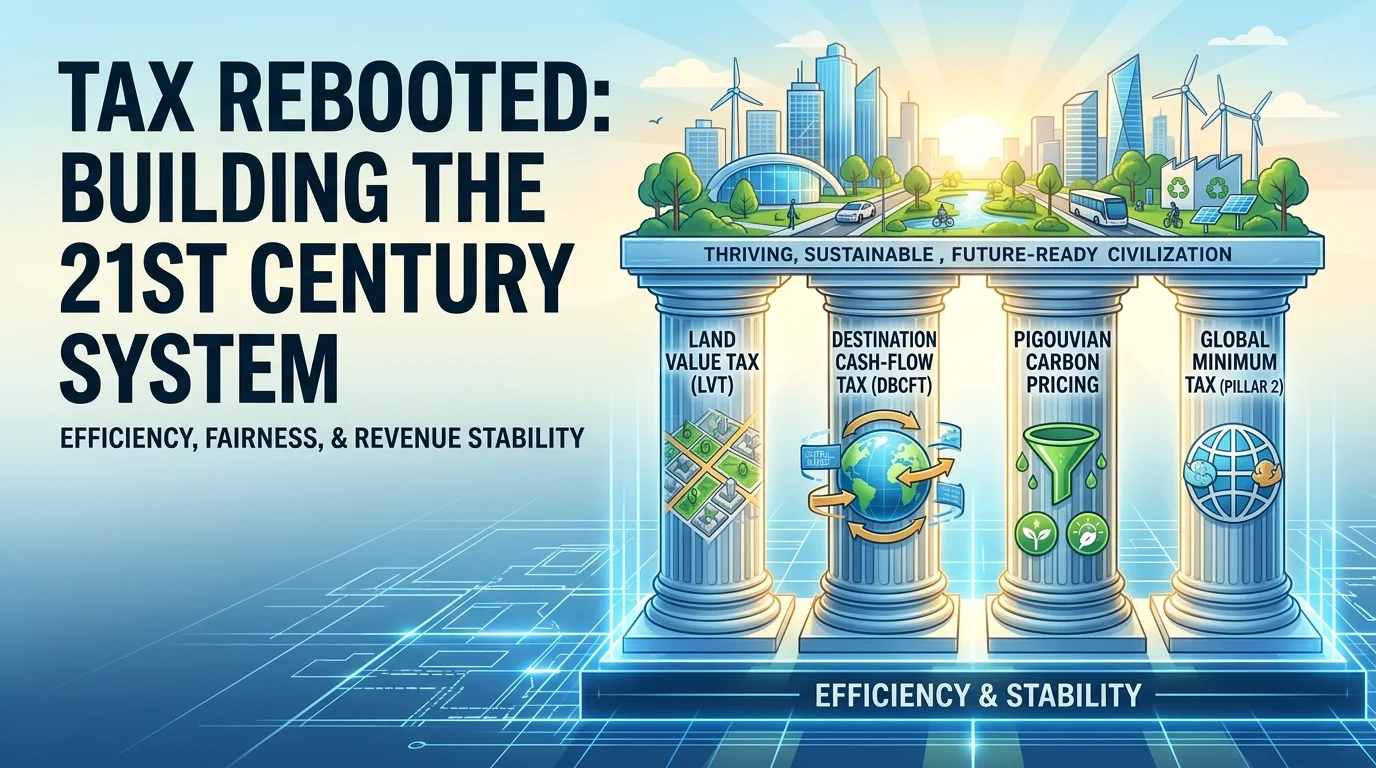
The Four Pillars of the Modern Tax System
                  ┌─────────────────────────────────────────┐
                  │    21st Century Tax Architecture        │
                  └────────────────────┬────────────────────┘
                                       │
        ┌──────────────────┬───────────┴───────────┬──────────────────┐
        ▼                  ▼                       ▼                  ▼
┌───────────────┐  ┌───────────────┐       ┌───────────────┐  ┌───────────────┐
│  Land Value   │  │  Destination  │       │   Pigouvian   │  │  Global Min   │
│ Tax (LVT)     │  │  Cash-Flow    │       │ Carbon Pricing│  │  Pillar 1/2   │
└───────────────┘  └───────────────┘       └───────────────┘  └───────────────┘
1. Land Value Taxation (LVT)
Land is inelastic in supply. Taxing the unimproved value of land creates zero economic deadweight loss because land cannot relocate or shrink in response to taxation.
- Abolish Standard Property Taxes on Improvements: Traditional property taxes penalize building construction and urban development. Taxing only the underlying land value incentivizes efficient land use and infill development.
- Recapture Unearned Location Value: Urban land values appreciate primarily due to public infrastructure (transit, utilities, public safety) and community growth. An LVT captures these economic rents for public revenue without taxing private capital improvements.
2. Progressive Destination-Based Consumption Tax
Replacing corporate income taxes and high personal income brackets with a progressive cash-flow consumption tax removes the double-taxation penalty on savings and investment.
- Destination-Based Cash-Flow Tax (DBCFT): Tax is levied where goods or services are consumed, rendering corporate tax avoidance via offshore profit-shifting obsolete.
- Full Expensing of Capital Investments: Businesses immediately deduct all capital expenditures, removing investment distortions and accelerating productivity growth.
- Individual Progressive Consumption Tax: Individuals report total income minus net savings. The remaining spending is taxed at progressive rates, shielding low-income households via prebates or personal allowances.
3. Pigouvian Externality Pricing
Taxes should actively discourage activities that impose unpriced costs on society. Pigouvian levies convert social harms into direct fiscal revenue.
- Upstream Carbon Taxation: Implementing a border-adjusted carbon tax prices environmental damage directly into energy and goods production. As outlined in the IMF Fiscal Policy Frameworks, pricing carbon provides market signals for green technology transitions while generating revenue to offset lower income taxes.
- Resource and Congestion Levies: Variable tolling on urban roadways and extraction fees on finite natural resources internalize spatial and environmental costs.
4. Coordinated Multilateral Corporate Minimum Taxes
To address profit-shifting by digital multinationals, international tax law must transition from physical presence rules to destination-based profit allocation.
- Implementation of OECD Pillar 1 & Pillar 2: Adopting a global minimum corporate tax rate of 15% eliminates race-to-the-bottom tax competition, as detailed in the OECD Global Tax Framework.
- Formula Apportionment for Digital Services: Allocating multinational taxable income based on sales destination and active user bases ensures fair revenue distribution without requiring physical offices.
Comparative Analysis of Tax Regimes
| Tax Model | Economic Efficiency | Distributional Equity | Evasion Resilience | Administrative Complexity |
| Traditional Income & Corporate Tax | Low (High deadweight loss, double taxation of savings) | Moderate (Progressive on paper, vulnerable to deductions) | Low (Prone to offshore shifting and tax shelters) | High (Requires extensive compliance and auditing) |
| Wealth & Inheritance Taxation | Low-Moderate (Risks capital flight and valuation disputes) | High (Targets accumulated asset concentration) | Low (Capital moves to non-reporting jurisdictions) | Very High (Requires complex annual asset valuations) |
| Land Value Taxation (LVT) | Maximum (Zero supply distortion on unimproved land) | High (Progressive; land ownership is heavily concentrated) | Maximum (Immobile physical asset) | Low (Requires transparent cadastral land valuation) |
| Destination Cash-Flow Consumption Tax | High (Promotes investment, eliminates capital penalties) | High (Progressive spending tiers + prebates) | High (Border adjustments eliminate transfer pricing) | Moderate (Relies on border adjustments and financial transaction data) |
Mitigating AI-Driven Disruption to Public Finance
As AI tools and automation displace labor income, tax systems relying on payroll fees face declining receipts. Attempting to tax AI directly through “robot taxes” slows innovation and distorts technical adoption.
┌────────────────────────────────────────────────────────────────────────┐
│                        AI DISRUPTION & TAX BASE                        │
├──────────────────────────────────┬─────────────────────────────────────┤
│  Flawed Approach: Robot Taxes    │  Optimal Approach: Cash-Flow Tax    │
├──────────────────────────────────┼─────────────────────────────────────┤
│ • Penalizes technology adoption  │ • Taxes economic output at spending │
│ • Arbitrary definition of "robot" │ • Captures AI super-normal rents    │
│ • Slows productivity growth      │ • Neutral to technology choice      │
└──────────────────────────────────┴─────────────────────────────────────┘
The solution is to decouple public revenues from labor payrolls altogether:
- Shift Base to Corporate Cash-Flow and Land: As capital yields an increasing share of national income relative to wages, taxation must target corporate economic rents and land values rather than wage receipts.
- Eliminate Payroll Tax Caps: Remove income thresholds on social insurance contributions to maintain equity during structural shifts in high-earner distributions.
- Expand Universal Citizen Dividends: Fund social safety nets using revenues generated from Pigouvian carbon taxes and land value capture rather than taxing wage transactions.
Political Execution & Transition Roadmap
Reforming a tax code requires managing transition shocks to prevent capital flight or political paralysis.
Phase 1: Stabilization (Years 1-2)
├── Introduce upstream Carbon Tax with dividend returns
└── Enact OECD Pillar 2 15% global minimum tax

Phase 2: Base Shift (Years 3-5)
├── Replace local property taxes with Land Value Tax (LVT)
└── Allow 100% immediate expensing for business investments

Phase 3: Structural Realignment (Years 6-10)
├── Consolidate Personal Income Tax into Progressive Consumption Tax
└── Phase down distortionary corporate income tax rates
- Revenue-Neutral Phase-In: Pair new Land Value Taxes and carbon levies with immediate rate reductions on wage income and full capital expensing for businesses.
- Granular Tax Prebates: Mitigate regressivity in consumption taxes by distributing monthly advance rebates to low-and-middle-income households.
- International Harmonization: Secure treaty compliance through the IMF International Tax Reform Guidelines, ensuring uniform adoption of destination-based rules across major trading blocs.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
On Monday, September 28, President Trump announced from the Oval Office what the White House calls the largest steel plant in U.S. history. The price tag is $15 billion, the backer is an Indian industrial group, and the target date is 2030. Here’s what’s confirmed and what’s still unanswered.
Key Takeaways
- Cost and timing: The White House says production begins in 2030 and the project creates more than 2,000 U.S. jobs. lanacion
- Builder: Mesabi Metallics, a Minnesota company owned by India’s Essar Group, is building it. fox35orlando
- Output: A White House official told CBS the plant should make 7.5 million or more tons of steel a year, with 1,750 permanent jobs in Iowa. CBS News
- Politics: The event highlighted Iowa as a battleground where Republicans face competitive midterm races. wsbtv
- Open questions: Exact location, financing structure and the 2030 timeline remain unproven.
What Was Announced
Trump unveiled the project alongside steel executives, commerce officials and Iowa Republicans. The Wall Street Journal reported the plan first. Iron ore will come from a $2.5 billion mine Mesabi developed on Minnesota’s Mesabi Range. wdbowsbtv
CBS News reported that Mesabi had not yet said where in Iowa the plant would go. One syndicated report described it as a proposed plant in eastern Iowa, so treat location claims cautiously until the company confirms a site. CBS Newsfox35orlando
| Detail | What’s reported |
|---|---|
| Investment | $15 billion |
| Builder | Mesabi Metallics (owned by India’s Essar Group) |
| Start of production | 2030 (projected) |
| Capacity | 7.5M+ tons/year (White House official, via CBS) |
| Jobs | 2,000+ U.S. jobs overall; 1,750 permanent in Iowa |
| Raw material | $2.5B Minnesota iron ore mine |
| Status | “Largest in U.S.” is a White House claim |
Why Now? Tariffs and the Midterms
The announcement landed under 40 days before the November midterms, in a state where governor and Senate races are tight. AP’s reporting tied the timing directly to Republican efforts to energize voters there.
The policy backdrop matters just as much:
- Trump raised steel and aluminum import tariffs to 50% earlier this year. lanacion
- In June he approved Nippon Steel’s takeover of U.S. Steel, a deal Biden blocked and Trump had initially opposed. lanacion
- At the event, Trump credited the 50% tariffs for a steel industry “roaring back to life.” wsbtv
The plant is the latest piece of a trade strategy built on protecting domestic metals. Tariffs make new U.S. capacity more attractive because they raise the price of imports it competes with.
The Foreign-Capital Twist
An Indian conglomerate funding “the nation’s biggest” U.S. steel plant sits awkwardly with an “America First” message. The White House framed it as prioritizing American workers over foreign labor. The ownership question is a fair one for readers: the jobs and the plant are American, while the capital and parent company are not. That’s common in U.S. manufacturing, but it’s rarely announced from the Oval Office. wftv
What It Means for Steel Markets and Investors
This section is analysis, not reporting.
Supply: 7.5 million tons a year would be a meaningful addition to domestic capacity, but not until 2030. Nothing about steel prices changes this year because of it.
Integration: Pairing a mine with a mill is vertical integration. It insulates a producer from iron ore swings and could lower unit costs if executed well.
Tariff dependence: The economics lean on protection. If tariffs are lowered after an election or a trade deal, a plant built on today’s price assumptions faces a different market. Investors should ask what the plant’s break-even looks like without a 50% wall.
Competitors: Incumbent U.S. producers face a well-capitalized new entrant in four years. That’s a long-term negative for their pricing power and a short-term signal that the sector attracts capital.
What Wealth Managers and Industrial Buyers Should Watch
Projects of this size pull money into adjacent sectors. Here are the places to look:
| Area | Why it matters |
|---|---|
| Equipment and engineering firms | Mega-projects generate multi-year contracts |
| Industrial software and automation | New plants buy control systems, ERP and predictive-maintenance tools |
| Regional banks and municipal bonds | Local infrastructure, housing and utilities expand around large employers |
| Energy and utilities | A steel mill is a major power customer |
| Logistics and rail | Ore moves from Minnesota to Iowa, steel moves to customers |
Five Questions That Will Decide Whether This Gets Built
- Where exactly will it go?
- Site selection drives permitting, power and water.
- How is it financed?
- $15 billion needs debt, equity and likely incentives.
- Who buys the steel?
- Offtake agreements make projects bankable.
- Will the tariff regime hold?
- Policy risk is the biggest swing factor.
- Can the timeline hold?
- A 2030 start leaves little room for delays on a first-of-its-kind facility.
The plant is a real announcement with real money behind it, but it’s also a campaign-season event for a battleground state. The confirmed facts are the investor, the price, the capacity target and the 2030 goal. The unconfirmed ones, especially location and financing, will determine whether the “largest steel plant in U.S. history” gets built on schedule. Watch for Mesabi’s own filings and site announcements over the coming months.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025