
Energy Economy
Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

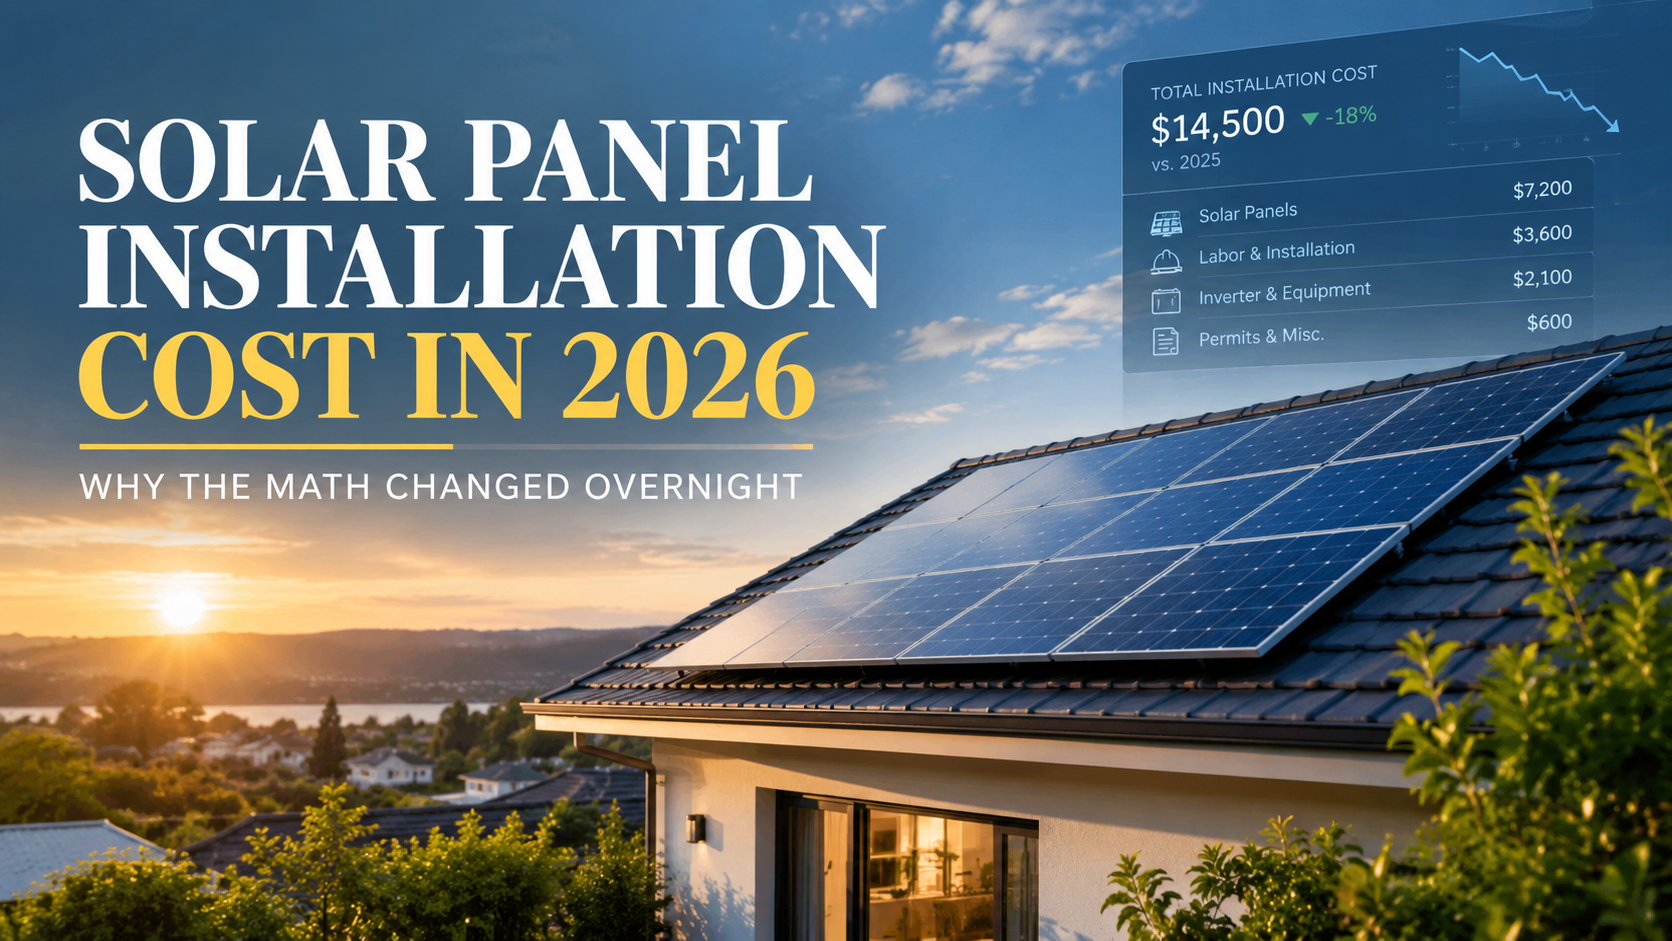
The 30% federal solar tax credit that made rooftop solar affordable for millions of American homeowners is gone. It isn’t phasing out, and it wasn’t reduced—it was abruptly terminated for anyone who didn’t have a residential system installed, inspected, and placed in service by December 31, 2025.
Solar panel installation has always required careful math, but 2026 marks the first year homeowners are shopping for solar entirely without the safety net of the federal Investment Tax Credit (Section 25D). With the passage of the One Big Beautiful Bill Act (OBBBA), the industry’s primary affordability pitch for the last two decades has been stripped away.
Understanding the real, un-subsidized price of a system—and which alternative incentives still apply where you live—is now the single most important step before signing a contract.
Here is what solar panels actually cost in 2026 without the federal credit, how the “third-party loophole” is changing the market, and how to evaluate a solar quote in this new landscape.
How Solar Pricing Actually Works in 2026
The core pricing unit in the solar industry is cost per watt (installed). When multiplied by your system’s size in watts, this gives you the gross project cost before any remaining state or local incentives are applied.
Key Policy Shift: The Residential Clean Energy Credit (Section 25D) was terminated for systems placed in service after December 31, 2025, under the OBBBA, with no phase-down period. This accelerated the credit’s originally planned 2034 expiration by nearly a decade. (Note: If you installed a system in 2025 and have unused credit, you can still carry it forward to reduce your 2026 tax liability).
What a Solar Quote Actually Includes
- Solar Panels: Typically 25% to 35% of total installed cost, varying by panel efficiency and brand tier.
- Inverter(s): Converts DC power from panels to usable AC power; a meaningful cost and reliability factor.
- Mounting & Racking: The structural and electrical components securing panels to your roof.
- Permits & Interconnection: Required paperwork and utility inspections that vary heavily by municipality.
- Labor & Soft Costs: Customer acquisition, overhead, and installation labor. With hardware costs bottoming out, soft costs now make up 50% to 65% of total project expenses.
- Battery Storage (Optional): Adding a home battery typically adds $8,000 to $15,000 to the installed cost, though it is increasingly necessary in states with volatile grid reliability.
Financial Realities: What Solar Costs Without the Federal Credit
Understanding current gross pricing—without assuming a federal credit that no longer exists for new residential installations—is essential for realistic budgeting.
| System Size | Gross Installed Cost Range (2026) | Estimated Cost Per Watt |
| 5 kW | $12,500 – $17,500 | ~$2.50 – $3.50 |
| 8 kW | $20,000 – $28,000 | ~$2.50 – $3.50 |
| 10 kW | $25,000 – $35,000 | ~$2.50 – $3.50 |
| 15 kW | $37,500 – $52,500 | ~$2.50 – $3.50 |
Figures reflect gross cost before any state, local, or utility incentives. The federal 30% residential tax credit no longer applies.
Industry Insight: In 2025, U.S. homeowners claimed billions in federal tax credits. Without it, analysts project a 20% to 30% drop in residential direct-purchases in 2026 as the true, un-subsidized cost becomes the new baseline.
The “Loophole”: Third-Party Leases and PPAs
While homeowners buying systems with cash or standard loans are locked out of federal credits, there is a major caveat driving the 2026 market.
Homeowners who choose a third-party lease or Power Purchase Agreement (PPA) can still access savings. Under these models, the solar company technically owns the equipment, allowing them to claim the commercial clean energy tax credit (Section 48E), which survived the OBBBA cuts.
The leasing company can, in principle, pass those tax savings through to the homeowner via lower monthly rates. However, the value of that pass-through varies significantly by provider. Contracts must be scrutinized carefully to ensure the savings are actually reaching you.
How to Evaluate a Quote in the Post-Credit Era
- Check for “Phantom Credits”: Every solar cost calculator, payback estimate, or sales pitch you encounter should be checked against a single question: Does this figure still assume the 30% federal tax credit? Many outdated online resources and aggressive sales materials have not yet been updated.
- Verify State and Local Incentives: Do not rely solely on installer claims. Program availability varies wildly by state and now carries the primary weight of your ROI.
- Compare Cost Per Watt: Always evaluate cost per watt across quotes for similarly sized systems. A lower total price on a smaller system doesn’t necessarily represent better value.
- Model a Realistic Payback Period: Model your break-even timeline using current, un-subsidized pricing. Older payback estimates built around the expired 30% credit will severely understate how long it takes to recoup your investment.
- Understand Your Net Metering Policy: How your utility compensates you for excess solar production significantly affects the ongoing value of your system, sometimes mattering just as much as the upfront installation cost.
Future Outlook: Trends Through 2027
- Market Contraction & Stabilization: Installation volume will likely decline in the near term as consumer sticker shock sets in, before stabilizing at a new, lower baseline demand level.
- The Rise of PPAs: Because of the commercial tax credit loophole, third-party ownership models will likely dominate the residential market over direct cash or loan purchases.
- State Programs Take the Wheel: Expect massive migration of solar development to states that maintain strong local incentive programs and favorable net metering laws.
- Battery Attach Rates Will Climb: Despite higher overall costs, grid instability and unfavorable time-of-use rates will continue pushing homeowners to bundle battery storage with their solar panels.
Frequently Asked Questions
Is the federal solar tax credit still available in 2026?
No, not for homeowner-owned residential systems. The 30% Residential Clean Energy Credit (Section 25D) was terminated for systems placed in service after December 31, 2025, under the OBBBA. However, unused credits generated from a 2025 installation can be carried forward into 2026.
How much does a solar panel installation cost in 2026 without the tax credit?
A typical residential system costs $2.50 to $3.50 per watt installed before any remaining state or local incentives. This means an average 8 kW system runs roughly $20,000 to $28,000 gross.
Can I still get any tax benefit from going solar in 2026?
While direct purchases no longer qualify for the federal residential credit, you can opt for a third-party lease or PPA. Because the solar company owns the system, they can claim the related commercial tax credit (Section 48E) and potentially pass those savings on to you through lower energy rates.
Why did the federal solar tax credit end so abruptly?
The One Big Beautiful Bill Act, signed into law in July 2025, terminated the residential credit effective December 31, 2025, accelerating what was originally scheduled as a gradual phase-out ending in 2034.
Should I still get multiple solar quotes even without the federal credit?
Yes, arguably more than ever. Prices commonly vary 20% to 40% between installers for functionally identical systems. With the federal subsidy gone, locking in a competitive baseline price is the only way to ensure a reasonable payback period.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Energy security in 2026 means more than having enough oil in storage. It means sustaining affordable, reliable power and fuel through geopolitical disruption, extreme weather and a rapid rise in electricity demand. The economic consequences reach from factories and transport fleets to inflation, fiscal budgets and national competitiveness. Energy resilience has become a central part of macroeconomic policy.
The International Energy Agency’s October 2026 Oil Market Report describes severe pressure on the diesel market following disruptions to supplies and refining. On October 15, the IEA Governing Board noted that approximately 330 million barrels had been released under coordinated emergency action, with further releases planned. These figures show the scale of the response, not evidence that the supply system has returned to normal.
Key takeaways
- Diesel availability and refining capacity matter as much as headline crude-oil prices.
- High energy costs affect inflation, trade competitiveness, employment and government finances.
- Diversified supplies, efficiency and a reliable grid work together; no single technology guarantees security.
- Emergency inventories buy time but do not replace durable investment in energy systems.
- Pakistan’s priority is to reduce import exposure and electricity-system inefficiency without imposing unsustainable subsidy bills.
Why an oil-price headline is not enough
News coverage often reduces energy markets to a single crude-oil benchmark. Households and businesses, however, buy gasoline, diesel, electricity, gas and heating fuels. Those products depend on refining capacity, transport, storage and local distribution. A country can have access to crude yet face a shortage of a specific refined product.
The IEA’s October report described diesel exports in September running 700,000 barrels a day below the year-earlier level, with declines from Russia and the Middle East only partly offset elsewhere. It also warned that tight diesel markets could extend into 2027 despite an expected recovery in refinery operations. These are forecast conditions, not guaranteed future shortages in every country.
Why diesel? It powers freight, buses, agriculture, backup generation and parts of industry. A bottleneck therefore raises the cost of moving and producing goods even in economies where motorists primarily notice gasoline prices. A slower delivery network can become a food-price and manufacturing problem.
Five layers of energy security
| Layer | Failure mode | Example policy response |
|---|---|---|
| Supply access | Fuel imports or production disrupted | Supplier and route diversification |
| Conversion | Refineries or generation cannot meet need | Maintenance, compatible capacity and flexibility |
| Transportation | Shipping chokepoint or network outage | Alternative routes, storage and grid reinforcement |
| Affordability | Prices exceed household or firm capacity | Targeted relief and efficiency |
| Sustainability | System depends on costly or vulnerable assets | Long-term efficiency and diversified generation |
Original analytical framework; optimal combinations vary by geography.
The layers interact. Strategic inventories are of limited use if fuel cannot reach the point of consumption. Large generation capacity may not prevent blackouts when transmission and distribution fail. Even abundant energy can undermine economic performance if tariffs are unpredictable or hidden public subsidies exhaust budget capacity.
Strait of Hormuz and the limits of emergency reserves
The 2026 disruption to energy flows through the Strait of Hormuz demonstrated how a single maritime route can affect multiple regions. The IEA’s October statement referred to collective action initiated in March and plans to accelerate remaining releases, including diesel. Strategic stocks can smooth the immediate shock and prevent panic buying, but they are finite.
A strategic stock programme works best alongside transparent triggers, monitoring, logistics planning and a strategy for replenishment. Governments that release stocks without a credible replacement plan may reduce current price pressure at the expense of future readiness. Conversely, withholding supplies during a severe shortage can increase the economic cost of interruption. Decisions should be based on severity and duration, not politics alone.
This also illustrates why demand-side options matter. If some activities can shift timing, improve fuel efficiency or use alternative energy sources, the same available supply can support more essential economic activity. Conservation is not merely an environmental appeal during a disruption; it can be a supply-security instrument.
Asia’s rising exposure
Southeast Asia is a useful example because economic growth, urbanization and electrification are simultaneously increasing energy demand. The IEA’s 2026 ASEAN Energy Security Review highlights imported oil and LNG exposure, maritime chokepoints, electricity reliability, clean-energy minerals and regional cooperation. The IEA expects electricity demand in the region to rise around 5.4% annually during 2026–2030 under the report’s projection.
The scale of growth creates a planning challenge. More power stations are not sufficient if grids, storage, demand response and equipment maintenance lag behind. Policymakers must protect reliability while accommodating new demand from industry, cooling and data centres. Fuel choices should reflect local resources, realistic network conditions and whole-system costs.
The IEA’s Southeast Asia Energy Outlook 2026 provides longer-term context for this tension. Some countries can rely on domestic resources for portions of their needs; others depend on international fuel trade. Regional cooperation can improve resilience, but shared networks require transparent rules and investment in cross-border infrastructure.
The electricity problem inside the AI boom
Artificial intelligence is increasing demand for computing infrastructure, which requires steady electricity. The IEA’s October 14 report on powering AI assesses the challenge of integrating data centres without undermining affordability, sustainability or reliability. Power capacity cannot be created by financial investment announcements alone.
There are at least three economic questions. Who pays for the new grid connection and network upgrade? How quickly can additional supply be delivered? What happens if data-centre demand is lower than originally forecast? Poor contracts can leave utilities and their customers with stranded assets. Better contracts allocate capital and demand risk to parties able to manage them.
For developing economies, the opportunity is conditional. A technology facility can anchor skilled work and high-quality connectivity, but it should not crowd out factories and households through exclusive access to cheap or subsidized electricity. The economic test is broad productivity, not the count of data-centre announcements.
Pakistan’s three energy challenges
The import bill. Higher world prices for oil and refined products can strain foreign-exchange needs. Currency movements, shipping and taxation alter the final local cost. Avoiding a narrow focus on one benchmark helps explain why domestic prices may move differently from international crude prices.
The electricity system. Transmission losses, collection problems, costly generation and contract design can influence tariffs and reliability. The IMF’s October Pakistan assessment calls for energy-sector efficiency, cost-reducing reforms and prevention of renewed circular debt accumulation. A supply emergency should not become a justification for avoiding operational reform.
Household affordability. When prices rise, protection is needed for vulnerable consumers. The dilemma is designing support that does not encourage excess use or transfer most resources to high-volume consumers. The IMF October World Economic Outlook argues that temporary targeted transfers can be substantially more cost-efficient than broad price suppression.
A coherent 2026–2030 strategy
First, measure exposure clearly: fuel import dependency, usable inventories, refinery constraints, grid bottlenecks and financial obligations. Second, diversify the system where economics support it, including domestic resources, renewables, storage, transmission and regional links. Third, improve efficiency in buildings, agriculture, transport and industry so each unit of energy produces greater value.
Fourth, design emergency plans before a shortage. Fifth, ensure tariff structures recover legitimate system costs while protecting essential consumption by vulnerable households. Finally, publish investment appraisal and procurement details to guard against expensive contracts entered under crisis pressure.
The IEA ASEAN review emphasizes diversification, electrification, efficiency and regional preparedness as reinforcing elements. The approach is useful beyond ASEAN because energy-system risks rarely respect borders.
What energy resilience is worth to an economy
The value of resilience is often invisible until a crisis. A fuel reserve can appear costly in a normal year; a reinforced grid may look expensive when electricity flows without interruption. Traditional cost comparisons can underestimate these assets when they ignore the economic losses associated with rare but severe failures. A better appraisal estimates expected interruption costs and measures the reduction provided by each investment.
Consider an industrial exporter reliant on consistent electricity. An outage can damage materials, interrupt production schedules, impose generator costs and delay contractual delivery. Lower tariffs are welcome, but a nominally cheap grid that repeatedly fails may be more expensive to the exporter than a dependable system with transparent cost recovery. The same principle applies to irrigation pumps, refrigerated food chains and hospitals, although the social consequences differ.
The IEA’s October ASEAN electricity analysis expects regional demand to rise around 5.4% a year during 2026–2030. That projection strengthens the case for planning generation, networks and flexibility jointly instead of authorizing capacity in isolated projects. It also creates a timing dilemma: build too slowly and reliability deteriorates; build on exaggerated demand projections and customers may pay for unused assets.
Financing structures matter as much as engineering. Public guarantees for fuel supply, generation or grid investment can create contingent liabilities that are not obvious in a project’s advertised tariff. The IMF’s October financial-stability review emphasizes broader vulnerabilities from leverage and funding structures. Energy planners should publish obligations under contracts and test project economics against both lower demand and higher financing costs.
For Pakistan, a resilience agenda should combine better collection and metering with cost-effective grid investment, more transparent contract terms and measures that reduce consumption per unit of output. A durable policy saves fuel, lowers the impact of external shocks and improves business competitiveness at the same time.
Risks and uncertainties
Conflict conditions and fuel forecasts can change abruptly. The October IEA projection may not capture subsequent attacks, refinery outages or policy decisions. Renewables and storage can improve resilience but need appropriate grids and operational planning; gas and oil infrastructure can provide flexibility but also expose consumers to imports and price volatility. Policy evaluation must include total life-cycle costs, fiscal risks and system reliability rather than endorse a single technology.
Frequently asked questions
What is energy security?
The capacity to maintain reliable, affordable and accessible energy supplies through normal conditions and unexpected disruptions.
Why can diesel be expensive even if crude is available?
Diesel prices depend on refinery output, trade routes, inventories, freight and regional product shortages as well as crude supply.
What did the IEA do in 2026?
It coordinated emergency stock actions in response to the Hormuz crisis; its October board statement reported substantial released volumes and further planned releases.
Do renewable technologies automatically eliminate import risk?
No. They can reduce fuel-import exposure but require grids, equipment, storage or flexibility and, in some cases, imported components.
Why are data centres an energy-security issue?
They increase concentrated electricity demand and can require expensive upgrades, affecting tariffs and grid planning.
What should Pakistan prioritize first?
Lower losses and avoidable costs, dependable distribution, transparent energy procurement, targeted household protection and diversified supply.
Conclusion
Energy security is economic security because almost every productive activity depends on fuel or electricity. The correct response to the 2026 shock is not permanent emergency pricing; it is a system capable of withstanding disruptions without sacrificing affordability or fiscal stability. That requires resilience across supplies, networks, investment and institutions—not a single fuel or a single headline announcement.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
An energy shock affects Pakistan through much more than the petrol pump. It can raise electricity costs, squeeze exporters, push up fertilizer bills and increase demand for foreign exchange. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
How disruptions travel from global markets to Pakistan
For how disruptions travel from global markets to pakistan, An energy price increase is a supply shock and a balance-of-payments shock at once. It can raise the amount paid for imported fuels before domestic firms have time to adjust production or prices. Electricity-intensive exporters are especially exposed to this timing mismatch.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For how disruptions travel from global markets to pakistan, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Oil and LNG create different vulnerabilities
For oil and lng create different vulnerabilities, Supply diversification can be valuable, but not if it simply transfers risk into costly contracts or underused infrastructure. Energy security requires portfolio thinking: fuel alternatives, reliable grids, transparent procurement, and efficiency in final use.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For oil and lng create different vulnerabilities, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Why fertilizer is an economic-security issue
For why fertilizer is an economic-security issue, The political challenge is that universal subsidies make a shock less visible in the short run but can crowd out spending on services and resilience. Explicit, budgeted protection for people in need is more transparent.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why fertilizer is an economic-security issue, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
The exchange-rate and current-account feedback loop
For the exchange-rate and current-account feedback loop, An energy price increase is a supply shock and a balance-of-payments shock at once. It can raise the amount paid for imported fuels before domestic firms have time to adjust production or prices. Electricity-intensive exporters are especially exposed to this timing mismatch.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the exchange-rate and current-account feedback loop, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Building shock resistance before the next crisis
For building shock resistance before the next crisis, Supply diversification can be valuable, but not if it simply transfers risk into costly contracts or underused infrastructure. Energy security requires portfolio thinking: fuel alternatives, reliable grids, transparent procurement, and efficiency in final use.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For building shock resistance before the next crisis, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
An energy shock affects Pakistan through much more than the petrol pump. It can raise electricity costs, squeeze exporters, push up fertilizer bills and increase demand for foreign exchange. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Wind power is expanding globally, yet the economics of an individual wind farm remain highly sensitive to where it is built, how much energy it delivers and how cheaply that energy can reach customers. Rising installation totals cannot by themselves establish that every project will make money.
According to the International Energy Agency’s Global Energy Review 2026, annual wind capacity additions reached roughly 160 gigawatts after a rapid increase. The Global Wind Energy Council projects substantial additional installations through 2030. These are measures of industry momentum, not uniform project returns.
Revenue begins with the capacity factor
A turbine’s rated power describes its maximum output under suitable conditions. Its annual generation depends on actual wind speeds, air density, maintenance downtime and curtailment. The capacity factor expresses real generation as a share of what continuous nameplate output would have produced. Because turbine construction costs are largely incurred upfront, a modest difference in annual output can change the entire financial model.
Developers therefore spend years measuring wind resources and considering wake effects, where an upstream turbine reduces wind available to one behind it. Taller towers, larger rotors and better forecasting can improve performance, but they also affect permitting, transport and maintenance costs.
The price of power matters as much as the amount
A project with excellent wind conditions can still struggle if electricity prices are low when it produces, if the grid cannot accept its output, or if its power-purchase agreement has unfavorable terms. Merchant projects face price volatility directly; contracted projects exchange some upside for revenue visibility. Both need credible assumptions about future congestion, transmission access and local demand.
Investors should ask whether headline tariffs or contract prices include grid connection costs, balancing responsibilities and curtailment provisions. Comparisons between two wind farms are meaningful only if financing, generation, currency and contractual risk are measured on the same basis.
Why interest rates change the equation
Wind farms are capital-intensive. A large fraction of lifetime costs is committed before the first unit of electricity is sold. This makes the cost of capital crucial: higher borrowing rates and required equity returns raise the price at which the project must sell electricity to remain viable.
Inflation affects steel, concrete, installation ships, labor and electrical components. Offshore farms in particular can face expensive marine construction, specialized vessels and difficult repairs. Onshore projects generally avoid some marine costs but still contend with land rights, transmission queues and community concerns.
Grid availability is not optional
Building turbines without transmission capacity can produce a stranded asset. Interconnection studies, new substations and upgrades to neighboring networks may determine the commercial timeline. Generation also varies by season and hour, so grids need flexible demand, storage, interconnections or other resources to balance supply.
The IEA’s Electricity 2026 supply analysis expects strong growth in wind generation over the forecast horizon. That makes network planning and system flexibility an economic priority rather than a minor engineering footnote.
Communities have legitimate questions
Local approval frequently turns on land payments, noise, visual effects, wildlife considerations and tax revenues. A serious project proposal should be specific about setback rules, environmental surveys, decommissioning guarantees and who receives the financial benefits. Developers improve outcomes when they publish operational evidence and avoid presenting every concern as ignorance or obstruction.
The bottom line: wind farm profitability is a project-level conclusion, built from generation forecasts, contracts, financing and grid access. Global growth provides an opportunity, not a substitute for due diligence.
How a developer models a hypothetical project
Consider a proposed 100-megawatt wind farm. At a hypothetical 35% capacity factor, output would be roughly 306,600 megawatt-hours per year before other losses. At a hypothetical realized sale price of $60 per megawatt-hour, gross electricity revenue would be about $18.4 million annually. Neither figure is a real-world offer or estimate for a named site. From that revenue, developers must pay operations and maintenance, land rents, balancing costs, insurance, financing and eventual decommissioning. Curtailment, lower wind speeds or an unfavorable contract can quickly change the result. A project-level article should show the assumptions and stress-test them rather than publishing a single payback period as a universal fact.
Frequently asked questions
Are wind farms profitable in 2026?
Some are; others face unfavorable financing, connection or construction economics. Profitability cannot be inferred from national capacity additions.
Is offshore wind better than onshore wind?
Neither is universally superior. Offshore resources can be strong, but marine construction and maintenance typically introduce different costs and risks.
What should a community ask a developer?
Request clear estimates for local tax receipts, land arrangements, environmental monitoring, decommissioning funding and transmission works.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Personal Injury Lawyer Near Me in NYC: How to Find the Right Attorney After an Accident

Why Falling World Food Prices Do Not Always Lower Grocery Bills

Oil Shocks and Core Inflation: Why the Two Move Differently

Singapore Cannot Fight Financial Fraud by Making Victims Bear the Risk Alone

Singapore Banking’s Real Test: Beyond Profits, Who Will Safeguard Financial Trust?

Nvidia’s Share Price Is Not a Scorecard for Singapore’s AI Future

The Australian Dollar Is Not Asia’s Oracle. Singapore Should Listen Anyway

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth

Why a Weaker Currency Makes Imported Food More Expensive

How Oil Price Shocks Raise Food Prices in Importing Countries

Petrol and Diesel Prices in Pakistan Today: Complete Update for 9 November 2026

Wall Street’s Renminbi Paradox: Banks, Beijing and the Dollar

The Market Economy Is Winning

Bitcoin’s Dollar Trap: The Chart That Exposes the Future of Money

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

Stock Market Crash 2026? What the November Rout Actually Tells Us

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025