
Economic Costs of Wars
How the 2026 Iran War Reshaped the Global Economy

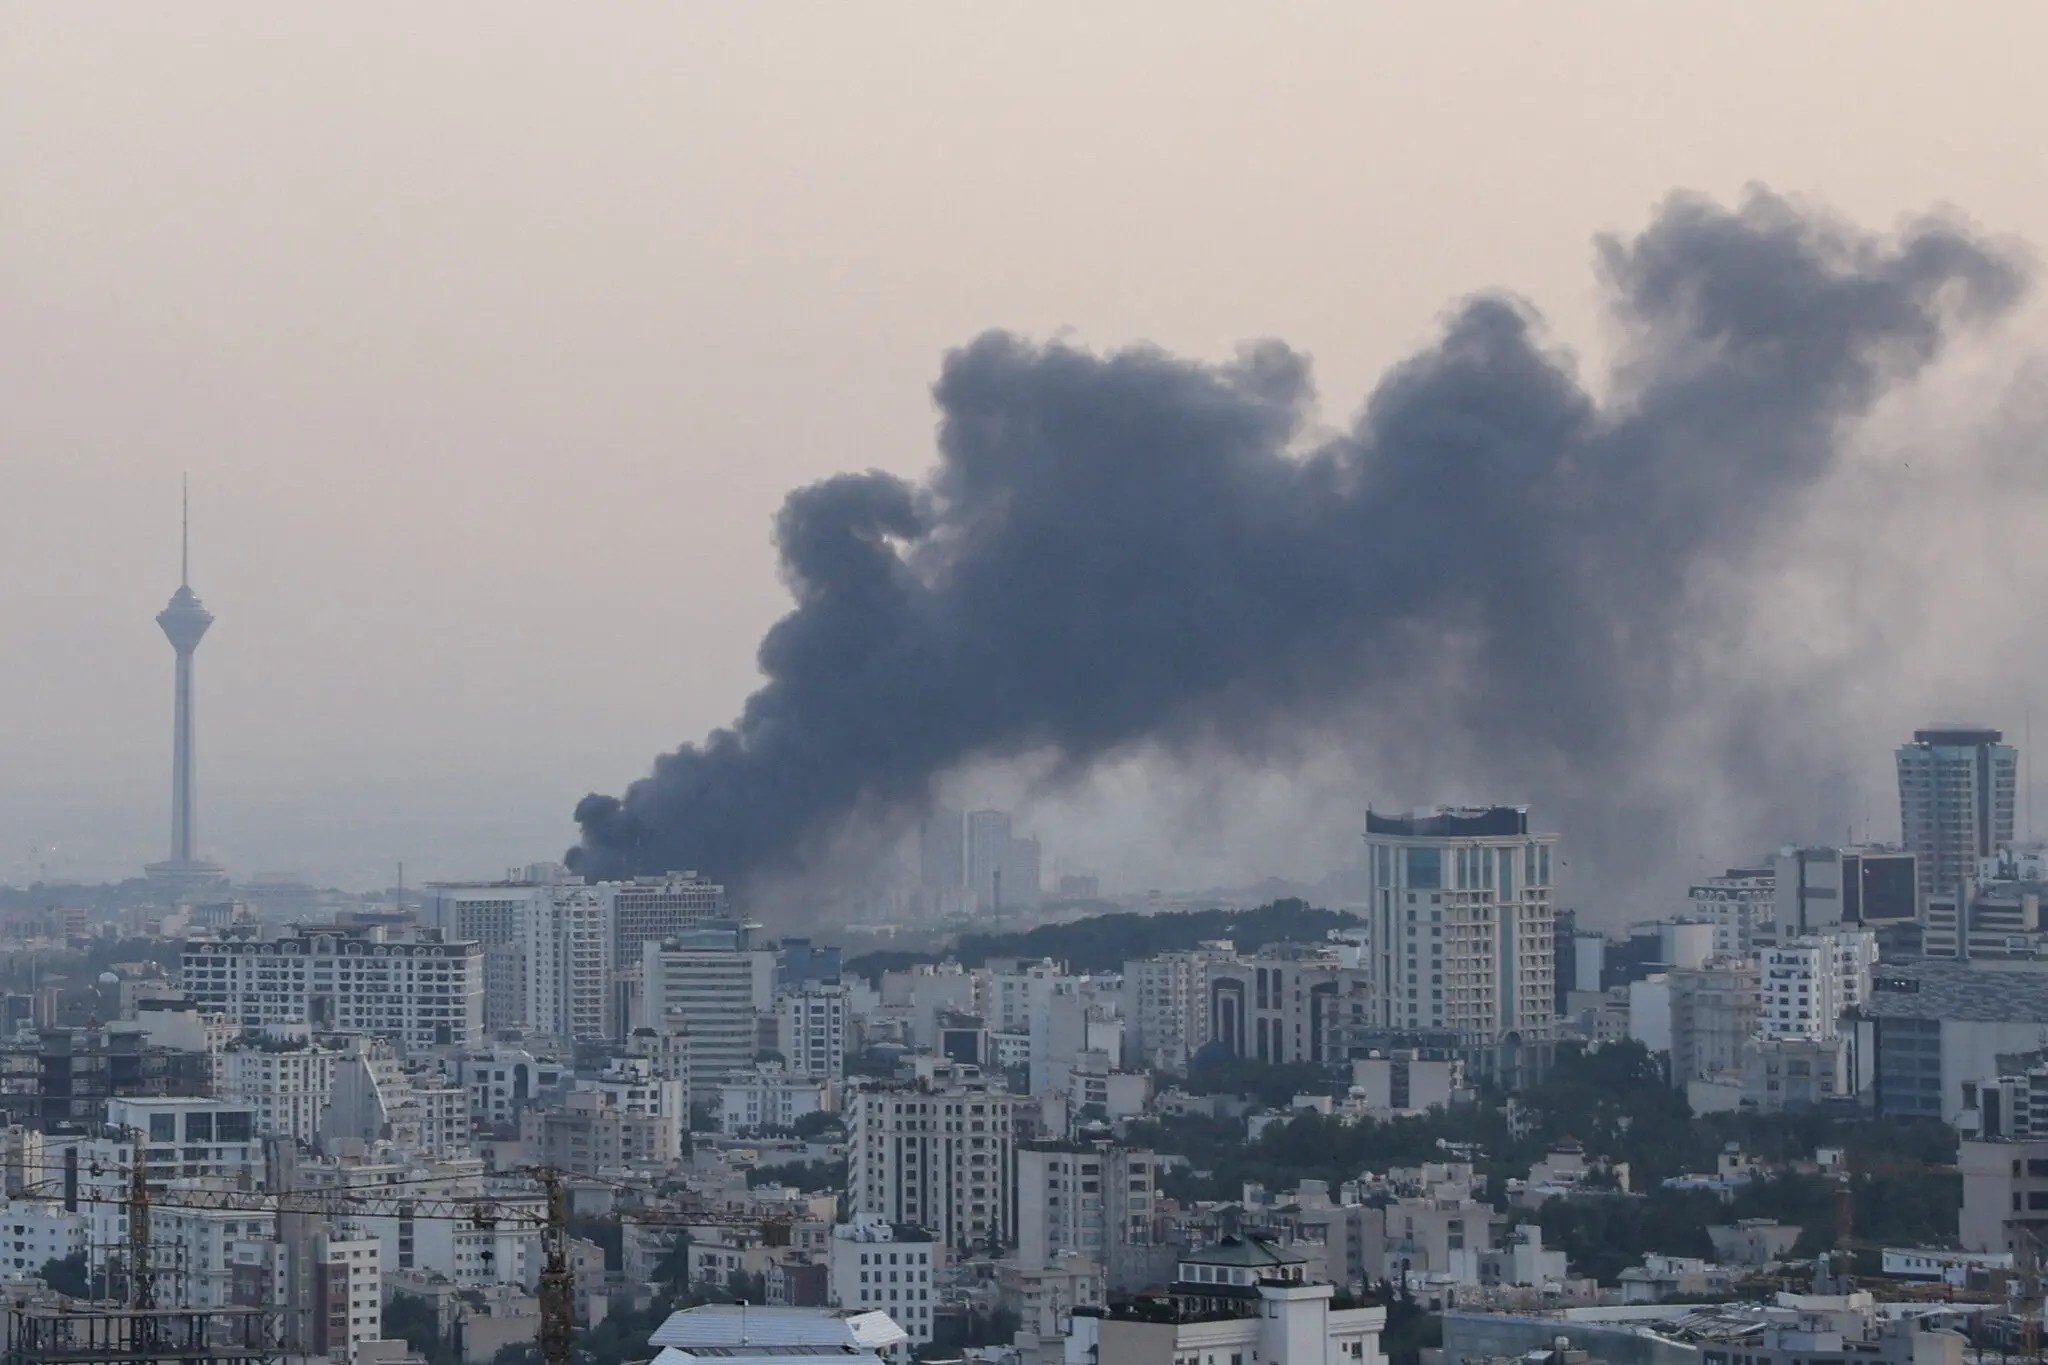
The 2026 Iran war and Strait of Hormuz closure triggered the largest oil supply disruption in history. From $120 oil to Gulf food crises to global stagflation fears — here is the full economic reckoning.
Introduction: The Day the World’s Oil Tap Closed
On the morning of March 4, 2026, Iran announced the closure of the Strait of Hormuz to commercial shipping. The waterway — a 33-kilometer-wide chokepoint between Iran and Oman — carries approximately 20% of the world’s seaborne crude oil and significant volumes of liquefied natural gas (LNG). Its closure triggered an economic chain reaction that reverberated from the gas stations of California to the rice markets of Bangladesh to the balance sheets of Asia’s largest central banks.
Three months later, with a fragile peace agreement signed and the first tankers cautiously returning to the strait, the world is beginning to count the cost of what the International Energy Agency has characterized as “the largest supply disruption in the history of the global oil market” (Wikipedia: Economic impact of the 2026 Iran war).
This is the comprehensive economic reckoning.
The Timeline: From War to Global Shock
February 28, 2026: The United States and Israel launch military operations against Iran. Brent crude immediately surges 10–13% to around $80–82 per barrel (Wikipedia: 2026 Iran War Fuel Crisis).
March 4, 2026: Iran formally closes the Strait of Hormuz. Oil and LNG exports from the Gulf are immediately stranded.
March 4–12, 2026: Qatar Energy declares force majeure on all exports. Kuwait, Iraq, Saudi Arabia, and UAE collectively lose an estimated 6.7 million barrels per day of production capacity.
March 12, 2026: By this date, at least 10 million barrels per day of production has been removed from global markets. Brent crude surpasses $100 per barrel. Net retail buying of oil ETFs hits a record $211 million in a single day (CNBC).
March–April 2026: Panic buying erupts worldwide. The Philippines, Pakistan, Bangladesh, Zimbabwe, Nigeria, and Vietnam face severe fuel shortages. The Philippines declares a state of national energy emergency.
April 2026: Brent crude peaks above $120 per barrel. US gas prices approach $5.00 per gallon. California — heavily reliant on energy imports from Asia — sees gasoline exceed $6.00 per gallon in seven counties (Wikipedia: 2026 Iran War Fuel Crisis).
June 18, 2026: Trump signs the US-Iran peace MoU. The first Saudi-flagged supertankers transit the reopened strait. Oil begins falling sharply.
The Scale of Disruption: Unprecedented in Modern History
The numbers are staggering:
- 20% of global seaborne oil supply disrupted at peak (Wikipedia)
- 10+ million barrels per day of production removed
- Brent crude surged over 50% from pre-war to peak levels
- One billion barrels of oil production estimated as lost in total, according to Vitol CEO Russell Hardy (Wikipedia: 2026 Iran War Fuel Crisis)
- Jet fuel in North America spiked 95% since the war’s start, causing airlines to raise baggage fees and fares
- The IEA called it “the greatest global energy security challenge in history” by May 2026 (Wikipedia)
For historical context: the 1973 Arab oil embargo cut global supply by approximately 7–8%. The 2026 crisis removed nearly 14 million barrels per day at its worst — roughly double the 1973 shock.
The Gulf Catastrophe: A Civilizational Supply Shock
The economic impact on Gulf Cooperation Council (GCC) states was arguably the most acute of anywhere in the world. The Hormuz closure created a perverse trap: Gulf states depend on the strait both for their oil exports and for over 80% of their food imports (Wikipedia).
The results:
- 70% of the region’s food imports were disrupted within weeks of the closure
- Retailers like Lulu Retail resorted to airlifting staple goods at enormous cost
- Consumer food prices in Gulf states spiked 40–120% within months
- Iranian strikes on desalination plants — which produce the drinking water for millions across the Gulf — raised fears of a humanitarian crisis beyond mere economic disruption
The GCC’s economic model — built on hydrocarbon export revenues funding high per-capita welfare states and massive food import programs — was, as one analysis described it, experiencing “a systemic collapse” (Wikipedia).
Qatar faced a particularly acute crisis. QatarEnergy declared force majeure on its LNG contracts. As a major LNG exporter to Singapore, Taiwan, Pakistan, and Bangladesh — countries that are both more price-sensitive and more dependent on Qatari gas than major economies — the ripple effect of Qatar’s production shutdown was devastating for import-dependent Asian nations (Wikipedia).
The Global Inflation Cascade
The oil shock didn’t stay in the energy sector — it propagated through the entire global inflation landscape.
Food Security: The Fertilizer Dimension
Over 30% of global urea — the most widely used nitrogen fertilizer — is exported from Gulf countries through the Strait. With fertilizer supply disrupted, the cost of food production in importing nations spiked. The British think tank the Food Policy Institute warned of long-term increases in food prices as fertilizer and energy markets remained disrupted (Wikipedia: 2026 Iran War Fuel Crisis).
Aviation: Grounded by Fuel Costs
Airlines across Asia and Oceania faced shortages of jet fuel in the immediate aftermath of the Hormuz closure. Jet fuel prices in North America surged 95%, forcing carriers to implement fuel surcharges on passengers and baggage. Multiple logistics operators — including USPS, Amazon, and FedEx — imposed energy surcharges on deliveries (Wikipedia).
Monetary Policy: The Rate-Cut Dream Dies
Central banks across Asia, Europe, and North America had entered 2026 expecting a benign rate-cutting environment. The oil shock ended that dream. Interest rate cuts were universally postponed; in the US, rate hikes entered the policy conversation. Stock markets globally experienced declines and a simultaneous bond market selloff drove yields higher (Wikipedia).
Regional Economic Breakdown
Asia — Most Exposed
China, India, Japan, and South Korea together account for 75% of Gulf oil exports and 59% of LNG exports from the region (Wikipedia). Asia bore the brunt of the initial disruption, with industrial production, transportation, and power generation all affected by fuel shortages and price spikes.
Pakistan — A Nation Under Pressure
Pakistan — already under IMF fiscal adjustment — faced fuel shortages that directly threatened economic stability, agricultural production (due to fertilizer shortages), and transport. The country’s energy import dependency, price sensitivity, and reliance on Qatari LNG made it one of the most economically vulnerable nations during the crisis. Pakistan’s foreign exchange situation was further strained by the surge in import costs.
Europe — Medium-Term Risk
Europe does not source the majority of its oil from the Gulf, but its LNG dependence — particularly from Qatar — made it vulnerable in the medium term. The Hormuz closure underscored the fragility of Europe’s post-Russia energy diversification strategy, which had leaned heavily on Qatari and other Middle Eastern LNG.
United States — Paradoxical Beneficiary
In a striking paradox, the energy crisis produced windfall revenues for American oil producers. As an energy-exporting nation with significant domestic oil production, the US benefits from higher global oil prices even as domestic consumers suffer at the pump. US oil export revenues surged in Q1 and Q2 2026 (Wikipedia).
The Longer Shadow: Structural Shifts in Energy Policy
The 2026 crisis will leave permanent marks on global energy policy:
- Strategic reserve buildups — Every major economy is reassessing the size and accessibility of its strategic petroleum reserves
- Energy diversification acceleration — China’s public statements calling for faster energy transition reflect a broad global recalibration of dependence on Gulf hydrocarbons
- LNG infrastructure investment — The crisis exposed critical bottlenecks in LNG liquefaction and regasification capacity outside the Gulf
- Geopolitical risk premiums — Oil markets will now permanently price a higher geopolitical risk premium than before the war
- Payment system sovereignty — Concerns about economic sovereignty are fueling interest in alternatives to Visa and Mastercard for international energy transactions, particularly among non-Western states (Bloomberg)
Frequently Asked Questions (FAQ)
Q: What was the economic impact of the 2026 Iran war?
The war triggered the largest oil supply disruption in history — removing up to 10 million barrels per day from global markets, pushing Brent crude above $120/barrel, causing US gas to approach $5/gallon, and generating global inflation, food security crises, and stagflation fears.
Q: Which countries were most affected by the Strait of Hormuz closure?
Gulf states (Saudi Arabia, UAE, Qatar, Kuwait, Iraq) were severely affected by both export disruption and food import blockage. In Asia, Pakistan, Bangladesh, Vietnam, Singapore, and Taiwan were most vulnerable. The Philippines declared a national energy emergency.
Q: Did Pakistan face an oil shortage in 2026?
Yes. Pakistan was among the countries facing severe fuel shortages and economic strain during the Hormuz closure, given its reliance on Gulf energy imports and high price sensitivity.
Q: What did the IEA say about the 2026 energy crisis?
The IEA characterized the 2026 Iran war as triggering “the largest supply disruption in the history of the global oil market” and “the greatest global energy security challenge in history.”
Q: How much oil production was lost in the 2026 Iran war?
Vitol CEO Russell Hardy estimated a total loss of approximately one billion barrels of oil production due to the conflict. At its peak, disruption removed over 10 million barrels per day from global markets.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


There is an economic argument for diplomacy that rarely appears in the photographs of negotiators. Each tanker delayed, shipping premium raised or energy contract disrupted can become a higher fuel bill for an importer thousands of kilometres away. For Pakistan, involvement in talks concerning the United States, Iran and the Strait of Hormuz therefore has a practical domestic dimension.
On October 24, Iran’s ambassador in Islamabad said Tehran was open to further talks under an interim agreement brokered by Pakistan in June, according to Associated Press reporting. The ambassador described disagreements over the US naval blockade and reopening the strait. Those claims reflect Iran’s account of the talks, not proof that all parties have accepted a final settlement.
What would the dividend actually be?
The first potential benefit is not a new investment pledge. It is risk reduction. More predictable shipping through a major energy corridor could reduce the uncertainty priced into fuel contracts, maritime insurance and freight. This would matter for Pakistan’s import bill even without an immediate drop in benchmark oil prices.
Second, stability could support business planning. Refiners, large industrial consumers and shipping firms struggle to price future activity when cargo timing is unpredictable. A credible security arrangement would reduce costly contingency measures. Third, calmer regional relations could improve the prospects for lawful trade and energy cooperation—subject to sanctions rules, commercial feasibility and financing constraints.
None of these benefits is automatic. A pause in fighting can be fragile. A shipping route can be nominally open yet commercially unattractive if insurers and crews judge risks too high. And a diplomatic breakthrough might not remove domestic weaknesses in Pakistan’s energy sector.
Why Islamabad’s role matters beyond prestige
Pakistan has relationships across competing regional camps and faces powerful incentives to limit escalation along the Gulf. Its geography, diaspora links and reliance on imported energy give it a stake in outcomes. Qatar has also played a role in mediation; depicting Islamabad as the only channel would be misleading. The AP account specifically describes a Pakistan-brokered agreement reached with Qatar’s help.
A successful intermediary can sometimes gain diplomatic credibility that facilitates subsequent economic engagement. But credibility is earned through confidentiality, sustained contact and practical implementation, not by announcing an imaginary peace dividend in advance.
How the effect would reach Pakistan
Consider four linked markets. Crude oil responds to threats to supply. Tanker freight responds to route length, vessel availability and security. Marine insurance reacts to exposure and perceived escalation risk. Foreign exchange reflects the dollars needed to settle import transactions. Improvements in only one of these areas could leave the total landed bill elevated.
The World Bank’s October Pakistan report credits stabilization and remittances for supporting reserves, while acknowledging the Middle East conflict’s effects. That is the relevant context for diplomacy: external relief would support reform, not replace it.
Three possible diplomatic outcomes
| Outcome | Economic implications | What to verify |
|---|---|---|
| Durable shipping arrangement | Lower disruption risk and improved cargo predictability | Insurer terms, actual tanker movement, official commitments |
| Limited temporary understanding | Short-lived relief, risk of reversal | Monitoring mechanism and duration |
| Talks stall | Continued elevated energy and freight risk | Official statements, sanctions and blockade status |
A credible article about US–Iran talks should identify whose proposal is being discussed, which conditions remain disputed and whether shipping operators can actually use the route. Diplomatic language such as close to a deal is not the same as a binding document.
The investment narrative needs realism
Suggestions that a mediation role will immediately unlock billions in foreign investment are speculative unless linked to signed contracts, financing structures and feasibility studies. Pakistan could instead prioritize incremental gains: energy-security planning, better logistics, diaspora finance channels and trade facilitation that remains consistent with international obligations.
The wider economy matters too. The IMF’s October forecast projects global growth of 3.1% for 2026 and warns about conflict-related downside risks. Lower geopolitical uncertainty is welcome, but it does not instantly erase weak export productivity or fiscal bottlenecks.
How to measure a peace dividend without inventing a number
An economic dividend needs a counterfactual: what would energy, freight and trade costs have been without an agreement? That is inherently difficult to establish during simultaneous shifts in global demand and US interest rates. An analyst could compare tanker transit counts, average freight quotations and cargo arrival delays before and after a verified arrangement, while acknowledging unrelated market influences.
The most immediate indicators would likely be operational. Did ships complete voyages that had been postponed? Did underwriters alter war-risk premiums? Did counterparties begin offering more normal delivery windows? Only after those changes can analysts reasonably discuss effects on Pakistan’s import payments and inflation. A fall in crude on the day of a diplomatic announcement is suggestive, not conclusive evidence of causation.
There is also a policy lesson for Islamabad: mediation can create room for reforms that improve shock absorption. Energy efficiency, diversified procurement, stronger reserves and more productive exports reduce the cost of the next disruption regardless of who negotiates it. A foreign-policy success becomes more economically valuable when domestic institutions can make use of it.
The appropriate headline should therefore distinguish potential from realised savings. Diplomatic momentum is valuable, but an accounting entry requires more than optimistic language.
Has a comprehensive US–Iran agreement been finalized?
Not established by the cited October 24 reporting. The parties remain divided over the blockade and passage arrangements.
Would peace immediately lower Pakistan’s petrol prices?
Not necessarily. Domestic prices depend on refined-product benchmarks, the exchange rate, freight, taxes and procurement lags.
What is the strongest measure of diplomatic success?
Implementation: safer transit, sustained dialogue and measurable reduction in disruption, rather than the number of meetings or headlines.
The real prize for Pakistan is predictability. If mediation helps turn a volatile strategic corridor into a safer commercial route, the economic benefit will be felt in quieter import invoices and more confident business decisions—long before any grand diplomatic dividend can be calculated.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Ukraine’s expanding campaign against Russian oil infrastructure is revealing vulnerabilities in Vladimir Putin’s war economy. Yet damaging refineries is only the beginning. The real challenge is converting industrial disruption into sustained economic and diplomatic leverage.
A New Front in the War of Attrition
Wars are often decided not simply by what armies capture, but by what governments can continue to afford. Ukraine appears increasingly determined to test that proposition against Russia’s oil industry.
On October 15, Ukrainian drones struck a refinery in Russia’s Ryazan region, roughly 300 kilometres southeast of Moscow. The attack followed a short-lived pause in strikes on energy infrastructure, which Kyiv said it had observed despite continued Russian attacks. The Associated Press reported that Russian authorities acknowledged the strike, while Reuters documented its growing diplomatic significance.
The episode illustrates an uncomfortable reality for Moscow: Russia’s enormous geographical depth no longer guarantees the security of its industrial heartland.
But it also reveals Ukraine’s dilemma. The more effectively Kyiv disrupts Russian refining, the more it risks upsetting international petroleum markets and frustrating governments anxious about fuel prices.
The distinction matters. Ukraine is not physically destroying Russia’s vast underground oil reserves. Its campaign primarily targets the infrastructure that transforms crude into usable fuels, stores petroleum products and moves energy supplies.
Ukraine’s strategic achievement will therefore not be measured by the number of refineries hit, but by whether their disruption changes Russia’s capacity and willingness to continue the war.
That is a much more demanding test.
Why Oil Remains Central to Russia’s War Economy
Russia’s dependence on hydrocarbons is one of the enduring contradictions of its geopolitical position.
Energy exports provide Moscow with international revenues, fiscal resources and relationships with countries that have declined to join Western sanctions. At the same time, the concentration of valuable industrial facilities creates vulnerabilities that military spending alone cannot eliminate.
The scale of the industry is considerable. According to a September 2026 International Energy Agency assessment, Russia operates 32 major refineries with approximately 6.5 million barrels per day of installed processing capacity.
Yet the country’s oil wealth is not interchangeable with its refining capacity.
A barrel of crude underground is a geological resource. A barrel extracted is a marketable commodity. A barrel refined into diesel, aviation fuel or gasoline serves a different economic purpose.
Disrupting one stage does not automatically eliminate the others.
That distinction becomes especially important when considering the Russian treasury.
On October 15, Reuters calculated that Russian federal oil and gas tax receipts were expected to reach approximately one trillion roubles in October, an increase of 10 percent from a year earlier.
The projected rise largely reflected scheduled tax payments, while elevated global petroleum prices provided further support.
Yet Reuters also estimated that cumulative oil and gas revenue from January through October would be 14 percent lower than in the corresponding period of 2025.
The apparently contradictory figures point to a central challenge in evaluating Ukraine’s campaign: Russia can suffer industrial losses while still collecting substantial revenues.
A financially strained war economy is not necessarily a financially defeated one.
Ukraine’s Drone Campaign Is Changing the Industrial Battlefield
The expansion of Ukraine’s long-range drone operations represents one of the war’s most consequential technological developments.
For a country facing an adversary with substantially greater territory, industrial resources and conventional military power, relatively inexpensive unmanned aircraft offer a means of imposing costs far beyond the immediate battlefield.
The consequences are increasingly measurable.
The IEA’s September analysis found that Russian refinery throughput fell to approximately 3.8 million barrels per day in June 2026, roughly 30 percent below its level a year earlier and the lowest in more than two decades.
Reported gasoline output had declined by about 20 percent compared with 2025 levels, while estimated diesel production was down nearly 30 percent.
The agency also reported that a Russian refinery was struck, on average, once every three days during the first eight months of 2026.
These findings from the IEA’s detailed refinery assessment are important because they describe an increasingly persistent problem rather than a collection of isolated attacks.
There is a difference between damaging an installation and repeatedly preventing it from operating normally.
When refineries are forced into recurring cycles of shutdown, repair and restart, the economic burden extends beyond lost fuel production. Maintenance schedules become unreliable, replacement equipment becomes more valuable, and operators must devote greater resources to protection.
The IEA reports that damage to complex secondary processing units can require six to eight months to repair, compared with considerably shorter periods for some less complicated refinery equipment.
The effects of such damage are not necessarily limited to the individual facility. Even if Russia can continue extracting and exporting crude, its ability to supply refined petroleum products domestically and internationally may deteriorate.
This helps explain why Moscow has repeatedly restricted fuel exports in an effort to preserve domestic supplies.
The tactical appeal to Ukraine is evident: sustained disruption can force Russia to defend industrial assets hundreds or even thousands of kilometres from the front.
As the Center for Strategic and International Studies has argued, the conflict increasingly involves competing strategies of long-range attrition, with Ukraine seeking to expose Russian economic vulnerabilities while Moscow continues to attack Ukraine’s infrastructure.
Neither side can assume that success against infrastructure automatically produces success in negotiations.
The Problem With Trying to Bankrupt an Oil Power
The economic logic of Ukraine’s strategy is powerful, but its limitations are frequently underestimated.
It is tempting to assume that every damaged Russian refinery represents a proportional reduction in Moscow’s ability to finance its military operations.
Oil markets do not operate so conveniently.
Consider three separate effects.
First, reduced refining capacity can diminish Russia’s production of diesel, gasoline and aviation fuel, creating domestic shortages and reducing the availability of exportable petroleum products.
Second, Moscow may attempt to redirect some crude that can no longer be processed domestically toward international buyers, provided extraction, storage, transport and export capacity allow it.
Third, disruptions to global petroleum supplies may increase prices, helping Russia earn more on barrels it continues to sell.
The third possibility is particularly uncomfortable for those hoping that infrastructure attacks will rapidly exhaust Russia’s finances.
If world prices rise sufficiently, a producer can sometimes earn more from fewer exported barrels. The outcome depends on discounts, freight costs, sanctions, taxes, volumes and buyers’ willingness to continue trading.
Russia’s ability to take advantage of that mechanism is constrained, however.
On October 13, Reuters reported that shipping costs for Russian Urals crude from western ports to India had reached record levels. Some one-way voyages from the Black Sea were costing between $27 million and $30 million, compared with about $19 million in September.
Those costs illustrate another source of pressure on Moscow: high oil prices do not necessarily translate into equally high net export earnings.
Still, the distinction between damage to refining assets and losses to government finances must remain at the center of the argument.
The decisive economic question is not how much refining capacity Ukraine can temporarily disable, but how much sustained revenue, productive capacity and strategic flexibility Russia ultimately loses.
An effective assessment would track refinery throughput, petroleum-product exports, repair durations, crude export volumes, domestic fuel availability, tax receipts and transport costs over several months.
Judged against those measures, the campaign has already imposed meaningful disruption. It has not yet demonstrated that energy strikes alone can force an end to Russia’s military campaign.
The Global Energy Dilemma: When Pressure on Russia Hurts Everyone
Ukraine’s oil strategy now operates within a global energy market already destabilized by conflict in the Middle East.
The IEA’s October 2026 Oil Market Report described severe pressure on diesel markets as disruptions in Russian and Middle Eastern supplies compounded one another.
The agency reported that global diesel exports in September were approximately 700,000 barrels per day lower than a year earlier.
That decline cannot be attributed entirely to Ukraine’s strikes. Middle Eastern disruptions, shipping constraints and refinery problems elsewhere have played major roles.
Indeed, this distinction is essential to understanding the diplomatic controversy.
Some political leaders may find it expedient to blame expensive fuel on Ukrainian attacks. But the market evidence points to multiple interacting causes rather than a single campaign.
The wider economic consequences are substantial.
Diesel powers freight transport, agricultural equipment, construction machinery and important industrial activities. When it becomes scarce or expensive, the effects spread into food prices, business costs and household budgets.
Oil-importing economies are particularly vulnerable. Countries with limited fiscal capacity may struggle to protect consumers from sustained increases in fuel prices.
The geopolitical consequences also reach India and China, major destinations for Russian crude exports.
For New Delhi, access to Russian petroleum must be balanced against international sanctions exposure, shipping costs and domestic energy security. Beijing similarly has commercial incentives to maintain supply diversity while avoiding excessive dependence on any single geopolitical relationship.
These countries are not merely observers of Ukraine’s campaign. Their purchasing decisions influence how effectively economic pressure on Russia can be sustained.
Europe faces its own dilemma: maintaining support for Ukraine while controlling energy costs that can weaken industrial competitiveness and political confidence.
For Kyiv, the danger is that the success of its operations may become an argument used by others to restrain them.
A strategy designed to increase Russia’s economic pain could also create political pressure on Ukraine if its perceived contribution to global fuel scarcity becomes substantial.
That does not automatically make the strategy misguided. It means its economic effects must be judged globally, not only within Russia.
Washington’s Changing Position Complicates Kyiv’s Calculations
The most immediate strategic risk may not lie in Russian retaliation, but in the uncertain position of the United States.
The October 2026 controversy over refinery strikes has exposed the extent to which energy policy and diplomacy are becoming intertwined.
President Donald Trump has criticized Ukraine’s renewed attacks on Russian refineries and sought arrangements to increase Russian diesel supplies.
The Financial Times reported Zelenskyy’s rejection of pressure to abandon the campaign, while Reuters on October 17 detailed the broader deterioration in relations between Washington and Kyiv.
The dispute extends beyond rhetoric.
Ukraine remains dependent on external military equipment, intelligence cooperation and technological systems. Diplomatic confrontation with a major security partner therefore carries practical risks.
On October 18, Reuters reported that U.S. Secretary of State Marco Rubio had outlined a period of up to 60 days for reviewing the economic implications of Russia-related sanctions and tariffs temporarily waived by Washington.
The same report discussed a separate arrangement intended to increase Russian diesel supplies to international markets.
For Ukraine, these developments create a paradox.
Kyiv is trying to raise the economic cost of Russia’s invasion at a moment when Washington is seeking additional Russian fuel supplies to relieve market pressure.
Europe’s willingness to maintain sanctions, financial assistance and military support consequently becomes even more important.
Yet Ukraine should not confuse political frustration with strategic independence.
An effective campaign must consider not only what can be damaged inside Russia, but also what diplomatic support could be endangered outside it.
The objective should be to preserve the greatest possible pressure on Moscow while maintaining the international coalition necessary to sustain Ukraine’s defense.
That requires political judgment as well as military capability.
The Question of Legality and Civilian Harm
Any serious examination of energy warfare must confront a question that strategic calculations often neglect: when does an industrial facility become a lawful military target?
The answer is not that every installation contributing economically to an enemy state may automatically be attacked.
Under international humanitarian law, civilian objects are protected unless they qualify as military objectives under the applicable rules.
The International Committee of the Red Cross explains that a facility’s contribution to an adversary’s general economic strength is not, by itself, sufficient to establish that it is a lawful military target.
A specific facility must make an effective contribution to military action, and its destruction, capture or neutralization must offer a definite military advantage in the circumstances.
Even when infrastructure qualifies as a military objective, the rules governing distinction, proportionality and precautions remain applicable.
Refineries and fuel depots may have both civilian and military functions. Their legal status cannot therefore be determined simply by describing them as components of the Russian economy.
The foreseeable effects on workers, nearby communities and essential civilian services must also be considered.
Oil facilities carry environmental hazards that can extend beyond the immediate site of an attack. Fires, spills and contamination may create consequences lasting much longer than the military operation itself.
The ICRC’s guidance on the environment and warfare emphasizes that environmental harm is relevant to the legal assessment of military operations.
These principles must apply consistently.
Russia’s long-running attacks on Ukraine’s electricity and heating infrastructure have exposed civilians to severe humanitarian risks. Kyiv’s own operations must nevertheless be assessed under the same applicable humanitarian protections.
On October 18, Zelenskyy alleged that Russian forces had attacked Ukraine’s energy and oil-and-gas sectors 76 times in the preceding week, according to Reuters. The figure was presented as the Ukrainian president’s account, not as an independently established count.
Russia’s responsibility for launching the full-scale invasion in 2022 remains a fundamental part of the conflict’s context. But that responsibility does not eliminate the legal obligations governing individual attacks by either belligerent.
Ukraine’s international standing is strengthened, not weakened, when its military strategy is accompanied by a credible commitment to civilian protection.
Why Even Successful Strikes May Not Produce a Strategic Breakthrough
Ukraine’s approach contains an understandable assumption: economic pressure can alter the incentives of a government engaged in a prolonged war.
History suggests that such pressure can matter. It does not establish that disruption will necessarily bring concessions.
Authoritarian governments may shift economic burdens onto households, ration scarce supplies, redirect resources from civilian consumption and suppress political opposition.
Russia also retains considerable adaptation capacity.
The IEA reports that Russian refiners have responded to repeated damage through accelerated repairs, postponed maintenance and the reactivation of idle processing equipment.
Sanctions may complicate the replacement of specialized machinery, but they do not make all repairs impossible.
Nor does public inconvenience necessarily translate into political opposition capable of changing Kremlin decisions.
There is another complication: Ukraine itself is acutely vulnerable to energy disruption.
According to Reuters reporting on October 12, the country relies almost entirely on imported fuel because its own refineries have been destroyed or seriously damaged during the war.
Logistical difficulties, rising prices and interruptions to transport routes have consequently created additional risks for Ukraine’s domestic diesel supplies.
The result is a conflict in which both countries are attempting to impose costs on the other’s energy system while remaining vulnerable to the same international markets.
An energy truce could, in principle, reduce those mutual losses. But it would require credible commitments, verification and enforcement mechanisms.
As a recent CSIS assessment examines, the effectiveness of reciprocal restraint depends on the broader military and bargaining environment.
A ceasefire that removes Ukraine’s leverage while leaving Russian attacks or other coercive capabilities intact would be strategically unbalanced.
Equally, an unlimited campaign of mutual infrastructure destruction could deepen civilian suffering without bringing either side closer to a negotiated settlement.
A sustainable strategy must therefore be capable of both imposing costs and supporting diplomacy.
The Real Test: Converting Disruption Into Leverage
Ukraine’s attacks on Russian oil facilities have demonstrated an important reality: even a major energy power cannot assume that its industrial infrastructure is insulated from a technologically adaptable opponent.
Russia’s refineries are under pressure. Domestic fuel supplies have been disrupted. Repair and protection costs are rising. Moscow is being forced to devote attention and resources to threats far from the conventional front.
Ukraine does not need to exhaust Russia’s oil reserves to expose the vulnerabilities of its war economy. But it does need to turn temporary disruption into durable strategic advantage.
These are genuine strategic gains.
But Ukraine should resist the illusion that economic warfare offers a rapid substitute for military endurance, effective sanctions, dependable alliances or a credible diplomatic settlement.
The most effective approach would combine pressure on militarily relevant energy infrastructure with international economic restrictions, careful monitoring of Russia’s fiscal condition and sustained diplomatic coordination.
Success should be measured against a clear standard: whether the campaign reduces Moscow’s ability to sustain aggression and improves Ukraine’s prospects for a secure peace.
If disruption merely rearranges Russian export flows while high oil prices protect Kremlin revenues, the strategic gains may prove smaller than the physical damage suggests.
If, however, sustained attacks increase repair costs, constrain critical fuel supplies, reduce Russia’s net energy earnings and reinforce international diplomatic pressure, the cumulative effect could become significant.
The danger is mistaking the visibility of an explosion for the permanence of an economic loss.
That is the difference between attacking an industry and changing the course of a war.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Economic Costs of Wars
Ceasefire Negotiations in 2026: Predicting the Rebound of European and Asian Economies
Key Takeaways
- The European Commission has already cut its 2026 eurozone growth forecast to 0.9% (from 1.2%) and raised inflation projections to 3.0%, directly citing the Middle East war’s energy shock — with a full rebound contingent on how quickly, and how durably, any ceasefire holds.
- The ECB has laid out an explicit scenario split: its June 2026 baseline assumes gradual de-escalation and sees growth reaching 1.3% in 2027, while an adverse scenario with oil peaking near $180/barrel would roughly halve projected 2026 growth and push inflation 1.1 percentage points higher in 2027.
- Historical ceasefire episodes from earlier in 2026 show Asian markets — Japan’s Nikkei, South Korea’s Kospi — rallying 5%+ in single sessions on de-escalation headlines, only to reverse sharply when agreements broke down within days to weeks.
- As of mid-September 2026, no ceasefire is currently in place — the conflict has escalated rather than eased this month — meaning both the EU’s baseline and adverse scenarios remain live possibilities rather than settled outcomes.
- The World Bank’s April 2026 regional outlook shows the MENAAP region absorbing the sharpest growth downgrade of any global region, while South Asia remains comparatively resilient — illustrating how unevenly any eventual rebound would likely be distributed.
Every economic forecasting body tracking the global economy in 2026 — the European Commission, the ECB, the World Bank — has built its projections around the same fundamental uncertainty: nobody knows exactly when, or how durably, the US-Iran war will end. This piece works through what the major institutions’ own published scenarios say about how European and Asian economies would actually rebound once a ceasefire holds, and how sharply those forecasts diverge from what’s likely if the conflict instead drags on.
Europe’s Baseline vs. Adverse Scenario
The European Commission’s most recent forecast, published in May 2026, cut its eurozone 2026 growth projection to 0.9%, down from an earlier 1.2% estimate, while raising expected inflation to 3.0% — well above the ECB’s 2% target. EU economy chief Valdis Dombrovskis attributed the downgrade directly to the Middle East conflict, which he said “triggered a major energy shock, further testing Europe as it navigates an already volatile geopolitical and trade environment.”
Critically, the Commission built its forecast around two explicit scenarios. The baseline assumes energy prices gradually normalize as the conflict eases — even accounting for a “fragile ceasefire” that was in place at the time of the forecast’s cutoff date (though the Strait of Hormuz remained effectively closed even under that truce). The adverse scenario assumes oil prices continue climbing toward $180 per barrel by year-end; under that path, the Commission estimated inflation would run 0.3 percentage points higher in 2026 and a full 1.1 percentage points higher in 2027, while growth would come in at roughly half the baseline forecast.
The ECB has published its own parallel scenario work. Its June 2026 projections put baseline euro-area growth at 0.9% in 2026, improving to 1.3% in 2027 and 1.4% in 2028 — a “downward revision, especially for 2026,” reflecting what the ECB explicitly called “the global effects of the war on commodity markets, real incomes and confidence.” By September, more recent ECB commentary noted the euro area economy was proving “more resilient than expected” to the shock, supported by domestic demand, a robust labour market, and AI-related investment — suggesting some of the earlier worst-case assumptions may not be fully materializing, even without a durable ceasefire yet in place.
Asia’s Pattern: Sharp Rallies, Sharper Reversals
Asian equity markets have shown a far more volatile, headline-driven relationship with ceasefire news than Europe’s more gradual, forecast-revision-based response. When the US and Iran announced a framework agreement to end hostilities in June 2026, Japan’s Nikkei 225 surged 5.5% in a single morning session, South Korea’s Kospi jumped as much as 5.7%, and Taiwan’s Taiex climbed 2.7%. A separate ceasefire announcement in April 2026 produced a similar pattern: the Nasdaq 100 rose nearly 3% while Japan and Korea posted comparable Asia-Pacific gains.
In both cases, the rallies proved short-lived. The April ceasefire unraveled within roughly two weeks amid mutual accusations of violations, and by early September 2026, fighting had resumed in earnest, with oil prices climbing back above $107 per barrel and diesel approaching a record $6 per gallon in the US. This pattern — sharp, headline-driven Asian equity rallies followed by reversal once agreements prove unstable — has now repeated at least three times in 2026, a track record worth weighing heavily against any future ceasefire headline.
Scenario Comparison Table
| Scenario | Eurozone 2026 Growth | Eurozone Inflation | Asian Equity Pattern |
|---|---|---|---|
| EU baseline (gradual de-escalation) | 0.9% | 3.0% | Gradual stabilization |
| EU adverse (oil to $180/bbl, prolonged conflict) | ~0.4-0.5% (roughly half baseline) | +1.1pp above baseline by 2027 | Continued volatility, no durable rally |
| Historical pattern: ceasefire announcement | N/A (US/Euro-specific) | N/A | Nikkei/Kospi +5%+ single session |
| Historical pattern: ceasefire collapse | N/A | N/A | Reversal within 1-3 weeks |
The Uneven Regional Picture
Not every region would rebound equally even in the optimistic baseline scenario. The World Bank’s April 2026 regional economic update found that, excluding Iran itself, the broader MENAAP region’s growth is expected to slow from 4.0% in 2025 to just 1.8% in 2026 — the sharpest downgrade of any region the Bank tracks. By contrast, the Bank’s July 2026 Global Economic Prospects report identifies South Asia as remaining the fastest-growing region globally despite the conflict, with the Bank explicitly noting that regional impacts differ based on each economy’s energy exposure, strategic reserves, and available policy buffers — meaning net energy importers without deep reserves face a structurally slower rebound path than better-insulated economies even after any ceasefire takes hold.
Why This Matters: Treat Ceasefire Headlines as Scenario Triggers, Not Resolutions
For investors and businesses trying to plan around the global economy’s trajectory, the most useful framework isn’t predicting exactly when a ceasefire arrives — it’s understanding which of the major institutions’ published scenarios that ceasefire would activate. A durable, Hormuz-reopening ceasefire would plausibly validate the EU Commission and ECB’s baseline growth and inflation paths, alongside a genuine (rather than headline-driven) Asian equity rebound. A fragile, easily-reversed truce — the pattern seen three times already in 2026 — would instead simply reset the clock on the adverse scenario, with markets likely repeating the same rally-then-reversal cycle that has defined 2026 so far. Given that no ceasefire is currently in place as of mid-September, and given the specific track record of the last three attempts, the adverse-scenario framework remains the more probable near-term base case.
Frequently Asked Questions
How would a Middle East ceasefire affect European economic growth?
Under the European Commission’s baseline scenario, a durable de-escalation would support eurozone growth around 0.9% in 2026, improving further in 2027. A prolonged conflict instead risks roughly halving that growth figure, per the Commission’s own adverse scenario.
Do Asian stock markets typically rally on ceasefire news?
Yes, historically sharply — Japan’s Nikkei and South Korea’s Kospi have both surged 5%+ in single sessions following prior 2026 ceasefire announcements, but those rallies have reversed within one to three weeks each time the agreements subsequently broke down.
Which regions would benefit most from a durable ceasefire?
The World Bank identifies the MENAAP region (Middle East, North Africa, Afghanistan, Pakistan) as having absorbed the sharpest 2026 growth downgrade, meaning it stands to see the largest relative rebound from a durable ceasefire, while South Asia has remained comparatively resilient throughout the conflict.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Democrats Won Congress. Can They Fix the U.S. Economy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025