
Asia
The Great Singapore Disinflation: Why MAS Will Stand Firm as a Global Storm Abates

Singapore’s core inflation fell to 0.7% in 2025. With price pressures receding, the MAS is expected to hold policy steady in January 2026, marking a new phase for the city-state’s economy.
The late afternoon sun slants through the canopy of the Tiong Bahru Market hawker centre, glinting off stainless steel steamers and the well-worn handles of kopi cups. Here, at the heart of Singapore’s quotidien life, the most consequential economic conversation of the year is being had, not in the jargon of central bankers, but in the simple calculus of daily purchases. An auntie considers the price of char siew before ordering; a taxi driver compares the cost of his teh tarik to last year’s. For the first time in nearly half a decade, that mental math is bringing a faint, collective sigh of relief. The fever of inflation—which spiked to a 14-year high in 2023—has broken. The Monetary Authority of Singapore (MAS), the nation’s powerful central bank, now faces a delicate new reality: not of battling runaway prices, but of navigating a return to profound price stability in a world still rife with uncertainty.
On January 29, 2026, the MAS will release its first semi-annual monetary policy statement of the year. All signs, confirmed by the latest data from the Singapore Department of Statistics (SingStat), point to a unanimous decision: the central bank will keep its exchange rate-centered policy settings unchanged. The full-year data for 2025 is now in, and it tells a story of remarkable disinflation. Core Inflation—the MAS’s preferred gauge, which excludes private transport and accommodation costs—came in at 0.7% for 2025, a dramatic decline from 2.8% in 2024 and 4.2% in 2023.

Headline inflation for the year was 0.9%. December’s figures showed both core and headline inflation holding steady at 1.2% year-on-year, indicating a stable plateau as the economy adjusts to a post-shock norm. This outcome, while slightly above the government’s earlier 2025 forecast of 0.5%, underscores a victory in the battle against imported global inflation. Economists widely anticipate that alongside its stand-pat decision, the MAS and the Ministry of Trade and Industry (MTI) will revise the official 2026 inflation forecast range upward, from the current 0.5–1.5% to a likely 1–2%. This adjustment would not signal a new tightening impulse, but rather a recognition of stabilizing domestic price pressures and base effects, framing a modestly more hawkish guardrail for the year ahead.
The Data Unpacked: A Return to Pre-Pandemic Normality
To appreciate the significance of the 0.7% core inflation print, one must view it through the corrective lens of recent history. Singapore, as a miniscule, trade-reliant economy, is a hyper-sensitive barometer of global price pressures. The supply-chain cataclysm of 2021-2022 and the energy shock following Russia’s invasion of Ukraine were transmitted directly into its domestic cost structure, amplified by robust post-pandemic domestic demand.
Table: Singapore Core Inflation (CPI-All Items ex. OOA & Private Road Transport)
| Year | Core Inflation Rate (%) | Key Driver |
|---|---|---|
| 2022 | 4.1 | Broad-based imported & domestic cost pressures |
| 2023 | 4.2 | Peak passthrough, tight labour market |
| 2024 | 2.8 | MAS tightening, global disinflation begins |
| 2025 | 0.7 | Sustained MAS policy, falling import costs |
| 2026F | 1.0 – 2.0 | Stabilising domestic wages, moderated global decline |
The journey down from the peak has been methodical, reflecting the calibrated tightening by the MAS. Since October 2021, the authority had undertaken five consecutive rounds of tightening, primarily by adjusting the slope, mid-point, and width of the Singapore Dollar Nominal Effective Exchange Rate (S$NEER) policy band. This unique framework, which uses the exchange rate as its primary tool, effectively imported disinflation by strengthening the Singapore dollar, making imports cheaper in local currency terms. The decision to pause this tightening cycle in July 2024 was the first signal that the worst was over.
The 2025 disinflation was broad-based. Key contributors included:
- Food Inflation: Eased significantly from 3.8% in 2024 to an average of 1.8% in 2025, as global supply chains normalized and commodity prices softened.
- Retail & Other Goods: Inflation turned negative in several quarters, reflecting lower imported goods prices and weaker discretionary spending.
- Services Inflation: Moderated but remained stickier, a testament to persistent domestic wage pressures in a tight labour market. However, even here, the pace decelerated markedly by year-end.
The slight overshoot of the 0.7% outcome relative to the official 0.5% forecast is statistically marginal but analytically noteworthy. It likely reflects the residual stickiness in domestic services costs and perhaps a firmer-than-anticipated trajectory for accommodation costs, which are excluded from the core measure but feed into overall economic sentiment.
The MAS Mandate in a New Phase: Vigilance Over Volatility
The MAS operates under a singular mandate: to ensure price stability conducive to sustainable economic growth. Unlike most central banks, it does not set an interest rate but manages the S$NEER. The current expectation of an unchanged policy stance is a statement of confidence that the existing level of the currency’s strength is sufficient to keep imported disinflation flowing while guarding against any premature loosening of financial conditions.
“The current rate of appreciation of the S$NEER policy band is sufficient to ensure medium-term price stability,” the MAS stated in its October 2025 review. The latest inflation data validates this assessment. Holding the policy band steady now achieves two objectives:
- It Anchors Expectations: It signals to businesses and unions that the central bank sees no need for further tightening, but is equally not prepared to risk its hard-won credibility by easing policy while core inflation, though low, is expected to rise modestly through 2026.
- It Provides a Buffer: A stable, moderately strong Singapore dollar acts as a shock absorber against potential renewed volatility in global energy and food prices, which remain susceptible to geopolitical flare-ups.
The anticipated upward revision of the 2026 forecast range to 1–2% is the key nuance in this meeting. This is not a hawkish pivot, but a realistic recalibration. It acknowledges several forward-looking dynamics:
- Base Effects: The very low inflation in late 2024 and early 2025 will create less favourable base effects for year-on-year comparisons in late 2026.
- Domestic Cost Pressures: Wage growth, while moderating, is expected to remain above pre-pandemic trends, supported by structural tightness in the local labour market and ongoing initiatives like the Progressive Wage Model.
- Policy-Driven Price Increases: The scheduled 1%-point GST increase to 10% in January 2026 will impart a one-time upward push to price levels, which the MAS will look through but must account for in its communications.
The Global and Comparative Lens: Singapore as a Bellwether
Singapore’s disinflation narrative is not occurring in a vacuum. It mirrors, and in some respects leads, trends in other small, advanced, open economies. A comparative view is instructive:
- Switzerland: Like Singapore, Switzerland has seen inflation return to target rapidly, aided by a strong currency (the Swiss Franc) and direct government interventions on energy prices. The Swiss National Bank has already shifted to a neutral stance, with discussions of easing emerging.
- Hong Kong: Linked to the US dollar via its currency peg, Hong Kong has had its monetary policy dictated by the Federal Reserve. Its disinflation path has been bumpier, complicated by its unique economic integration with mainland China and a slower post-pandemic recovery in domestic demand.
- New Zealand: The Reserve Bank of New Zealand has maintained a more hawkish stance, with inflation proving stickier due to a less open consumption basket and intense domestic capacity constraints. New Zealand’s cash rate remains restrictive.
Singapore’s experience stands out for the precision of its policy tool. The S$NEER framework allowed it to respond directly to the imported nature of the inflation shock. As Bloomberg Economics noted in a January 2026 analysis, “The MAS’s exchange-rate centered policy has acted as a targeted filter for global inflation, proving highly effective in the post-pandemic cycle.” This successful navigation has bolstered the authority’s international credibility and the Singapore dollar’s status as a regional safe-haven asset.
The Looming Risks: Why Complacency is Not an Option
The path to a sustained 2% inflation environment is not without its pitfalls. The MAS’s steady hand in January belies a watchful eye on several risk clouds:
- Geopolitical Supply Shocks: Any major escalation in the Middle East or renewed disruption in key trade lanes like the Straits of Malacca could trigger a sudden spike in global energy and freight costs. Singapore’s strategic petroleum reserves and diversified supply chains provide a buffer, but the inflationary impact would be swift.
- Wage-Price Spiral Precautions: The slope of Singapore’s Phillips Curve—the historical relationship between unemployment and inflation—has flattened but remains a concern. Robust wage settlements in 2026, if they significantly outstrip productivity growth, could embed inflation in the services sector, which is less sensitive to exchange rate policy.
- Global Monetary Policy Divergence: The timing and pace of interest rate cuts by the US Federal Reserve and the European Central Bank will cause significant currency and capital flow volatility. The MAS must ensure the S$NEER moves in an orderly fashion amidst this global repricing of risk.
- Climate Transition Costs: The green energy transition, while deflationary in the long term, may impose episodic cost pressures through carbon taxes, regulatory costs, and investments in new infrastructure. Singapore’s carbon tax is scheduled to rise significantly in the coming years.
As the Financial Times reported following the release of the 2025 data, analysts caution that “the last mile of disinflation—stabilising at the 2% sweet spot—is often the most treacherous.” The MAS is acutely aware that premature declarations of victory could unanchor inflation expectations.
Conclusion: The Steady Centre in a Churning World
As the hawker centre stalls begin to shutter for the evening, the economic reality they embody is one of cautious normalization. The MAS’s expected decision to hold policy unchanged is a powerful signal of this new phase. It is the policy equivalent of a skilled sailor easing the sails after successfully navigating a storm: the vessel is steady, the immediate danger has passed, but the horizon is still watched for the next shift in the wind.
The recalibration of the 2026 forecast to a 1–2% range is a masterclass in central bank communication—acknowledging progress while managing expectations upward from unsustainably low levels. It leaves the MAS with maximum optionality: it can maintain its stance through much of 2026 if inflation drifts toward the upper end of the band, but it is not locked into any pre-committed path.
For Singaporeans, the profound disinflation of 2025 offers tangible respite. For global investors and policymakers, Singapore’s trajectory serves as a compelling case study in the effective use of an unconventional monetary framework in a crisis. The nation has emerged from the global inflationary maelstrom not just with stable prices, but with reinforced confidence in the institutions that guard its economic stability. The challenge ahead is one of preservation, not conquest. And in that endeavour, a steady hand on the tiller is the most valuable tool of all.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Asian equity markets have delivered a reminder that the AI investment boom is not simply an American technology story. South Korean memory producers, Taiwanese chip manufacturers, Japanese equipment suppliers and regional exporters are connected to global capital spending on computing. That creates an opportunity when orders surge and a vulnerability when assumptions change.
A Reuters market report on October 13 described a sharp risk-off episode in technology-linked Asian shares. Subsequent Wall Street Journal coverage described a partial rebound. Those moves are best understood as a test of expectations, not as proof that regional growth has reversed.
The first link: US AI spending and Asian earnings
The global chip supply chain has multiple layers. Advanced logic semiconductors, high-bandwidth memory, equipment, materials and packaging each respond differently to investment cycles. An AI server ordered in the United States can create revenue for numerous Asian firms, while supplier earnings remain vulnerable to delays or changes in product mix.
This concentration means broad stock indices may react strongly to a relatively narrow group of companies. The movement of an index is not necessarily a reliable representation of household consumption or the local services economy. Readers should check the contribution of leading constituents before interpreting a headline percentage drop.
Korea, Taiwan and Japan have different exposures
Korea’s market has significant memory-chip exposure. Taiwan has a major role in contract semiconductor manufacturing and its suppliers. Japan combines technology-related manufacturers with banks, exporters and domestic sectors. Exchange rates can amplify or offset changes in export competitiveness and returns for foreign investors.
Currency matters especially when an investor buys shares denominated in won, Taiwan dollars or yen. Even if a local index is unchanged, the return measured in dollars can change because of foreign-exchange movements. A regional market roundup should therefore include both equity and currency context.
Interest rates and oil can overwhelm the chip narrative
The AI industry competes for capital with governments, housing and ordinary businesses. When bond yields climb, distant profits are discounted more heavily; heavily indebted firms face rising refinancing expenses. Meanwhile high energy prices can pressure importers and manufacturers even when some technology exporters remain strong.
The IMF’s October outlook highlights both AI-related opportunities and inflation, conflict and fiscal vulnerabilities. That mixed picture argues against a single “Asia is booming” or “Asia is crashing” explanation.
The danger of extrapolating one trading session
A large daily decline can reflect positioning, forced selling or an abrupt change in sentiment. A rebound can reflect bargain hunting or short covering without resolving the original valuation issue. Neither movement establishes a sustainable trend. Investors should connect price action to revisions in earnings guidance, orders and financing conditions.
Useful evidence includes export orders, manufacturing surveys, semiconductor inventories, central-bank signals and capital flows. Compare the same measures over several months and distinguish expectations from realized data.
How to follow Asian markets responsibly
Build a dashboard with major indices, local-currency performance, exchange rates, benchmark bond yields and relevant oil prices. Record dates and market closing times; an Asian close may precede major US news that influences futures later. Avoid combining prices from different sessions as though they represent the same moment.
For a long-term investor, diversification across sectors and countries matters more than guessing the next technology stock to rebound. For a news reader, the essential question is whether a market move reflects an earnings change, financing risk or only a revision to how much investors are willing to pay.
Market structure can magnify headline moves
Market-capitalization-weighted benchmarks allocate more influence to companies with high market value. As chip and platform businesses grow, their success can make an index more concentrated. During a drawdown, selling pressure in those same names may dominate the index even if the median constituent is relatively stable. Equal-weighted sector comparisons and the share of stocks advancing can help distinguish broad weakness from concentration effects. Investors should also review whether an exchange was closed for a holiday and whether a quoted movement refers to a futures contract or the cash session. Time alignment is essential when comparing Asian and US markets.
Frequently asked questions
Why do Asian markets fall when US AI stocks sell off?
Regional firms supply chips, memory and equipment to the same global investment cycle, and investors frequently adjust exposure across markets at once.
Is a rebound proof the AI bubble is over?
No. Price recoveries do not necessarily resolve doubts about future returns and financing.
Which numbers are worth monitoring?
Earnings expectations, memory prices, exports, bond yields, currencies and oil prices give a more balanced picture than an index close alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Are Asian stock markets rising in 2026?
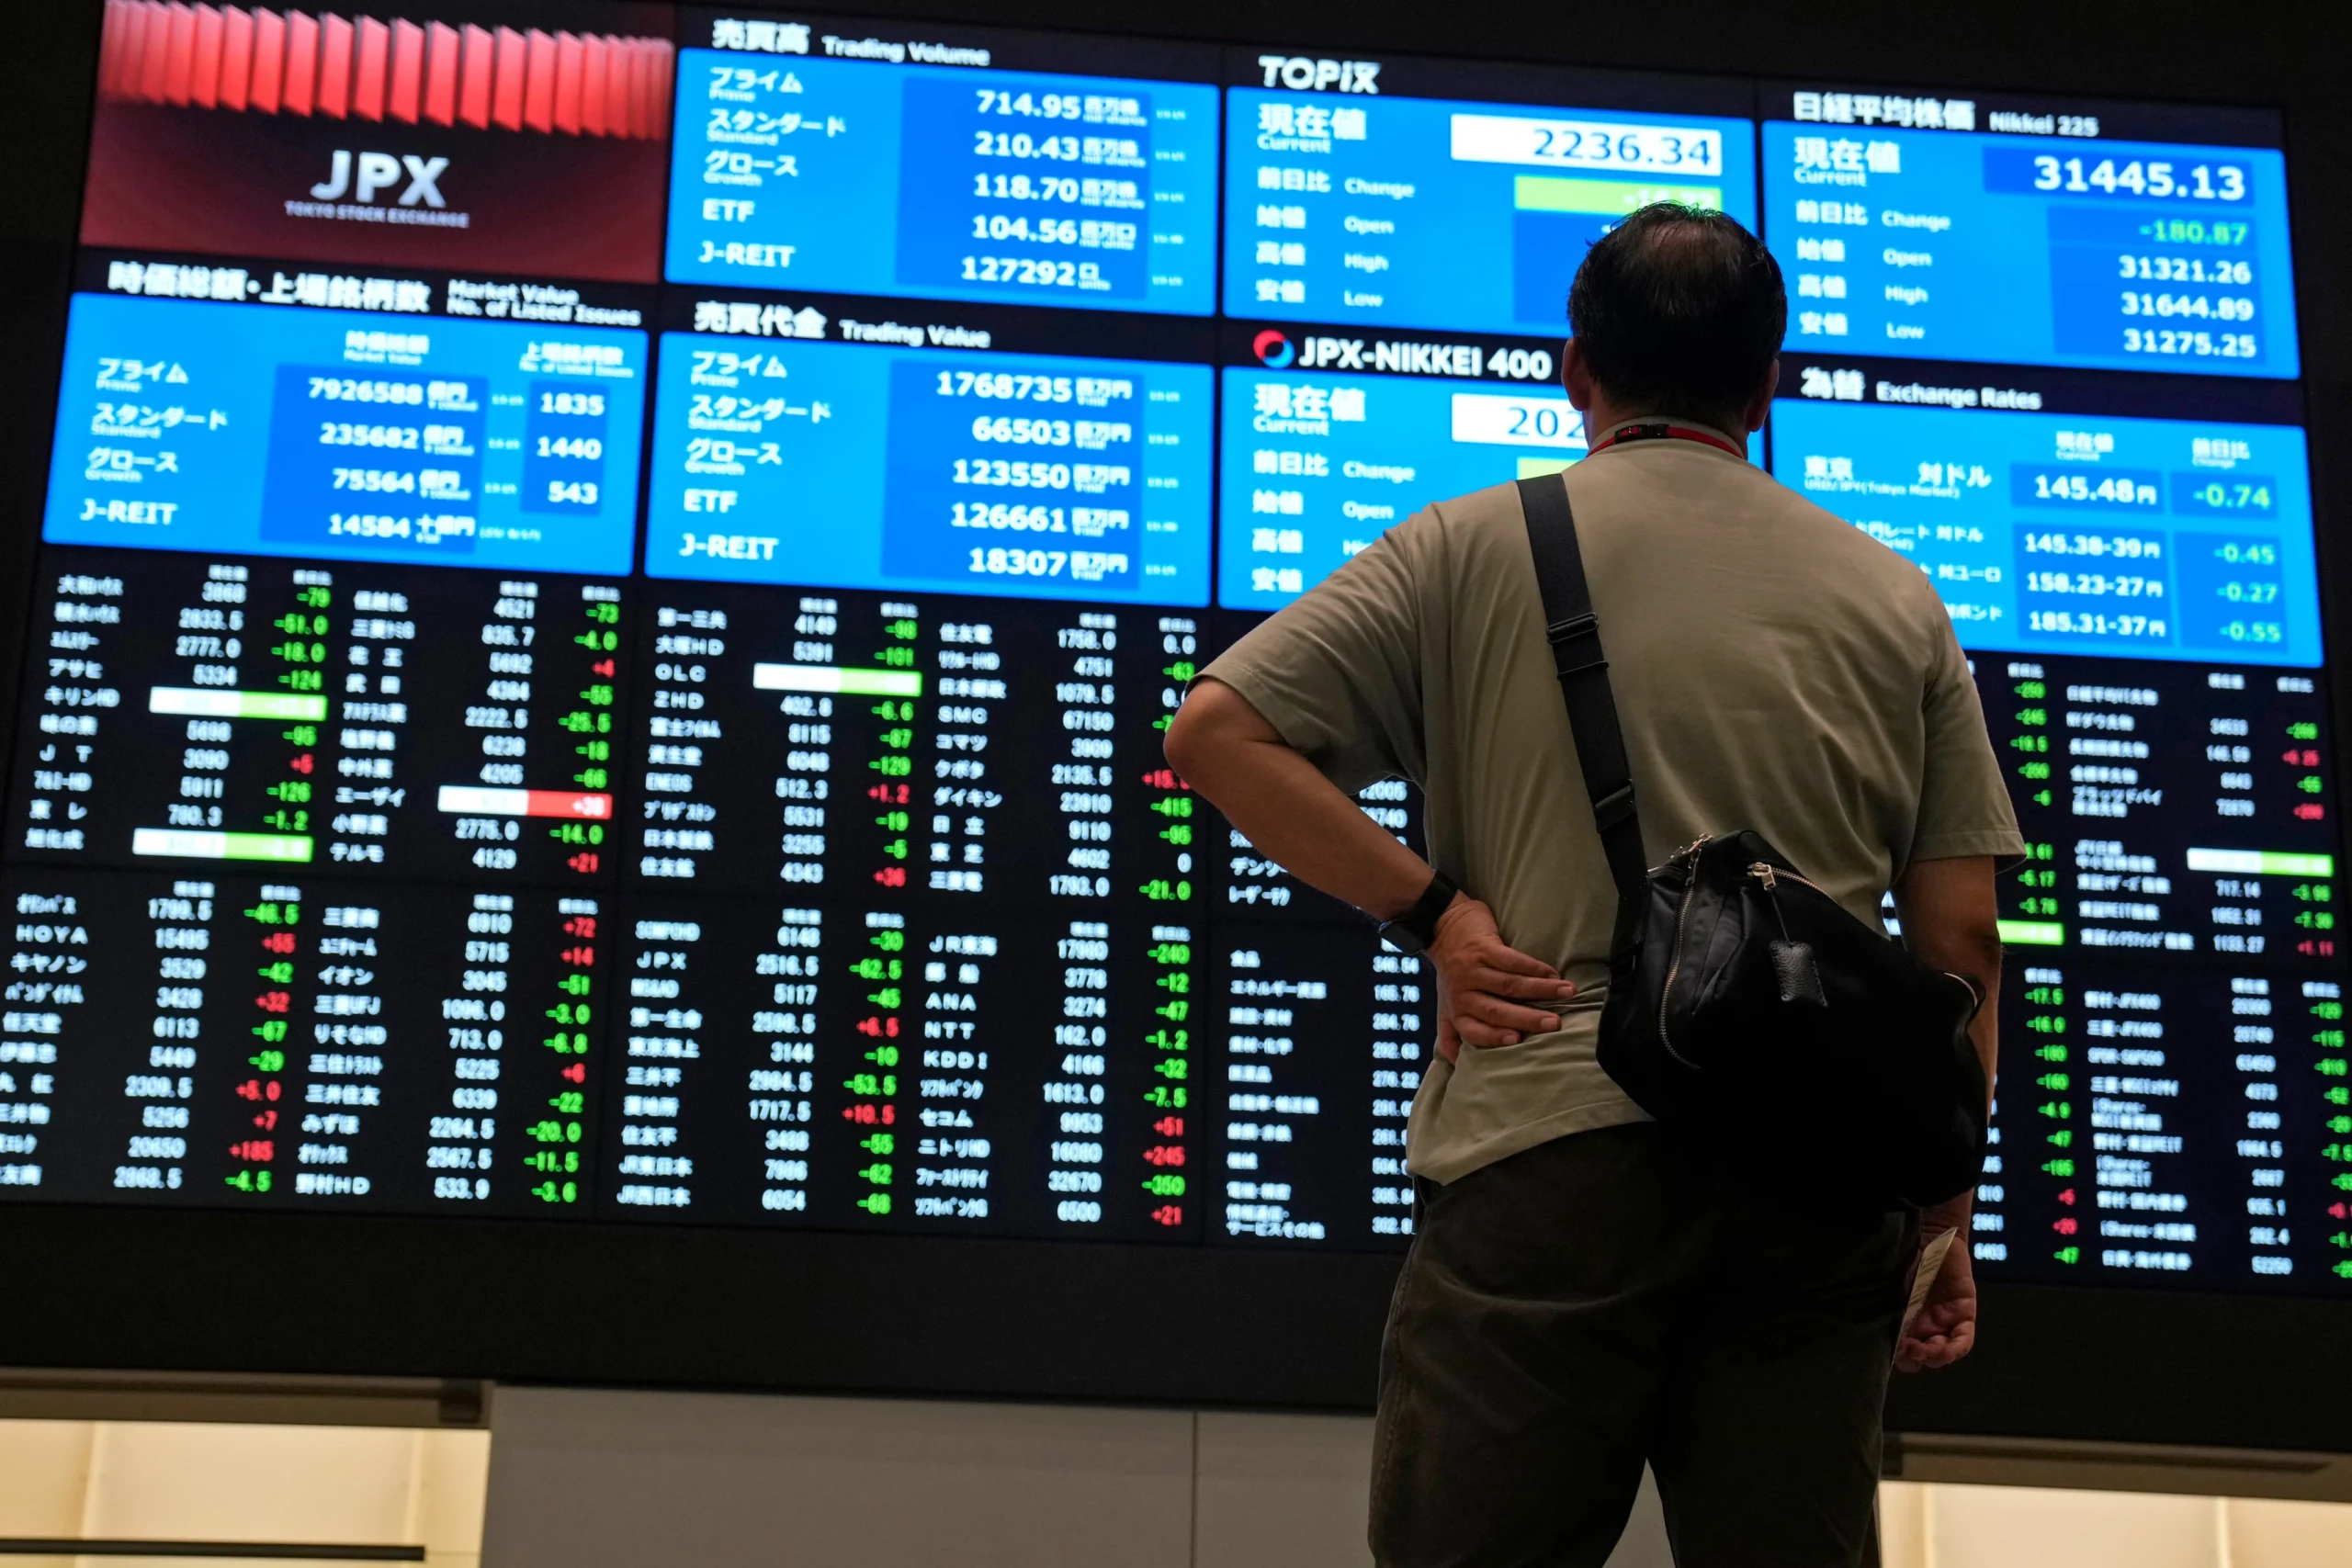
Most of them are, but for very different reasons. Japan’s Nikkei 225 is trading at levels roughly 44% higher than a year ago on continued AI-linked technology strength; China’s benchmark indices climbed to multi-year highs at the start of the year on AI optimism and signs of economic recovery; and Pakistan’s KSE-100 has been one of the most volatile large gainers globally, crossing record highs early in the year before enduring sharp single-session pullbacks in September. Understanding each market separately matters more than treating “Asia” as one trade.
Japan: A 15-Year-Plus Bull Run Meets a Hawkish Central Bank
The Nikkei 225 closed at 65,018.95 on September 18, 2026, gaining 1.38% on the session and sitting 44.34% above where it stood a year earlier, according to data compiled by Trading Economics. That move came even as the Bank of Japan raised its policy rate by 25 basis points to 1.25% — a widely expected but still consequential tightening step, as policymakers balance elevated inflation and wage growth against pressure from U.S. Treasury Secretary Scott Bessent for currency and trade cooperation. Japan’s annual inflation rate held at 1.9% in August, with core inflation at 1.7% — below the Bank of Japan’s 2% target for a seventh straight month, suggesting the central bank still has room to normalize policy gradually rather than aggressively.
Technology and AI-related names have led Japan’s rally, with chip-equipment and materials names such as Advantest and Lasertec posting some of the sharpest single-day gains, echoing similar advances on Wall Street. That correlation is a theme across the region: Asian equity performance in 2026 has tracked the U.S. AI-capex story almost as closely as it has tracked domestic fundamentals.
China: AI Optimism Meets an Overheating Warning
China’s equity markets opened 2026 on a tear. The benchmark CSI 300 Index advanced 1.6% to close at its highest level in four years on January 6, while the Shanghai Composite rose 1.5% to its strongest level since July 2015, fueled by sustained optimism over the country’s AI advances and early signs of broader economic recovery, according to Bloomberg. Materials and technology shares led the advance, and the rally coincided with a robust pipeline of onshore AI-related IPOs.
That said, the rally showed early signs of overheating even in January: the 14-day relative strength index on the Shanghai Composite climbed above 75 — firmly into technical overbought territory — a level it had not touched since the previous September. Momentum has been uneven since; by late July, the Shanghai Composite had pulled back to a 16-week low on the CSI 300 gauge even as the broader index posted modest daily gains, reflecting a market still working through the tension between AI-driven optimism and valuation discipline. On the macro side, the IMF’s own China growth revisions this year have tracked a similar push-pull, with earlier 2025 forecasts putting Chinese growth near 4.8% before moderating toward roughly 4.2% as trade and property-sector headwinds persist.
Malaysia and Singapore: Steady Gains, Regional Correlation
Malaysia’s FTSE Bursa Malaysia KLCI has spent much of 2026 grinding toward multi-year highs rather than posting dramatic single-day swings. The index touched a more-than-six-year high near 1,686 points in early January, according to New Straits Times, and by early September had climbed further to around 1,714–1,715 points, per Bursa Malaysia futures data reported by Bernama, Malaysia’s state news agency. Analysts at Rakuten Trade have described the index as being in a healthy uptrend across both short- and long-term timeframes, with pullbacks read as consolidation rather than a change in trend.
Singapore’s Straits Times Index has moved in tandem with regional sentiment through the year, trading in the high-3,900-point range during mid-2026 sessions alongside comparable moves in Hong Kong’s Hang Seng and South Korea’s Kospi — a reminder that Southeast Asian and Northeast Asian benchmarks remain tightly correlated on any given trading day, even when their underlying economic drivers differ.
Pakistan: The Region’s Most Volatile Outperformer
Featured Snippet Target: Pakistan’s KSE-100 Index began 2026 at a record high above 176,000 points, climbed further past 186,000 and 188,000 in the following days on institutional buying and expectations of a policy rate cut, but has since seen sharp single-session pullbacks — including a 3,078-point, 1.79% drop on September 10 — underscoring how the world’s best-performing frontier market in early 2026 has also been among its most volatile.
The Pakistan Stock Exchange’s rally traces back to a shift in domestic asset allocation: brokerage house Topline Securities described the move from fixed-income instruments into equities — driven by falling returns on traditional savings vehicles — as the primary fuel behind sustained liquidity and elevated valuations, according to coverage from Aaj News. Banking names including United Bank Limited, Habib Bank, and MCB, alongside energy majors like Oil and Gas Development Company, have repeatedly featured among the index’s top contributors on both up and down days.
By early September, the picture had turned choppier. The KSE-100 gained 399 points on September 4 to close at 175,328, per ARY News, before dropping over 3,000 points just days later on September 10 — a reminder that Pakistan’s rally, while historic in percentage terms, remains far more sensitive to single-session sentiment shifts than its larger regional peers.
The Cross-Market Pattern
Three threads tie these otherwise disconnected markets together in 2026. First, AI-linked capital spending is now a genuine cross-border driver — Japanese and Chinese tech names have both rallied on echoes of the same U.S. hyperscaler capex story. Second, central bank policy divergence is widening: Japan is tightening from historically ultra-loose settings, while Pakistan has been cutting rates to support a still-fragile broader economy. Third, frontier and emerging markets — Pakistan chief among them — are delivering far larger percentage swings, in both directions, than developed Asian benchmarks, rewarding investors who can tolerate volatility but punishing those who chase momentum without hedging for pullbacks.
The Bottom Line
Asia’s 2026 story is not one market but five distinct ones moving on different clocks — Japan’s AI-and-rate-hike rally, China’s optimism-versus-overheating tension, Malaysia and Singapore’s steadier regional drift, and Pakistan’s high-beta swings around a genuine structural re-rating. Anyone allocating across the region needs a market-by-market view rather than a single “Asia” thesis.
Next step: Track Bank of Japan policy meetings, China’s Politburo economic guidance sessions, and Pakistan’s State Bank Monetary Policy Committee decisions together — the three events, spaced through the remainder of 2026, are the clearest near-term catalysts for each market’s next move.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025