
Analysis
IJM Board Rejects Sunway’s RM11bn Takeover as ‘Not Fair’ — 46% Discount Exposed

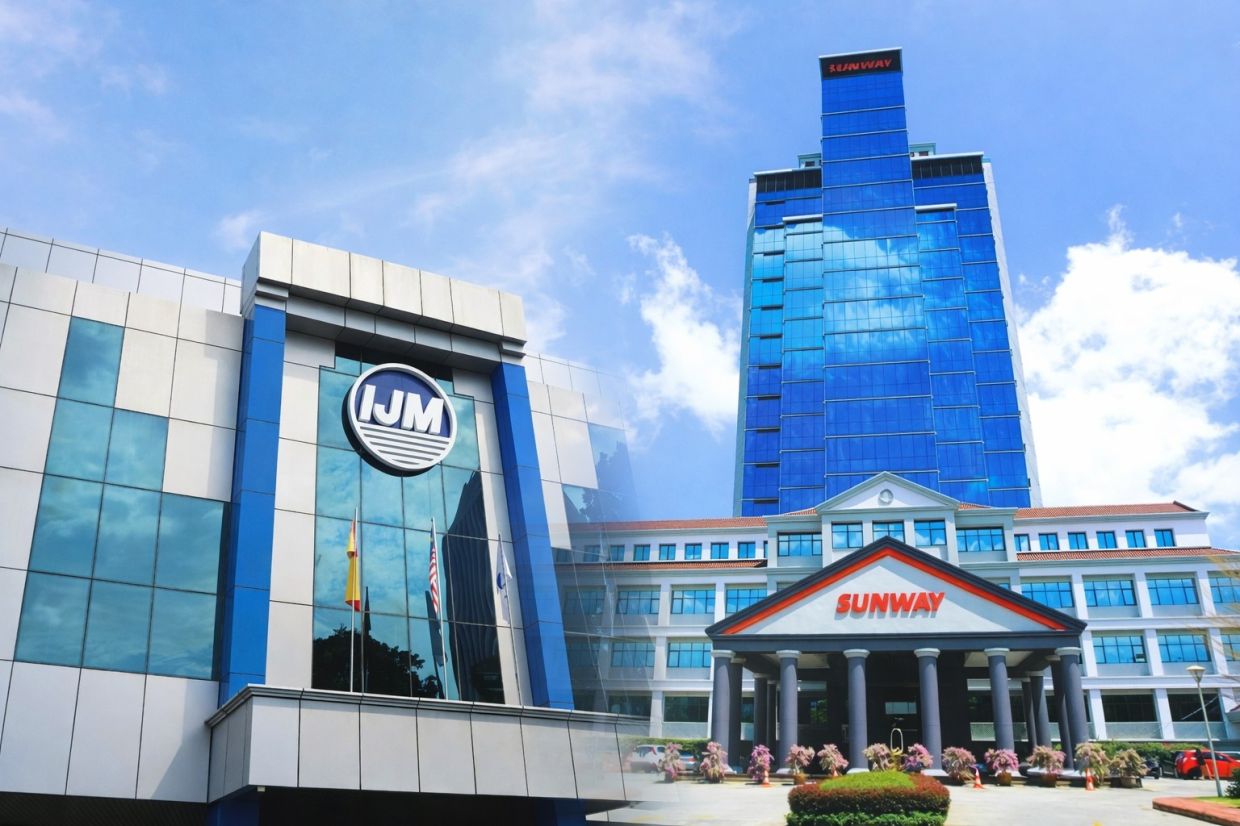
A unanimous board rejection, an independent valuation gap that beggars belief, and a political firestorm over Bumiputera rights. Malaysia’s biggest corporate drama of 2026 just reached its watershed moment.
Somewhere between the glass towers of Kuala Lumpur’s financial district and the legal filing rooms of Bursa Malaysia’s exchange, a RM11 billion gambit unravelled in slow motion on Friday. IJM Corporation Bhd’s board unanimously recommended that shareholders reject Sunway Bhd’s conditional voluntary takeover offer of RM3.15 per share, after appointed independent adviser M&A Securities declared the bid “not fair and not reasonable.” Free Malaysia Today The language was clinical. The implications were seismic.
M&A Securities found the offer price represents a discount of between RM2.69 and RM3.33 per share — roughly 46.1% to 51.4% below IJM’s estimated sum-of-parts value Scoop of between RM5.84 and RM6.48 per share. In plain English: Sunway’s opening bid, dressed up as a transformational merger, was asking IJM shareholders to surrender a blue-chip Malaysian conglomerate at roughly half its independently assessed worth. For a deal this size, that is not a negotiating discount. That is a devaluation.
The IJM Sunway takeover rejection now stands as one of the most decisive and well-reasoned rebuffs in Malaysian corporate history — a verdict that reverberates across ASEAN boardrooms, foreign investor portfolios, and the charged political terrain of Bumiputera economic policy.
How the RM11 Billion Bid Was Born — and Why It Was Always Controversial
The origins of this Malaysia construction takeover 2026 saga trace back to 12 January, when Sunway Bhd tabled a conditional voluntary offer to acquire all 3.51 billion outstanding shares in IJM Corp at RM3.15 per share — a total consideration of RM11.04 billion, structured as 10% cash (RM0.315 per share) and 90% via new Sunway shares valued at RM2.835 each, based on an issue price of RM5.65 per new Sunway share. BusinessToday
On paper, the rationale was compelling. A combined Sunway-IJM entity would create Malaysia’s largest integrated property-construction conglomerate, able to compete on a genuinely ASEAN scale at a moment when regional infrastructure spending is entering a multi-decade supercycle. Sunway’s founder and executive chairman, Tan Sri Jeffrey Cheah, framed the deal as a nation-building exercise — a champion ready to bid for mega-projects from Johor’s Forest City development to Indonesia’s new capital, Nusantara.
But the market read it differently. IJM’s shares tumbled as much as 16% on January 19, plunging to a three-month low of RM2.34, prompting Bursa Malaysia to suspend intra-day short-selling of the stock. Free Malaysia Today Investors were not celebrating a strategic premium. They were selling on the belief that the offer undervalued IJM and the political controversy surrounding the deal made its completion far from certain.
Within days, the controversy metastasised. UMNO Youth chief Datuk Dr Akmal Saleh publicly raised concerns that the takeover could dilute the equity interests of the Malaysian government and the rights of the country’s Bumiputera majority, while the Malay Businessmen and Industrialists Association also questioned the deal. Bloomberg For any corporate transaction in Malaysia, where affirmative-equity policies remain politically sensitive and government-linked investment companies (GLICs) serve as the pillars of the capital markets, this kind of political headwind is not incidental noise. It is structural resistance.
The 46–51% Discount: What ‘Not Fair and Not Reasonable’ Actually Means
The phrase “not fair and not reasonable” in Malaysian securities law has a precise, two-limbed meaning. An offer is not fair when the price does not reflect the target company’s intrinsic value; it is not reasonable when accepting shareholders would be worse off than simply remaining shareholders in the status quo. The Sunway RM11 billion IJM bid discount managed to fail both tests simultaneously — an analytical verdict rarely achieved at this magnitude of deal size.
M&A Securities’ circular filed with Bursa Malaysia found the RM3.15 per share offer represents a 46.1% discount to the estimated low value of IJM shares at RM5.84, and a 51.4% discount to the estimated high value of RM6.48. The Star The assessment uses a sum-of-parts valuation methodology — the standard approach for diversified conglomerates — which values each business division individually before aggregating. IJM’s sprawling portfolio spans toll roads, ports (including the strategic Kuantan Port), property development, construction, manufacturing, and plantation assets. Each line generates independently supportable cashflows. The IJM sum-of-parts valuation Sunway gap is not a rounding error. It is a canyon.
To contextualise just how extraordinary this discount is: comparable ASEAN construction and infrastructure mergers typically offer premiums of 15–30% to the pre-announcement share price, not discounts of nearly half. The implied value fell further to RM3.08 per share once Sunway’s two-sen interim dividend — announced on 25 February — was factored in, deepening the effective discount to 47.3% and 52.4% against the low and high valuation estimates respectively. The Star
Structurally, too, the deal’s composition amplified the unfairness argument. Nine-tenths of the consideration is paid not in cash but in newly issued Sunway shares — shares that M&A Securities assessed are already trading at premium multiples that embed substantial future growth expectations. Accepting those shares at that price, in exchange for IJM equity valued at a significant discount, is a double-compression trade that no disciplined institutional investor should accept without resistance.
What Minority Status in Sunway Would Really Cost IJM Shareholders
The control dimension of this story deserves sharper focus than it has received in the local financial press, and it is central to understanding why IJM shareholders should reject Sunway’s offer.
IJM shareholders who accept the offer would transition from being 100% equity holders in IJM — with full voting rights, direct asset exposure, and dividend control — to holding approximately a 20.6% minority stake in the combined Sunway entity. The Star That dilution is not merely numerical. It represents a qualitative transformation in shareholder rights.
As a minority stakeholder in Sunway, an IJM shareholder would have no meaningful ability to influence capital allocation, dividend policy, management decisions, or strategic direction. They would assume exposure to the integration risks of merging two large, culturally distinct conglomerates with different asset compositions. They would lose direct ownership of IJM’s strategic infrastructure — including four toll-road concessions and the Kuantan Port, which sits at the heart of Malaysia’s deepening trade relationship with China under the Belt and Road corridor.
M&A Securities made this point explicitly: as minority shareholders, accepting holders would assume significant integration, execution and transitional risks arising from the combination of two sizeable and diversified conglomerates with distinct operating models, asset compositions, and management cultures. The Star The advisory language, stripped of its legalese, is unambiguous: the deal trades known, direct ownership for uncertain, diluted exposure.
The Shadow Over the Deal: MACC, the UK Fraud Office, and Governance Questions
No analysis of the IJM board recommends reject Sunway takeover story is complete without confronting the extraordinary governance cloud that has hung over IJM throughout the bid process.
By March 4, Malaysia’s Anti-Corruption Commission had opened three separate investigation papers relating to IJM Corporation, including an inquiry into financial transactions and overseas investments worth approximately RM2.5 billion, a bribery case involving a project, and a probe into the Sunway share transaction itself. BERNAMA MACC chief commissioner Tan Sri Azam Baki confirmed active cooperation with the UK’s Serious Fraud Office in what he described as an ongoing, multi-jurisdictional investigation.
Critics including the Malay Chamber of Commerce warned that any takeover could undermine Bumiputera ownership in IJM, where government-linked investment companies currently control more than 50% of the shareholding. The Corporate Secret The Ministry of Finance subsequently confirmed that GLICs held a combined 45% equity interest in IJM as of 30 January 2026 — a figure that frames the deal not as a purely private-sector transaction but as a de facto restructuring of public savings.
For the foreign institutional investors who collectively form a significant slice of both companies’ free float, this combination of valuation uncertainty, regulatory investigation, and political sensitivity is precisely the kind of environment that prompts capital to step back and wait.
The Macro Lens: ASEAN Consolidation, Infrastructure Cycles, and Foreign Capital
The IJM-Sunway saga unfolds against a backdrop that gives it significance beyond two Malaysian companies. Southeast Asia is entering what the Asian Development Bank estimates will be a US$210 billion annual infrastructure investment cycle through the 2030s, driven by energy transition infrastructure, data centre buildouts, urbanisation, and post-pandemic industrial reshoring.
In this environment, the logic of creating regional construction champions has real merit. ASEAN property developers merger Malaysia dynamics are not illusory — consolidation that creates companies capable of competing for billion-dollar projects across Vietnam, Indonesia, the Philippines, and Bangladesh is strategically sound. The question has always been price, governance, and process — not direction.
What the IJM Sunway impasse reveals, however, is that Malaysia’s capital markets are not yet willing to accept large-scale ASEAN consolidation at valuations that disadvantage existing shareholders. The independent adviser’s verdict, the board’s unanimous alignment, and the institutional shareholder base’s likely disposition all point toward a rejection outcome that will reverberate beyond Malaysia’s borders. Foreign fund managers watching from Singapore, Hong Kong, and London will note that Malaysia’s regulatory and advisory infrastructure functioned as designed — providing substantive, independent analysis rather than rubber-stamping a politically connected deal.
That is a positive signal for the long-term credibility of Bursa Malaysia as an investable market. The short-term message, however, is more complicated: Malaysia’s largest infrastructure assets remain fragmented, and the path toward sector champions capable of competing regionally just got harder.
Jeffrey Cheah’s Exit Clause — and What Happens Next
Sunway founder Jeffrey Cheah, speaking to reporters on Friday, confirmed the group is prepared to walk away if IJM shareholders do not accept the offer by the April 6 deadline. “There’s no compulsion for the shareholders to sell to us,” Cheah said, adding simply: “We walk away.” Bloomberg
That equanimity — whether genuine or tactical — suggests Sunway understands the arithmetic. With the IJM board unanimously opposed, independent advice formally on record, GLICs holding a controlling block likely to follow the board’s recommendation, and an active MACC investigation casting a shadow, the conditions for a successful takeover have effectively evaporated. Sunway’s own share price trajectory will now be closely watched: a failed large acquisition attempt can, paradoxically, unlock value for the acquirer by removing the dilution risk embedded in the share issuance component of the offer.
The offer window remains open until 5pm on April 6, 2026. An EGM on March 26 will give shareholders a formal platform to voice their position. But the trajectory is clear. Unless Sunway revises its offer materially — and there is no indication it will — this Malaysia construction takeover 2026 will end in failure, becoming a case study in valuation discipline, governance complexity, and the limits of strategic vision unmatched by fair commercial terms.
The Columnist’s Verdict: A Justified Rejection, and a Missed Opportunity
The IJM board and its independent adviser have done exactly what they should do. The Sunway IJM offer not fair finding is not an ideological verdict; it is a financial one. A 46–51% discount to independently computed sum-of-parts value is not a negotiating position — it is an insult to shareholders who have held IJM through multiple economic cycles, infrastructure downturns, and pandemic-era uncertainty. Institutional investors who hold IJM on behalf of Malaysian pensioners and ordinary savers cannot, in good conscience, accept that exchange.
What makes this story genuinely important, however, is what it leaves unresolved. Malaysia’s construction sector fragmentation is a real competitive disadvantage. The country’s infrastructure ambitions — high-speed rail, the Johor-Singapore Special Economic Zone, renewable energy buildout — require contractors of regional scale and financial depth. The failure of this particular deal does not make the case for consolidation disappear. It makes the need for a better-structured, more fairly priced next attempt more urgent.
Sunway, for its part, remains a formidable operator — financially disciplined, well-governed, and with the operational depth to absorb a large acquisition. Jeffrey Cheah built one of Asia’s most respected property-construction empires over four decades. The vision to create a regional champion is not the problem. The price was.
When the right deal — at the right price, with the right governance protections, free of regulatory clouds — is eventually presented, Malaysia’s capital markets will be watching. For now, the answer from IJM’s board, its independent adviser, and, in all probability, its shareholders is unambiguous: not at RM3.15.
The offer for IJM shares remains open for acceptance until 5pm on 6 April 2026.
Further Reading
- Bursa Malaysia — IJM Corporation Bhd Filings
- Bloomberg: Sunway Willing to Walk Away If IJM Bid Rejected
- Bloomberg: Sunway’s IJM Bid Questioned Over Bumiputera Rights
- Nikkei Asia: Malaysia’s IJM Urges Shareholders to Reject Sunway Takeover Bid
- Bernama: Three Investigation Papers Opened Against IJM Corporation
- The Edge Malaysia: Sunway’s Offer for IJM Not Fair, Not Reasonable
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

2026 Real Estate Market News: Are We Heading for a Correction?

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Fidelity Crypto vs. Traditional Brokerages: A Guide for Modern Investors

The 2026 Global Smartphone Market: AI Integration and Competitor Analysis

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

Fidelity Investments Review: Maximizing Returns in a Volatile Stock Market

How Crypto Transformed the Trump Fortune: A $1.4 Billion Financial Breakdown

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Global Supply Chain Vulnerabilities: From Eurasian Trade Corridors to Food Consumer Recalls

Why 5% U.S. Treasury Yields Signal a Global Market Regime Shift.

Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025