
Oil Markets
US Energy Secretary Chris Wright Pushes for Flood of Investment in Venezuela Oil Amid Revival Efforts

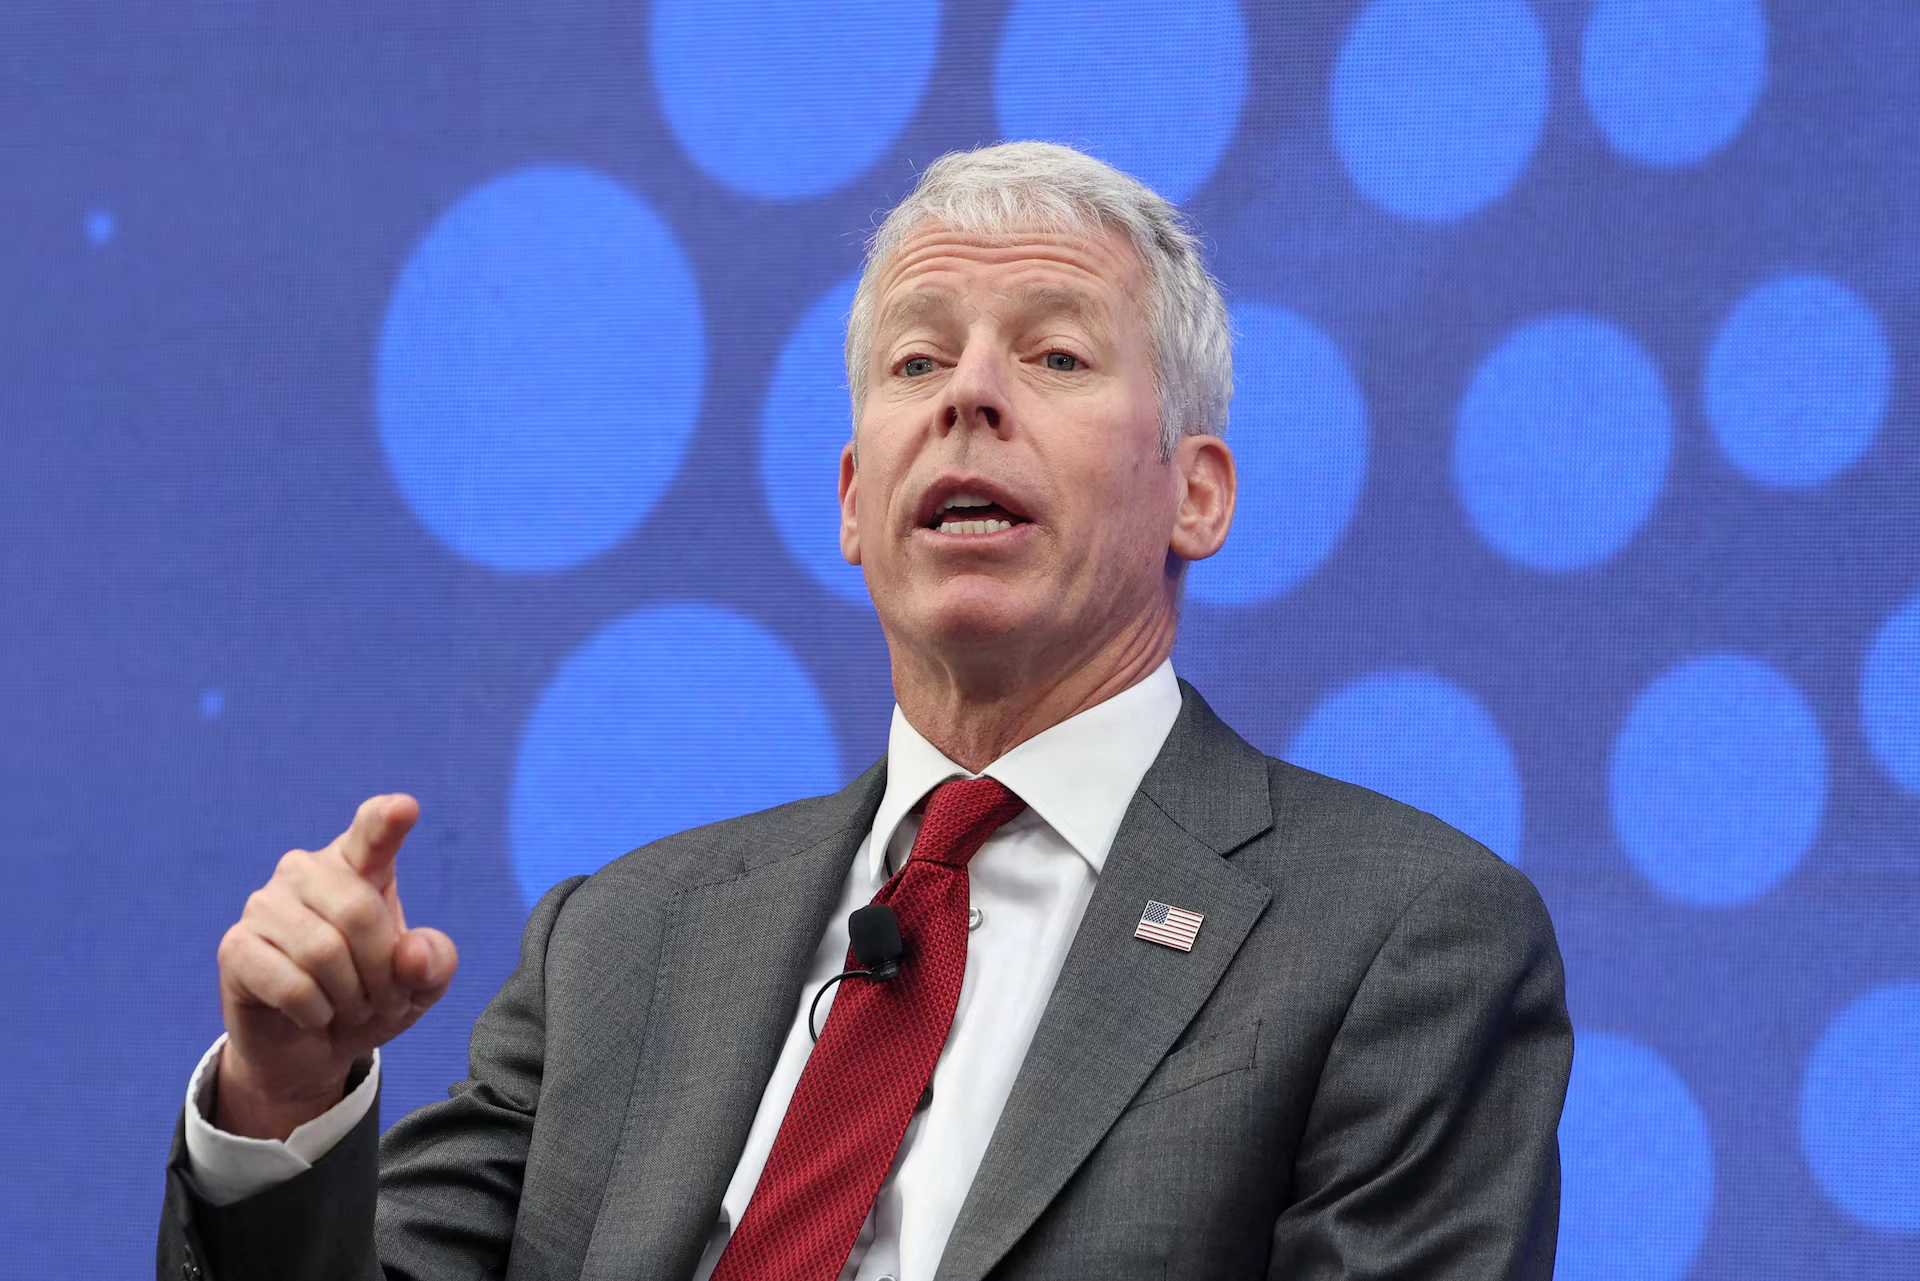
US Energy Secretary’s Venezuela visit signals major push for oil investment, but industry concerns and legal reforms complicate Trump’s $100B revival plan.
In an unprecedented diplomatic mission that signals a dramatic shift in hemispheric energy politics, US Energy Secretary Chris Wright touched down in Caracas on February 11, 2026, carrying with him Washington’s ambitious blueprint for resurrecting Venezuela’s moribund oil sector. The three-day visit—marking the highest-level American energy delegation to Venezuela in nearly three decades—encapsulates both the audacious promise and profound uncertainty surrounding President Donald Trump’s $100 billion gambit to transform the country with the world’s largest proven oil reserves into a reliable energy partner.
Wright’s handshake with interim President Delcy Rodríguez at the Miraflores Palace wasn’t merely a photo opportunity. It represented the culmination of a month-long whirlwind that began with the January 3 capture of former President Nicolás Maduro and has since unleashed a cascade of regulatory reforms, sanctions relief, and industry skepticism that will define the next chapter of global energy markets.
The Push for Venezuela Energy Sector Revival
“I bring today a message from President Trump,” Wright declared, standing alongside Rodríguez with both nations’ flags flanking them. “He is passionately committed to absolutely transforming the relationship between the United States and Venezuela, part of a broader agenda to make the Americas great again.”
The rhetoric matches the scale of ambition. Venezuela’s oil production has plummeted from 3.5 million barrels per day in the late 1990s to a mere 900,000 barrels currently—roughly equivalent to North Dakota’s output. As reported by The New York Times, the infrastructure decay is staggering: refineries operating at fraction capacity, pipelines corroded, skilled workers fled, and PDVSA—the state oil company—hollowed out by decades of mismanagement and corruption.
Wright’s itinerary reflected the magnitude of the challenge. Beyond high-level meetings with Rodríguez and executives from Chevron and Spain’s Repsol, according to Reuters, the Energy Secretary toured the Petropiar project in the Orinoco Oil Belt, where heavy crude extraction requires sophisticated technology and billions in capital investment. His assessment was diplomatically blunt: while Venezuela’s January 29 legal reforms represent “a meaningful step in the right direction,” they fall short of providing “the kind of large capital flows” Washington envisions.
The reforms in question fundamentally restructure Venezuela’s hydrocarbon sector. For the first time since Hugo Chávez’s 2007 nationalizations, private companies can now operate upstream activities through production-sharing contracts rather than being forced into joint ventures where PDVSA holds majority stakes. The law introduces independent arbitration for disputes, caps certain taxes, and includes economic stabilization mechanisms—all designed to reassure foreign investors scarred by past expropriations.
Yet the devil lurks in implementation. Venezuela passed this sweeping legislation in a matter of weeks, under obvious pressure from Washington. The Financial Times noted that Wright emphasized the administration’s desire for a “flood of investment,” but the rushed nature of reforms has raised eyebrows among legal experts who question whether such fundamental changes can provide the long-term stability that multibillion-dollar oil projects require.
Challenges in Attracting Flood of Investment in Venezuela Oil
The industry’s response to Trump’s Venezuela push has been decidedly mixed—and instructive about the real barriers to US Venezuela oil investment.
Chevron, the only major American oil company currently operating in Venezuela under special licenses, occupies the pole position. The company believes it can increase production by 50% over the next 18 to 24 months without significant additional capital expenditure. Its Vice Chairman Mark Nelson told Trump the company has “a path forward here very shortly to be able to increase our liftings from those joint ventures 100% essentially effective immediately.”
But beyond Chevron’s existing foothold, the landscape grows considerably more complex. According to CNBC, ExxonMobil CEO Darren Woods delivered a stark assessment to Trump on January 9: Venezuela is “uninvestable” in its current state. Woods’ blunt verdict—which reportedly angered the president—reflects hard-learned lessons from 2007, when Chávez nationalized ExxonMobil’s Venezuelan assets. The company is still pursuing approximately $2 billion in arbitration claims.
ConocoPhillips faces even steeper hurdles, with roughly $10 billion in outstanding claims from similar expropriations. CEO Ryan Lance echoed Woods’ concerns, emphasizing that Venezuela’s energy system requires fundamental restructuring before major capital commitments make sense.
The hesitancy extends beyond historical grievances. Energy consultancy Rystad Energy estimates that maintaining Venezuela’s current production flat would require $53 billion in investment through 2040. Returning to the glory days of 3 million barrels per day? That demands a staggering $183 billion—roughly equivalent to the entire annual GDP of Portugal.
The Washington Post highlighted another uncomfortable reality: at current oil prices, the economics of reviving Venezuela’s heavy, sulfur-rich crude are marginal at best. The country’s oil requires expensive diluents for transport and specialized refining capacity. Meanwhile, neighboring Guyana—where ExxonMobil has struck bonanza discoveries—offers lighter, cleaner crude with lower taxes, no state oil company partnership requirements, and crucially, political stability.
Treasury Secretary Scott Bessent’s comments on February 6 revealed the administration’s recalibration. “The big oil companies who move slowly, who have corporate boards, are not interested,” he acknowledged. Instead, Washington may rely more heavily on independent oil companies and “wildcatters” whose appetite for risk—and tolerance for political uncertainty—runs higher than publicly traded majors answerable to shareholders.
Geopolitical and Economic Implications
Wright’s Venezuela visit reverberates far beyond the oil patch, carrying profound implications for global energy security and geopolitical alignments.
From Washington’s perspective, Venezuelan oil represents a strategic lever on multiple fronts. Increased production from a friendly Caracas could dampen Russia’s energy influence, particularly if Venezuelan crude diverts buyers—like India—away from Russian supplies. Trump has explicitly framed this as part of his plan to weaken Moscow’s war-making capacity while simultaneously addressing American energy dominance.
The environmental calculus, however, complicates this narrative. Climate analysts warn that fully exploiting Venezuela’s reserves could add 13% to the global carbon budget—a sobering figure as nations struggle to meet Paris Agreement commitments. European energy companies with net-zero pledges may find Venezuelan crude incompatible with their climate strategies, potentially limiting the pool of willing investors despite the legal reforms.
The broader Latin American energy landscape is also shifting. Venezuela’s potential recovery alters regional dynamics, from pipeline politics in Colombia to refining capacity in the Caribbean. If Caracas can indeed ramp production meaningfully, it would reshape market fundamentals that have prevailed for over a decade.
China’s conspicuous absence from the current Venezuela equation warrants attention. Beijing had been Venezuela’s lifeline during the Maduro years, providing loans against future oil deliveries. Reuters reported that the new US sanctions framework explicitly blocks entities linked to China, Iran, and Russia from participating in Venezuela’s oil sector—a clear signal that Washington views energy development as inseparable from broader strategic competition.
The Reality Check: Timeline and Expectations
Industry analysts urge tempering expectations about Venezuela’s oil comeback. Francisco Monaldi, director of the Latin America Energy Program at Rice University’s Baker Institute, draws parallels to Iraq: it took nearly two decades to revitalize that country’s oil industry after the 2003 invasion, and corruption and mismanagement remain endemic.
Even optimistic scenarios envision Venezuela reaching 1.2 million barrels per day by late 2027—a modest 33% increase from current levels that still leaves production far below pre-crisis peaks. The challenges are structural: Venezuela needs to rebuild its electrical grid (chronic blackouts plague oil installations), import vast quantities of diluents, restore corroded pipelines, and most critically, attract and retain the skilled workforce that fled during the economic collapse.
Political stability remains the x-factor. While Rodríguez’s interim government has cooperated with Washington’s directives—including the oil law reforms and release of some political prisoners—Venezuela’s long-term governance trajectory remains uncertain. Opposition groups boycotted the hydrocarbons law vote, arguing that legislation governing the world’s largest oil reserves should emerge from inclusive national dialogue rather than rushed decree.
Wright acknowledged these concerns obliquely, noting during his Caracas press conference that professionalization of PDVSA would be “a subject of dialogue” with Venezuelan authorities. The state company, once Latin America’s crown jewel of technical competence, has been gutted by brain drain and politicization. Rebuilding institutional capacity may prove more challenging than repairing physical infrastructure.
Conclusion: A Generational Wager on Uncertain Terrain
Chris Wright’s Venezuela mission represents more than energy diplomacy—it’s a high-stakes wager on whether American influence and capital can resurrect a collapsed petro-state in months rather than years. The Trump administration’s swagger belies a complex reality where legal reforms, sanctions relief, and political will confront industry wariness, economic headwinds, and institutional decay.
The pieces for Venezuela energy sector revival are falling into place: reformed laws, sanctions relief, existing infrastructure (however degraded), and the world’s largest proven reserves. Yet as ExxonMobil’s Darren Woods bluntly reminded Trump, oil majors don’t commit tens of billions based on one month of political change and hurried legislation. They require clarity about contract terms, confidence in dispute resolution, certainty about political stability, and crucially, oil prices that justify the enormous capital and risk.
For now, the flood of investment in Venezuela oil remains more aspiration than reality—a “generational opportunity” that may yet materialize, but only if Washington, Caracas, and the global oil industry can bridge the chasm between rhetoric and the hard economics of heavy crude extraction in a still-fragile political environment.
The coming months will reveal whether Wright’s Caracas handshake marks the beginning of Venezuela’s energy renaissance—or merely another chapter in the country’s long history of promises unfulfilled. For investors, policymakers, and energy markets watching closely, the answer will reshape not just Venezuelan fortunes, but the broader equilibrium of global energy security for decades to come.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


As of Sunday, 8 November 2026, the official Oil and Gas Regulatory Authority (OGRA) notified price of petrol (motor spirit) in Pakistan stands at Rs 346 per litre, while high-speed diesel (HSD) is priced at Rs 378 per litre. These rates came into effect from midnight on 7 November 2026 after a cut of Rs 6.59 in petrol and Rs 4.25 in diesel. The reductions continue a clear downward trend that began in late October and accelerated through the first week of November as international oil benchmarks softened.
This article provides the complete current price picture, explains the new daily pricing mechanism, traces 2026 price history, analyses the real-world impact on households and businesses, and outlines the outlook for the rest of the year.
Current Official Fuel Prices Effective 7–9 November 2026
The latest OGRA notification sets the following national ex-depot prices:
| Fuel Type | New Price (Rs/litre) | Change (Rs) | Previous Price | Effective Period |
|---|---|---|---|---|
| Petrol (Motor Spirit) | 346.00 | −6.59 | 352.59 | 7–9 Nov 2026 |
| High-Speed Diesel (HSD) | 378.00 | −4.25 | 382.25 | 7–9 Nov 2026 |
| Kerosene (SKO) | 308.52 | −15.15 | 323.67 | 7 Nov onwards |
| Light Diesel Oil (LDO) | 251.37 | −17.72 | 269.09 | 7 Nov onwards |
These figures have been widely reported by The News, Geo News, Business Recorder, and Dawn. Pump prices at individual stations are typically a few rupees higher because of inland freight costs that vary by location. OGRA also publishes city-wise pump prices for greater transparency.
High-octane blended component (HOBC) remains around Rs 415 per litre, set by individual oil marketing companies rather than a single OGRA rate. LPG cylinder prices are notified separately on a monthly basis and currently sit near Rs 294 per kg at the regulated maximum.
Why Prices Have Fallen in Early November 2026
Three main factors drove the recent cuts:
- Softer international oil prices. Brent crude has retreated from peaks above $100 per barrel earlier in the autumn as some geopolitical risk premium eased.
- Daily pricing mechanism. Since late October the government passes through changes in landed cost much more quickly.
- Refinery and premium differential adjustments. A portion of the benefit arising from premium differentials is being shared with consumers.
Earlier in the same week, OGRA had already announced larger cuts (Rs 9.41 for petrol and Rs 5.56 for diesel effective 6 November). The cumulative reduction from the late-October peak has been roughly Rs 28–32 for petrol within about ten days.
How the Daily Fuel Pricing Mechanism Works
On 30 October 2026 the federal cabinet approved a shift from the traditional fortnightly review to a daily fuel price revision system. The decision was taken against the backdrop of extreme volatility caused by the ongoing US-Israel-Iran tensions. Key features of the new system, as explained in official notifications and detailed by Express Tribune and Dawn, include:
- The import parity price is calculated on the actual landed cost of the relevant Pakistan State Oil (PSO) cargo rather than a fixed fortnightly average.
- A short-term premium differential adjustment (currently approximately $2.95 per barrel) is applied to smooth extreme daily swings.
- Refineries are required to surrender a portion of the differential into the petroleum levy account; the resulting benefit is passed on to consumers.
- The Petroleum Levy remains fixed at Rs 80 per litre for both petrol and diesel.
- An additional Climate Support Levy of Rs 5 per litre is still applied.
- Dealer margin is unchanged at Rs 9.98 per litre and oil marketing company margin at Rs 7.87 per litre.
- Prices are published on the OGRA website every day for public scrutiny.
The system improves transparency and allows faster relief when international prices fall. At the same time it means consumers can see price changes almost daily, which requires closer monitoring by transporters and households.
Detailed 2026 Price History and Volatility
Fuel prices in 2026 have been among the most volatile in the past decade. Compiled OGRA notification data shows:
- Petrol’s 2026 high was approximately Rs 398.96 in early October.
- The lowest point in the second half of the year was around Rs 315.80 on 21 July 2026.
- From 21 July to 7 November, petrol still rose overall by about 9.6% even after the recent cuts.
- Diesel followed a parallel path, peaking near Rs 424.92 in mid-September before declining to the present Rs 378.
Month-by-month summary (approximate closing levels):
| Month | Petrol (approx. end) | Diesel (approx. end) | Notable Events |
|---|---|---|---|
| July 2026 | 336 | 360 | Post-Eid recovery |
| August 2026 | 342 | 365 | Gradual rise |
| September 2026 | 387 | 400+ | Middle East escalation |
| October 2026 | 378–399 | 400–425 | Peak volatility |
| Early Nov 2026 | 346 | 378 | Daily mechanism + falling crude |
The sharp rises earlier in the year were directly linked to Brent crude trading above $100 per barrel for extended periods. Higher global freight rates and a relatively stable but still elevated USD/PKR rate (around 276–282) amplified the impact on local prices.
Real Economic Impact on Households, Transporters and Industry
Even modest cuts produce noticeable savings:
- A typical family car (40-litre tank filled once a week) saves approximately Rs 260–280 per week, or more than Rs 1,100 per month.
- Motorcycle users (5–8 litre tank) save Rs 30–55 per fill-up.
- Ride-hailing drivers and small transporters see improved margins.
- Goods transporters benefit most from the diesel cut; lower freight costs can gradually feed through into food and consumer goods prices, helping moderate inflation.
Despite the relief, absolute prices remain high. Petrol is still more than Rs 90 above early-2026 levels. Combined with the separate NEPRA fuel cost adjustment of Rs 2.37 per unit that will appear on November electricity bills, overall energy expenditure continues to pressure middle- and lower-income households. Analysts writing in Business Recorder and Profit by Pakistan Today note that sustained lower fuel prices could contribute to a further easing of core inflation (recently averaging 6–7%), but only if international prices remain soft for several more weeks.
Outlook for the Remainder of November and December 2026
Market participants and independent trackers expect continued volatility. Key variables:
- Brent crude trajectory. If crude stays below $95–98, further modest reductions are possible within the next 7–10 days. Any escalation in the Middle East could reverse the trend quickly.
- PSO cargo schedule and premiums. The exact landed cost of upcoming shipments will determine the next daily notifications.
- Exchange rate. The USD/PKR has been relatively stable near 276–282; any sharp depreciation would offset oil price declines.
- Government policy choices. Decisions on the petroleum levy, climate levy, or any temporary relief packages remain possible under the IMF programme.
Most observers currently lean toward a mildly positive short-term outlook for consumers, provided global supply conditions do not deteriorate.
Frequently Asked Questions
What is the petrol price in Pakistan today (8 November 2026)?
Rs 346 per litre according to the latest OGRA notification.
What is the current diesel price?
Rs 378 per litre.
Why do fuel prices change every day now?
The government adopted a daily review mechanism on 30 October 2026 to respond more quickly to global oil volatility.
Will prices rise again soon?
It depends on international oil prices, freight rates and the exchange rate. Monitor OGRA’s daily notifications.
Are there any consumer subsidies currently in place?
No broad-based consumer subsidies exist beyond the fixed levy structure. Targeted support measures remain under discussion.
How much has petrol fallen in the past ten days?
Roughly Rs 28–32 from late-October peaks, depending on the exact starting date.
Does the daily mechanism apply to LPG and kerosene?
Kerosene and light diesel oil are still adjusted less frequently; LPG follows a separate monthly notification process.
Detailed Breakdown of Price Components (November 2026)
Understanding why petrol costs Rs 346 requires looking beyond the headline number. According to the pricing formula used by OGRA and reported extensively by Business Recorder and Dawn, the final consumer price consists of several layers:
- Ex-refinery price / Import parity: This is the largest variable component and moves with international crude and product prices plus freight.
- Petroleum Levy: Fixed at Rs 80 per litre. This is a major revenue source for the federal government and is protected under the IMF programme.
- Climate Support Levy: Rs 5 per litre.
- Inland Freight Equalisation Margin (IFEM): Varies by location to equalise prices across the country.
- Dealer margin: Rs 9.98 per litre.
- OMC margin: Rs 7.87 per litre.
- Sales tax and other duties: Applied according to the prevailing regime.
Because the levy and margins are largely fixed, most of the daily movement comes from the import parity component. This is why a $5–6 drop in Brent crude can translate into a Rs 5–8 reduction at the pump once the daily mechanism is applied.
Comparison with Regional Prices
As of early November 2026, Pakistani fuel prices remain higher than several neighbouring and peer economies when adjusted for income levels:
- India (major cities): Petrol roughly equivalent to Rs 280–310 in Pakistani rupees after conversion.
- Bangladesh: Lower regulated prices with heavier subsidies.
- UAE and Saudi Arabia: Significantly lower (under Rs 200 equivalent) because of local production and subsidies.
- Sri Lanka: Has seen sharp reductions after earlier crises.
The gap is largely explained by Pakistan’s high petroleum levy, import dependence (over 80% of refined products or crude), and the exchange rate. Policymakers frequently cite the need to keep the levy high to meet fiscal targets while arguing that lower international prices should eventually provide relief.
Impact on Inflation and Monetary Policy
Fuel prices have a direct and indirect effect on inflation. Directly, they appear in the transport component of the CPI. Indirectly, they raise the cost of moving food, cement, steel, and consumer goods. The State Bank of Pakistan raised the policy rate by 50 basis points to 12% in late October 2026, citing elevated energy costs and the inflation outlook.
If the current downward trend in fuel prices persists for the next 4–6 weeks, it could ease pressure on the central bank and support a more stable inflation path into early 2027. Conversely, a rebound in oil prices would complicate the disinflation process and could force the SBP to maintain higher rates for longer. Independent analysis published by Profit and Business Recorder suggests that every sustained Rs 10 reduction in petrol contributes roughly 0.15–0.25 percentage points to lower headline inflation over a quarter, assuming no offsetting shocks.
What Consumers and Businesses Should Do Now
- Households: Consider filling tanks if further cuts are expected in the next few days, but avoid panic buying. Monitor OGRA’s website or reliable news sources daily.
- Transporters and logistics firms: Update freight rates cautiously. Many contracts allow pass-through of fuel costs; document the recent reductions.
- Businesses with high fuel intensity (manufacturing, agriculture, construction): Recalculate operating costs and review hedging or bulk-purchase options where available.
- Investors: Watch oil marketing companies and refineries for margin impacts. Lower prices can boost volume but squeeze refining margins if the differential narrows.
Frequently Asked Questions (Expanded)
Is the Rs 346 price the same in every city?
No. The OGRA rate is the ex-depot or base rate. Actual pump prices include inland freight, which is higher in northern and remote areas. Differences of Rs 3–8 per litre are common.
When will the next price announcement be made?
Under the daily mechanism, OGRA typically publishes the next day’s rate in the evening or late afternoon. Always check the official OGRA website or trusted news outlets.
Does the government still provide any fuel subsidy?
There is no general consumer subsidy. The government collects a high petroleum levy. Some targeted schemes for public transport or agriculture have been discussed but are not currently active on a large scale.
How does the current price compare with January 2026?
Petrol was near Rs 253 in January 2026. The present Rs 346 represents a substantial increase over the year despite the recent cuts.
Will electric vehicles become more attractive because of high fuel prices?
Yes. The combination of elevated petrol prices and the new Auto Policy 2026-31 incentives (1% sales tax on battery EVs and higher financing limits) is expected to accelerate EV adoption, especially among urban middle-class buyers.
Long-Term Structural Issues
Pakistan remains heavily dependent on imported petroleum products. Local refineries operate well below capacity, and new refining investments have been slow. The government has repeatedly stated that shifting toward electric vehicles, improving public transport, and eventually developing domestic energy resources are necessary to reduce vulnerability to global oil shocks. The recent Auto Policy and ongoing discussions around the National Electric Vehicle Policy are part of that longer-term strategy. Until those measures scale up, fuel price volatility will continue to affect the economy.
Conclusion
The latest OGRA cuts bring welcome and measurable relief after a prolonged period of elevated fuel prices. At Rs 346 for petrol and Rs 378 for diesel, Pakistani consumers are paying substantially less than they did in early October, though absolute levels remain high by historical standards. The new daily pricing system offers greater transparency and faster pass-through of international declines, but it also means more frequent adjustments. Households, transporters, logistics companies and policymakers will continue to watch global oil markets and OGRA notifications closely in the coming weeks. Sustained lower prices would support inflation moderation and household purchasing power, while any sharp rebound in crude would quickly reverse the gains under the current mechanism.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Brent futures reached about $115 a barrel on Tuesday, a six-month high, according to CNBC, after touching roughly $117 the day before. WTI traded just above $101, per FXStreet. The move extended gains from last week, when Iranian attacks on tankers pushed prices to their highest since April.
Two Forces Pulling Opposite Ways
Diplomacy. Iran is weighing a Qatari draft proposal to end the war, and a reply is expected by the end of the week. The Wall Street Journal reports that Washington has also asked Gulf states to prepare for a possible renewed US campaign after the 3 November midterm elections, which complicates the picture. Separately, the Journal reports that Vice President JD Vance wrote to Iran’s Mohsen Rezaei in an attempt to reopen talks; this was not independently confirmed. Oil eased in Asian trading on Thursday on those outreach reports, according to Investing Live.
Supply risk. CNBC reports that Houthi attacks on Saudi infrastructure keep supply worries alive even as diplomatic hopes lift sentiment. The Strait of Hormuz carried about a fifth of the world’s energy supplies before the conflict began in February, which is why any disruption feeds quickly into prices. Kitco’s market report this week described Hormuz uncertainty as the reason oil stayed elevated ahead of the Fed meeting.
The Inventory Signal
US data adds a mixed picture. EIA figures show crude inventories fell by about 1.9 million barrels last week while gasoline stocks rose by about 3.9 million barrels, per FXStreet. Falling crude stocks support prices; rising gasoline stocks suggest weaker US demand for the refined product.
The Medium-Term Supply Gap
The World Bank expects global oil supply to fall about 5.2% in 2026, according to FXStreet’s summary. That is a structural, not just sentiment-driven, shortfall, and it explains why diplomatic headlines move prices by a few dollars while the level stays high.
Scenarios for the Next Two Weeks
- Deal progress: if Iran accepts the Qatari draft, expect a risk premium unwind; prices could fall sharply but not back to pre-war levels given the supply loss already incurred.
- Stalemate: prices stay in a high, headline-driven range.
- Escalation after the midterms: renewed US action or further attacks on Gulf infrastructure would test the recent highs.
These are scenarios, not forecasts; the single largest driver is Iran’s reply.
Who Feels It
- Central banks: the Fed held rates on 28 October with two members preferring a hike, and Pakistan’s central bank cited oil near $100 when it raised its rate to 12%.
- Importers: energy-importing economies see pressure on inflation and external balances.
- Airlines and travel: fuel is the largest swing cost for carriers; see our airfare outlook.
- Gold: precious metals have traded as a hedge against the same uncertainty.
Bottom Line
Oil above $100 is the product of a war premium and a real supply loss. A Qatari-brokered deal could take some heat out of prices, but the market is pricing a good deal of caution until Iran actually answers.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
An unexpected shift in US sanctions policy has given Asian energy buyers a potentially important reprieve. It has also opened fresh questions about how importers should balance cheap fuel, diplomatic relationships and the risk that trading rules may change again.
On October 17, Reuters reported that President Donald Trump had issued an order waiving important Russia-related sanctions and tariffs before planned measures took effect. A subsequent Reuters account identified India as a significant beneficiary, given its role as a major Russian oil customer. The move reduces one category of immediate concern; it does not guarantee unlimited imports free of every restriction.
Why buyers in Asia care
Asia’s refineries compete for crude on price, quality, transport economics and availability. A sanction or tariff threat adds uncertainty to contracts even before it is implemented. Trading banks, insurers and shipowners may become more cautious; buyers may diversify supply or ask for discounts to compensate for risks.
A waiver can therefore matter before a single new tanker sails. It may improve the feasibility of existing contracts and ease pressure for rapid, expensive substitution. Still, the benefit depends on the precise terms of the waiver, the identity of the buyer and seller, the bank handling payment and the practical shipping route.
India is the immediate test case
India’s refining industry has cultivated access to discounted Russian crude, but its policymakers also value the trading relationship with Washington. The reported waiver potentially reduces friction between energy security and trade negotiations. Reuters’ October 19 analysis connected the decision to hopes for progress on a broader US–India trade deal.
Yet it would be a mistake to treat the waiver as permanent diplomatic alignment. Policy decisions may be reviewed, challenged or narrowed. India’s future purchases will still depend on relative crude prices and refinery requirements, not diplomatic headlines alone.
Why oil did not simply collapse
Market reports described some easing after the policy decision, but Middle East disruption and threats to physical energy infrastructure remained important. A Reuters oil-market report cautioned that implementation uncertainty limited confidence in sustained additional supply.
More Russian barrels accessible on paper may fail to solve problems caused by damaged refining equipment, disrupted shipping lanes or unusually tight diesel stocks elsewhere. Crude oil is also not a homogeneous product. Refineries are configured for specific blends; changing the input can increase costs or reduce efficiency.
Winners and losers are not obvious
| Stakeholder | Potential benefit | Important caveat |
|---|---|---|
| Indian refiners | Access to competitive crude | Compliance and financing |
| Other Asian importers | Some relief from global supply pressure | Eligibility differs by transaction |
| Tanker operators | More potential freight business | Insurance and security costs |
| Oil exporters competing with Russia | Demand can shift away | Overall prices and volumes still uncertain |
| Asian consumers | Possible easing in fuels | Taxes, FX and local distribution affect pump prices |
Smaller importers should not assume a waiver affecting one set of transactions automatically provides legal cover for every Russian energy purchase. Compliance teams must examine operative legal documents, not rely on a news summary as advice.
The geopolitical trade-off
Critics argue that relaxing pressure on Russia can weaken coercive leverage relating to the war in Ukraine. Supporters of relief emphasise the cost of energy scarcity and the need to stabilise prices. These perspectives reflect a genuine policy trade-off: reducing immediate energy stress may conflict with broader sanctions objectives.
A rigorous regional article should distinguish the economic effects of the waiver from an endorsement of its foreign-policy rationale. It should also avoid forecasting specific oil-price declines from a change whose practical effects are still being assessed.
What to watch in November
Importers and analysts should monitor official US rules, commercial purchase announcements, actual tanker arrivals, refinery throughput and the spread between competing crude grades. Other developments—including renewed conflict around Hormuz—could easily overwhelm the marginal supply effect of the waiver.
The paperwork behind a cheap barrel
A tanker purchase is not simply a quoted price multiplied by volume. The buyer must consider contract origin, payment route, shipping ownership, insurance, discharge location, refinery compatibility and applicable legal restrictions. Even when particular sanctions measures are waived, businesses should confirm whether related banking or export controls remain relevant to the proposed transaction.
The economic gain from a discounted crude grade also depends on refining yields. A barrel that produces a lower share of the products a refinery needs may be less valuable than a seemingly more expensive alternative. Freight routes, demurrage and quality specifications can erase an advertised discount. That is why refinery-level economics matter more than a headline claim that Russian oil is ‘cheap’.
Asian policymakers also need to distinguish short-term energy security from strategic dependence. Diversification across suppliers, fuels and transport routes generally provides resilience when a major trading partner or shipping corridor is disrupted. An importer that shifts too much procurement to one politically sensitive source may exchange today’s cheaper invoices for tomorrow’s concentrated risk.
A practical follow-up story should compare actual arrival data and refinery purchases after the waiver. Only then can readers distinguish a change in legal permission from a change in physical supply.
Are all Russian sanctions now removed?
No. Reporting describes waivers of specified measures. The exact surviving restrictions and compliance obligations must be checked against current official documents.
Will Indian petrol immediately become cheaper?
Not necessarily. Crude prices, refining margins, taxes and distribution costs intervene.
Does the waiver solve Asia’s energy security problem?
No. It can ease one bottleneck while leaving transport, geopolitical and market vulnerabilities intact.
For Asian buyers, the opportunity is flexibility—not certainty. The sensible response is to diversify procurement and understand the legal terms before betting a fuel strategy on a political announcement.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Oil Shocks and Core Inflation: Why the Two Move Differently

Singapore Cannot Fight Financial Fraud by Making Victims Bear the Risk Alone

Singapore Banking’s Real Test: Beyond Profits, Who Will Safeguard Financial Trust?

Nvidia’s Share Price Is Not a Scorecard for Singapore’s AI Future

The Australian Dollar Is Not Asia’s Oracle. Singapore Should Listen Anyway

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth

Why a Weaker Currency Makes Imported Food More Expensive

How Oil Price Shocks Raise Food Prices in Importing Countries

Petrol and Diesel Prices in Pakistan Today: Complete Update for 9 November 2026

Wall Street’s Renminbi Paradox: Banks, Beijing and the Dollar

The Market Economy Is Winning

Bitcoin’s Dollar Trap: The Chart That Exposes the Future of Money

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

Australia’s AI-Driven Economic Strategy Is Redefining National Resilience

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy
Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025