
Global Economy
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation

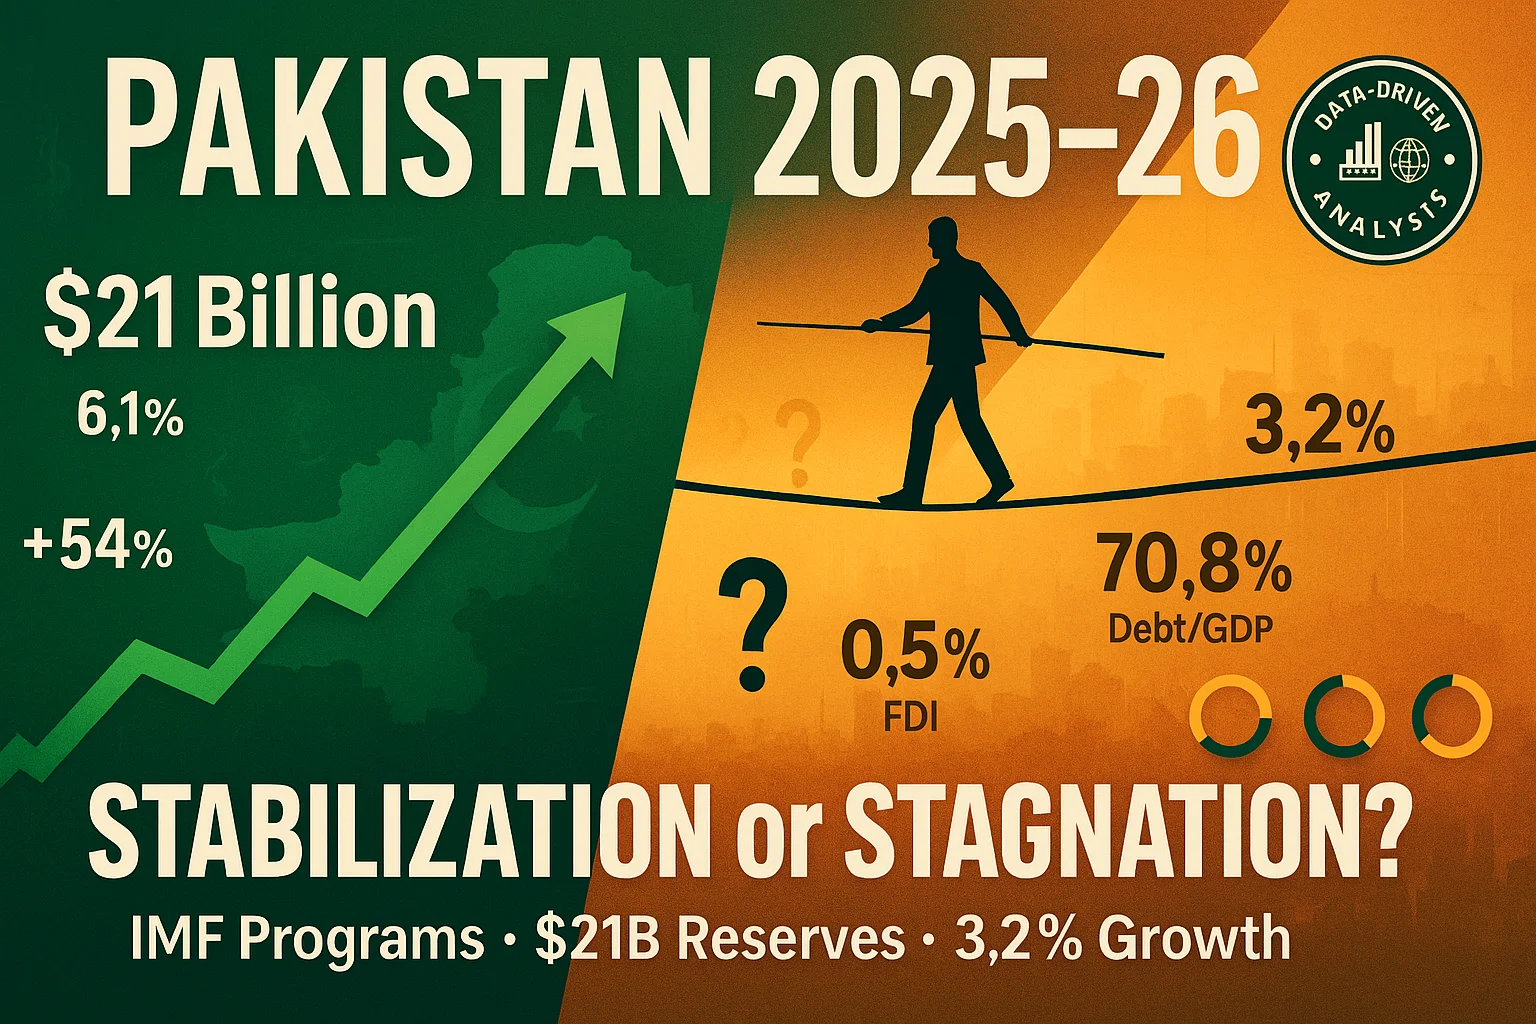
Can Pakistan finally break its bailout addiction, or is 2025 just another chapter in a recurring crisis?
Pakistan’s economy shows stabilization with $21B reserves and 6% inflation, but 3.2% growth barely exceeds population. Analyzing IMF programs, debt dynamics, and 2026 prospects for investors and policymakers.
The International Monetary Fund’s latest disbursement of $1.2 billion to Pakistan in December 2025 represents far more than a routine financial transaction. It’s a barometer of a nation caught between tentative stabilization and the persistent gravitational pull of economic inertia. Pakistan achieved a primary surplus of 1.3 percent of GDP in fiscal year 2025, in line with IMF targets, marking genuine fiscal progress. Yet beneath this achievement lies an uncomfortable truth: growth projections inch from 2.6% in FY25 to just 3.2% by FY26—barely matching population growth for a country of 240.5 million people.
This isn’t recovery. It’s containment.
For investors, policymakers, and Pakistan’s burgeoning middle class, 2025 presents a watershed moment. The immediate crisis of 2023—when foreign reserves plummeted to dangerously low levels and default fears paralyzed markets—has receded. But the challenge now is profoundly different: translating stabilization into sustained, inclusive growth that creates jobs and opportunities at scale.
The Stabilization Mirage: Real Progress or Borrowed Time?
Pakistan’s economic metrics tell a story of contradictions. On one hand, foreign exchange reserves surged to $21.1 billion as of December 2025, the highest level since March 2022. The rupee has shown unexpected resilience, with a 15.4 percent real effective appreciation in FY25 signaling currency stability after years of depreciation. The Pakistan Stock Exchange’s KSE-100 index has been nothing short of spectacular, climbing 54.70% year-over-year to reach 170,830 points, making it one of Asia’s strongest-performing equity markets.
These aren’t trivial achievements. Remittances hit a record $31.2 billion during the first ten months of fiscal year 2025, rising 30.9% year-over-year, with Saudi Arabia emerging as the top source. Inflation eased to 6.1% in November 2025 from a one-year high of 6.2% in October, a dramatic decline from the 23.4% average of the previous year.
“Pakistan’s economic outlook for 2025-2026 shows stabilization after crisis, with foreign reserves reaching $21 billion and inflation declining to 6.1%. However, GDP growth of 3.2% barely exceeds population growth, while 70.8% debt-to-GDP ratio and weak 0.5% FDI signal persistent challenges. The country must implement structural reforms to transition from containment to genuine inclusive growth.”
Yet dig deeper, and fragility persists. Foreign direct investment remains subdued at just 0.5-0.6% of GDP—levels that reflect continuing investor skepticism about Pakistan’s business environment. Unemployment is projected to fall only modestly from 8.3% to 7.5%, revealing weak job creation capacity. The country’s public debt reached Rs80.52 trillion (70.8% of GDP) by end-June 2025, up from Rs71.24 trillion the previous year—an increase of Rs9.3 trillion in a single year.
Consider what this means: Pakistan is running faster just to stay in place. Per capita income of $1,677 combined with 3.2% growth against 2% population growth translates to barely 1% improvement in living standards annually. For a nation where around 45% of the population lives below the poverty line according to a June 2025 World Bank report, this trajectory offers little hope.
The Debt Trap: Pakistan’s Fiscal Straitjacket
Here’s the brutal arithmetic constraining Pakistan’s future: nearly half of projected FY26 outlays—Rs7.5 trillion out of Rs17.4 trillion—is earmarked for debt servicing, equaling 77% of net federal revenues. This leaves Pakistan in what economists call “fiscal capture”—a situation where debt service crowds out virtually all productive spending.
Compare this globally. India, with debt around 82% of GDP, devotes 25-30% of central revenues to interest; Brazil spends roughly 20-25% with 88% debt-to-GDP. Pakistan’s debt servicing burden rivals Argentina’s, a country synonymous with fiscal distress. The difference? Pakistan borrows in currencies it cannot print, at interest rates it cannot control, making it acutely vulnerable to global financial shocks.
The IMF projects some relief, with public debt expected to decline from 70.8% to 60.8% of GDP by FY28 under continued fiscal consolidation. But this depends on maintaining primary surpluses of 2-2.5% of GDP annually—an extraordinary political challenge requiring sustained austerity in a democracy where 45% of citizens live in poverty.
What makes Pakistan’s debt particularly concerning isn’t just its size but its cost. Pakistan recorded a quarterly decline of Rs1.37 trillion in public debt in September 2025, the first since December 2019, achieved through early repayments of expensive debt. Yet the underlying structure remains precarious: domestic debt accounts for nearly half of GDP, keeping interest costs elevated, while external debt fell to 26% of GDP in FY25 from 31% two years earlier—progress, but from dangerously high levels.
The IMF Paradox: Lifeline or Dependency Trap?
Pakistan is operating under two simultaneous IMF programs: a 37-month Extended Fund Facility focused on economic stabilization and a Resilience and Sustainability Facility addressing climate vulnerabilities. Together, these have disbursed around $3.3 billion, with the latest reviews unlocking another $1.2 billion.
This marks Pakistan’s 25th IMF program since joining in 1950—a statistic that speaks volumes about the country’s inability to break its boom-bust cycle. Each program stabilizes the economy temporarily, but structural reforms remain incomplete. Tax collection as a percentage of GDP languishes around 10-11%, one of the lowest globally. Energy sector circular debt continues to accumulate despite repeated restructuring attempts. State-owned enterprises hemorrhage billions in losses annually.
The IMF’s 2025 Governance and Corruption Diagnostic Assessment found Pakistan’s economy loses an estimated 5-6.5% of GDP to corruption through “elite capture,” where influential groups shape policy for their benefit. This isn’t just morally troubling—it’s economically catastrophic. When market distortions and policy capture persist, private investment remains suppressed, foreign investors stay away, and productive capacity stagnates.
Yet paradoxically, the IMF program is working—at least on paper. The fiscal discipline it enforces has stabilized the currency, rebuilt reserves, and restored some international credibility. The question isn’t whether the IMF program is effective; it’s whether Pakistan can internalize these disciplines once external oversight ends.
2026 Prospects: Three Scenarios
Base Case: Muddle-Through Stabilization (60% probability)
Under current policies, Pakistan limps forward with 3-3.5% growth, just ahead of population expansion. The IMF program continues through 2027, providing external anchor and financing. The budget deficit narrows from -6.8% to -4.0% of GDP, with a primary surplus rising to 2.5%. Inflation stabilizes in the 5-7% range. Foreign reserves gradually build toward $25-28 billion by end-2026, providing 3.5-4 months of import cover.
This scenario delivers stability but not transformation. Living standards improve marginally. Job creation remains weak. Brain drain continues as educated Pakistanis seek opportunities abroad. The country avoids crisis but doesn’t achieve escape velocity. Think of it as economic purgatory—not hell, but certainly not heaven.
Upside Case: Reform Breakthrough (25% probability)
Imagine Pakistan actually implements long-delayed structural reforms. Tax-to-GDP ratio increases 2-3 percentage points through base broadening and digitalization. Major state-owned enterprises undergo genuine privatization, not cosmetic restructuring. Energy sector reforms sustainably reduce circular debt. The Special Investment Facilitation Council delivers $5-7 billion in Gulf investments, particularly in agriculture, IT, and mining.
In this scenario, growth accelerates to 4.5-5% by late 2026. Foreign direct investment doubles to 1-1.2% of GDP. The stock market rally continues, with the KSE-100 reaching 200,000 points. Pakistan begins attracting portfolio flows as international investors recognize improved fundamentals. Manufacturing competitiveness improves as energy costs decline.
What makes this plausible? Pakistan has demonstrated capacity for reform under pressure. The recent debt prepayment and fiscal consolidation show technical competence exists. The question is political will. Coalition governments prioritizing short-term survival over long-term transformation make sustained reform unlikely, but not impossible.
Downside Case: External Shock Relapse (15% probability)
Global commodity price spikes, particularly oil, blow out the current account. Regional geopolitical tensions escalate, disrupting trade and investor confidence. Political instability undermines policy continuity. Climate shocks—floods or droughts—require expensive emergency spending, blowing fiscal targets.
In this scenario, the current account deficit widens beyond 1% of GDP. Reserves deplete rapidly. The rupee comes under severe pressure. Inflation rebounds to double digits. The stock market corrects 30-40%. Pakistan returns to IMF mid-program for emergency adjustment, triggering another painful stabilization cycle.
This isn’t alarmist speculation—it’s Pakistan’s historical pattern. The country has faced similar setbacks repeatedly. What’s changed is improved reserve buffers and a more disciplined fiscal stance provide better shock absorption than in past cycles. But vulnerabilities remain acute.
The 2026 Inflection Point: What Must Happen
For Pakistan to transition from stabilization to genuine growth in 2026, five critical factors must align:
Revenue mobilization breakthroughs. Pakistan cannot sustain itself on 10-11% tax-to-GDP. Broadening the tax base, improving compliance, and rationalizing exemptions must deliver at least 1-1.5 percentage points of GDP in additional revenues. This isn’t technically difficult—digitalization and data integration can dramatically improve collection. It’s politically difficult because it requires taxing privileged sectors that have historically evaded their obligations.
Energy sector resolution. Circular debt and high electricity costs strangle industrial competitiveness. Pakistan’s electricity tariffs are among the highest in South Asia, making manufacturing globally uncompetitive. Addressing this requires politically painful decisions: rationalizing capacity payments to independent power producers, reducing transmission losses, improving recovery rates, and possibly renegotiating contracts. Without this, Pakistan cannot compete in global manufacturing.
Investment climate transformation. Why does Pakistan attract only 0.5% of GDP in FDI while Bangladesh draws 1.5% and Vietnam 6%? The answer: bureaucratic red tape, policy unpredictability, weak contract enforcement, and infrastructure deficits. Creating genuine one-stop investment facilitation, reducing regulatory approvals from months to weeks, and providing policy certainty would unlock billions in investment.
Export competitiveness revival. Pakistan’s exports have stagnated around $30-32 billion annually for years while regional peers have surged. Vietnam’s exports exceeded $370 billion in 2024; Bangladesh, despite political turmoil, maintains $45-50 billion. Pakistan needs export-led growth, requiring currency competitiveness, trade facilitation, value chain integration, and quality upgrading. The textile sector alone could double exports with better policy support.
Human capital investment. With 64% of the population under age 30, Pakistan possesses a demographic dividend that could propel growth—or become a demographic disaster if unmanaged. This requires massive investment in education, vocational training, and healthcare. Currently, education spending hovers around 2% of GDP, among the world’s lowest. Doubling this, with reforms ensuring quality, would transform long-term potential.
The Corruption Challenge: Elite Capture and Growth
The IMF’s corruption diagnostic reveals something Pakistan has long known but rarely confronted systematically: 5-6.5% of GDP is lost annually to corruption through elite capture. This isn’t petty bribery—it’s systemic policy distortion where powerful groups extract rents through protective regulations, subsidized inputs, tax exemptions, and procurement manipulation.
Consider the energy sector. Independent power producers negotiated extraordinarily favorable contracts in the 1990s and 2000s, guaranteeing dollar returns regardless of demand. These “capacity payments” now drain billions annually, creating circular debt that cascades through the economy. Why do these contracts persist? Because the beneficiaries have political influence to block reform.
Or examine tax exemptions. Pakistan grants hundreds of billions in tax expenditures annually—concessions to specific sectors, mostly benefiting large, connected businesses. A 2024 analysis found rationalizing just 30% of these exemptions could raise 1.5% of GDP in additional revenue. Yet reform stalls because beneficiaries lobby intensively against rationalization.
Breaking elite capture requires more than anti-corruption campaigns; it demands institutional reform: transparent procurement systems, merit-based bureaucracy, independent regulators, and genuine competition policy. The IMF diagnostic is helpful precisely because it shifts the conversation from moralistic hand-wringing to concrete institutional diagnostics.
Climate and Resilience: The Overlooked Variable
Here’s what makes Pakistan’s outlook uniquely precarious: climate vulnerability. The 2025 monsoon floods affected almost 7 million people and caused an estimated 0.6% of GDP in damage. This follows the catastrophic 2022 floods that inundated one-third of the country, causing $30 billion in damages.
Pakistan ranks among the world’s most climate-vulnerable nations despite contributing negligible global emissions. Rising temperatures threaten agricultural productivity in a country where agriculture employs 40% of the workforce. Glacier melt in the north creates water scarcity risks for irrigation-dependent farming. Extreme weather events—floods, droughts, heatwaves—are increasing in frequency and intensity.
The IMF’s Resilience and Sustainability Facility, providing $200 million in the latest disbursement, addresses this directly. But Pakistan needs far more comprehensive climate adaptation: improved water storage and irrigation systems, disaster-resilient infrastructure, agricultural diversification, and early warning systems. The World Bank estimates Pakistan requires $8-10 billion annually in climate adaptation investments through 2030.
Climate isn’t just an environmental issue—it’s a macroeconomic variable that can blow apart fiscal plans, devastate agricultural output, and trigger massive humanitarian emergencies requiring expensive relief. Any serious 2026 outlook must account for climate risk.
The Regional Context: Where Pakistan Stands
Pakistan doesn’t compete in isolation. Its South Asian neighbors offer instructive contrasts. India, despite comparable governance challenges, maintains 6-7% growth through a larger domestic market, more diversified economy, and deeper capital markets. Bangladesh, having graduated from least-developed status, sustains 5-6% growth driven by garment exports and steady policy continuity.
Even Sri Lanka, having endured debt default and political crisis in 2022, is stabilizing faster than expected. Its reform program, while painful, has restored some fiscal credibility and attracted investment interest.
Pakistan’s advantages are real: a large, young population; strategic location between South Asia, Central Asia, and the Middle East; reasonable infrastructure; and a substantial diaspora providing remittances and potential investment. Its disadvantages are equally real: political instability, security challenges, weak institutions, and policy inconsistency.
The critical question: can Pakistan leverage its advantages while addressing its weaknesses? Historical evidence suggests caution. Pakistan has squandered similar opportunities repeatedly. But circumstances have changed. The regional security environment has stabilized somewhat. China’s Belt and Road infrastructure provides connectivity options. Gulf states, particularly Saudi Arabia and UAE, show investment interest. Global firms seeking China+1 diversification could include Pakistan.
The window exists. Whether Pakistan can seize it depends on choices made in 2025-26.
What This Means for Stakeholders
For investors: Pakistan offers asymmetric opportunities with commensurate risks. The stock market’s 50%+ returns in 2025 reflect compressed valuations catching up to improved fundamentals. Banking, cement, energy, and consumer sectors show promise. But political and policy risks remain elevated. Diversification is essential. Consider Pakistan as a 5-10% portfolio allocation, not a concentrated bet.
For businesses: Pakistan’s 240 million person market and low per-capita income suggest massive consumption growth potential as incomes rise. But doing business requires patient capital, local partnerships, and willingness to navigate bureaucracy. Sectors with demonstrated success—textiles, IT services, food processing—offer proven paths. Emerging sectors like renewable energy, e-commerce, and fintech show potential but require regulatory navigation.
For policymakers: The 2025-26 period represents a narrow window for transformative reform. Stabilization creates space for politically difficult decisions—but that space won’t last forever. Prioritize revenue mobilization, energy sector restructuring, investment climate improvement, and export competitiveness. Most critically, build institutional capacity that outlasts any single government. Pakistan’s problem isn’t lack of plans—it’s lack of implementation and sustainability.
For citizens: Understand that stabilization isn’t prosperity. Demand more than fiscal metrics; demand job creation, service delivery, education access, and corruption accountability. Pakistan’s youth represent its greatest asset—but only if provided opportunities to contribute productively. Brain drain isn’t inevitable; it’s a policy choice reflecting failure to create domestic opportunity.
The Verdict: Cautious Optimism Grounded in Reality
So where does this leave Pakistan in 2025, looking toward 2026? In a place simultaneously better and more fragile than simple metrics suggest.
The stabilization is real. Pakistan has stepped back from the 2023 precipice. Reserves are rebuilding, inflation has declined, fiscal discipline has improved, and market confidence has partially returned. These aren’t trivial achievements—they required painful adjustment and represent genuine progress.
But stabilization isn’t transformation. Growth barely outpacing population expansion doesn’t create jobs at scale. Debt servicing consuming half the budget leaves no fiscal space for development. Foreign investment at 0.5% of GDP signals ongoing skepticism. Poverty affecting 45% of citizens demands far more aggressive inclusive growth.
The choice Pakistan faces isn’t between crisis and prosperity—it’s between muddling through and breakthrough. Muddling through means 3-3.5% growth indefinitely, stable but stagnant, avoiding disaster but not achieving potential. Breakthrough means accelerating to 5-6% sustained growth through genuine reform, creating millions of jobs, dramatically reducing poverty, and fulfilling Pakistan’s considerable potential.
Which path materializes depends on choices made in 2025-26. The external environment is reasonably favorable—global growth continues, commodity prices are manageable, Gulf investment interest exists, and IMF support provides buffer. The domestic environment is more uncertain—political stability is fragile, coalition dynamics complicate reform, and vested interests resist change.
History suggests skepticism. Pakistan has disappointed repeatedly, choosing expedience over reform, short-term survival over long-term strategy. But history also shows capacity for surprise. Pakistan has demonstrated resilience through extraordinary challenges. The question isn’t capability—it’s will.
For 2026, expect continued stabilization with modest growth acceleration if reforms progress. The base case of 3.2-3.5% growth, 5-6% inflation, $25-28 billion reserves, and gradual debt-to-GDP improvement is achievable and likely. Whether Pakistan breaks through to 5%+ sustained growth depends on policy courage—expanding the tax base, restructuring energy, improving business climate, and prioritizing exports.
The immediate crisis has passed. The chronic challenges remain. Pakistan’s economic outlook for 2025-26 is neither euphoric nor catastrophic—it’s cautiously optimistic, grounded in real progress but acutely aware of formidable obstacles ahead.
The country stands at a crossroads. One path leads to continued muddling—stable but mediocre, avoiding crisis but not achieving potential. The other leads to genuine transformation—politically difficult but economically transformative. Which path Pakistan takes will define not just 2026, but the trajectory of the next decade.
The data is mixed. The potential is real. The choice is Pakistan’s.
Sources Referenced:
- International Monetary Fund (IMF) reports and projections
- State Bank of Pakistan data
- World Bank Pakistan assessments
- Trading Economics statistical data
- Ministry of Finance debt sustainability analysis
- Pakistan Stock Exchange performance metrics
- Multiple authoritative economic research institutions
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The global Banking growth is becoming more uneven, capital is increasingly sensitive to financing costs, and investors must distinguish a convincing story from an investable price. This guide focuses on research methods and risks rather than predictions of guaranteed returns. The IMF October 2026 outlook projects 3.1% global growth and 4.7% inflation for 2026, while the IMF financial-stability assessment warns that market resilience coexists with important vulnerabilities.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind global banking trends 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Digital banks are extending beyond borders
Technology can reduce the need to duplicate large physical branch networks, but banking remains subject to local licensing, deposit protection, consumer law and capital rules. Cross-border scale is a business model, not a regulatory exemption. Readers should distinguish a licensed bank from an e-money provider, broker or unregulated payments application. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Artificial intelligence in credit and fraud
Banks use machine learning for transaction screening, fraud detection, service operations and risk analysis. The operational promise is significant, but opaque credit models can create unfair outcomes, and false-positive fraud alerts can disrupt customers. Model governance requires testing, human accountability, explainability and correction routes. Customer consent does not remove every data-protection obligation. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Cybersecurity is now systemic finance risk
An attack against a large processing vendor can affect many institutions simultaneously. The IMF’s October 2026 stability assessment identifies sophisticated cyber threats alongside sovereign-yield and AI valuation shocks. Banks should test recovery procedures, third-party concentration, authentication controls and incident communications, not merely purchase security software. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Compliance: technology must support judgment
Anti-money-laundering monitoring, sanctions screening and know-your-customer processes are increasingly automated. False matches and poor data can cause excessive account restrictions, while under-detection carries serious legal exposure. Institutions need measurable controls, independent audits and escalation channels. The Financial Stability Board provides international coordination context but rules vary by jurisdiction. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
What Pakistani customers and banks should do
Customers should verify a provider’s licensing status, understand complaint mechanisms, enable strong authentication and never disclose one-time passcodes. Financial firms need resilient payment systems, staff training and clear consent practices. Track SBP circulars for locally applicable requirements rather than extrapolating foreign regulations to Pakistan. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
Why the headline growth rate hides divergence
For why the headline growth rate hides divergence, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why the headline growth rate hides divergence, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Pakistan’s four exposure channels
For pakistan’s four exposure channels, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For pakistan’s four exposure channels, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What the latest IMF agreement does and does not mean
For what the latest imf agreement does and does not mean, Economic resilience is the capacity to manage adverse shocks without repeatedly disrupting investment and consumption. Predictable policy, transparent fiscal choices and adequate external liquidity matter alongside short-term growth acceleration.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what the latest imf agreement does and does not mean, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What businesses should prepare for
For what businesses should prepare for, Growth averages blur distribution. A country manufacturing sought-after electronics can gain from a technology upcycle while an energy importer faces a larger fuel invoice. That contrast explains why Pakistan needs an exposure-weighted reading of international forecasts rather than simply celebrating a higher headline GDP projection.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what businesses should prepare for, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
The policy choices that determine resilience
For the policy choices that determine resilience, The most useful indicator is not one number but a sequence: orders received by exporters, import bills, financial inflows, electricity charges and jobs created. These measures reach families at different speeds, which is why apparently stable GDP figures can coexist with a sense of economic pressure.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the policy choices that determine resilience, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
Global growth is not the same as broad prosperity. Pakistan’s outcomes will depend less on the global average than on the channels through which external demand, energy, financing, and technology influence local firms. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
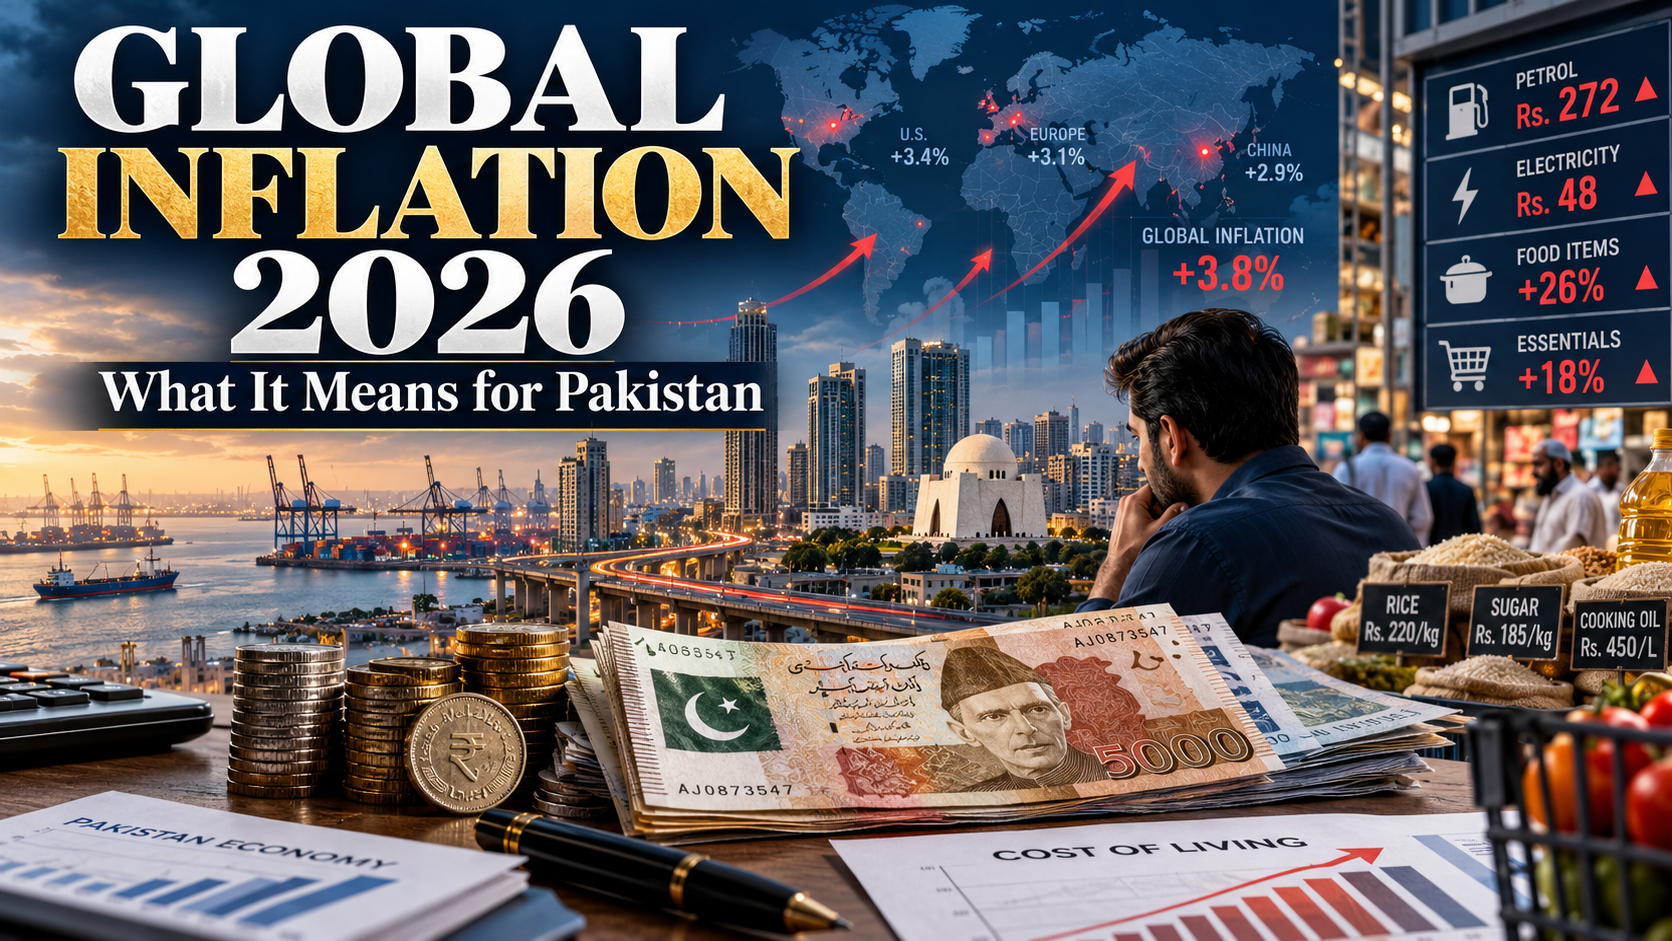
Global inflation is rising again in 2026, and energy is the main cause. The International Monetary Fund expects global headline inflation to climb to 4.7% this year, up from 4.1% in 2025, mainly because of higher energy and food prices (IMF, World Economic Outlook, October 2026). For import-dependent countries such as Pakistan, the shock arrives through fuel pumps, transport fares and the cost of imported goods.
Key Takeaways
- The IMF projects global inflation of 4.7% in 2026, easing to 4.1% in 2027.
- Energy and food prices are the main drivers, linked to the Middle East conflict and supply disruptions.
- Global growth is slowing at the same time, to about 3.1% in 2026, which makes the trade-off harder for central banks.
- Pakistan’s headline inflation was 10.26% year on year in September 2026, well above the State Bank’s 5 to 7% target range.
- Households and businesses should plan for higher transport and import costs, and should not assume a quick return to lower inflation.
The IMF numbers in brief
The IMF sees global growth slowing from 3.5% in 2025 to 3.1% in 2026, before recovering to 3.4% in 2027 (Trend.az, reporting the IMF release). The more worrying signal is that inflation is rising while growth slows. When an economy slows and prices rise together, policymakers have fewer good options.
The IMF has also said the global economy is resilient but increasingly uneven. Countries that benefit from the AI investment boom or favourable terms of trade are doing relatively well. Many energy-importing and low-income countries face much harder conditions (Trend.az).
Why energy is doing the damage
Energy feeds into almost everything: freight, fertiliser, food processing, manufacturing and electricity. One press summary of the IMF analysis reports that energy prices remain roughly a quarter higher than before the shock (Outlook India).
This is why interest rates alone cannot solve the problem. Higher borrowing costs reduce demand, but they do not produce more oil or gas. Central banks can slow second-round effects, where higher fuel costs feed into wages and expectations. They cannot lower the price of a barrel.
Supply shock or demand boom?
Demand-driven inflation comes from too much spending chasing too few goods. Supply-driven inflation comes from higher input costs that squeeze output. The 2026 episode is mostly supply-driven, and that changes the policy answer. Rate rises work well against demand-driven inflation. Against supply-driven inflation, they work more slowly and at a higher cost to growth.
A Pakistani analysis published in April made this point directly: inflation there is no longer driven solely by excess demand, yet policy still relies heavily on high interest rates (Bol News).
Our reading is that global inflation in 2026 is a supply problem that central banks will try to treat with demand tools. A prolonged period of high rates looks more likely than a sharp reversal.
Pakistan: inflation above 10% and the rate dilemma
Headline inflation in September 2026 was 10.26% year on year, and the monthly rise of 1.27% was driven by energy costs (ARY News, citing PBS data). Electricity and fuel offset a sharp slowdown in food prices. Core inflation, which excludes food and energy, ran between 8.1% and 8.6% (The Express Tribune).
The State Bank kept its policy rate at 11.5% in September, by a seven-to-three vote (The Express Tribune). It had raised rates by 100 basis points in April, the first hike in nearly three years (Bol News).
The government has told the IMF that inflation could fall to 7.5% if the Middle East situation normalises and Brent averages $80 a barrel in the current fiscal year. That is a conditional assumption, not a forecast. The IMF has urged Pakistan to adjust both exchange-rate and interest-rate policy to keep inflation and the current account deficit under control (The Express Tribune).
How the shock travels
For a Pakistani household, the chain is short. Petrol and diesel prices move first. Transport fares follow within weeks. Food prices rise through freight and packaging. Imported goods become more expensive as the rupee comes under pressure.
Food complicates the picture. Tomato prices fell about 25% month on month in the September data, and chicken prices fell about 8% (ARY News). Seasonal food swings can hide energy pressure for a month or two, which is why economists watch core inflation alongside headline figures.
What this means for households and businesses
Households: Treat transport and utility costs as fixed for budgeting purposes. If you carry variable-rate debt, remember that the policy rate feeds directly into repayments.
Small businesses and importers: Build fuel and freight surcharges into quotes where possible. Review supplier contracts for currency clauses. Keep working capital buffers, because higher rates raise the cost of bridging cash gaps.
Investors: A prolonged hold at high rates is a different environment from a rapid easing cycle. This is general information, not investment advice.
Risks, limitations and uncertainties
- IMF figures are projections. They will change as conflict and energy prices evolve, and the October outlook flags downside risks.
- The government’s 7.5% assumption depends on Brent averaging $80 a barrel. A sustained spike would push inflation higher.
- Pakistan’s monthly CPI and policy-rate figures are subject to revision.
- Pakistan can diverge from the global average because of the rupee, administered prices and food supply.
This article is for general information and is not personalised financial or economic advice.
FAQ
Will global inflation rise in 2026? The IMF expects global headline inflation to rise to 4.7% in 2026, from 4.1% in 2025 (IMF).
Why is inflation rising again? Energy and food costs are the main drivers, with supply disruptions linked to the Middle East conflict pushing fuel prices up.
Will inflation fall in 2027? The IMF projects global inflation easing to 4.1% in 2027. That could change quickly if energy supply worsens.
Why is Pakistan’s inflation above the global average? Pakistan imports much of its fuel, so energy shocks pass through quickly. Electricity and fuel rose in the latest data, and the rupee adds pressure.
Will the State Bank raise rates again? It has kept rates at 11.5% and has signalled it will tighten further if needed to prevent second-round effects. Future decisions depend on inflation, the exchange rate and energy prices.
Conclusion
Global inflation is rising in 2026 because energy and food costs have jumped, and the IMF expects it to ease only gradually. For Pakistan, the challenge is sharper, with inflation above 10% and limited room to cut rates. Watch oil prices, the State Bank’s next decision and monthly CPI releases. Those signals will show whether the shock is fading or becoming entrenched.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

How Global Interest Rates Affect Savings, Loans and Investments

How to Invest During High Inflation: A Global Guide

Best Global Stocks to Watch in 2026: Four Sectors to Research

Pakistan’s 2027 Growth Strategy: Exports, AI, Energy and Jobs

Pakistan Economy FY2027: IMF Reform, Debt and Recovery Outlook

Global Interest Rates 2027: Risks for Pakistan’s Rupee and Debt

Energy Shock 2026–2027: Oil, Gas and Pakistan’s Economy

World Trade 2027: Tariffs, Supply Chains and Pakistan Exports

AI Investment Boom 2026–2027: Can Pakistan Capture the Upside?

Global Economy 2026–2027: What Slower Growth Means for Pakistan

Why Global Inflation Is Rising Again in 2026, and What It Means for Pakistan

Raast Pakistan 2026: Digital Payments, Fintech

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

SpaceX IPO 2026: History’s Biggest Stock Debut?

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Is AI a Stock Bubble in 2026? What the Data Shows

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pingback: Pakistan's Startup Revival: How Hybrid Financing Drove a $74 Million Surge in 2025 - The Economy
Pingback: K-Electric Tariff Cut Sparks $2B Arbitration Crisis - The Economy