
Analysis
Pakistan’s Economic Rebound: Why the Central Bank Sees Brighter Growth Than the IMF in 2026

A closer look at competing forecasts reveals a nation threading the needle between recovery and risk
Pakistan’s economy stands at a peculiar crossroads in early 2026. While international institutions hedge their bets with cautious projections, the country’s central bank is painting a decidedly more optimistic picture—one backed by emerging data that suggests the South Asian nation may finally be breaking free from years of boom-bust cycles.
At the heart of this divergence lies a fundamental disagreement over trajectory. The State Bank of Pakistan (SBP) projects GDP growth between 3.75% and 4.75% for fiscal year 2026 (July 2025-June 2026), a forecast that sits notably above the International Monetary Fund’s more conservative 3.2% estimate. It’s not just numbers on a spreadsheet—this gap represents competing visions of Pakistan’s economic resilience amid floods, export contractions, and global uncertainty.
The Optimist in the Room
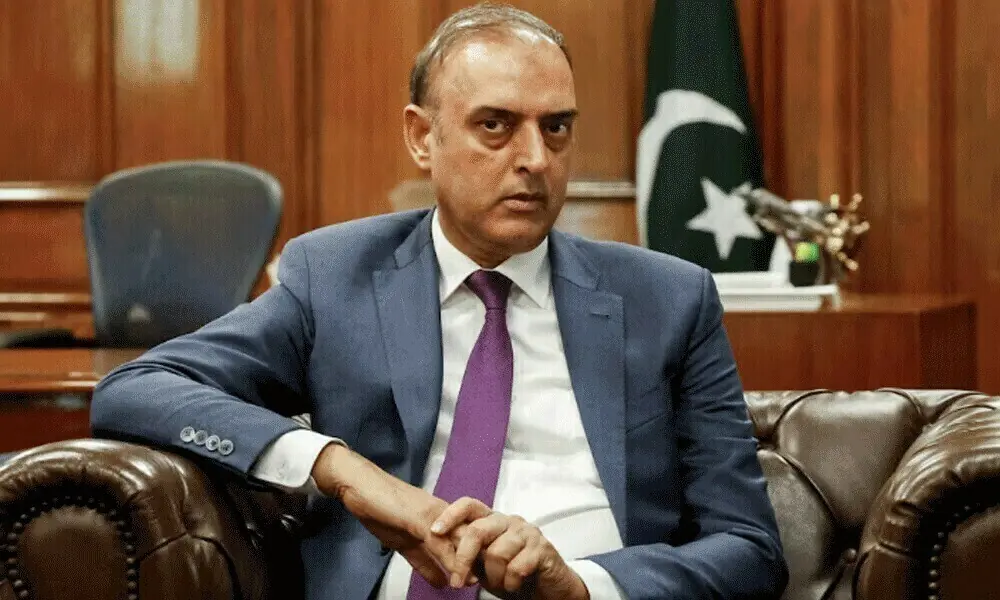
Speaking through written responses to Reuters this week, SBP Governor Jameel Ahmad made his case with the confidence of someone watching real-time indicators most analysts don’t yet see. “All these sources and indicators, along with FY26-Q1 data, point to a broad-based recovery in all three sectors of the economy,” Ahmad stated, emphasizing that the rebound extends beyond headline figures into agriculture, industry, and services.
The numbers support his optimism to a degree. Pakistan’s economy expanded 3.7% year-over-year in the first quarter of FY26, compared to a mere 1.6% in the same period last year. Large-scale manufacturing—often considered the bellwether of industrial health—posted 6% growth during July-November 2025, with the Quantum Index of Manufacturing reaching its highest level since FY2016. Automobiles surged 61% year-over-year in November, petroleum products jumped 44%, and even wearing apparel climbed 18%.
These aren’t marginal improvements. They suggest something fundamental may be shifting in Pakistan’s economic machinery, particularly as financial conditions ease following a cumulative 1,150 basis points in policy rate cuts since June 2024. The SBP’s benchmark rate now sits at 10.5%, down from a punishing 22% that choked off growth during the 2023 crisis.
Why the IMF Sees Things Differently
The Fund’s January 2026 World Economic Outlook Update tells a more subdued story, downgrading Pakistan’s FY26 growth forecast from 3.6% to 3.2%—a revision that reflects persistent concerns about structural weaknesses. The IMF’s caution isn’t unfounded. Pakistan’s export earnings fell 8.7% year-over-year in the first half of FY26, declining to $15.18 billion from $16.63 billion in the same period last year. The trade deficit widened as imports climbed back to $5.5 billion monthly, up from $3.5 billion during the height of capital controls.
Moreover, the IMF’s assessment incorporates the economic drag from 2025’s devastating floods, which Finance Minister Muhammad Aurangzeb acknowledged would shave 0.5 percentage points off GDP growth. The disaster killed over 1,000 people and caused at least $2.9 billion in damage to agriculture and infrastructure—a reminder that Pakistan remains among the world’s most climate-vulnerable nations despite contributing less than 1% of global emissions.
“The flooding this year is going to shave off roughly point 5% from our GDP growth forecast, so it’s real,” Aurangzeb said at a population summit, underscoring that climate adaptation can no longer be treated as an academic discussion but must be embedded in fiscal planning.
The World Bank projects 3.0% growth for FY26, while S&P Global Market Intelligence forecasts 3.5% for FY26 rising to 4.4% in FY27. The Asian Development Bank sits at 3.0% for 2026. The consensus among multilateral lenders: Pakistan is recovering, but fragility remains high.
The Hidden Strength: Remittances and Resilience
Here’s where Ahmad’s confidence finds solid footing. Workers’ remittances surged 11.3% to $23.2 billion during July-January FY26, with January alone bringing in $3.5 billion—a 15.4% year-over-year increase. The SBP governor projects remittances will reach $42 billion by year’s end, which would represent the highest annual inflow on record and play a crucial role in keeping the current account deficit within the projected 0-1% of GDP range.
This matters enormously. Pakistan’s previous growth spurts often led to currency pressure and reserve depletion as imports surged faster than export earnings. But sustained remittance growth—driven by higher manpower exports, reduced gaps between formal and informal exchange rates, and government incentive packages—is providing a more stable external financing cushion.
Foreign exchange reserves tell a similar story of improvement. SBP reserves surpassed $16.1 billion in mid-January, exceeding the IMF program target, with Governor Ahmad projecting they’ll climb to $18 billion by June 2026 and potentially $20.2 billion by December 2026. That would mark an all-time high, a far cry from the $2.8 billion nadir of early 2023 when Pakistan teetered on the edge of default.
Agriculture: Performing Beyond Expectations
Perhaps the most surprising element of Ahmad’s optimism centers on agriculture, which accounts for roughly 23% of GDP. Despite last year’s floods affecting significant swaths of farmland, the sector has demonstrated remarkable resilience. “Agricultural activity had remained resilient despite floods, and it is even performing better than its targets,” the governor noted.
High-frequency indicators suggest crop output recovered faster than anticipated, partly due to improved water management and rapid post-flood rehabilitation. This matters not just for GDP accounting but for food inflation, employment in rural areas where 60% of Pakistanis live, and the political stability that flows from keeping staple prices in check.
The contrast with 2022’s catastrophic floods—which submerged one-third of the country and caused an estimated $30 billion in losses—is instructive. Authorities have learned, albeit expensively, that pre-positioning disaster response and accelerating agricultural credit disbursement can significantly mitigate economic fallout.
The Manufacturing Momentum
Large-scale manufacturing’s rebound deserves closer examination. The 6% growth in July-November wasn’t uniform—machinery and equipment contracted 16%, and leather products fell 2.3%—but the breadth of expansion across 16 industrial groups suggests this isn’t a one-sector story.
Cement dispatches rose 9.7% to 25.8 million tonnes in July-December, reflecting construction sector revival. Food and beverages, coke and petroleum products, and electrical equipment all posted solid gains. According to Topline Securities, the brokerage increased its LSM growth target from 2.5% to 4.0% for FY26 based on sustained momentum into the second quarter.
The question is whether this industrial recovery can translate into export competitiveness. Governor Ahmad argues that export declines reflect “low global prices and border disruptions rather than softer activity”—a claim that finds some support in high-frequency production data but remains contentious among trade analysts who point to persistent competitiveness challenges.
Inflation: The Dog That Hasn’t Barked
One of Pakistan’s most remarkable achievements has been taming inflation, which peaked at 38% in May 2023 but dropped to a historic low of 3.2% by June 2025. The SBP now projects inflation will remain within the 5-7% target range during both FY26 and FY27, barring near-term volatility.
This inflation-growth combination—if sustained—would be unprecedented in Pakistan’s recent history. Previous growth accelerations typically coincided with surging prices as supply constraints bound quickly. The current episode suggests structural improvements in food supply chains, reduced import dependency for key staples, and credible monetary policy may be creating a different dynamic.
Still, risks abound. Global commodity price volatility, particularly for oil and food, could quickly upend projections. Recent border closures with Afghanistan have disrupted trade flows, while the specter of new global tariffs under shifting U.S. trade policy adds uncertainty.
Comparing Regional Trajectories
Context matters. India’s economy is projected to grow 6.4% in FY26 according to the IMF, while Bangladesh faces its own set of challenges with growth forecasts around 5-5.5%. Pakistan’s 3.75-4.75% range—if achieved—would represent solid recovery but still trail regional peers in absolute terms.
The gap reflects deeper structural differences. India has successfully diversified its export base, attracted significant foreign direct investment in manufacturing and technology, and built a services sector that now accounts for 55% of GDP. Bangladesh leveraged its garment industry into a export powerhouse, though political instability in 2025 has created new uncertainties.
Pakistan’s challenge is threading a narrower needle: maintaining macroeconomic stability while implementing productivity-enhancing structural reforms that can lift trend growth above 4-5%. Governor Ahmad acknowledged this explicitly, noting that “productivity-enhancing structural reforms will be essential over the medium term to achieve higher and more sustainable growth.”
What This Means for Investors
For international investors eyeing Pakistani assets, the divergent forecasts present both opportunity and risk. Pakistani equities have rallied on improving macro fundamentals, with the KSE-100 index posting strong gains through late 2025 and early 2026. Corporate earnings in cement, banking, and consumer goods have exceeded expectations as borrowing costs declined and domestic demand recovered.
Pakistan also plans to issue panda bonds—yuan-denominated debt sold in China’s domestic market—around the Lunar New Year as part of efforts to diversify external financing and broaden its investor base. This follows successful Eurobond placements that saw healthy demand from frontier market specialists betting on continued stabilization.
Yet sustainability concerns linger. Pakistan’s debt-to-GDP ratio, while declining from peak levels, remains elevated at around 72%. The IMF warns outstanding debt may increase to Rs117,441 billion by 2030, though the ratio should gradually decline to 60.7%. Interest payments are projected to consume ever-larger shares of the budget, limiting fiscal space for development spending.
Tax revenue remains a persistent weak spot. Despite government targets to raise the tax-to-GDP ratio to 13%, current projections suggest this goal is unlikely by 2030. Persistent tax evasion, narrow bases, and weak enforcement continue to constrain fiscal capacity.
The Role of Digital Economy Growth
One angle largely missing from traditional forecasts is the accelerating digitalization of Pakistan’s economy. Fintech adoption has surged, with mobile wallet users exceeding 100 million and digital payments growing rapidly. E-commerce platforms have proliferated, creating new retail channels and employment opportunities, particularly for young people and women in urban areas.
Governor Ahmad’s optimism may partly reflect these hard-to-measure but real shifts in how Pakistanis transact, save, and invest. Digital financial inclusion is creating formal economic activity that previous generations conducted entirely in cash, outside official statistics. The SBP has been notably forward-leaning in licensing digital banks and payment platforms, betting that financial technology can help leapfrog traditional infrastructure gaps.
Scenarios and Risks
Looking ahead, several scenarios could play out. In the optimistic case, policy rate cuts continue to percolate through the economy, manufacturing momentum sustains, and agriculture delivers another solid year despite climate risks. Remittances stay strong, the current account remains manageable, and foreign reserves continue building. In this scenario, Pakistan hits the upper end of SBP’s 4.75% growth forecast, validating Ahmad’s confidence.
The pessimistic scenario sees global commodity price spikes (particularly oil), renewed border tensions affecting trade, climate disasters exceeding current assumptions, and domestic political instability undermining reform momentum. Export competitiveness fails to improve, the trade deficit widens beyond projections, and reserves come under pressure. Growth settles toward the IMF’s 3.2% forecast or even lower.
The base case likely falls somewhere between—growth around 3.5-4.0%, muddling through with incremental improvements but lacking the breakout transformation Pakistan’s young, growing population needs. The difference between these scenarios often comes down to execution on structural reforms: tax administration, energy sector efficiency, privatization of loss-making state enterprises, and trade facilitation.
The Bottom Line
Is SBP Governor Jameel Ahmad right to be more optimistic than the IMF? The honest answer is that we’re watching competing narratives play out in real time, each supported by different data points and analytical frameworks.
Ahmad has high-frequency indicators, manufacturing rebounds, and remittance strength on his side. He sees financial conditions improving, agriculture resilient, and broad-based recovery taking hold. The IMF sees structural weaknesses, export fragility, climate vulnerability, and a track record of false starts. Both can be simultaneously correct depending on which risks materialize and which policy bets pay off.
What’s undeniable is that Pakistan’s economy in early 2026 looks meaningfully better than it did 12 or 24 months ago. Inflation has cooled, reserves have rebuilt, growth has resumed, and the immediate crisis has passed. Whether this evolves into sustainable, inclusive development or proves another temporary respite in a longer cycle of instability remains Pakistan’s defining economic question.
For now, Governor Ahmad is making his case with conviction backed by emerging data. The next two quarters will reveal whether his optimism was prescient—or premature.
Analysis based on State Bank of Pakistan Monetary Policy Report (February 2026), IMF World Economic Outlook Update (January 2026), and reports from Reuters, Bloomberg, Financial Times, World Bank, and Asian Development Bank.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025