
Oil Markets
Pakistan and India Most Vulnerable from Oil Shock as Strait of Hormuz Tensions Escalate

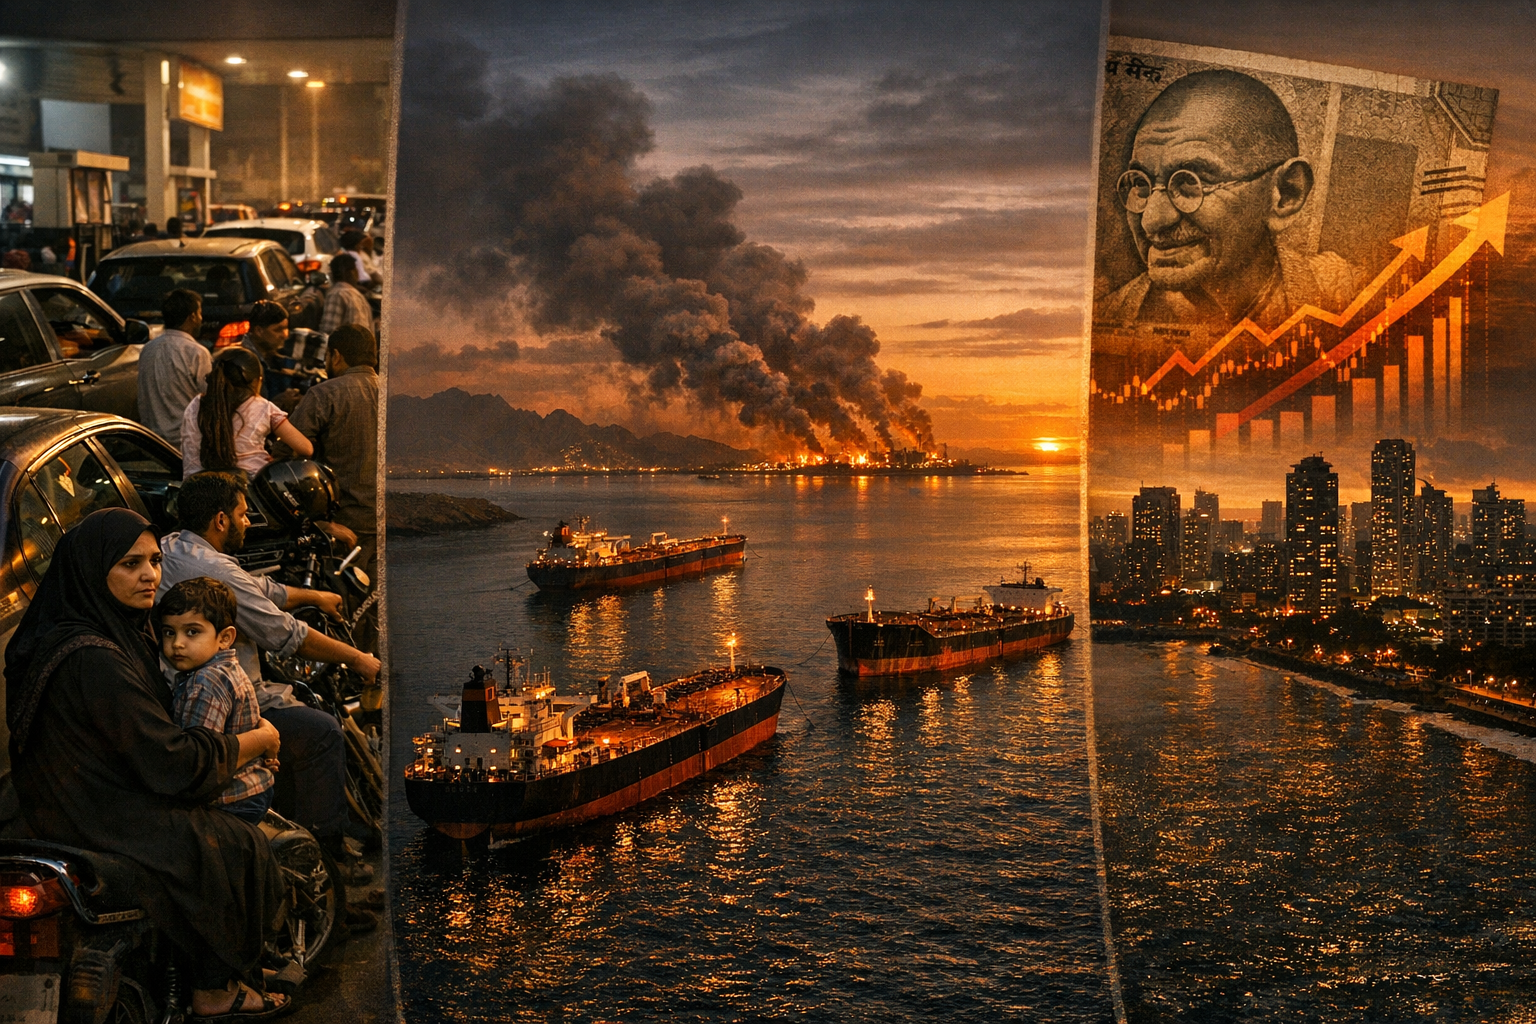
In a cramped flat in Karachi’s Lyari district, Fatima Siddiqui runs the calculations she hoped she would never have to make again. The LPG cylinder that kept her family’s stove burning through winter now costs 40 percent more than it did a fortnight ago. Across the border in Mumbai, autorickshaw driver Rajan Patil stares at a fuel pump showing prices he last saw in 2022. Neither of them has ever heard of Operation Epic Fury. Both of them are paying for it.
Oil prices surged past $100 a barrel on Sunday, March 9 — the first time crude has traded in triple digits since Russia’s invasion of Ukraine — after Brent jumped more than 30 percent, at one point topping $119, as the US and Israeli war on Iran entered its second week. Al Jazeera International benchmark Brent crude futures traded 11.6 percent higher at $103.47 per barrel on Monday morning, while US West Texas Intermediate futures were last seen 12.2 percent higher at $101.97, putting oil on track for one of its biggest single-day jumps on record. CNBC
The trigger is as structural as it is sudden. On February 28, 2026, the United States and Israel initiated coordinated airstrikes on Iran under Operation Epic Fury, targeting military facilities, nuclear sites, and leadership, resulting in the death of Supreme Leader Ali Khamenei. Wikipedia Iran’s retaliation was immediate and surgical: tanker traffic through the Strait of Hormuz dropped to four vessels on Sunday, March 1, compared with an average of 24 per day since January. Euronews For the world’s most critical energy chokepoint — the narrow passage connecting the Persian Gulf to the Arabian Sea — that is the equivalent of cardiac arrest.
For Pakistan and India, it is something closer to a pre-existing condition suddenly, violently exposed.
Why the Strait of Hormuz Is the Aorta of South Asian Energy
The geography of South Asia’s energy dependency is stark. Almost half of India’s crude oil imports and about 60 percent of its natural gas supplies move through the Strait of Hormuz. Seatrade Maritime Qatar and the United Arab Emirates account for 99 percent of Pakistan’s LNG imports and 53 percent of India’s, according to Kpler data. CNBC No other major economy outside the Gulf itself carries that kind of concentrated exposure to a single 21-mile-wide chokepoint.
The majority of the crude oil shipped through the Strait of Hormuz goes to Asia, with China, India, Japan, and South Korea accounting for nearly 70 percent of shipments, according to the US Energy Information Administration. NPR But the strategic buffer that separates China — with its substantial onshore storage — from India and Pakistan is decisive. India’s limited crude oil reserves of about 100 million barrels are sufficient for only 40 to 45 days of consumption, leaving the country particularly vulnerable to supply disruptions through the Strait of Hormuz, the Asian Development Bank warned on Friday. Business Standard Pakistan has no meaningful strategic petroleum reserve at all.
The prognosis from analysts is blunt. BMI (Fitch Solutions) identifies Pakistan and India as the most vulnerable among emerging markets, as energy importers with relatively high exposure to the Strait of Hormuz, while Egypt and Turkey are singled out for secondary exposure due to high energy import bills, fragile external positions, large energy subsidies, and unanchored inflation. Business Recorder
The Supply Shock: Unprecedented, and Worsening
Energy market veterans are reaching for superlatives they rarely deploy. Claudio Galimberti, chief economist at Rystad Energy, compares the effective halt of oil flows through the Strait of Hormuz to blocking the aorta in a circulatory system, adding that “we have not seen anything like this in pretty much the history of the Strait of Hormuz.” NPR
The anatomy of the disruption has several compounding layers. QatarEnergy halted activity at the world’s largest liquefied natural gas export facility after it was targeted in an Iranian drone attack, while tanker traffic through the Strait of Hormuz — which handles around a quarter of global seaborne oil trade and a fifth of LNG supply — has come to a near standstill. Bloomberg Iraq and Kuwait have already begun to shut in production, with analysts warning that the UAE and Saudi Arabia may also be vulnerable if the Strait of Hormuz remains closed for a sustained period. CNBC
Goldman Sachs, which had forecast a second-quarter Brent average of $76 per barrel as recently as Wednesday, now warns of a far darker scenario. The bank estimates that traders demand about $14 more per barrel than before the conflict to compensate for increased risks, roughly corresponding to the effect of a full four-week halt in flows through the Strait of Hormuz with spare pipeline capacity used as a partial offset. If flows are halted for five weeks, prices could reach $100 per barrel — a threshold already breached. Goldman Sachs
Saul Kavonic, a senior energy analyst, captures the systemic danger with particular clarity: cutting off 15 to 20 percent of the world’s oil supply not only slows down every economy globally but also introduces an inflation impulse — and inflation plus slowing growth is stagflation, which constitutes an economic disaster. Business Recorder
Pakistan: Structurally Fragile, Acutely Exposed
Pakistan enters this crisis with no margin. An IMF bailout program, a current account that was only just stabilizing, and energy subsidies already consuming a destabilizing share of the federal budget — the Hormuz shock arrives at the worst possible moment.
Petrol prices in Pakistan rose by Rs55 per litre in March 2026, triggering long queues at filling stations, increased transport costs, and widespread public frustration. Modern Diplomacy The government’s official line — that the increase is an inevitable consequence of global oil volatility — is accurate as far as it goes. What it understates is the structural dimension: Pakistan’s near-total LNG dependence on Qatar and the UAE, combined with the absence of meaningful storage infrastructure, leaves the country exposed not just to price spikes but to physical shortfalls.
Pakistan has limited storage and procurement flexibility, meaning disruption would likely trigger fast power-sector demand destruction rather than aggressive spot bidding, according to Go Katayama, principal insight analyst at Kpler. CNBC In practical terms, that means rolling blackouts in a country where electricity shortfalls are already politically explosive.
On March 4, Pakistan officially requested that Saudi Arabia reroute oil supplies through Yanbu’s Red Sea port, with Riyadh providing assurances and arranging at least one crude shipment to bypass the closed strait. Wikipedia The arrangement provides temporary relief. It cannot substitute for the volume, reliability, or price levels to which Pakistan’s energy system is calibrated.
The Pakistani rupee, already among the most depreciated major currencies of the past three years, faces renewed downward pressure. Every $10 increase in oil prices widens Pakistan’s current account deficit by an estimated 0.4 to 0.6 percent of GDP — an economy that cannot absorb that hit without either rationing foreign exchange or accelerating monetary loosening that further stokes inflation already running above 20 percent in food categories.
India: Scale Amplifies Vulnerability
India’s exposure is structural rather than acute — but at Indian scale, structural vulnerability produces acute consequences.
With nearly 90 percent of India’s crude oil requirement met through imports, any disruption in global energy supply — particularly through the Strait of Hormuz — poses a direct risk to macroeconomic stability, according to SBI Research. Business Today Moody’s warned that costly energy imports would weaken the rupee, raise inflation, worsen the current account balance, and complicate monetary policy as well as fiscal management if they lead to expanded subsidies to offset the economic shock. Business Standard
The fiscal arithmetic is unforgiving. India’s Union Budget for 2026–27 was constructed on oil averaging $68 to $70 per barrel. At $103, every rupee of subsidy relief the government extends to consumers — and political pressure to do so is intense, with state elections pending — translates directly into fiscal slippage. Every rupee of subsidy withheld translates into retail fuel price increases of ₹5 to ₹15 per litre on current trajectory estimates.
India has already ordered refiners to maximise production of cooking fuel as imports from the Middle East decline, while gas-intensive industries, particularly fertiliser manufacturers, may face pressure if LNG supplies remain tight. Business Standard The fertiliser link is particularly consequential: disrupted LNG supply constrains domestic fertiliser production just as Rabi crop planting cycles approach, threatening both agricultural output and rural inflation.
The Indian rupee’s recent relative stability — it had appreciated marginally against the dollar in early 2026 — faces a sharp test. India’s oil imports are priced in dollars, so a weaker rupee means the same barrel of oil costs more in local currency, driving inflation through the transport, manufacturing, and agriculture chains simultaneously. Wordzz
The Comparison Table: Pakistan vs India vs GCC
| Indicator | Pakistan | India | GCC Average |
|---|---|---|---|
| Oil import dependency | ~85% imported | ~90% imported | Net exporter |
| LNG sourced from Gulf | ~99% | ~53% | Exporter |
| Strategic petroleum reserve | Effectively none | 40–45 days | Substantial |
| Current account position | Fragile surplus | ~1.5% deficit | Surplus |
| Fiscal space for subsidies | Very limited | Constrained | Ample |
| Currency resilience | Low | Moderate | High |
| Exposure rating (BMI/Fitch) | Most vulnerable | Most vulnerable | Adverse but manageable |
Tourism, Logistics, and the Invisible Multiplier
The economic damage radiating from the Strait of Hormuz crisis extends well beyond oil prices. The waterway is not merely an energy corridor — it is a central artery of the global logistics system, and its disruption is reshaping aviation, hospitality, and freight networks with consequences that will outlast any ceasefire.
Cruise ships reduced activity in the Persian Gulf and stopped using the strait, stranding 15,000 passengers on six major cruise ships. Wikipedia The Gulf aviation hub model — built on Dubai and Abu Dhabi serving as transfer points between Asia and Europe — is under immediate pressure as war-risk insurance surcharges inflate operating costs and itinerary rerouting adds hours and fuel burns to long-haul routes.
For Pakistan and India, the tourism dimension cuts both ways. The Gulf diaspora — some 7 million Pakistanis and 8 million Indians working in the Gulf Cooperation Council states — represents a critical source of remittances. Any sustained economic disruption to Gulf economies, whether through reduced oil revenues or conflict-related instability, threatens remittance flows that collectively account for 7 to 8 percent of Pakistan’s GDP and a meaningful share of India’s foreign exchange receipts. BMI’s baseline scenario is that the conflict in Iran will be large but short-lived, though there is a clear risk of a prolonged war. Among emerging markets, the economic impact will be most pronounced in the GCC, reflecting the shock’s adverse effects on trade, logistics, tourism, and investment. Business Recorder The knock-on to South Asian remittance economies would be severe.
The Forward Scenarios: Baseline and Downside
Baseline (BMI/Goldman Sachs): The conflict remains intense but contained, with the Strait of Hormuz beginning to partially reopen within three to four weeks as US naval escorts provide a corridor. Goldman Sachs estimates that a four-week full halt in Hormuz flows would push Brent to around $85 to $90 per barrel, with prices moderating as Strategic Petroleum Reserve releases from the G7 — which finance ministers discussed on Monday — provide partial offset. Goldman Sachs Under this scenario, Pakistan faces six to eight months of elevated inflation and currency pressure but avoids balance-of-payments crisis. India absorbs a current account widening of approximately 0.8 to 1.2 percent of GDP.
Downside (Prolonged Disruption): If the disruption in the Strait of Hormuz persists for another one to two weeks beyond current levels, prices could move toward $130 to $150 per barrel, according to senior market analysts. Business Recorder Under this scenario, Pakistan would almost certainly require an emergency IMF facility enhancement; India would face stagflationary pressure combining slowing growth with food and fuel inflation above 8 percent. The rupee and Pakistani rupee would both face disorderly adjustment risk.
The tail risk is darker still. If infrastructure is seriously damaged in oil-rich countries along the Gulf, it could take much longer for production to normalize even after missile strikes stop, and a full closure of the Strait of Hormuz would leave OPEC barrels in the region as effectively stranded assets in an extended war scenario. NPR
Policy Responses: What Islamabad and New Delhi Are Doing
Pakistan’s immediate moves:
- Emergency request to Saudi Arabia to reroute crude shipments via the Red Sea corridor through Yanbu port
- Engagement with the State Bank of Pakistan to manage rupee liquidity and cap speculative dollar demand
- Preliminary discussions with the IMF on contingency facility options if the crisis extends beyond six weeks
India’s immediate moves:
- Directive to state refiners to maximize domestic fuel production capacity
- Reopening of discussions on Russian crude procurement from floating storage in Asian waters
- Review of strategic petroleum reserve release protocols in coordination with the IEA
Both governments face the same fundamental dilemma: subsidise to protect consumers and blow up fiscal balances, or pass through prices and risk political instability. There is no clean answer when the originating shock is geopolitical and beyond domestic control.
Investor and Traveller Takeaways
For investors with exposure to South Asian equities and credit: the Pakistani rupee and Indian rupee face asymmetric downside risk in a prolonged disruption scenario. Pakistani sovereign spreads, already elevated, will widen further on any indication of IMF program slippage. Indian equities’ energy-sector composition and the fiscal arithmetic of subsidy policy make consumer staples and financial sector names most vulnerable to earnings revisions.
For travellers and the travel industry: Gulf aviation hubs face operational disruption and insurance cost inflation that will flow through to ticket prices across Asia-Europe routes within days. Bangladesh is experiencing severe strain, with the government bringing forward Eid holidays, ordering universities to close temporarily to reduce electricity demand, and imposing limits on fuel sales amid panic buying. Business Standard Regional tourism recovery, which had only just returned to pre-pandemic levels across South and Southeast Asia, faces a significant setback.
The Strait of Hormuz has been threatened before. It has never actually closed — until now. What the markets are pricing, and what Fatima Siddiqui and Rajan Patil are already living, is the realisation that 50 years of energy-security wargaming has finally become a news headline. The models suggested Pakistan and India would be most vulnerable. The models were right.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


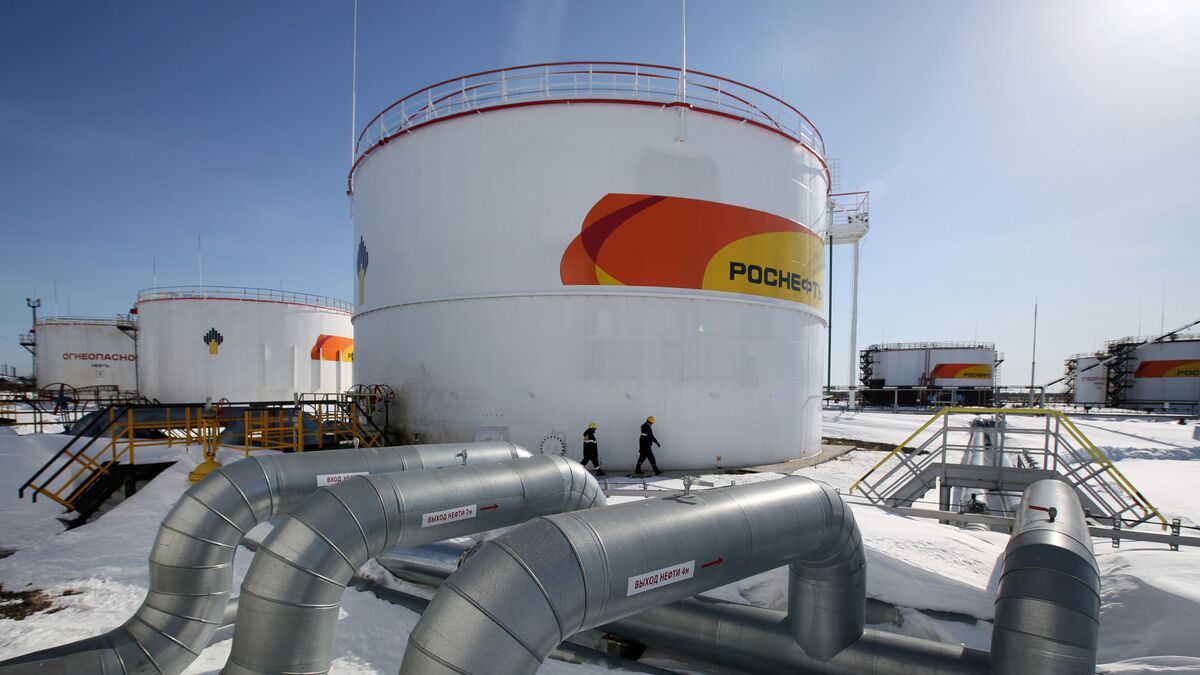
An unexpected shift in US sanctions policy has given Asian energy buyers a potentially important reprieve. It has also opened fresh questions about how importers should balance cheap fuel, diplomatic relationships and the risk that trading rules may change again.
On October 17, Reuters reported that President Donald Trump had issued an order waiving important Russia-related sanctions and tariffs before planned measures took effect. A subsequent Reuters account identified India as a significant beneficiary, given its role as a major Russian oil customer. The move reduces one category of immediate concern; it does not guarantee unlimited imports free of every restriction.
Why buyers in Asia care
Asia’s refineries compete for crude on price, quality, transport economics and availability. A sanction or tariff threat adds uncertainty to contracts even before it is implemented. Trading banks, insurers and shipowners may become more cautious; buyers may diversify supply or ask for discounts to compensate for risks.
A waiver can therefore matter before a single new tanker sails. It may improve the feasibility of existing contracts and ease pressure for rapid, expensive substitution. Still, the benefit depends on the precise terms of the waiver, the identity of the buyer and seller, the bank handling payment and the practical shipping route.
India is the immediate test case
India’s refining industry has cultivated access to discounted Russian crude, but its policymakers also value the trading relationship with Washington. The reported waiver potentially reduces friction between energy security and trade negotiations. Reuters’ October 19 analysis connected the decision to hopes for progress on a broader US–India trade deal.
Yet it would be a mistake to treat the waiver as permanent diplomatic alignment. Policy decisions may be reviewed, challenged or narrowed. India’s future purchases will still depend on relative crude prices and refinery requirements, not diplomatic headlines alone.
Why oil did not simply collapse
Market reports described some easing after the policy decision, but Middle East disruption and threats to physical energy infrastructure remained important. A Reuters oil-market report cautioned that implementation uncertainty limited confidence in sustained additional supply.
More Russian barrels accessible on paper may fail to solve problems caused by damaged refining equipment, disrupted shipping lanes or unusually tight diesel stocks elsewhere. Crude oil is also not a homogeneous product. Refineries are configured for specific blends; changing the input can increase costs or reduce efficiency.
Winners and losers are not obvious
| Stakeholder | Potential benefit | Important caveat |
|---|---|---|
| Indian refiners | Access to competitive crude | Compliance and financing |
| Other Asian importers | Some relief from global supply pressure | Eligibility differs by transaction |
| Tanker operators | More potential freight business | Insurance and security costs |
| Oil exporters competing with Russia | Demand can shift away | Overall prices and volumes still uncertain |
| Asian consumers | Possible easing in fuels | Taxes, FX and local distribution affect pump prices |
Smaller importers should not assume a waiver affecting one set of transactions automatically provides legal cover for every Russian energy purchase. Compliance teams must examine operative legal documents, not rely on a news summary as advice.
The geopolitical trade-off
Critics argue that relaxing pressure on Russia can weaken coercive leverage relating to the war in Ukraine. Supporters of relief emphasise the cost of energy scarcity and the need to stabilise prices. These perspectives reflect a genuine policy trade-off: reducing immediate energy stress may conflict with broader sanctions objectives.
A rigorous regional article should distinguish the economic effects of the waiver from an endorsement of its foreign-policy rationale. It should also avoid forecasting specific oil-price declines from a change whose practical effects are still being assessed.
What to watch in November
Importers and analysts should monitor official US rules, commercial purchase announcements, actual tanker arrivals, refinery throughput and the spread between competing crude grades. Other developments—including renewed conflict around Hormuz—could easily overwhelm the marginal supply effect of the waiver.
The paperwork behind a cheap barrel
A tanker purchase is not simply a quoted price multiplied by volume. The buyer must consider contract origin, payment route, shipping ownership, insurance, discharge location, refinery compatibility and applicable legal restrictions. Even when particular sanctions measures are waived, businesses should confirm whether related banking or export controls remain relevant to the proposed transaction.
The economic gain from a discounted crude grade also depends on refining yields. A barrel that produces a lower share of the products a refinery needs may be less valuable than a seemingly more expensive alternative. Freight routes, demurrage and quality specifications can erase an advertised discount. That is why refinery-level economics matter more than a headline claim that Russian oil is ‘cheap’.
Asian policymakers also need to distinguish short-term energy security from strategic dependence. Diversification across suppliers, fuels and transport routes generally provides resilience when a major trading partner or shipping corridor is disrupted. An importer that shifts too much procurement to one politically sensitive source may exchange today’s cheaper invoices for tomorrow’s concentrated risk.
A practical follow-up story should compare actual arrival data and refinery purchases after the waiver. Only then can readers distinguish a change in legal permission from a change in physical supply.
Are all Russian sanctions now removed?
No. Reporting describes waivers of specified measures. The exact surviving restrictions and compliance obligations must be checked against current official documents.
Will Indian petrol immediately become cheaper?
Not necessarily. Crude prices, refining margins, taxes and distribution costs intervene.
Does the waiver solve Asia’s energy security problem?
No. It can ease one bottleneck while leaving transport, geopolitical and market vulnerabilities intact.
For Asian buyers, the opportunity is flexibility—not certainty. The sensible response is to diversify procurement and understand the legal terms before betting a fuel strategy on a political announcement.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi
The global market’s biggest stories can look deceptively American: a Federal Reserve decision, a Treasury yield and a Wall Street earnings call. Yet the cost of these events is often felt most sharply across Asia, where energy import dependence, divergent monetary policies and unequal access to technology investment create different winners and losers.
The next scheduled Federal Reserve policy decision is October 28, according to its official calendar. The US 10-year Treasury yield was around 5.00% by October 23, down from higher levels earlier in the month. Oil was still elevated, while the IMF’s latest global outlook sees world growth slowing to 3.1% in 2026. These common shocks will not produce uniform Asian market returns.
Tokyo: currency moves complicate the equity story
Japan’s multinational exporters can be sensitive to yen movements because overseas revenue must be translated back into local currency, while domestic consumers and importers face different pressures when the yen weakens. The effect is not one-directional: a weaker currency may support export competitiveness but raise fuel and food import costs.
Investors should distinguish a broad index rally driven by a few large manufacturers or technology names from improving profits across the economy. Japanese government-bond yields and domestic monetary policy also matter. A US rate move may change yen-dollar incentives, but it does not dictate Japanese policy.
Kuala Lumpur: energy exposure is mixed
Malaysia’s place in the global energy system is different from that of a pure importer. Some businesses benefit from upstream prices, while manufacturers, transport operators and households can face higher costs. Currency and fiscal effects depend on domestic subsidy design, trade receipts and the balance between oil and gas revenues and imported refined products.
For equity investors, oil up should not be treated as a universal buy signal. Airlines, logistics companies, industrial users and energy-related firms can have opposing sensitivities. Malaysia’s electrical and electronics export exposure also links the country to the AI hardware cycle, but final demand and margins deserve scrutiny.
Karachi: the import bill dominates
Pakistan’s external vulnerability is sharper because energy prices can quickly affect dollar demand, local prices and business borrowing costs. The World Bank reported on October 22 that reforms and macro stabilisation had supported growth, but conflict-related pressures remained. Higher energy costs can erode these improvements even when the US equity market rises on technology earnings.
For the Pakistan Stock Exchange, sector analysis matters more than a generic Asian risk-on or risk-off label. Banks, energy firms, exporters, consumer businesses and highly leveraged industrial companies have distinct exposures to rates and exchange rates.
The regional transmission map
| Shock | Japan | Malaysia | Pakistan |
|---|---|---|---|
| US yields rise | Yen and valuation sensitivity | Funding costs, foreign flows | Dollar pressure and external borrowing context |
| Brent crude rises | Import cost pressure | Mixed effects across producers and users | Import bill, petrol and inflation pressure |
| AI investment accelerates | Capital goods and semiconductor ecosystem | Electronics supply chain opportunities | Selective digital services potential, energy constraints |
| Global demand softens | Exporters affected | Trade and tourism affected | Export and remittance channels |
These are transmission mechanisms, not guaranteed daily market movements. Political measures, domestic policies and company-specific developments can overwhelm them.
What to watch next week
The Fed’s statement and press conference will indicate how officials weigh inflation against growth. US technology earnings will test whether expensive AI infrastructure is translating into profitable demand. Oil-market shipping and security developments remain a separate source of risk that can upset even the strongest company results.
Investors should also check Asian market holidays, local economic releases and currency fixing times. Comparisons made across different trading-session cutoffs can create false narratives about which exchange responded first.
A sharper method than daily prediction
A regional investor can create a four-factor watchlist: oil, US yields, the dollar and domestic policy. For each market, identify companies with pricing power, foreign-currency debt, export income and energy-cost exposure. That framework is more durable than confident predictions about Monday’s opening index point.
How to read a cross-market comparison properly
A strong weekly comparison should fix each market’s closing date and reporting currency. If one exchange is closed for a holiday while another has traded through a major US event, their percentage changes cover different information sets. A reader can misinterpret this as one market being more resilient when the difference is mostly timing.
Currency conversion adds another complication. A stock index may gain in local currency but deliver a smaller return to an investor measuring wealth in dollars. This does not mean one series is incorrect; it means the investor’s benchmark is different. Analysts should label both local and dollar-adjusted comparisons and resist mixing them within a single ranking.
The regional supply-chain connection deserves the same precision. AI demand can benefit semiconductor and electrical-equipment producers, but the benefit is not evenly distributed across Tokyo and Kuala Lumpur, and it may have little immediate impact on a Pakistani small business facing higher power bills. A regional theme should identify channels rather than assume countries move together.
At the end of each weekly roundup, list the coming policy announcements and company results with local times. A reliable calendar may be more valuable to investors than an index-level prediction.
Will a Fed hike automatically trigger an Asian sell-off?
No. Expectations, positioning and the Fed’s message matter, alongside domestic fundamentals.
Which Asian markets benefit when oil rises?
The answer depends on the mix of producers, refiners, importers, subsidy arrangements and market valuations.
What is the most useful common comparison?
Compare earnings and cash-flow sensitivity to oil, currency and rates rather than comparing headline index changes alone.
The regional lesson: Asia is not one trade. From Tokyo to Kuala Lumpur to Karachi, the same global shock is filtered through a different currency, industrial structure and policy response.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports
Pakistan does not need to be the centre of a Middle East conflict to feel its economic consequences. When crude oil moves above $100 a barrel, the effects travel through refinery orders, shipping invoices, the rupee and ultimately the household budget. The transmission is neither immediate nor identical across products—but it is difficult to escape.
The U.S. Energy Information Administration’s Brent price series provides the benchmark that importers and analysts watch. Market datasets tracking that series showed Brent around $115 on October 20, 2026, although dated spot assessments and actively traded futures contracts are different instruments. The point is not one precise tick: sustained triple-digit crude imposes an external bill on Pakistan.
The arithmetic of a more expensive barrel
A useful illustration is deliberately simple. If a country buys an additional one million barrels at a price $10 per barrel higher, its dollar cost rises by $10 million, before freight, insurance, refining margins or taxes. That is a scenario, not a claim about Pakistan’s daily purchase volume. Scale it to actual import quantities and the significance becomes clear.
The first effect is a higher energy invoice in foreign currency. Importers need more dollars to purchase the same physical amount of fuel. Other things equal, that can worsen the merchandise trade balance and increase pressure on foreign-exchange markets. Remittances, exports, financing inflows and central-bank reserves determine how much of that pressure actually reaches the rupee.
Why petrol prices do not move one-for-one with Brent
Consumers buy refined petroleum products, not barrels of Brent. Domestic pump prices depend on refined-product prices, the timing of cargo purchases, exchange-rate conversion, freight, distribution margins and the government’s pricing and taxation arrangements. A $10 rise in benchmark crude does not mechanically imply a fixed rupee increase per litre at the pump.
There are also lags. A retailer may still be selling inventory purchased earlier, while the next shipment is already being priced at higher international rates. High diesel costs can eventually raise the prices of freight-intensive groceries, building materials and agricultural products—even where households use little diesel directly.
The rupee: a second channel of inflation
A rising dollar oil bill can be compounded by exchange-rate weakness. For an importer, a barrel priced at $110 is more expensive in local currency if the rupee depreciates than if the currency remains stable. Conversely, strong remittances and adequate foreign exchange buffers can temper pass-through. The World Bank’s October 22 Pakistan Development Update notes that strong remittances have helped rebuild reserves, highlighting why the external account must be read as a whole.
This is why headlines predicting an exact rupee level purely from Brent are unreliable. Oil is a major driver, not the only one. Capital flows, the dollar’s international strength, policies governing fuel taxes and the duration of regional disruption all matter.
Which groups feel the squeeze first?
Transport operators, airlines, logistics providers and energy-intensive factories are exposed quickly, although their ability to pass costs to customers varies. Farmers face fuel and fertilizer pressures; exporters may lose competitiveness if higher electricity and freight bills are not offset by improved prices abroad. Households experience the shock through commuting, distribution-linked food costs and changing disposable income.
For the government, the consequences are ambiguous. Certain fuel-related tax receipts may respond differently from subsidy or relief spending. A policy that cushions consumers can protect demand but create fiscal trade-offs. Public discussion should quantify those choices rather than assume that every rupee of pump-price relief is costless.
A dashboard that tells more than the oil ticker
| Indicator | What it reveals | What it cannot tell you alone |
|---|---|---|
| Brent spot and futures | Benchmark crude conditions | Pakistan’s final landed fuel cost |
| Refined diesel/petrol benchmarks | Product-market tightness | Local tax and margin decisions |
| USD/PKR and SBP reserves | Capacity to meet dollar demand | The size of future financing flows |
| Import volumes and values | Whether higher bills reflect price or quantity | Household inflation immediately |
| Domestic CPI and transport fares | Consumer pass-through | The next central-bank rate decision |
The IMF’s October world outlook flags a particularly difficult outlook for energy-importing economies outside the technology investment boom. Pakistan’s challenge fits that description: it has to preserve growth while protecting external stability.
What can businesses and households do?
Businesses should stress-test cash flow against higher freight and energy costs rather than assume a quick reversal. Firms with dollar-denominated purchases should map invoice dates and currency exposures; any hedging decision requires professional assessment of cost and suitability. Households should compare real transport and utility expenses over time instead of trying to time oil futures.
A practical import-bill sensitivity calculation
Suppose a fuel importer expects to buy 500,000 barrels over the next delivery window. At $100 per barrel, the notional crude cost is $50 million; at $115 it is $57.5 million. The additional $7.5 million arises before shipping, insurance and refining differences. This illustrative calculation should never be represented as Pakistan’s national import volume, but it helps readers understand why changes that look modest on a chart can become material in large transactions.
An important second question is whether consumption changes when prices rise. Transport firms may consolidate routes, industrial plants may adjust production and households may reduce discretionary travel. These responses lower fuel demand somewhat but can also suppress growth. An apparent improvement in the import bill caused by weak industrial activity is not the same economic success as higher export earnings.
The transmission can also be uneven across provinces and occupations. A taxi driver who purchases fuel daily faces a different adjustment period from a manufacturing company with a multi-month supply contract. Consumers may experience cost increases even before the official next-price announcement when vendors begin adjusting delivery charges.
For a transparent newsroom dashboard, report separate series for global crude, refined products, USD/PKR and domestic pump prices. Putting them on one axis without units obscures rather than clarifies the story.
Will Brent above $100 automatically cause a balance-of-payments crisis?
No. The outcome depends on volumes, financing, reserve buffers, exports, remittances and policy responses.
Can Pakistan benefit from cheaper Russian or other discounted crude?
Potentially, but only if the delivered economics work after sanctions compliance, shipping, refining compatibility and payment constraints. A headline discount is not a complete landed-cost calculation.
The deeper story: expensive oil is an economy-wide import tax paid first in dollars and then, often, through the prices that businesses and families face.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025