
Analysis
Malaysia’s 10-Year Chip Design Goal Faces Ultimate Test Amid Global Semiconductor Shifts

Malaysia stands at a crossroads in its semiconductor journey. For decades, the Southeast Asian nation has thrived as a global hub for chip assembly and testing, ranking sixth worldwide in semiconductor exports. Yet beneath this impressive statistic lies a vulnerability that policymakers can no longer ignore: Malaysia lacks the intellectual property and design capabilities that command premium margins in today’s chip industry.
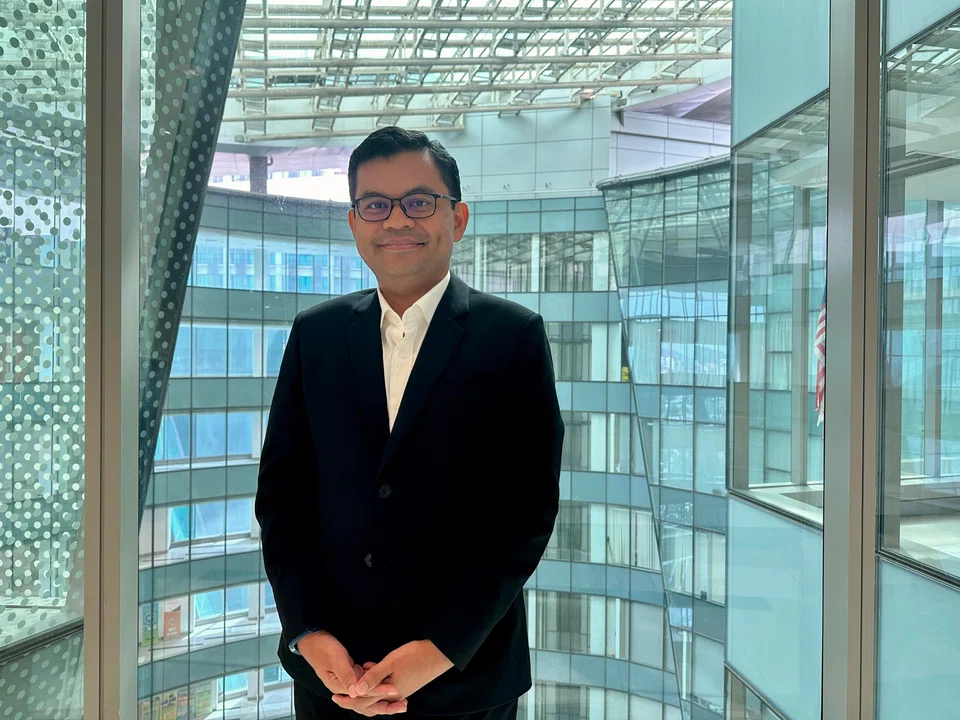
Economy Minister Akmal Nasrullah Mohd Nasir recently framed the challenge with remarkable candor. Speaking to The Business Times ahead of the Malaysia Economic Forum on February 5, 2026, he emphasized that the nation must transition from low-value assembly work to IP creation—a shift he described as the “ultimate test” for Malaysia’s semiconductor ambitions. This test isn’t merely rhetorical. It’s embedded in the 13th Malaysia Plan (RMK-13), a comprehensive blueprint that seeks to reposition the country’s semiconductor industry over the next decade.
The stakes couldn’t be higher. As global chip demand surges and supply chains undergo tectonic realignments following pandemic-era disruptions and geopolitical tensions, Malaysia faces both unprecedented opportunity and formidable competition. The question isn’t whether Malaysia can continue assembling chips—it’s whether the nation can climb the value chain to design them.
The RMK-13 Pivot: From Assembly to Innovation
The 13th Malaysia Plan represents a fundamental recalibration of the country’s semiconductor strategy. Unlike previous initiatives that reinforced Malaysia’s position in downstream activities—assembly, packaging, and testing (APT)—RMK-13 explicitly targets upstream capabilities in chip design and intellectual property development.
This pivot reflects economic necessity. According to Statista, global semiconductor revenues exceeded $600 billion in 2024, with design and IP licensing commanding profit margins two to three times higher than assembly operations. Malaysia’s current model, while generating substantial export volumes, captures only a fraction of this value creation.
The National Semiconductor Strategy (NSS), unveiled as part of RMK-13’s implementation framework, sets ambitious quantitative targets:
- RM500 billion in investment attraction over the plan’s duration
- 60,000 skilled semiconductor workers by 2030, representing a near-doubling of the current technical workforce
- GDP growth of 4.5-5.5% annually, with semiconductors identified as a key high-growth sector
- Home-grown chip designs within 5-7 years through strategic partnerships
These aren’t aspirational figures pulled from thin air. They’re undergirded by concrete partnerships, most notably a $250 million collaboration with Arm, the British chip architecture firm now owned by SoftBank. This deal, reported by Reuters, aims to develop Malaysia-designed processors leveraging Arm’s instruction set architecture—the same foundation used by Apple, Qualcomm, and countless other industry leaders.
Challenges in the Ultimate Test
Yet Minister Akmal’s characterization of this transition as an “ultimate test” acknowledges the formidable obstacles ahead. Moving from assembly to design isn’t a linear progression—it’s a quantum leap requiring fundamentally different capabilities, infrastructure, and mindsets.
The Intellectual Property Gap
Malaysia’s current semiconductor footprint is impressive in scale but limited in scope. The country hosts operations for multinational giants including Intel, Infineon, Texas Instruments, and NXP Semiconductors. These facilities perform sophisticated packaging and testing, but the underlying chip designs—the IP that drives profitability—originate elsewhere.
Creating indigenous IP requires years of R&D investment, extensive patent portfolios, and design expertise that Malaysia is only beginning to cultivate. According to The Economist, Taiwan spent three decades building TSMC into a foundry powerhouse, while South Korea invested hundreds of billions establishing Samsung’s design and manufacturing capabilities. Malaysia is attempting a comparable transformation on an accelerated timeline.
Talent Acquisition and Development
The NSS’s target of 60,000 skilled workers by 2030 underscores perhaps the most acute constraint: human capital. Chip design engineers require specialized training in areas like circuit design, verification, and electronic design automation (EDA) tools—competencies that take years to develop and aren’t easily imported.
Malaysian universities are expanding semiconductor programs, but they’re competing globally for both students and faculty. A design engineer in Penang must be convinced to forgo potentially higher salaries in Silicon Valley, Bangalore, or Shanghai. This brain-drain challenge, analyzed in depth by the Lowy Institute, affects all emerging semiconductor hubs but is particularly acute for countries without established design ecosystems.
The government’s response involves scholarship programs, industry-academia partnerships, and incentive packages for returning diaspora engineers. Yet scaling these initiatives to produce tens of thousands of qualified professionals in four years represents an unprecedented mobilization of educational resources.
Infrastructure and Ecosystem Development
Designing advanced chips requires more than talented engineers—it demands a comprehensive ecosystem. This includes:
- Fabrication partnerships: Design houses need access to foundries willing to manufacture their chips, either domestically or through international agreements
- EDA tool access: Software from Synopsys, Cadence, and Siemens (Mentor) costs millions annually and requires extensive training
- IP licensing frameworks: Legal expertise to navigate complex patent landscapes and licensing negotiations
- Venture capital: Patient capital willing to fund 5-10 year development cycles before revenue generation
- Customer relationships: Trust-building with global OEMs who currently source designs from established providers
Malaysia’s competitors—particularly Singapore, Taiwan, and increasingly Vietnam—are simultaneously strengthening their own ecosystems, creating a regional arms race for semiconductor supremacy.
Global Context and Geopolitical Currents
Malaysia’s semiconductor ambitions unfold against a backdrop of profound industry transformation. The US CHIPS Act, the EU Chips Act, and China’s extensive subsidies have injected hundreds of billions into semiconductor development, reshaping global capacity allocation.
These initiatives present both opportunities and challenges for Malaysia. Financial Times reporting indicates that multinational corporations are diversifying supply chains away from over-concentration in Taiwan and South Korea—a trend that positions Malaysia favorably. The country’s political stability relative to some regional peers, combined with existing semiconductor infrastructure, makes it an attractive diversification destination.
However, this same diversification has intensified competition. Vietnam, Thailand, and India are also aggressively courting semiconductor investment, often with comparable or superior incentive packages. According to Bloomberg, India’s semiconductor mission involves $10 billion in government backing, while Vietnam offers corporate tax holidays extending beyond those available in Malaysia.
Moreover, technology transfer restrictions—particularly US export controls on advanced chip-making equipment and design software—complicate Malaysia’s path to indigenous capabilities. While these controls primarily target China, they create ripple effects throughout Asia’s semiconductor ecosystem, potentially limiting Malaysia’s access to cutting-edge tools and technologies.
Strategic Pathways Forward
Despite these challenges, Malaysia possesses genuine advantages that, if leveraged effectively, could make RMK-13’s goals achievable.
Established Manufacturing Presence: Unlike greenfield semiconductor initiatives, Malaysia can leverage decades of manufacturing experience. Its workforce understands cleanroom protocols, quality systems, and supply chain logistics—capabilities that complement design skills rather than replace them.
Pragmatic Partnerships: The Arm collaboration represents a viable model—partnering with established IP providers rather than developing everything indigenously. Similar arrangements with design automation companies, foundries, and academic institutions could accelerate capability development.
Focused Applications: Rather than competing directly with Taiwan or South Korea across all chip categories, Malaysia could target specific niches—automotive semiconductors for the ASEAN market, IoT chips for smart manufacturing, or specialized sensors. Success in focused applications can build credibility for broader ambitions.
Regional Integration: ASEAN’s collective market of 680 million people provides a substantial customer base for Malaysia-designed chips, particularly in consumer electronics, automotive, and industrial applications where extreme miniaturization isn’t always required.
The government’s approach, as articulated by Minister Akmal, appears to recognize these realities. Rather than wholesale abandonment of assembly operations—which remain profitable and employ thousands—RMK-13 seeks parallel development of higher-value activities, gradually shifting the country’s semiconductor center of gravity toward design and IP.
Measuring Success in the Ultimate Test
As Malaysia embarks on this transformation, clear metrics will determine whether the “ultimate test” yields passing grades. Beyond the NSS’s quantitative targets, qualitative indicators matter equally:
- Patent filings in semiconductor design originating from Malaysian entities
- Tape-outs (completed designs sent to fabrication) by domestic design houses
- Talent retention rates among semiconductor graduates and experienced engineers
- IP licensing revenue generated by Malaysian-developed designs
- Diversification of the customer base beyond traditional assembly clients
Early results won’t appear for years—chip design timelines extend well beyond political cycles. This requires sustained commitment across administrations, insulation of semiconductor policy from electoral politics, and patience from stakeholders accustomed to faster returns.
Conclusion: A Decade-Defining Endeavor
Malaysia’s semiconductor transition represents more than industrial policy—it’s a bet on the nation’s capacity for economic transformation. The pathway from sixth-largest chip exporter to significant design player demands execution excellence, sustained investment, and perhaps most crucially, resilience in the face of inevitable setbacks.
Minister Akmal’s framing as an “ultimate test” captures both the high stakes and the uncertainty ahead. Yet unlike academic tests with predetermined answers, Malaysia’s semiconductor future remains unwritten. Success isn’t guaranteed by ambition alone, but the country’s combination of existing infrastructure, regional positioning, and—if RMK-13 is executed effectively—growing design capabilities provides a foundation that many emerging economies would envy.
As global semiconductor demand continues accelerating, driven by AI, electric vehicles, and ubiquitous connectivity, the question for Malaysia isn’t whether opportunity exists—it’s whether the nation can seize it before the window closes. The next decade will provide the answer, making RMK-13 not merely another development plan but potentially the defining initiative of Malaysia’s economic generation.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025