
Asia
Inside Singapore’s AI Bootcamp to Retrain 35,000 Bankers: Reshaping Asia’s Financial Future

When Kelvin Chiang presented his team’s agentic AI models to Singapore’s Monetary Authority, he knew he was demonstrating something unprecedented. What used to consume an entire workday for a private banker—compiling wealth reports, validating sources of funds, drafting compliance documents—now takes just 10 minutes. But before Bank of Singapore could deploy these tools across its wealth management division, Chiang’s data scientists had to walk regulators through every safeguard, every failsafe, and every human oversight mechanism designed to prevent the system from “hallucinating” false information.
The regulators didn’t push back. They embraced it.
That collaborative spirit between government and industry defines Singapore’s radically different approach to the AI transformation sweeping global banking. While financial institutions in the United States and Europe announce mass layoffs—Goldman Sachs warning of more job cuts as AI takes hold—Singapore is executing the world’s most ambitious banking workforce retraining program. DBS Bank, OCBC, and United Overseas Bank are retraining all 35,000 of their domestic employees over the next two years, a government-backed initiative that represents not just a skills upgrade, but a fundamental reimagining of what it means to work in financial services.
The Revolutionary Scale of Singapore’s AI Training Initiative
The numbers tell only part of the story. Singapore’s three banking giants are investing hundreds of millions in a training infrastructure that reaches from entry-level tellers to senior executives. But unlike generic technology upskilling programs that plague many organizations, this bootcamp targets specific, measurable competencies needed to work alongside autonomous AI systems.
Violet Chung, a senior partner at McKinsey & Company, identifies what makes this initiative unique: “The government is doing something about it because they realize that this capability and this change is actually infusing potentially a lot of fear.” That acknowledgment of worker anxiety—combined with proactive solutions rather than platitudes—sets Singapore apart from Western approaches that often prioritize shareholder returns over workforce stability.
The Monetary Authority of Singapore (MAS) isn’t just cheerleading from the sidelines. Deputy Chairman Chee Hong Tat, who also serves as Minister for National Development, has made workforce resilience a regulatory expectation. The message to banks is clear: deploy AI aggressively, but ensure your people evolve with the technology. Singapore’s National Jobs Council, working through the Institute of Banking and Finance, offers banks up to 90% salary support for mid-career staff reskilling—an unprecedented level of public investment in private sector workforce development.
Understanding Agentic AI: The Technology Driving the Transformation
To grasp why 35,000 bankers need retraining, you must first understand what agentic AI does differently than the chatbots and recommendation engines that preceded it.

Traditional AI systems respond to prompts. Ask a question, get an answer. Agentic AI, by contrast, pursues goals autonomously. According to research from Deloitte, these systems can plan multi-step workflows, coordinate actions across platforms, and adapt their strategies in real-time based on changing circumstances—all without constant human intervention.
Consider OCBC’s implementation. Kenneth Zhu, the 36-year-old executive director of data science and AI, oversees a lab where 400 AI models make six million decisions every single day. These aren’t simple calculations. The models flag suspicious transactions, score credit risk, filter false positives in anti-money laundering systems, and even draft preliminary reports that once consumed hours of compliance officers’ time.
At DBS Bank, an internal AI assistant now handles more than one million prompts monthly. The bank has deployed role-specific tools that reduce call handling time by up to 20%—not by replacing customer service staff, but by handling the tedious documentation and data retrieval that used to interrupt human conversations. Customer service officers now spend their time actually serving customers, while AI manages the administrative burden.
The source of wealth verification process at Bank of Singapore exemplifies agentic AI’s potential. Relationship managers previously spent up to 10 days manually reviewing hundreds of pages of client documents—financial statements, tax notices, property valuations, corporate filings—to write compliance reports. The new SOWA (Source of Wealth Assistant) system completes this same analysis in one hour, cross-referencing Bank of Singapore’s extensive database and OCBC’s parent company records to validate information plausibility.
Bloomberg Intelligence forecasts that DBS will generate up to S$1.6 billion ($1.2 billion) in additional pretax profit through AI-derived cost savings—roughly a 17% boost. These aren’t theoretical projections. DBS CEO Tan Su Shan reports the bank already achieved S$750 million in AI-driven economic value in 2024, with expectations exceeding S$1 billion in 2026.
Inside the Bootcamp: How 35,000 Bankers Are Actually Learning AI
The phrase “AI bootcamp” might conjure images of programmers teaching SQL queries. Singapore’s program looks nothing like that.
The curriculum divides into three tiers, each calibrated to job function and AI exposure level:
Tier 1: AI Literacy for Everyone (All 35,000 employees)
- Understanding what AI can and cannot do
- Recognizing AI-generated content and potential hallucinations
- Data privacy and security in AI contexts
- Ethical considerations when deploying automated decision-making
- Prompt engineering basics for interacting with AI assistants
Tier 2: AI Collaboration Skills (Frontline and Middle Management)
- Working with AI co-pilots for customer service
- Interpreting AI-generated insights and recommendations
- Overriding AI decisions when human judgment is required
- Monitoring AI system performance and reporting anomalies
- Translating customer needs into AI-friendly inputs
Tier 3: AI Development and Governance (Technical Teams and Senior Leaders)
- Model risk management frameworks
- Building and validating AI use cases
- Implementing responsible AI principles (fairness, explainability, accountability)
- Regulatory compliance for AI systems
- Strategic AI investment and ROI measurement
The Institute of Banking and Finance Singapore doesn’t just offer online modules. Through its Technology in Finance Immersion Programme, the organization partners with banks to create hands-on learning experiences. Participants work on actual banking challenges, developing practical skills rather than theoretical knowledge.
Dr. Jochen Wirtz, vice-dean of MBA programs at National University of Singapore, emphasizes the urgency: “Banks would be completely stupid now to load up on employees who they will then have to let go again in three or four years. You’re much better off freezing now, trying to retrain whatever you can.”
That philosophy explains why DBS has frozen hiring for AI-vulnerable positions while simultaneously training 13,000 existing employees—more than 10,000 of whom have already completed initial certification. Rather than the classic “hire-and-fire” cycle that characterizes American banking, Singapore pursues “freeze-and-train.”
The Human Reality: Fear, Adaptation, and Unexpected Opportunities
Not everyone welcomes their AI co-worker with open arms.
Bank tellers watching their branch traffic decline, back-office analysts seeing AI handle tasks they spent years mastering, relationship managers uncertain how to add value when machines draft perfect emails—the anxiety is real and justified. Singapore’s approach acknowledges these concerns rather than dismissing them.
Walter Theseira, associate professor of economics at Singapore University of Social Sciences, notes that banks are managing workforce transitions through “natural attrition rather than forced redundancies.” When employees retire, change roles internally, or move to other companies, banks increasingly choose not to backfill those positions. This gradual adjustment—combined with the creation of new AI-adjacent roles—softens the disruption.
The emerging job categories reveal how AI transforms rather than eliminates work:
- AI Quality Assurance Specialists: Testing AI outputs for accuracy, bias, and regulatory compliance
- Digital Relationship Managers: Handling complex wealth management with AI-generated insights
- Automation Process Designers: Identifying workflows suitable for AI augmentation
- Model Risk Officers: Ensuring AI systems operate within approved parameters
- Customer Experience Strategists: Designing human-AI interaction patterns
UOB has given all employees access to Microsoft Copilot while deploying more than 300 AI-powered tools across operations. OCBC reports that AI-assisted processes have freed up capacity equivalent to hiring 1,000 additional staff—capacity redirected toward higher-value customer interactions and strategic initiatives rather than eliminated.
One success story circulating in Singapore’s banking community involves a former transaction processor who completed the AI training program and now leads a team designing automated fraud detection workflows. Her deep understanding of payment patterns—knowledge that seemed obsolete when AI took over transaction processing—became invaluable when combined with technical AI literacy. She didn’t lose her job to automation; she gained leverage over it.
Singapore’s Regulatory Philosophy: Partnership Over Policing
What separates Singapore’s approach from virtually every other financial center is how its regulator, the Monetary Authority of Singapore, engages with AI deployment.
In November 2025, MAS released its consultation paper on Guidelines for AI Risk Management—a document that reflects months of collaboration with banks rather than top-down dictates imposed on them. The guidelines focus on proportionate, risk-based oversight rather than prescriptive rules that could stifle innovation.
MAS Deputy Managing Director Ho Hern Shin explained the philosophy: “The proposed Guidelines on AI Risk Management provide financial institutions with clear supervisory expectations to support them in leveraging AI in their operations. These proportionate, risk-based guidelines enable responsible innovation.”
The guidelines address five critical areas:
- Governance and Oversight: Board and senior management responsibilities for AI risk culture
- AI Risk Management Systems: Clear identification processes and accurate AI inventories
- Risk Materiality Assessments: Evaluating AI impact based on complexity and reliance
- Life Cycle Controls: Managing AI from development through deployment and monitoring
- Capabilities and Capacity: Building organizational competency to work with AI safely
Rather than banning certain AI applications, MAS encourages banks to experiment while maintaining rigorous documentation of safeguards. When Kelvin Chiang presented his agentic AI tools, regulators wanted to understand the thinking process, the oversight mechanisms, and the escalation protocols—not to obstruct deployment, but to ensure responsible implementation.
This collaborative regulatory stance extends to funding. Through the IBF’s programs, Singapore effectively subsidizes workforce transformation, recognizing that individual banks cannot bear the full cost of societal-scale reskilling. PwC research shows organizations offering AI training report 42% higher employee engagement and 38% lower attrition in technical roles—benefits that justify public investment.
MAS Chairman Gan Kim Yong, who also serves as Deputy Prime Minister, framed the imperative at Singapore FinTech Festival: “It is important for us to understand that the job will change and it’s very hard to keep the same job relevant for a long period of time. As jobs evolve, we have to keep the people relevant.”
The ROI Case: Why Massive AI Investment Makes Business Sense
Singapore’s banks aren’t retraining 35,000 workers out of altruism. The business case for AI transformation is overwhelming—provided the workforce can leverage it.
DBS CEO Tan Su Shan described AI adoption as generating a “snowballing effect” of benefits. The bank’s 370 AI use cases, powered by more than 1,500 models, contributed S$750 million in economic value in 2024. She projects this will exceed S$1 billion in 2026, representing a measurable return on years of investment in both technology and people.
The efficiency gains manifest across every banking function:
Customer Service: AI handles routine inquiries, reducing average response time while allowing human agents to focus on complex problems requiring empathy and judgment. DBS’s upgraded Joy chatbot managed 120,000 unique conversations, cutting wait times and boosting satisfaction scores by 23%.
Risk Management: OCBC’s 400 AI models process six million daily decisions related to fraud detection, credit scoring, and compliance monitoring—work that would require thousands of additional staff and still produce inferior results due to human attention limitations.
Wealth Management: AI-powered portfolio analysis and market insights allow relationship managers at private banks to serve more clients at higher quality. What once required a team of analysts now happens in real-time, personalized to each client’s specific situation.
Operations: Back-office processing that once consumed entire departments now runs largely automated, with humans focused on exception handling and quality assurance rather than manual data entry.
According to KPMG research, organizations achieve an average 2.3x return on agentic AI investments within 13 months. Frontier firms leading AI adoption report returns of 2.84x, while laggards struggle at 0.84x—a performance gap that could determine competitive survival.
The transformation isn’t limited to cost savings. DBS now delivers 30 million hyper-personalized insights monthly to 3.5 million customers in Singapore alone, using AI to analyze transaction patterns, life events, and financial behaviors. These “nudges”—reminding customers of favorable exchange rates, suggesting timely financial products, flagging unusual spending—drive engagement and revenue while genuinely helping customers make better decisions.
Global Context: How Singapore’s Model Differs from Western Approaches
The contrast with American and European banking couldn’t be starker.
JPMorgan Chase CEO Jamie Dimon speaks enthusiastically about AI’s opportunities while the bank deploys hundreds of use cases. Yet JPMorgan analysts project global banks could eliminate up to 200,000 jobs within three to five years as AI scales. Goldman Sachs continues warning employees to expect cuts. The narrative centers on efficiency gains and shareholder value, with workforce impact treated as an unfortunate but necessary consequence.
European banks face different pressures. Strict labor protections make large-scale layoffs difficult, but they also complicate rapid workforce transformation. Banks attempt gradual transitions through attrition, but without Singapore’s comprehensive retraining infrastructure, displaced workers often struggle to find equivalent roles.
Singapore’s model succeeds through three unique factors:
1. Government-Industry Alignment The close relationship between MAS, the National Jobs Council, and major banks enables coordinated action impossible in more fragmented markets. When Singapore decides workforce resilience matters, resources flow accordingly.
2. Social Contract Expectations Singapore’s three major banks operate with implicit understanding that their banking licenses come with social responsibilities. Massive layoffs would trigger regulatory and reputational consequences, creating strong incentives for workforce investment.
3. Manageable Scale With 35,000 domestic banking employees across three major institutions, Singapore can execute comprehensive training that would be logistically impossible for American banks with hundreds of thousands of global staff.
Harvard Business Review analysis suggests Singapore’s approach, while difficult to replicate exactly, offers lessons for other nations: establish clear regulatory expectations around workforce transition, provide financial support for retraining, create industry-specific training partnerships, and measure success not just by AI deployment speed but by workforce adaptation rates.
The 2026-2028 Horizon: What Comes Next
As Singapore approaches the halfway point of its two-year retraining initiative, early results suggest the model works—but also highlight emerging challenges.
DBS has already reduced approximately 4,000 temporary and contract positions over three years, while UOB and OCBC report no AI-related layoffs of permanent staff. The banking sector is discovering that AI changes job composition more than job quantity, at least in the medium term.
The next wave of transformation will test whether current training adequately prepares employees. Gartner forecasts that by 2028, agentic AI will enable 15% of daily work decisions to be made autonomously—up from essentially zero in 2024. As AI agents gain more autonomy, the human role shifts from executor to orchestrator, requiring even higher-order skills.
MAS is already considering how to hold senior executives personally accountable for AI risk management, recognizing that autonomous systems create novel governance challenges. The proposed framework would mirror the Monetary Authority’s approach to conduct risk, where individuals bear clear responsibility for failures.
Singapore is also grappling with an unexpected challenge: Singlish, the local English creole, creates complications for AI natural language processing. Models trained on standard English struggle with Singapore’s unique linguistic patterns, requiring localized AI development—which in turn demands more sophisticated training for local AI specialists.
The broader implications extend beyond banking. If Singapore succeeds in demonstrating that massive AI deployment can coexist with workforce stability through strategic retraining, it provides a template for other industries and nations facing similar disruptions.
McKinsey estimates that AI could put $170 billion in global banking profits at risk for institutions that fail to adapt, while pioneers could gain a 4% advantage in return on tangible equity—a massive performance gap. Singapore’s banks, with their AI-literate workforce, position themselves firmly in the pioneer category.
Lessons for the Global Banking Industry
Singapore’s AI bootcamp experiment offers actionable insights for financial institutions worldwide:
Start with Culture, Not Technology: The most sophisticated AI fails if employees resist or misuse it. Comprehensive training that addresses fears and demonstrates value creates buy-in impossible to achieve through top-down mandates.
Partner with Government: Workforce transformation at this scale exceeds individual firms’ capacity. Public-private partnerships can distribute costs while ensuring industry-wide capability building.
Measure What Matters: Singapore tracks not just AI deployment metrics but workforce adaptation rates, employee satisfaction with AI tools, and the emergence of new hybrid roles. These human-centric measures predict long-term success better than pure technology KPIs.
Reimagine Rather Than Replace: The most successful AI implementations augment human capabilities rather than substituting for them. Relationship managers with AI insights outperform both pure humans and pure machines.
Invest in Adjacent Capabilities: AI literacy alone isn’t enough. Workers need complementary skills—critical thinking, emotional intelligence, creative problem-solving—that AI cannot replicate but can amplify.
Create New Career Paths: As traditional roles evolve, new opportunities in AI quality assurance, model risk management, and human-AI experience design create advancement paths for ambitious employees.
Accept Gradual Transition: Singapore’s two-year timeline, with flexibility for individual banks to move faster or slower based on their readiness, acknowledges that workforce transformation cannot be rushed without creating unnecessary disruption.
The Verdict: A Model Worth Watching
As the financial world watches Singapore’s unprecedented experiment, the stakes extend far beyond one nation’s banking sector. The question isn’t whether AI will transform banking—that transformation is already underway. The question is whether that transformation must inevitably create massive worker displacement, or whether strategic intervention can enable human adaptation at the pace of technological change.
Singapore bets on the latter possibility. By retraining all 35,000 domestic banking employees, by creating robust public-private partnerships, by developing comprehensive curricula that address both technical skills and existential anxieties, the city-state attempts to prove that the future of work doesn’t have to be a zero-sum battle between humans and machines.
Early returns suggest the model works. Banks report measurable productivity gains without mass layoffs. Employees initially resistant to AI training increasingly embrace it as they discover enhanced rather than diminished job prospects. Regulators fine-tune an approach that enables innovation while maintaining safety.
Yet challenges remain. Can retraining keep pace with accelerating AI capabilities? Will the job categories being created prove as numerous and lucrative as those being transformed? What happens to workers who cannot or will not adapt, despite comprehensive support?
These questions lack definitive answers. What Singapore demonstrates beyond doubt is that workforce transformation of this magnitude is possible—that major financial institutions can deploy cutting-edge AI aggressively while simultaneously investing in their people’s futures.
When historians eventually assess the AI revolution’s impact on work, Singapore’s banking sector bootcamp may be remembered as either a successful proof of concept that other nations and industries replicated, or as an admirable but ultimately isolated experiment that proved impossible to scale beyond a small, tightly integrated economy.
The next two years will tell us which.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Asian equity markets have delivered a reminder that the AI investment boom is not simply an American technology story. South Korean memory producers, Taiwanese chip manufacturers, Japanese equipment suppliers and regional exporters are connected to global capital spending on computing. That creates an opportunity when orders surge and a vulnerability when assumptions change.
A Reuters market report on October 13 described a sharp risk-off episode in technology-linked Asian shares. Subsequent Wall Street Journal coverage described a partial rebound. Those moves are best understood as a test of expectations, not as proof that regional growth has reversed.
The first link: US AI spending and Asian earnings
The global chip supply chain has multiple layers. Advanced logic semiconductors, high-bandwidth memory, equipment, materials and packaging each respond differently to investment cycles. An AI server ordered in the United States can create revenue for numerous Asian firms, while supplier earnings remain vulnerable to delays or changes in product mix.
This concentration means broad stock indices may react strongly to a relatively narrow group of companies. The movement of an index is not necessarily a reliable representation of household consumption or the local services economy. Readers should check the contribution of leading constituents before interpreting a headline percentage drop.
Korea, Taiwan and Japan have different exposures
Korea’s market has significant memory-chip exposure. Taiwan has a major role in contract semiconductor manufacturing and its suppliers. Japan combines technology-related manufacturers with banks, exporters and domestic sectors. Exchange rates can amplify or offset changes in export competitiveness and returns for foreign investors.
Currency matters especially when an investor buys shares denominated in won, Taiwan dollars or yen. Even if a local index is unchanged, the return measured in dollars can change because of foreign-exchange movements. A regional market roundup should therefore include both equity and currency context.
Interest rates and oil can overwhelm the chip narrative
The AI industry competes for capital with governments, housing and ordinary businesses. When bond yields climb, distant profits are discounted more heavily; heavily indebted firms face rising refinancing expenses. Meanwhile high energy prices can pressure importers and manufacturers even when some technology exporters remain strong.
The IMF’s October outlook highlights both AI-related opportunities and inflation, conflict and fiscal vulnerabilities. That mixed picture argues against a single “Asia is booming” or “Asia is crashing” explanation.
The danger of extrapolating one trading session
A large daily decline can reflect positioning, forced selling or an abrupt change in sentiment. A rebound can reflect bargain hunting or short covering without resolving the original valuation issue. Neither movement establishes a sustainable trend. Investors should connect price action to revisions in earnings guidance, orders and financing conditions.
Useful evidence includes export orders, manufacturing surveys, semiconductor inventories, central-bank signals and capital flows. Compare the same measures over several months and distinguish expectations from realized data.
How to follow Asian markets responsibly
Build a dashboard with major indices, local-currency performance, exchange rates, benchmark bond yields and relevant oil prices. Record dates and market closing times; an Asian close may precede major US news that influences futures later. Avoid combining prices from different sessions as though they represent the same moment.
For a long-term investor, diversification across sectors and countries matters more than guessing the next technology stock to rebound. For a news reader, the essential question is whether a market move reflects an earnings change, financing risk or only a revision to how much investors are willing to pay.
Market structure can magnify headline moves
Market-capitalization-weighted benchmarks allocate more influence to companies with high market value. As chip and platform businesses grow, their success can make an index more concentrated. During a drawdown, selling pressure in those same names may dominate the index even if the median constituent is relatively stable. Equal-weighted sector comparisons and the share of stocks advancing can help distinguish broad weakness from concentration effects. Investors should also review whether an exchange was closed for a holiday and whether a quoted movement refers to a futures contract or the cash session. Time alignment is essential when comparing Asian and US markets.
Frequently asked questions
Why do Asian markets fall when US AI stocks sell off?
Regional firms supply chips, memory and equipment to the same global investment cycle, and investors frequently adjust exposure across markets at once.
Is a rebound proof the AI bubble is over?
No. Price recoveries do not necessarily resolve doubts about future returns and financing.
Which numbers are worth monitoring?
Earnings expectations, memory prices, exports, bond yields, currencies and oil prices give a more balanced picture than an index close alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Are Asian stock markets rising in 2026?
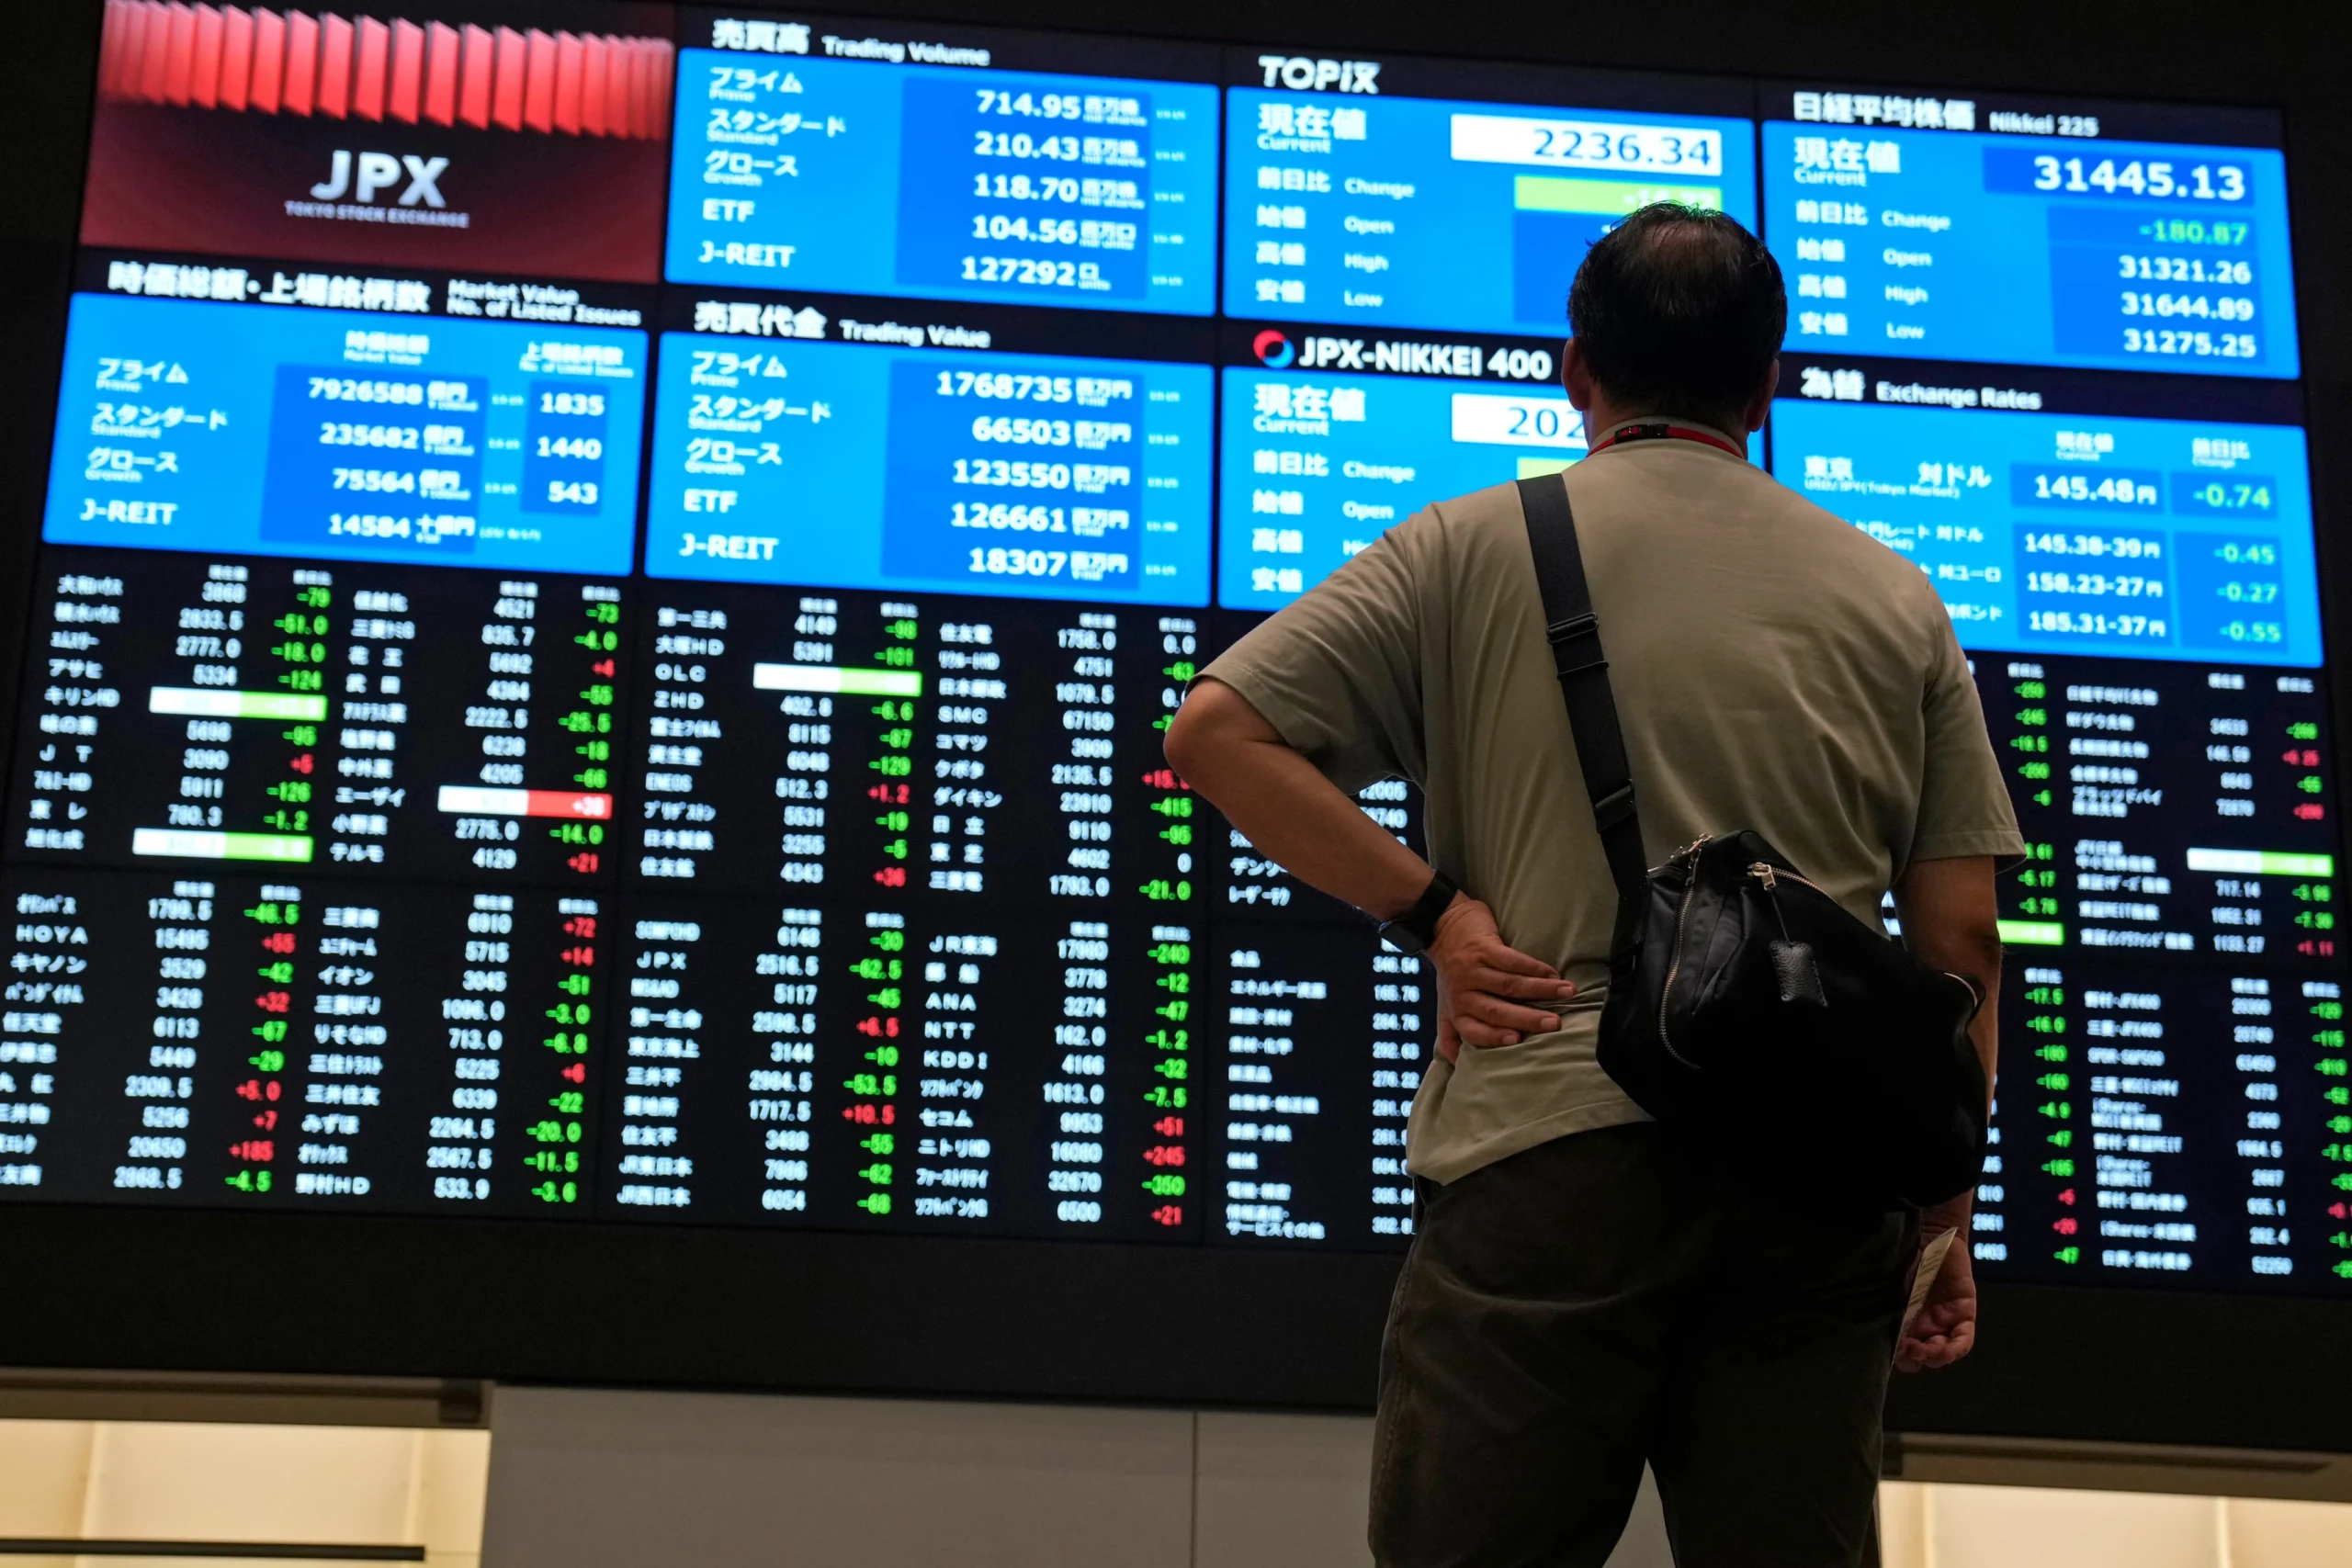
Most of them are, but for very different reasons. Japan’s Nikkei 225 is trading at levels roughly 44% higher than a year ago on continued AI-linked technology strength; China’s benchmark indices climbed to multi-year highs at the start of the year on AI optimism and signs of economic recovery; and Pakistan’s KSE-100 has been one of the most volatile large gainers globally, crossing record highs early in the year before enduring sharp single-session pullbacks in September. Understanding each market separately matters more than treating “Asia” as one trade.
Japan: A 15-Year-Plus Bull Run Meets a Hawkish Central Bank
The Nikkei 225 closed at 65,018.95 on September 18, 2026, gaining 1.38% on the session and sitting 44.34% above where it stood a year earlier, according to data compiled by Trading Economics. That move came even as the Bank of Japan raised its policy rate by 25 basis points to 1.25% — a widely expected but still consequential tightening step, as policymakers balance elevated inflation and wage growth against pressure from U.S. Treasury Secretary Scott Bessent for currency and trade cooperation. Japan’s annual inflation rate held at 1.9% in August, with core inflation at 1.7% — below the Bank of Japan’s 2% target for a seventh straight month, suggesting the central bank still has room to normalize policy gradually rather than aggressively.
Technology and AI-related names have led Japan’s rally, with chip-equipment and materials names such as Advantest and Lasertec posting some of the sharpest single-day gains, echoing similar advances on Wall Street. That correlation is a theme across the region: Asian equity performance in 2026 has tracked the U.S. AI-capex story almost as closely as it has tracked domestic fundamentals.
China: AI Optimism Meets an Overheating Warning
China’s equity markets opened 2026 on a tear. The benchmark CSI 300 Index advanced 1.6% to close at its highest level in four years on January 6, while the Shanghai Composite rose 1.5% to its strongest level since July 2015, fueled by sustained optimism over the country’s AI advances and early signs of broader economic recovery, according to Bloomberg. Materials and technology shares led the advance, and the rally coincided with a robust pipeline of onshore AI-related IPOs.
That said, the rally showed early signs of overheating even in January: the 14-day relative strength index on the Shanghai Composite climbed above 75 — firmly into technical overbought territory — a level it had not touched since the previous September. Momentum has been uneven since; by late July, the Shanghai Composite had pulled back to a 16-week low on the CSI 300 gauge even as the broader index posted modest daily gains, reflecting a market still working through the tension between AI-driven optimism and valuation discipline. On the macro side, the IMF’s own China growth revisions this year have tracked a similar push-pull, with earlier 2025 forecasts putting Chinese growth near 4.8% before moderating toward roughly 4.2% as trade and property-sector headwinds persist.
Malaysia and Singapore: Steady Gains, Regional Correlation
Malaysia’s FTSE Bursa Malaysia KLCI has spent much of 2026 grinding toward multi-year highs rather than posting dramatic single-day swings. The index touched a more-than-six-year high near 1,686 points in early January, according to New Straits Times, and by early September had climbed further to around 1,714–1,715 points, per Bursa Malaysia futures data reported by Bernama, Malaysia’s state news agency. Analysts at Rakuten Trade have described the index as being in a healthy uptrend across both short- and long-term timeframes, with pullbacks read as consolidation rather than a change in trend.
Singapore’s Straits Times Index has moved in tandem with regional sentiment through the year, trading in the high-3,900-point range during mid-2026 sessions alongside comparable moves in Hong Kong’s Hang Seng and South Korea’s Kospi — a reminder that Southeast Asian and Northeast Asian benchmarks remain tightly correlated on any given trading day, even when their underlying economic drivers differ.
Pakistan: The Region’s Most Volatile Outperformer
Featured Snippet Target: Pakistan’s KSE-100 Index began 2026 at a record high above 176,000 points, climbed further past 186,000 and 188,000 in the following days on institutional buying and expectations of a policy rate cut, but has since seen sharp single-session pullbacks — including a 3,078-point, 1.79% drop on September 10 — underscoring how the world’s best-performing frontier market in early 2026 has also been among its most volatile.
The Pakistan Stock Exchange’s rally traces back to a shift in domestic asset allocation: brokerage house Topline Securities described the move from fixed-income instruments into equities — driven by falling returns on traditional savings vehicles — as the primary fuel behind sustained liquidity and elevated valuations, according to coverage from Aaj News. Banking names including United Bank Limited, Habib Bank, and MCB, alongside energy majors like Oil and Gas Development Company, have repeatedly featured among the index’s top contributors on both up and down days.
By early September, the picture had turned choppier. The KSE-100 gained 399 points on September 4 to close at 175,328, per ARY News, before dropping over 3,000 points just days later on September 10 — a reminder that Pakistan’s rally, while historic in percentage terms, remains far more sensitive to single-session sentiment shifts than its larger regional peers.
The Cross-Market Pattern
Three threads tie these otherwise disconnected markets together in 2026. First, AI-linked capital spending is now a genuine cross-border driver — Japanese and Chinese tech names have both rallied on echoes of the same U.S. hyperscaler capex story. Second, central bank policy divergence is widening: Japan is tightening from historically ultra-loose settings, while Pakistan has been cutting rates to support a still-fragile broader economy. Third, frontier and emerging markets — Pakistan chief among them — are delivering far larger percentage swings, in both directions, than developed Asian benchmarks, rewarding investors who can tolerate volatility but punishing those who chase momentum without hedging for pullbacks.
The Bottom Line
Asia’s 2026 story is not one market but five distinct ones moving on different clocks — Japan’s AI-and-rate-hike rally, China’s optimism-versus-overheating tension, Malaysia and Singapore’s steadier regional drift, and Pakistan’s high-beta swings around a genuine structural re-rating. Anyone allocating across the region needs a market-by-market view rather than a single “Asia” thesis.
Next step: Track Bank of Japan policy meetings, China’s Politburo economic guidance sessions, and Pakistan’s State Bank Monetary Policy Committee decisions together — the three events, spaced through the remainder of 2026, are the clearest near-term catalysts for each market’s next move.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Geopolitics and Your Portfolio: How International Affairs Move Global Markets
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pingback: DBS Hits S$1 Billion AI Value Milestone — But Agentic AI Poses Talent Challenges for Singapore Banks - The Economy