
AI
How AI, Delivery Drones Helped China Cut Logistics Costs to a New Low

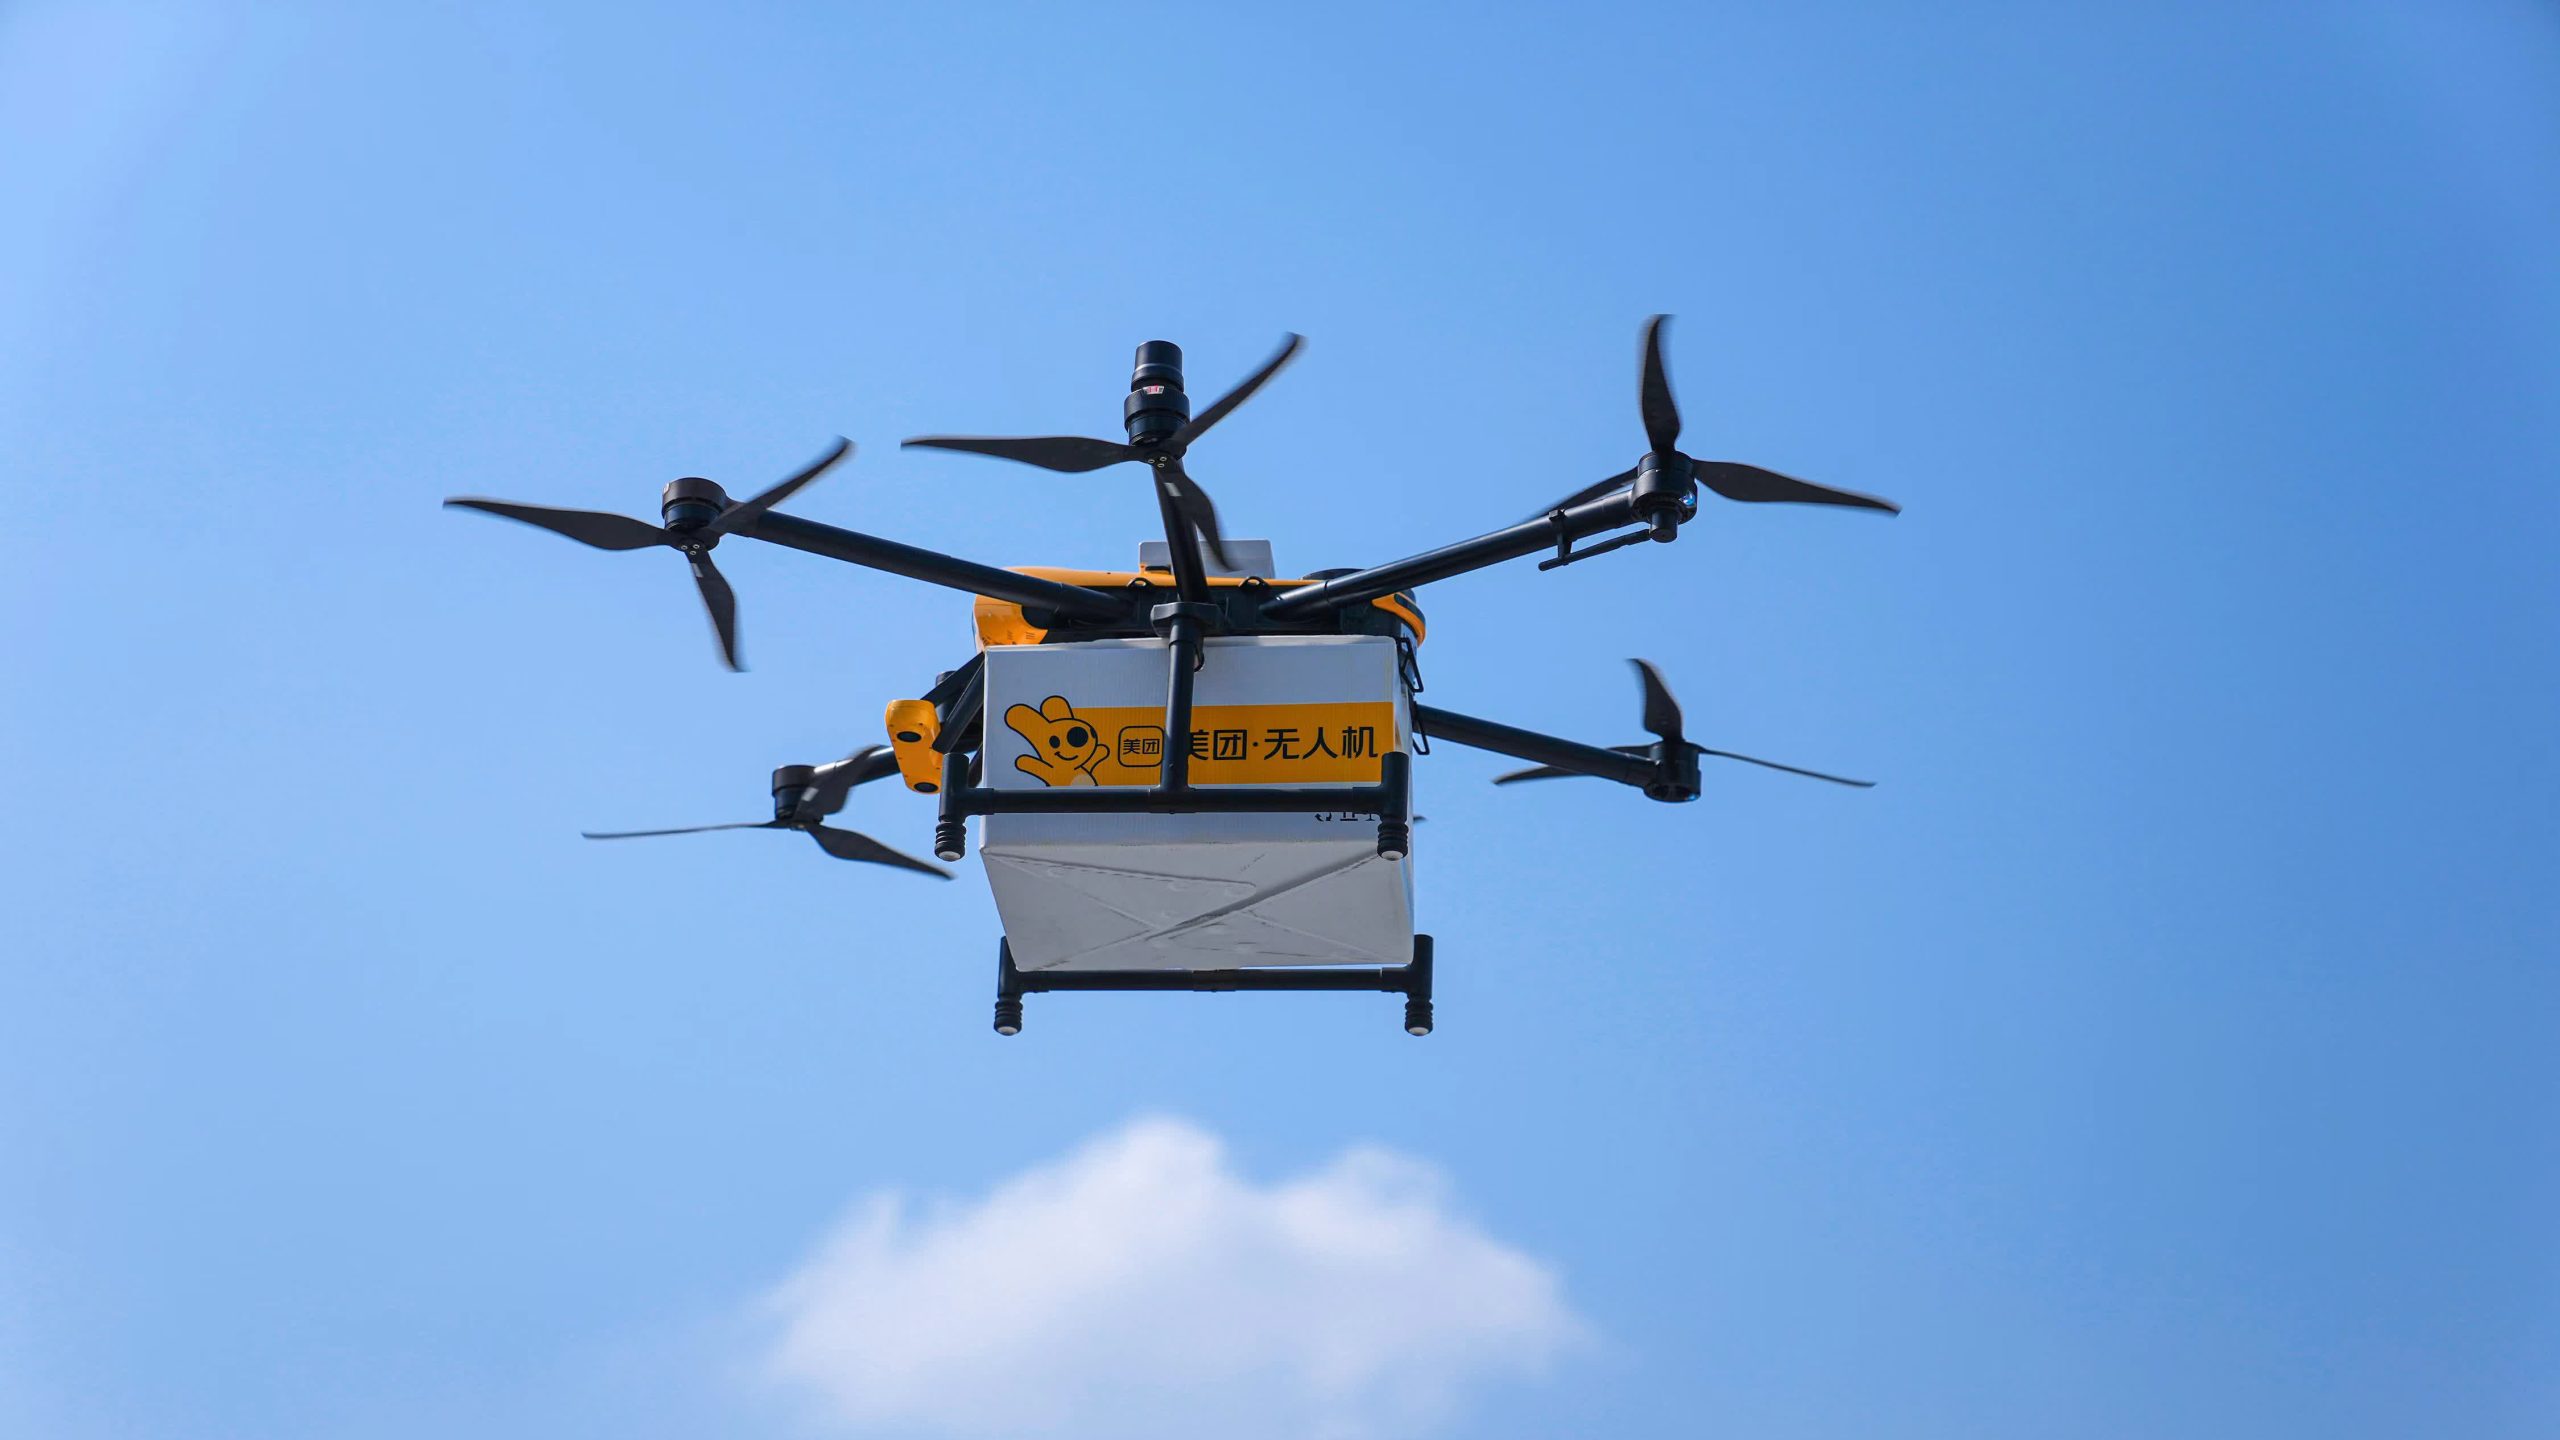
China’s logistics costs fell to 13.9% of GDP in 2025, a record low driven by AI route optimization and delivery drones reducing expenses by 30-50% in key sectors.
Imagine in rural Jiangsu Province, a package containing life-saving medication lands precisely at a remote village health clinic—delivered not by a courier navigating treacherous mountain roads, but by an autonomous drone that completed the 40-kilometer journey in just 18 minutes. What once took four hours now happens before breakfast, at a fraction of the cost. This isn’t science fiction. It’s the new reality of China’s logistics revolution, and it’s reshaping the world’s largest supply chain into one of its most efficient.
A Historic Milestone in Supply Chain Efficiency
China’s logistics costs-to-GDP ratio fell to 13.9% in 2025, dropping below the 14% threshold for the first time, according to the National Development and Reform Commission (NDRC). This translates to 13.9 yuan (US$2.01) spent on logistics for every 100 yuan of economic output—a crucial benchmark of supply chain efficiency that signals Beijing’s transformation of the world’s largest logistics market from a volume-driven behemoth into a precision-tuned ecosystem.
The achievement marks a 0.8 percentage point improvement since the end of the 13th Five-Year Plan period (2016-2020) and reflects steady improvements in logistics infrastructure, coordination and cost control. Yet context matters: while the United States maintains logistics costs at approximately 8.7-8.8% of GDP, China’s ratio remains elevated by comparison, suggesting significant headroom for further optimization.
Beijing isn’t resting on its laurels. The government is targeting a further reduction to around 13.5% by 2027, part of a broader push to boost overall economic efficiency as the nation confronts slowing growth and mounting global economic pressures.
The AI Advantage: Intelligence Meets Infrastructure
The path to this record low wasn’t paved with traditional infrastructure alone—it was coded into algorithms and trained into neural networks. Artificial intelligence has emerged as the invisible hand guiding China’s logistics transformation, touching everything from warehouse automation to real-time route optimization.
Consider the textile manufacturer Fu Yefei in Shaoxing, Zhejiang Province. His company previously hemorrhaged 30,000 yuan monthly on in-house drivers plagued by empty return trips and inefficient routing. After adopting intelligent logistics platforms, AI-powered matching systems reduced transportation costs by nearly 70% while boosting delivery efficiency by over 50%. The platform’s AI bridges information gaps between shippers and carriers, optimizing load matching with a 92% success rate across 1.86 million daily orders.
This isn’t an isolated case. Across China’s logistics landscape, AI is delivering measurable impact:
Route Optimization at Scale: Machine learning algorithms process real-time traffic data, weather patterns, and historical delivery information to dynamically adjust routes. A 2025 DHL report found that AI-driven route optimization can cut fuel use by up to 15%, translating to major cost savings and reduced environmental impact. In China’s context, where JD Logistics operates across thousands of routes daily, these efficiency gains compound into hundreds of millions in annual savings.
Predictive Analytics: AI systems forecast demand patterns, enabling logistics companies to position inventory strategically and avoid costly last-minute shipments. JD Logistics’ regional distribution hubs have cut delivery times by eight hours on average across platforms, reducing warehouse space requirements and associated costs.
Warehouse Automation: Unstaffed warehouses powered by AI-controlled robotics have become increasingly common. JD.com founder Liu Qiangdong projects that with AI and robotics integration, China’s social logistics costs could drop from over 14% to less than 10% of GDP within five years—a transformation that would save the economy hundreds of billions of yuan annually.
Industry analyses suggest AI implementation in logistics enables cost reductions between 10% and 25% across operational pools such as last-mile delivery, sorting, and warehouse management, with aggregate improvements in earnings before income and taxes of 1% to 2%—significant uplifts for an industry operating on razor-thin margins.
The Drone Economy: China’s Low-Altitude Revolution
While AI optimizes existing infrastructure, delivery drones are creating entirely new logistics corridors—quite literally above the gridlocked streets below. China’s “low-altitude economy,” encompassing drones and electric vertical take-off and landing (eVTOL) aircraft flying below 1,000 meters, has evolved from experimental trials to commercial reality with remarkable speed.
The numbers tell a compelling story. Meituan’s drone delivery services had opened 53 delivery routes in major cities including Shenzhen, Beijing, Shanghai, Guangzhou, and Nanjing by the end of 2024, completing over 450,000 orders. The food delivery giant secured China’s first nationwide low-altitude logistics operating certificate in April 2025, positioning it to scale drone deliveries across the country.
JD.com has been equally aggressive. The e-commerce giant tested drone delivery networks in Jiangsu, Shaanxi, and Sichuan, reducing shipping times by up to 70% for rural customers. In January 2025, JD unveiled its lightweight urban model JDX20 drone and has been testing deliveries in cities such as Nanjing, Shanghai, Xi’an and Guangzhou.
SF Express, China’s leading logistics provider, demonstrates the technology’s maturity. In the Guangdong-Hong Kong-Macau Greater Bay Area, SF’s drone operations range between 800 and 2,000 daily take-offs, with daily deliveries exceeding 12,000 times—a scale that transitions drones from novelty to necessity.
The economic impact extends beyond speed. Drones eliminate the need for costly last-mile vehicle fleets, reduce labor requirements, and bypass traffic congestion that plagues traditional delivery. For rural and remote areas where infrastructure remains limited, drones provide access that simply wasn’t economically viable before. Beijing’s drone delivery service at the Badaling section of the Great Wall reduces human labor costs while enhancing visitor experience by delivering refreshments and emergency supplies in minutes.
Healthcare logistics has emerged as a particularly impactful application. In October 2024, Hefei launched a drone-based blood delivery route connecting Luyang Blood Donation Center to the Anhui Provincial Blood Center, helping reduce critical delivery times that can mean the difference between life and death.
The Broader Technology Stack
AI and drones don’t operate in isolation—they’re part of a comprehensive digital transformation reshaping China’s logistics infrastructure:
Multimodal Transport Optimization: Strategic integration of sea-rail intermodal transport has slashed transit times. The “China-Europe Express” shipping route has cut transit time from 38 to 26 days through coordinated rail-sea operations, with containers transferring from trains to ships without reloading—significantly reducing logistics costs.
IoT and Real-Time Visibility: Internet of Things sensors throughout the supply chain provide unprecedented transparency, enabling dynamic adjustments and reducing exceptions. Companies report improvements in on-time delivery rates exceeding 20% through enhanced visibility alone.
Autonomous Vehicles: Beyond drones, ground-based autonomous delivery vehicles are proliferating. By the end of 2024, Meituan’s street-legal autonomous delivery vehicles had completed nearly 5 million orders, primarily in dense urban pilot zones, making it one of the world’s largest real-world autonomous delivery operations.
The Global Context: Efficiency Gaps and Opportunities
China’s 13.9% logistics costs-to-GDP ratio represents significant progress, but global comparisons reveal both the achievement and the challenge ahead. The United States maintains logistics costs at 8.7-8.8% of GDP, while Japan operates at just 3.8% of GDP—one of the world’s most efficient logistics systems.
The gap isn’t merely academic—it represents hundreds of billions in potential economic value. Every percentage point reduction in China’s logistics costs frees capital for productive investment elsewhere in the economy. China’s logistics sector anticipates reducing national logistics costs by 300 billion yuan in 2025, providing substantial support for manufacturing sector growth.
Several structural factors explain China’s higher ratio. The nation’s vast geography—with production often concentrated in coastal regions while consumption spreads across diverse interior markets—inherently increases logistics complexity. Infrastructure quality, while improving rapidly, still lags developed economies in some regions. Labor costs, though rising, remain relatively low compared to advanced automation benefits, sometimes reducing incentives for rapid technology adoption.
Yet these same factors make China’s achievement more remarkable. The country has managed to drive down costs while handling unprecedented volume—China handled 132 billion express delivery parcels in 2023, more than the rest of the world combined.
Challenges on the Horizon
Despite impressive progress, significant obstacles remain. Industry-wide penetration and depth of intelligent operations lag behind those of leading global logistics companies, while some high-end technologies continue to depend on imported components—creating potential vulnerabilities in supply chains and limiting China’s technological sovereignty.
Regulatory Hurdles: Low-altitude airspace management remains complex, with safety protocols and flight path approvals creating bottlenecks for drone expansion. Each new route requires extensive regulatory review, slowing scalability.
Payload Limitations: Current drone models typically carry 5-10 kg, restricting their use to lightweight goods. This limits applications to specific use cases and prevents drones from displacing traditional delivery for bulk shipments.
Weather Dependence: Adverse conditions—heavy rain, strong winds, fog—can ground drone fleets, creating service reliability concerns that undermine customer confidence.
Urban Congestion: While drones bypass ground traffic, urban environments present their own challenges. Tall buildings, electromagnetic interference, and crowded airspace complicate navigation and raise safety concerns.
Infrastructure Investment: Scaling AI and drone systems requires substantial capital outlays at a time when China’s economic growth is moderating. Most AI use cases reach deployment within 6 to 12 months, with initial investments generally around €0.5 million to €1 million per application.
Data Privacy and Security: AI-driven logistics systems collect vast amounts of data on movement patterns, consumption behaviors, and supply chain operations—raising important questions about privacy protection and cybersecurity that regulators are still addressing.
The Road to 13.5%: What Comes Next
Beijing’s target of 13.5% by 2027 appears achievable based on current trajectories, but reaching developed-economy efficiency levels will require sustained innovation and investment. The blueprint is taking shape:
Expanded Drone Corridors: Shenzhen launched 94 new drone logistics routes in 2024, bringing the total to over 200 operational corridors and completing 600,000 flights. Guangzhou aims to develop a 150 billion RMB low-altitude economy by 2027. Expect this model to replicate across other major metropolitan areas.
Next-Generation AI: Current systems optimize existing operations, but emerging technologies promise transformation. Generative AI could revolutionize demand forecasting, while quantum computing might solve complex routing problems that remain computationally intensive today.
5G and Beyond: Enhanced connectivity enables real-time coordination of drone swarms, autonomous vehicle fleets, and warehouse robots—creating truly integrated logistics networks that operate with minimal human intervention.
Green Logistics: Environmental pressure is mounting. Electric drones and vehicles, optimized routes that minimize fuel consumption, and AI systems that reduce waste all align with China’s carbon neutrality goals while cutting costs—a rare convergence of environmental and economic incentives.
Cross-Border Expansion: Meituan plans to establish four to five new drone delivery routes in Shanghai before the end of 2025, including routes that cross the Huangpu River, while expanding internationally with multiple routes planned for Dubai Marina. Chinese logistics innovations are going global, potentially reshaping international supply chains.
Conclusion: The Logistics Advantage in a Multipolar World
China’s logistics efficiency gains matter far beyond domestic markets. In an era of geopolitical fragmentation and supply chain resilience concerns, the ability to move goods faster and cheaper translates directly into economic competitiveness. As the United States grapples with logistics costs that have stabilized at a new baseline 1-2 percentage points above pre-COVID levels and faces structural pressures from nearshoring and tariff uncertainties, China’s continued progress in logistics optimization provides a strategic advantage.
The convergence of AI and drones represents more than incremental improvement—it’s the foundation of a fundamentally different logistics paradigm. Where once efficiency meant optimizing truck routes and warehouse layouts, tomorrow’s gains will come from algorithms that predict demand before orders are placed, drones that deliver before customers know they need something, and autonomous systems that coordinate across modalities with superhuman precision.
China’s journey from 14.1% to 13.9% may seem modest—just 0.2 percentage points. But in an economy approaching $19 trillion, that represents tens of billions in freed capital, millions of hours saved, and a blueprint for how technology can reimagine one of humanity’s oldest challenges: getting things from here to there.
The race to 13.5% is underway. The rest of the world would be wise to watch closely.
Sources:
- China Daily: China’s logistics costs-to-GDP ratio hits record low in 2025
- South China Morning Post: How AI, delivery drones helped China cut logistics costs to a new low
- Ningbo Daily: Reduced logistics costs help release China’s economic vitality
- Chinadaily: Tech giants target unmanned logistics
- MN Shipping: China’s Drone Logistics Revolution in 2025
- DHL/McKinsey: AI-driven route optimization reports
- TRADLINX: $2.6 Trillion and Rising: What U.S. Logistics Costs Reveal
- FreightWaves: Logistics GDP share rose in ’24
- Cargoson: How Big is the Logistics Market?
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The crucial economic question about artificial intelligence is no longer whether it can perform useful tasks. It is who captures the savings, who bears the transition costs and whether productivity gains become better wages or merely lower labour demand. In 2026, the evidence points to meaningful changes in tasks and workplace organization, but not to a uniform wave of whole-job replacement.
The International Labour Organization’s 2025 occupational exposure index found that one in four workers globally are in an occupation with some exposure to generative AI; 3.3% of employment was in the highest exposure category. Exposure measures what the technology could affect, not how many workers have lost their jobs. The ILO’s June 2026 review says measured gains are uneven, and reported time savings have not yet consistently appeared as higher aggregate output or earnings.
Key takeaways
- Exposure to AI is not the same as job destruction; many occupations contain tasks that still need human judgment.
- Productivity gains may flow to consumers, owners, skilled workers or employers, depending on competition and bargaining power.
- Entry-level career pathways may be particularly vulnerable if firms automate routine tasks used for training juniors.
- Technical skills matter, but communication, domain expertise, validation and accountability remain economically valuable.
- Pakistan and other South Asian economies need skills systems and service-export strategies built around human-plus-AI work.
Why the job count is the wrong first question
The public debate frequently divides occupations into two categories: those that AI will replace and those it cannot touch. Labour markets are more complicated. A job is a bundle of tasks involving routine work, exceptions, relationships, judgment and responsibility. AI may automate some tasks, improve others and create new obligations for oversight.
Consider an accountant. Software can help classify transactions and draft reports, but reconciliation, control design, auditing standards and professional responsibility remain important. An employer may redesign staffing, prices and workflow rather than dismiss the entire occupational category. The direction of employment depends on whether higher productivity expands demand for the service as well as reduces hours per client.
That is why the ILO’s refined index treats transformation as a more likely broad outcome than total redundancy. The study also finds exposure varies by occupation, sex and country-income group, making a single global job-loss prediction especially unreliable.
Who receives the productivity dividend?
There are at least four potential recipients. Customers may receive lower prices or better service. Owners may receive larger margins. Workers may receive higher wages, shorter hours or more secure employment. And firms may reinvest the gains to expand services and create different jobs.
The distribution depends on competition, regulation, bargaining, training and the scarcity of complementary skills. A monopolistic or highly concentrated market can produce a different wage outcome from a competitive sector with strong demand for skilled labour. Productivity and wage growth are connected over the long run, but there is no mechanical guarantee that each worker receives a proportional raise immediately.
The OECD’s January 2026 study of digital technology diffusion finds firms that adopt advanced technologies tend to be more productive, while human and technological capital help explain part of that advantage. It does not establish that installing an AI application alone causes the full observed productivity difference. Managers who treat adoption as a software purchase without organizational reform may be disappointed.
The entry-level bottleneck
Entry-level workers traditionally learn through simpler tasks: preparing documents, reviewing routine cases, researching first drafts or organizing datasets. If AI absorbs much of this work, firms can gain immediate efficiency while unintentionally weakening the training ladder into senior roles.
The ILO’s June 2026 evidence review identifies the erosion of opportunities for younger workers as a potential risk. The outcome is not predetermined. Firms can preserve junior development by assigning AI-assisted work that still requires explanation, validation, client interaction and progressively harder decisions.
Governments and educators should respond to the training challenge, not assume that all workers can instantly retrain themselves into engineering roles. Apprenticeships, supervised work experience and accessible continuing education may be more useful than generic certificates promising expertise after a short course.
A distributional framework for AI at work
| Change | Who might gain | Who faces risk | Policy or firm response |
|---|---|---|---|
| Faster routine drafting | Consumers, businesses | Junior task specialists | Train verification and client judgment |
| Automated customer support | Firms, customers | Entry-level support staff | Create escalation and complex-case paths |
| AI-assisted coding | Software teams | Workers dependent on simple tasks | Emphasize testing, architecture and security |
| Better scheduling and logistics | Companies, customers | Workers facing closer monitoring | Transparent standards and worker input |
| Data-driven performance scoring | Managers | Workers under opaque evaluation | Explainability, contestability and privacy |
Original framework. Effects vary across sectors, occupations and labour institutions.
The table reveals a larger point: automation can improve consumer service while imposing concentrated transition costs on a smaller workforce. That may increase total economic welfare and still be socially disruptive. Policy needs to address both realities rather than reject useful technology or dismiss affected workers.
Skills that are becoming more valuable
AI literacy is necessary but insufficient. The highest-value professional often understands a real-world domain and can judge whether the model’s answer is correct. In healthcare, finance, engineering and law, mistakes carry consequences; responsibility cannot simply be handed to a chatbot. Data protection, communication, conflict resolution and ethical judgment remain valuable.
For workers entering the market, a useful portfolio should show the outcome of their work: a verified analysis, a functioning application, a documented process improvement or credible client results. Employers have reason to value candidates who can explain how they checked AI-generated outputs, handled uncertainty and recognized limitations.
In practical terms, training should emphasize three layers: foundational numeracy and communication; field-specific expertise; and the ability to supervise and integrate digital tools. Treating prompt-writing alone as a complete career strategy risks leaving workers exposed as interfaces and model capabilities change.
The international wage divide
The technology can make some digital services easier to trade internationally, potentially expanding demand for remote professionals. It can also lower the price of routine outsourced work if many suppliers use the same tools. A country dependent on repetitive low-margin services might face pricing pressure even as total service volumes grow.
The IMF’s October 2026 global outlook describes AI investment as a key economic support in parts of the world, but benefits are uneven. That asymmetry could widen if only countries with strong digital infrastructure, capital and skills capture the higher-value segments of the market.
A policy response should focus on enabling complementary capabilities: language and communication standards, secure cross-border payments, dependable internet, domain-specialized training and professional certification. Subsidizing AI-tool subscriptions without building these foundations is unlikely to deliver sustainable wage growth.
Pakistan’s labour-market opportunity
Pakistan has potential in software, digital services, accounting support, design and specialized remote work. But competitiveness depends on the quality, reliability and accountability of the service delivered. AI tools can improve throughput while also exposing lower-value tasks to international competition.
Education policy should therefore avoid a narrow choice between teaching everyone to code and protecting all existing jobs. Students need mathematics, writing, digital competency and real project work; mid-career workers need flexible retraining; employers need incentives to train juniors rather than merely cut routine roles.
A domestic labour-market strategy should also address access. Workers with unreliable electricity, poor connectivity, limited English proficiency or costly international payments are less likely to capture new opportunities. Improving these foundations can turn a technological change into a broader economic opening instead of a concentrated dividend.
How firms should measure AI productivity honestly
Counting AI users or prompts is not enough. A better evaluation compares quality-adjusted output, cycle time, error rates, customer satisfaction and employee workload before and after introduction, while accounting for the cost of software, training, quality assurance and security. Controlled trials where feasible are stronger evidence than anecdotal success stories.
The ILO’s empirical review cautions that reported time savings do not necessarily translate into higher measured output. Firms must decide what they do with time saved: increase output, improve quality, reduce overtime or reduce staff. These choices shape both productivity numbers and labour relations.
Workers should be involved in workflow design because they often know where automated outputs fail. Transparent accountability can increase adoption by making expectations clearer. Secretive surveillance and opaque performance penalties can undermine trust, even when tools are technically efficient.
Why macro growth is not a promise of job security
The world economy can benefit from AI capital spending before the associated productivity gains reach ordinary workplaces. The WTO’s October 2026 analysis attributes a large contribution to global merchandise-trade growth to AI-enabling goods. That measures orders for equipment moving through international supply chains, not higher wages for employees using AI tools.
The UNCTAD 2026 investment report highlights investment concentrated in strategic sectors. This creates a possible mismatch: capital owners and specialized suppliers can record gains while workforces elsewhere encounter task restructuring and uncertain pay. The issue is not whether investment should proceed, but whether adoption and worker development broaden its benefits.
Market concentration also creates financial risk. The IMF Global Financial Stability Report raises concerns about an AI-related asset correction. If expectations are revised abruptly, firms may cut recruitment or training even while the underlying technology remains useful. Workforce programmes should therefore avoid depending entirely on continuous capital-market optimism.
Policy choices that could improve wage outcomes
The labour-market response should combine high-quality basic education with affordable skills upgrading, rules for worker data and performance monitoring, support for genuine job transitions and stronger competition so the benefits of innovation are not captured only by a few dominant firms.
Publicly funded training should be evaluated by real employment and wage outcomes, not enrolments or certificates issued. Industrial and export policy should reward measurable skills transfer and customer value. Schools and universities should teach students to interrogate machine-generated results rather than treat them as authoritative.
None of this implies that governments can or should guarantee every historical job title. The more realistic objective is to help people retain bargaining power, income opportunities and routes into high-value work as tasks change.
Risks and limits of the evidence
Occupational exposure scores describe technological potential, not realized unemployment. Firm surveys may overstate adoption or time savings, while national productivity data are slower to reflect reorganization. Labour-market outcomes also vary across countries with different regulations and welfare systems. Predictions about the exact number of jobs AI will remove should be treated skeptically unless based on transparent methods and dates.
Frequently asked questions
Will AI replace one in four jobs?
No. The ILO found one in four workers are in occupations with some exposure, not that one in four jobs will disappear.
Does AI always raise wages?
No. Wage outcomes depend on competition, bargaining, demand, skills and whether firms pass productivity gains to employees.
Why might entry-level workers be vulnerable?
Some routine tasks used to train junior workers are easier to automate, potentially narrowing the first steps of a career unless companies redesign training.
Is AI improving productivity in 2026?
Studies show task-level gains, but evidence of widespread measured output and earnings improvements remains uneven.
Which skills should students build?
Foundational reasoning, domain expertise, communication, data literacy, critical verification and responsible tool integration.
How can Pakistan benefit?
By strengthening digital infrastructure, education, international payments and high-quality exportable services that combine AI with human expertise.
Conclusion
The AI labour debate should move beyond dramatic forecasts of mass replacement and equally unhelpful promises of effortless prosperity. Technology changes tasks; institutions determine how many people share the gains. The best economic strategy is to measure genuine productivity, preserve routes into skilled work and strengthen workers’ capacity to negotiate the transition. If those conditions fail, AI can raise measured efficiency while deepening the divide between those who own the systems and those whose labour is reorganized around them.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
AI investment is supporting global activity in 2026, but that does not by itself prove the investment will earn satisfactory returns.
Spending on data centres, chips, networking and electricity infrastructure boosts production today. Profits and productivity may arrive much later—or fall short of expectations. The most useful way to understand the boom is to separate the real assets being built from the valuations attached to their future cash flows.
The IMF’s October 2026 World Economic Outlook identifies AI-led investment as one reason growth has held up despite energy and geopolitical shocks. Meanwhile the IMF Global Financial Stability Report lists an AI-related market correction among the threats that could tighten financial conditions. Those two findings are compatible: a technology can be economically consequential while assets associated with it are mispriced.
Key takeaways
- AI capital expenditure contributes immediately to equipment orders, construction and power infrastructure.
- The WTO says AI-enabling goods accounted for 47% of global merchandise trade growth by value in the first half of 2026.
- Large investment does not automatically establish durable profits, nor do high valuations prove a speculative bubble.
- Power, water, grid access, financing and actual adoption are constraints on the return to AI infrastructure.
- Asia has supply-chain advantages, but emerging economies need to compete in services, skills and reliable infrastructure too.
Follow the economic chain, not the slogans
A cloud company decides to build computing capacity. It buys advanced processors, storage and networking equipment. Contractors build or expand a facility. A utility upgrades substations; engineering firms install cooling. Suppliers hire workers and purchase materials. These are real economic activities even before the data centre’s first customer pays for a computing service.
The supply-chain effects can travel across borders. A server system may depend on design, fabrication, assembly, electrical equipment and software from different economies. The WTO’s October 2026 trade analysis found that AI-enabling goods accounted for 47% of global merchandise trade growth in value terms during the first half of the year. The statistic covers contribution to trade-value growth, not 47% of all world exports and not 47% of GDP growth.
The distinction matters. It shows that AI equipment demand has become unusually important to the change in trade, but it does not mean the gains are widely distributed. Economies producing the most specialized equipment may gain disproportionately, while energy importers or countries outside these supply chains experience few immediate benefits.
Three separate investment stories
The hardware cycle
Demand for processors, memory, networking and cooling systems generates revenue for companies with production capacity. But supply can eventually catch up, and buyers may change specifications or postpone purchases. Equipment that is scarce in one year can have weaker pricing power in another. The investment case should therefore consider order durability and dependence on a few major customers.
The infrastructure cycle
Data centres require land, grid connections, resilient power, fibre links and cooling. The IEA’s October 2026 report on powering AI evaluates electricity-system issues across 34 jurisdictions covering roughly 90% of global data-centre capacity. It identifies affordability, emissions, water use and electricity security as policy concerns. A financially attractive building can still impose costs on surrounding ratepayers if grid upgrades and pricing are poorly designed.
The adoption cycle
Businesses need to integrate AI into actual workflows. A model that produces draft documents faster may reduce working time, but a company does not automatically record higher revenue or better output quality. Training, verification, cybersecurity and software integration can absorb part of the gains. The OECD’s 2026 cross-country evidence finds advanced-technology adoption varies greatly across industries and firm sizes, with human and technological capital important to productivity differences.
This is why the third cycle may take longer than the first two. Building capacity is easier to measure than reorganizing an entire business around a new tool.
What would make the boom a bubble?
The word ‘bubble’ is often used to describe any rapidly rising market. A more disciplined test asks whether asset prices depend on cash-flow assumptions that are both unusually optimistic and difficult to revise. In AI, analysts should consider whether customer demand and price per unit of computing will support the cost of hardware replacement, capital financing, energy, staffing and security.
Another issue is circular financing. If infrastructure suppliers, major customers and financiers depend heavily on the same expected growth trajectory, an adverse revision can affect multiple balance sheets simultaneously. This does not prove that such a collapse will happen. It explains why concentration can magnify a shock even when initial projects are economically genuine.
The IMF’s 2026 financial-stability assessment warns that an AI-related correction could be amplified by leverage and concentrated positions. The relevant question is therefore how much risk sits outside transparent public equity markets—in private credit, leveraged investment vehicles and large contractual commitments.
An investor’s and policymaker’s dashboard
| Question | Healthy evidence | Warning sign |
|---|---|---|
| Are customers paying? | Repeat revenue and demonstrable usage | Rising capacity without confirmed demand |
| Is computing economic? | Positive returns after energy and replacement costs | Profitability reliant on permanent high prices |
| Is electricity available? | Funded grid connection and transparent tariffs | Unfunded or delayed grid upgrades |
| Is adoption productive? | Better verified output per worker or process | Only demonstrations and time-saved surveys |
| Is financial exposure diversified? | Broad customer base and prudent funding | Crowded positions, leverage and opaque obligations |
| Can low-income countries participate? | Skills, connectivity and export access | Incentives restricted to a small group of hubs |
Original editorial due-diligence framework; the indicators are tests, not factual ratings of particular companies.
Why Asia could win without every economy winning
AI hardware’s international supply chain rewards clusters with manufacturing expertise, deep supplier networks and reliable power. But clustering also means a handful of economies capture much of the immediate capital expenditure. The UNCTAD World Investment Report 2026 describes a global investment rebound concentrated in a narrow set of recipients and strategic sectors.
For South Asia the route to participation may be less glamorous but more achievable. Software services, testing, security review, back-office workflow redesign and domain-specific digital services all sell expertise rather than massive server farms. These activities still require reliable broadband, predictable cross-border payments, trained workers and credible data governance.
Pakistan’s economic policy should distinguish an exportable service from a subsidized prestige project. Investing public funds in computing infrastructure makes sense only if realistic demand, electricity availability and measurable local benefits justify the expenditure. A smaller programme improving technical education, network reliability and digital payments may sometimes deliver more development value than a headline-grabbing facility.
Productivity is the ultimate scorecard
The International Labour Organization’s June 2026 evidence review finds real but uneven gains, with reported time savings not yet consistently translated into measured output, earnings or employment. That observation neither debunks AI nor validates unlimited spending. It suggests adoption and measurement are lagging behind deployment.
Consider a legal services business. Faster document drafting might reduce the hours needed for a first version. But lawyers must check accuracy, safeguard confidentiality and remain responsible for advice. Whether the firm becomes more productive depends on client pricing, workload, quality control and staff redeployment. A narrowly defined speed improvement should not be extrapolated into an economy-wide productivity miracle.
Productivity can also appear in unexpected places: lower error rates, fewer customer callbacks, better scheduling or quicker identification of equipment faults. Firms should measure outcomes, not only the number of employees using AI tools. Governments in turn should measure diffusion among ordinary enterprises, not just investment announcements by technology leaders.
The energy bill is part of the AI bill
The new infrastructure cannot run on investor expectations alone. It needs physical electricity, generation capacity, transformers, water or alternative cooling systems and dependable grid management. Pricing decisions determine who bears those costs. A development strategy that promises cheap dedicated electricity to data centres while passing network expenses to households can distort both competition and social acceptance.
The IEA’s October 2026 AI-electricity study makes the challenge concrete: policymakers must integrate fast-growing concentrated demand while maintaining affordability and security. The opportunity is to build infrastructure that serves broader industrial needs, not merely one class of customers.
There is an additional investment trap. Infrastructure can remain productive for decades, while specialized chips may face faster economic obsolescence. Valuations must reflect depreciation and replacement cycles. A data centre may have a long-lived building and grid connection but require costly hardware renewal to remain competitive.
What would change the verdict in 2027?
A credible bullish case would feature continued broad customer adoption, profits after depreciation, productivity improvements and expansion beyond the richest firms and countries. A bearish case would feature overcapacity, falling revenue per unit of computing, financing stress or slower-than-expected enterprise uptake. Between those extremes lies a more plausible uneven outcome: useful AI services alongside disappointed investors in some projects.
To judge the outcome, watch capital expenditure and customer revenue, investment commitments and grid availability, user adoption and verified output. Avoid treating stock-market performance as a direct proxy for society’s benefit from technology.
Frequently asked questions
Is the AI boom causing global GDP growth?
AI-related investment supports construction, hardware sales and services. The IMF identifies it as an important source of current resilience, but not the sole explanation for global growth.
Does a large increase in AI trade mean all countries benefit?
No. The WTO’s statistic concerns AI-enabling goods’ contribution to merchandise trade growth in value terms. Benefits depend on each economy’s position in the supply chain.
Is there definitely an AI bubble in 2026?
No definitive test establishes that the whole sector is a bubble. Valuation risk is elevated where expected future earnings are highly optimistic or financing is fragile.
Why do data centres affect household electricity costs?
They can require new network capacity and generation. Whether households pay part of the bill depends on utility regulation, connection charges and electricity tariffs.
Can Pakistan benefit without making chips?
Potentially, through software, compliance, workflow redesign, data services and workforce skills—provided domestic infrastructure and payment systems improve.
What is the most important performance measure?
Sustainable returns and verified productivity gains after total costs are counted, not just the number of models, users or newly announced facilities.
Conclusion
AI can sustain near-term global activity and still disappoint some investors. That is not a contradiction; it is the difference between economic spillovers and financial returns. For policymakers, the priority should be broad diffusion, affordable infrastructure and competition. For investors, it should be evidence of durable customers and profits. The boom becomes more valuable—and less fragile—when its benefits extend beyond an expensive and concentrated build-out.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The AI capital-spending boom is driving a concentrated global trade expansion. Pakistan cannot assume it will capture semiconductor profits, but it can compete for selective services, implementation and skills-intensive opportunities. This feature explains the mechanisms, risks and practical decisions that matter through 2027, with particular attention to Pakistan’s different exposure to energy prices, external financing, global trade and AI investment.
At a glance
- World output is forecast to rise, but opportunities and costs are uneven across countries.
- Global inflation forecasts do not predict household prices in Pakistan.
- The AI capital expenditure cycle lifts trade in electronics but may not translate into productivity gains everywhere.
- Pakistan’s IMF staff-level agreement is a milestone, not final Board approval.
- Stronger exports, competitive energy, fiscal credibility and skills are essential to durable growth.
The verified starting point: what the numbers actually say
The IMF October 2026 World Economic Outlook projects global growth of 3.1% in calendar 2026 and 3.4% in calendar 2027, alongside global headline inflation of 4.7% and 4.1%, respectively. Its statistical cutoff is 1 October 2026. The WTO October 2026 trade outlook projects merchandise trade volume growth of 3.9% in 2026 and 4.1% in 2027, versus commercial-services trade volume growth of 3.3% and 6.4%. These are forecasts from different statistical systems, not interchangeable growth measures.
For Pakistan, the IMF Pakistan October 7 staff-level agreement estimated FY2026 growth of 3.6%, September headline inflation of approximately 10.3%, and gross reserves near $21.5 billion at end-September. The fourth EFF review and third RSF review had reached staff-level agreement only, pending IMF Executive Board approval as of the release. Pakistan’s fiscal years run July–June; IMF global growth figures refer to calendar years.
| Indicator | 2026 | 2027 | Important distinction |
|---|---|---|---|
| IMF world GDP growth | 3.1% | 3.4% | Calendar-year projection |
| IMF world headline inflation | 4.7% | 4.1% | Global estimate, not Pakistan CPI |
| WTO goods trade volume growth | 3.9% | 4.1% | Real volume, not nominal trade value |
| WTO commercial services volume growth | 3.3% | 6.4% | Conditional rebound, not guaranteed |
The World Bank June 2026 Global Economic Prospects provides an earlier comparison framework, but its publication date and methodology differ from the October IMF and WTO releases. A thoughtful analysis should compare like with like and should never treat projections as realized outcomes. For a Pakistan-focused story, the crucial question is how global conditions enter domestic economic life.
Why this story matters now
The WTO October 2026 executive summary says AI-enabling goods accounted for 47% of year-on-year growth in the value of world merchandise trade during the first half of 2026. That does not mean 47% of all merchandise trade was AI-related. It identifies a contribution to growth, and in nominal value terms. The same source notes that AI-enabling goods trade rose 67% year-on-year in that period. These figures show how a narrow technology cycle can make global trade appear stronger even as other sectors struggle.
Meanwhile the Reuters October 2026 IMF annual meetings reports persistent concern about global financial risks, geopolitical disruptions and the uneven sharing of AI gains. The Reuters October 2026 Asian growth describes a region where technology investment supports some exporters while energy costs and higher yields challenge others. Pakistan is therefore exposed simultaneously to a potential technology opportunity and to more conventional fuel, financing and trade vulnerabilities.
The evidence for an extraordinary AI hardware cycle
For the evidence for an extraordinary ai hardware cycle, The spectacular rise of AI-enabling goods trade should not be confused with a universal productivity breakthrough. Buying servers is an input; measurable economic gains require organizations to redesign processes and solve problems for customers.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For the evidence for an extraordinary ai hardware cycle, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Why AI-enabled trade is geographically concentrated
For why ai-enabled trade is geographically concentrated, Pakistan’s competitive case is more likely to begin in software implementation, business-process services, local-language tools and industry-specific integration than in cutting-edge semiconductor fabrication. That is an assessment of attainable starting conditions, not a forecast of guaranteed success.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For why ai-enabled trade is geographically concentrated, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Pakistan’s realistic position in the value chain
For pakistan’s realistic position in the value chain, A healthy AI investment program measures output per worker, error rates, export revenues and customer retention. If those indicators do not improve, expenditure on software licenses may merely raise operating costs.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For pakistan’s realistic position in the value chain, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Electricity and connectivity as economic constraints
For electricity and connectivity as economic constraints, The spectacular rise of AI-enabling goods trade should not be confused with a universal productivity breakthrough. Buying servers is an input; measurable economic gains require organizations to redesign processes and solve problems for customers.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For electricity and connectivity as economic constraints, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
What would signal a sustainable AI payoff
For what would signal a sustainable ai payoff, Pakistan’s competitive case is more likely to begin in software implementation, business-process services, local-language tools and industry-specific integration than in cutting-edge semiconductor fabrication. That is an assessment of attainable starting conditions, not a forecast of guaranteed success.
This matters for economic decision-making because firms and households cannot adjust instantaneously when conditions shift. Prices, contracts, worker skills and financial obligations move on different schedules. Analysts should identify the timetable, who bears the immediate cost, and who may capture the longer-term benefit.
A credible implementation plan requires named institutions, measurable indicators and regular public reporting. The point is not to promise an effortless transition; it is to make policy options concrete enough to compare their benefits and trade-offs.
Pakistan-specific decision test. For what would signal a sustainable ai payoff, ask four questions: (1) Which import cost, export opportunity, credit channel or productivity constraint is affected? (2) Which groups face the first-round effects? (3) What could policymakers or firms change within six months? (4) Which published indicator would demonstrate improvement rather than merely announce activity?
What to monitor: (i) official monthly or quarterly data; (ii) movements in export receipts and import bills; (iii) price changes versus changes in physical volumes; (iv) borrowing and working-capital costs; and (v) job quality and household purchasing power. A single monthly reading can be noisy. Comparing several releases helps distinguish a trend from a short-lived disturbance.
Policy options: three alternative paths, not numerical forecasts
| Scenario | Assumptions | Implications for Pakistan | Early warning or confirmation |
|---|---|---|---|
| More favorable | Energy costs stabilize; export markets remain open; AI use generates measurable efficiency | Space for investment, steadier purchasing power and stronger services exports | Export orders, real income and private investment improve together |
| Central case | Global growth follows the broad institutional outlook; commodity and funding pressures fluctuate | Gradual recovery with uneven gains across sectors | Stable external balances without a broad productivity surge |
| Adverse | Energy disruptions persist; financing costs rise; AI investment is repriced | Imports become more costly, credit tighter and fiscal choices harder | Reserves, inflation expectations and financing costs weaken at once |
These are qualitative editorial scenarios, not probabilities assigned by an econometric model. Their value lies in clarifying which evidence would require an updated judgment. The IMF October 2026 World Economic Outlook explicitly emphasizes downside risks involving conflict, trade tension, debt and reassessment of AI expectations.
A practical action agenda
For policymakers, the first responsibility is to protect hard-won macroeconomic stability while removing barriers to productivity. Regulatory predictability, tax administration, targeted social protection and transparent energy decisions are more useful than shifting incentives that are impossible for businesses to plan around. The IMF Pakistan 2026 country report identifies revenue mobilization, reform of state enterprises, energy-sector viability and improvements in human capital as linked policy priorities.
For exporters, resilience means identifying where demand is growing, investing in reliable delivery and obtaining credible certifications. Export strategies should track volumes, domestic value added and customer retention; gross receipts alone do not disclose profitability. For small businesses, the practical priority is to map exposure to fuel, electricity, imports and foreign-exchange requirements and to stress-test cash flows before making expansion commitments.
For households, risk management begins with an affordable budget, attention to debt servicing and a realistic distinction between nominal wage gains and purchasing power. For workers, portable skills and credible training can expand options across changing industries. None of this makes external shocks harmless; it simply offers concrete ways to be less exposed.
How this analysis differs from generic global coverage
Major international reporting is indispensable for establishing what happened. The Reuters October 2026 WTO briefing emphasizes the boost from AI to merchandise trade and the pressure of geopolitical disruption. Institutional releases provide detailed projections. This article goes a step further by asking how those macroeconomic signals might translate into local import costs, export competitiveness, employment, household budgets and reform choices. It is an interpretation of attributed evidence, not a claim of exclusive interviews or original field reporting.
The difference is particularly relevant for Pakistan because a global technology boom may coincide with higher costs for countries that import fuel but do not manufacture the equipment in highest demand. No serious strategy should assume that a worldwide headline rate automatically delivers the same benefits locally.
Frequently asked questions
What is the IMF’s global growth forecast for 2027?
The IMF’s October 2026 World Economic Outlook projects 3.4% global GDP growth in 2027, following 3.1% in 2026. These are calendar-year forecasts and may be revised as new data becomes available. See the IMF October 2026 World Economic Outlook.
Is global inflation expected to fall in 2027?
Yes, the October IMF forecast projects global headline inflation easing from 4.7% in 2026 to 4.1% in 2027. That describes the world aggregate and does not imply that prices in Pakistan will fall in absolute terms.
Is Pakistan’s latest IMF financing already approved?
The 7 October 2026 IMF release announced staff-level agreement for the fourth EFF and third RSF reviews, subject to Executive Board approval. The release should not be described as a completed Board decision. See the IMF Pakistan October 7 staff-level agreement.
Will AI investment create jobs in Pakistan?
It could create demand for implementation, software services and specialist support, while also changing tasks in existing occupations. The result depends on skills, investment, electricity reliability and competitive access to customers. No credible source guarantees a particular employment gain.
Does the WTO predict rapid growth in all kinds of trade?
No. Its October outlook differentiates merchandise volume growth from commercial-services volume growth and notes uneven performance by sector and region. Read the WTO October 2026 executive summary.
What should Pakistani companies monitor through 2027?
Export order books, input costs, electricity reliability, financing terms, exchange-rate conditions and customer demand are more operationally useful than a single global growth figure. Businesses should compare these against their own cash flows and margins.
Conclusion: the decisive issue is transmission, not the headline
The AI capital-spending boom is driving a concentrated global trade expansion. Pakistan cannot assume it will capture semiconductor profits, but it can compete for selective services, implementation and skills-intensive opportunities. The balance of risks is mixed: advanced technology can expand world production and trade, but it does not neutralize an energy shock or a financing squeeze. For Pakistan, policy credibility, internationally competitive exports and productivity-enhancing investment will determine how much of a fragile global expansion becomes better living standards at home.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Fed Meeting on October 28: Hike or Hold—and Why Pakistan Investors Should Care

Can Pakistan Turn US–Iran Mediation Into an Economic Dividend?

Oil Above $100: How Higher Crude Prices Reach Pakistan’s Rupee, Petrol and Imports

SBP Interest Rate at 11.5%: What Will Decide Pakistan’s Next Policy Move?

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025