
Analysis
The Pragmatic Pivot: Etihad European Expansion Signals New Strategy

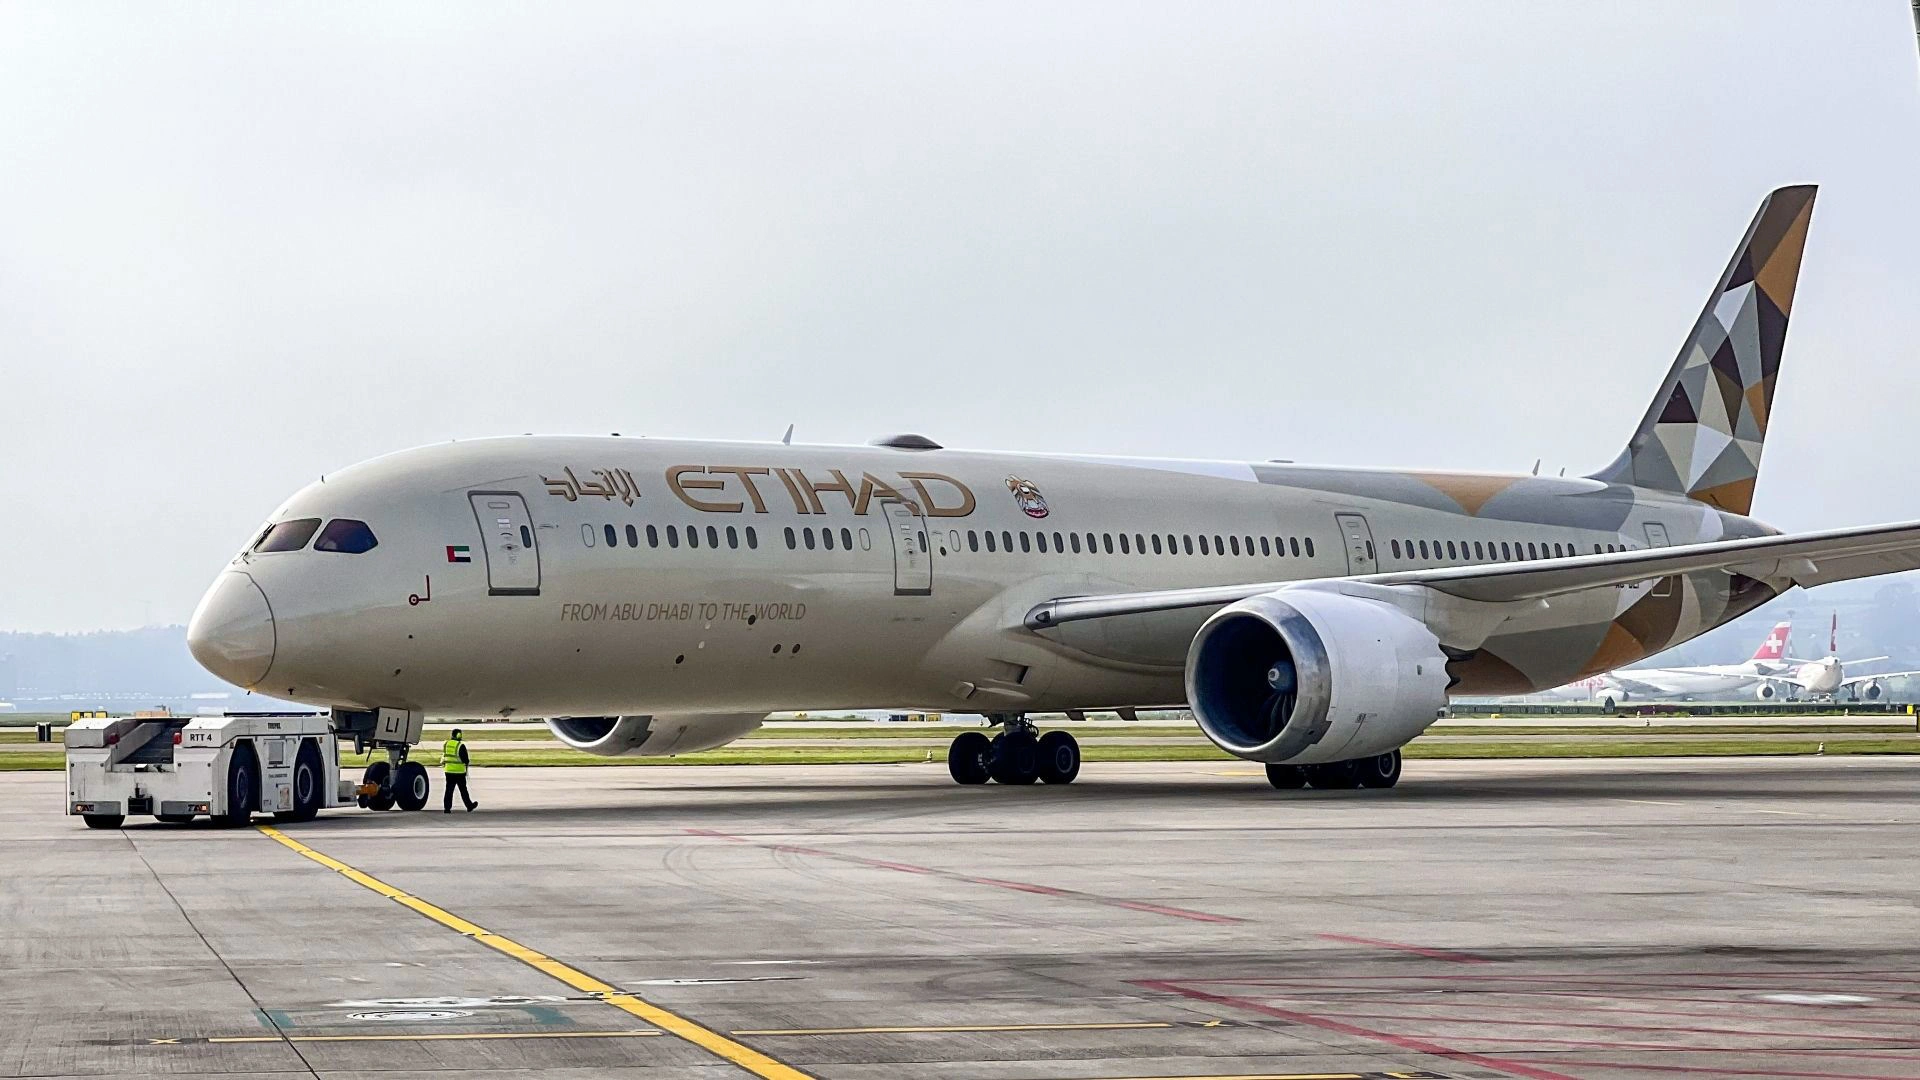
Antonoaldo Neves, Etihad Airways’ chief executive, took the helm with a singular, unsentimental mandate: strip away the vanity and chase the yield. The ghosts of the airline’s disastrous 2010s equity spending spree—a period defined by burning cash on doomed European carriers like Air Berlin and Alitalia—are finally exorcised. Today, from the polished concourses of the newly inaugurated Terminal A at Zayed International Airport, a quieter, deadlier calculus is taking shape. This week’s announcement of an Etihad European expansion—specifically adding Prague and Warsaw to its summer 2025 route map—is not merely about planting flags in foreign capitals. It is a calculated strike in the escalating air war over the global transit passenger.
The aviation landscape of the Arabian Gulf has fundamentally transformed since the pandemic. Abu Dhabi is no longer trying to outspend Dubai or out-fly Doha. Instead, it is playing a game of surgical precision.
Global passenger demand is currently testing the physical limits of airport infrastructure and aircraft leasing markets. According to the International Air Transport Association (IATA), Middle Eastern carriers posted a 10.8% year-on-year increase in international traffic midway through 2024. Yet, growth is bottlenecked by systemic delivery delays from both Boeing and Airbus, forcing airline executives to treat every available aircraft as an ultra-premium asset.
That said, Etihad remains remarkably unbothered by the macro-level chaos. Armed with a leaner fleet and a restructured balance sheet, the carrier is selectively targeting secondary European markets where legacy competitors are retreating or failing to meet surging point-to-point demand.
The Economics of Eastern Europe
Prague and Warsaw are not the glittering long-haul megahubs of London or Frankfurt. They are, however, formidable economic engines in their own right. By deploying Boeing 787 Dreamliners to these cities, Etihad is capturing a highly specific demographic. They are targeting affluent Eastern European tourists heading to Southeast Asia, alongside a rapidly growing cohort of corporate travellers facilitating trade between the Arabian Peninsula and the Visegrád Group.
Etihad new destinations are chosen through ruthless route profitability algorithms, not political prestige.
For years, passengers from Poland and the Czech Republic bound for Thailand, Vietnam, or the Maldives had to transit through Munich, Paris, or Amsterdam. This geographic inefficiency enriched Air France-KLM and the Lufthansa Group. Abu Dhabi is simply cutting out the middleman. By flying directly into these Eastern European capitals, Etihad captures the full fare premium while dramatically reducing the total travel time for the consumer.
The numbers justify the aggression. Passenger footfall between Eastern Europe and the United Arab Emirates has surged, driven by relaxed visa regimes and an influx of foreign direct investment. Reuters market data indicates that European outbound leisure travel has fully eclipsed 2019 levels, with premium cabin yields holding stubbornly high despite lingering inflationary pressures across the eurozone.
This is where the Neves strategy shines. He knows widebody aircraft are precious commodities in a supply-constrained world. You do not park a $250 million jet on the tarmac for nine hours at Heathrow if you can turn it around in two hours at Warsaw Chopin Airport. The asset utilisation rates on these mid-haul, six-hour European sectors are phenomenally efficient. They allow the aircraft to return to Abu Dhabi just in time to catch the midnight departure wave feeding traffic to Mumbai, Bangkok, and Sydney.
Reframing the Abu Dhabi Aviation Strategy
The obvious question requires a direct answer. Why is Etihad expanding its European network? Etihad is expanding its European network to capture underserved point-to-point premium leisure traffic and to feed its highly profitable Southeast Asian transit routes. This strategy bypasses congested Western European hubs while maximising the daily utilisation of its current widebody aircraft fleet.
That 43-word reality dictates every move the airline makes today.
The era of “The Residence”—the hyper-luxurious three-room suite in the sky that once defined the brand under former CEO James Hogan—is fading into aviation history. Today, the Abu Dhabi aviation strategy is defined by load factors, belly-hold cargo revenue, and operating margins.
The picture is more complicated when you look 130 kilometres up the road. Emirates, the colossus of Dubai, operates a fundamentally different model. Tim Clark built a machine designed to move the entire world through a single point using massive, high-density Airbus A380s. Qatar Airways, under the relentless drive of former chief Akbar Al Baker and his successor Badr Mohammed Al Meer, built an obsessive, high-frequency network that blankets the globe.
Etihad is choosing the middle path. It cannot match Emirates on pure volume, and it will not bleed cash to match Qatar on sheer connectivity.
What follows, however, is a masterclass in niche dominance. By targeting cities like Prague and Warsaw, Etihad avoids entering a financial bloodbath over landing slots at London Heathrow or Paris Charles de Gaulle. They are finding uncontested airspace. The Financial Times recently observed that mid-sized network carriers are currently posting the highest operating margins in the industry. They achieve this precisely because they are not forced to dump excess capacity on hyper-competitive trunk routes just to maintain market share.
Supply Chains and Sovereign Ambitions
This expansion ripples far beyond the departure gates of Eastern Europe. Downstream, the implications for European legacy carriers are severe.
Air France-KLM and the Lufthansa Group have historically relied on their Eastern European feeder networks to prop up the profitability of their long-haul Asian operations. When Middle East carriers Europe strategies shift toward these secondary cities, the European incumbents bleed high-yielding transit passengers. A Polish executive travelling to Singapore no longer needs to connect in Frankfurt; they can fly south to Abu Dhabi and connect east, often on newer aircraft and with superior service.
There is also the physical reality of the metal. The global aviation supply chain is severely fractured. Both Boeing and Airbus are missing delivery targets by months, and in some cases, years. Airlines are being forced to extend the leases of older, less fuel-efficient aircraft and cannibalise parts just to maintain their published schedules. Engine durability issues from manufacturers like Pratt & Whitney have grounded dozens of narrowbody jets globally.
In this hostile environment, launching two medium-haul destinations is a flex of operational reliability.
It signals to the market—and to the sovereign wealth funds backing the enterprise—that Etihad has secured the necessary lift to execute its “Journey 2030” growth mandate. The carrier plans to double its fleet to 150 aircraft and triple its passenger numbers to 33 million by the end of the decade. Adding routes is easy; flying them profitably when aircraft are scarce is the true test of management.
Every new European route also serves the broader geopolitical mandate of the UAE. Abu Dhabi is aggressively pivoting away from hydrocarbon dependency. Bloomberg Intelligence estimates that the broader tourism, logistics, and aviation sector now accounts for a rapidly growing percentage of the emirate’s non-oil GDP. Zayed International Airport capacity was built for exactly this moment. The glittering Terminal A, a $3 billion architectural marvel capable of handling 45 million passengers annually, needs humans to justify its existence. Prague and Warsaw are merely the latest tributaries feeding the river.
The Limits of the Desert Hub Model
Still, skepticism remains. The rapid scaling of Gulf carriers has historically triggered fierce protectionist backlash from European regulators and domestic airlines.
Can a region roughly the size of Scotland truly sustain three massive global aviation hubs operating within a 400-kilometre radius? Dissenting voices argue that the current yield environment is an anomaly, artificially inflated by post-pandemic revenge travel and constrained global capacity. Once Airbus and Boeing resolve their supply chain bottlenecks and flood the market with new jets, yields will inevitably soften.
“The Gulf carrier model is heavily reliant on a continuous, uninterrupted flow of global free trade and open borders,” notes a recent structural analysis by CAPA – Centre for Aviation. “As European states become increasingly protective of their environmental targets and domestic carriers, securing bilateral air rights for unlimited expansion will become exponentially more difficult.”
This is a structural vulnerability that cannot be ignored. European governments, spurred by Brussels, are imposing synthetic aviation fuel mandates and aggressive carbon taxes that disproportionately affect long-haul transit carriers. If Poland or the Czech Republic face pressure from the European Union to cap Gulf carrier frequencies on environmental grounds, the economics of these new routes collapse overnight. Lufthansa CEO Carsten Spohr has spent the better part of a decade lobbying for what he terms a “level playing field” against state-backed Gulf carriers.
Etihad’s smaller scale—its very advantage in agility—makes it susceptible to targeted price wars. If Emirates decides to drop a 500-seat A380 into Prague, or if Qatar Airways slashes fares out of Warsaw to protect its market share, Etihad lacks the immense financial shock absorbers of its neighbours to sustain a protracted war of attrition.
Closing the Loop on Legacy
The addition of Prague and Warsaw is a microcosm of modern aviation economics. It is not a story of flag-waving vanity, but of calculated, almost clinical efficiency. Etihad has learned the hardest lesson of the airline industry through bitter experience: prestige does not pay the fuel bill, and equity stakes in failing airlines do not buy loyalty.
By hunting in the geographic gaps left by European incumbents and avoiding the brutal crossfire of its larger Gulf neighbours, the airline is engineering a quiet, highly profitable resurrection. The battle for the global transit passenger is no longer being won solely on the flagship routes between London and Sydney. It is being fought, and won, in the margins.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025