
Analysis
China’s 15th Five-Year Plan: Inside the Tech Masterplan Reshaping the World Economy by 2030

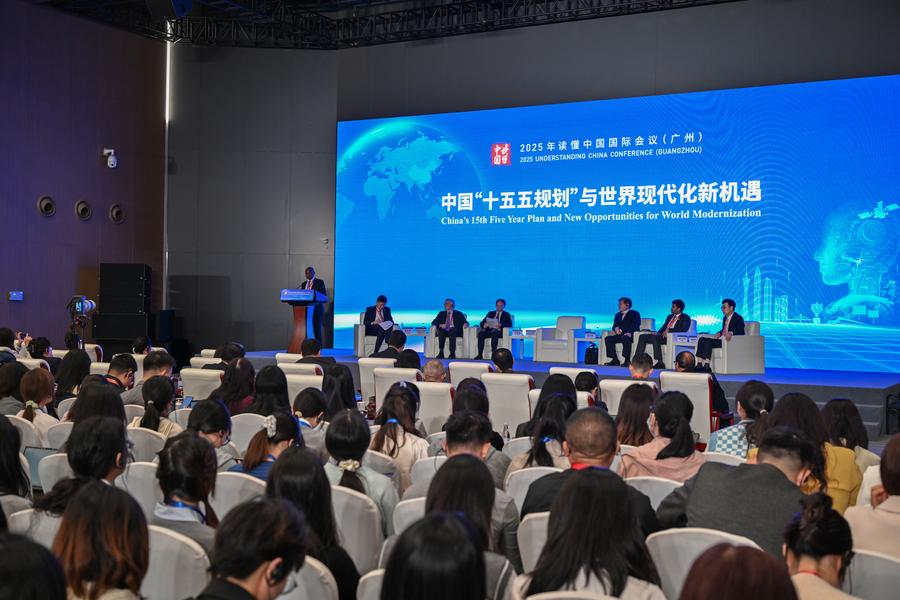
China’s 15th Five-Year Plan (2026–2030) maps a breathtaking tech transformation — humanoid robots, fusion power, 6G brain interfaces, and 109 mega-projects. Here’s what it means for the world.
On the morning of March 12, as delegates filtered out of Beijing’s Great Hall of the People clutching their customary red volumes, the world’s most consequential economic document had just been made official. China’s 15th Five-Year Plan — a 141-page blueprint covering 2026 to 2030 — was formally adopted by the National People’s Congress with the kind of bureaucratic solemnity that belies its radical ambition. The headlines, as usual, fixated on the GDP growth target of 4.5–5 percent, the lowest since China began publishing five-year plans in earnest, and moved on.
That was a mistake.
Strip away the deadening officialese — the ritual invocations of “new quality productive forces,” the calls for “industrial upgrading,” the exhortations toward “high-quality development” — and what emerges is something far more remarkable. China’s 15th FYP is effectively a state-sponsored moonshot program on a civilizational scale: skies dotted with delivery drones and flying taxis; hydrogen and fusion power plants supplying electricity to factories run by humanoid robots; quantum computers crunching problems that would take today’s machines the lifetime of the universe; 6G networks ultimately wired into human cognition itself. The document reads less like a communist planning instrument and more like the collected fever dreams of Silicon Valley’s most ambitious technologists — except it is backed by the full industrial and financial muscle of the world’s second-largest economy, and it has a deadline.
China’s New Quality Productive Forces: What the Jargon Actually Means
The phrase “new quality productive forces” (新质生产力) has been Xi Jinping’s preferred economic shorthand since 2023. In the 15th FYP, it becomes load-bearing architecture. The term translates, in practical terms, to a decisive pivot away from the debt-fuelled, steel-and-concrete model that powered China’s growth for three decades, and toward an economy built on frontier technology, high-value manufacturing, and innovation-led productivity gains.
According to the plan’s formal outline, China’s emerging pillar industries — spanning new-generation information technology, intelligent connected vehicles, advanced robotics, biomedicine, aerospace, and new materials — are expected to break the 10-trillion-yuan benchmark by 2030. Frontier technologies, meanwhile, are projected to generate an entirely new high-tech sector over the following decade. The government has also committed to increasing nationwide research and development spending by at least 7 percent annually — a pace that, if sustained, would push China’s total R&D expenditure to levels rivalling the United States by the early 2030s.
The sequencing matters. Where the 14th Five-Year Plan (2021–2025) led with technological innovation, the 15th plan places a modernized industrial system first. As the World Economic Forum observed, this reflects a hard-won practical lesson: turning laboratory breakthroughs into scalable, high-value production capacity is the true bottleneck, and Beijing intends to close it. This is less about acceleration and more about reengineering the vehicle itself.
The Embodied Intelligence Revolution: 150 Firms, One Trillion Yuan, and a Procurement Directive
Of all the plan’s technological targets, none is more striking — or more consequential for global manufacturing — than its treatment of humanoid robots and embodied artificial intelligence (具身智能). The term barely appeared in Chinese policy documents before 2023. In the 15th FYP, it commands its own dedicated inset box among the plan’s ten most prioritised “new industry tracks,” alongside integrated circuits, biomanufacturing, and commercial space.
The Diplomat’s primary-source analysis of the plan’s Box 3, Item 02 reveals language that is not aspirational but operational: China will “coordinate the layout of embodied intelligence training grounds, promote virtual-real fusion collaborative training and evolution, develop integrated big-brain/small-brain embodied models and algorithms, tackle key technologies in the body and core components, and accelerate the upgrade and deployment of humanoid robots.” That is a procurement directive, not a wish list.
The industrial reality underpinning this ambition is already formidable. In 2024, China installed 295,000 industrial robots — 54 percent of the global total — with an operational stock surpassing 2 million units. In the nascent humanoid segment, Chinese firms shipped roughly 90 percent of the world’s units in 2025, led by AgiBot (5,168 units), Unitree (over 4,200 units), and UBTech. More than 150 humanoid robot companies now operate in China. The government has committed a 1-trillion-yuan ($138 billion) state-backed fund to advancing humanoid robots, industrial automation, and embodied AI — a sum that dwarfs any comparable Western initiative.
The parallel with Elon Musk’s Optimus project is unavoidable. But where Tesla’s humanoid program represents a single company’s bet, China’s approach is a whole-of-nation mobilisation. The plan’s Chapter 13 establishes an “AI+” action plan as a cross-cutting national program covering six domains: science and technology, industrial development, consumer upgrades, social welfare, governance, and national security. Artificial intelligence appears more than 50 times in the 141-page document. The strategy is not to build the world’s best AI model — that remains, for now, a largely American contest — but to weave AI into the physical fabric of the economy more deeply and more quickly than any country has ever attempted.
The Low-Altitude Economy: When Drones Become Infrastructure
China’s “low-altitude economy” — a formal policy designation covering commercial drones, urban air mobility, flying taxis, and low-altitude logistics networks — is one of the 15th FYP’s most distinctive concepts, and one that has received insufficient attention in Western coverage.
The plan designates the low-altitude economy as a strategic emerging industry cluster. Multiple provincial governments, from Zhejiang to Inner Mongolia, have already allocated dedicated funding and industrial parks. The underlying logic is compelling: China’s vast geography, its already-dominant position in commercial drone manufacturing (EHang, XPeng AeroHT, and dozens of smaller firms), and its regulatory willingness to deploy technologies at scale give it structural advantages that Western regulators — still debating urban air traffic management frameworks — cannot easily replicate.
By 2030, Beijing envisages a multi-tier airspace management system capable of supporting millions of autonomous drone flights daily, encompassing last-mile delivery, agricultural monitoring, emergency services, and inter-city passenger transport. The economic prize is substantial. Chinese analysts estimate the low-altitude economy could generate 1.5 trillion yuan in annual output by the end of this decade.
Fusion, Hydrogen, and the Energy Backbone of a Tech Superpower
A technology economy of this ambition requires an equally ambitious energy supply. The 15th FYP earmarks hydrogen power and controlled nuclear fusion as “next-generation” energy technologies — a designation that reflects both strategic calculation and genuine scientific progress.
China’s ITER-adjacent fusion program and its Experimental Advanced Superconducting Tokamak (EAST) have already set world records for plasma duration. The 15th FYP provides the policy and financial framework to translate laboratory milestones toward commercial application. The plan’s 109 major engineering projects include dedicated energy infrastructure initiatives — offshore wind farms, coastal nuclear plants, and new power transmission corridors — designed to underpin the electricity demands of an AI-intensive economy.
The hydrogen dimension is particularly significant. Green hydrogen — produced via electrolysis powered by renewables — sits at the intersection of China’s clean energy surplus and its industrial decarbonisation agenda. The IDDRI notes that China’s solar manufacturing capacity now exceeds domestic consumption by a factor of three. That overcapacity is not merely a problem; it is a strategic asset, enabling green hydrogen costs to fall faster in China than anywhere else on earth.
Quantum, 6G, and the Brain-Computer Frontier
The 15th FYP’s most futuristic provisions — quantum computing, 6G communications, and brain-computer interfaces — are where its ambition most visibly strains against physical and ethical reality.
On quantum computing, Chinese research teams achieved significant milestones in photonic quantum computing and superconducting circuits during the 14th FYP period. The 15th FYP commits extraordinary-measures language — comparable, analysts note, to wartime mobilisation — to accelerating breakthroughs. The geopolitical stakes are profound: a functional cryptographically-relevant quantum computer would render most current encryption infrastructure obsolete overnight.
The plan’s 6G ambitions build on China’s commanding position in 5G standardisation. The plan explicitly targets 6G for development during the 2026–2030 period, with the ambition of integrating ultra-high-bandwidth wireless networks into medical devices, industrial systems, and — in the plan’s most provocative passage — brain-computer interfaces. The latter technology, already being developed by domestic firms alongside Neuralink-style devices, appears in the plan as a formal “future industry” alongside quantum technology and biomanufacturing. Its inclusion is not merely techno-utopian signalling. The Chatham House analysis notes that Beijing has elevated these frontier fields to the centre of its economic agenda, with fundamental breakthroughs treated as matters of national strategic priority.
The Semiconductor Pivot: Washington Hasn’t Noticed
One of the most analytically significant aspects of the 15th FYP has received almost no coverage in Western media. China has quietly abandoned the semiconductor self-sufficiency target established under Made in China 2025 — which called for 70 percent domestic chip production and which China missed by roughly 50 percentage points — and replaced it with a deployment metric: digital economy value-added at 12.5 percent of GDP by 2030, up from 10.5 percent in 2025.
The Diplomat’s forensic analysis of the 141-page plan document is striking in this regard: the word for “lithography machine” does not appear once. Neither do “wafer fab,” “extreme ultraviolet,” or “chip manufacturing.” What appears instead is a new strategic vocabulary. Artificial intelligence outnumbers references to integrated circuits by roughly 13 to 1. A new planning term has entered Five-Year Plan history for the first time: 模芯云用 — “model-chip-cloud-application” — encoding a full-stack deployment architecture.
This is not a retreat. The plan calls for “extraordinary measures” on advanced chip fabrication and continues to pursue domestic semiconductor production. But the strategic emphasis has shifted: from how many chips China produces to how deeply computing infrastructure penetrates the economy. The Biden-era export controls targeted the fabrication layer. China has restructured around the other three layers — models, cloud, and applications — where no equivalent countermeasures exist. Whether this represents genuine strategic evolution or an adaptation to inevitable constraints matters less than the operational reality: the infrastructure is being built, domestically and across the developing world via Belt and Road digital initiatives.
The Risks Beijing Isn’t Advertising
No premium analysis of China’s 15th FYP would be complete without confronting the formidable execution risks that the document — by design — underplays.
Overcapacity and involution. The plan acknowledges in unusually strong language the problem of destructive overcompetition — “involution” — in sectors from solar panels to electric vehicles. But enforcement remains politically fraught in an economy where most heavy industry is state-owned and local governments depend on factory employment for social stability. The IDDRI notes that China’s solar manufacturing capacity exceeds domestic consumption by a factor of three. The rest of the world should brace for continued waves of cost-competitive Chinese clean-technology exports.
The demographic constraint. A technology-heavy growth model is a rational response to a shrinking, ageing workforce. But it also demands a quality of human capital — software engineers, AI researchers, quantum physicists — that China is producing in enormous numbers, though not yet at the leading edge of all disciplines. The plan targets over 22 high-value invention patents per 10,000 people by 2030, up from 12 in the 14th FYP. Whether the quality matches the quantity remains an open question.
US export controls and the software gap. Even Beijing’s own technology industry acknowledges that software — operating systems, EDA tools, advanced compilers — remains the most vulnerable layer in China’s technology stack. The Diplomat’s analysis identifies this as the one constraint that US policy has targeted least effectively, and the one China finds hardest to domestically substitute. DeepSeek’s emergence at the start of 2026 demonstrated extraordinary ingenuity in working around hardware constraints, but the gap in frontier software tooling persists.
Energy demand and climate contradiction. An economy built on AI data centres, quantum computing, and electrified manufacturing will consume energy on a transformational scale. The plan’s GDP growth target of 4.5–5 percent, combined with a carbon intensity reduction target of only 17 percent by 2030, draws concern from climate analysts who note that China is likely to fall short of its Paris-aligned emissions commitments. The gap between Beijing’s green-technology leadership and its actual decarbonisation trajectory remains wide.
What This Means for the World
The 15th Five-Year Plan is not, as some Western commentators reflexively characterise it, merely another expression of authoritarian state capitalism paper-planning its way to an imagined future. Nor is it the unambiguous geopolitical threat that hawkish analysts in Washington and Brussels portray. It is something more complex and, in many ways, more consequential: the most coherent large-scale attempt by any government in history to engineer an economy’s transition from extensive to intensive growth through deliberate technological transformation.
For global supply chains, the implications are already unfolding. China installed more industrial robots in 2024 than the rest of the world combined. Its solar and wind manufacturing has structurally reduced the cost of renewable energy globally. Its AI deployment strategy — integrating models into factory floors, logistics networks, and healthcare systems — is generating productivity gains that are difficult to measure but impossible to ignore.
For the United States and Europe, the competitive challenge is genuine but not straightforwardly zero-sum. As Chatham House observes, Beijing has signalled that technological self-reliance and economic resilience are long-term strategic choices, not temporary responses to external pressure. The West’s instinct to restrict, contain, and decouple will shape Beijing’s incentives at the margins but will not fundamentally alter the trajectory of a plan backed by the savings of 1.4 billion people and the organisational capacity of a Leninist state that has repeatedly demonstrated its ability to execute at industrial scale.
For developing economies, China’s ambition may prove most immediately impactful. The plan explicitly targets the Global South as a market for Chinese computing infrastructure, clean technology, and eventually the fruits of the low-altitude economy. A proposed World AI Cooperation Organization and Belt and Road AI platform signal Beijing’s intent to make itself the technology partner of choice for countries locked out of the Silicon Valley ecosystem.
The deeper question — which no five-year plan can answer — is whether a system built on party control, information restriction, and the suppression of the kind of disruptive, bottom-up innovation that produced the internet, the smartphone, and now large language models can truly lead at the frontier. China’s own technology history offers a mixed verdict. It has been exceptional at scaling and deploying technologies invented elsewhere. It produced DeepSeek. It has not yet produced an iPhone.
By 2030, we will know considerably more. What is certain, today, is that the document adopted in Beijing’s Great Hall on March 12 deserves to be read — not in the deadening prose of its officialese, but in plain language, for what it is: the most ambitious attempt in human history to build a technology economy from the top down. Whether it succeeds or stumbles, it will reshape the world either way.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


In an era defined by global economic volatility, supply chain fracturing, and the relentless search for post-pandemic growth drivers, middle powers face a stark choice: passively import technological paradigms dictated by foreign tech superpowers or aggressively architect a sovereign framework that harnesses next-generation efficiencies. Under Prime Minister Anthony Albanese, Australia has chosen the latter.
Navigating the delicate equilibrium between accelerating productivity gains and enforcing robust governance, the Albanese administration’s strategic pivot toward artificial intelligence (AI) has emerged as a compelling blueprint for modern statecraft. Far from a mere policy footnote, Australia’s calculated embrace of AI integration is positioning the nation’s economy for an unprecedented transformation—one projected to inject billions into the domestic ledger while safeguarding social cohesion.
The Productivity Imperative: Bridging the Gap
For years, advanced economies have grappled with sluggish productivity growth—a trend that has severely tested traditional fiscal and monetary levers. Australia has been no exception, confronting multi-decade lows in labour productivity growth that have squeezed profit margins, constrained real wage progression, and fueled cost-of-living anxieties.
Enter artificial intelligence. Economic modelling highlights that large-scale AI adoption could unlock up to AUD $142 billion annually for the Australian economy by 2030, serving as a multi-factor productivity catalyst. Rather than viewing technological automation as a displacement threat, Canberra’s policy machinery has reframed AI as an essential force multiplier across key national sectors—from mining optimisation and agricultural tech to precision manufacturing under the Future Made in Australia agenda.
Small and medium-sized enterprises (SMEs)—the lifeblood of the domestic economy—stand to gain immensely. By automating administrative burdens, streamlining compliance, and optimising supply chain logistics, AI integration allows local businesses to redirect capital toward innovation and high-value creation.
Pioneering a World-First Regulatory Framework
What separates Australia’s approach from the fragmented regulatory environments of the United States or the heavy-handed compliance models of the European Union is its proactive, harmonised architecture.
In July 2026, the Albanese government unveiled a world-leading national AI framework designed to provide certainty for investors while establishing strict guardrails for ethical deployment. Key pillars of this strategy include:
- Sovereign Standards and Intellectual Property Protection: Australia became a global pioneer by enacting clear protections ensuring that local creative works, literature, music, and journalistic output cannot be scraped for AI training models without explicit artist consent and compensation.
- Streamlined Compliance for Frontier Investments: By establishing unified national standards, the framework cuts through bureaucratic red tape, offering international investors expedited approval pathways conditional on adherence to safety and security benchmarks.
- A Binding Social Licence: The framework emphasises that technology must serve human agency. Ensuring public trust remains paramount; algorithms cannot operate as black boxes when critical public services, employment markets, and national security are involved.
Navigating the Geopolitical and Economic Crosswinds
Australia’s economic strategy does not exist in a vacuum. As great power competition reshapes global trade and globalisation pivots toward regional resilience, Canberra is leveraging its vast reserves of critical minerals, rare earths, and clean energy assets.
AI acts as the computational glue binding these traditional resource strengths with future-facing capabilities. For instance, optimising the extraction and processing of critical minerals required for global energy transitions relies heavily on advanced machine learning models and automated logistics. By coupling its natural resource abundance with top-tier university research and skilled graduate pipelines, Australia is making a compelling pitch to global venture capital: come build here, on Australian terms.
Comparative Strategic Advantages
| Strategic Pillar | Traditional Model | Australia’s AI-Integrated Approach |
| Productivity Driver | Capital investment & raw volume expansion | Multi-factor efficiency via sovereign AI deployment |
| Regulatory Stance | Reactive policy or unbridled laissez-faire | Proactive, world-first unified national standards |
| Workforce Strategy | Reliance on lagging skills adaptation | Empowering workers through institutional AI literacy and secure transitions |
| IP & Innovation | Lax protections for digital creators | Enforceable ownership rights over AI training inputs |
The Road Ahead: Can Australia Stick the Landing?
While the macroeconomic projections are dazzling, translating policy ambition into structural reality carries inherent risks. The success of Albanese’s vision will ultimately be judged by execution metrics over the remainder of the decade:
- Skills Alignment: Ensuring that the national education and vocational training sectors can rapidly upskill workers to meet the demands of an AI-augmented labour market.
- Cybersecurity Resilience: As critical infrastructure becomes increasingly digitised and reliant on automated machine-learning networks, national security frameworks must scale defensively to prevent state-sponsored cyber exploitation.
- Equitable Distribution: Ensuring that productivity dividends do not concentrate solely within major metropolitan tech hubs, but actively flow to regional communities and working-class Australians.
Conclusion
Australia’s economic narrative under the Albanese administration is shedding the old tropes of the “lucky country” relying purely on cyclical commodity booms. Instead, it is writing a new chapter of purposeful economic design. By harmonising technological disruption with rigorous ethical standards and worker-centric policies, Australia is proving that middle powers do not have to be passive spectators in the digital revolution—they can help write the rules of the game.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
For decades, the global dominance of the U.S. dollar has rested on two primary pillars: deep, unencumbered liquid capital markets and an indispensable global financial messaging protocol known as SWIFT. When Beijing launched its e-CNY initiative, Western observers initially framed it as a central bank digital currency (CBDC) designed primarily for domestic surveillance, retail convenience, and financial inclusion.
However, recent strategic moves highlight a far more ambitious objective. As documented by the South China Morning Post, Beijing is actively leveraging Hong Kong as its central offshore laboratory to establish the infrastructure required for international cross-border digital yuan adoption.
The crucial strategic question is no longer whether China can engineer robust distributed ledger architecture, but whether an offshore financial hub operating under “One Country, Two Systems” can bridge the gap between rigid domestic capital controls and global institutional acceptance. To succeed, China must resolve the fundamental tension between absolute monetary sovereignty and the open networks required for international currency adoption.
1. The Paradox of the Offshore Laboratory
China’s monetary expansion faces a well-documented structural paradox. According to macroeconomic research from the Carnegie Endowment for International Peace, no currency can achieve true international reserve status without offering open capital accounts and deep, freely convertible liquidity. Yet, completely relaxing capital controls would expose China’s domestic banking system to volatile international capital flows and speculative pressures.
Hong Kong serves as the pressure valve and testing ground for this paradox:
- Legal & Regulatory Buffer: Hong Kong maintains a trusted common law judicial system and an independent monetary authority (Hong Kong Monetary Authority).
- Convertibility Bridge: It allows mainland authorities to test e-CNY settlement, cross-border retail links, and digital asset integration without opening mainland financial markets directly to global speculative shocks.
- Institutional Liquidity: As the world’s premier offshore renminbi hub, Hong Kong provides the institutional counterparties necessary to build real-world transaction volume.
“The digital yuan’s true test lies not in domestic retail adoption, but in whether foreign counterparties can settle cross-border trade without taking on unacceptable regulatory or capital risks.”
2. Wholesale Settlement and Project mBridge
While retail consumer wallets attract considerable media attention, the real geopolitical shift is occurring at the wholesale institutional level. Strategic initiatives like Project mBridge—developed in partnership with the Bank for International Settlements (BIS), the People’s Bank of China, and regional central banks—demonstrate how multi-CBDC platforms can streamline international trade.
As reported in market analyses by Bloomberg and trade finance studies covered by Reuters, multi-lateral CBDC platforms offer significant operational advantages:
- Elimination of Intermediaries: Direct ledger-to-ledger transactions bypass traditional correspondent banking networks.
- Speed and Efficiency: Cross-border settlement times are reduced from days to seconds.
- Cost Reduction: Transaction costs and foreign exchange spreads across regional trade corridors in Asia and the Middle East are dramatically lowered.
If commercial enterprises operating in Hong Kong can settle trade directly in e-CNY with instant finality, Beijing creates a compelling economic incentive for trade partners that operates independently of Western clearing networks.
3. Geopolitical Implications & The Road Ahead
Western policymakers and central bankers are monitoring these developments closely. Recent congressional testimony and Treasury reviews highlighted by Reuters reflect growing concern in Washington that alternative settlement rails could gradually erode the reach and enforcement of Western financial sanctions.
However, technological capability alone does not guarantee global currency dominance. Until foreign corporate treasuries and central banks have full confidence in converted currency liquidity, property rights, and transparent legal protections, the digital yuan will serve primarily as an efficient alternative mechanism for bilateral trade rather than an immediate replacement for the U.S. dollar.
Institutional Summary & Comparison
| Dimension | Conventional Retail Focus | Wholesale / Strategic Reality |
| Primary Mechanism | Retail e-CNY wallets for tourists & merchants | Multi-CBDC corridors (Project mBridge) & Project Ensemble |
| Core Objective | Domestic payments & payment app competition | Disintermediation of correspondent banking and SWIFT rails |
| Primary Barrier | Consumer habituation & merchant readiness | Capital controls, currency convertibility, and institutional trust |
Sources & Citations
- South China Morning Post: Beijing wants Hong Kong to sow the seeds for the digital yuan
- Bank for International Settlements (BIS): Central Bank Digital Currency (CBDC) & Cross-Border Payments Research
- Carnegie Endowment for International Peace: China’s Financial System and Capital Account Dynamics
- Bloomberg Financial Analysis: Global Macro & Digital Currency Integration
- Reuters News & Analysis: Cross-Border Settlement and Global Trade Finance
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
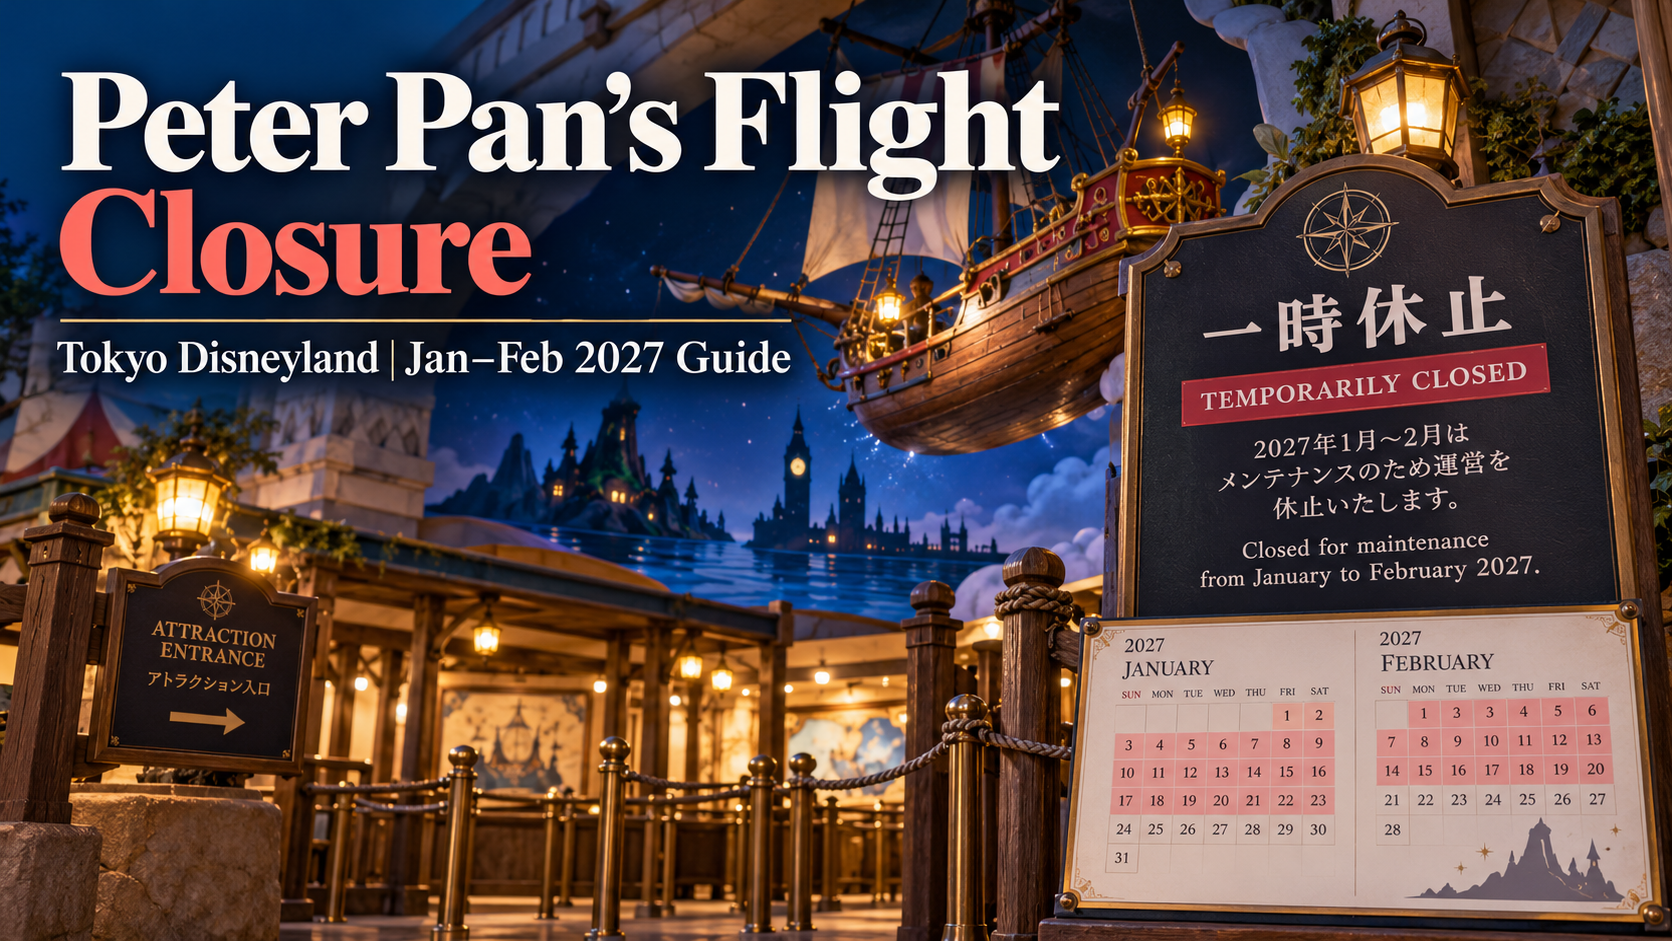
Guests planning a visit to Tokyo Disneyland in early 2027 should put one easily missed detail on their itinerary: Peter Pan’s Flight is scheduled to be temporarily closed from January 6 through February 2, 2027. The operator lists the dates both on its official attraction page and in the Tokyo Disneyland closure schedule. This is a scheduled interruption, not an announcement that the classic ride is being removed permanently. Travelers visiting on dates inside that window should assume the attraction will not be available unless Tokyo Disney Resort publishes a change.
The distinction matters because online references to “Peter Pan closing at Tokyo Disney” can confuse two different parks and two different experiences. Tokyo Disneyland’s Peter Pan’s Flight is a compact Fantasyland ride. Tokyo DisneySea has a separate, newer attraction called Peter Pan’s Never Land Adventure, with its own planned March 2027 maintenance period. The first planning step is making sure the information applies to the ticket you actually bought.
At a glance: what the operator currently says
| Planning question | Verified answer |
|---|---|
| Which attraction? | Peter Pan’s Flight |
| Which park? | Tokyo Disneyland, Fantasyland |
| Scheduled closure starts | January 6, 2027 |
| Scheduled closure ends | February 2, 2027 |
| Reopening expectation | After the listed closure window, subject to operator changes |
| Type of notice | Temporary closure; not announced as permanent |
| Where to recheck | Official attraction listing |
The dates are explicitly labeled as a temporary closure by Tokyo Disney Resort. Do not treat February 3 as an unconditional reopening guarantee: an operator may update maintenance information or temporarily suspend operations for other reasons. Check again shortly before travel and on the day you enter the park.
What is Peter Pan’s Flight?
Peter Pan’s Flight is a dark ride based on the familiar journey from London to Never Land. Guests sit in a flying pirate-ship vehicle that travels through a storybook environment. According to the operator’s ride information, it is in Fantasyland, lasts about two and a half minutes and carries two people per vehicle. It operates indoors and includes dark spaces. These details make it particularly appealing to families who want a gentle, classic Disney experience rather than a high-speed thrill ride.
There are restrictions worth noting even on operating days. The published guidance says a guest must be able to maintain a stable seated position independently and that children may not be held on an adult’s lap during the ride. If your group includes young children, anyone needing seating assistance or visitors uncomfortable with darkness, read the official description and accessibility guidance rather than assuming that the attraction suits everyone because it is short.
Short ride duration is not the same as short waiting time. Demand for well-known classics can vary with crowds, operating conditions and holiday schedules, so it is unwise to schedule a tight sequence of unrelated bookings around a predicted queue. The operator’s app and in-park staff can provide current operating information when the ride is available.
The dates around the closure are not interchangeable
A guest visiting January 5 has a fundamentally different planning position from someone arriving January 6. January 5 falls before the currently listed closure, while January 6 is its opening day. A February 2 visit falls on the final listed day of the maintenance window; February 3 is the earliest day after that window, not a contractual promise that the ride will run.
For a family staying at the resort for multiple days, the difference might be worth changing which day is assigned to Tokyo Disneyland. If one day is before January 6 and another is inside the closure, put Disneyland first if the classic Peter Pan ride is a must-do. But do not swap a park ticket or hotel reservation until you understand the applicable change and cancellation conditions. The economic cost of reshuffling an entire trip can exceed the benefit of experiencing one short ride.
A visitor traveling from overseas may be choosing between a single Disneyland day and a DisneySea day. In that case, consider the trip’s overall priorities. Someone who values vintage Fantasyland attractions may still prefer Disneyland even during the closure. Someone traveling expressly for an immersive Peter Pan adventure could be more interested in the DisneySea attraction—but must buy admission to that different park and verify its own operating schedule.
Other Tokyo Disneyland closures during the same period
The official park maintenance listing shows other attractions with early-2027 closure windows that may overlap your visit. At the time of this review, it lists Jungle Cruise: Wildlife Expeditions from January 6 through March 31, Splash Mountain from January 7 through February 4, and Haunted Mansion from January 8 through February 4. These are operator-published schedules, not independent predictions about refurbishment completion.
This makes the Peter Pan closure more significant for certain visitors than a single unavailable ride might suggest. A group that expected several classic experiences in one afternoon could find multiple priorities temporarily inaccessible. Conversely, the park contains many other attractions and entertainment offerings, and the attractions that remain open should be evaluated on their own current descriptions rather than guessed from historical schedules.
It is worth making a small “must ride / would enjoy / optional” list. Mark each attraction against the closure page. Then build flexibility around weather, performance calendars and queue variation. A plan with alternatives is more resilient than a rigid minute-by-minute schedule.
Better alternatives for different kinds of visitors
If the attraction’s appeal is gentle fantasy storytelling, explore other Fantasyland offerings listed in the official Tokyo Disneyland attraction directory. Filter for ride type and height or access restrictions, and read the current operating details. Do not assume that a neighboring attraction will be open merely because it is not listed in an older travel blog.
If the main attraction is Disney character immersion, devote time to character experiences, themed areas, shopping or scheduled entertainment that is actually available on your day. These can preserve the spirit of the trip without pretending they are substitutes for the ride itself. Some guests will prefer to spend the recovered time on a longer headliner; others may value an unhurried lunch and a park exploration that is less vulnerable to queues.
If the trip is built around Peter Pan specifically, Tokyo DisneySea’s Never Land Adventure may appear attractive. But it is not the same ride: it is a 3D boat-based experience in Fantasy Springs, with different restrictions and a different length. Tokyo Disney Resort’s DisneySea attraction page is the reliable way to compare them. Admission, access arrangements and the day’s capacity remain separate questions.
Parents should also avoid overstating the value of a replacement to children. “Another attraction has pirates” does not make it the planned Peter Pan experience. Setting expectations before entering the park is often more effective than negotiating disappointment in a crowded queue area.
Are refunds or ticket changes automatic?
The announcement of an attraction’s temporary closure does not itself demonstrate that every guest is entitled to a ticket refund or a date change. Theme-park tickets ordinarily grant admission subject to operating conditions, not a binding guarantee that every individual ride will operate. Actual ticket terms, package conditions and any operator-specific accommodation policy govern what can be changed.
Before buying or modifying a pass, review the official Tokyo Disney Resort ticket and reservations guidance and any reseller’s terms. A third-party package might combine transport, hotel rooms and tickets under separate cancellation rules. You should not rely on the statement “ride closed” as a universal reason for a penalty-free cancellation.
If your booking is complex, write down the name of the supplier, reservation reference, exact park date and type of admission. Seek a written answer before paying a change fee. This is particularly important if you plan to move only one day of a multi-day trip and keep the remainder unchanged.
Does Disney Premier Access help during the closure?
No paid queue-management product can make an attraction operate while it is closed. Disney Premier Access is a separate, paid tool for eligible operating experiences; eligibility and availability can change. The official Premier Access guide explains that places may sell out and that the price does not include park admission. It should not be marketed to families as a guaranteed workaround for a published maintenance closure.
The app can nevertheless be useful for other attractions and live operating information. If a ride is unavailable, remove it from the day’s queue-management plan and redirect attention to attractions genuinely offered that day. Check the current product terms before purchasing any additional access.
How to build a more reliable 2027 itinerary
Start with the official attraction closure list rather than the social-media version of it. Choose a date, read the list for the correct park, then check the pages for the two or three attractions most important to your group. If several favorites overlap with closures, compare another travel day, but preserve buffer time and cost limits.
Once you have a provisional itinerary, check whether your whole group can experience the alternatives. A family with a toddler and grandparents may have different needs from a group of teenagers. Ride seating rules, dark environments, height restrictions and walking distances deserve attention before buying optional upgrades.
A week before departure, look at the operator’s park calendar and attraction pages again. On the morning of your visit, follow current app information and staff instructions. Write down a backup plan that does not depend on a single ride reopening on the first conceivable day.
Quick visitor questions
Is Peter Pan’s Flight shutting permanently? The published notice says temporary closure January 6–February 2, 2027. It does not announce permanent removal.
Is it in Tokyo Disneyland or DisneySea? Peter Pan’s Flight is in Tokyo Disneyland’s Fantasyland. DisneySea has the separate Never Land Adventure.
Can I ride on February 2? The current listing includes February 2 in the closure window. Do not plan on riding that day.
Is February 3 the official reopening day? It is the first day after the presently announced closure period, assuming the dates are unchanged. Confirm the park’s live information rather than treating operation as guaranteed.
Should I change my trip? That depends on how important this specific ride is compared with hotel, flights, admission and other attractions. For most travelers, adjusting priorities within the same park is the lower-risk first option.
Final planning advice
This news is not a farewell to Peter Pan’s Flight. It is a defined, temporary gap in the operating calendar. The useful response is to check your exact visit date, compare the rides your family actually cares about and keep a realistic alternative ready. Tokyo Disneyland can still be an appealing destination during the listed closure; the difference between an enjoyable trip and a frustrating one may simply be accurate expectations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Hong Kong Land Acquires Wheelock Place and Renames It Landmark Orchard

DBS PayLah China QR Expansion: Now Accepted at Over 100 Million Merchants

Nvidia Stops Reporting Singapore Revenue After It Hit 22% of Sales: What Investors Need to Know

Global Trade and Tariffs 2026:WTO Barometer Still Shows Growth

Extended Producer Responsibility Changes and the UK Hospitality Sector

GDP and Economic Growth in the US: How It’s Measured, Current Trends

Economic Globalization: How Global Trade Shapes the US Economy, Jobs, and Consumers

Best Life Insurance Companies in the United States 2026: Our Top 5 Picks

Pakistan Auto Policy 2026-31 Explained: EV Tax Cuts, $6 Billion Export Target

When Dollar Debt and Food Imports Collide: The Currency Squeeze

Why Freight and Storage Costs Keep Food Prices High After Oil Falls

Personal Injury Lawyer Near Me in NYC: How to Find the Right Attorney After an Accident

Why Falling World Food Prices Do Not Always Lower Grocery Bills

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025