
IMF
Pakistan Moves From Stabilization to Recovery as IMF Review Puts Reform Momentum in Focus

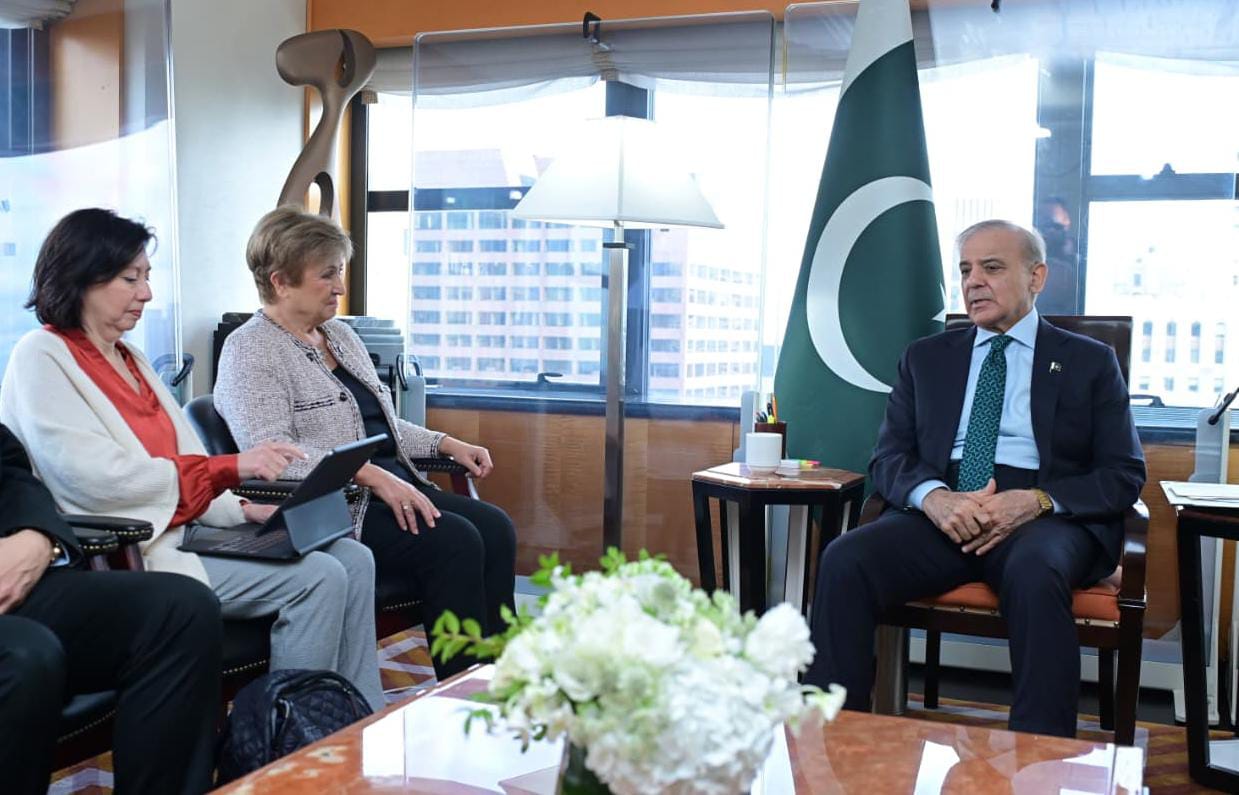
Pakistan is entering a new phase of its economic program, with Prime Minister Shehbaz Sharif saying the country is moving from macroeconomic stabilization toward recovery while reaffirming Islamabad’s commitment to IMF-backed reforms.
The statement came during Sharif’s meeting with International Monetary Fund Managing Director Kristalina Georgieva on the sidelines of the 81st United Nations General Assembly in New York.
The discussion comes at an important point for Pakistan’s economy. After a period dominated by efforts to restore fiscal and external stability, the government’s focus is increasingly shifting toward investment, productivity, exports and longer-term economic growth.

6
PM Shehbaz Sharif Reaffirms Pakistan’s Reform Commitment
According to the government and Radio Pakistan, Sharif told Georgieva that Pakistan was progressing from macroeconomic stabilization toward economic recovery despite regional conflict and external inflationary pressures.
The prime minister pointed to improvements in fiscal discipline, external buffers and investor confidence, while highlighting the National Tariff Regime, domestic revenue mobilization and privatization as important elements of the reform agenda.
Sharif also reiterated that Pakistan intends to remain committed to the IMF-supported reform program.
That commitment matters because the country’s recent economic stabilization has been closely connected to the IMF program and the government’s efforts to meet fiscal and structural targets.
IMF Says Stabilization Efforts Are Producing Results
The IMF’s own assessment provides important context to the government’s claims.
In its May 2026 review, the Fund said strong policy implementation had helped maintain economic stability and improve financing and external conditions. The IMF also approved approximately $1.1 billion under the Extended Fund Facility and about $220 million under the Resilience and Sustainability Facility, taking total disbursements under the two arrangements to about $4.8 billion.
The Fund identified several continuing priorities, including:
- strengthening public finances;
- broadening the tax base;
- improving competition and productivity;
- reforming state-owned enterprises;
- improving energy-sector viability;
- strengthening social protection;
- rebuilding foreign-exchange reserves; and
- improving public-service delivery.
This means Pakistan’s transition to recovery is not simply a question of higher GDP growth. The next phase depends heavily on whether stabilization measures can be converted into sustained productivity, investment and private-sector growth.
Pakistan’s Growth Has Improved, but the Recovery Remains Vulnerable
Pakistan recorded 3.7% GDP growth in FY2026, according to figures cited by the Finance Ministry and the Asian Development Bank. The ADB’s July 2026 outlook also puts Pakistan’s growth forecast at 3.7% for 2026 and 2027.
The ADB, however, has highlighted significant risks surrounding the outlook.
Its July forecast said Pakistan’s 2026 growth was being supported by the recovery in economic activity, but higher energy costs and pressure related to the Middle East conflict represented important downside risks. The ADB projects Pakistan’s inflation at 7.2% in 2026 and 8.3% in 2027.
That distinction is important.
Stabilization does not automatically mean a broad-based economic recovery. Pakistan still needs stronger investment, productivity and export performance to generate durable growth.
What Has Changed in Pakistan’s Economy?
Pakistan’s recent economic story has involved a combination of fiscal consolidation, monetary discipline, external financing and structural reforms.
The IMF reported that Pakistan’s reserves had increased, while fiscal performance remained strong. Its assessment also noted that the country’s economic recovery had gained momentum, although the Middle East conflict had complicated the near-term outlook.
The government’s current economic strategy is therefore moving beyond simply preventing another balance-of-payments crisis.
Finance Minister Muhammad Aurangzeb recently described the next stage as a move toward investment, capital formation, exports and private-sector-led growth. The government has identified macroeconomic stability, structural reforms, investment, exports and improved access to finance among its key priorities.
Why the IMF Review Matters
The upcoming IMF review is one of the most important tests for Pakistan’s reform program.
The IMF-supported Extended Fund Facility was approved in September 2024 and is designed to strengthen macroeconomic resilience while creating conditions for sustainable growth. The program includes fiscal reforms, reserve accumulation, tax-base expansion, SOE restructuring, energy-sector reforms and measures to improve competitiveness.
The forthcoming review will therefore provide an important assessment of whether Pakistan is continuing to meet the commitments associated with the program.
For financial markets and investors, successful implementation can influence perceptions of Pakistan’s external financing position and policy credibility. For households and businesses, however, the more important question is whether stabilization eventually translates into lower economic volatility, stronger investment and sustainable job creation.
Tariff and Revenue Reforms Could Reshape the Business Environment
The government’s National Tariff Regime is another significant component of the reform agenda.
The IMF’s latest Pakistan documentation says authorities are working to reduce tariffs and simplify non-tariff barriers while also pursuing broader regulatory reforms intended to reduce uncertainty and transaction costs for businesses.
The reform agenda also includes changes involving special economic zones and other fiscal incentives.
The objective is to gradually move away from policies that create distortions and toward a more competitive environment in which investment decisions depend more heavily on productivity and market conditions.
Privatization Remains Another Major Test
Privatization is also central to Pakistan’s structural-reform agenda.
The IMF has noted progress on the privatization agenda, including the agreement involving Pakistan International Airlines, while identifying additional SOE and electricity-distribution reforms as part of the broader program.
The government’s challenge will be to demonstrate that privatization and restructuring produce lasting improvements in efficiency rather than simply short-term fiscal relief.
External Financing Remains a Key Vulnerability
Pakistan’s recovery is also taking place against a complicated external backdrop.
Reuters reported in September that Pakistan was seeking an expansion of its 30 billion yuan currency swap arrangement with China when it comes up for renewal in 2027. Finance Minister Muhammad Aurangzeb also said Islamabad was awaiting a US decision concerning a proposed exchange-stabilization facility.
The report underscores an important reality: even as Pakistan’s macroeconomic indicators improve, the country continues to depend on external financing and bilateral and multilateral support to maintain reserves and meet debt obligations.
That makes continued reform implementation particularly important.
Energy Prices Could Complicate the Recovery
Higher energy costs represent another major challenge.
Reuters reported that Pakistan introduced austerity measures in September as rising fuel prices associated with the Gulf conflict increased pressure on the country’s economy. The measures included restrictions on official fuel use, government vehicle purchases and certain official expenditures.
The ADB has similarly warned that higher energy prices could increase inflationary pressure and weaken growth across the region, with Pakistan particularly exposed because of its external energy requirements.
This creates a difficult policy balance: authorities need to preserve fiscal and external stability while preventing higher energy costs from disproportionately affecting households and businesses.
What the Recovery Phase Means for Pakistan
The phrase “from stabilization to recovery” describes a shift in economic priorities.
The stabilization phase focused heavily on preventing external financing crises, controlling inflationary pressures, improving fiscal discipline and rebuilding reserves.
The recovery phase requires something broader:
more private investment + higher productivity + stronger exports + sustainable public finances + structural reform.
The ADB’s 2026–2030 country strategy for Pakistan similarly emphasizes private-sector development, inclusion, resilience and sustainability as key pathways toward longer-term growth.
That suggests the next stage of Pakistan’s economic story will be judged less by emergency stabilization and more by whether the country can turn improved macroeconomic conditions into sustained productive activity.
The Road Ahead
Pakistan has made measurable progress in restoring macroeconomic stability, and international institutions have acknowledged improvements in several areas.
But the economic recovery remains exposed to external shocks, particularly energy prices, geopolitical disruptions, financing conditions and inflation.
The government’s commitment to continued reforms therefore faces a critical test: whether stabilization can be maintained while investment, productivity, exports and private-sector activity expand.
For now, the latest meeting between Shehbaz Sharif and Kristalina Georgieva reinforces the government’s stated intention to remain on the reform path. The IMF review and the implementation of structural measures will provide more concrete evidence of how successfully Pakistan can turn stabilization into sustainable growth.
Key facts at a glance
| Indicator | Latest available information |
|---|---|
| FY2026 GDP growth | 3.7% |
| ADB 2026 Pakistan growth forecast | 3.7% |
| ADB 2027 Pakistan growth forecast | 3.7% |
| ADB 2026 inflation forecast | 7.2% |
| ADB 2027 inflation forecast | 8.3% |
| IMF EFF | 37-month program approved Sept. 2024 |
| IMF/RSF disbursements reported May 2026 | About $4.8 billion combined |
| Major reform areas | Taxation, SOEs, energy, tariffs, competition, reserves |
Sources:IMF
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The IMF’s July 2026 update projects global growth of 3.0% for 2026 and 3.4% for 2027 — a modest slowdown from the 3.5% average of 2024–25, driven by the economic drag of the Middle East conflict being partly offset by an accelerating AI-driven technology cycle. In short: the world economy is being carried by one trade, and it is concentrated in a handful of companies.
That single sentence captures the defining tension of the 2026 economy. Two forces are pulling in opposite directions, and which one wins will determine whether this is remembered as the year markets shrugged off geopolitical risk, or the year they didn’t see the correction coming.
The IMF’s Divergent World
According to the IMF’s World Economic Outlook Update, the growth slowdown is not evenly distributed. Economies deeply integrated into the AI and technology value chain — chiefly the United States and parts of Asia — are absorbing the benefits of the technology boom, while energy-importing and conflict-adjacent economies are absorbing most of the damage. That divergence has been the throughline of every IMF release this year: the April 2026 edition, published as the Middle East conflict first erupted, had cut its forecast to 3.1% for 2026 under a “reference forecast” that assumed the war would stay limited in scope and duration, while warning that a longer or broader conflict — or a reassessment of AI-driven productivity expectations — could meaningfully weaken growth.
For content targeting “IMF reports” and “world economy” search intent, the practical takeaway is this: growth forecasts have been revised four times in twelve months, each revision hinging on two swing factors — the war’s duration and the durability of the AI capital-spending cycle. Anyone publishing on this topic needs to track both, because either one turning could flip the entire growth story.
Wall Street’s AI Concentration Problem
Featured Snippet Target: Three companies — Alphabet, Amazon, and Meta — are now expected to drive roughly 70% of the S&P 500’s 2026 earnings growth, according to Charles Schwab’s market analysis, with combined 2026 capital expenditure guidance exceeding $500 billion. That concentration means the index’s headline diversification is largely cosmetic; its performance now rides on whether a handful of hyperscalers convert AI spending into earnings.
This is the risk hiding inside every “stock market today” headline. Reuters reported the S&P 500 climbing to a record high in early January 2026, powered by gains in Nvidia and Alphabet, with one Tulsa-based fund manager summing up the prevailing mood as a repeat of the prior year’s approach — buy the AI leaders and hold. Since then, hyperscaler capital spending has only accelerated: Alphabet, Amazon, and Microsoft each posted capex increases of well over 25% year-on-year in recent quarters, and combined hyperscaler AI spending commitments for 2026 have topped $700 billion, according to reporting relayed through Yahoo Finance’s technology coverage.
That spending is no longer being funded purely out of free cash flow. A growing share is debt-financed — Macquarie’s Investment Strategy Insights noted that consensus hyperscaler capex estimates for FY26–FY28 were revised up from roughly $2.5 trillion to $2.8 trillion during the reporting season, with gross debt issuance expected to peak near $460 billion in FY28, or about a third of total capex. Analysts have started describing this shift as a change in market character altogether — a move from an era where buybacks reliably supported share prices to one where capital expenditure, not shareholder returns, is what the market rewards.
That has two implications for markets content this year. First, market concentration has hit levels not seen since the dot-com era — roughly two dozen stocks now account for over half of the S&P 500’s total value, which is a comparable concentration level to the 32-stock peak reached during the 2000 bubble. Second, volatility has already started creeping back in: CNBC flagged in mid-September that bond yields were spiking and AI-linked names were selling off even as broader investor sentiment stayed constructive on equities — a split market where the AI trade and the rest of Wall Street are no longer moving in lockstep.
Why the Divergence Matters for Every Asset Class
The IMF’s macro divergence and Wall Street’s AI concentration are, in effect, the same story told twice — a bet on a narrow slice of the global economy carrying the rest. Energy importers and low-income developing economies are absorbing the geopolitical shock the IMF describes, just as the “average” S&P 500 stock is absorbing less of the earnings growth than the concentration numbers suggest. Both dynamics raise the same underlying question for 2026 planning: what happens to growth, and to equity valuations, if either pillar — the ceasefire holding, or hyperscaler capex converting into real earnings — gives way.
For now, neither has. The IMF’s reference forecast still assumes the conflict stays contained, and hyperscaler earnings, so far, have largely met or beaten the market’s demanding bar: Alphabet’s April quarter, for instance, saw earnings per share and Google Cloud growth both come in well ahead of consensus. But both are assumptions, not certainties, and the 2026 economy is being priced as though they will hold indefinitely.
The Bottom Line
Global growth of 3.0% sounds unremarkable in isolation. What makes 2026 distinctive is how much of that growth — and how much of the corresponding equity market gains — is concentrated in AI infrastructure spending by a small number of companies and countries. Investors, policymakers, and anyone allocating capital this year need to treat the AI capex cycle not as a side story to the macro picture, but as the macro picture’s main engine.
Next step: Track the IMF’s next World Economic Outlook update alongside hyperscaler earnings season — the two releases, taken together, are now the single best gauge of where the 2026 global economy is actually heading.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The International Monetary Fund has revised its view of the world economy three times in nine months, and the direction of travel is clear.
Global growth is now projected at 3.0% for 2026 and 3.4% for 2027 — down from the 3.5% average recorded across 2024–25.
The headline number, though, is the least interesting part of the report. What matters is why the Fund revised, and which economies it thinks will absorb the damage.
Key Takeaways
- The July 2026 forecast: 3.0% growth in 2026, 3.4% in 2027, broadly unchanged cumulatively from April.
- Two opposing forces. The Middle East war drags; the AI-driven technology cycle lifts.
- The split is not rich versus poor. It is energy exposure and position in the technology value chain.
- Inflation reversed course. The Fund projected headline inflation rising to 4.4% in its April assessment.
- Risks remain tilted downside. Longer conflict, AI expectation resets and fragmentation dominate the risk register.
The Forecast Trajectory Through 2026
| Report | 2026 Growth | 2027 Growth | Framing |
|---|---|---|---|
| October 2025 WEO | ~3.2% | 3.2% | Steady resilience |
| January 2026 Update | 3.3% | 3.2% | Revised slightly up |
| April 2026 WEO | 3.1% | 3.2% | “Reference forecast” under war |
| July 2026 Update | 3.0% | 3.4% | War drag vs AI lift |
Read as a sequence, this tells a story that a single data point cannot. January was optimistic: the Fund saw technology investment, fiscal and monetary support and accommodative financial conditions offsetting trade policy shifts.
Then war broke out.
April: The Reference Forecast
The April 2026 WEO abandoned the traditional baseline entirely. It presented instead a reference forecast predicated on the assumption that the war would have limited duration, intensity and scope, with disruptions fading by mid-2026, consistent with commodity futures prices as of 10 March.
That is an unusual methodological choice and worth understanding. The Fund was explicitly saying: we cannot forecast this, so here is a conditional projection plus scenarios.
Chief Economist Pierre-Olivier Gourinchas framed the reversal directly: the global economy had been on a steady trajectory around 3.3% and the Fund was looking to upgrade its projections before the war stopped that momentum, with inflation rising to 4.4%.
He identified three transmission channels: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock.
The adverse scenario modelled oil prices rising 80% and gas prices 160% from the second quarter of 2026 relative to January assumptions.
July: The AI Offset
The July Update introduced the year’s most important analytical point. The modest slowdown reflects the effects of the Middle East war being partly offset by accelerated demand-driven momentum in the global technology cycle, thanks to advances in artificial intelligence and its adoption.
Critically, the impact varies by two dimensions at once:
- Energy exporters outside the conflict zone benefit from favourable terms of trade.
- Economies plugged into the technology-led upturn experience stronger activity even if they are energy importers.
- Energy importers with limited participation in the technology value chain see activity weaken.
That third category is where the damage concentrates. It captures much of South Asia, Sub-Saharan Africa and parts of Latin America — economies paying more for energy without the AI export revenues to offset it.
This is the single most actionable framework in the 2026 IMF reporting. It explains why Japan and Korea have outperformed while frontier importers have stalled.
What the Reports Say About Major Economies
The January Update projected advanced economy growth of 1.8% in 2026 and 1.7% in 2027, with the United States expanding 2.4% in 2026 supported by fiscal policy and a lower policy rate, before settling at 2.0% in 2027 with a near-term boost from corporate investment tax incentives.
On inflation dynamics, the Fund noted inflation in China rising from low levels, while inflation in India was expected to return to near-target levels after a 2025 decline driven by subdued food prices.
Russia was projected to maintain growth of 1.1%.
Why Investors Should Read IMF Reports Differently
Most market participants treat the WEO as a headline number. Three better uses:
- The revision direction beats the level. A forecast cut from 3.3% to 3.0% tells you more about policy trajectory than the absolute figure does.
- The scenarios are the real content. The April adverse scenario’s 80% oil assumption is a stress test you can apply to your own portfolio.
- The country tables are underused. Annex Table 1’s selected-economy real GDP growth figures cover economies accounting for approximately 83% of world output.
How the IMF and World Bank Differ
The two institutions use different methodologies and produce different numbers for the same year. The IMF projects 3.0% global growth for 2026 on purchasing-power-parity weights. The World Bank projects 2.5% using market exchange rate weights.
Neither is wrong. PPP weighting gives more weight to faster-growing emerging economies. Market-rate weighting reflects actual dollar-denominated output. Quote the one that matches your analytical frame — and never compare the two headline figures directly.
Risks the Fund Flags
- Longer or broader conflict. The reference forecast assumes containment. It is an assumption, not a projection.
- AI expectation reset. A reassessment of expectations surrounding AI-driven productivity could significantly weaken growth and destabilise financial markets.
- Geoeconomic fragmentation. Trade and technology bloc formation raises costs structurally.
- Elevated public debt. Combined with eroding institutional credibility, this heightens vulnerabilities.
- Defence spending trade-offs. The Fund specifically warns policies must carefully manage the trade-offs involved in ramping up defence expenditure.
What This Means for the Global Market in 2027
3.4% in 2027 is a recovery forecast, not a boom. It sits well below the 2000–19 historical average of 3.7%, and the Fund expects growth to settle near that lower rate in the medium term.
The AI offset is a concentrated bet. If the technology cycle disappoints, there is no second offsetting force in the model. The war drag remains; the lift disappears.
Inflation persistence is the policy trap. Rising headline inflation alongside slowing growth limits how far central banks can cut, which in turn limits the equity valuation support markets have priced.
Energy-importing frontier economies face a structural squeeze. Pakistan, Bangladesh, Sri Lanka, Kenya and similar economies sit precisely in the Fund’s worst-affected category.
Watch the October 2026 WEO. It will be the first full report to assess whether the war disruptions actually faded on the assumed timeline. If they did not, the reference forecast framework collapses and forecasts move materially lower.
Frequently Asked Questions
What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, down from the 3.5% average recorded in 2024–25.
Why did the IMF cut its 2026 forecast?
The Middle East war raised energy prices and inflation while denting confidence. This drag is only partly offset by AI-driven demand in the global technology cycle.
How often does the IMF publish the World Economic Outlook?
Twice yearly as full reports (April and October), with shorter Updates in January and July.
Do the IMF and World Bank forecasts agree?
They differ by methodology. The IMF’s 3.0% for 2026 uses PPP weights; the World Bank’s 2.5% uses market exchange rates. The two headline numbers are not directly comparable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
IMF sees 3.0% global growth in 2026, the World Bank just 2.5%. Compare Europe and Asia forecasts, the gap between them, and what it means for capital.
Executive Summary / Key Takeaways
- The IMF’s July 2026 World Economic Outlook Update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average of 2024–25.
- The World Bank’s June 2026 Global Economic Prospects is far darker: 2.5% in 2026, the weakest since the pandemic, with two-thirds of economies downgraded since January.
- The two institutions are not contradicting each other — they use different weighting methodologies — but the direction of both revisions is the same, and the driver is the Middle East war.
- Europe and Central Asia was cut to 2.1% for 2026; East Asia and Pacific to 4.2%. The Middle East, North Africa, Afghanistan and Pakistan region takes the worst hit at 1.6%.
- The divergence that matters for allocators is not regional but structural: economies plugged into the AI-led technology cycle are outperforming energy importers that are not.
1. Introduction & Immediate Context
Two flagship forecasts, two very different headline numbers, one identical story underneath. Anyone building a 2027 capital plan needs to understand why.
The IMF’s July update projects global growth of 3.0% in 2026 and 3.4% in 2027, down from the 3.5% average observed across 2024–25 and broadly unchanged on a cumulative basis from the April 2026 World Economic Outlook. The Fund attributes the modest slowdown to the effects of the war in the Middle East, partly offset by accelerated demand-driven momentum in the global technology cycle thanks to advances in artificial intelligence and its adoption.
The World Bank is blunter. It forecasts global growth slowing to 2.5% in 2026 from 2.9% in 2025 — the lowest rate since the onset of the COVID-19 pandemic — amid higher energy prices, steeper inflation and increased borrowing costs. Forecasts for two-thirds of economies were downgraded relative to January. Growth is expected to improve to 2.8% in 2027 but will remain 0.4 percentage point below the 2010s average.
The gap between 3.0% and 2.5% is largely methodological: the IMF aggregates at purchasing-power-parity weights, the World Bank at market exchange rates, which gives slower-growing advanced economies more influence. Read the revisions, not the levels.
2. Core Market / Strategic Analysis
2.1 Regional forecasts side by side
| Region | World Bank 2026 | World Bank 2027 | Revision direction | Source |
|---|---|---|---|---|
| World | 2.5% | 2.8% | Cut from 2.6% (Jan) | World Bank |
| East Asia & Pacific | 4.2% | 4.4% | Cut from 4.4% (Jan) | World Bank |
| Europe & Central Asia | 2.1% | 2.3% | Cut from 2.4% (Jan) | World Bank |
| South Asia | 6.3% | 6.9% | Fastest-growing region | World Bank |
| MENA, Afghanistan & Pakistan | 1.6% | 5.0% | Cut from 3.6% (Jan) | World Bank |
| Sub-Saharan Africa | 4.0% | 4.4% | Marginal easing | World Bank |
| Low-income countries | 5.4% | — | Cut 0.3pp on the conflict | World Bank |
The MENAAP line is the single most violent revision in the dataset: from 3.6% to 1.6% for 2026 in five months, followed by a mechanical 5.0% rebound in 2027 as base effects and assumed energy normalisation kick in. For frontier-market investors with Pakistan or Gulf exposure, that V-shape is the entire investment thesis — and it rests on an assumption about how long the conflict lasts.
2.2 The European picture
Growth in Europe and Central Asia is projected to decelerate to 2.1% in 2026, weakening in roughly 70% of economies in the region, according to the World Bank’s regional highlights. Domestic demand remains the primary driver but is constrained in 2026 by elevated energy prices, which raise inflation and erode real incomes, and by tighter financial conditions.
Commodity exporters in the region — Azerbaijan, Kazakhstan and Turkmenistan among them — see export revenues supported by higher energy prices even as growth slows. In Russia, the World Bank estimates oil revenue gains at roughly 1.5% of 2025 GDP for each $10 per barrel increase in prices, with those gains mainly directed toward fiscal consolidation.
The euro area itself sits at the sluggish end. The IMF’s January 2026 update had projected euro-area growth steady at 1.3% in 2026 and 1.4% in 2027, noting that the region benefits less than others from the technology-driven investment boost and that lingering energy-price effects continue to drag on manufacturing. Planned defence spending increases are expected to show up in output only in later years given phased commitments running to 2035.
2.3 The Asian picture
East Asia and Pacific is projected to fall to 4.2% in 2026 before firming to 4.4% in 2027 — a downgrade, but still comfortably the second-fastest-growing region. South Asia leads globally at 6.3% in 2026 and 6.9% in 2027.
The IMF’s framing explains why Asia holds up better than Europe: economies plugged into the technology-led upturn experience stronger activity even when they are energy importers, while activity weakens for energy importers with limited participation in that cycle. Energy exporters outside the conflict zone benefit from favourable terms of trade.
3. Structural Drivers and Competitor Gaps
Most coverage treats these as two competing headline numbers. The more useful read is that both institutions have converged on the same three-channel transmission mechanism, articulated by IMF Chief Economist Pierre-Olivier Gourinchas when the April outlook was released: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock. The Fund noted at the time that the global economy had been on a roughly 3.3% trajectory and was heading for an upgrade before the war stopped that momentum, with inflation instead rising toward 4.4%.
Three structural points follow that competitors miss:
The dispersion is the story. The April WEO recorded a cumulative growth revision of nearly three percentage points for 2026 in the Middle East and North Africa, against comparatively modest effects in advanced economies. A single global number conceals a distribution this wide.
The 2027 rebound is conditional, not forecast. The World Bank’s recoveries across all regions in 2027–28 are driven by an assumed decline in energy prices and rebound in global activity. If Brent stays above $100, the rebound does not arrive on schedule.
AI is now a macro line item, not a sector story. Both institutions explicitly cite broader AI adoption as an upside risk offsetting the energy shock. That reframes technology capital expenditure as a national growth input, which is why Singapore, Malaysia and Taiwan are outperforming regional peers with similar energy exposure.
4. Key Implications for Stakeholders
Macro allocators. The IMF–World Bank spread is not noise to be averaged away; it is a signal about where you sit in the distribution. Market-weight exposure to advanced economies should be benchmarked against the World Bank’s 2.5%, not the IMF’s 3.0%.
Corporate strategists. Fiscal pressure is the binding constraint in developing markets. The World Bank flags that fiscal pressures will affect the ability to reduce poverty and food insecurity and to create jobs — which translates into weaker public procurement and slower infrastructure pipelines across frontier markets through 2027.
Frontier and EM investors. Emerging market and developing economies face their weakest per capita income growth since the pandemic. Pair that with the MENAAP downgrade and the case for selectivity over beta exposure is straightforward.
Watch the October calendar. The IMF’s next full World Economic Outlook lands with the Annual Meetings. Given the energy trajectory since July, the risk to the 3.0% figure is to the downside.
5. Frequently Asked Questions
Q1: What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, per its July 2026 World Economic Outlook Update — down from the 3.5% average recorded across 2024–25, with the Middle East war the principal drag.
Q2: Why does the World Bank forecast lower growth than the IMF?
The World Bank aggregates using market exchange rates while the IMF uses purchasing-power-parity weights, giving slower-growing advanced economies more influence in the World Bank’s 2.5% figure. Both revised downward for the same reasons.
Q3: Which region is growing fastest in 2026?
South Asia, at a projected 6.3% in 2026 rising to 6.9% in 2027, according to the World Bank. East Asia and Pacific follows at 4.2%.
Q4: How badly has the Middle East conflict hit growth forecasts?
The World Bank cut its MENA, Afghanistan and Pakistan forecast from 3.6% to 1.6% for 2026, and downgraded two-thirds of all economies since January. Global growth is now at its weakest since the pandemic.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Pakistan Moves From Stabilization to Recovery as IMF Review Puts Reform Momentum in Focus

Mesothelioma Attorney: How to Choose the Right Lawyer to Maximize Your 2026 Asbestos Settlement

SpaceX IPO 2026: History’s Biggest Stock Debut?

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Is AI a Stock Bubble in 2026? What the Data Shows

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Gold Price 2026: Inside the Wildest Rally in Decades

Federal Reserve 2026: Inside Kevin Warsh’s First Year

Fox Corp 2026: Record Revenue, Tubi Growth & Roku Deal

Wendy’s Stock 2026: Inside the Turnaround Plan

Technology News 2026: Inside the $1.3T AI Chip Boom

UK Stocks 2026: Inside the FTSE 100’s Record Run

Asian Stock Markets 2026: Japan, China, Pakistan & More

Mortgage Rates Today 2026: Full Rate Guide & Forecast

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

Leveraging Viral AI & Climate Hashtags for Brand Growth on X
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025