
Analysis
Trading in the Year of Geopolitics: Why Asian Markets Demand a Nuanced Strategy in 2026

How Asian investors can navigate the geopolitical impact on Asian markets without falling into the twin traps of complacency and panic — and why pricing geopolitical risk in 2026 demands a fundamentally different toolkit
The Fire Horse Meets the Year of Geopolitics
In the Chinese zodiac, 2026 belongs to the Fire Horse — a symbol of restless, combustible energy. Driven, brilliant, and unpredictably volatile, the Fire Horse is considered one of the most dramatic animals in the Chinese astrological cycle. In certain East Asian traditions, years bearing its mark are ones in which conventional wisdom gets upended and fortune favors those who move decisively rather than hesitantly.
For investors operating across Asian markets this year, that ancient metaphor has collided head-on with a grimmer, more modern label: the Year of Geopolitics.
It is a label earned in full. Consider the dizzying catalogue of risk events that greeted markets before the calendar had even turned to February. On January 3rd, US forces captured Venezuelan President Nicolás Maduro — barely three days into the new year — in an intervention that Lombard Odier’s strategists immediately flagged as a return of sphere of influence logic to geopolitics, with the operation mirroring the US intervention in Panama in 1989 and the arrest of Manuel Noriega. MarketPulse Within weeks, President Trump announced 10% tariffs on eight NATO allies, ostensibly tied to US demands over Greenland — a move that, according to Lombard Odier’s analysis, drove geopolitical risk premia higher, led by gold, though broader impacts were expected to stay contained unless tensions intensified. J.P. Morgan
Meanwhile, US military assets have been repositioned in the Gulf, pressuring Iran toward nuclear negotiations, with Lombard Odier warning that oil markets are a key transmission channel for geopolitical risks, and any Iranian action in the Strait of Hormuz would be a high-risk, high-cost option — but one that cannot be ruled out. Allianz Global Investors And as if a crowded geopolitical stage needed more actors, the independence of the US Federal Reserve has come into question, with Jerome Powell’s term ending in May and President Trump’s preference for a loyalist replacement threatening what markets once considered an institutional certainty.

Layering all of this is the ongoing shadow of Trump’s trade tariffs — tools whose legal foundations remain contested in the Supreme Court — and a tech decoupling between Washington and Beijing that has moved from rhetorical sparring to operational architecture.
The central question for Asian investors is not whether these risks are real. They are, spectacularly so. The question is: how should you price geopolitical risk in a world where economic growth remains remarkably resilient? Do you sell? Discount? Simply watch the headlines and hold firm? As we will argue, the answer is none of the above in isolation. What this moment demands — particularly for investors with Asian portfolio exposure — is analytical nuance, not instinct.
Loud Headlines, Quiet Markets — and Why That Pattern Can Deceive
There is a seductive and well-documented pattern in modern financial history: geopolitical events tend to produce sharp, short-lived volatility spikes, followed by recoveries that leave investors wondering what all the fuss was about. Geopolitical events tend to have only a temporary impact on markets as long as they have no lasting effect on oil prices or permanently disrupt global supply chains. BlackRock
This has been the dominant experience of the past several years. From Middle Eastern flare-ups to the initial phases of the Russia-Ukraine war, from North Korean missile tests to US-China semiconductor skirmishes, markets have repeatedly absorbed the shock, processed the information, and moved on — often within days. The global economy has shown surprising resilience. Despite the tax burdens and protectionist policies of the Trump administration, markets have grown accustomed to the rhythm of confrontation and compromise — particularly in the ongoing dynamic between President Trump and his global counterparts. Asia House
The clearest stress-test of this pattern came in April 2025 with “Liberation Day” — the Trump administration’s sweeping tariff announcement. Volatility spiked violently, and supply-chain-exposed stocks across Taiwan, South Korea, Vietnam, and Malaysia sold off hard. After Liberation Day, markets panicked. The dollar fell as volatility spiked — the opposite of its usual safe-haven behavior. Reserve managers sharply shifted allocations away from dollars; the greenback’s share of global reserves hit its lowest in two decades. Pundits rushed to declare American exceptionalism dead. Lombard Odier And yet, by the year’s end, a partial trade détente had been negotiated, and foreign investors had bought more US assets than in the prior year.
Despite fading market shocks, ongoing geopolitical tensions and elevated gold volatility signal that concerns about global risks may linger in 2026, as State Street’s Head of Macro Policy Research Elliot Hentov noted. Trade continues to grow despite trade wars — but deals are being closed only gradually, and uncertainty has not fully dissipated. BlackRock
The danger for investors lies in a subtle but crucial category error: confusing market recovery with market immunity. Geopolitical risks are often priced heuristically. Their uncertain duration, scope, and low frequency make them difficult to quantify in advance. In the meantime, their tail-risk nature — as relatively rare but potentially extreme occurrences — means they are underpriced until they materialise. J.P. Morgan Private Bank Put differently: the fact that a crisis passed without lasting damage does not mean the next one will. And for Asian investors, the structural transmission channels are uniquely numerous and direct.

BlackRock’s Geopolitical Risk Dashboard tracks a “market movement score” for each risk — measuring the degree to which asset prices have moved similarly to risk scenarios. The current environment reflects the US resetting of trade deals and alliances, intensifying US-China competition with AI at its core, and continued volatility from conflicts in Ukraine, Gaza, and the Caribbean. Allianz Global Investors The dashboard makes plain that market attention and market movement are two different things — and that the gap between them is where complacency breeds.
Asia’s Unique Position — Why Nuance Is Not Optional
Asia is not a spectator in the Year of Geopolitics. It is one of its primary stages. The region encompasses the world’s most consequential bilateral rivalry (US-China), the most contested maritime geography (the Taiwan Strait and South China Sea), the most trade-exposed economies in the developed world, and the most energy-import-dependent major markets on the planet. For Asian investors, the transmission channels for geopolitical shocks are not theoretical — they flow directly into earnings, currencies, bond yields, and capital flows.
The bilateral relationship between Washington and Beijing remains the most important indicator of geopolitical tensions to gauge in 2026 and for years to come. Long-term strategic decoupling is highly likely to continue amid growing great-power competition, especially in emerging technologies and defense. While there may be increased stability prior to an anticipated summit between Xi Jinping and Donald Trump, the underlying dynamic of technology and supply-chain competition is structural rather than episodic. SpecialEurasia
Several specific vulnerability channels demand attention:
Export dependency. South Korea, Taiwan, Malaysia, Singapore, and Vietnam are among the world’s most trade-reliant economies. Any durable deterioration in global trade flows hits their corporate earnings faster and harder than in more domestically insulated markets. China’s export machine continues to defy geopolitical headwinds, showing robust growth even as protectionist policies proliferate globally — yet the structural supply-demand imbalance will require years to resolve, and more time is needed for recent anti-involution policy measures to have a meaningful impact on the real economy. Pinebridge
Energy import vulnerability. Around one-third of the world’s seaborne crude oil flows through the Strait of Hormuz, which is also key for transporting liquefied natural gas, fertilisers, copper, and aluminium. Allianz Global Investors Japan and South Korea, as near-total energy importers, face the most direct exposure to any supply disruption emanating from Middle Eastern conflict.
Technology decoupling. Despite a trade detente with China, the military posture in Asia hasn’t softened. Washington sent Taipei its largest-ever arms sale package, and Beijing continues to assert its Taiwan position. Lombard Odier Meanwhile, China’s ambition to triple domestic semiconductor production by 2026 is reshaping investment flows across the electronics supply chain from Penang to Shenzhen.
Currency fragility. The Chinese yuan’s relative stability — maintained deliberately to preserve export competitiveness — acts as an anchor that constrains appreciation across the broader Asian currency complex. Dollar-yen is expected to breach 160 in 2026, with yen risks remaining key to the downside. Hartford Funds
Water and resource security. An often-overlooked vector of geopolitical risk in Asia is resource competition. The Indus Waters Treaty has been suspended. South Asian nuclear-armed rivals are turning rivers into leverage. The governance vacuum around shared water resources is deepening — and when the next shock comes, water will make it worse. Lombard Odier
Given these interlocking vulnerabilities, it should be clear why the standard market wisdom — “geopolitics rarely moves markets” — is an incomplete guide for Asian portfolios. Despite optimism about Asian equities in 2026, some challenges cannot be overlooked, including uncertain global demand, trade dynamics, and a volatile macro environment, all creating headwinds to medium-term potential growth. J.P. Morgan
The correct response, however, is not to flee risk entirely. Asia enters 2026 with genuine resilience and structural opportunity, driven by AI infrastructure investment, advanced manufacturing, and the green energy transition. The message for investors is clear: stay nimble, diversify beyond technology, and hedge strategically. Eurasia Group
The Lombard Odier Framework: How the Intelligent Allocator Approaches Geopolitical Risk
In managing clients’ money through successive geopolitical shocks over more than two centuries, Lombard Odier has developed what it calls the “Intelligent Allocator” framework — a discipline for separating analytical signal from emotional noise in volatile environments. Its core insight is worth absorbing in full.
The investor’s edge does not come from predicting events, but from understanding which outcomes are unaffordable. Rather than trying to anticipate geopolitical shocks, the goal is to build portfolios that can endure them through a robust strategic asset allocation. The idea is to understand the objectives of major economic actors, and more importantly the material constraints that limit those objectives — the hard physical, economic, and resource limits that bind policymakers regardless of ideology. J.P. Morgan Private Bank
This “material constraints” framework, developed by geopolitical strategist Marko Papic, is particularly illuminating in the context of US-China relations. At the February 2026 Lombard Odier “Rethink Perspectives” event in Paris, the firm’s chief strategists laid out the logic explicitly. The Americans possess what China needs — computing power — but China equally holds what the Americans require — rare earths. This symmetry is central to risk management. It sustains geopolitical tension, yet also reduces the probability of full decoupling, as the economic cost of a “pure” separation would be prohibitive. For markets, this translates into recurring cycles of political announcements, targeted restrictions, and industrial adaptation — in other words, volatility that is structural rather than episodic. Pinebridge
This insight directly challenges two equally mistaken responses: the first is to dismiss US-China tech tensions as noise that markets will look through; the second is to treat them as an existential rupture requiring wholesale portfolio defensiveness. The correct position is somewhere harder to hold: acknowledging the structural nature of the competition while maintaining exposure to the growth it generates.
On portfolio construction in this environment, Lombard Odier has been consistently clear since the start of the year. The key lesson from 2025 is to remain invested through the noise. Economies are still expanding, corporate growth is solid, policy offsets are in place, and the private sector is strong. While growth should slow through the year, stronger end-2025 momentum provides a higher buffer. Diversification is essential, with a preference for emerging markets, which offer higher earnings growth at a more reasonable price. Hartford Funds
On the Venezuela intervention specifically, Lombard Odier’s January analysis provided a useful template for how the framework operates in real time. The firm expected further spread compression in emerging bonds, precious metals outperforming due to a rise in the geopolitical risk premium, and a neutral view on the global energy sector — given both upside and downside risks to oil prices in the short term. MarketPulse This is the Intelligent Allocator in action: calibrated rather than reactive, nuanced rather than binary.
Real-Time Geopolitical Fault Lines: What Is Priced In and What Isn’t
Against this analytical backdrop, several specific 2026 geopolitical fault lines warrant close attention from Asian investors — both for the risks they present and, often, the opportunities embedded within them.
The US Political Revolution. According to the Eurasia Group’s Top Risks 2026 report, the United States is attempting to dismantle checks on presidential power and capture the machinery of government — making it the principal source of global risk in 2026. Lombard Odier As Eurasia Group founder Ian Bremmer put it: “The United States is itself unwinding its own global order. The world’s most powerful country is in the throes of a political revolution.” Lombard Odier For Asian markets, the implications ripple through trade policy, Federal Reserve independence, and the durability of US security commitments in the Indo-Pacific.
The Federal Reserve question is especially consequential. With Jerome Powell’s term ending in May 2026, the nomination process will be a market-moving spectacle. If a presidential loyalist is nominated, markets could price in a politicized, dovish Fed — producing a sharp equity rally and a sell-off in the dollar, with Senate confirmation hearings becoming the key volatility event of the spring. Societegenerale
The Electrons vs. Molecules Competition. China is betting on electrons — AI, advanced manufacturing, drones, batteries, and solar — while the United States is betting on molecules: energy, fossil fuels, critical minerals. 2026 will begin to reveal which bet is paying off. Lombard Odier The answer has significant implications for Asian supply chains. China tightens its grip on drones, battery storage, robots, and manufacturing, even as deflation clouds its domestic outlook with a quarter of all listed Chinese firms now unprofitable — the highest level in 25 years. Lombard Odier
The Supreme Court Tariff Ruling. Legal challenges to the administration’s reciprocal tariff executive orders are heading to the Supreme Court, with a ruling expected by June. If the Court strikes down the president’s authority to unilaterally set broad tariffs, the result could be a massive deflationary unwind and a rally in global trade proxies — shipping, emerging markets, and Asian export-oriented economies. Societegenerale The reverse scenario — Court upholding the tariffs — would entrench the current landscape of elevated trade friction.
Iran and Energy Risk. Lombard Odier’s February assessment concluded that the base case remains a negotiated outcome on US-Iran tensions, consistent with financial markets’ relative calmness. The VIX remained just below its long-term average, with no sign that risk premia were adjusting in anticipation of escalation. Allianz Global Investors But the tail risk remains real: a Strait of Hormuz disruption would function as a direct economic shock to virtually every energy-importing Asian economy.
Gray Zone Warfare Around Taiwan. Intelligence suggests China may be moving its timeline for “reunification readiness” forward. 2026 could see an increase in gray zone warfare — cyberattacks, blockades, and airspace incursions — that could trigger major repricing in risk assets and the US dollar. Any kinetic escalation around Taiwan would make 2025’s volatility look like a warm-up. Societegenerale Wellington Management’s geopolitical framework places this among the highest-consequence monitoring priorities for Asia-tilted portfolios.
China’s Deflation Trap. China enters 2026 with ten consecutive quarters of worsening deflation, personal consumption at just 39% of GDP — half the US share — and disposable income stalled at US$5,800 per person. Lombard Odier China’s export machine continues to defy geopolitical headwinds, showing robust growth. However, resolving the structural supply-demand imbalance will be a multi-year process. Pinebridge The irony is that Beijing’s response — accelerating exports — compounds competitive pressure on Asian neighbors even as it stabilizes Chinese growth.
Structural Beneficiaries: Vietnam, Malaysia, Indonesia. Not all of Asia’s geopolitical geography is risk. Vietnam has increasingly functioned as a “connector economy,” facilitating trade flows between the US and China. As corporates diversify production away from China, Vietnam has absorbed manufacturing activity tied to US end-demand while continuing to source intermediate inputs from China. Pinebridge Indonesia’s critical minerals position — particularly nickel for batteries and semiconductors — aligns directly with the AI-driven digital economy. These are genuine structural opportunities embedded within the geopolitical disruption.
Investment Strategies: Pricing Risk Without Being Paralyzed by It
What does a genuinely nuanced approach look like in practice? The following principles synthesize insights from across the major institutional frameworks operating in this environment.
Stay invested — but with eyes open. Despite its stellar performance in 2025, gold remains the most attractive portfolio hedge against market and geopolitical risks, with momentum from private inflows and central bank diversification expected to remain strong. As for the US dollar, renewed Fed easing and US policy uncertainty argue for sustained weakness and lower exposures. Hartford Funds The base case across major institutional investors entering 2026 is moderately pro-risk — not risk-off.
Use gold as a systematic hedge, not an emotional response. Adding gold in a sell-off makes sense given the multiple roles it can play as a hedge against geopolitical risk, stagflation, and US-dollar concerns. Stimson Center Lombard Odier advocates a gold allocation “of the order of 3–5%” as a line of portfolio defence when faced with extreme shocks — a structural position rather than a tactical reaction. Wellington Management The critical distinction is between owning gold before a crisis, when it is cheapest, versus scrambling to buy it after a spike.
Distinguish geopolitical categories. Geopolitical cycles are long — historically, they last between 80 and 100 years. Structural changes like those we’re witnessing now only come around once per century and tend to be disruptive. While market risk is structurally higher in this new regime, 2026 will afford ongoing and novel opportunities to seek portfolio winners and losers across defense technology, energy transition, and advanced manufacturing themes. SpecialEurasia
Diversify within Asia, not just out of it. Lombard Odier expects Swiss, Japanese, and emerging market equities to outperform. Within EM equities, more domestic-led markets such as China and India are expected to outperform more US-exposed markets such as Taiwan and Korea, which are more vulnerable to profit-taking when tariff tensions flare. J.P. Morgan
Watch sovereign bond dynamics for structural signals. Geopolitical shifts are reshaping global demand for government debt. As central banks diversify into gold, sovereign bonds may see higher domestic ownership and depend more on domestic demand — a structural shift that changes the diversification calculus for Asian fixed-income investors. State Street
Position for AI as a geopolitical theme, not merely a technology theme. A genuine transformation is underway, with the logic of efficiency and interdependence giving way to the logic of security. Security is replacing efficiency as the guiding principle of economic policy, prompting massive investment in energy, infrastructure, and industrial capacity — a shift that creates both risks and long-term opportunities for investors. Pinebridge In Asia, this means AI hardware infrastructure, semiconductor equipment makers, and advanced manufacturing platforms are not simply growth stocks — they are geopolitical position plays.
The comparison below illustrates how geopolitical risk transmission differs across key Asian markets:
| Market | Primary Risk Channel | Key Vulnerability | Structural Opportunity |
|---|---|---|---|
| Taiwan | Tech decoupling, Taiwan Strait | Semiconductor export controls | TSMC global supply chain dominance |
| South Korea | Trade tariffs, China slowdown | US-Korea trade tension | Defense tech, battery manufacturing |
| Japan | Yen weakness, energy costs | BoJ normalization pace | Governance reforms, fiscal stimulus |
| India | Tariff exposure (36% effective rate) | Energy import costs | Domestic demand, rate cutting cycle |
| Vietnam | China +1 beneficiary dynamics | US scrutiny of trade flows | Manufacturing connector economy |
| Indonesia | Critical minerals demand | Commodity price volatility | Nickel, AI infrastructure materials |
| China | Deflation trap, tech restrictions | Export overcapacity, property sector | Semiconductor self-sufficiency drive |
| Singapore | Financial hub volatility | Capital flow sensitivity | Digital economy, wealth management |
The Case for Active Management Over Passive Conviction
One underappreciated implication of the geopolitical environment is its structural favorability for active over passive investment management. This environment is naturally conducive to active management, which can seek to avoid increased market risks and capitalize on differentiation more nimbly than a passive approach. There may be alpha opportunities for long/short and other alternatives strategies that simply do not exist in a regime of smooth, globally coordinated growth. SpecialEurasia
Passive indices — particularly those heavily weighted toward Chinese or tech-dominant Asian benchmarks — embed specific geopolitical assumptions that may not reflect the rapidly evolving risk landscape. A passive Asia ex-Japan ETF, for example, carries significant Taiwan semiconductor and South Korean battery exposure, and limited hedging against the tail scenarios that both Wellington and Lombard Odier have flagged. Active management allows for the kind of within-region, within-sector rotation that a nuanced geopolitical view demands.
Geopolitical fragmentation does not lead to a generalised market retreat, but instead imposes a more detailed and refined hierarchy of risks, broken down by region and sector. It demands particular attention to sovereign balance sheets and microeconomic fundamentals. Wellington Management This is a world that rewards research depth and penalizes index-hugging.
The Intelligent Allocator’s Conclusion: Nuance Is the Strategy
The Fire Horse year demands that investors move: those who stand still, paralyzed by the sheer volume of geopolitical noise, risk being trampled by the opportunities passing them. Those who panic-sell risk exiting at precisely the moments when fundamentals argue for holding course. And those who are complacent — who assume that because markets have recovered from previous shocks, they will always recover quickly from the next — are building portfolios on a foundation that the Year of Geopolitics may not spare.
The geopolitical environment remains fraught with uncertainty. But markets have grown accustomed to the rhythm of confrontation and compromise. The balance of power, especially in trade and strategic resources like rare earths, has shifted. And yet, despite the tax burdens and protectionist policies of the Trump administration, the global economy has shown surprising resilience. Asia House
A moderate pace of economic growth, more accommodative monetary conditions, and a weaker dollar create fertile ground for risk assets, even as the fixed income outlook remains constrained. By seeking value opportunities, embracing emerging markets, and diversifying further through real assets, investors can position portfolios for resilience amid inevitable risks and potential shocks. Societegenerale
The analytical discipline that this moment demands is not exotic. It is, at its core, a commitment to asking a more precise question than either “should I be scared?” or “should I be calm?” The better question is: which specific outcomes are unaffordable for my portfolio, which geopolitical risks have economic transmission channels that could materialize those outcomes, and am I appropriately positioned to endure them while remaining exposed to the genuine growth that Asia’s structural story continues to offer?
That question, asked with rigor and answered with evidence rather than instinct, is the whole of the nuanced response. In the Year of Geopolitics, it may also be the difference between a good year and a great one.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


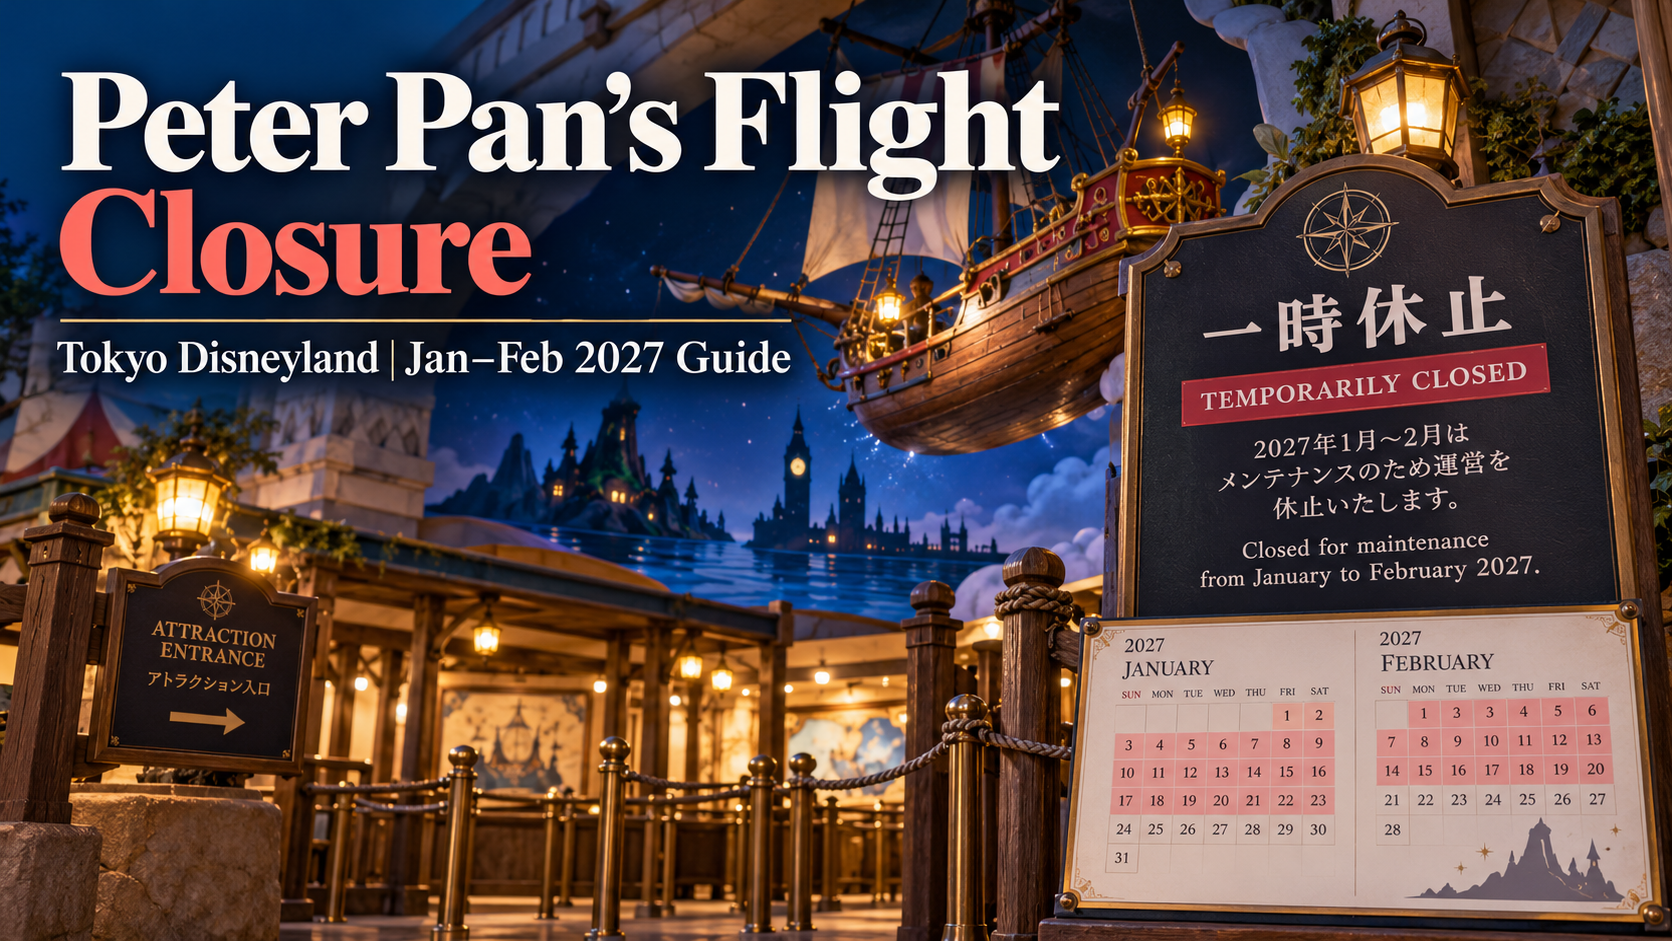
Guests planning a visit to Tokyo Disneyland in early 2027 should put one easily missed detail on their itinerary: Peter Pan’s Flight is scheduled to be temporarily closed from January 6 through February 2, 2027. The operator lists the dates both on its official attraction page and in the Tokyo Disneyland closure schedule. This is a scheduled interruption, not an announcement that the classic ride is being removed permanently. Travelers visiting on dates inside that window should assume the attraction will not be available unless Tokyo Disney Resort publishes a change.
The distinction matters because online references to “Peter Pan closing at Tokyo Disney” can confuse two different parks and two different experiences. Tokyo Disneyland’s Peter Pan’s Flight is a compact Fantasyland ride. Tokyo DisneySea has a separate, newer attraction called Peter Pan’s Never Land Adventure, with its own planned March 2027 maintenance period. The first planning step is making sure the information applies to the ticket you actually bought.
At a glance: what the operator currently says
| Planning question | Verified answer |
|---|---|
| Which attraction? | Peter Pan’s Flight |
| Which park? | Tokyo Disneyland, Fantasyland |
| Scheduled closure starts | January 6, 2027 |
| Scheduled closure ends | February 2, 2027 |
| Reopening expectation | After the listed closure window, subject to operator changes |
| Type of notice | Temporary closure; not announced as permanent |
| Where to recheck | Official attraction listing |
The dates are explicitly labeled as a temporary closure by Tokyo Disney Resort. Do not treat February 3 as an unconditional reopening guarantee: an operator may update maintenance information or temporarily suspend operations for other reasons. Check again shortly before travel and on the day you enter the park.
What is Peter Pan’s Flight?
Peter Pan’s Flight is a dark ride based on the familiar journey from London to Never Land. Guests sit in a flying pirate-ship vehicle that travels through a storybook environment. According to the operator’s ride information, it is in Fantasyland, lasts about two and a half minutes and carries two people per vehicle. It operates indoors and includes dark spaces. These details make it particularly appealing to families who want a gentle, classic Disney experience rather than a high-speed thrill ride.
There are restrictions worth noting even on operating days. The published guidance says a guest must be able to maintain a stable seated position independently and that children may not be held on an adult’s lap during the ride. If your group includes young children, anyone needing seating assistance or visitors uncomfortable with darkness, read the official description and accessibility guidance rather than assuming that the attraction suits everyone because it is short.
Short ride duration is not the same as short waiting time. Demand for well-known classics can vary with crowds, operating conditions and holiday schedules, so it is unwise to schedule a tight sequence of unrelated bookings around a predicted queue. The operator’s app and in-park staff can provide current operating information when the ride is available.
The dates around the closure are not interchangeable
A guest visiting January 5 has a fundamentally different planning position from someone arriving January 6. January 5 falls before the currently listed closure, while January 6 is its opening day. A February 2 visit falls on the final listed day of the maintenance window; February 3 is the earliest day after that window, not a contractual promise that the ride will run.
For a family staying at the resort for multiple days, the difference might be worth changing which day is assigned to Tokyo Disneyland. If one day is before January 6 and another is inside the closure, put Disneyland first if the classic Peter Pan ride is a must-do. But do not swap a park ticket or hotel reservation until you understand the applicable change and cancellation conditions. The economic cost of reshuffling an entire trip can exceed the benefit of experiencing one short ride.
A visitor traveling from overseas may be choosing between a single Disneyland day and a DisneySea day. In that case, consider the trip’s overall priorities. Someone who values vintage Fantasyland attractions may still prefer Disneyland even during the closure. Someone traveling expressly for an immersive Peter Pan adventure could be more interested in the DisneySea attraction—but must buy admission to that different park and verify its own operating schedule.
Other Tokyo Disneyland closures during the same period
The official park maintenance listing shows other attractions with early-2027 closure windows that may overlap your visit. At the time of this review, it lists Jungle Cruise: Wildlife Expeditions from January 6 through March 31, Splash Mountain from January 7 through February 4, and Haunted Mansion from January 8 through February 4. These are operator-published schedules, not independent predictions about refurbishment completion.
This makes the Peter Pan closure more significant for certain visitors than a single unavailable ride might suggest. A group that expected several classic experiences in one afternoon could find multiple priorities temporarily inaccessible. Conversely, the park contains many other attractions and entertainment offerings, and the attractions that remain open should be evaluated on their own current descriptions rather than guessed from historical schedules.
It is worth making a small “must ride / would enjoy / optional” list. Mark each attraction against the closure page. Then build flexibility around weather, performance calendars and queue variation. A plan with alternatives is more resilient than a rigid minute-by-minute schedule.
Better alternatives for different kinds of visitors
If the attraction’s appeal is gentle fantasy storytelling, explore other Fantasyland offerings listed in the official Tokyo Disneyland attraction directory. Filter for ride type and height or access restrictions, and read the current operating details. Do not assume that a neighboring attraction will be open merely because it is not listed in an older travel blog.
If the main attraction is Disney character immersion, devote time to character experiences, themed areas, shopping or scheduled entertainment that is actually available on your day. These can preserve the spirit of the trip without pretending they are substitutes for the ride itself. Some guests will prefer to spend the recovered time on a longer headliner; others may value an unhurried lunch and a park exploration that is less vulnerable to queues.
If the trip is built around Peter Pan specifically, Tokyo DisneySea’s Never Land Adventure may appear attractive. But it is not the same ride: it is a 3D boat-based experience in Fantasy Springs, with different restrictions and a different length. Tokyo Disney Resort’s DisneySea attraction page is the reliable way to compare them. Admission, access arrangements and the day’s capacity remain separate questions.
Parents should also avoid overstating the value of a replacement to children. “Another attraction has pirates” does not make it the planned Peter Pan experience. Setting expectations before entering the park is often more effective than negotiating disappointment in a crowded queue area.
Are refunds or ticket changes automatic?
The announcement of an attraction’s temporary closure does not itself demonstrate that every guest is entitled to a ticket refund or a date change. Theme-park tickets ordinarily grant admission subject to operating conditions, not a binding guarantee that every individual ride will operate. Actual ticket terms, package conditions and any operator-specific accommodation policy govern what can be changed.
Before buying or modifying a pass, review the official Tokyo Disney Resort ticket and reservations guidance and any reseller’s terms. A third-party package might combine transport, hotel rooms and tickets under separate cancellation rules. You should not rely on the statement “ride closed” as a universal reason for a penalty-free cancellation.
If your booking is complex, write down the name of the supplier, reservation reference, exact park date and type of admission. Seek a written answer before paying a change fee. This is particularly important if you plan to move only one day of a multi-day trip and keep the remainder unchanged.
Does Disney Premier Access help during the closure?
No paid queue-management product can make an attraction operate while it is closed. Disney Premier Access is a separate, paid tool for eligible operating experiences; eligibility and availability can change. The official Premier Access guide explains that places may sell out and that the price does not include park admission. It should not be marketed to families as a guaranteed workaround for a published maintenance closure.
The app can nevertheless be useful for other attractions and live operating information. If a ride is unavailable, remove it from the day’s queue-management plan and redirect attention to attractions genuinely offered that day. Check the current product terms before purchasing any additional access.
How to build a more reliable 2027 itinerary
Start with the official attraction closure list rather than the social-media version of it. Choose a date, read the list for the correct park, then check the pages for the two or three attractions most important to your group. If several favorites overlap with closures, compare another travel day, but preserve buffer time and cost limits.
Once you have a provisional itinerary, check whether your whole group can experience the alternatives. A family with a toddler and grandparents may have different needs from a group of teenagers. Ride seating rules, dark environments, height restrictions and walking distances deserve attention before buying optional upgrades.
A week before departure, look at the operator’s park calendar and attraction pages again. On the morning of your visit, follow current app information and staff instructions. Write down a backup plan that does not depend on a single ride reopening on the first conceivable day.
Quick visitor questions
Is Peter Pan’s Flight shutting permanently? The published notice says temporary closure January 6–February 2, 2027. It does not announce permanent removal.
Is it in Tokyo Disneyland or DisneySea? Peter Pan’s Flight is in Tokyo Disneyland’s Fantasyland. DisneySea has the separate Never Land Adventure.
Can I ride on February 2? The current listing includes February 2 in the closure window. Do not plan on riding that day.
Is February 3 the official reopening day? It is the first day after the presently announced closure period, assuming the dates are unchanged. Confirm the park’s live information rather than treating operation as guaranteed.
Should I change my trip? That depends on how important this specific ride is compared with hotel, flights, admission and other attractions. For most travelers, adjusting priorities within the same park is the lower-risk first option.
Final planning advice
This news is not a farewell to Peter Pan’s Flight. It is a defined, temporary gap in the operating calendar. The useful response is to check your exact visit date, compare the rides your family actually cares about and keep a realistic alternative ready. Tokyo Disneyland can still be an appealing destination during the listed closure; the difference between an enjoyable trip and a frustrating one may simply be accurate expectations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

SBP Raises Policy Rate to 12%: What It Means for Your Loans, Savings and Business

IMF’s $1.2bn Staff-Level Deal: What Pakistan Promised on Surplus

Decoding the DBS–BCA Merger Rumour: Market Volatility, Strategic Realities

New Xbox Games October 26–30, 2026: Releases and Game Pass

Tokyo Disneyland Peter Pan’s Flight Closure: January–February 2027 Guide

Neocloud Economics in 2026: GPU Debt, Utilization and Power

What Is a Neocloud? How AI GPU Clouds Work and Compare

Lula Re-elected in 2026: What Changes for the Dollar, Brazilian Stocks, and Interest Rates?

Lula Wins Brazil’s 2026 Election: Five Economic Tests for 2027

SSI November 2026 Payment: Why Benefits Arrive October 30

Russia Sanctions Waiver: What Asian Oil Buyers Gain

Asia Markets Weekly: How Oil, US Yields and the Fed Reach Tokyo, Kuala Lumpur and Karachi

Gold Near $4,000: Buy, Hold or Wait? A Pakistan Tola Price Guide

US 10-Year Treasury Yield Near 5%: The Hidden Cost for Pakistani Investors

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025