
Asia
Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

As global markets navigate a turbulent macroeconomic landscape defined by fluctuating energy costs, trade shifts, and rapid technological transformation, the Asia-Pacific region continues to act as the primary anchor for the world economy.
Recent data from the International Monetary Fund’s (IMF) October 2026 Regional Economic Outlook places Asia-Pacific growth at 4.8%. While this marks a minor moderation from previous years, it significantly outperforms baseline global metrics, establishing Asia as the source of nearly two-thirds of total global growth.
However, beneath this resilient headline figure lies a complex web of structural vulnerabilities and unprecedented opportunities. Can Asia sustain this momentum, or will external shocks compromise its long-term trajectory? This deep-dive analysis breaks down the core pillars driving Asia’s economy, exposes hidden structural risks, and outlines the definitive strategies required to outpace global competitors.
The Three Forces Shaping Modern Asian Economics
The current economic architecture of the Asia-Pacific region is driven by three competing vectors:
- The AI-Driven Tech Supercycle: Explosive demand for advanced semiconductors, automated solutions, and electronics manufacturing hubs (particularly spanning South Korea, Singapore, Malaysia, and Vietnam) has heavily offset sluggish consumption in Western markets.
- Persistent Energy Market Volatility: Geopolitical friction in the Middle East continues to pose direct threats to net energy importers. Because Asia consumes a disproportionate share of global oil and natural gas relative to its GDP, crude price fluctuations hit regional refiners and industrial supply chains harder than Europe or the Americas.
- Trade Reconfiguration & Supply Chain Diversification: Ongoing tariff pressures and trade policy adjustments have forced multinational corporations to decentralise production lines, boosting intra-Asian trade and strengthening manufacturing alternatives.
Core Data Matrix: Key Regional Performance Indicators
| Country / Region | Projected Real GDP Growth (2026) | Primary Economic Drivers | Key Vulnerabilities |
| ASEAN-5 (Average) | 4.4% | Domestic consumption, tourism, electronics export diversification | Commodity dependency, external debt financing |
| Vietnam | 8.4% | High-tech manufacturing, foreign direct investment (FDI), semiconductor assembly | Infrastructure bottlenecks, export concentration |
| Indonesia | 5.1% | Domestic market scale, downstream mineral processing | Inflationary pressures from fuel pricing |
| Malaysia | 5.2% | Semiconductor testing/packaging, digital economy transition | High exposure to global energy price swings |
| Singapore | 5.0% | Financial services, high-value tech innovation, global trade hub | Global financial tightening, talent constraints |
Key Analytical Insights: Beyond the IMF Baseline
While institutional reports offer macro-level comfort, an expert-level review reveals critical nuances that investors, policymakers, and business leaders must account for:
- Artificial Intelligence as a Labor Transformer, Not Just an Eliminator: IMF findings emphasize that AI is reshaping tasks rather than outright wiping out work. In aging economies (such as Japan, South Korea, and parts of East Asia), AI mitigates acute labor shortages. Conversely, in younger, demographic-dividend economies, it risks complicating entry-level job creation unless educational pipelines pivot toward technical integration.
- The Intra-Asian Trade Buffer: Historically reliant on US and European end-demand, Asian economies have successfully pivoted toward intra-regional supply chains. This localized trade ecosystem acts as a shock absorber against Western economic softening.
- Fiscal Space Constraints: Following years of pandemic-era spending and subsequent energy subsidies, sovereign balance sheets are stretched. Policymakers face a tightrope walk: they must rebuild fiscal buffers while simultaneously investing heavily in green energy transitions and digital infrastructure.
Strategic Recommendations for Sustainable Growth
To convert short-term resilience into permanent structural dominance, regional stakeholders must execute three tactical shifts:
- Deepen Services Trade Integration: While manufacturing trade is well-optimized, intra-regional services trade (fintech, digital services, logistics, and professional consultancy) remains heavily fragmented by regulatory red tape. Harmonizing cross-border data and service frameworks will unlock massive untapped productivity gains.
- Modernize Social Safety Nets and Labor Reskilling: To counteract job displacement from automation and AI, governments must transition from rigid employment protection laws toward dynamic active labor market policies—funding continuous retraining programs for displaced workers.
- Accelerate Renewable Energy Independence: Given that Asia’s oil and gas intensity per unit of GDP is nearly double that of Europe, aggressive investments in domestic solar, wind, and grid-storage infrastructure are no longer just climate goals—they are baseline national security imperatives.
Conclusion
Asia’s economic narrative for 2026 is one of calculated grit. By successfully balancing technological modernization with pragmatic trade adaptation, the region has defied pessimistic global forecasts. However, sustaining this engine requires moving past passive “coping mechanisms” into proactive structural reform. Those economies that bridge the digital skills gap and insulate themselves against energy shocks will dictate the pace of global prosperity for the next decade.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings.
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
Asian equities illustrate the danger of treating the region as a single asset class. Reuters reported on November 6 that South Korea’s Kospi had fallen about 8% and Japan’s Nikkei about 5% during the regional technology rout, while India’s Nifty 50 advanced roughly 0.51%. The divergence is notable because investors had spent years viewing Asian markets through a shared narrative of AI-led investment and export growth.
The IMF’s October Asia-Pacific outlook anticipated regional growth easing from 4.8% in 2026 to 4.4% in 2027, while still contributing disproportionately to global expansion. That is a strong headline but no guarantee for any individual exchange or company.
Chip supply chains create asymmetric risk
Japan, South Korea and Taiwan occupy different parts of the semiconductor, component and manufacturing ecosystem. Memory producers, equipment makers and foundries benefit when chip production and installation accelerate. Their shares can also fall sharply if markets question the volume, margins or ultimate returns on AI investment.
It is simplistic to equate the market reaction with the disappearance of AI demand. A business may continue growing while its share price corrects because valuations previously assumed flawless execution for years. Investors must separate an actual order cancellation from a fall in the multiple they are willing to pay for those orders.
India offers a different earnings composition.
India’s benchmarks include substantial financial, consumer and domestic-facing businesses. Lower imported crude prices can improve macroeconomic expectations through inflation, the trade balance and corporate margins. Reuters reported strong foreign buying on November 5 as sentiment improved. Such resilience can be meaningful even though it may reverse on later sessions.
An index’s headline performance can also conceal divergence. Financials may rise while smaller companies, richly valued technology suppliers or exporters weaken. A well-constructed comparison checks market breadth and earnings concentration instead of stopping at one benchmark return.
China and Hong Kong face their own constraints.
Chinese and Hong Kong-listed assets respond to property conditions, domestic consumption, export restrictions, currency dynamics and policy credibility. Their technology exposure overlaps with but is not identical to the U.S. AI trade. If global investors rotate away from expensive semiconductor leaders, relative valuations can help other markets—but only where credible profit growth supports them.
Exchange-rate effects complicate international performance. A local index can rise in home currency and still lose value for an investor whose base currency strengthens. Cross-border comparisons should therefore state whether results are in local currency or U.S. dollars.
Energy import dependence changes the ranking
The World Bank commodity outlook projects an elevated oil-price environment in 2026. Higher fuel prices reduce household purchasing power and raise transport and production costs in import-dependent economies. A reversal can offer relief, but the benefit varies with subsidy structures, hedging and exchange rates.
For Asian investors, the most revealing basket is not simply “technology versus everything else.” It includes oil-import sensitivity, export revenues, cash generation, financing costs and regulatory conditions. This is why a global shock can produce deeply divergent Asian sessions.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Asian market divergence |
| Interpretive opportunity | Contrast national sector mixes |
| Secondary question | Use oil import exposure |
| Next verification | Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
The regional average hides national balance sheets. Manufacturers, banks, households and governments experience an oil shock differently. Even countries in the same region may face opposite effects through exports, import bills and currencies. In this article’s subject—Asian stock markets 2026—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
The most useful comparison holds time and currency constant. Always align trading dates and specify whether reported returns are local-currency returns, translated-dollar returns or total returns. Otherwise, a comparison can be precise in appearance and misleading in substance. Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Contrast national sector mixes. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Use oil import exposure. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Separate multiple compression from demand. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three Asian market paths worth distinguishing
Technology spending stabilises. Asian chip exporters could recover if cloud companies reaffirm orders and memory suppliers report stable contract pricing. The recovery would still be uneven: a foundry, a memory producer and a consumer-electronics manufacturer respond to different demand drivers. Confirmation should come from corporate order books and earnings rather than a single regional index rebound.
A deeper investment retrenchment. If financing and power constraints delay new data-centre capacity, export-orientated producers in Japan, South Korea and Taiwan could face prolonged multiple compression and order revisions. Currency volatility may intensify foreign-investor returns, while an oil-price rebound would again pressure importers. The IMF’s regional growth projection would remain a baseline, not proof that equity earnings are safe.
Domestic-market rotation persists. India could continue to outperform on better energy terms of trade, bank earnings and household consumption even while North Asian technology stocks remain volatile. Yet an inflow-driven rally becomes fragile if valuations run ahead of earnings. Compare domestic profits, net foreign flows and oil import costs within each country before making regional generalisations.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
Questions readers are asking
Why did India outperform some Asian markets on November 6?
Reuters highlighted lower oil prices, foreign inflows and rotation away from AI-related names as important contributors.
Are all Asian technology stocks exposed equally?
No. Memory, foundry, equipment, consumer electronics and software firms face different customers and valuation risks.
Does lower oil help every Asian country?
No. Net importers often benefit, while exporters and energy producers can be hurt, subject to domestic policy and exchange rates.
Which data matters for an Asia comparison?
Synchronised index closes, local currency moves, industry weights, foreign flows, sovereign yields and corporate earnings.
The judgement
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. The most responsible conclusion is conditional: Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
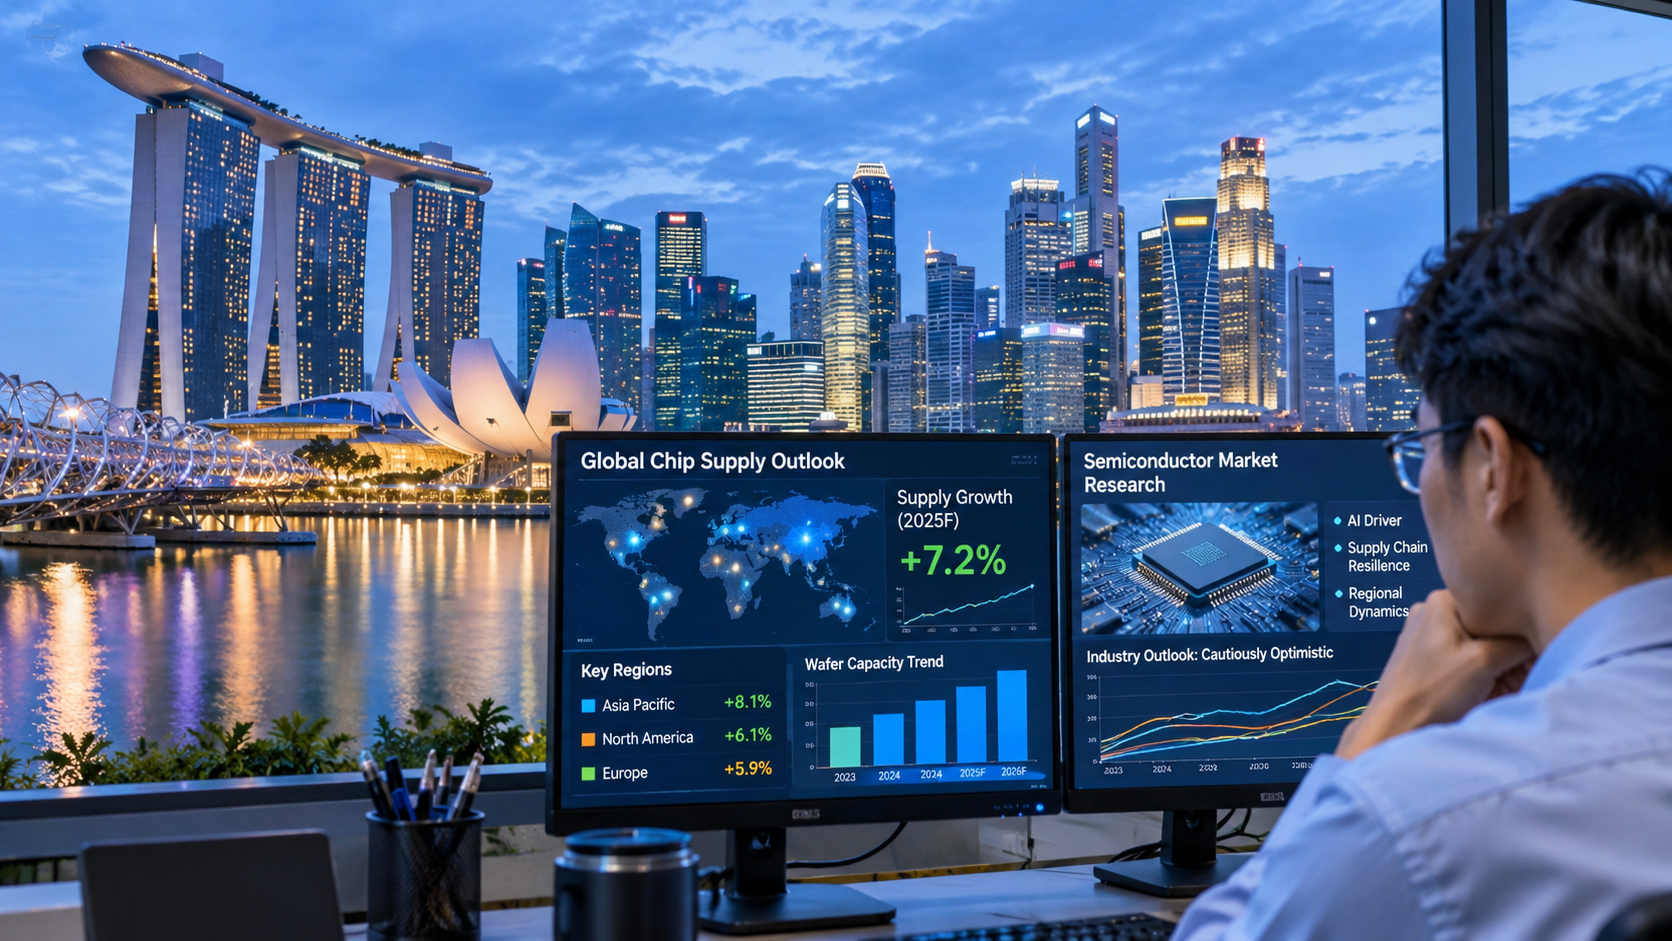
Asian equity markets have delivered a reminder that the AI investment boom is not simply an American technology story. South Korean memory producers, Taiwanese chip manufacturers, Japanese equipment suppliers and regional exporters are connected to global capital spending on computing. That creates an opportunity when orders surge and a vulnerability when assumptions change.
A Reuters market report on October 13 described a sharp risk-off episode in technology-linked Asian shares. Subsequent Wall Street Journal coverage described a partial rebound. Those moves are best understood as a test of expectations, not as proof that regional growth has reversed.
The first link: US AI spending and Asian earnings
The global chip supply chain has multiple layers. Advanced logic semiconductors, high-bandwidth memory, equipment, materials and packaging each respond differently to investment cycles. An AI server ordered in the United States can create revenue for numerous Asian firms, while supplier earnings remain vulnerable to delays or changes in product mix.
This concentration means broad stock indices may react strongly to a relatively narrow group of companies. The movement of an index is not necessarily a reliable representation of household consumption or the local services economy. Readers should check the contribution of leading constituents before interpreting a headline percentage drop.
Korea, Taiwan and Japan have different exposures
Korea’s market has significant memory-chip exposure. Taiwan has a major role in contract semiconductor manufacturing and its suppliers. Japan combines technology-related manufacturers with banks, exporters and domestic sectors. Exchange rates can amplify or offset changes in export competitiveness and returns for foreign investors.
Currency matters especially when an investor buys shares denominated in won, Taiwan dollars or yen. Even if a local index is unchanged, the return measured in dollars can change because of foreign-exchange movements. A regional market roundup should therefore include both equity and currency context.
Interest rates and oil can overwhelm the chip narrative
The AI industry competes for capital with governments, housing and ordinary businesses. When bond yields climb, distant profits are discounted more heavily; heavily indebted firms face rising refinancing expenses. Meanwhile high energy prices can pressure importers and manufacturers even when some technology exporters remain strong.
The IMF’s October outlook highlights both AI-related opportunities and inflation, conflict and fiscal vulnerabilities. That mixed picture argues against a single “Asia is booming” or “Asia is crashing” explanation.
The danger of extrapolating one trading session
A large daily decline can reflect positioning, forced selling or an abrupt change in sentiment. A rebound can reflect bargain hunting or short covering without resolving the original valuation issue. Neither movement establishes a sustainable trend. Investors should connect price action to revisions in earnings guidance, orders and financing conditions.
Useful evidence includes export orders, manufacturing surveys, semiconductor inventories, central-bank signals and capital flows. Compare the same measures over several months and distinguish expectations from realized data.
How to follow Asian markets responsibly
Build a dashboard with major indices, local-currency performance, exchange rates, benchmark bond yields and relevant oil prices. Record dates and market closing times; an Asian close may precede major US news that influences futures later. Avoid combining prices from different sessions as though they represent the same moment.
For a long-term investor, diversification across sectors and countries matters more than guessing the next technology stock to rebound. For a news reader, the essential question is whether a market move reflects an earnings change, financing risk or only a revision to how much investors are willing to pay.
Market structure can magnify headline moves
Market-capitalization-weighted benchmarks allocate more influence to companies with high market value. As chip and platform businesses grow, their success can make an index more concentrated. During a drawdown, selling pressure in those same names may dominate the index even if the median constituent is relatively stable. Equal-weighted sector comparisons and the share of stocks advancing can help distinguish broad weakness from concentration effects. Investors should also review whether an exchange was closed for a holiday and whether a quoted movement refers to a futures contract or the cash session. Time alignment is essential when comparing Asian and US markets.
Frequently asked questions
Why do Asian markets fall when US AI stocks sell off?
Regional firms supply chips, memory and equipment to the same global investment cycle, and investors frequently adjust exposure across markets at once.
Is a rebound proof the AI bubble is over?
No. Price recoveries do not necessarily resolve doubts about future returns and financing.
Which numbers are worth monitoring?
Earnings expectations, memory prices, exports, bond yields, currencies and oil prices give a more balanced picture than an index close alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Open Banking Trends 2026: What Consumers Should Know

Nvidia After the Selloff: What to Watch Before Earnings

Black Friday 2026 Early Deals: A Data-Driven Shopping Guide

Fed Policy Path 2027: Rate Expectations After the Hold

Asia’s Economic Resilience in 2026: The Strategic Blueprint for Sustaining the Global Growth Engine

Credit Scoring Changes 2026: What Mortgage Buyers Need to Know

10-Year Treasury Yield Outlook for 2027 After the Democratic Sweep

Is the AI Infrastructure Boom Sustainable? A Reality Check

Disability Insurance Demand in 2026: Who’s Buying and Why

What the 2026 Midterms Mean for Treasury Yields and Bond Markets

Payroll Outlook After the Midterms: 2027 Tax Changes, Compliance Risks and AI Trends

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

Singapore’s Bank Sell-Off Is Really a Test of What Stability Is Worth
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025