
Technology
US Chip Export Controls on China: How Huawei & SMIC Defy Sanctions

When Canadian researchers cracked open the casing of a newly minted smartphone in late August 2023, the silicon inside sent an immediate shockwave through Washington. The processor was simply not supposed to exist. Powered by a highly classified 7-nanometer architecture, the device proved that the expanding web of US chip export controls China faces is highly porous. The revelation forced Western intelligence and tech analysts to confront an uncomfortable reality. Silicon blockades can degrade an adversary’s manufacturing efficiency, but they rarely destroy the underlying engineering ambition.
The global semiconductor supply chain was historically defined by extreme geographic specialization and frictionless trade. Today, it is defined by weaponized interdependence. Since late 2022, the US Department of Commerce’s Bureau of Industry and Security (BIS) has issued increasingly stringent regulations designed to cap Chinese logic chip capabilities at the 14-nanometer node. Yet, Beijing’s response has been an unprecedented capitalization of its domestic technology sector.
State-backed investment funds have poured an estimated $142 billion into the domestic semiconductor industry, aiming to build localized alternatives to Western chokepoints. This capital tsunami buys time, attracts rogue talent, and crucially subsidizes gross inefficiency. It allows designated national champions to absorb staggering manufacturing losses that would bankrupt a purely commercial enterprise within quarters. The structural tension is now vividly clear. America relies on the precision of targeted technology controls and legal frameworks, while Beijing relies on the brute force of effectively unlimited capital.
The Physics of Defiance: SMIC’s 7nm Process
The specific mechanism allowing Semiconductor Manufacturing International Corp (SMIC) to manufacture advanced processing nodes is neither magic nor outright corporate theft; it is an exercise in extreme physical endurance. Unable to acquire the extreme ultraviolet (EUV) lithography machines exclusively produced by the Dutch giant ASML, SMIC engineers systematically repurposed older, legally obtained equipment. They utilize deep ultraviolet (DUV lithography) machines, pushing them radically past their intended physical limits through a highly complex process called multipatterning.
This technique involves exposing the silicon wafer to light three or four separate times to etch the ultra-fine circuitry required for 7nm chips. While mathematically functional, it introduces massive margins for error at the atomic level. Industry analysts estimate that SMIC’s 7nm yield rate sits at a commercially disastrous 15 percent, compared to the 90 percent yields enjoyed by Taiwan’s TSMC. At those margins, standard unit economics disintegrate entirely. Every successful chip costs exponentially more to produce because the manufacturer must discard the vast majority of the silicon as toxic electronic waste.
Still, Huawei is not operating a standard commercial playbook. As a designated national champion, it functions as the spearhead of state industrial policy. When the company rolled out the Ascend 910B—an AI accelerator designed to directly rival Nvidia’s restricted A100—it signaled a shift from basic consumer survival to enterprise infrastructure dominance. The Chinese state effectively subsidizes the 85 percent of silicon that ends up in the scrap heap. According to research from the Center for Strategic and International Studies, this willingness to absorb massive financial penalties transforms a crippling hardware bottleneck into a purely financial equation.
Beyond the Silicon: Mastering the Semiconductor Supply Chain Bypass
How is China bypassing US chip sanctions?
China bypasses US chip sanctions by repurposing older DUV lithography equipment through complex multipatterning techniques. State-backed tech champions absorb massive financial losses from low manufacturing yields, while exploiting regulatory loopholes to smuggle restricted AI processors through complex third-party shell networks.
The reality of the modern technological ecosystem is that it actively resists hermetic sealing. Washington’s strategy relies heavily on a “small yard, high fence” doctrine, aggressively restricting the most advanced artificial intelligence technologies while allowing legacy chips to flow freely. The critical flaw in this architecture is the underlying fungibility of mid-tier technology. By restricting the absolute pinnacle of semiconductor manufacturing, the US inadvertently incentivized Beijing to dominate the legacy, or “mature-node,” market.
These 28nm and larger chips are the unseen backbone of the global economy. They control everything from automotive braking systems and civilian aerospace controls to industrial medical equipment. As heavily subsidized Chinese fabrication plants flood the global market with cheap legacy chips, they threaten to systematically price Western foundries out of existence. If Western nations eventually rely entirely on Chinese foundries for legacy hardware, what geopolitical advantage remains when choking off advanced AI silicon? The strategic dependency simply shifts from the top of the supply chain to the foundation.
Furthermore, the grey market continues to mature at a frightening pace. Corporate shell companies operating in Southeast Asia and the Middle East procure restricted Nvidia H100 GPUs and simply rent their compute power via cloud instances to mainland AI developers. The high fence built by Washington is continually scaled by global capital looking for an arbitrage return. The strict physical containment of silicon hardware is increasingly undermined by the borderless nature of cloud computing architecture.
The Second-Order Effects on Global Markets
The downstream consequences of this escalating technological friction are radically reshaping capital expenditure across the globe. For Western policymakers, the immediate and harsh realization is that export controls are inherently a depreciating asset. Every single month a sanction is successfully maintained in place, the targeted entity works furiously to engineer a domestic alternative, recruit foreign engineering talent, or establish a covert smuggling route.
This dynamic forces a relentless, almost automated expansion of the US BIS entity list, creating three distinct macro-economic shifts:
- Capital Repatriation: Western equipment makers see mainland revenue plummet, forcing defensive domestic layoffs and the slashing of advanced R&D budgets.
- Legacy Dumping: Heavily subsidized Chinese fabs pivot to dominating older nodes, threatening the commercial viability of Western automotive and industrial supply chains.
- Grey Market Maturation: Smuggling networks transition rapidly from opportunistic hardware mules to highly sophisticated cloud-compute leasing structures.
Secretary of Commerce Gina Raimondo has continually emphasized the absolute necessity for dynamic, real-time enforcement, but regulatory bodies are perennially one step behind agile, well-funded corporate adversaries. As the banned list grows, collateral damage steadily mounts for allied technology firms. American equipment manufacturers like Applied Materials and Lam Research are watching their mainland market share evaporate, rapidly replaced by maturing domestic competitors like Naura Technology.
This bifurcated tech ecosystem creates a brutal financial reality for third-party nations and smaller enterprises. Hardware developers operating in Europe and Southeast Asia face diverging technological standards and increasingly incompatible supply chains. They must now design distinct, separate products for Western and Chinese markets, effectively doubling basic research costs and destroying long-standing economies of scale. According to a report by the OECD assessing global supply chain fragmentation, this forced decoupling could reduce global economic output by up to 2 percent over the next decade. The friction deliberately introduced into the system acts as a persistent, unyielding tax on global innovation.
The Case for the Controls: A Strategy of Attrition
Vocal critics of the current sanctions regime argue that export controls have merely accelerated China’s drive for absolute self-sufficiency, rapidly forging a resilient domestic supply chain that might never have existed under free-market conditions. That said, a mathematically rigorous analysis must acknowledge the intended timeline and true objective of Washington’s economic strategy. The goal was never an absolute, leak-proof embargo; it was an artificial and highly managed deceleration.
By forcing Huawei and SMIC to rely on highly inefficient multipatterning DUV techniques, the US imposes a massive time and capital tax on Chinese artificial intelligence development. As highlighted by semiconductor analysts at Bloomberg Intelligence, while SMIC struggles bitterly to master 7nm architectures at commercial scale, TSMC is already commercializing advanced 2nm architectures and gate-all-around (GAAFET) transistor designs for Apple and Nvidia.
This widening gap in fundamental physics matters immensely. In the trillion-dollar race for artificial general intelligence, the energy efficiency and computational density of the leading edge dictate the ultimate winner. A 7nm AI accelerator requires exponentially more electrical power and physical liquid-cooling infrastructure to match the standard output of a 3nm equivalent. Over a five-year horizon, this compute deficit aggressively compounds. The sanctions may be inherently leaky, but they systematically succeed in keeping Chinese developers a full generation or two behind the absolute frontier of global computational capability.
The Margin of Physics and Finance
The narrative of a hermetically sealed technological blockade is ultimately a political fiction. The reality playing out across the sprawling fabrication plants of Shenzhen and Shanghai is a grinding, brutal war of attrition, fought fiercely on the margins of atomic physics and sovereign finance. The expanding sanctions regime has not miraculously stopped China’s tech champions from advancing, but it has drastically altered the underlying cost of that advancement, forcing a heavy reliance on brute-force government subsidies over commercial elegance.
Washington’s export controls have successfully bought time, tangibly expanding the distance between the cutting edge of Western innovation and the trailing pursuit. Yet, this bought time is exceptionally expensive, paid for directly with the fragmentation of a highly globalized industry and the steady erosion of Western market share in vital legacy components. The ultimate test of this geopolitical policy is not whether Huawei can successfully produce a 7nm chip today, but whether the Chinese state can afford to indefinitely subsidize the raw physics of defying silicon sanctions tomorrow.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
TSMC reported record third-quarter revenue of approximately NT$1.49 trillion, up about 50% year over year. The key editorial question is how much optimism was already priced into shares. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
The AI boom increasingly looks like an industrial investment cycle rather than a story about chatbots alone. Reuters’ October 12 preview described expectations for another very strong quarter at TSMC, reflecting demand for advanced chips and packaging. The nuance matters: a foundry’s sales, a GPU supplier’s orders and a cloud operator’s eventual return on investment occupy different points in the chain. Sources: Reuters chip demand report and IREN fiscal results.
The important context competitors can overlook
Investors should distinguish model training hardware from inference demand, production capacity from booked orders, and one-time buildouts from recurring utilization. Advanced packaging, memory, power availability and data-center cooling can become bottlenecks even when silicon demand is strong. A boom in infrastructure spending is not automatically proof that every new capacity project will produce attractive cash returns. For primary-source checks and current reporting, see Reuters chip demand report and Reuters bond market analysis. The key distinction is connect chipmaker profits to supply-chain constraints.
A practical way to use this information
An evidence-led article should compare announced capital spending with actual deployments, gross margin trends, customer concentration and power constraints. Avoid ranking chip companies solely on price appreciation; a more useful framework examines whether a business captures durable economics as the cost of AI computation changes. Revenue forecasts must be dated and clearly identified as estimates.
Follow the money along the AI supply chain
A cloud company budgets for compute; a chip designer sells accelerators; a foundry fabricates the designs; memory and packaging suppliers help assemble deployable systems; and a data-center operator supplies space, cooling and power. Delays at any stage can push revenue recognition into a different quarter. The October 12 Reuters TSMC preview is a useful piece of the story, but not proof that all participants share equally in the profits.
The strongest follow-up article would compare order backlogs, capital intensity and gross margins across these stages rather than extrapolating from one supplier’s exceptional growth.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why is TSMC important to AI? It manufactures advanced semiconductors used by major technology companies.
Can rising AI demand still hurt some investors? Yes. Heavy capital spending, valuation risk and financing costs can offset revenue growth.
Follow the hardware from design to deployment
An AI accelerator does not arrive in a functioning data center simply because a chipmaker announces high demand. Designers such as Nvidia develop chips and systems; contract manufacturers such as TSMC fabricate advanced semiconductors; packaging providers integrate critical components; memory suppliers deliver high-bandwidth memory; network equipment and power infrastructure complete the installation. Bottlenecks at any stage can prevent a customer from using purchased capacity on schedule. Investors who focus only on the most visible brand miss the economics and constraints of the suppliers behind it.
The supply chain is also geographically distributed. Semiconductor fabrication and advanced packaging involve specialized equipment and long qualification processes. A customer cannot necessarily replace one advanced production facility with another at short notice. This supports supplier bargaining power in some circumstances but can increase geopolitical and operational concentration risk. The right editorial question is which constraint is binding now, supported by current evidence, rather than assuming every part of the chain faces identical shortages.
Four numbers reveal more than a chip-sales headline
First, look at revenue by segment and how rapidly each segment is changing. Second, inspect gross margin to see whether pricing power and production efficiency are translating into earnings. Third, review capital expenditure and capital intensity: growth that needs enormous new factories has a different funding profile from growth on existing capacity. Fourth, compare customer inventories and order visibility where those details are disclosed. Rising shipments into warehouses are not equivalent to a sustainable rise in end-user consumption.
Companies report different financial calendars and currencies. A Taiwanese foundry’s monthly sales announcement may not align neatly with a U.S. semiconductor designer’s fiscal quarter. Foreign-exchange translation can distort comparisons. When an article uses quarter-on-quarter or year-on-year growth, make the period explicit and avoid mixing projected sales with realized earnings. A comparison table should describe the business model of each company as well as its latest relevant metric.
Why packaging, memory and electricity can limit AI growth
Advanced packaging connects processors and memory in dense, high-performance systems. Manufacturing these components at scale requires engineering expertise and expensive equipment. Even when enough compute chips are available, a shortage of qualified packaging or memory can delay completed systems. At the deployment site, customers need reliable grid connections, transformers, cooling and networking. An equipment delivery that arrives before the building is ready does not immediately create usable computing capacity.
Power availability is not a purely technological footnote. Electricity contracts can influence operating costs for years; permitting and interconnection queues can delay planned facilities. Investors evaluating a data-center project should distinguish contracted megawatts, physically energized capacity and servers generating billable workloads. Headlines often conflate those milestones. The gap between ordering equipment and earning revenue is a critical part of the investment risk.
How AI investment could disappoint without a collapse
One scenario is that software adoption grows but not fast enough to justify every planned data-center investment. Another is that demand remains high, but competition lowers the price customers pay per unit of computing. A third is that hardware improves quickly, making recent generations less economically attractive before they are fully depreciated. None implies that AI is useless; they describe how a useful technology can produce uneven shareholder returns. Telecom investment cycles offer an instructive reminder that demand growth and attractive capital returns are not identical.
The upside scenario also deserves fair treatment. If enterprises discover reliable, high-value applications and capacity becomes heavily utilized, recurring compute revenue could support continued equipment demand. Evidence would include contracted usage, improved utilization, margins and identifiable business outcomes—not just press releases announcing larger model sizes. Investors should evaluate multiple possibilities rather than extrapolate the best recent quarter indefinitely.
An AI infrastructure due-diligence sheet
For chip designers: note product mix, customer concentration, gross margin and potential restrictions on sales. For foundries: monitor leading-edge capacity, packaging constraints, yield trends and capital expenditure. For memory suppliers: distinguish conventional memory from advanced HBM demand. For cloud operators: track compute utilization, capital cost, customer retention and cash generation. For data-center developers: verify grid power, physical construction, commissioning and signed customer commitments.
Use earnings materials and regulatory filings from each company, supported by market coverage that distinguishes analyst estimates from actual results. A strong AI chip article can capture the excitement of the investment cycle without implying that all parts of the supply chain will prosper equally.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Jeff Bezos has floated a future in which artificial intelligence makes workers productive enough that some people might choose a three-day workweek while still supporting their families. The Amazon founder made the point during an October 7, 2026 interview with Fox News. He did not announce that Amazon is adopting a three-day schedule or that AI guarantees shorter hours for everyone. The underlying distinction is crucial: Bezos was describing a possible long-term economic outcome, not a new employment policy. Fox News’s account of the interview and Fast Company’s focused coverage make that clear.
Key takeaways:
- Bezos linked the possibility of fewer working days to future gains in AI-driven productivity.
- He suggested greater output could make single-income households or shorter working schedules financially feasible for some families.
- There is no evidence in the cited interview of a universal three-day-workweek plan at Amazon.
- Research shows AI can save time on some tasks, but broad effects on compensation and employment remain unsettled.
What did Jeff Bezos say?
In the Fox interview, Bezos discussed an optimistic vision of technological progress. His argument was that powerful AI tools could raise economic output enough to expand people’s choices. If a person can generate greater value in less time—and share financially in that improvement—working fewer days could become an option rather than a forced reduction in income.
That scenario is different from predicting every office will close on Thursdays and Fridays. It is also different from a government-mandated reduction in work hours. Fast Company reported Bezos’s additional concern that firms might face labor shortages if people respond to higher productivity by choosing more leisure time.
The prediction has attracted attention because it reverses the most alarming version of the AI-and-jobs debate. Instead of imagining machines replacing so many workers that employment vanishes, Bezos emphasized the possibility of prosperity, shorter hours and tighter labor supply.
Why the productivity argument matters
Labor productivity is commonly measured as output per hour worked. That is the U.S. Bureau of Labor Statistics’ definition. A software developer completing work that used to require ten hours in six may produce more per hour. A customer-service team handling routine requests faster may serve more customers without increasing headcount at the same rate.
But greater task efficiency does not automatically mean that an employee receives proportionally higher wages or fewer shifts. Businesses choose how to allocate productivity gains among pricing, investment, expansion, profits, compensation and staffing. Workers’ bargaining power, competition, management priorities and public policy can all shape the outcome.
A simple illustration—not a forecast
Imagine an employee currently produces 40 units of useful output during a 40-hour week. Productivity is one unit per hour. If technology raises the rate to 1.67 units an hour, a 24-hour week could, arithmetically, produce approximately 40 units.
That calculation only shows a technical possibility. It assumes the tasks can be reorganized, demand stays sufficiently steady, management accepts the schedule, and pay arrangements remain favorable. Healthcare, aviation, emergency services, logistics and many other occupations require coverage across specific hours; AI cannot simply eliminate the need for people to be present.
The important question is not whether an AI tool sometimes saves time. It is whether the gain is widespread, reliable and shared in a way that makes shorter schedules financially sustainable.
What does current research show about AI and jobs?
The evidence is more restrained than the boldest predictions. A June 2026 International Labour Organization review found evidence of real but uneven productivity gains. It also concluded that large-scale job displacement had remained limited in the material reviewed, while warning about inequality, weakened entry-level pathways and shifting job quality.
Separately, Yale’s Budget Lab tracker, updated September 15, 2026, reported no clear economy-wide labor-market disruption attributable to AI in the indicators it examined. Its researchers cautioned that the findings could change as technology adoption and data evolve.
These results do not prove Bezos wrong. They show that the conditions for a large-scale three-day week have not yet been demonstrated by broad labor data. Firms are experimenting with AI, but productivity effects differ among tasks, occupations and organizations.
Task savings are not the same as job transformation
An AI assistant might draft a first version of a memo quickly, but a professional still needs to check accuracy, speak with clients, make decisions and accept responsibility. A factory might improve planning efficiency while remaining constrained by physical machinery. A hospital might automate paperwork yet still need the same number of nurses for bedside care.
This distinction between automating tasks and replacing whole jobs is essential. Headlines suggesting a direct line from better chatbots to a nationwide three-day week skip multiple economic steps.
Could workers keep the same pay while working less?
They could in some workplaces, but that would require an employer decision, collective agreement, regulatory change or a labor-market environment supportive of higher effective hourly compensation. An employee moving from five eight-hour days to three eight-hour days would cut weekly hours from 40 to 24—a 40% reduction in hours. Keeping weekly pay unchanged would require compensation per hour to increase by about 67%, before considering other changes in productivity or operating costs.
That is a much larger adjustment than ordinary schedule flexibility. The arithmetic does not make it impossible; it makes the necessary improvement explicit. By contrast, a four-day, 32-hour schedule requires a 20% reduction in hours, a different benchmark entirely.
Any employer trial must ask whether output, service quality, employee retention and customer coverage are maintained. Studies of particular programs may be promising, but results do not transfer uniformly to every industry.
What about Amazon employees?
There is no verified connection between Bezos’s prediction and an official companywide Amazon three-day-workweek policy. Bezos is Amazon’s founder and executive chair, but his personal economic forecast should not be presented as a company announcement.
Amazon operates a mixture of offices, warehouses, cloud-computing facilities, transportation networks and other businesses. Working-hour patterns depend on the role and contract. A broad change in hours would require formal employee communications and operational planning, not merely comments in a television interview.
Readers searching “Is Amazon switching to three days?” should therefore receive an unambiguous answer: not on the basis of this interview.
Could AI create a labor shortage instead of mass unemployment?
Bezos’s labor-shortage concern is plausible as a scenario, but it is not an established forecast. If incomes rose while more workers elected to reduce hours, businesses might face greater competition for labor. Yet other forces could push the opposite way: some jobs could be automated, employers could reduce hiring, or new industries might absorb displaced workers.
The net result will depend on adoption speed, which tasks AI performs reliably, the cost of computing and energy, economic growth and how governments and companies manage the transition. Reuters’ October 2026 discussion of AI at work also emphasized that AI is changing tasks within jobs, with younger and experienced workers potentially affected differently.
Frequently asked questions
Did Jeff Bezos predict a three-day workweek?
Yes. He discussed it as a possible consequence of greater AI productivity during an October 7, 2026 Fox News interview. It was not a commitment to a timetable.
Is Amazon moving to a three-day workweek?
No companywide shift was announced in the interview. Any claimed policy should be verified against Amazon’s official employment communications.
Would a three-day workweek mean three eight-hour days?
Not necessarily. A three-day schedule could mean 24 hours, longer shifts or another arrangement. Bezos did not establish a universal definition or wage agreement.
Will AI eliminate the need to work?
There is no evidence supporting that as an inevitable outcome. The ILO’s 2026 review describes heterogeneous gains and risks rather than the disappearance of work.
Could AI make one-income households more common?
It could in theory if household purchasing power rises materially, but wages, housing costs, childcare, benefits and employment security also matter. The claim remains a scenario, not a confirmed demographic trend.
When could three-day workweeks become common?
No defensible national timetable can be inferred from the cited interview. Some employers may experiment sooner than others.
The bigger economic question
The provocative part of Bezos’s vision is not whether software can perform individual tasks faster. It is whether future productivity gains become broadly shared prosperity. If workers capture enough benefit, shorter schedules may become more feasible. If gains are concentrated in profits or paired with job insecurity, fewer working hours could instead mean lower household income. Those are fundamentally different futures, and the evidence today does not settle which will dominate.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
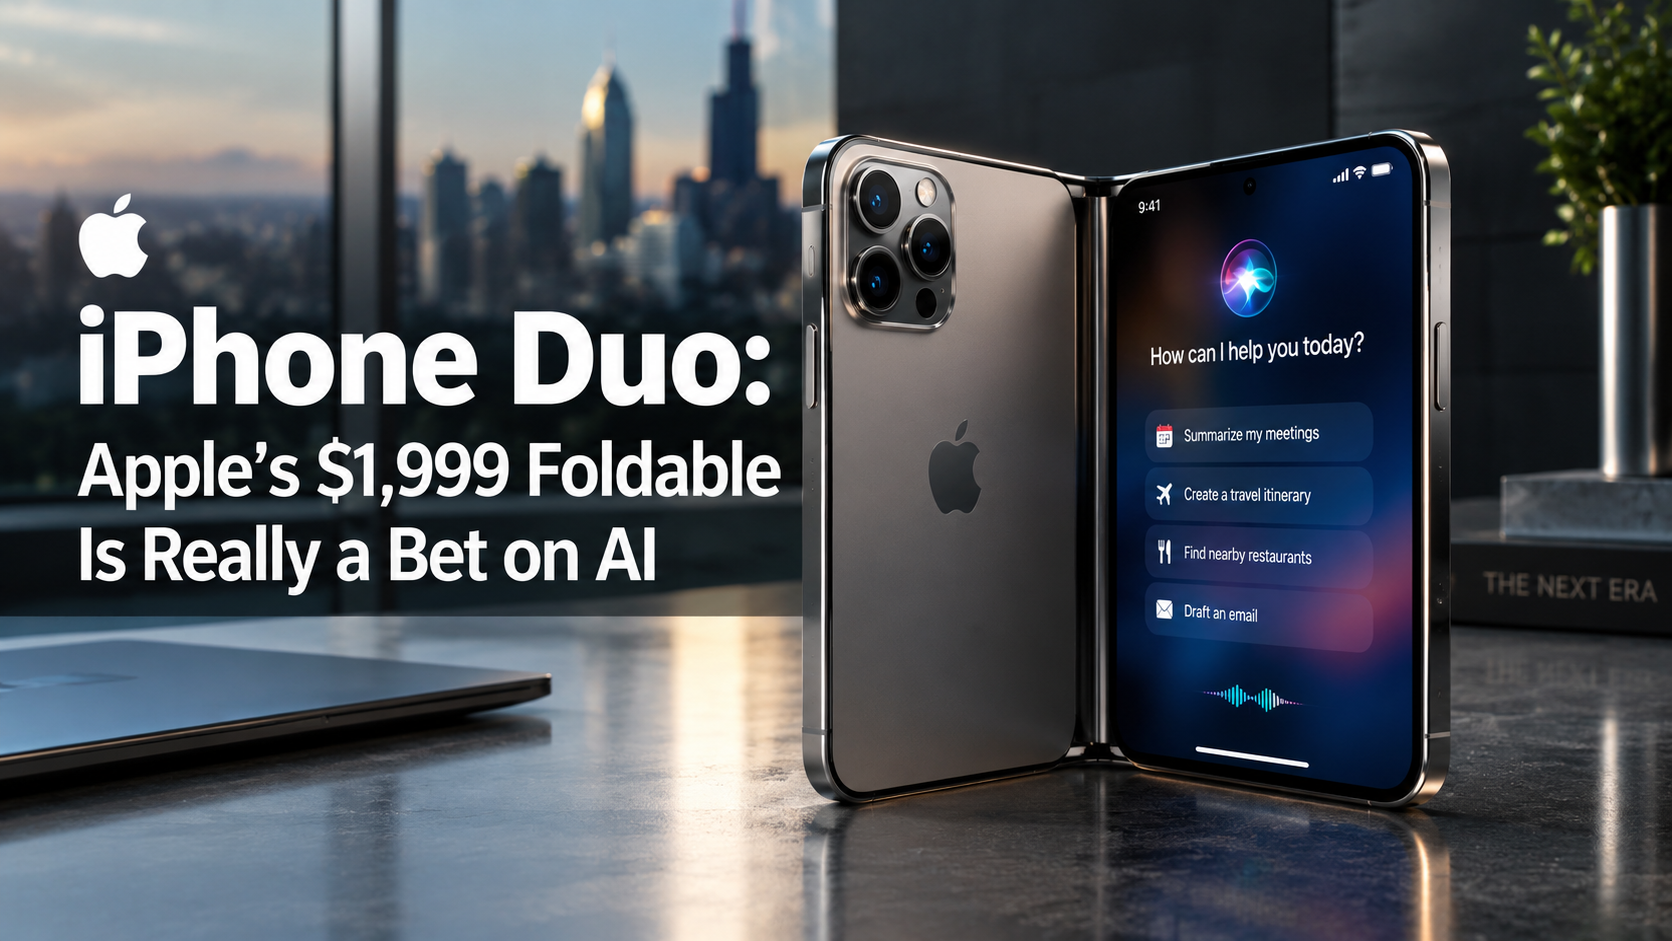
Apple waited seven years to build a foldable. When the company finally showed one, the pitch wasn’t the hinge. It was the screen real estate, and what Apple’s rebuilt AI assistant can do with it.
On September 9, Apple unveiled the iPhone Duo at its Cupertino headquarters, with a starting price of $1,999 and an October 23 release date. It was also the first Apple launch event run by new CEO John Ternus, who took over from Tim Cook on September 1. hawaiitribune-herald
Here’s what the Duo is, what it costs, and why it matters beyond the spec sheet.
Key Takeaways
- Price and date: The iPhone Duo starts at $1,999 and arrives October 23. That makes it the most expensive iPhone Apple has sold. hawaiitribune-heraldazfamily
- Screen: It opens to a 7.6-inch display, about 80% larger than the iPhone 18 Pro’s. wrdw
- Form factor: Folded, the front screen is roughly passport-sized. Opened, it runs two apps side by side. hawaiitribune-herald
- AI is the headline: Apple pitches the iPhone as a “personal intelligent hub,” and Siri AI is the software that is supposed to prove it.
- Market impact: Foldables are under 2% of global smartphone shipments, but IDC expects Apple to capture about a third of foldable demand. citizen
- Financing: Apple Upgrade, a new leasing program, lets buyers pay over one or two years. citizen
What Is the iPhone Duo?
The iPhone Duo is Apple’s first foldable phone. It folds like a book into a compact, passport-sized device and opens into a tablet-style screen. CNN reports Apple claims it is the thinnest iPhone ever when unfolded. keyt
Apple’s pitch was aimed squarely at existing foldables. Ternus said, “Others have created foldables that just feel like two phones awkwardly stuck together.” The Duo’s answer is a larger working canvas that still fits a pocket, with iOS 27 built around multitasking on that canvas. hawaiitribune-herald
Apple also put the Duo in its AP-reported lineup alongside the iPhone 18 Pro and 18 Pro Max, not above them as a separate product line. That framing matters. Apple wants the Duo read as a new iPhone shape, not a niche experiment.
iPhone Duo Specs and Price at a Glance
| Feature | iPhone Duo | Notes |
|---|---|---|
| Starting price | $1,999 | Most expensive iPhone to date |
| Release date | October 23, 2026 | Per Apple’s announcement |
| Main display | 7.6 inches (open) | About 80% larger than iPhone 18 Pro |
| Cover display | Passport-sized | Per CNN |
| Frame and hinge | Grade 5 titanium, 3D-printed hinge cover | Per Technology Magazine’s spec rundown |
| Chip | A20 Pro | Handles on-device AI and Apple Intelligence tasks |
| Pencil support | Yes | A first for iPhone |
| Multitasking | Two apps or two windows of one site | Split-screen on the large display New iPhone lineup includes a foldable version called Duo +7 |
Camera, battery and storage specifics are on Apple’s product page. I’d verify those directly before quoting them in a buying guide.
iPhone Duo vs iPhone 18 Pro: Which One Fits You?
The iPhone 18 Pro starts at $1,199 and the 18 Pro Max at $1,299. The Duo costs $700 to $800 more than either. irishexaminer
| iPhone 18 Pro | iPhone 18 Pro Max | iPhone Duo | |
|---|---|---|---|
| Starting price | $1,199 | $1,299 | $1,999 |
| Form | Slab | Large slab | Foldable |
| Best for | Everyday power users | Battery and camera-first buyers | Multitaskers, readers, Pencil users |
| AI features | Full Apple Intelligence | Full Apple Intelligence | Full Apple Intelligence, larger canvas |
Here’s the honest framing. Apple Intelligence and Siri AI run on the iPhone 15 Pro and 16 series or newer. The AI itself isn’t a reason to pay for the Duo. The screen is. If you mostly text, shoot photos and scroll, an 18 Pro does the same AI work for far less. propakistani
Why the Duo Is an AI Story
Look at how Apple framed the launch. Ternus emphasized Apple’s AI work and called the iPhone the ideal “personal intelligent hub.” The foldable is the hardware argument for that idea: more room to show an assistant’s output, research, and your apps at once. hawaiitribune-herald
The software side is Siri AI. It is Apple’s redesigned assistant, built on the latest generation of Apple Intelligence, and it rolls out initially in English. Two limits are worth knowing. Siri AI is not initially available on iPhones in the European Union, and Apple Intelligence features remain unavailable in China while regulatory work continues. French, Japanese, Korean, Portuguese and Spanish arrive in October. Apple Confirms iOS 27 Release Date for Eligible iPhones +2
Why does this matter commercially? Large screens make AI more useful. Compare two documents, keep a chat open beside a web page, mark up a PDF with the Pencil. Those are tasks where a 6-inch slab feels cramped and a 7.6-inch canvas doesn’t. If Siri AI delivers, the Duo becomes the best showcase for it. If Siri AI stumbles, a $1,999 phone becomes a hard sell.
How the Duo Could Reshape the Foldable Market
The numbers explain why the industry is watching. Counterpoint Research says nearly 20 million foldables shipped last year, under 2% of all smartphones. That’s a rounding error for a company that sells hundreds of millions of iPhones. hawaiitribune-herald
Two analyst views frame the opportunity:
- Demand: IDC expects Apple to take roughly a third of foldable demand and says the entry could shift competition in both China and global markets. citizen
- Strategy: Forrester’s Dipanjan Chatterjee called it classic Apple: let others work out the kinks, then enter and shape the category. wrdw
Samsung, Motorola, Google and Huawei have sold foldables for years. CNN notes Apple’s entry could push the category beyond early adopters. The likely effect is a bigger overall foldable market, with Android makers forced to compete on price and software polish against Apple’s ecosystem pull. keyt
The Supply Chain Angle
Foldables are hard to manufacture at volume, and the Duo’s reported component list shows who benefits. TSMC fabricates the A20 Pro, and Foxconn handles the complex assembly, including the titanium and 3D-printed hinge parts. Expect hinge suppliers, display makers and assembly partners to be central to Apple’s earnings commentary this quarter. technologymagazine
What the $1,999 Price Really Means
Apple clearly knows that number is steep. That’s why Apple Upgrade matters. The monthly leasing program spreads the cost over one or two years. Leasing turns a $1,999 sticker into a manageable monthly figure and keeps buyers inside Apple’s upgrade cycle. citizen
Accessories add to the total. The iPhone Duo Case is $79 and the Duo Folio with Kickstand is $129, both orderable October 16. A buyer who wants the Folio is looking at about $2,128 before tax. blakecrosley
Should You Buy the iPhone Duo?
Buy it if:
- You work on documents, spreadsheets or research on your phone and want a real second pane
- You want Apple Pencil on an iPhone
- You’re upgrading from an older foldable and want to stay in iOS
- Your employer or business can absorb the cost
Wait or skip if:
- You want the lowest-risk choice. First-generation hardware, especially hinges, deserves a few months of real-world reviews
- You live in the EU or China and want Siri AI on day one
- Your use is mostly calls, messaging and photos, where an 18 Pro does the job for $800 less
What to Watch Before October 23
- Hands-on reviews: Hinge durability and crease visibility will decide the first-wave verdict.
- Siri AI quality: Early beta impressions will shape whether the Duo is seen as an AI device or a pricey gadget.
- App support: Developers need to adapt layouts for the larger screen. Fox News’ iOS 27 rundown shows how much of Apple’s software push centers on Apple Intelligence.
- Android response: Expect Samsung and Google to counter with pricing and promotions.
The Bottom Line
The iPhone Duo isn’t Apple copying foldables. It’s Apple using a foldable to make its AI case on a screen big enough to matter. At $1,999 it will stay a premium product, but its real influence is on the category: bigger market, higher expectations, more pressure on rivals.
If you’re deciding, wait for hands-on reviews and Siri AI’s first weeks in the wild. If Apple delivers on both, the Duo could be the phone that finally makes foldables mainstream.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The Global South: Debt, Climate Finance and Investment in 2026

Energy Security Is the New Economic Security

Can Global Tourism Survive Geopolitical Shocks?

Global Maritime Hegemony: How China Secured Over 81% of All New Shipbuilding Orders

The Coming Battle Over AI, Jobs and Wages

Why Developing Economies Face a Sharper Inflation Problem

The New Geography of Trade: Are Supply Chains Coming Home?

Is AI Saving Global Growth or Creating the Next Bubble?

Global Banking Trends 2026: Digital Banks, AI and Compliance

Gold vs US Dollar vs Bitcoin in 2026: Inflation Hedge Compared

How Global Interest Rates Affect Savings, Loans and Investments

How to Invest During High Inflation: A Global Guide

Best Global Stocks to Watch in 2026: Four Sectors to Research

Pakistan’s 2027 Growth Strategy: Exports, AI, Energy and Jobs

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

US 10-Year Yield Hits 5.24%: What the Historic Bond Market Sell off Means for Mortgages and Investors

Gold Falls 3.7% as Yields Surge: Is Gold Still a Safe Haven in 2026?

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

MAS Allocates S$1.45 Billion to Five Asset Managers in Third EQDP Batch: Total Deployment Reaches S$5.4 Billion
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025