
Auto
The Hidden Maintenance Realities of EVs: Auto Financing and Insurance Costs in 2026

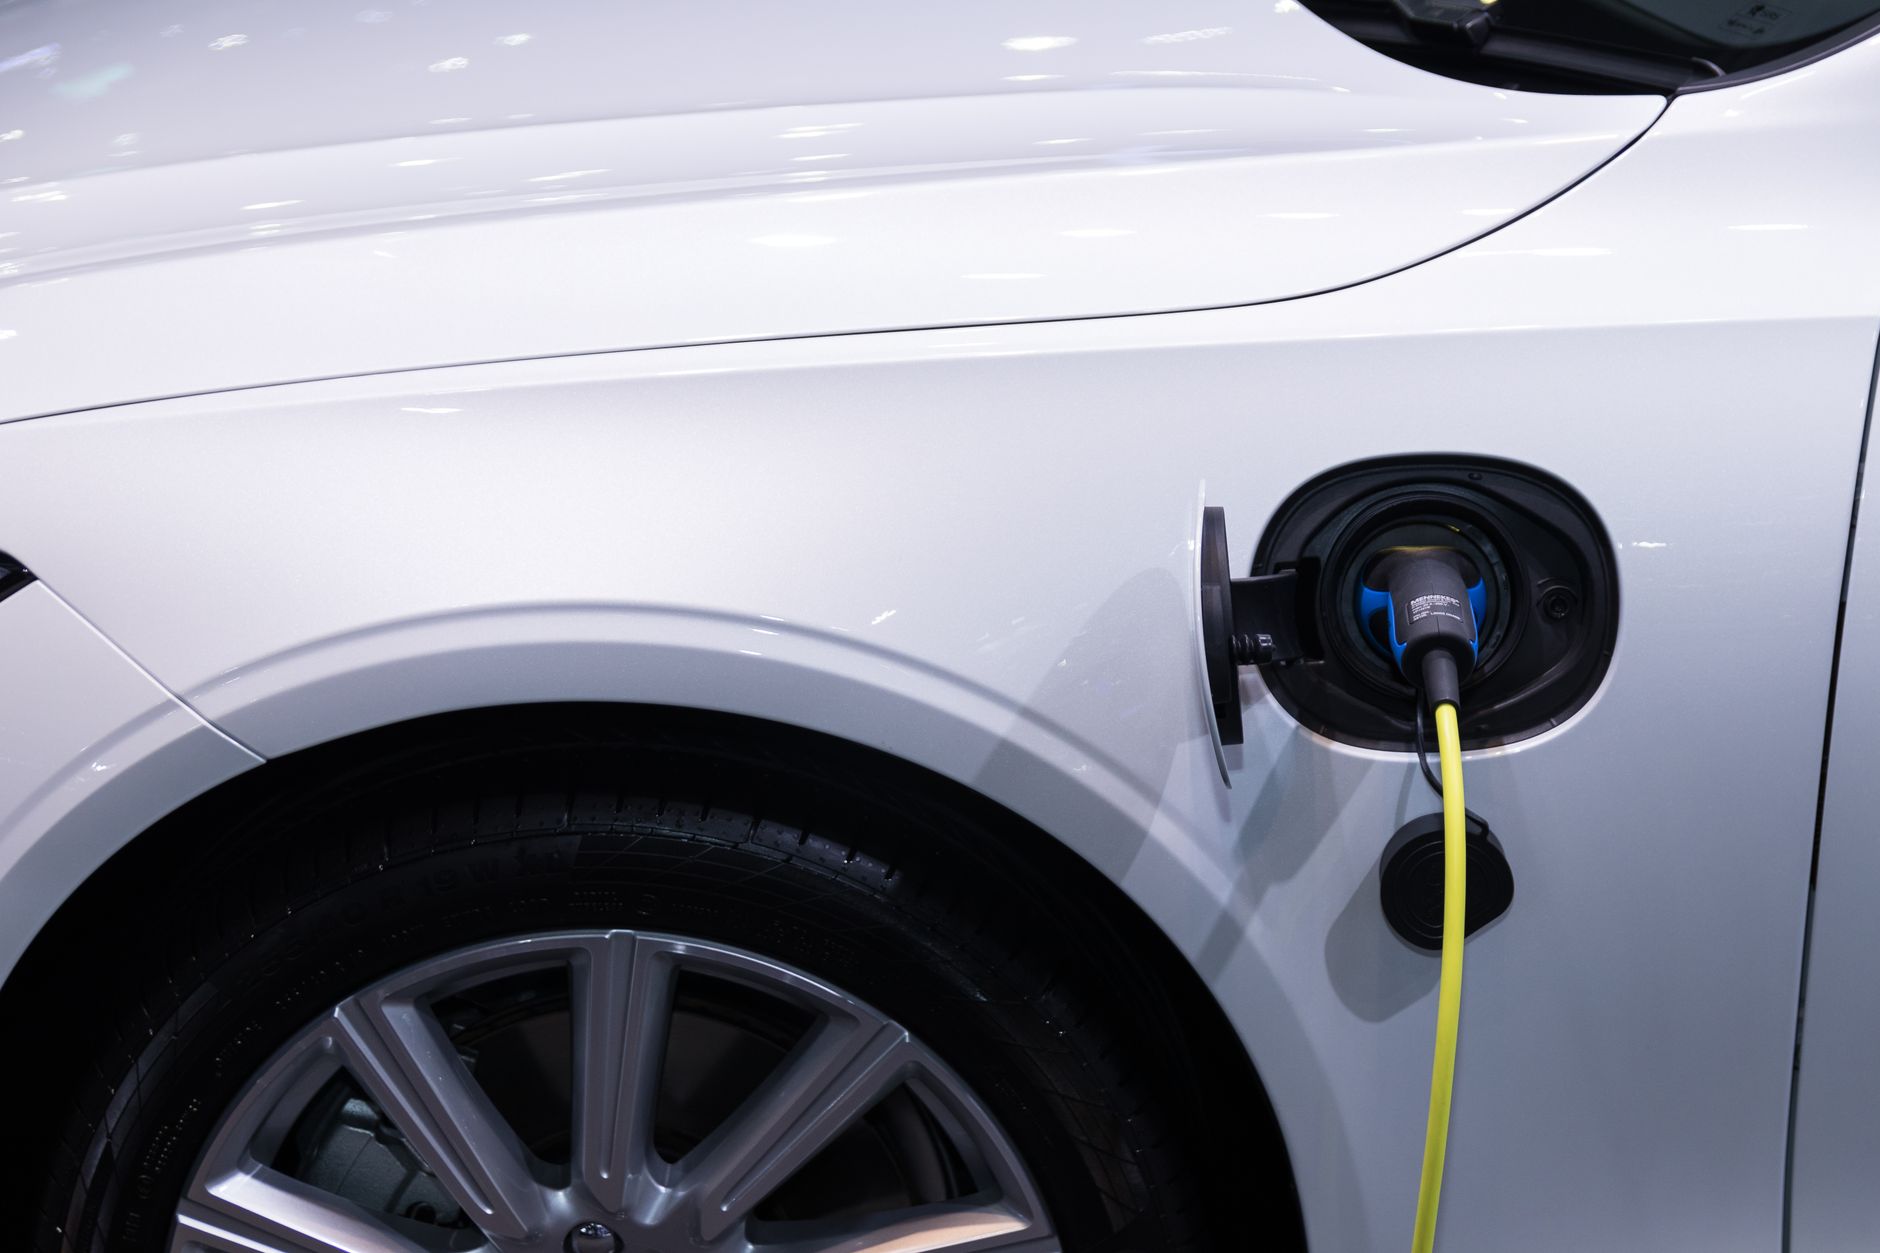
The electric vehicle pitch has always rested on a simple financial promise: fewer moving parts, lower fuel costs, and reduced routine maintenance. That promise is largely holding up in 2026 — but it obscures a second, less-discussed cost center that has grown more expensive, not less: insurance. For buyers and financing professionals evaluating total cost of ownership in 2026, the real story is a financial trade-off between genuine maintenance savings and a meaningfully higher insurance burden driven by battery economics.
Key Takeaways
- EVs cost about $330 less per year in routine maintenance than gas-powered vehicles, averaging roughly $949 annually versus higher combustion-engine upkeep, according to AAA driving-cost research — the “fewer moving parts” savings claim holds up in the data.
- EV insurance premiums run 15–42% higher than comparable gas vehicles, with 2026 estimates from Insurify putting average monthly EV insurance at $263 versus $185 for gas-engine cars.
- Battery pack replacement costs range from $4,000 to $22,000 depending on model and pack size, typically representing 30–40% of a vehicle’s total value — the single largest driver of elevated comprehensive and collision premiums.
- The average new EV cost $55,300 as of February 2026, per Cox Automotive — about $6,532 more than the average new gas vehicle — while used EVs have narrowed to just $1,334 above used gas-vehicle pricing.
- Car insurance rates broadly are projected to rise in 32 US states by the end of 2026, meaning EV owners face a double pressure: category-specific EV premiums layered on top of a generally rising rate environment.
The Maintenance Savings Case: Still Real, Still Meaningful
The mechanical simplicity argument for EVs remains well-supported by 2026 data. Electric vehicles have no oil changes, no transmission fluid service, no timing belt replacement, and no exhaust system — eliminating an entire category of scheduled maintenance that combustion vehicles require throughout their ownership life. AAA’s driving-cost research puts the resulting savings at roughly $330 per year, with average annual EV maintenance costs near $949.
This savings is real and durable, but it is smaller in absolute dollar terms than many buyers assume, and — critically for total-cost-of-ownership modeling — it is frequently outweighed by the insurance side of the ledger for higher-value EV models.
The Insurance Cost Reality: Where the Math Shifts
Where the EV financial story gets more complicated is insurance. Multiple 2026 data sources converge on a consistent range: EVs cost between 15% and 42% more to insure than comparable gas-powered vehicles, depending on the specific models compared and the data provider’s methodology. Insurify’s 2026 figures put the average monthly premium for a gas-engine vehicle at $185, versus roughly $263 for an EV — a 42% premium gap. Full-coverage annual premiums across a range of EV models span more than $8,000, from around $1,947 for a Chevrolet Silverado EV up to $10,402 for a higher-end model like the Audi SQ8 e-tron.
Why EV Insurance Costs More
- Higher replacement value. EVs generally carry a higher purchase price than comparable gas vehicles, which insurers translate directly into higher comprehensive and collision exposure.
- Proprietary parts and limited aftermarket competition. Many EV manufacturers — Tesla being the most cited example, alongside Rivian and Lucid — rely on proprietary components with no aftermarket alternative, keeping repair costs elevated and uncompetitive.
- Specialized labor scarcity. EV repairs require technicians trained on high-voltage systems and advanced driver-assistance technology; the limited pool of qualified shops reduces price competition on labor.
- Sensor and ADAS recalibration costs. A minor collision can cost roughly twice as much to repair on some EVs compared to an equivalent gas vehicle, due to the sensor recalibration required after even minor bodywork.
Battery Replacement: The Core Financial Risk
The battery pack is the single most consequential cost variable in EV ownership economics. Replacement costs in 2026 range from approximately $4,000 to $22,000 depending on the vehicle and pack size, and this single component typically represents 30% to 40% of a vehicle’s total value — a concentration of risk that has no real analog in combustion-engine vehicles, where no single component approaches that share of total vehicle value.
This concentration explains why insurers price EV comprehensive and collision coverage more conservatively: a covered loss involving battery damage exposes the insurer to a claim that can represent a third or more of the vehicle’s insured value in a single event.
Battery Risk Exposure Framework
A useful way to frame the uninsured risk gap for financing and insurance planning:
Annual Uninsured Risk = Battery Replacement Cost ÷ Remaining Warranty Years
Example: a $16,000 battery replacement cost against 4 remaining warranty years implies $4,000 in annual uninsured risk exposure once the manufacturer warranty lapses — a figure that should directly inform decisions around extended mechanical breakdown insurance (MBI) and battery-specific coverage riders.
What Standard Policies Actually Cover
Standard auto policies generally cover EV battery damage caused by a covered event — collision, fire, vandalism, or storm damage — under standard collision or comprehensive coverage, minus the policy deductible. However, normal battery wear and gradual capacity degradation are typically excluded from auto insurance entirely and fall instead under the manufacturer’s warranty or an extended service plan — a gap that becomes financially material as vehicles age past the typical 8-year/100,000-mile battery warranty window common across the industry.
Total Cost of Ownership: Running the Numbers
| Cost Category | EV (2026 average) | Gas Vehicle (2026 average) |
|---|---|---|
| Average new vehicle price | $55,300 | ~$48,768 |
| Average annual maintenance | ~$949 | ~$1,279 |
| Average monthly insurance premium | ~$263 | ~$185 |
| Battery/engine catastrophic replacement risk | $4,000–$22,000 (30–40% of vehicle value) | Comparatively lower, more distributed |
Even accounting for roughly $1,850–$2,800 in annual net advantage that some EV-focused ownership models calculate once fuel savings, amortized tax incentives, and maintenance savings are weighed against the insurance premium gap, the insurance line item alone can erase a meaningful share of the EV’s headline savings case for buyers who do not shop insurance carefully.
Financing and Insurance Strategies for 2026 EV Buyers
- Shop EV-specific insurance discounts explicitly. Green-vehicle or EV-specific rate reductions exist at many carriers but are frequently not advertised — buyers should ask directly rather than assume a standard quote reflects the best available EV rate.
- Evaluate usage-based/telematics insurance. EV owners with shorter commutes and predominantly home charging are strong candidates for pay-per-mile or telematics-based policies, which can meaningfully offset the base-rate premium gap.
- Model mechanical breakdown insurance against the battery risk formula above. For most EVs on the market in 2026, the annual uninsured risk from a post-warranty battery failure exceeds ten times the cost of a typical MBI premium — a favorable risk-transfer trade for most buyers.
- Weigh used EV pricing carefully. With used EV pricing now only about $1,334 above comparable used gas vehicles, the total-cost-of-ownership case for used EVs has improved meaningfully relative to new EVs, where the price premium remains over $6,500.
Frequently Asked Questions
Are EVs cheaper to maintain than gas cars in 2026?
Yes for routine maintenance — EVs save owners roughly $330 per year on average by eliminating oil changes and other combustion-specific servicing — but this saving is frequently offset by higher insurance premiums.
Why is EV insurance more expensive than gas car insurance?
EV insurance runs 15–42% higher due to higher vehicle replacement values, expensive proprietary battery and sensor components, limited aftermarket parts competition, and a smaller pool of specialized repair technicians.
How much does an EV battery replacement cost in 2026?
Battery replacement costs range from approximately $4,000 to $22,000 depending on the vehicle and battery pack size, typically representing 30–40% of the vehicle’s total value.
Conclusion
The EV total-cost-of-ownership picture in 2026 is more nuanced than either enthusiasts or skeptics typically present: the maintenance-savings case remains genuinely true, but it is a smaller number than most buyers expect, while the insurance cost gap — driven overwhelmingly by battery economics — has grown into a comparably sized, and in some cases larger, financial factor. Buyers, financing professionals, and insurers evaluating EVs in 2026 need a total-cost model that weighs both sides of this ledger explicitly, rather than relying on the maintenance-savings narrative alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The gap between the cheapest and most expensive auto insurer for the exact same driver and the exact same coverage can exceed $500 a year — meaning the single highest-leverage financial decision most drivers never make is simply comparing quotes before renewal.
Auto insurance pricing isn’t a fixed number set by the market; it’s a highly individualized calculation that varies dramatically between insurers for identical coverage. Two drivers with the same age, location, and driving record can receive wildly different quotes from the same set of companies, which is precisely why shopping multiple quotes — rather than auto-renewing with a single carrier — remains one of the most reliable ways to reduce a major recurring household expense.
This guide covers how auto insurance quotes are actually calculated, current 2026 rate benchmarks, and how to compare quotes effectively without accidentally under-insuring yourself.
How Auto Insurance Quotes Are Actually Calculated
Insurers use dozens of variables to price a policy, and because each company weighs these factors differently, the “best” insurer for one driver is frequently not the best for another.
Key takeaway: The national average cost of full coverage car insurance is $2,315 per year, or about $193 per month, while minimum coverage averages $621 per year, according to NerdWallet’s 2026 rate analysis — but your own quote will likely differ substantially based on factors specific to you.
The Core Factors That Drive Your Quote
- Location — state and even ZIP code meaningfully affect rates, with full coverage ranging from roughly $128 per month in the cheapest states to over $330 per month in the most expensive.
- Driving record — accidents, violations, and DUIs are among the largest individual rate drivers.
- Credit-based insurance score — used in most states (though prohibited in a handful) as a statistically validated predictor of claims likelihood.
- Age and driving experience — younger, less experienced drivers consistently pay significantly more.
- Vehicle make, model, and year — repair costs, safety ratings, and theft rates all factor into pricing.
- Coverage limits and deductibles — higher liability limits and lower deductibles increase premiums.
Step-by-Step: How to Shop Auto Insurance Quotes Effectively
- Gather your current policy details — coverage limits, deductibles, and driver information — so you’re comparing equivalent coverage across quotes.
- Get quotes from at least three to five insurers, including both large national carriers and regional companies, since regional insurers frequently beat national rates in specific states.
- Request identical coverage limits on every quote — comparing a $500 deductible quote against a $1,000 deductible quote will produce a misleading price comparison.
- Ask about all available discounts explicitly, since not every discount is applied automatically.
- Compare the final out-the-door price, including fees, not just the advertised premium.
- Review coverage details, not just price — the cheapest quote sometimes reflects lower liability limits or missing coverage types.
Financial and Strategic Implications: 2026 Rate Benchmarks
Understanding current market rates helps you evaluate whether a quote you’ve received is actually competitive.
| Coverage Level / Company | 2026 Rate Benchmark | Source |
|---|---|---|
| National average, full coverage | $193/month ($2,315/year) | NerdWallet April 2026 analysis |
| National average, minimum coverage | $52/month ($621/year) | NerdWallet April 2026 analysis |
| Cheapest large insurer, full coverage | Travelers, ~$139/month | NerdWallet March 2026 analysis |
| Cheapest large insurer, liability-only | GEICO, ~$41/month | NerdWallet March 2026 analysis |
| Most expensive state (full coverage) | Nevada, ~$335/month | ValuePenguin 2026 State of Auto Insurance |
| Cheapest state (full coverage) | Vermont, ~$128/month | ValuePenguin 2026 State of Auto Insurance |
Expert insight: 2026 is shaping up to be the calmest year for auto insurance pricing since 2022, with national rates projected to rise less than 1% on average — following double-digit annual increases in 2023 and 2024. That relative stability makes this a favorable year to shop aggressively, since insurers competing for market share in a flatter-rate environment are often more willing to offer competitive new-customer pricing.
Why Identical Coverage Can Still Produce Very Different Quotes
Because each insurer’s underwriting model weighs risk factors differently — one company might penalize a recent speeding ticket heavily while barely adjusting for credit score, while another does the reverse — your price can vary meaningfully between insurers even for the same driver and coverage, which is exactly why comparison shopping consistently produces savings that simply renewing with the same insurer does not.
How to Choose the Right Auto Insurance Quote
- Don’t default to price alone — verify the liability limits, comprehensive/collision deductibles, and any exclusions match across every quote you’re comparing.
- Ask about bundling discounts — combining auto with homeowners or renters insurance frequently produces a meaningful discount with the same carrier.
- Check for usage-based/telematics programs — safe drivers can often secure additional discounts through an insurer’s driving-monitoring app.
- Re-shop annually, not just at renewal notice, since insurer pricing models shift and a company that was competitive last year may not be this year.
- Confirm the insurer’s claims-handling reputation, not just price, using state insurance department complaint ratios or third-party satisfaction surveys.
- Review minimum coverage carefully — the cheapest liability-only policy may leave you underinsured relative to your actual assets in a serious at-fault accident.
Key takeaway: The single biggest mistake drivers make isn’t picking the wrong insurer — it’s not requoting at all. Insurance pricing models change frequently enough that a policy competitive two years ago can quietly become overpriced relative to the current market, with no notification from your current insurer.
Future Outlook: Auto Insurance Rate Trends Through 2027
- Rate growth is expected to remain unusually flat. ValuePenguin projects national auto insurance rates to rise by less than 1% on average in 2026, the smallest increase since 2022, though state-level trends diverge significantly — some states are projected to see rates fall by several percentage points while others, led by New Jersey, are projected to rise more sharply.
- State-level divergence is widening. More than half of states are expected to see rates decline in 2026, even as a handful of states see continued increases, making location-specific comparison shopping more valuable than ever.
- Usage-based insurance adoption continues to grow. As more insurers expand telematics-based discount programs, safe drivers increasingly have access to meaningfully lower rates than standard pricing models would otherwise offer.
- Credit-based insurance scoring remains a contested policy issue. Several states continue to debate restricting or eliminating the use of credit history in auto insurance pricing, a change that could meaningfully shift relative pricing among insurers if enacted more broadly.
Frequently Asked Questions
How many auto insurance quotes should I get before choosing a policy? Most experts recommend comparing quotes from at least three to five insurers, including a mix of large national carriers and regional companies, since regional insurers can significantly undercut national pricing in specific states.
Will getting multiple auto insurance quotes hurt my credit score?
Generally no. Auto insurance quotes typically use a “soft pull” that doesn’t affect your credit score, unlike a hard inquiry from a loan or credit card application.
Why did my auto insurance quote go up even though I haven’t had any accidents?
Rate changes can reflect broader factors unrelated to your personal driving record, including inflation in vehicle repair costs, regional claims trends, and insurer-wide rate filings approved by state regulators.
Is the cheapest auto insurance quote always the best choice?
Not necessarily. A lower price can reflect reduced liability limits, higher deductibles, or missing coverage types, so it’s important to confirm you’re comparing genuinely equivalent coverage before choosing based on price alone.
How often should I shop for new auto insurance quotes?
Annually is a reasonable standard practice, since insurer pricing models and competitive positioning change over time, and a policy that was competitively priced in a prior year may no longer be.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
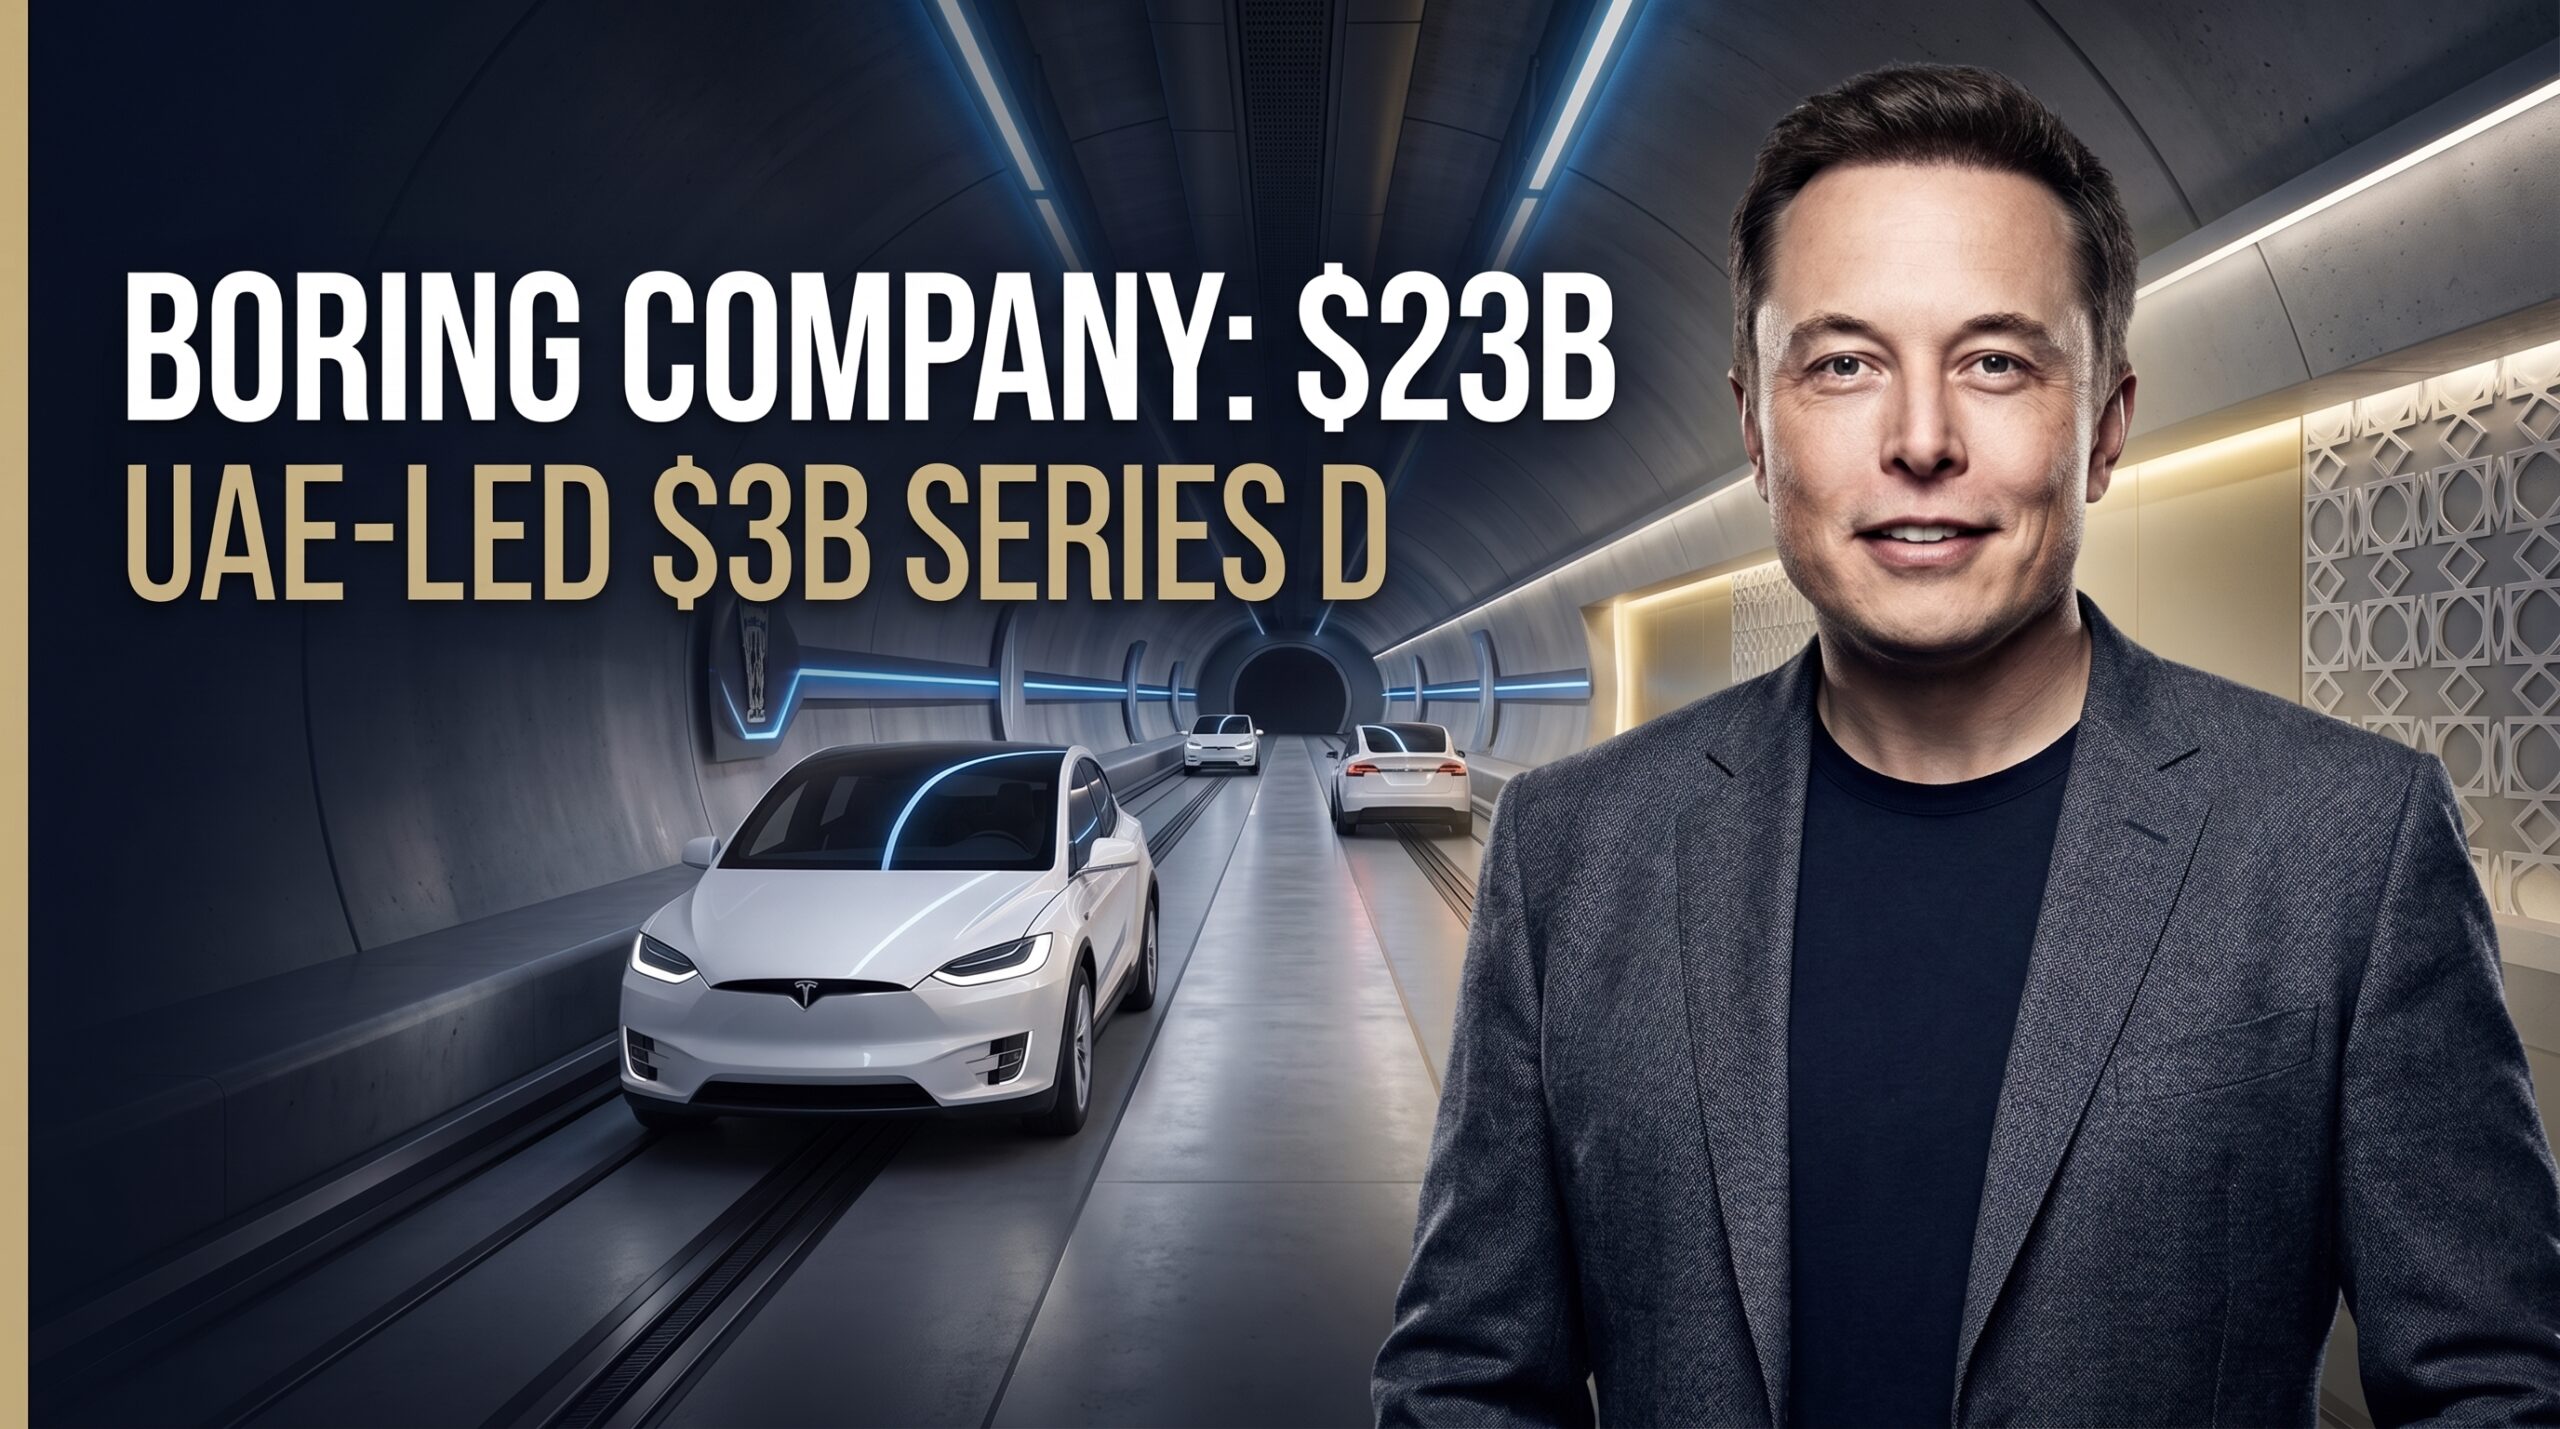
Elon Musk’s ambitious underground transit venture is officially scaling up its global footprint. The Boring Company has closed a massive $3 billion Series D funding round, catapulting its valuation to $23 billion. This represents a staggering four-fold increase from its $5.7 billion valuation in 2022.
Led by the United Arab Emirates (UAE) alongside a syndicate of heavyweight tech investors, this capital injection signals a decisive shift from a localized Las Vegas demonstration project to an international, multi-city infrastructure enterprise.
The Middle Eastern Pivot: A $3 Billion War Chest
The Series D round wasn’t just a capital raise; it was a strategic alignment. The UAE spearheaded the investment, joined by a roster of tier-one venture capital and private equity firms, including Sequoia Capital, Andreessen Horowitz (a16z), and Singapore’s state-owned Temasek. Additional participation came from Valor Equity Partners, Vy Capital, and Baron Capital.
The UAE’s role as the lead investor is deeply intertwined with its status as The Boring Company’s premier international customer. The funding is earmarked to deploy over 150 kilometers of underground infrastructure across the Emirates. This massive undertaking builds upon the foundation of the Dubai Loop, a project that was solidified at the World Governments Summit.
| Project Phase | Details | Estimated Cost |
| Dubai Pilot | 6.4 km route with 4 stations linking DIFC and Dubai Mall | ~$154 Million |
| Full UAE Network | >150 km of interconnected underground transit | TBD |
Manufacturing of precast tunnel segments for the Dubai pilot has already commenced, with active tunnel boring expected to begin in late 2026.
Scaling the Loop: Vegas, Nashville, and Beyond
While the Middle East represents the frontier of expansion, The Boring Company is simultaneously aggressively scaling its domestic operations in the United States.
- The Vegas Loop Expansion: Las Vegas remains the company’s operational showcase. Having already transported over four million passengers, the network recently added Tesla Cybertrucks to its autonomous fleet. Clark County regulators have greenlit a massive expansion, entitling the network to 123 stations, complete with a dedicated connector to the Harry Reid International Airport.
- Music City Loop (Nashville): Moving beyond the softer soils of Nevada, the company has broken ground in Nashville, Tennessee. Following regulatory approval in early 2026, crews are actively operating two Prufrock machines concurrently. This marks the company’s first foray into complex, hard-rock tunneling.
Prufrock and the Autonomous R&D Push
A significant portion of the new capital is allocated for aggressive hiring across engineering, operations, and production to scale the Prufrock tunnel-boring platforms.
The Boring Company’s core value proposition isn’t just digging holes—it’s automating the excavation process to drastically reduce costs and timelines. Recent milestones indicate that ring-building has become fully autonomous. Heavy concrete segments are now placed with millimeter precision via remote monitoring from the company’s Global Operations Control Center in Texas, effectively demonstrating “Zero-People-in-Tunnel” continuous mining.
For Musk, the mission remains philosophical as much as it is mechanical. In a statement accompanying the funding announcement, he noted: “Defeating traffic is the ultimate boss battle. Even the most powerful humans in the world cannot defeat traffic.”
With a $23 billion valuation and sovereign wealth backing, The Boring Company now has the financial firepower to test whether silicon valley automation can finally conquer legacy urban congestion.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Nvidia CEO Jensen Huang called it the “ChatGPT moment for physical AI” at CES in early 2026 — and by September, the capital markets have taken the claim seriously. Physical AI robotics has moved decisively from research demo to commercial deployment: PepsiCo is running 35 driverless trucks on public Arizona highways, Tesla has committed $20 billion in capital expenditure to convert Model S/X production lines into Optimus humanoid robot manufacturing, and venture capital poured $47.4 billion into physical AI startups across 521 deals in just the first half of 2026. This is not a speculative technology narrative anymore — it is an industrial IoT and supply chain automation software buildout with real revenue, real deployed hardware, and a credible multi-trillion-dollar addressable market.
Key Takeaways
- The global physical AI market was valued at $81.4 billion in 2025 and is projected to reach roughly $1.145 trillion by 2035 (33.5% CAGR), with some more conservative estimates putting the narrower AI-robotics segment at $15.24 billion by 2032.
- Humanoid robot shipments in China were revised sharply upward by Morgan Stanley — from 14,000 units at the start of 2026 to a projected 50,000 units by year-end, following Tesla’s own Optimus Gen 3 production ramp.
- Autonomous trucking has crossed from pilot to paid commercial operation: Gatik has completed 60,000 driverless orders incident-free with $600 million in contracted revenue, and Volvo plans to remove safety drivers entirely on U.S. highways by Q1 2027.
- Full trucking automation could save the U.S. economy an estimated $300 billion annually in labor costs, with $100–125 billion in net savings after accounting for technology costs.
- Roland Berger projects the humanoid robot industry alone could reach $750 billion by 2035 and $4 trillion by 2050 — a scale comparable to today’s global automotive industry.
From Pilot to Production: The 2026 Inflection Point
For years, physical AI robotics and driverless tech lived in the same category as flying cars — perpetually five years away. That changed in mid-2026, when a cluster of commercial milestones landed within days of each other. PepsiCo became the first major U.S. consumer-goods company to disclose large-scale autonomous truck use on public roads, running driverless vehicles between bottling plants, storage facilities, and retail customers including Walmart and Dollar General. Simultaneously, Einride completed its business combination and began trading on Nasdaq, and multiple autonomous trucking developers — Aurora, PlusAI, Waabi, Kodiak Robotics — began preparing factory-built, driver-out trucks for mass production rather than retrofitted pilot vehicles.
| Milestone | Company | 2026 Status |
|---|---|---|
| Driverless highway trucking at scale | PepsiCo / Aurora | 35 trucks operating in Arizona |
| Fully driver-out commercial deliveries | Gatik | 60,000 orders completed, $600M contracted revenue |
| 1,000-mile validated driverless lane | Aurora Innovation | Fort Worth–Phoenix, 250,000+ driverless miles, zero system-attributed collisions |
| Long-haul paid delivery with no human in cab | Bot Auto | Houston–Dallas (230 miles) completed |
| Full safety-driver removal target | Volvo Autonomous Solutions | Q1 2027, U.S. Sunbelt corridor, 300+ trucks by end of 2027 |
| Humanoid production scale-up | Tesla Optimus | $20B capex; Gen 3 with 22 degrees of freedom, 50 actuators |
The Regulatory Map Is Catching Up
Autonomous freight is no longer operating in a legal gray zone in its core markets. Over half of U.S. states now have autonomous truck testing or operation rules, and 24+ states explicitly permit self-driving trucks, led by Texas, Arizona, Florida, Arkansas, and Nebraska — where the majority of current commercial operations run. Both Aurora and Gatik briefed the FMCSA and NHTSA ahead of launching driverless operations, establishing a federal engagement pattern other operators are now following. Internationally, Japan is targeting Level 4 autonomous trucks in 2026, UN regulatory harmonization for autonomous vehicles is expected by mid-2026, and Dubai has launched Apollo Go robotaxis via Uber with an explicit goal of 25% autonomous transportation by 2030.
The Humanoid Robot Market: From Demonstrators to Factory Floors
The industrial IoT story of 2026 isn’t just wheels — it’s hands. Hyundai Motor Group debuted its Atlas humanoid robot for production settings at CES 2026, and BMW Group is deploying Figure AI’s Figure 02 humanoid to improve productivity, safety, and consistency in automotive operations. Tesla’s Optimus Gen 3, now in production at the Fremont facility, features 22 degrees of freedom and 50 actuators — a meaningful dexterity leap that is the underlying justification for Tesla’s unprecedented $20 billion capex commitment to convert core vehicle production lines toward robot manufacturing, the single largest physical-AI capital investment made by any automotive OEM to date.
| Market Sizing Estimate | 2025/2026 Baseline | Long-Term Projection | Source Methodology |
|---|---|---|---|
| Broad physical AI market | $81.4B (2025) | $1.145T by 2035 (33.5% CAGR) | Kaiso Research |
| Narrower AI-robotics component | $0.89B (2025) | $15.24B by 2032 (47.2% CAGR) | Edge AI/perception-focused definition |
| Humanoid robotics specifically | ~$4.2B (2026) | $40.5B by 2033 (38.2% CAGR) | Industrial + service applications |
| Humanoid industry (long-run) | — | $750B by 2035 / $4T by 2050 | Roland Berger |
The variance across these estimates — spanning more than a factor of three — reflects genuine definitional disagreement in the industry: some trackers count only AI-native perception/planning software, others include the full hardware, sensor, and actuator supply chain. What’s consistent across every methodology is the direction and steepness of the growth curve, not the exact terminal number.
Where the Capital Is Actually Flowing
Investment in supply chain automation software and industrial IoT is concentrated in a few clear categories:
- Logistics and warehousing — the single largest application vertical by 2026 market share, spanning autonomous forklifts, pick-and-pack robotics, and warehouse fleet orchestration software.
- Automotive manufacturing — both as a deployment site (BMW, Hyundai) and as a capital source (Tesla’s Optimus pivot).
- Long-haul freight — Aurora, Gatik, Kodiak, Waabi, Bot Auto, and Volvo Autonomous Solutions collectively represent the most commercially mature driverless segment.
- Compute infrastructure — Nvidia’s Isaac GR00T and Cosmos models underpin a large share of the perception and planning stack across multiple manufacturers, making Nvidia a structural beneficiary regardless of which individual robotics vendor wins.
Amazon, notably, already operates over 1 million robots handling roughly 75% of its global fulfillment volume, illustrating that at true hyperscale, physical AI has already moved well past the pilot stage into core operational infrastructure — a preview of where the broader industrial economy is heading.
Risk Factors Every Investor and Operator Should Price In
| Risk Category | Detail |
|---|---|
| Deployment pace overstatement | IFR (International Federation of Robotics) takes a more conservative view than industry vendors, noting real-world humanoid deployment remains largely limited to demonstrators/pilots, with true commercialization sitting later in China’s 2026–2030 plan period |
| Battery and power limitations | Cited as a persistent technical constraint on humanoid endurance and continuous operation |
| Labor market disruption framing | Industry voices like Gatik’s VP of Government Relations argue automation is complementing, not replacing, the existing truck-driver workforce — a narrative distinction with real policy implications |
| Capital concentration risk | A small number of players (Tesla, Nvidia, Amazon, Figure AI, Aurora) account for a disproportionate share of both funding and deployed units |
| Cybersecurity and compliance readiness | Analysts now cite this as mandatory for global and regional market access, not an optional add-on |
FAQ
How large is the physical AI market expected to become? Estimates vary by methodology, but the most-cited long-run figures point to roughly $1.1–1.15 trillion by 2035 for the broad physical AI market, with the humanoid robotics segment alone potentially reaching $750 billion by 2035 and $4 trillion by 2050.
Are driverless trucks actually operating commercially today, or is this still a pilot technology? Both, depending on the operator. Companies like Gatik and Aurora have moved beyond pilots into paid, driver-out commercial operations with real contracted revenue, while others are still in supervised testing phases. Volvo has publicly committed to full driverless highway operations by Q1 2027.
Which industries are adopting physical AI robotics fastest? Logistics and warehousing hold the largest current market share, followed closely by automotive manufacturing and long-haul freight. Amazon’s fulfillment network, handling roughly 75% of its volume via over 1 million robots, represents the most mature large-scale deployment today.
What is the biggest risk to the physical AI investment thesis? Deployment-pace overstatement is the most commonly cited risk — more conservative industry bodies like the IFR note that real-world humanoid deployment remains largely limited to demonstrators and pilots, with full commercialization likely later in the decade than some vendor projections suggest.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy

Planet Labs and Goldman: How Satellite Geospatial Data Is Reshaping Wall Street

Red Dye Diesel in 2026: Tax Exemptions, Regulations, and the Real Agricultural Impact

Student Loans in 2026: Forgiveness Updates, Consolidation, and Repayment Strategies

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Goldman vs. Citi: Which Banking Giant Leads Modern Global Finance in 2026?

Beyond Hanoi & HCMC: How Northern Industrial Clusters Are Driving Vietnam’s 10% Growth Surge

Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”

Southeast Asia’s LNG Dilemma: Navigating Price Volatility, Infrastructure Gaps, and Energy Security

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

Middle East War Economics 2026: Oil Prices & Energy Markets

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Social Security Trust Fund 2032: OASI Depletion Timeline Explained

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

World’s Largest Economies: Ranking the Top Global Powers

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025