
AI
How AI Is Systematically Transforming Education

For nearly half a century, Benjamin Bloom’s research has haunted educators with a tantalizing possibility. In 1984, the educational psychologist demonstrated that students receiving one-on-one tutoring performed two standard deviations better than those in conventional classrooms—a difference so profound that the average tutored student outperformed 98% of students in traditional settings. Bloom called this the “2-Sigma Problem”: how could schools possibly deliver such transformative results at scale when human tutors remain prohibitively expensive and scarce?
The answer, it seems, is finally emerging—not from hiring millions of tutors, but from intelligent machines that never tire, never lose patience, and can simultaneously serve millions of students while learning from each interaction. From classrooms in Estonia to rural India, from struggling readers in Detroit to gifted mathematicians in Singapore, AI-powered learning systems are beginning to deliver the kind of personalized instruction that Bloom could only dream of. The implications extend far beyond test scores: how nations learn, compete, and prosper in the coming decades may be defined not by their geography or natural resources, but by how effectively they harness this educational transformation.
The Personalized Learning Revolution Finally Arrives
The promise of personalized education has been recycled so often it risks becoming a cliché. Yet something genuinely different is happening now. Where previous technologies merely digitized traditional content—turning textbooks into PDFs or lectures into videos—today’s adaptive learning platforms powered by AI fundamentally reimagine the learning process itself.
Consider Duolingo, which has evolved from a simple vocabulary app into a sophisticated AI tutor serving over 500 million learners worldwide. Its latest iteration employs large language models to generate contextual explanations, adapts difficulty in real-time based on performance patterns, and provides conversational practice that mimics human interaction. The Economist recently noted that such platforms are achieving learning outcomes comparable to human tutoring at a fraction of the cost—precisely the kind of breakthrough Bloom sought.

Khan Academy’s Khanmigo represents another inflection point. Built atop OpenAI’s GPT-4, this AI teaching assistant doesn’t simply provide answers but guides students through Socratic questioning, adapting its pedagogical approach based on each learner’s responses. Early trials show remarkable results: students using Khanmigo demonstrated 30% faster mastery of algebraic concepts compared to traditional methods, while reporting higher engagement and reduced math anxiety.
These aren’t isolated experiments. Century Tech, deployed across hundreds of UK schools, uses neuroscience-informed algorithms to map how individual students learn and continuously adjusts content delivery. Squirrel AI in China serves millions of students with granular diagnostic assessments that identify knowledge gaps human teachers might miss. Microsoft’s AI-powered education initiatives are bringing similar capabilities to underserved communities globally, from refugee camps to remote villages.
What makes this wave different is the sophistication of the personalization. Earlier adaptive systems could adjust difficulty; today’s AI tutors understand context, detect misconceptions, recognize when students are frustrated or bored, and vary their teaching strategies accordingly. They’re beginning to approximate what great human tutors do instinctively—and doing it for millions simultaneously.
Augmenting Teachers, Not Replacing Them
The dystopian narrative of AI replacing teachers makes for compelling headlines but misses the more nuanced reality emerging in classrooms. The most successful implementations treat AI as what it truly is: a powerful tool that amplifies human educators rather than supplanting them.
Administrative burden consumes an astonishing portion of teacher time—an estimated 30-40% in most developed nations, according to OECD research. Grading essays, tracking attendance, generating progress reports, answering repetitive questions: tasks that drain energy from what teachers do best. AI teaching assistants are systematically eliminating this drudgery. Natural language processing systems can now provide substantive feedback on student writing, flagging not just grammar errors but structural weaknesses and opportunities for stronger argumentation. Automated grading systems handle multiple-choice assessments and even numerical problems, freeing teachers to focus on higher-order thinking.
More profoundly, AI is transforming teachers’ ability to differentiate instruction—the educational ideal honored more in rhetoric than reality. In a typical classroom of 30 students, providing truly individualized learning paths has been practically impossible. AI changes this calculus entirely. Teachers using platforms like DreamBox or ALEKS receive granular dashboards showing exactly where each student struggles, which concepts require reteaching, and which students need additional challenges. This intelligence allows educators to intervene precisely when and where it matters most.
In South Korea, the government’s ambitious AI textbook initiative pairs digital learning materials with teacher analytics that surface patterns invisible to the naked eye: which students consistently stumble on word problems versus computational tasks, who masters concepts quickly but forgets them within weeks, which peer groups might benefit from collaborative work. Teachers report that such insights transform their effectiveness, allowing them to orchestrate learning with unprecedented precision.
The role is evolving from “sage on the stage” to something more sophisticated: curator, coach, and conductor. Teachers design learning experiences, provide emotional support and motivation, facilitate discussion and debate, teach collaboration and critical thinking—the irreducibly human elements of education. Meanwhile, AI handles the mechanical, the repetitive, and the computationally intensive analysis that humans perform poorly at scale.
Narrowing the Great Divide: AI and Educational Equity
Perhaps the most consequential promise of AI in education lies in its potential to narrow yawning inequities—both within wealthy nations and globally.
In the United States, the gap between advantaged and disadvantaged students costs the economy an estimated $390-$550 billion annually in lost output, according to McKinsey research. Students in affluent districts enjoy experienced teachers, abundant resources, and often private tutoring. Their peers in struggling schools face overcrowded classrooms, teacher shortages, and outdated materials. AI tutors potentially democratize access to high-quality instruction regardless of zip code.
The transformation is perhaps most visible in developing nations. In India, BYJU’S serves over 150 million students, many in rural areas previously lacking access to quality education. Its AI-driven platform adapts to local languages, cultural contexts, and varying levels of prior knowledge, effectively bringing world-class teaching to villages without reliable electricity. UNESCO reports highlight similar initiatives across Sub-Saharan Africa, where AI-powered learning on low-bandwidth mobile platforms is reaching students who have never seen a traditional textbook.
Estonia offers an instructive policy model. The small Baltic nation, having digitized its entire education system, now uses AI to identify at-risk students early and deploy interventions before they fall irreparably behind. The results are striking: Estonia now ranks among the global leaders in educational outcomes despite spending substantially less per student than the United States or UK. The secret, according to education officials, lies in using AI to ensure no child becomes invisible—the system flags struggling students automatically, triggering human support.
Yet equity concerns cut both ways. The same technology that could democratize education might also deepen divides if deployed unevenly. Students in well-resourced schools may gain access to sophisticated AI tutors while their peers in underfunded districts receive outdated or inferior systems. The Brookings Institution warns that without deliberate policy intervention, AI could replicate existing inequalities rather than remedy them. The digital divide—in infrastructure, devices, and connectivity—remains a formidable barrier in many regions.
Moreover, AI systems trained predominantly on data from advantaged populations may serve those students better, embedding bias into the learning process itself. Ensuring that AI in education genuinely promotes equity requires conscious design choices, substantial public investment, and vigilant oversight.
The Considerable Risks We Cannot Ignore
No discussion of AI transforming education would be complete without confronting legitimate concerns that extend beyond access and equity.
Algorithmic bias represents perhaps the most insidious challenge. AI systems learn from historical data, and when that data reflects societal prejudices, the systems perpetuate them. A recent New York Times investigation found that some AI tutoring platforms consistently provided more detailed explanations and encouragement to students with traditionally European names than those with names common in minority communities—a subtle but consequential form of discrimination. Facial recognition systems used to monitor student attention have been shown to perform poorly on darker-skinned students, raising both accuracy and privacy concerns.
Privacy itself deserves careful scrutiny. AI learning platforms collect vast amounts of data about student performance, behavior, and even emotional states. While this data fuels personalization, it also creates troubling possibilities for surveillance and misuse. Who owns this information? How long is it retained? Could it be used to track individuals into adulthood, affecting college admissions or employment? The Financial Times has documented instances where student data from educational platforms was shared with third parties or used for purposes beyond learning—a troubling precedent as AI systems proliferate.
Perhaps most philosophically concerning is the risk of over-reliance undermining the very capabilities education should cultivate. If AI provides instant answers and step-by-step guidance, do students lose opportunities to struggle productively, to develop resilience through challenge, to think independently? Critics worry that excessive dependence on AI tutors might atrophy critical thinking skills, creativity, and intellectual autonomy—the qualities most essential in an AI-saturated world.
There’s also the question of what gets optimized. AI systems excel at improving measurable outcomes: test scores, completion rates, efficiency. But education encompasses much that resists quantification: wisdom, character, citizenship, the capacity for moral reasoning. An education system dominated by AI might systematically undervalue these harder-to-measure dimensions while over-emphasizing the easily trackable. As the educational philosopher Nel Noddings might ask: are we teaching students to learn, or merely to perform?
Finally, the pace of change itself presents challenges. Teachers need training, not just in using AI tools, but in redesigning pedagogy around them. Curricula must evolve to emphasize skills AI cannot replicate. Assessment systems built for a pre-AI era seem increasingly obsolete when students can generate essays or solve problems with chatbots. Educational institutions, traditionally slow to change, must somehow transform rapidly without losing sight of their core mission.
The Future: National Competitiveness and Lifelong Learning
The nations that successfully integrate AI into education may gain decisive advantages in the emerging global economy. When The World Economic Forum analyzes future competitiveness, it increasingly emphasizes not natural resources or manufacturing capacity, but human capital and adaptability—precisely what AI-enhanced education cultivates.
Consider the trajectory. Students educated with personalized AI tutors may master fundamental skills faster and more thoroughly, freeing time to develop higher-order capabilities: creativity, complex problem-solving, ethical reasoning, collaboration across differences. They’ll grow accustomed to learning continuously, adapting to new tools and concepts with AI-assisted agility. By some estimates, these students could complete traditional K-12 curricula two to three years faster while achieving deeper mastery—a profound competitive advantage multiplied across entire populations.
The implications extend well beyond childhood education. In an era where technological disruption renders skills obsolete with alarming frequency, lifelong learning transitions from aspiration to necessity. AI tutors available on-demand make continuous upskilling dramatically more accessible. A factory worker displaced by automation might learn coding through an AI tutor that adapts to her schedule and prior knowledge. A nurse could master new medical technologies through simulations and personalized instruction. A retiree might finally learn that language or skill he always dreamed of acquiring.
Singapore offers a glimpse of this future. The city-state’s SkillsFuture initiative, enhanced with AI-powered learning platforms, enables citizens at any career stage to acquire new competencies efficiently. The economic payoff appears substantial: workers transition between sectors more smoothly, productivity increases as skills continuously improve, and the workforce remains perpetually competitive despite rapid technological change.
Yet this future also demands thoughtful policy choices. Governments must invest not just in AI technology but in the infrastructure and training to use it effectively. They must establish guardrails around data privacy, algorithmic transparency, and equity. They must reimagine credentialing systems for an era when traditional degrees matter less than demonstrated capabilities. And crucially, they must prepare for labor market disruptions as AI-enhanced education accelerates both skill acquisition and obsolescence.
The most forward-thinking nations are already making such investments. Estonia’s AI strategy explicitly links educational transformation to economic competitiveness. China’s ambitious plans for AI in education form part of a broader bid for technological supremacy. The United States, despite its AI leadership in other domains, risks falling behind in educational deployment without coordinated national strategy—a concern raised repeatedly by think tanks and policy experts.
Conclusion: Realizing the 2-Sigma Dream
Benjamin Bloom died in 1999, never seeing whether his 2-Sigma Problem might be solved. But the solution he couldn’t have imagined—AI tutors combining infinite patience with individual adaptation—is emerging precisely as he predicted: dramatically improving learning outcomes at scale.
We stand at an inflection point. The technology enabling truly personalized learning AI has arrived. Early evidence suggests it works, sometimes remarkably well. The question is no longer whether AI will transform education, but how—and whether that transformation will be equitable, ethical, and genuinely beneficial.
The optimistic scenario is compelling: millions of students worldwide receiving instruction calibrated precisely to their needs, advancing at their own pace, never left behind or held back. Teachers liberated from drudgery to focus on the human elements of education. Learning becoming truly lifelong and accessible, enabling continuous adaptation in a fast-changing world. Nations competing not through military might or resource extraction, but through the flourishing of their people’s potential.
Yet this future is far from guaranteed. It requires sustained investment in educational infrastructure and teacher training. It demands vigilance against bias and exploitation. It necessitates preserving the irreplaceable human elements of education—mentorship, inspiration, moral formation—even as machines handle much of the instruction. And it calls for profound reimagining of what education means and measures in an age of artificial intelligence.
The transformation is already underway. AI in education has moved from speculation to implementation, from pilot programs to widespread deployment. What remains to be determined is whether we’ll harness this revolution thoughtfully, ensuring that Bloom’s dream of exceptional outcomes for every student becomes reality rather than merely another form of technological determinism.
The answers we provide—through policy, investment, and ethical frameworks—will shape not just how the next generation learns, but what kind of world they’ll inherit and create. In that sense, the systematic transformation of education by AI is about far more than schools or test scores. It’s about whether we can build a future where human potential is genuinely democratized, where geography and circumstance matter less than curiosity and effort, where learning never stops because the tools to support it are always available.
That future is within reach. Whether we grasp it wisely will define the coming decades.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


China’s explosive growth in AI usage marks a pivotal turn from building models to putting them to work. But conflicting token estimates, soaring infrastructure bills and weak pricing power complicate the story of a technological breakthrough.
For years, the global artificial-intelligence contest was measured by the scale of models being trained: the number of parameters, the sophistication of chips and the cost of the next spectacular breakthrough. China’s latest figures suggest that a different contest is moving to the centre of the industry. The question is no longer only who can build the smartest machine. It is who can afford to run intelligent software, continuously, for millions of customers and across entire industrial systems.
A report released on October 31 by the China Centre for Information Industry Development (CCID), a research organisation linked to the Ministry of Industry and Information Technology, says data used to run AI models — known as inference — has overtaken the data used to train them. The institute reported more than 175 trillion daily token calls by June 2026, more than 1,000 times the volume at the beginning of 2024, according to the South China Morning Post’s November 2 account.
That is a meaningful marker of adoption, but it should not be confused with proof that China now leads the world in AI computing, or that the companies processing those tokens are earning attractive profits. More importantly, the milestone is not quite as new as the headlines imply.
The overlooked fact: China had reported the crossover months earlier
On April 29, 2026, China’s National Data Administration published findings from its 2025 national data-resource survey. The government announcement said the combined volume of data used for AI training and inference in 2025 reached 199.48 exabytes, of which 101.34 exabytes was attributed to inference. By subtraction, training accounted for roughly 98.14 exabytes. Inference therefore represented approximately 50.8% of the measured total.
The government had already described this as the first time inference-data volume exceeded training-data volume. October’s CCID statement is better understood as further evidence of the shift, not the first public announcement that it had happened.
A second complication is that the latest usage estimates do not agree. CCID’s figure is more than 175 trillion daily token calls in June. Yet an October 12 report carried by Xinhua, citing the National Data Administration, says average daily token calls had surpassed 500 trillion by June. A separate late-October analysis from the China Academy of Information and Communications Technology likewise described daily token consumption of roughly 500 trillion.
The two figures differ by nearly a factor of three if the lower one is treated as 175 trillion. That does not automatically mean one report is wrong: they may cover different providers, kinds of token traffic or counting methods. But the publicly available accounts do not reconcile their scope well enough to justify treating either number as a complete, directly comparable measure of national AI activity.
What China’s AI figures actually measure
| Indicator | Reported figure | Period | How to interpret it |
|---|---|---|---|
| Training and inference data combined | 199.48 exabytes | Full year 2025 | Total reported data volume, not GPU computation |
| Data attributed to inference | 101.34 exabytes | Full year 2025 | About 50.8% of that measured total |
| Data attributed to training | About 98.14 exabytes | Full year 2025 | Calculated as the difference, not separately quoted |
| Daily token calls | 100 trillion | End of 2025 | National Data Administration historical figure |
| Daily token calls | More than 175 trillion | June 2026 | CCID-reported figure |
| Daily token calls or consumption | More than/about 500 trillion | June 2026 | Reported separately by official and industry sources; scope may differ |
| Generative-AI users | More than 700 million | End of June 2026 | People counted as users, not necessarily daily active users |
Sources: China’s National Data Administration, SCMP reporting on CCID, Xinhua on token activity, and Xinhua on generative-AI users. Different units and samples should not be merged into a single growth series.
Training versus inference: why this distinction changes the business model
Training is the expensive process through which a model learns statistical patterns from vast datasets. It typically requires intensive computing over a defined period. Inference begins after a model is deployed: each time a customer asks a chatbot a question, a coding assistant edits a program or an automated agent reviews an invoice, the model consumes and produces tokens.
A token is a unit of information a model processes, often a fragment of a word in text applications. Token size and significance vary across models and content types. An inference request can contain input tokens, generate output tokens, and involve repeated internal steps. A token count is not a count of human questions, customers, or completed tasks.
The economics are different. Training costs can be concentrated in large projects. Inference creates recurring bills that rise with usage, the length of requests, model complexity and the number of steps an AI agent takes. A business deploying a model across thousands of employees must manage this expense every working day.
Crucially, more inference data than training data does not establish that inference consumes more electricity, GPU-hours, or capital than training. Data volume, token throughput and computational operations are different measures. A credible comparison would require consistent definitions, coverage of private deployments and evidence on actual computing workloads.
What the crossover does indicate is a change in industrial emphasis: companies are trying to make AI useful at scale, rather than treating new model launches as the only measure of progress.
China’s advantage may be practical deployment, not just frontier performance
China has several reasons to push the economics of inference. It has a large domestic digital market, major cloud platforms, a dense industrial base and government policies aimed at deploying AI in manufacturing. As of June 2026, China had more than 700 million generative-AI users, according to official reporting. That figure suggests a broad potential market, although it does not reveal how often each person uses the technology or what they pay.
China’s factories are an especially consequential test. The government said in November 2025 that it had already established more than 500 excellence-level smart factories. A January 2026 industrial AI action plan called for wider use of large models in manufacturing by 2027. Such applications could include quality inspection, maintenance scheduling, technical documentation, inventory decisions, and specialized industrial assistants.
But the number of designated factories or pilot projects is not a productivity statistic. The real evidence will come from improvements in defect rates, downtime, energy consumption, output per worker and return on investment — independently measured against meaningful baselines. A laboratory demonstration, a government designation and a self-sustaining commercial deployment are three different achievements.
The underlying competitive context has also changed. Stanford University’s 2026 AI Index found that the performance gap between leading US and Chinese models had narrowed dramatically; as of March 2026, the best US model led by 2.7% on the benchmark comparison used by the report. This is not evidence that all models are equivalent in reliability, safety or specialized tasks. It does mean that price, accessibility, and the quality of integration increasingly influence purchasing decisions.
Cheap AI could become China’s greatest export — and its profit trap
Chinese developers including DeepSeek, Alibaba’s Qwen, Moonshot and Z.ai have helped normalise an alternative to buying every inference call from an expensive proprietary frontier model. An organisation can use an open-weight model, customise it for a particular task, or run lower-cost models for routine work while reserving premium systems for difficult questions.
The Financial Times reported in 2026 that companies in the US and Europe were using Chinese models to reduce costs and increase flexibility. This represents more than a marketing victory: it creates the possibility that Chinese AI technology can spread globally through applications even where Chinese consumer chatbots are not dominant.
There is a paradox, however. As Reuters Breakingviews observed in April, selling enormous quantities of inexpensive tokens can become a race to the bottom. If suppliers compete chiefly on price, usage may soar while the margin earned on each additional token contracts. If models become interchangeable, much of the economic value may accrue to the businesses that own customer relationships, data, workflows, and distribution—not necessarily to the model developers.
Consider a simple, hypothetical example: an enterprise processes 100 million billable tokens daily. At $0.50 per million tokens, its model-usage bill is $50 a day. At $5 per million, it is $500 a day. That is a tenfold difference before accounting for input-output pricing, caching, infrastructure, review and support. This is an illustration, not a quotation of any vendor’s current price.
But price per token is not the same as cost per successful task. A weaker model that repeatedly fails, requires human correction or makes multiple retries could cost more than a premium model that gets the job done once. Enterprises will increasingly measure the cost of a verified outcome, not simply the cost of generating a million tokens.
The revenue test: more tokens do not automatically mean more profit
China’s cloud giants are already demonstrating both the opportunity and the tension. In its April–June 2026 quarter, Alibaba’s cloud and AI-computing revenue rose 45% to 48.44 billion yuan, while capital expenditure increased to 67.68 billion yuan as the company expanded AI infrastructure, according to Reuters. Revenue growth is genuine demand; the spending also shows how much capacity providers must build in pursuit of that demand.
That is not proof that Alibaba’s AI operation is unprofitable — the revenue and capital-spending figures are not directly comparable profit measures. It is a reminder that an attractive market can still generate poor returns if servers, electricity, financing and depreciation absorb too much of the revenue.
Nor is the profitability question confined to China. The Financial Times has examined whether cheaper model usage will expand the AI market enough to justify the industry’s enormous infrastructure commitments. The optimistic case resembles the Jevons paradox: cheaper AI enables so many new tasks that total consumption rises. The pessimistic case is that efficiency drives prices down faster than revenue grows, leaving excess capacity and disappointing shareholder returns.
The relevant questions for investors are therefore less theatrical than the headline token count: What share of usage is paid? What is gross margin after serving the model? Are enterprise customers renewing contracts? How much hardware sits idle outside peak periods? Can providers sustain quality and latency while prices fall?
The hidden constraint: chips, power and memory
An AI service can be inexpensive only if the physical systems behind it remain reliable. Inference at national scale requires accelerators, networking equipment, high-bandwidth memory, cooling systems, software optimisation and a steady electricity supply.
The International Energy Agency’s updated 2026 assessment forecasts worldwide data-centre electricity use rising from 485 terawatt-hours in 2025 to about 950 TWh in 2030. It says AI-focused data-centre electricity consumption could triple over that period. The same report notes that energy use per simple AI task has become dramatically more efficient, but video generation, advanced reasoning and agentic workloads may require vastly more energy than a basic text response.
This is the central paradox of efficient AI: making each individual request cheaper may stimulate so many additional requests — and more computationally demanding ones — that total infrastructure requirements still rise.
China’s local chip industry may benefit from steady inference demand, particularly where software can be tuned to domestic accelerators. Yet advanced chip and memory constraints have not disappeared. Restricted access to leading-edge US technology creates incentives to optimise algorithms, use domestic hardware and manage capacity carefully. None of those strategies automatically eliminates the performance and supply-chain advantages held by competitors.
A practical benchmark for an AI provider should combine tokens per second, time to first response, task accuracy, reliability, security and energy efficiency. A fast but unreliable service can be an expensive bargain.
The US-China rivalry is shifting from benchmarks to ecosystems
For the United States, the strength of frontier-model laboratories, advanced semiconductors, enterprise software distribution and high-value commercial customers remains formidable. For China, low-cost models, industrial applications, a large domestic market and manufacturing depth provide a different route to global influence.
Neither model is guaranteed to win outright. The Stanford AI Index reports that the US invested far more private capital in AI in 2025, although private-investment measures understate China’s wider state-backed financing channels. Meanwhile, the Financial Times’ reporting on international adoption suggests that customers may increasingly use several providers rather than committing their entire businesses to a single AI ecosystem.
Trade policy adds another complication. Reuters reported on October 28 that China had proposed restrictions on exporting certain advanced AI technologies and expertise, while generally allowing overseas clients to access models through cloud services. Those proposals were not yet final at the time of reporting. Taken together with US chip controls, such policies could determine not just who develops the technology but where it can be hosted, modified and operated.
AI competition is thus becoming a contest over ecosystems: hardware, model weights, cloud infrastructure, operating costs, national rules, developer tools and trusted customer relationships. The lowest sticker price will matter, but so will the ability to offer dependable service across borders.
What this means for Pakistan and other emerging economies
The new emphasis on inference may be more important for emerging markets than the pursuit of ever-larger frontier models. Pakistan, for example, does not need to build a trillion-dollar AI training ecosystem to deploy useful tools for agriculture, export manufacturing, customer service, health administration, financial compliance or Urdu and regional-language applications.
The World Bank’s World Development Report 2026 argues that developing countries should concentrate on adopting and adapting AI for local conditions instead of assuming that building frontier models is a necessary first step. It also warns that electricity, connectivity, skills, appropriate local data and institutions can be more decisive constraints than the availability of a fashionable chatbot.
For Pakistani firms, affordable inference could make automation and specialised digital services more accessible. But purchasing an AI subscription is not itself productivity growth. Companies will need secure data-handling practices, careful evaluation in local languages, workers who can supervise systems and evidence that deployments actually save time or improve results.
The opportunity is not simply to consume more tokens. It is to convert affordable intelligence into better services and competitive businesses.
Five indicators that will reveal whether China’s inference boom is sustainable
The next stage of the AI race will be easier to assess if companies and policymakers release consistent data on five measures:
- Comparable token activity: input and output tokens, coverage of public and private deployments, and definitions that explain divergent national estimates.
- Verified business value: revenue from paying customers, renewal rates, and savings or productivity gains measured after accounting for human oversight.
- True inference economics: cost and gross margin per successfully completed task, rather than the headline price of a token.
- Infrastructure efficiency: accelerator utilisation, latency, failure rates, electricity consumption and the ability to serve peaks in demand.
- International reach: genuine overseas enterprise adoption, model portability and the effect of trade, security and data-governance restrictions.
Until those measures become more transparent, the token boom should be read as compelling evidence of activity and adoption — but only partial evidence of financial value.
The real milestone is economic, not numerical
China’s AI crossover has symbolic significance. It marks a moment when using AI appears to have become at least as important, in one national data-volume measure, as preparing the models themselves. The April 2026 evidence shows the transition was already visible in the previous year’s data; the October figures suggest the market is accelerating, albeit under inconsistent definitions.
The next winners may not be the firms that announce the largest models or print the most astonishing token totals. They may be the ones that turn abundant computation into something scarcer: reliable outcomes customers will pay for, at a price that produces durable profits.
The future of artificial intelligence will not be decided by how many tokens machines generate. It will be decided by how much value those tokens create.
Frequently asked questions
What is AI inference, and how does it differ from training?
Training builds or updates an AI model using examples and computing resources. Inference is the process of running the deployed model to answer requests, analyse information or complete tasks. Training and inference can both be expensive, but their operating patterns differ.
Did China’s AI inference data first exceed training data in October 2026?
No. A Chinese government announcement on April 29, 2026, had already reported that inference accounted for 101.34 exabytes of the 199.48 exabytes of combined AI training and inference data measured for 2025. The October announcement reinforced a previously reported crossover.
Does China use 175 trillion or 500 trillion AI tokens a day?
Both numbers appeared in 2026 reporting about June activity, but they came from different official or research sources and have not been publicly reconciled in the accounts reviewed. They should not be treated as interchangeable without matching definitions, time windows and coverage.
Does using more AI tokens mean a country has stronger AI models?
No. Token volume measures activity under a particular counting method. Model capability requires separate assessment of accuracy, reasoning, reliability, safety and performance in useful tasks.
Will cheaper AI inference reduce electricity demand?
It can reduce the energy needed for a specific task, but overall electricity consumption may still increase if more people adopt AI or shift to more computationally intensive services. The IEA projects global data-centre electricity use to roughly double between 2025 and 2030.
Which companies could benefit from an inference-led AI economy?
Potential beneficiaries include cloud platforms, accelerator and memory suppliers, networking and power-equipment manufacturers, model-optimisation firms and businesses that use AI to deliver valuable services. Benefiting from greater usage does not necessarily mean earning higher margins.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Why investors punished Google while largely sparing Microsoft—and what the historic sell-off reveals about the economics of artificial intelligence.
Wall Street has spent years rewarding technology companies for promising an artificial intelligence revolution. On October 29, it sent one of the revolution’s largest financiers a brutally different message: innovation may be impressive, but investors still expect a return on their money.
In a single trading session, approximately $500 billion evaporated from Alphabet’s stock market valuation. Shares in Google’s parent company plunged 12.6 percent, their worst one-day performance since the company’s public listing in 2004.
The extraordinary sell-off came after a quarter that, by many conventional measures, should have been cause for celebration. Alphabet reported revenue of $127.6 billion, a 25 percent increase from a year earlier. Its cloud division more than doubled its revenue. Operating income rose 30 percent.
Yet investors responded not with applause but with alarm.
The explanation lies in a troubling contradiction at the heart of the AI economy. The industry’s technological ambitions are accelerating faster than its capacity to translate those ambitions into cash.
What happened to Alphabet was not simply an earnings disappointment. It was a warning that the financial rules governing Silicon Valley’s AI investment boom may be changing.
And the contrasting treatment of Microsoft, which reported results on the same evening, offers an illuminating explanation.
The $500 Billion Warning
Alphabet’s financial results, released on October 28, exposed an uncomfortable imbalance.
The company generated $42.3 billion in operating cash flow during the third quarter. But it spent $51.4 billion on capital expenditure, primarily technical infrastructure. That left negative free cash flow of approximately $9.1 billion.
The previous quarter had produced a free-cash-flow deficit of $5.9 billion.
Two consecutive quarters in which capital investment exceeded internally generated operating cash represent a significant change in the financial profile of a business long celebrated for converting digital advertising into enormous amounts of cash.
The numbers are particularly striking because Alphabet’s investment programme shows little sign of slowing.
Management maintained its capital-expenditure forecast of $195 billion to $205 billion for 2026 and warned that spending would rise significantly again in 2027.
For investors, this raises a question that no amount of enthusiasm about large language models can easily answer: How much investment will be required before the financial rewards become commensurate with the costs?
The market was not reacting merely to the size of the expenditure. It was reacting to the possibility that infrastructure commitments could continue rising faster than the cash available to finance them.
There is, however, an essential distinction.
Alphabet is not a financially distressed company. According to its third-quarter regulatory filing, it held approximately $265 billion in cash, cash equivalents and marketable securities at the end of September, although that total included substantial equity holdings, including restricted SpaceX shares.
Its free cash flow over the preceding 12 months remained positive at $19.7 billion.
Moreover, an approximately $8.7 billion loss on equity securities—largely associated with SpaceX—depressed reported earnings without representing an equivalent quarterly operating cash outflow.
These distinctions matter. A temporary cash-flow deficit is not proof of impending insolvency, just as a large accounting profit is not proof that every investment creates economic value.
Alphabet has the resources to continue financing its ambitions. What investors are questioning is the price shareholders must pay for those ambitions, and the returns they will ultimately receive.
The market’s message is therefore more subtle than a rejection of AI: extraordinary financial capacity no longer guarantees unlimited investor patience.
Why Microsoft Escaped the Same Punishment
Microsoft’s earnings announcement provided a revealing contrast.
The company reported quarterly revenue of $92.3 billion, up 19 percent, while Azure revenue grew 48 percent.
It generated approximately $58 billion in operating cash flow and recorded $18.6 billion in positive free cash flow, despite capital expenditures of $45.2 billion.
Microsoft’s share price finished October 29 almost unchanged, declining approximately 0.2 percent.
That relative resilience was not because Microsoft had abandoned infrastructure spending. Nor was its investment programme fundamentally modest.
The company was continuing to commit extraordinary sums to data centres, processors and cloud infrastructure. Management projected approximately $170 billion in capital expenditures for calendar 2026, with some capacity deliveries delayed.
The distinction was that Microsoft’s operating cash generation continued to cover its cash capital investment, providing a financial cushion that Alphabet lacked during the latest quarter.
Microsoft also presented investors with a more immediately visible commercial connection between infrastructure and revenue.
Azure sells computing capacity directly to business customers. Microsoft can monetize AI through cloud consumption, enterprise software, development platforms and productivity subscriptions.
The relationship between customer demand, computational capacity and revenue is not perfectly transparent, but it is relatively straightforward.
When a business buys additional Azure computing capacity, Microsoft can demonstrate the associated revenue. That does not guarantee attractive returns on capital, but it offers investors a clearer path toward measuring them.
Alphabet faces a more complicated challenge.
Its infrastructure must support cloud customers, AI-model development and a vast collection of consumer services. Much of the expenditure is directed toward transforming products that users already access, including Search.
In those businesses, greater AI usage does not automatically produce a corresponding increase in revenue.
Nevertheless, the argument that Microsoft can finance its AI expansion entirely from internally generated cash also requires qualification.
On October 29, Microsoft priced a $25 billion offering of senior unsecured notes, with proceeds available for general corporate purposes, potentially including capital expenditure.
Even one of the industry’s strongest cash generators has chosen to supplement its financial resources through capital markets.
The real distinction is therefore not between companies that borrow and those that do not.
It is between companies whose investors remain confident in the relationship between investment, operating cash generation and future returns—and those for which that relationship has become harder to forecast.
Google’s Most Dangerous AI Problem Is Its Greatest Business
The more consequential challenge may lie beneath Alphabet’s capital expenditure.
Google’s search engine remains one of the most profitable commercial platforms ever created. For decades, its advertising model has depended on a remarkably efficient transaction: users express an intention, advertisers compete for their attention, and Google collects revenue.
Artificial intelligence threatens to alter that relationship.
Alphabet reported that Google Search and other advertising revenue grew 12 percent to approximately $63.4 billion in the third quarter, down from 17 percent growth in the preceding quarter.
The slowdown was not solely attributable to AI. Company executives pointed to currency effects and changing advertising patterns in specific industries, with foreign exchange identified as the largest factor.
But they also acknowledged that lower monetization in Google’s AI Mode was contributing to the deceleration.
This is the economic dilemma at the centre of Google’s transformation.
Traditional search presents users with advertisements alongside links to external websites. AI-powered search increasingly attempts to answer questions within Google’s own interface.
These experiences can be more useful, more conversational and more engaging. But the established commercial architecture does not transfer automatically.
A user who receives a comprehensive AI-generated answer may have less reason to click on conventional search results. Advertisers may need different formats to reach that user. Google must discover how to generate sufficient revenue from those interactions without compromising their usefulness.
Chief Executive Sundar Pichai has said AI investments are helping produce the fastest year-over-year growth in search queries in five years.
He has also reported that queries in AI Mode are, on average, three times longer than traditional searches.
Longer queries do not necessarily mean three times the computational cost. But they illustrate how significantly the product is changing.
The crucial question is whether this increased engagement can become sufficiently profitable engagement.
If Google’s new AI services attract greater usage but generate less advertising revenue per interaction, the company faces a double challenge: increasing infrastructure costs alongside uncertainty about monetization.
That possibility makes Alphabet’s situation different from a conventional infrastructure investment cycle.
Google is not merely building a new business. It is spending heavily to reinvent an existing one, partly to defend it against technologies that could undermine its established advantages.
And that creates a difficult strategic calculation.
Moving too slowly risks allowing competitors to redefine how consumers discover information. Moving too quickly could weaken the economics of the search business that finances Google’s technological ambitions.
For Alphabet, therefore, the cost of AI is not limited to servers, chips and electricity.
It also includes the possibility of disrupting one of the world’s most successful advertising models before an equally profitable successor is firmly established.
The Case Against Wall Street’s Verdict
There is a powerful counterargument to the market’s reaction.
Alphabet’s latest earnings contained evidence that its AI investments are already producing substantial commercial results.
Google Cloud revenue increased 103 percent to $30.7 billion, while the division’s operating income climbed from approximately $3.6 billion to $11.1 billion.
These are not the financial results of a business experiencing a collapse in AI demand.
They suggest that Alphabet is gaining meaningful commercial traction.
Importantly, the company said sales of its tensor processing unit systems made a significant contribution to Cloud’s expansion. Such hardware sales are not economically identical to recurring cloud-service revenue, and investors should distinguish between them when evaluating future growth.
Even so, the improvement in operating income is difficult to dismiss.
Alphabet has also built substantial expertise across semiconductor design, AI models, cloud infrastructure and consumer distribution.
Its ability to combine these capabilities may ultimately create advantages that narrower competitors struggle to replicate.
And large infrastructure investments frequently require cash long before their economic benefits become visible.
Data centres may take years to build and operate at full capacity. Customers may increase their spending gradually as applications move beyond experimentation into widespread deployment.
Judging a multiyear investment programme solely by two quarters of negative free cash flow would be shortsighted.
Indeed, if Alphabet’s investments strengthen its cloud business, improve the economics of inference and preserve Google’s position in search, the present spending surge could ultimately appear justified.
The difficulty is that investors must evaluate these possibilities before the returns become fully measurable.
That is what makes the debate so consequential.
The question is not whether Alphabet possesses valuable technology or whether demand for AI infrastructure exists. Its latest cloud results provide compelling evidence of both.
The question is whether today’s investment will earn sufficient returns to justify the company’s valuation after allowing for operating costs, depreciation, financing requirements and technological obsolescence.
That is a substantially higher standard than simply demonstrating rapid revenue growth.
The AI Boom Has Entered Its Financing Era
Alphabet’s experience is part of a much broader transformation in the economics of America’s largest technology companies.
The industry’s leading platforms are committing sums once associated with national infrastructure programmes.
Meta expects capital expenditures of $135 billion to $145 billion in 2026. It also reported negative free cash flow of approximately $2.1 billion in the third quarter.
Amazon’s October 29 results revealed a $42.4 billion free-cash-flow outflow over the preceding 12 months, despite AWS revenue growing 39 percent in the third quarter. Amazon maintained plans for approximately $220 billion in cash capital expenditures in 2026.
The enormous scale of these commitments suggests that AI is moving from a software-led innovation cycle into something closer to an industrial investment cycle.
Building the infrastructure requires land, electricity, cooling systems, semiconductors, financing and years of planning.
It also introduces risks unfamiliar to investors accustomed to the exceptional profitability of asset-light internet businesses.
An AI accelerator purchased today may become less economically competitive as newer processors arrive. Data-centre capacity must attract customers at prices sufficient to recover its cost. Electricity and cooling requirements can place lasting pressure on operating margins.
Accounting profits may remain strong while cash is tied up in new infrastructure.
Nor is the industry insulated from the cost of capital.
When borrowing becomes more expensive, when investors demand higher returns or when economic uncertainty affects enterprise spending, projects that once appeared compelling can become less attractive.
This does not mean an AI investment bubble must inevitably burst. Technological revolutions can deliver extraordinary productivity gains and create profitable businesses.
But history offers no guarantee that every company financing a technological revolution will capture a proportionate share of its economic benefits.
Railways transformed trade. Telecommunications transformed communication. The internet transformed commerce.
In each case, society’s long-term gains and the financial returns available to particular investors were not always the same thing.
Artificial intelligence may prove no different.
The Next Test Is Not Revenue Growth. It Is Return on Capital.
Investors should now demand more useful answers from technology companies than ever-larger announcements of capital expenditure.
How much additional revenue is generated by each dollar invested in computing infrastructure?
How quickly does new capacity reach commercially productive utilization?
Are businesses earning attractive margins after accounting for depreciation, energy, financing and maintenance?
And perhaps most importantly for Alphabet, can AI-powered search eventually produce revenue per user interaction comparable to—or better than—the traditional model it is replacing?
These questions matter more than headline declarations about model capabilities or user engagement.
Alphabet’s forthcoming fourth-quarter results, including further guidance on 2027 capital expenditure, will provide another opportunity to assess whether spending is beginning to stabilize relative to cash generation.
Microsoft will face similar scrutiny, especially as delayed GPU capacity becomes available and its own financing requirements increase.
The market’s relative tolerance toward Microsoft should not be mistaken for permanent immunity.
If AI revenue growth disappoints, or if capital requirements continue escalating faster than cash flow, even the strongest balance sheets will be tested.
There is another possibility, of course.
If AI adoption accelerates, infrastructure becomes more efficient and companies successfully develop profitable products, today’s expenditure could support years of earnings growth.
That outcome remains plausible.
But the burden of proof is shifting from technological promise to financial performance.
The End of Silicon Valley’s Blank Cheque
Alphabet’s historic sell-off may ultimately be remembered not as the moment Wall Street abandoned artificial intelligence, but as the moment it began taking the technology’s economics seriously.
The company did not lose roughly $500 billion in market value because its engineers had failed to build compelling AI products. It lost that value because investors became less confident about how much future cash shareholders would receive from the investments required to commercialize them.
Microsoft’s comparative resilience demonstrates the importance of that distinction. Investors were more willing to tolerate enormous capital commitments when supported by strong operating cash flow and clearer monetization prospects.
But Microsoft is not exempt from the same arithmetic, and Alphabet is far from defeated by it.
The real reckoning lies ahead.
Silicon Valley has successfully convinced the world that artificial intelligence will reshape how businesses operate and how people live.
Now it must prove that the economics of building that future will reward those paying for it.
For years, the defining question of the AI boom was who could build the most powerful technology. The defining question now is who can turn that technology into sustainable cash returns.
That is not the end of the AI revolution.
It may be the beginning of its financial maturity.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
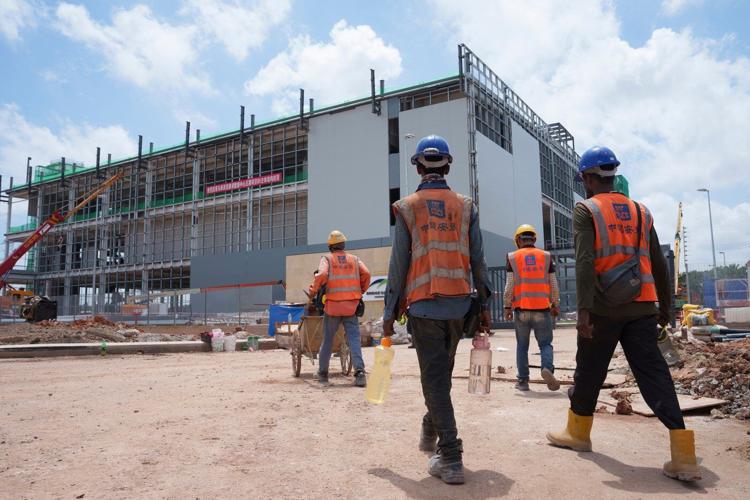
As Silicon Valley’s artificial intelligence boom triggers a global power strain, Southeast Asia’s new energy masterplan offers a pragmatic blueprint: integrating nuclear reactors with cross-border grids to sustain the digital future.
Across the tech corridors of Johor, Singapore, and West Java, massive server farms are quietly transforming Southeast Asia into the engine room of the global artificial intelligence economy. Every algorithmic query, large language model training run, and cloud computation requires staggering amounts of electricity. Yet, beneath this digital gold rush lies a uncomfortable physical reality: the region’s power grids are reaching their threshold, caught in a high-stakes collision between soaring energy demand and urgent net-zero climate imperatives.
For years, policy circles framed the energy transition as a binary choice between expanding weather-dependent solar and wind arrays or continuing a hazardous reliance on coal and natural gas. But the sheer scale of the AI boom has shattered this false dichotomy. Hyper-scale data centres require uninterrupted 24/7 baseload power—a standard that intermittency-prone renewables alone cannot guarantee without prohibitively expensive battery storage. To solve this dilemma, Southeast Asia is embarking on a bold pivot: embracing nuclear power as a foundational pillar of its upcoming regional energy architecture.
| “Small Modular Reactors represent a paradigm shift: providing clean, continuous baseload power directly adjacent to digital infrastructure clusters without straining fragile municipal grids.” |
The Shift Toward Small Modular Reactors
Unlike the gigawatt-scale conventional atomic plants of the twentieth century, which suffered from notorious construction delays and massive capital requirements, modern nuclear strategy centers on Small Modular Reactors (SMRs). Producing between 50 and 300 megawatts per unit, SMRs offer factory-fabricated scalability, advanced passive safety mechanisms, and a footprint compact enough to sit alongside industrial parks or sub-grid data hubs.
Across the Association of Southeast Asian Nations (ASEAN), member states are already establishing tactical readiness pathways:
- Vietnam: Re-engaging international vendor partnerships and updating its nuclear regulatory policy under International Atomic Energy Agency (IAEA) guidance to supply high-density manufacturing and processing corridors.
- Indonesia: Targeting early SMR deployments across its vast archipelago, offering off-grid clean electricity to power remote technological and industrial nodes outside Java.
- Malaysia: Reviving its Nuclear Energy Program Implementation Organization to support rapid data centre expansion in Johor and the Klang Valley while keeping power tariffs competitive.
- Singapore: Conducting rigorous feasibility studies into next-generation nuclear tech, paving the way for low-carbon energy imports through cross-border trade agreements.
Cross-Border Integration & Global Implications
The true strategic force multiplier lies in integrating nuclear energy into the multilateral ASEAN Power Grid (APG). By allowing nuclear-generated electricity to flow across borders alongside hydro and solar power, Southeast Asia can achieve grid resiliency that individual countries could never build alone. During dry seasons when hydroelectric output wanes, continuous nuclear generation keeps cross-border interconnectors energized and data centres operational.
For international policymakers in Washington and European capitals, Southeast Asia’s nuclear transition carries profound geopolitical implications. Western reactor developers must engage proactively with financing frameworks and regulatory assistance; failing to do so risks ceding civil nuclear leadership in the Indo-Pacific to state-backed entities from rival powers.
A Pragmatic Path Forward
Navigating this nuclear dawn will not be without hurdles. Updating legal safety frameworks, securing public trust, and unlocking private capital will require sustained international coordination. However, the economic incentive could not be clearer. In an era where computational power dictates national competitiveness, securing clean, reliable, and scalable energy is no longer just an environmental goal—it is a core national security imperative.
By aligning its digital ambition with atomic innovation under the new ASEAN Energy Masterplan, Southeast Asia is offering a valuable lesson to the world: the AI revolution does not have to compromise our climate targets—provided we have the courage to power it smartly.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

China’s 175 Trillion AI Tokens Reveal a Bigger Shift: The AI Boom

The Philippines’ Stagflation Trap: Higher Interest Rates

Alphabet’s $500 Billion Reckoning: Wall Street Is Losing Patience With the AI Boom

4 Reasons Why China’s Trade Concessions to Europe Will Not Solve the Crisis

The AI Revolution Needs Atomic Power. Southeast Asia Is Ready to Build It.

Zhuhai Airshow 2026: How China’s Stealth Jets, Drones and Missiles Are Redrawing Global Air Power

The $8 Billion Runway: China’s Strategic Bet on Guangzhou and the Future of Aviation

The Sandbox Imperium: Why Beijing’s Digital Yuan Needs Hong Kong

Gold at the $4,000 Line: Possible December Fed Hike

Oil at $100+: Hormuz, a Qatari Peace Draft and the Iran Deadline

The Fed’s 10-2 Hold: Why Two Dissenters Wanted a Rate Hike

SBP Raises Policy Rate to 12%: What It Means for Your Loans, Savings and Business

IMF’s $1.2bn Staff-Level Deal: What Pakistan Promised on Surplus

Decoding the DBS–BCA Merger Rumour: Market Volatility, Strategic Realities

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Stock Market Today: Dow, S&P 500, and Nasdaq Retreat as Treasury Yields

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Geopolitics and Your Portfolio: How International Affairs Move Global Markets

Why Did I Get $90 From Social Security? 8 Reasons Behind an Unexpected SSA Payment
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025