
Analysis
Trump Signs Executive Order Enabling Secondary Tariffs on Iran’s Trade Partners as Nuclear Talks Resume

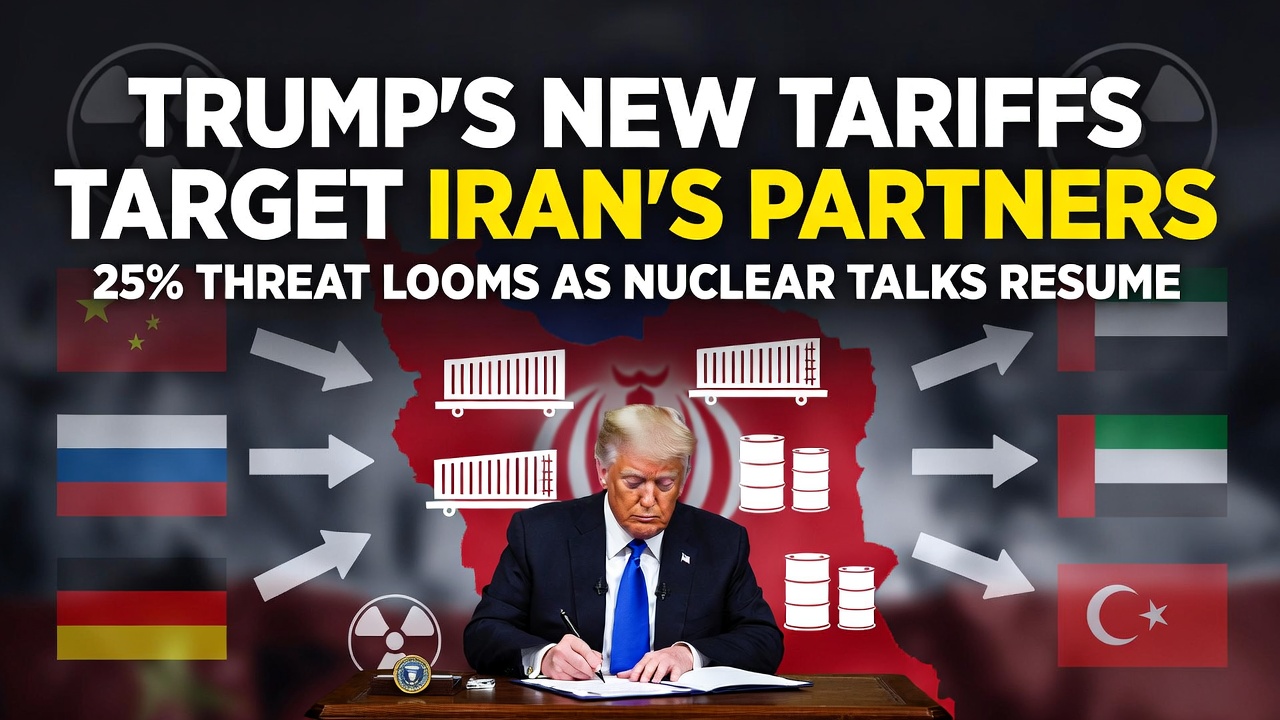
The framework for sweeping trade penalties arrives amid diplomatic overtures in Oman, raising questions about whether economic coercion can succeed where military pressure has failed
On February 6, 2026, President Donald Trump signed an executive order that could fundamentally reshape global trade architecture around Iran, establishing a legal framework to impose additional tariffs on any nation conducting commerce with the Islamic Republic. The order, which took effect February 7, represents the administration’s most ambitious attempt yet to weaponize America’s economic leverage against Tehran—while simultaneously opening a potential Pandora’s box of diplomatic and commercial complications for US allies and adversaries alike.
The timing is striking: Trump announced the measure even as American and Iranian officials engaged in indirect negotiations in Muscat, Oman—the first substantive dialogue since US involvement in coordinated strikes on Iranian nuclear facilities last June. Speaking to reporters aboard Air Force One en route to Mar-a-Lago, the president characterized the Oman talks as “very good” and indicated further sessions would occur “early next week,” suggesting the tariff framework may serve as both stick and carrot in a renewed campaign of maximum economic pressure.
Yet unlike Trump’s first-term sanctions regime, which primarily targeted Iran directly, this executive order casts a far wider net—one that could ensnare some of America’s most important economic and security partners.
The Mechanics of Secondary Economic Coercion
The executive order does not immediately impose tariffs. Instead, it reaffirms the national emergency declaration concerning Iran and establishes a bureaucratic process through which the Secretaries of State, Commerce, and Treasury can identify countries or entities “directly or indirectly” purchasing, importing, or acquiring goods and services from Iran. Once identified, those nations could face additional import duties—with Trump’s mid-January Truth Social post suggesting a 25% rate as the benchmark.
This framework represents secondary sanctions on steroids, extending beyond traditional financial restrictions to encompass broad trade penalties. The mechanism’s flexibility is both its power and its peril: administration officials retain discretionary authority over implementation, creating significant policy uncertainty for global businesses and governments alike.
The legal architecture builds on emergency powers Congress has granted presidents since the International Emergency Economic Powers Act of 1977, though legal scholars have increasingly questioned the constitutional boundaries of such delegated authority. Still, the Supreme Court has historically deferred to executive discretion in foreign commerce matters, particularly those framed as national security imperatives.
Who Stands in the Crosshairs?
The list of potential targets reads like a roster of the world’s largest economies and most strategically significant nations. China tops the list as Iran’s primary trading partner, with bilateral commerce reaching approximately $32.5 billion in 2024 according to World Trade Organization data—driven predominantly by Chinese oil imports that have sustained Iran’s economy despite Western sanctions.
Beijing’s response will prove critical. Chinese officials have consistently maintained that their economic relationship with Iran complies with international law, and Foreign Ministry spokesperson statements have repeatedly asserted China’s right to conduct “normal trade and economic cooperation.” A 25% tariff on Chinese goods entering the United States—even if selectively applied—would represent a dramatic escalation beyond the Trump administration’s existing tariff regime, potentially triggering retaliatory measures that could spiral into a broader economic confrontation.
The European Union faces its own dilemma. Germany, despite scaling back relations with Tehran, maintains residual trade ties, while several member states have worked to preserve economic channels even under US sanctions pressure. Brussels has historically resisted American extraterritorial sanctions applications, viewing them as violations of international law and European sovereignty. The Trump administration’s approach threatens to force a choice between transatlantic alliance cohesion and principles of trade autonomy.
Turkey presents perhaps the most acute diplomatic complication. As a NATO ally hosting crucial American military installations, Ankara has nevertheless maintained pragmatic economic relations with Iran, driven by geography, energy needs, and President Recep Tayyip Erdoğan’s regional ambitions. Penalizing Turkish trade could undermine alliance cooperation at a moment when NATO faces multiple security challenges from the Black Sea to the Eastern Mediterranean.
The United Arab Emirates occupies equally complex terrain. Despite Abraham Accords normalization with Israel and close security cooperation with Washington, Dubai’s business community has long served as a critical commercial hub for Iranian entities seeking to circumvent sanctions. Abu Dhabi has walked a careful line between American security partnership and regional economic pragmatism—a balancing act this executive order could render untenable.
India, the world’s fastest-growing major economy and an increasingly important US strategic partner in Indo-Pacific competition with China, imports significant Iranian oil when sanctions waivers permit. New Delhi has historically resisted choosing between Washington and Tehran, instead pursuing its national interests through strategic autonomy. Secondary tariffs could test that doctrine’s limits.
Even Russia, already heavily sanctioned over Ukraine, conducts substantial commerce with Iran, including reported arms transfers and energy cooperation. While Moscow has limited vulnerability to additional US trade penalties given existing restrictions, the executive order signals Washington’s willingness to treat the Russia-Iran partnership as an integrated strategic threat.
Economic Ripple Effects and Market Uncertainties
The global economic implications extend well beyond bilateral trade balances. Iran remains a significant oil producer despite sanctions, with exports estimated between 1.5 and 2 million barrels daily—much of it flowing to China through opaque channels. Any disruption to these flows, whether through enhanced enforcement or preemptive cutbacks by nervous buyers, could tighten global energy markets already navigating geopolitical volatility from Ukraine to the South China Sea.
Energy analysts at several investment banks have noted that Brent crude futures showed modest upticks following the executive order’s announcement, reflecting trader concerns about supply disruption risks. While global oil markets currently show adequate spare capacity, the psychological impact of threatening major importers like China could introduce new price volatility, particularly if Beijing responds by accelerating strategic petroleum reserve accumulation or seeking alternative suppliers at premium prices.
Supply chain vulnerabilities present another concern. Many products imported to the United States contain components manufactured in countries that trade with Iran, even if final assembly occurs elsewhere. The “directly or indirectly” language in the executive order creates ambiguity: Would a German automotive manufacturer sourcing steel from a company that also sells to Iranian clients face penalties? The lack of clarity generates compliance nightmares for multinational corporations and could trigger preemptive supply chain reorganizations with associated costs and inefficiencies.
For American consumers, secondary tariffs risk compounding inflation pressures. The US imports substantial volumes from China, the EU, Turkey, and other potential targets. Even selectively applied 25% duties would likely translate to higher retail prices for electronics, automobiles, textiles, and other goods—an awkward political reality for an administration that has emphasized economic strength as a signature achievement.
Diplomatic Calculations and the Oman Talks
The executive order’s announcement concurrent with renewed nuclear negotiations raises fundamental questions about the administration’s strategic theory. Is economic coercion meant to pressure Tehran toward concessions at the negotiating table? Or does it reflect skepticism about diplomacy’s prospects, with commercial warfare pursued as a parallel track?
Historical precedent offers mixed lessons. Trump’s first-term “maximum pressure” campaign succeeded in devastating Iran’s economy—GDP contracted roughly 13% between 2017 and 2020—but failed to produce the comprehensive nuclear agreement the administration sought. Instead, Tehran responded by expanding its nuclear program beyond Joint Comprehensive Plan of Action (JCPOA) limits, enriching uranium to near-weapons-grade levels and accumulating substantial stockpiles.
The June 2025 strikes on Iranian nuclear facilities, in which the United States reportedly provided intelligence and logistical support to regional partners, marked a dramatic escalation beyond economic pressure. Yet six months later, with Iran’s program damaged but not eliminated and regional tensions simmering, both sides appear willing to explore diplomatic off-ramps.
The Muscat talks—hosted by Oman, which has long served as a discreet intermediary between Washington and Tehran—represent the most serious engagement since the strike operations. While details remain closely held, informed observers suggest discussions focus on verifiable constraints on Iran’s nuclear program in exchange for sanctions relief and security assurances.
Into this delicate diplomatic dance, the tariff executive order injects significant complexity. Iranian officials have historically viewed economic pressure as evidence of American bad faith, arguing that Washington uses sanctions to pursue regime change rather than genuine policy modification. The timing could reinforce hardline narratives within Tehran’s political establishment, potentially strengthening voices skeptical of negotiation.
Conversely, the administration likely calculates that threatening third-party trade partners demonstrates resolve and raises the costs of Iranian intransigence, potentially accelerating Tehran’s timeline for concessions. The theory holds that fear of economic isolation—not just for Iran but for its vital commercial partners—creates additional pressure channels unavailable through direct bilateral sanctions alone.
Whether this strategy succeeds depends substantially on execution. Measured application targeting specific sectors or entities might preserve diplomatic space while signaling seriousness. Sweeping implementation against major economies would likely trigger defensive responses that harden positions rather than facilitate compromise.
Alliance Strains and the Broader Strategic Context
Beyond immediate Iran policy, the executive order raises fundamental questions about American alliance management and the sustainability of unilateral economic statecraft. European officials have long complained that US extraterritorial sanctions force compliance with American foreign policy preferences or exclusion from dollar-denominated finance and US markets—a choice they view as coercive and corrosive to transatlantic partnership.
The executive order arrives amid broader tensions over trade policy. Trump has threatened or imposed tariffs on numerous partners over issues ranging from steel production to digital services taxes, treating commerce as a primary tool of geopolitical influence. While this approach enjoys domestic political support, it risks accelerating efforts by allies and competitors alike to reduce dependence on US-dominated financial and commercial systems.
China has invested heavily in payment systems alternatives to SWIFT, Yuan-denominated oil contracts, and bilateral trade arrangements that bypass dollar settlement. Russia has pursued similar de-dollarization strategies. The threat of tariffs on Iran trade could provide additional impetus for developing economies to participate in these alternative frameworks, potentially eroding American economic leverage over the long term.
For regional Middle Eastern partners, the executive order creates difficult choices. The UAE and Saudi Arabia have sought to position themselves as indispensable US security partners while maintaining economic flexibility to pursue national interests, including periodic accommodation with Iran. Forcing stark binary choices risks either alienating partners who resist or creating dependencies that reduce their regional influence.
What Happens Next: The Week Ahead and Beyond
President Trump’s indication that further talks would occur “early next week” suggests the diplomatic track remains active despite economic saber-rattling. The proximity of these events—executive order signing and continued negotiations—may be deliberate sequencing: establish the framework for enhanced pressure while leaving actual implementation as a negotiating variable.
Several scenarios merit consideration. First, negotiations could produce preliminary agreements on nuclear monitoring or enrichment caps, with the United States agreeing to delay or limit tariff implementation as a reciprocal confidence-building measure. This would represent classic coercive diplomacy—threatening pain to secure concessions, then withholding implementation as reward for cooperation.
Second, talks could stall over verification mechanisms or sanctions relief sequencing, leading the administration to begin designating countries for tariffs—likely starting with smaller players rather than China or major European economies, testing international reaction before escalating further.
Third, external events could overtake both negotiation and tariff tracks. Iran’s domestic political calendar, potential Israeli actions, or regional proxy conflicts could shift calculations rapidly, either accelerating diplomatic urgency or rendering negotiations moot.
For global markets and policymakers, the executive order injects substantial uncertainty into an already complex geopolitical environment. Businesses engaged in Iran trade face pressure to demonstrate compliance or risk US market access. Governments must calibrate responses that balance sovereignty principles against economic interests. And all parties must navigate an administration that has demonstrated willingness to rapidly shift tactical approaches while pursuing strategic objectives.
The ultimate question remains whether economic coercion of this scale and scope can achieve outcomes that previous approaches—direct sanctions, military pressure, and diplomatic isolation—have not. History suggests that while economic pressure can inflict costs, translating those costs into desired policy changes requires adversaries to perceive acceptable off-ramps and negotiating partners to maintain credibility through consistent implementation.
As talks resume in Oman this week, the world will watch not only what occurs in closed-door negotiating sessions but also how the Trump administration wields—or restrains—the expansive economic weapon it has just forged. The answer will shape not only the Iranian nuclear issue but the broader international order’s trajectory in an age of renewed great power competition and economic nationalism.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
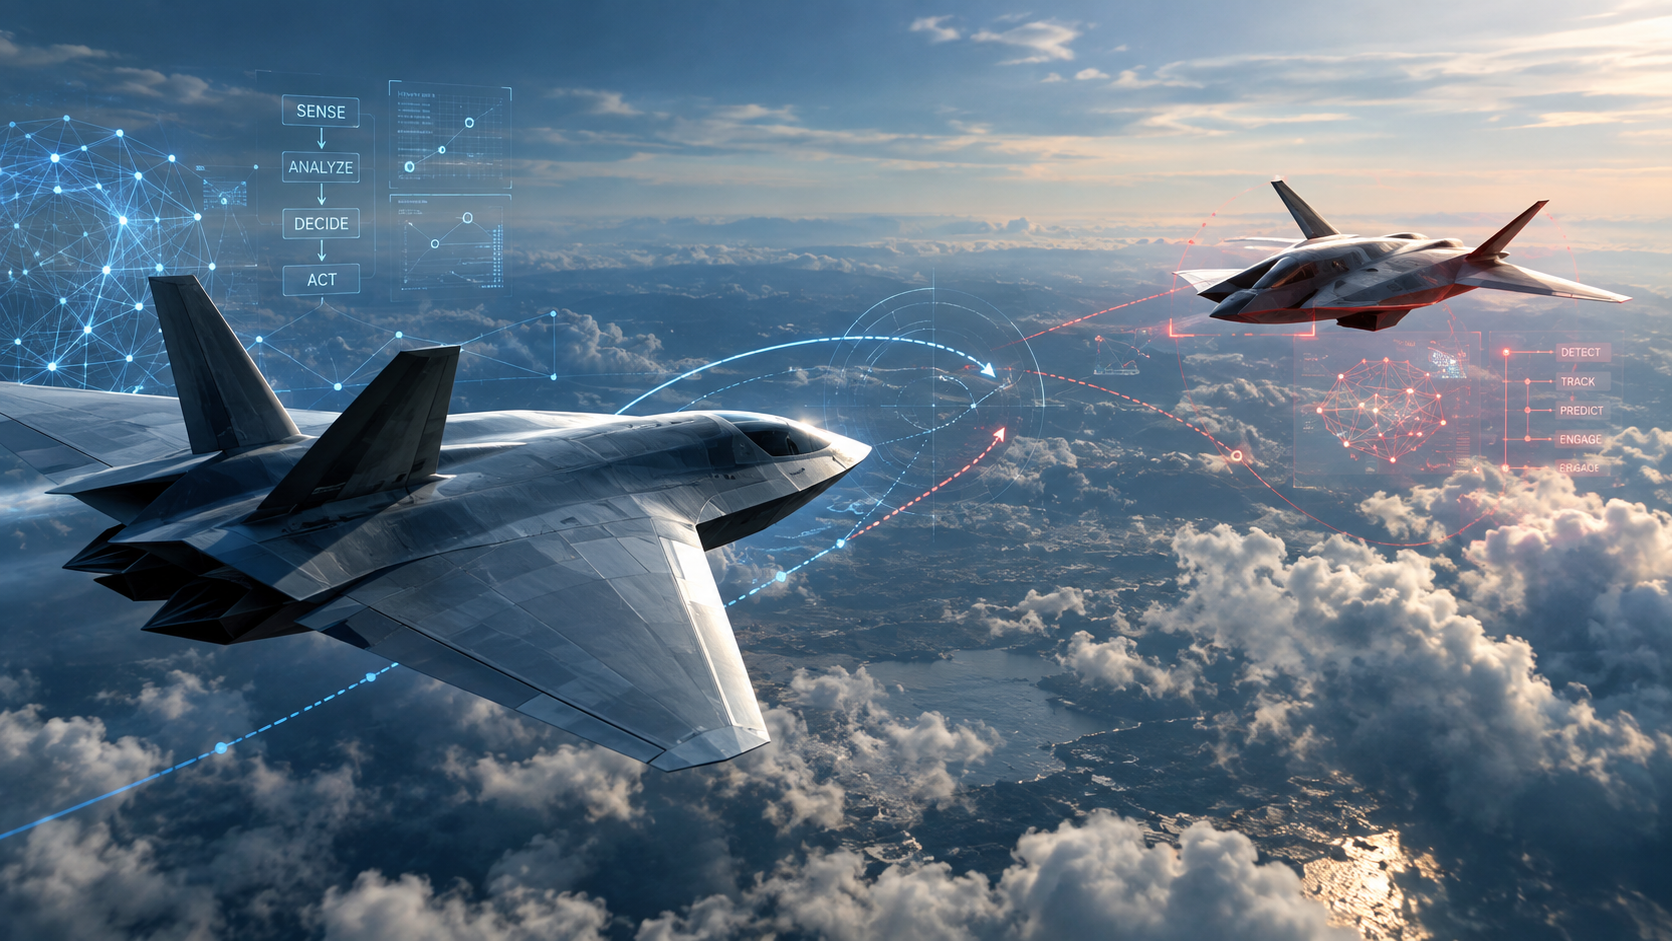
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A new Reuters poll shows 90% of economists expect the BoE to hold rates at 3.75% for the rest of 2026 — up from 83% last month. Here’s why the consensus hardened.
The Bank of England looks set to sit tight for the rest of 2026, and the consensus behind that view is getting stronger, not weaker. Per Investing.com’s coverage of the Reuters poll, the Bank will leave rates unchanged at 3.75% for the rest of the year according to a strong majority of economists, who have held that view since the war began in late February. Nearly 90% — 56 of 64 respondents — now expect no change through year-end, up from 83% last month, with six expecting a hike and two a cut; no one in the poll, conducted August 13–18, expects a September move.
Key Takeaways
- A Reuters poll of 64 economists (Aug 13–18) shows 56 now expect the BoE to hold Bank Rate at 3.75% through year-end — 90%, up from 83% last month.
- No economist in the poll expects a rate change at the September MPC meeting.
- The consensus has held since the US-Israeli war on Iran began in late February, with little evidence yet of energy-price spillover into the broader economy.
- Markets remain slightly more hawkish than economists, still pricing some chance of a rise by year-end.
- The BoE’s own guidance flags rising Q3/Q4 inflation risk tied specifically to Middle East energy prices.
The consensus is driven less by domestic demand and more by an external variable the Bank has flagged repeatedly. Per the same Reuters poll coverage, the UK economy has stayed mostly resilient since the war began, with little evidence of energy-price spillover into the broader economy — giving the Bank room to stay on the sidelines.
That resilience is fragile by the Bank’s own admission. According to an August 2026 review from Hanbury Wealth, the MPC voted six-to-three at its July 30 meeting to hold at 3.75%, with policymakers signaling rates could rise if Middle East-linked inflationary pressure intensifies; Governor Andrew Bailey said inflation had fallen faster than expected, but the conflict continues to mean high and volatile energy prices that will push inflation back up later in the year. The Bank’s own trajectory reflects this: per the House of Commons Library’s inflation briefing, based on mid-June energy pricing, the Bank projected CPI at “a little under 3%” in Q3 2026 and “a little over 3¼%” in Q4 — a downgrade from its April forecast.
There’s a genuine two-sided risk the poll’s headline framing tends to flatten. On the downside for inflation, the same House of Commons briefing notes that if Middle East energy disruption proves short-lived and oil and gas prices decline, inflation could instead fall from a September 2026 peak toward the Bank’s 2% target by Q2 2027. On the upside risk, HSBC UK economist Elizabeth Martins told Reuters (via Investing.com) that “a big rebound in energy prices would certainly change things.”
Markets aren’t as settled as the economist consensus: per the same poll coverage, financial markets are still pricing in one quarter-point rate rise by year-end — a genuine gap between what economists expect and what traders are hedging against, reported by outlets as two separate data points rather than connected explicitly.
Underlying data support a “resilient but fragile” framing. A KPMG-cited economic overview from Opus Business Advisory Group shows GDP grew 0.7% in the three months to May, slightly down from 0.8% in April, while core inflation fell more than expected in the twelve months to June, reaching its lowest rate since March 2025 — evidence the disinflation trend independent of energy hasn’t reversed. Separately, the House of Commons Library data shows food price inflation eased to 1.7% in June, its lowest since August 2024, reinforcing that the risk is concentrated in energy rather than broad-based prices.
Why It Matters
For borrowers, a prolonged hold at 3.75% keeps mortgage costs elevated relative to sharper-cut scenarios floated earlier in the year. For savers, it sustains relatively attractive cash returns. For the government, Opus’s review notes Prime Minister Andy Burnham has pledged a £2 bus-fare cap and removal of VAT from household electricity bills from October while maintaining existing fiscal rules and avoiding tax rises — a combination that gets harder to fund if borrowing costs stay elevated through year-end.
Data and Evidence
- Bank Rate: held at 3.75% since the July 30 MPC vote (6-3)
- Reuters poll: 56 of 64 economists (90%) expect no change through year-end, up from 83% last month
- BoE inflation forecast: ~3% Q3 2026, ~3.25%+ Q4 2026
- GDP growth: 0.7% in the three months to May 2026
- Food inflation: 1.7% in June 2026, lowest since August 2024
Global Impact
A UK central bank holding firm against energy-driven inflation risk is a data point other energy-importing economies — including Pakistan and much of South and Southeast Asia — are watching as a template for treating Middle East-linked price shocks as transitory.
What Happens Next
The next live decision point is the September MPC meeting, where the poll shows unanimous expectation of no change. The Q3/Q4 inflation prints will show whether the Bank’s own ~3.25% forecast materializes — and whether the hold consensus survives contact with that data.
Frequently Asked Questions
What is the UK’s current interest rate?
3.75%, unchanged since July 30, 2026.
Why isn’t the BoE cutting further?
Concern that Middle East-driven energy prices could push inflation back up in H2 2026.
Will UK mortgage rates change soon?
Based on the current poll, no near-term move is expected.
What would change the outlook?
A significant rebound — or further de-escalation — in Middle East energy prices.
Do markets agree with economists?
Not entirely — traders still price some chance of a year-end rate rise.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Pakistan is running two demanding reform programs at once, and they don’t obviously fit together. On one track, the IMF is pressing for stricter fiscal controls, expanded tax collection, and continued tight monetary policy under its Extended Fund Facility. On the other, Pakistan’s own constitution now mandates the removal of “riba” — interest — from the economy entirely, with a deadline set for January 2028, following a constitutional amendment passed in October 2024, according to IMF Country Report 25/109.
The IMF’s side of the ledger
Pakistan’s economic recovery gained real momentum in the first half of FY26, with GDP growth averaging 3.8% year-on-year, driven by the auto, construction, and garment industries, even as flooding in July-August weighed on output, according to IMF staff reporting. Inflation, however, climbed to 7.3% year-on-year in March as higher global commodity prices passed through to domestic energy costs. Foreign reserves have been rebuilding steadily — from $14.5 billion at end-June 2025 to $16 billion by end-December — while the primary fiscal surplus is expected to reach 1.6% of GDP in FY26, in line with IMF targets.
In May 2026, the IMF Executive Board completed the third review of Pakistan’s Extended Fund Facility and second review of its Resilience and Sustainability Facility, unlocking roughly $1.1 billion and $220 million respectively and bringing total disbursements under the two programs to about $4.8 billion, according to the IMF’s official press release. The Fund explicitly credited Pakistan’s “strong implementation” for maintaining stability despite the disruption from the Middle East war.
The parallel Islamic finance transformation
Running alongside that fiscal program is a structural transformation few outside Pakistan are tracking closely: the State Bank of Pakistan is required to develop a full financial sector strategy detailing the legal, regulatory, and strategic path to a riba-free economy, addressing monetary policy implementation, public debt management, and bank supervision — with a strategy deadline the IMF set for end-June 2026, per the same country report. Parliament has already moved on a related front, approving the Virtual Assets Bill in March 2026 and formally establishing the Pakistan Virtual Assets Regulatory Authority.
Why the IMF is watching this transition warily
The IMF’s own language signals concern about execution risk: publishing the riba-free transition plan “will help align the expectations of market participants, investors, and regulators… and mitigate concerns about any possible cliff effect,” according to the country report language. That is diplomatic phrasing for a real structural risk — an abrupt, poorly sequenced transition away from conventional interest-based finance could destabilize a banking sector the IMF has spent years helping stabilize.
The tax reform Pakistan still owes
Beyond monetary policy, Pakistan has committed to finalizing a new audit manual and centralizing taxpayer audit selection by August 2026, accelerating its Retailer Tax Registration Scheme, and making its Tax Policy Office fully operational, according to ProPakistani’s summary of IMF commitments. The Federal Board of Revenue has continued missing collection targets, prompting the IMF to propose making FBR revenue goals a formal Quantitative Performance Criteria — a stricter enforcement mechanism than before.
Why this matters for Gulf and global investors
Pakistan’s dual reform track — IMF-style fiscal orthodoxy alongside a constitutionally mandated Islamic finance transition — is unusual among IMF program countries and is drawing renewed Gulf capital interest, visible in DIFC’s decision to bring its Dubai FinTech Summit to Pakistan for the first time in August 2026 (see our companion report). Investors assessing Pakistan’s banking sector need to model both trajectories simultaneously, not just the more familiar IMF fiscal metrics.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Hong Kong Land Acquires Wheelock Place and Renames It Landmark Orchard

DBS PayLah China QR Expansion: Now Accepted at Over 100 Million Merchants

Nvidia Stops Reporting Singapore Revenue After It Hit 22% of Sales: What Investors Need to Know

Global Trade and Tariffs 2026:WTO Barometer Still Shows Growth

Extended Producer Responsibility Changes and the UK Hospitality Sector

GDP and Economic Growth in the US: How It’s Measured, Current Trends

Economic Globalization: How Global Trade Shapes the US Economy, Jobs, and Consumers

Best Life Insurance Companies in the United States 2026: Our Top 5 Picks

Pakistan Auto Policy 2026-31 Explained: EV Tax Cuts, $6 Billion Export Target

When Dollar Debt and Food Imports Collide: The Currency Squeeze

Why Freight and Storage Costs Keep Food Prices High After Oil Falls

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Global Finance 2027: Debt, Inflation and AI Are Pulling the Economy Apart

Democrats Won Congress. Can They Fix the U.S. Economy
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025